
 Video Surveillance Market | 2026-2036
Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Video Surveillance Market Intelligence
The EU AI Act is expanding compliance obligations for biometric surveillance across European public procurement, forcing manufacturers to redesign analytics pipelines. Hangzhou Hikvision Digital Technology Co., Ltd. dominates camera hardware manufacturing at scale across Asia and emerging economies. Dahua Technology Co., Ltd. competes aggressively on price while extending its cloud platform footprint. Axis Communications AB specializes in open-architecture IP cameras that sustain premium positioning in Western enterprise accounts.
Video surveillance encompasses camera systems, recording devices, and analytics software that capture, store, and process visual data for security monitoring and operational intelligence. Modern IP cameras transmit compressed H.265 video over Ethernet at resolutions up to 4K, enabling centralized management and AI-powered detection of anomalies in real time. IP Cameras now lead product type value generation as analog infrastructure ages out of installed bases across developed economies. AI-Based Analytics represents the fastest-expanding technology segment, with edge-computing deployments reducing bandwidth costs and latency for motion detection and object classification. Smart Cities application demand concentrates where municipal budgets fund integrated command centers linking transportation hubs with critical infrastructure protection.
The US FCC governs wireless spectrum allocation for cellular-connected surveillance devices, while the EU GDPR imposes strict limits on biometric data retention that constrain facial recognition deployments in public spaces. China's SAMR and GB standards mandate domestic encryption protocols for government security installations, creating technical barriers for foreign equipment. Stakeholders must monitor divergence between privacy-centric Western regulations and security-prioritized frameworks in Asia when allocating R&D and certification resources.
Market Dynamics
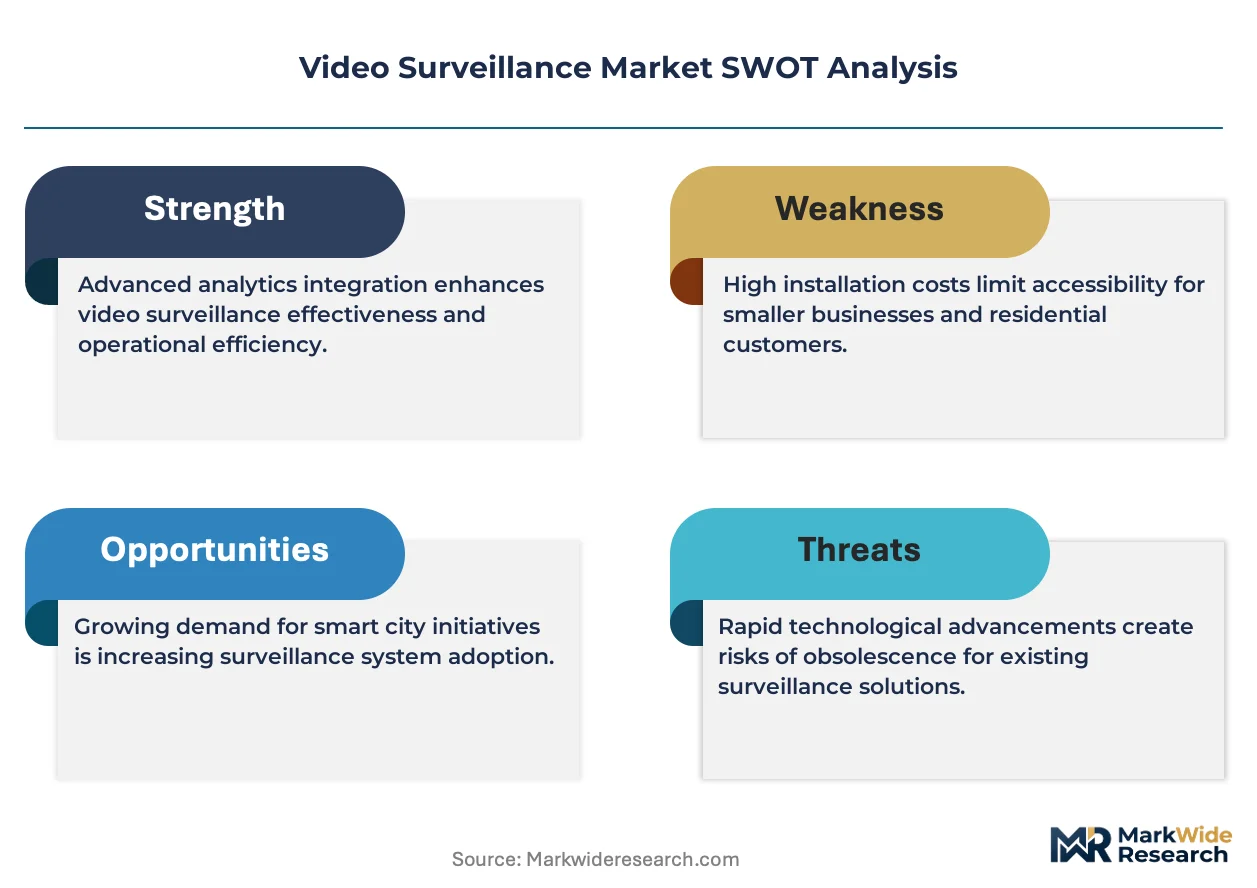
The migration from analog to IP infrastructure is compressing replacement cycles while edge AI deployment is redistributing computational load from centralized servers to camera endpoints, fundamentally altering hardware specifications and vendor margin structures.
Growth Catalysts
- EU AI Act compliance mandates:Biometric surveillance restrictions in European public procurement are accelerating demand for privacy-preserving analytics that process data at the edge without centralized facial recognition databases.
- Smart city infrastructure:Municipal command centers in Singapore and Dubai are integrating transportation, critical infrastructure, and public safety networks into unified platforms requiring AI-enabled camera density.
- H.265 compression adoption:Bandwidth efficiency gains from advanced video codecs are enabling 4K streaming over existing municipal fiber networks without parallel infrastructure investment.
Market Restraints
- Image sensor supply concentration:CMOS sensor fabrication concentrates among Taiwanese and South Korean foundries, exposing camera OEMs to geopolitical disruption in semiconductor supply chains.
- GDPR biometric retention limits:European data protection authorities impose strict temporal boundaries on facial template storage, constraining cloud-based identification service revenue models.
- Silicon carbide substrate costs:Advanced thermal imaging sensors require expensive wide-bandgap semiconductor materials that inflate unit economics for perimeter security deployments.
Strategic Opportunities
- India urban security modernization:Smart city missions under the Ministry of Housing and Urban Affairs are funding integrated surveillance for 100 metropolitan areas with limited legacy analog displacement costs.
- Convergence of LiDAR and video:Sensor fusion combining optical cameras with depth-sensing arrays creates new product categories for autonomous perimeter monitoring in critical infrastructure.
- Outcome-based municipal contracting:City governments are shifting from capital expenditure procurement to performance-linked service agreements that bundle hardware, software, and maintenance.
Industry Challenges
- Edge AI firmware integration:Camera manufacturers face complex software engineering requirements to deploy neural network inference on resource-constrained embedded processors without thermal degradation.
- Multi-jurisdiction certification timelines:Products must simultaneously satisfy China's SAMR encryption mandates, EU CE marking, and US FCC radio equipment authorization, extending time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Surveillance Market |
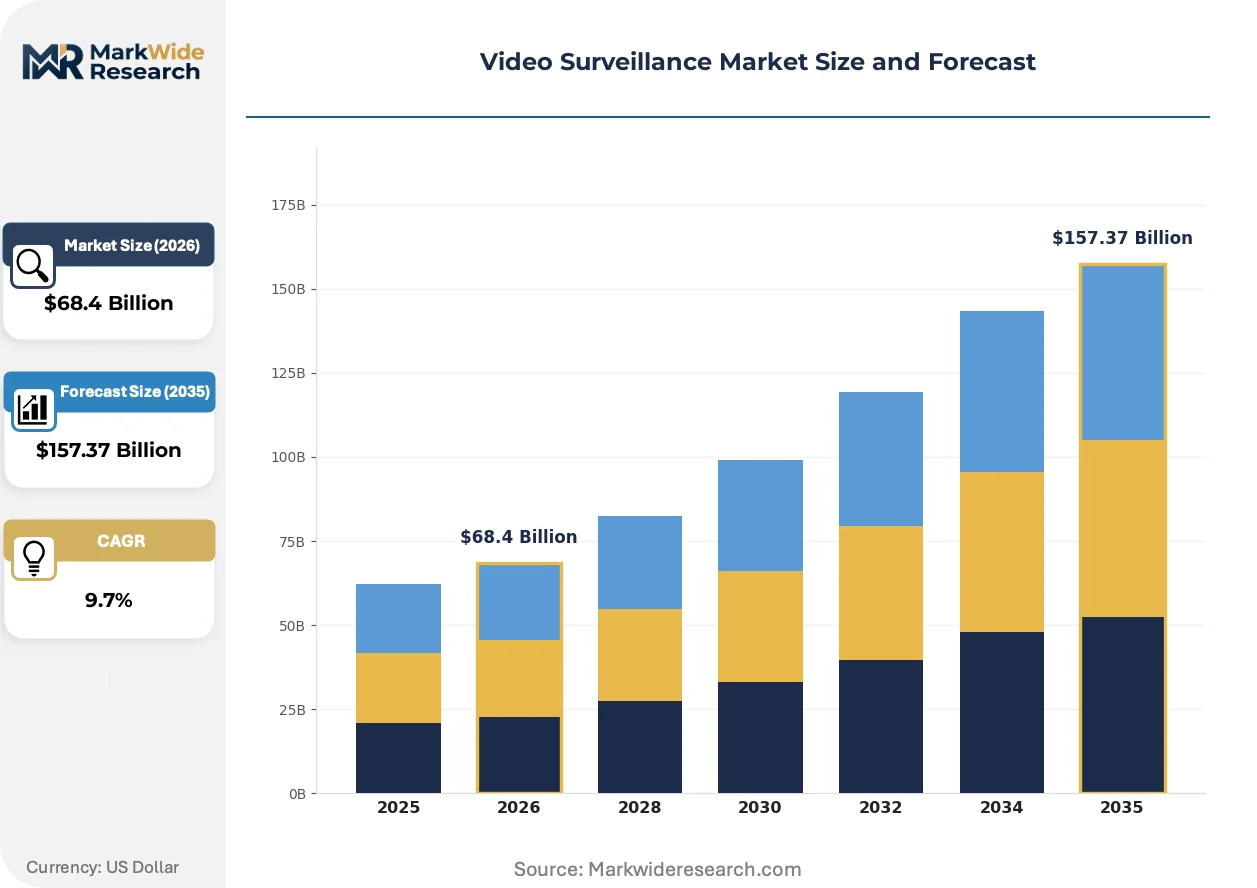
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cameras, IP Cameras, Network Video Recorders, Digital Video Recorders, Infrared Cameras Technology: Cloud-Based, Edge Computing, AI-Based Analytics, Thermal Imaging, Motion Detection Application: Public Safety, Transportation Hubs, Smart Cities, Critical Infrastructure, Commercial Complexes End User: Government Agencies, Educational Institutions, Manufacturing Plants, Hospitality Venues, Residential Communities |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., Axis Communications AB, Hanwha Vision Co., Ltd., Honeywell International Inc., Motorola Solutions, Inc., Bosch Security Systems GmbH, Teledyne FLIR LLC, Zhejiang Uniview Technologies Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Surveillance Market Strategic Shifts & Innovations
Computational migration toward camera endpoints is compressing latency requirements while regulatory fragmentation is forcing modular hardware architectures. Procurement patterns are shifting from equipment sales to integrated service contracts.
Edge-native AI inference is electrifying camera functionality by embedding object classification and anomaly detection directly into firmware. Critical infrastructure operators in Saudi Arabia and UAE are deploying these systems for real-time perimeter breach identification without cloud dependency. This distributed architecture is compressing response latency from seconds to milliseconds while reducing backhaul bandwidth requirements by orders of magnitude.
The EU AI Act's risk-classification framework for biometric identification systems is forcing manufacturers to segment product portfolios between prohibited practices and high-risk compliance pathways. Systems deployed in French and German public spaces now require conformity assessments, technical documentation, and human oversight protocols that inflate development costs. Western European integrators are responding by specifying open-architecture cameras that permit software-defined feature disablement for jurisdiction-specific deployment.
Municipal procurement departments are unbundling hardware acquisition from analytics subscriptions and maintenance services, reversing decades of integrated vendor relationships. Singapore's Land Transport Authority and Dubai's Roads and Transport Authority have pioneered performance-based contracts where payment correlates with incident detection accuracy rather than equipment installation. This shift is visible most acutely in Middle Eastern smart city deployments where sovereign wealth funds prioritize operational expenditure flexibility over capital asset ownership.
Video Surveillance Market Segmentation
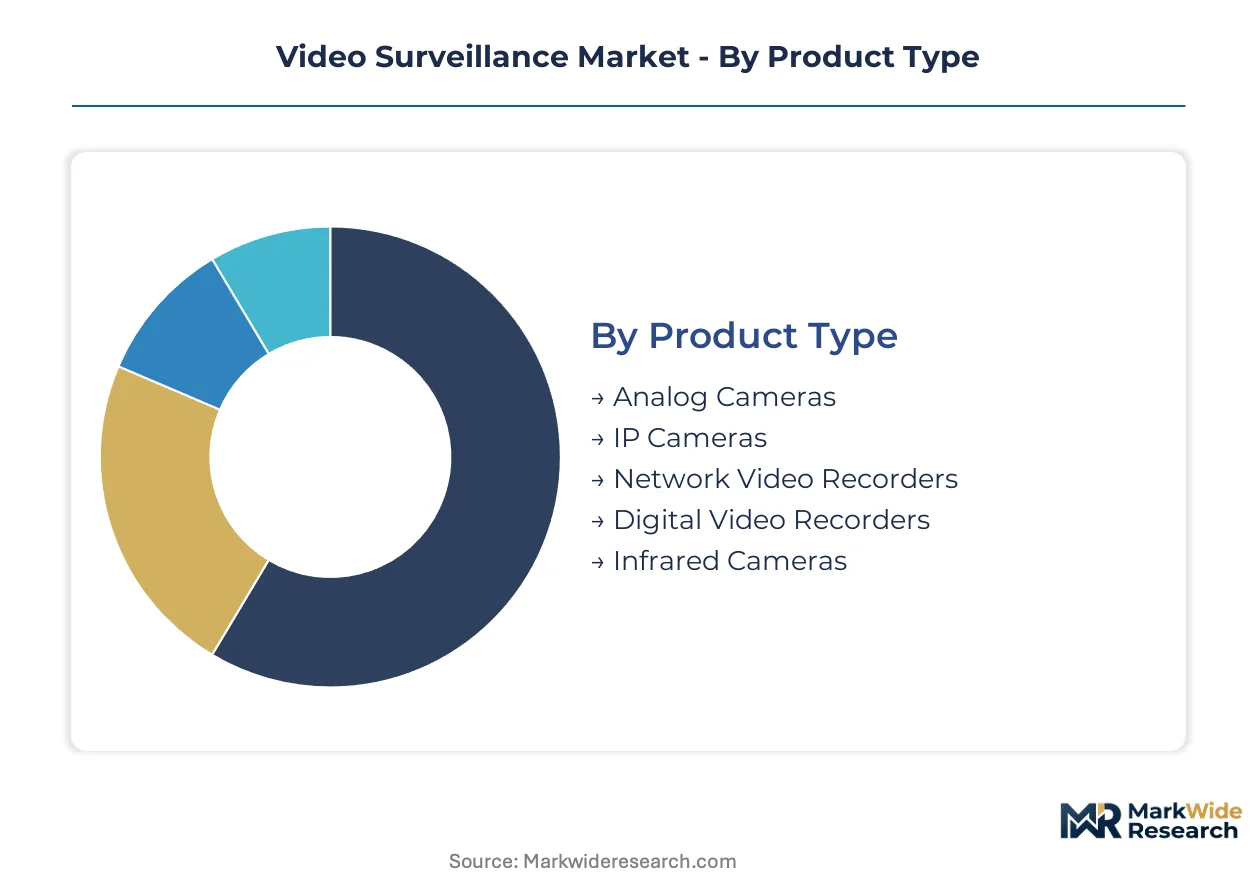
Video surveillance segmentation reveals how certification burdens, edge computing migration, and procurement modality reshape competitive positioning across hardware, software, and service layers. Distinct compliance pathways for biometric analytics versus perimeter monitoring create divergent margin structures within each category.
Product Type:
IP Cameras and Network Video Recorders carry the heaviest certification load, requiring simultaneous FCC authorization for wireless variants, CE marking for European export, and SAMR encryption validation for Chinese government tenders.
- IP Cameras:These devices transmit compressed H.265 video over Ethernet at resolutions up to 4K, enabling centralized management and real-time AI processing. Demand concentrates in Singapore and Dubai smart city deployments where municipal command centers mandate AI-enabled camera density for transportation hub integration.
- Network Video Recorders:NVRs manage multi-channel IP camera feeds with embedded storage arrays and analytics preprocessing capabilities. Procurement accelerates across India's 100 metropolitan smart city missions under the Ministry of Housing and Urban Affairs, where limited legacy analog displacement reduces infrastructure overhaul costs.
- Analog Cameras:Legacy coaxial-based systems persist in cost-constrained emerging economy installations requiring minimal network infrastructure.
- Digital Video Recorders:DVRs continue serving hybrid deployments bridging analog camera fleets with partial IP migration pathways.
- Infrared Cameras:Thermal imaging units deploy silicon carbide substrates for perimeter security in critical infrastructure, though material costs inflate unit economics.
Leading the category by volume: IP Cameras. Expanding most quickly: Network Video Recorders.
Technology:
Cost tier stratification separates premium AI-Based Analytics deployments from commoditized Motion Detection, with Cloud-Based services commanding recurring revenue premiums against capital-intensive Edge Computing hardware.
- AI-Based Analytics:Neural network inference embedded directly into camera firmware enables object classification and anomaly detection without cloud dependency. Critical infrastructure operators in Saudi Arabia and UAE deploy these systems for real-time perimeter breach identification, compressing response latency from seconds to milliseconds.
- Edge Computing:Distributed processing architectures reduce backhaul bandwidth requirements by orders of magnitude while satisfying GDPR biometric retention limits through localized data handling. Municipal procurement in French and German public spaces now mandates human oversight protocols and conformity assessments under the EU AI Act risk-classification framework.
- Cloud-Based:Centralized storage and analytics platforms face European data protection authority constraints on facial template temporal boundaries.
- Thermal Imaging:Advanced sensors requiring wide-bandgap semiconductor materials serve autonomous perimeter monitoring applications.
- Motion Detection:Legacy algorithmic approaches retain share in price-sensitive residential and small commercial installations.
Dominant by deployment scale: Edge Computing. Steepest expansion trajectory: AI-Based Analytics.
Application:
Application selection tracks customer procurement sophistication, with Smart Cities and Critical Infrastructure demanding outcome-based contracting while Commercial Complexes retain traditional capital expenditure models.
- Smart Cities:Integrated command centers linking transportation hubs with critical infrastructure protection require unified platforms with AI-enabled camera density. Singapore's Land Transport Authority and Dubai's Roads and Transport Authority pioneered performance-based contracts where payment correlates with incident detection accuracy rather than equipment installation.
- Critical Infrastructure:Perimeter security for energy, water, and telecommunications facilities deploys sensor fusion combining optical cameras with LiDAR depth-sensing arrays. Operators in Saudi Arabia and UAE prioritize operational expenditure flexibility through sovereign wealth fund-backed service agreements.
- Public Safety:Government security installations in China mandate domestic encryption protocols under SAMR and GB standards, creating technical barriers for foreign equipment.
- Transportation Hubs:Airports and rail terminals balance passenger flow analytics against strict biometric data retention limits imposed by European regulators.
- Commercial Complexes:Retail and office deployments favor open-architecture cameras permitting software-defined feature disablement for jurisdiction-specific compliance.
Highest contract value concentration: Critical Infrastructure. Gaining share fastest: Smart Cities.
End User:
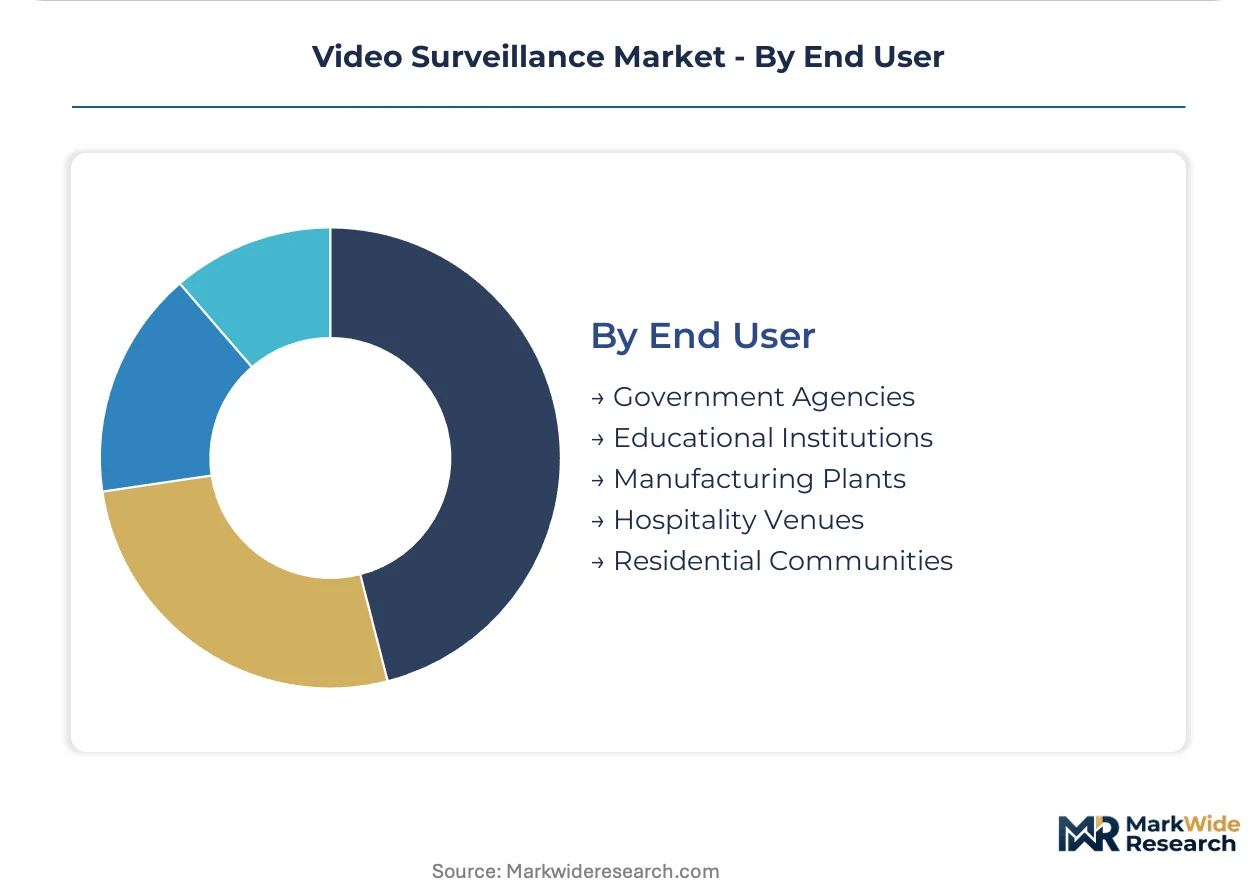
End user segmentation reflects divergent procurement authority structures, with Government Agencies and Educational Institutions bound by public tender regulations while Manufacturing Plants and Hospitality Venues exercise direct commercial negotiation.
- Government Agencies:Chinese urban security modernization programs drive massive state-led safe-city infrastructure investments with domestic encryption mandates. Multi-jurisdiction certification timelines extend time-to-market by 8-14 months for equipment satisfying China's SAMR, EU CE marking, and US FCC requirements simultaneously.
- Educational Institutions:Campus security deployments across K-12 and university systems balance child protection imperatives against privacy-preserving analytics requirements in European jurisdictions.
- Manufacturing Plants:Industrial facilities prioritize thermal imaging and motion detection for perimeter and process monitoring with minimal regulatory compliance overhead.
- Hospitality Venues:Hotels and resorts deploy IP cameras with cloud-based guest flow analytics subject to GDPR biometric restrictions in European operations.
- Residential Communities:Gated developments and apartment complexes represent price-sensitive demand for analog and entry-level IP camera systems.
Largest procurement volume: Government Agencies. Climbing the fastest: Educational Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Punggol Digital District anchors smart city surveillance deployment, with municipal command centers integrating transportation and critical infrastructure networks into unified AI-enabled platforms.
United States
Federal smart city grants and critical infrastructure protection mandates drive procurement of edge-computing camera networks. The FCC governs wireless spectrum allocation for cellular-connected surveillance devices, creating compliance pathways for municipal deployments. New York Metro and Los Angeles County concentrate public safety infrastructure modernization with integrated command center investments.
China
State-led safe-city programs and urban security modernization campaigns fund massive camera network density in metropolitan areas. SAMR and GB standards mandate domestic encryption protocols for government security installations, creating technical barriers for foreign equipment suppliers. Hangzhou and Shenzhen anchor manufacturing clusters where Hikvision and Dahua Technology maintain production scale.
Germany
Industrial facility modernization and transportation hub security drive demand for privacy-preserving edge analytics. The EU AI Act and GDPR impose strict biometric data retention limits and conformity assessment requirements for public space deployments. The Rhine-Ruhr corridor concentrates manufacturing plant surveillance upgrades with emphasis on open-architecture systems.
India
Smart city missions under the Ministry of Housing and Urban Affairs fund integrated surveillance for 100 metropolitan areas with limited legacy analog displacement costs. BIS certification requirements and domestic procurement preferences shape vendor selection for government tenders. Mumbai and Delhi-NCR anchor urban security modernization with municipal command center investments.
United Arab Emirates
Sovereign wealth fund-backed smart city initiatives in Dubai and Abu Dhabi prioritize AI-enabled camera density for transportation and critical infrastructure integration. MOHAP and local regulatory frameworks emphasize operational expenditure flexibility through performance-linked service agreements. Dubai's Roads and Transport Authority pioneered outcome-based contracting where payment correlates with incident detection accuracy.
Video Surveillance Market Key Industry Players
The competitive structure tilts toward diversified technology conglomerates with security divisions and specialized video surveillance pure-plays. Hardware manufacturing concentrates among Asian firms with scale advantages, while Western vendors occupy premium positioning through open-architecture software ecosystems. Two strategic archetypes dominate: vertically integrated camera manufacturers controlling sensor-to-software stacks, and modular platform specialists enabling third-party analytics integration. Competitive moves center on edge AI firmware development partnerships and municipal service contract restructuring from capital sales to subscription models.
Among Chinese manufacturers, Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology Co., Ltd. exemplify scale-driven archetypes with integrated production capabilities. Axis Communications AB represents the open-architecture specialist tier, occupying premium positioning in Western enterprise accounts through software-defined feature modularity. These three anchors illustrate the geographic bifurcation between Asia-Pacific manufacturing scale and European-North American premium software integration.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| Axis Communications AB |
| Hanwha Vision Co., Ltd. |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Bosch Security Systems GmbH |
| Teledyne FLIR LLC |
| Zhejiang Uniview Technologies Co. |
| Others |
Cost & Logistics Intelligence
Silicon carbide substrate pricing indices cascade through thermal imaging camera manufacturing, compressing margins at the premium tier while H.265 codec licensing fees differentiate mid-range IP camera positioning against economy analog alternatives.
Pricing Analysis
Outcome-linked municipal contracts anchor value-based pricing for smart city deployments, where Singapore's Land Transport Authority and Dubai's Roads and Transport Authority pay for incident detection accuracy rather than hardware installation. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled edge cameras with EU AI Act conformity assessments from basic motion detection units. Pricing pressure stems from CMOS sensor supply concentration among Taiwanese and South Korean foundries, with government agencies showing least price sensitivity due to sovereign security mandates while residential communities drive aggressive cost compression.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Taipei, and Seoul orchestrate hub-and-spoke patterns for camera OEMs serving Asian manufacturing clusters and Western enterprise accounts. Image sensor fabrication concentrates in Taiwan and South Korea, while lens assembly and final integration anchor in China's Yangtze River Delta and Pearl River Delta manufacturing corridors. Supply chain risk centers on single-source vulnerability for advanced CMOS sensors subject to geopolitical semiconductor export controls. Distribution runs through authorized systems integrators for government and critical infrastructure verticals, with direct e-commerce channels penetrating SMB and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The video surveillance market operates as a cost-of-compliance story where the EU AI Act's high-risk system classification creates a barrier-to-entry moat for manufacturers with established conformity assessment infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into edge AI chip design partnerships, reducing dependency on external neural network accelerator suppliers. Prioritize CE marking and SAMR certification maintenance as emerging Chinese manufacturers without EU technical documentation capabilities face 8-14 month time-to-market extensions. Channel control through municipal service contract restructuring from capital sales to subscription models protects recurring revenue against price-aggressive hardware competitors.
For New Entrants and Emerging Players: Begin with India's 100 metropolitan smart city missions under the Ministry of Housing and Urban Affairs, where limited legacy analog displacement costs reduce infrastructure overhaul barriers and domestic procurement preferences favor local integrators. Target educational institutions across European jurisdictions with privacy-preserving edge analytics that satisfy GDPR biometric retention limits without cloud dependency. A software-defined feature disablement go-to-market angle permits jurisdiction-specific compliance adaptation without hardware SKU proliferation.
For Investors and Strategic Acquirers: The window for entry favors modular platform specialists with open-architecture software ecosystems over vertically integrated hardware manufacturers facing margin compression. Long-term viability hinges on edge AI firmware development capabilities and municipal outcome-based contracting relationships. The signal to watch is EU AI Act enforcement intensity against biometric surveillance deployments in French and German public spaces, which would accelerate demand for compliant analytics pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Development Partnership | Reduces latency for Saudi Aramco perimeter monitoring while satisfying GDPR localization mandates. |
| Outcome-Based Municipal Service Contract | Aligns revenue with incident detection accuracy for Singapore Land Transport Authority deployments. |
| Multi-Jurisdiction Certification Investment | Accelerates time-to-market for simultaneous SAMR, CE marking, and FCC authorization compliance. |
| Sensor Fusion Product Line Extension | Creates LiDAR-video convergence category for UAE critical infrastructure autonomous monitoring. |
| Privacy-Preserving Analytics Platform | Enables EU AI Act high-risk system deployment without centralized facial recognition databases. |
Research Approach
Document review covered customs trade data for camera component imports, EU AI Act technical documentation requirements, and FCC equipment authorization databases, complemented by interviews with municipal procurement officers, critical infrastructure security directors, systems integration specialists, and edge AI firmware engineers. Secondary validation drew from SAMR encryption standard filings, BIS certification records for Indian smart city tenders, and Dubai Roads and Transport Authority performance contract disclosures. Bottom-up unit economics modeling triangulated against top-down municipal budget allocation analysis across the projection horizon.
Cross-referencing historical replacement cycle data with panel input from OEM product planning executives established the analytical framework. Segmentation dimensions modeled include product type tier, technology deployment architecture, application procurement sophistication, and end-user regulatory binding intensity. CAGRs were derived through iterative convergence of shipment volume trajectories and average selling price evolution. Industry-specific forecast inputs incorporated H.265 codec adoption curves and edge AI processor availability timelines.
Underlying measurement precision varies by segment; government agency procurement carries tighter precision than hospitality venue demand forecasting. Outputs reflect assumptions around EU AI Act enforcement consistency and semiconductor supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Canada Video Surveillance Market