
 United States Positive Displacement Pumps Market | 2026-2036
United States Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
United States Positive Displacement Pumps Market Intelligence
The gap between premium engineered pumps and commodity units is shifting wider as end-users prioritize total lifecycle cost over upfront price. Flowserve Corporation dominates severe-service applications in upstream oil and gas with proprietary sealing technologies. IDEX Corporation anchors the sanitary pump segment through its specialized food and pharmaceutical product lines.
Positive displacement pumps trap fixed fluid volumes within cavities and mechanically displace them, achieving flow rates proportional to drive speed with typical viscosities from water-like fluids to million-centipoise slurries. These machines serve critical functions in metering, transfer, and lubrication across process industries where flow precision matters more than volume throughput. Diaphragm pumps lead the product type landscape due to their leak-free operation and compatibility with abrasive or hazardous media. Gear pumps sustain strong positions in lubrication and hydraulic power applications where steady pulse-free flow outweighs initial cost concerns.
The EPA enforces Clean Water Act standards that mandate precise chemical dosing in municipal water treatment, directly elevating demand for metering-grade positive displacement technology. OSHA workplace exposure limits and FDA sanitary requirements for food and pharmaceutical contact surfaces shape material selection and validation protocols for pump manufacturers. Stakeholders must monitor how state-level decarbonization mandates in California and New York reshape energy efficiency specifications and drive electric technology substitution across installed pump bases.
Market Dynamics
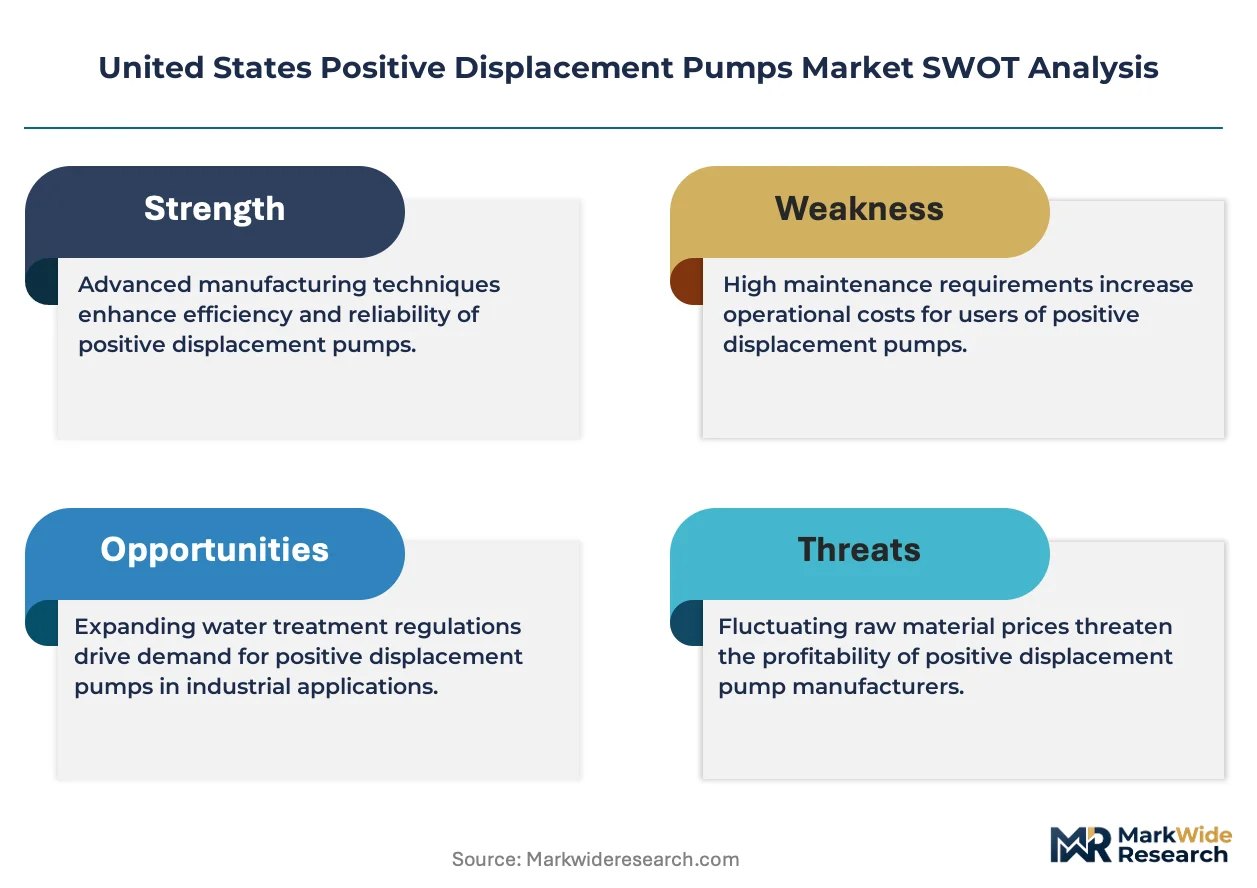
The US positive displacement pumps market is experiencing structural recalibration as municipal water utilities accelerate capital replacement cycles under intensifying EPA enforcement. This regulatory pressure is compressing procurement timelines and favoring suppliers with pre-validated metering technologies and established compliance documentation.
Growth Catalysts
- EPA Clean Water Act enforcement:Tightening discharge standards across Midwest and Southeast municipal systems are mandating precision chemical dosing infrastructure upgrades.
- Petrochemical cluster expansion:Texas and Louisiana Gulf Coast facilities are procuring heavy-duty positive displacement pumps for high-viscosity hydrocarbon transfer and injection applications.
- Food-grade stainless steel adoption:FDA sanitary requirements for pharmaceutical and dairy contact surfaces are elevating specification thresholds for diaphragm and lobe pump configurations.
Market Restraints
- Specialized alloy cost volatility:Duplex stainless steel and Hastelloy price swings compress margins on severe-service pump configurations for upstream oil and gas.
- Domestic casting capacity concentration:Foundry consolidation in Ohio and Pennsylvania creates single-source vulnerability for large pump housings above 500 horsepower.
- Centrifugal pump substitution:Advances in magnetic drive centrifugal technology threaten positive displacement share in low-viscosity chemical transfer below 100 centipoise.
Strategic Opportunities
- California decarbonization mandates:State-level electrification requirements for industrial equipment are creating retrofit demand for variable-frequency drive compatible positive displacement systems.
- Hydrogen economy infrastructure:Emerging high-pressure hydrogen dispensing and pipeline injection applications favor diaphragm and piston pump technologies with metal-seated sealing.
- Direct-to-utility digital channels:Pump OEMs are bypassing traditional distribution to capture municipal specification authority through online configuration tools and lifecycle cost calculators.
Industry Challenges
- Specialized sealing technician scarcity:Expertise in mechanical seal specification for abrasive slurry service is concentrating among retiring workforce cohorts in Houston and Chicago industrial corridors.
- OSHA process safety management compliance:Documentation burden for positive displacement pumps in hazardous chemical service extends sales cycles by four to eight months for new installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Positive Displacement Pumps Market |
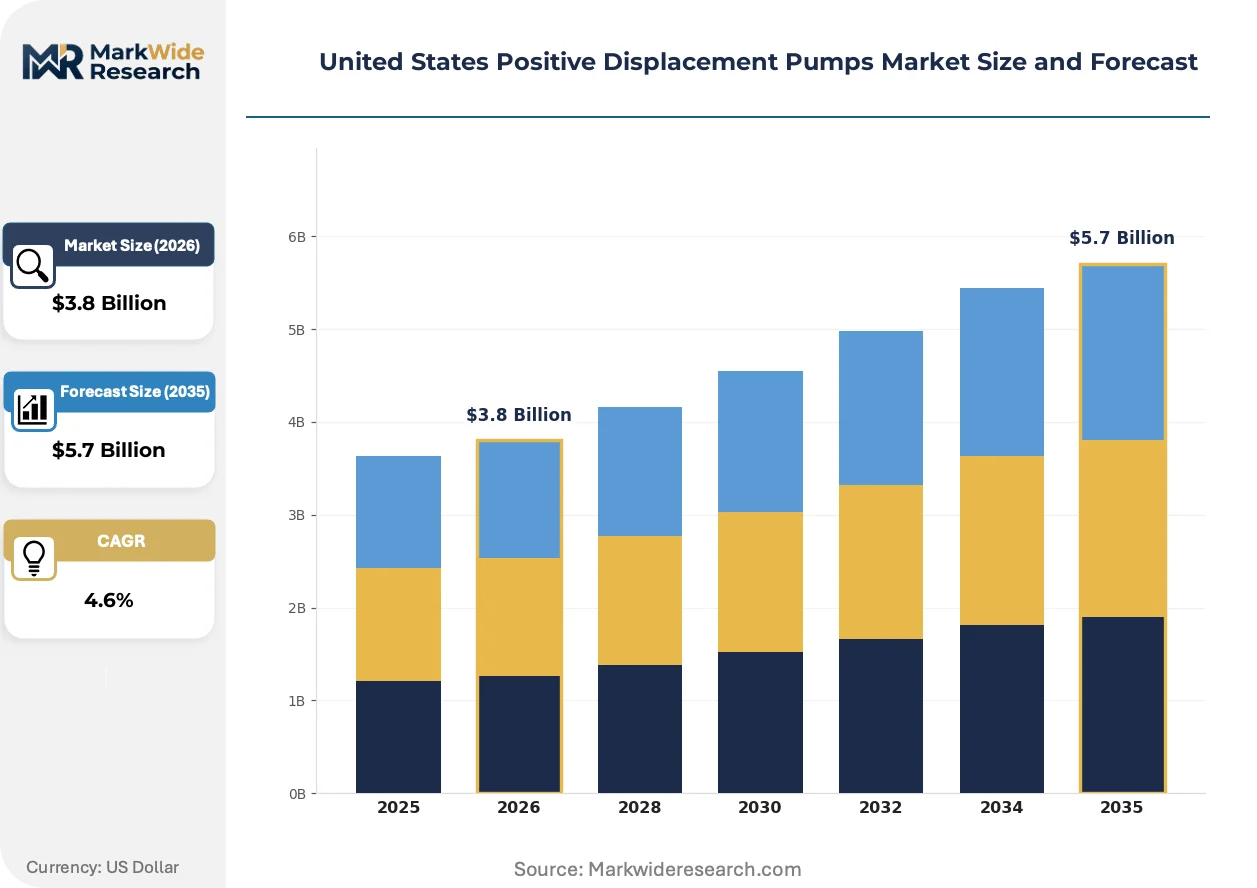
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Screw Pumps, Piston Pumps End User: Oil & Gas, Water Treatment, Food & Beverage, Pharmaceuticals Technology: Electric, Pneumatic, Hydraulic, Manual Application: Transfer, Metering, Recirculation, Lubrication |
| Companies Covered | Ingersoll Rand Incorporated, SPX FLOW Incorporated, Grundfos Holding A/S, Flowserve Corporation, Alfa Laval AB, IDEX Corporation, Dover Corporation, Sulzer Ltd, Xylem Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Positive Displacement Pumps Market Strategic Shifts & Innovations
Smart pump technologies and predictive maintenance architectures are redefining value capture in the US positive displacement pumps market. Equipment suppliers are embedding sensors and edge computing to shift revenue models from hardware sales toward performance-based service agreements.
Advanced polymer composites for diaphragm and sealing elements is absorbing market share from traditional elastomer configurations in abrasive chemical service. Petrochemical facilities in Louisiana and Texas are specifying PTFE-overmolded diaphragms for hydrofluoric acid transfer. This material transition is compressing maintenance intervals from quarterly to annual cycles while extending pump rebuild horizons.
The EPA's Lead and Copper Rule revisions are mandating orthophosphate dosing infrastructure across aging municipal distribution networks. Water utilities in Michigan, Ohio, and Illinois are procuring precision metering pumps with automated calibration systems. Diaphragm pump OEMs with pre-certified NSF/ANSI 61 materials documentation are capturing specification authority in accelerated procurement windows.
Lifecycle cost analysis has displaced upfront capital expenditure as the dominant municipal procurement criterion. Engineering firms in California and New York are embedding total cost of ownership models into bid evaluation matrices. Pump suppliers with verified energy consumption data and documented mean-time-between-failure statistics are winning multi-year framework agreements with regional water authorities.
United States Positive Displacement Pumps Market Segmentation
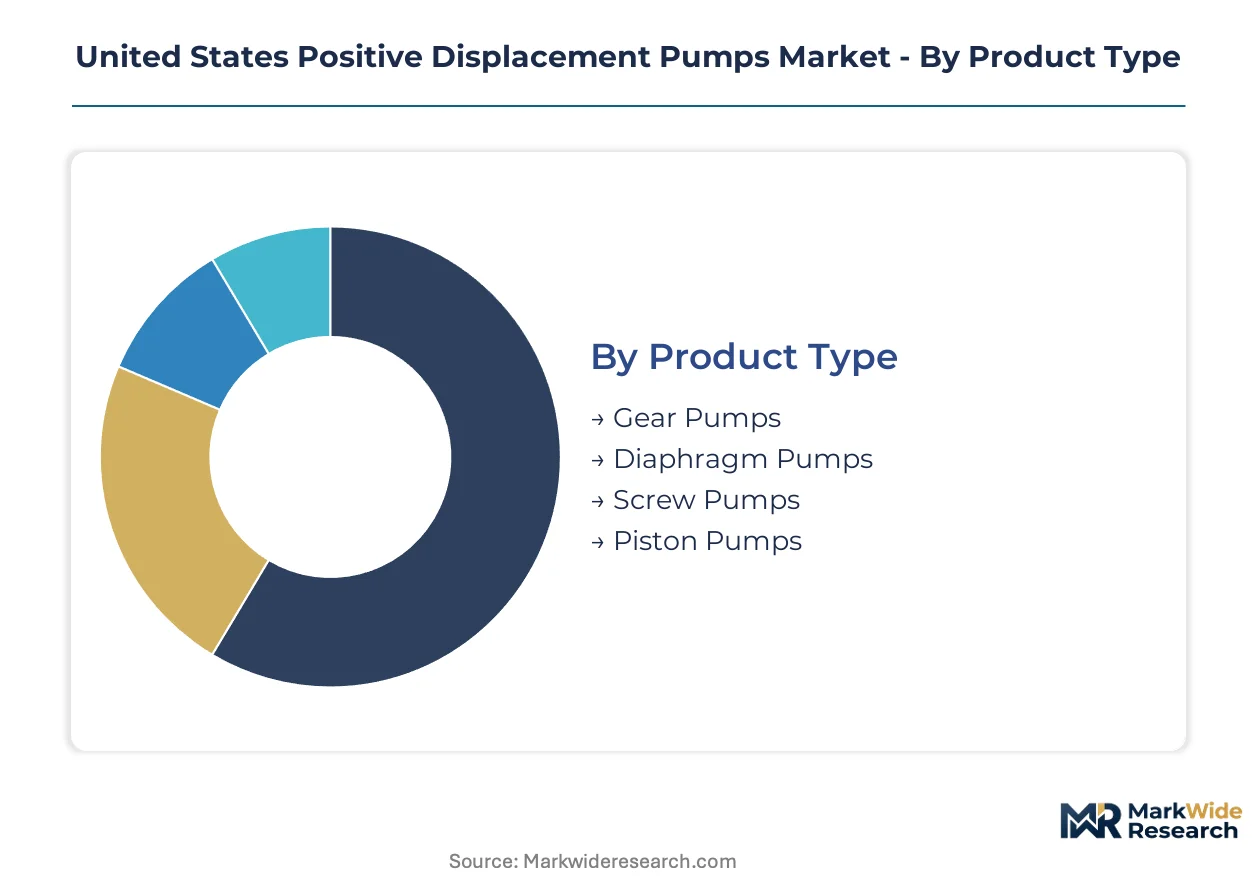
Segmentation in the United States positive displacement pumps market reveals how regulatory certification requirements fragment procurement pathways. Water treatment utilities demand NSF/ANSI 61 validation, while oil and gas operators prioritize API 674/675 compliance for severe service.
Product Type:
Diaphragm and gear pumps carry distinct certification burdens—diaphragm configurations require FDA or NSF validation for sanitary contact, while gear pumps face API and ATEX-equivalent standards for hydrocarbon service.
- Diaphragm Pumps:Leak-free positive displacement through reciprocating elastomer or PTFE membranes. Municipal water utilities in Michigan and Ohio specify these for orthophosphate dosing under EPA Lead and Copper Rule mandates. FDA-compliant PTFE-overmolded diaphragms are displacing traditional elastomers in pharmaceutical transfer lines.
- Gear Pumps:Intermeshing rotors deliver pulse-free flow for lubrication and hydraulic power. Texas and Louisiana petrochemical clusters specify heavy-duty external gear configurations for million-centipoise crude oil transfer. API 674 compliance separates premium engineered units from commodity imports in upstream procurement.
- Screw Pumps:Single or twin-screw architectures excel in multiphase hydrocarbon handling. Progressive cavity variants dominate wastewater sludge transfer across Midwest municipal systems.
- Piston Pumps:High-pressure reciprocating action suits metering and injection duties. Hydrogen economy infrastructure in California is specifying metal-seated piston pumps for 700-bar dispensing applications.
Diaphragm pumps sit at the top of the volume ranking, with piston pumps climbing the fastest on hydrogen infrastructure demand.
End User:
Oil and gas operators command premium pricing tiers through severe-service specifications, while food and pharmaceutical end-users impose margin pressure via consolidated multi-site procurement frameworks.
- Oil & Gas:Upstream production, midstream transfer, and downstream refining applications. Gulf Coast facility expansion in Texas and Louisiana drives procurement of duplex stainless steel pumps for sour crude service. OSHA process safety management documentation extends sales cycles substantially.
- Water Treatment:Municipal and industrial chemical dosing, sludge handling, and filtration. EPA Clean Water Act enforcement across Midwest and Southeast utilities is compressing procurement timelines for metering-grade infrastructure. NSF/ANSI 61 pre-certification now functions as a table-stakes requirement.
- Food & Beverage:Sanitary transfer of dairy, beverage, and viscous food products. 3A sanitary standards and FDA 21 CFR compliance govern material selection for diaphragm and lobe pump configurations.
- Pharmaceuticals:Precision metering of active pharmaceutical ingredients and biologics. ASME BPE validation and USP Class VI material certification elevate specification thresholds above standard industrial grades.
Water treatment commands the largest installed base, with pharmaceuticals expanding most quickly on biologics manufacturing growth.
Technology:
California and New York state electrification mandates are reshaping technology mix, compressing hydraulic and pneumatic share in favor of variable-frequency drive compatible electric systems.
- Electric:AC induction and permanent magnet motors with VFD compatibility. California decarbonization mandates for industrial equipment are accelerating retrofit demand across legacy installed bases. NEMA Premium efficiency ratings separate specification tiers.
- Pneumatic:Compressed air-driven diaphragm and piston configurations. Explosion-proof operation without electrical classification drives residual demand in hazardous chemical service.
- Hydraulic:Fluid power transmission for high-force applications. Mobile equipment and offshore platforms sustain niche demand despite electrification headwinds.
- Manual:Hand-operated pumps for backup and remote service. Water treatment plant emergency chemical dosing maintains minimal procurement volume.
Electric systems dominate new installations, with pneumatic configurations retaining share in hazardous classified locations.
Application:
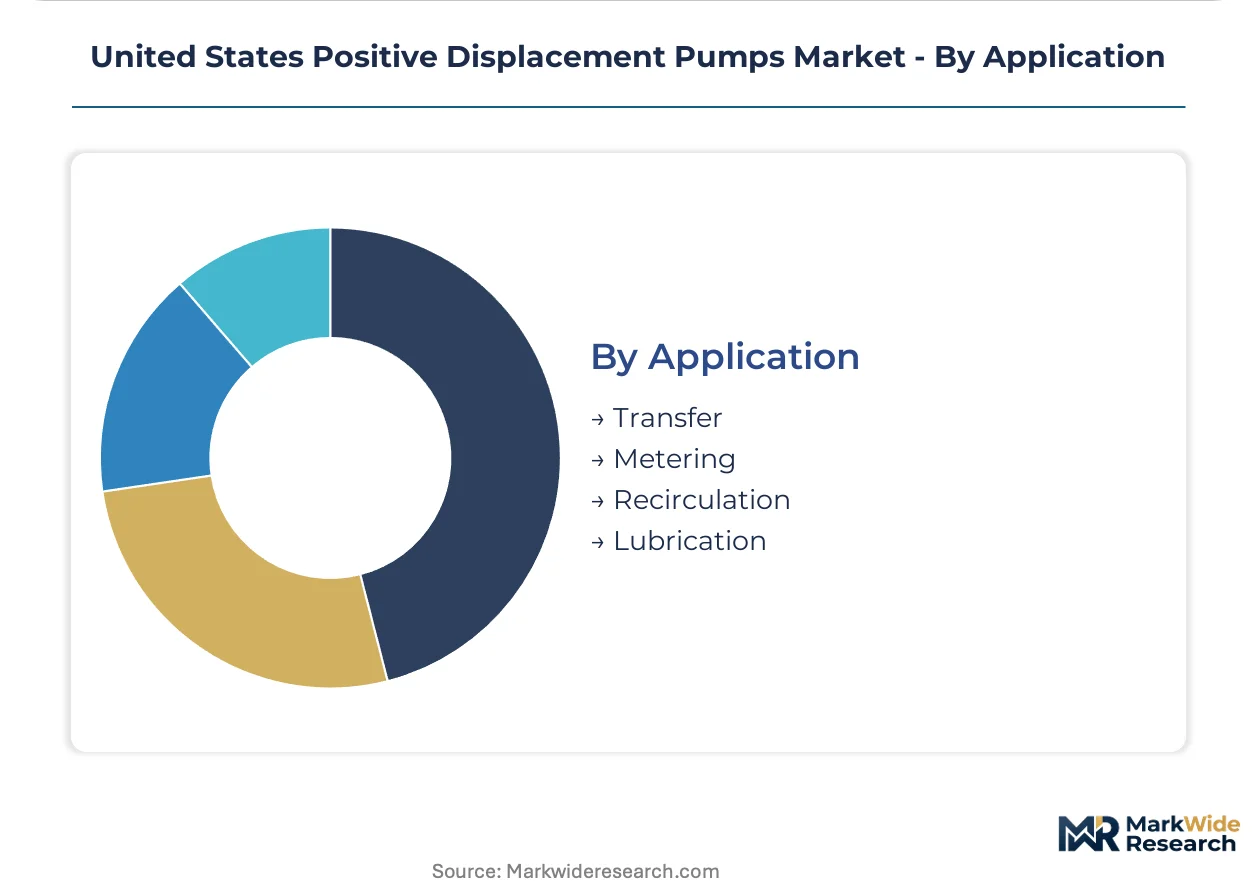
Metering applications concentrate margin capture through precision engineering requirements, while transfer applications compete on lifecycle cost optimization.
- Metering:Precision volume delivery for chemical dosing and additive injection. EPA discharge standard enforcement is elevating specification authority for calibrated diaphragm and piston pump systems. Automated calibration documentation now features in municipal bid evaluations.
- Transfer:Bulk fluid movement between process stages. Gear and screw pump configurations compete on total cost of ownership metrics across petrochemical and food processing installations.
- Recirculation:Continuous loop circulation for temperature control and filtration. Cooling water and hydraulic power units sustain steady replacement demand.
- Lubrication:Oil delivery to rotating equipment bearings and gearboxes. Positive displacement gear pumps maintain entrenched positions against centrifugal alternatives in high-viscosity service.
Transfer applications generate the highest unit volumes, with metering gaining share fastest on regulatory precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sealing technicians and pump engineers concentrate in Houston and Chicago industrial corridors, anchoring service capabilities for severe-service applications. This workforce distribution shapes procurement patterns and aftermarket support networks across domestic manufacturing clusters.
Texas Gulf Coast
Petrochemical facility expansion drives heavy-duty positive displacement pump procurement for high-viscosity hydrocarbon transfer. EPA Clean Water Act enforcement tightens discharge standards for coastal refineries. The Houston Ship Channel complex sustains demand for duplex stainless steel pumps in sour crude service applications.
Louisiana Chemical Corridor
Hydrofluoric acid transfer operations specify PTFE-overmolded diaphragm pumps for extended maintenance intervals. OSHA process safety management documentation requirements compress supplier qualification timelines. Baton Rouge and Lake Charles industrial zones anchor procurement for severe-service chemical injection systems.
California
State-level decarbonization mandates accelerate retrofit demand for variable-frequency drive compatible electric pump systems. The California Air Resources Board electrification requirements reshape industrial equipment specifications. Los Angeles and Bay Area water utilities procure precision metering infrastructure under accelerated procurement windows.
Midwest Manufacturing Belt
Foundry consolidation in Ohio and Pennsylvania creates single-source vulnerability for large pump housings above 500 horsepower. The EPA Lead and Copper Rule revisions mandate orthophosphate dosing infrastructure across aging municipal networks. Michigan, Ohio, and Illinois water authorities specify NSF/ANSI 61 pre-certified diaphragm pumps.
Southeast Utilities
Municipal water treatment capacity expansion concentrates procurement for chemical dosing and sludge handling equipment. EPA enforcement intensifies across Florida, Georgia, and Carolinas municipal systems. Atlanta and Charlotte metropolitan utilities compress replacement cycles for metering-grade positive displacement technology.
United States Positive Displacement Pumps Market Key Industry Players
Top-tier vendors anchor the premium engineered segment, while commodity fabricators compete on upfront price for standardized applications. The vendor base stratifies across three tiers differentiated by certification depth and lifecycle documentation capabilities. Strategic archetypes include severe-service specialists with proprietary sealing portfolios, sanitary pump providers with FDA validation infrastructure, and diversified industrial conglomerates with captive distribution networks. Competitive moves concentrate on M&A for technology access and direct-to-utility digital channel development.
Within the diversified industrial tier, Ingersoll Rand Incorporated and Dover Corporation represent archetypes of scale-driven manufacturers with broad pump portfolios spanning multiple end-use verticals. Flowserve Corporation anchors the severe-service specialist position, exemplifying vendors that capture specification authority through API compliance documentation and aftermarket service networks. IDEX Corporation occupies a position within the sanitary and precision metering segment, reflecting how FDA and NSF certification capabilities function as competitive moats in regulated end markets.
| Leading Market Players |
|---|
| Ingersoll Rand Incorporated |
| SPX FLOW Incorporated |
| Grundfos Holding A/S |
| Flowserve Corporation |
| Alfa Laval AB |
| IDEX Corporation |
| Dover Corporation |
| Sulzer Ltd |
| Xylem Inc |
| Others |
Cost & Logistics Intelligence
Captive foundry integration in Ohio and Pennsylvania anchors domestic pricing power for large pump housings above 500 horsepower. This backward consolidation into specialized casting capacity insulates premium engineered tiers from commodity import pressure while concentrating supplier leverage in the severe-service segment.
Pricing Analysis
The bundled-vs-unbundled service split separates specification tiers across the US positive displacement pumps landscape. Three-tier pricing structure across premium, standard, and economy levels differentiates API 674-compliant severe-service units from NSF/ANSI 61 municipal grades and unvalidated commodity imports. Certification grade and aftermarket service bundling drive price differentiation between tiers. Cost compression in economy-grade gear pumps is intensifying because magnetic drive centrifugal technology erodes share in low-viscosity transfer below 100 centipoise. Municipal water utilities exhibit the highest price sensitivity due to compressed procurement timelines under EPA enforcement, while Gulf Coast petrochemical operators prioritize lifecycle documentation over upfront capital outlay.
Supply Chain Analysis
Warehouse-distribution layer concentration in Chicago and Houston industrial corridors shapes aftermarket parts availability and emergency service response. Foundry capacity draws from Ohio, Pennsylvania, and Indiana for large ductile iron and duplex stainless steel castings. Specialized alloy feedstock hinges on nickel and molybdenum price exposure from Canadian and Australian mining operations. Single-source vulnerability in domestic casting above 500 horsepower creates structural risk for severe-service pump lead times. Distribution runs through authorized service networks and direct-to-utility digital channels that bypass traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US positive displacement pumps market reads as a late-cycle quality story as municipal procurement shifts toward total lifecycle cost frameworks and NSF/ANSI 61 pre-certification requirements.
For Market Incumbents: Cement specification authority in severe-service oil and gas by deepening proprietary sealing technology portfolios against magnetic drive centrifugal substitution threats. Expand captive foundry capacity in Ohio and Pennsylvania to defend margin position against alloy cost volatility. Prioritize API 674 compliance documentation infrastructure to compress sales cycles in upstream procurement. For New Entrants and Emerging Players: Predictive maintenance software integration offers a technology-first wedge into municipal water utility retrofit demand under California and New York electrification mandates. Target Midwest orthophosphate dosing infrastructure expansion as the most penetrable application segment. Pursue direct-to-utility digital specification tools as the primary go-to-market angle to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Roll-up economics work for sanitary pump specialists with FDA 21 CFR validation infrastructure because pharmaceutical and dairy contact surface requirements create certification moats that resist commoditization. Five-to-ten year viability centers on biologics manufacturing growth and hydrogen economy infrastructure buildout. Monitor California Air Resources Board electrification mandate enforcement velocity as the critical inflection signal for variable-frequency drive retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Foundry Capacity | Captive casting for duplex stainless steel housings insulates margin from nickel price volatility in severe-service configurations. |
| Direct-to-Utility Digital Channel Development | Online configuration tools with lifecycle cost calculators capture municipal specification authority from traditional distribution networks. |
| Predictive Maintenance Platform Integration | Sensor-enabled smart pumps shift revenue models from hardware sales toward performance-based service agreements with water utilities. |
| NSF/ANSI 61 Pre-Certification Investment | Pre-validated materials documentation compresses procurement timelines for EPA Lead and Copper Rule compliance mandates. |
| Hydrogen Infrastructure Technology Licensing | Metal-seated piston pump designs for 700-bar dispensing applications capture emerging California hydrogen economy procurement. |
Research Approach
Coverage spans Texas Gulf Coast, Louisiana Chemical Corridor, California, Midwest Manufacturing Belt, and Southeast Utilities, with primary inputs from each. The approach combines structured interviews with plant engineers, municipal procurement directors, aftermarket service heads, and OEM specification teams with secondary validation from EPA enforcement databases, FERC industrial load filings, and ACC regional capacity reports. Bottom-up unit demand modeling triangulates against top-down value estimates derived from utility capital expenditure disclosures and petrochemical facility expansion announcements.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models product type, end-use vertical, technology architecture, and application duty cycle as core segmentation dimensions. CAGRs derive from regression against industrial production indices, utility capital formation rates, and regulatory enforcement intensity metrics. Hydrogen infrastructure deployment curves and state-level electrification mandate compliance timelines function as scenario-weighted inputs.
The model holds under stable EPA enforcement intensity and continued petrochemical cluster expansion; deviation in alloy price volatility or centrifugal technology substitution rates would shift volume trajectories. Forecasts reflect documented assumptions regarding municipal replacement cycle acceleration and foundry capacity utilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Southeast Asia Industrial Pumps Market