
 Canned Motor Pumps Market | 2026-2036
Canned Motor Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Motor Pumps Market Analysis
China is narrowing the historical supply gap in canned motor pump manufacturing through capacity additions in Jiangsu and Zhejiang provinces. KSB SE & Co. KGaA leverages its German engineering base to dominate high-pressure chemical transfer specifications. TEIKOKU ELECTRIC MFG. CO., LTD. anchors Asian nuclear cooling applications with JIS-certified designs. HERMETIC-Pumpen GmbH specializes in zero-leakage systems for European pharmaceutical and fine-chemical clients.
Canned motor pumps integrate a hermetically sealed motor and pump assembly where the rotor operates within the process fluid, eliminating shaft seals and enabling leak-free operation for hazardous, corrosive, or high-purity liquids. Standard units handle temperatures from minus 120°C to 400°C and differential pressures exceeding 200 bar depending on stator liner material and coolant circuit design. Horizontal pumps occupy the largest installed base in chemical processing and oil transfer duties where floor-mounted maintenance access reduces downtime. Submersible pumps represent the fastest-expanding category as offshore platform operators and underground storage facilities adopt immersed motor configurations to eliminate surface seal maintenance and reduce footprint.
EPA leak detection and repair standards under the Clean Air Act push US refineries toward sealless pump architectures, while REACH chemical safety obligations in Europe favor stator materials free from restricted substances. China's MEE enforces volatile organic compound containment rules that accelerate domestic canned motor adoption in coastal petrochemical clusters. Stakeholders must weigh regional certification timelines against localized service network depth when allocating capital between established European suppliers and expanding Asian manufacturers.
Market Dynamics
Sealed-system architecture mandates from environmental regulators are compressing demand for conventional centrifugal pumps across chemical processing, nuclear cooling, and pharmaceutical transfer applications. Procurement committees now weight fugitive emissions compliance above upfront capital expenditure in vendor selection criteria.
Growth Catalysts
- EPA Clean Air Act enforcement:US refineries face escalating penalties for volatile organic compound leakage, redirecting maintenance budgets toward sealless pump retrofits.
- China's coastal petrochemical clusters:State-directed refinery upgrades in Jiangsu and Zhejiang provinces absorb premium vertical canned motor units for high-temperature hydrocarbon transfer.
- Stator liner material advances:Ceramic-composite and PEEK-based designs extend temperature tolerance beyond 400°C, unlocking molten salt and thermal oil circulation in concentrated solar plants.
Market Restraints
- Specialized foundry capacity concentration:Hastelloy and titanium castings for corrosion-resistant pump housings concentrate among German and Japanese suppliers, creating 16-24 week lead times.
- Copper and rare-earth magnet cost volatility:Neodymium price swings directly compress motor manufacturing margins, forcing quarterly contract renegotiations.
- Mechanical seal substitution in low-risk fluids:Water treatment and food-grade applications retain magnetic drive pumps or double-mechanical-seal architectures where leakage tolerance permits.
Strategic Opportunities
- Hydrogen liquefaction infrastructure:Minus 253°C liquid hydrogen transfer demands cryogenic-rated canned motor pumps with vacuum-insulated stator jackets, a specification category with limited qualified vendors.
- Carbon capture solvent circulation:Amine-based post-combustion capture systems require leak-free pumps for corrosive alkanolamine solutions at 120-bar discharge pressures.
- Small modular reactor deployment:Factory-built nuclear units in the US and UK specify standardized coolant circulation packages, favoring suppliers with N-Stamp and ASME III certifications.
Industry Challenges
- Stator winding impregnation expertise:Hermetic motor manufacturing requires vacuum-pressure impregnation technicians with 10-plus-year experience profiles, a workforce segment with accelerating retirement rates.
- Multi-jurisdiction certification sequencing:Nuclear-grade pumps require ASME, RCC-M, and KTA approvals with non-overlapping test protocols, extending commercialization timelines by 18-30 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Motor Pumps Market |
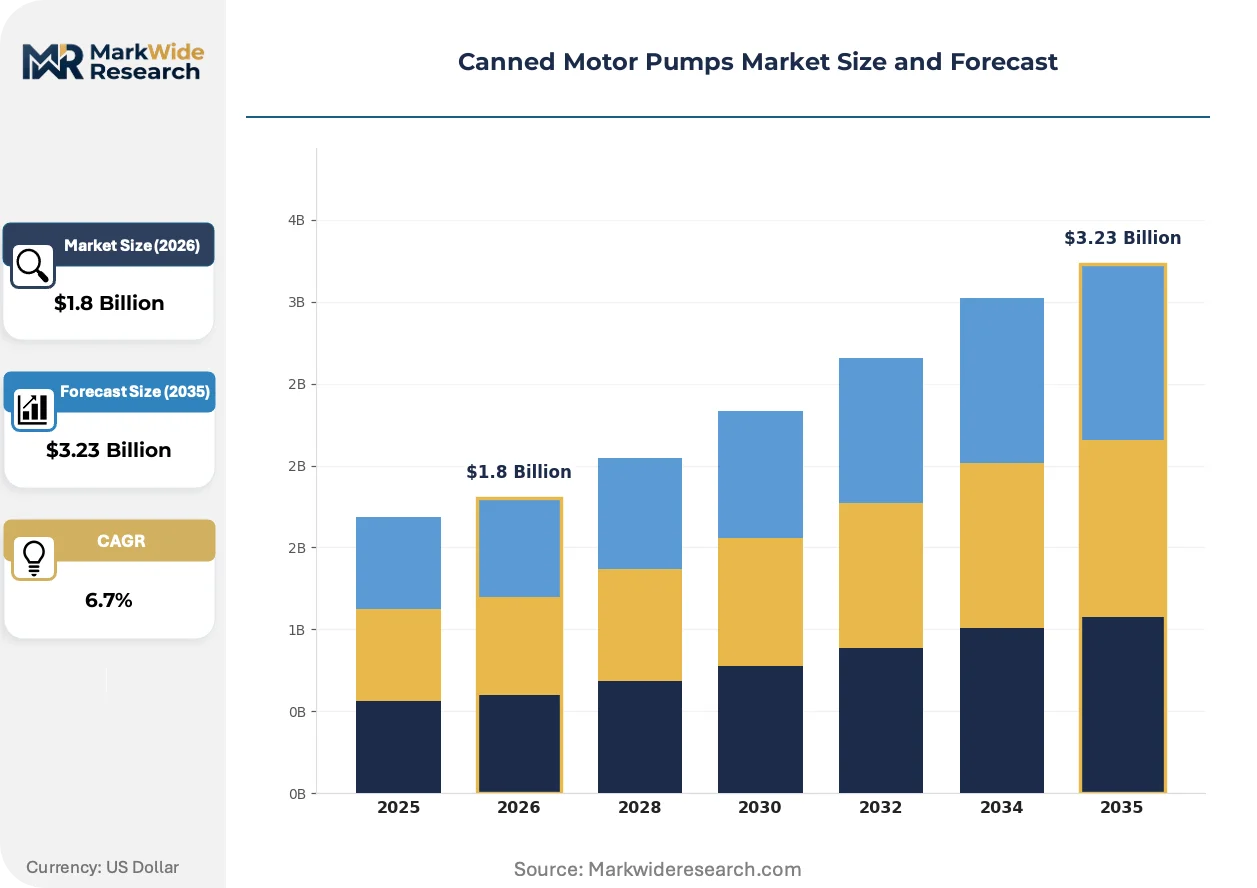
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Pumps, Horizontal Pumps, Submersible Pumps, Screw Pumps End User: Oil & Gas, Chemical Processing, Water Treatment, Power Generation Installation: Onshore, Offshore, Utility, Industrial Application: Transfer, Circulation, Recirculation, Booster |
| Companies Covered | KSB SE & Co. KGaA, Flowserve Corporation, TEIKOKU ELECTRIC MFG. CO., LTD., Ebara Corporation, Sulzer AG, Nikkiso Co., Ltd., Kirloskar Brothers Limited, Xylem Inc., HERMETIC-Pumpen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Motor Pumps Market Emerging Trajectories
Digital condition monitoring and predictive maintenance architectures are embedding sensor arrays directly into stator housings and bearing cartridges. Equipment suppliers now compete on data-analytics integration depth rather than purely hydraulic performance specifications.
Silicon carbide (SiC) power electronics are migrating from premium nuclear applications toward mainstream chemical processing pumps. KSB and HERMETIC-Pumpen now specify SiC variable frequency drives for motors above 200 kW, cutting switching losses by 40 percent compared to IGBT equivalents. The technology is migrating from high-reliability installations to cost-sensitive refinery units as module prices decline.
REACH chemical safety obligations in Europe are restricting per- and polyfluoroalkyl substances in stator liner materials. ECHA substance evaluation timelines are forcing reformulation of PTFE-based isolation barriers toward ceramic or PEEK alternatives. German pharmaceutical manufacturers now require full material disclosure certificates extending to sub-component suppliers.
Integrated service contracts are displacing transactional spare-parts procurement in offshore platform operations. Charterers in the North Sea and Gulf of Mexico now specify availability-based payment structures where pump vendors retain ownership and liability for continuous runtime. Norwegian platform operators pioneered this model; Brazilian pre-salt developments are adopting comparable terms.
Canned Motor Pumps Market Segmentation
Canned motor pump architectures vary dramatically across pressure ratings, thermal envelopes, and fluid compatibility requirements. Procurement patterns diverge sharply between mature chemical processing specifications and emerging hydrogen liquefaction demands.
Product Type:
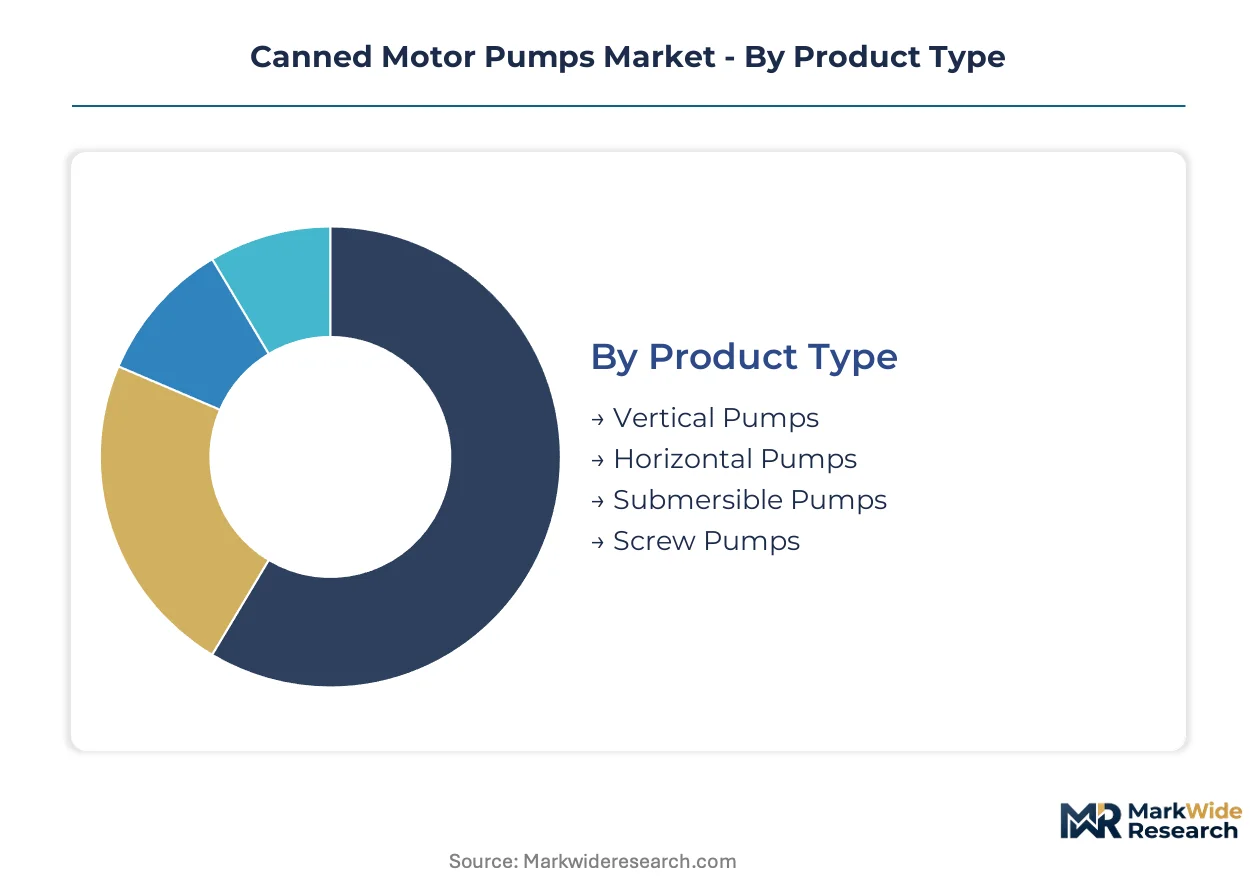
Mature horizontal configurations dominate installed base economics while submersible designs emerge from offshore platform specifications.
- Vertical Pumps:Inline motor-pump assemblies with thrust bearings handling axial loads through the process fluid column. Jiangsu and Zhejiang refinery upgrades absorb premium units for high-temperature hydrocarbon transfer under China's MEE volatile organic compound containment rules.
- Horizontal Pumps:Floor-mounted configurations with split-case access for bearing and stator maintenance. German chemical processors specify these for REACH-compliant fugitive emissions control in continuous-duty aromatic transfer loops.
- Submersible Pumps:Immersed motor configurations eliminating surface seal maintenance. North Sea charterers now specify availability-based contracts for these units.
- Screw Pumps:Positive-displacement canned variants for high-viscosity thermal oils and molten salts in concentrated solar applications.
Horizontal pumps retain volume leadership; submersible pumps hold the steepest expansion curve.
End User:
Cost tier stratification separates premium nuclear specifications from standard refinery retrofits.
- Oil & Gas:Refinery operators face EPA Clean Air Act penalties for seal leakage, redirecting maintenance budgets toward sealless retrofits. US Gulf Coast facilities prioritize horizontal units for crude transfer and vertical configurations for coker unit feed.
- Chemical Processing:Fine-chemical and pharmaceutical manufacturers demand zero-leakage systems for pyrophoric or toxic intermediates. REACH substance restrictions on PTFE liners force ceramic or PEEK alternative qualification cycles.
- Water Treatment:Magnetic drive pumps and double-mechanical-seal architectures retain share where leakage tolerance permits.
- Power Generation:Nuclear coolant circulation demands ASME III and RCC-M certified packages with vacuum-pressure impregnated stator windings.
Chemical processing commands the highest specification density; oil and gas delivers the largest unit volumes.
Installation:
Geography-linked regulatory intensity shapes procurement priority across deployment modes.
- Onshore:Standardized skid-mounted packages for refinery and chemical plant integration. Floor-mounted horizontal units reduce downtime through accessible bearing cartridges.
- Offshore:Space-constrained platform decks favor compact vertical or submersible architectures. Norwegian operators pioneered integrated service contracts with availability-based payment structures.
- Utility:District heating and thermal storage networks specify canned units for pressurized hot water circulation.
- Industrial:General manufacturing applications with moderate pressure and temperature requirements.
Onshore installations retain the broadest application footprint; offshore specifications are climbing fastest as Brazilian pre-salt developments adopt Norwegian contracting models.
Application:
Margin concentration aligns with duty cycle intensity and fluid hazard classification.
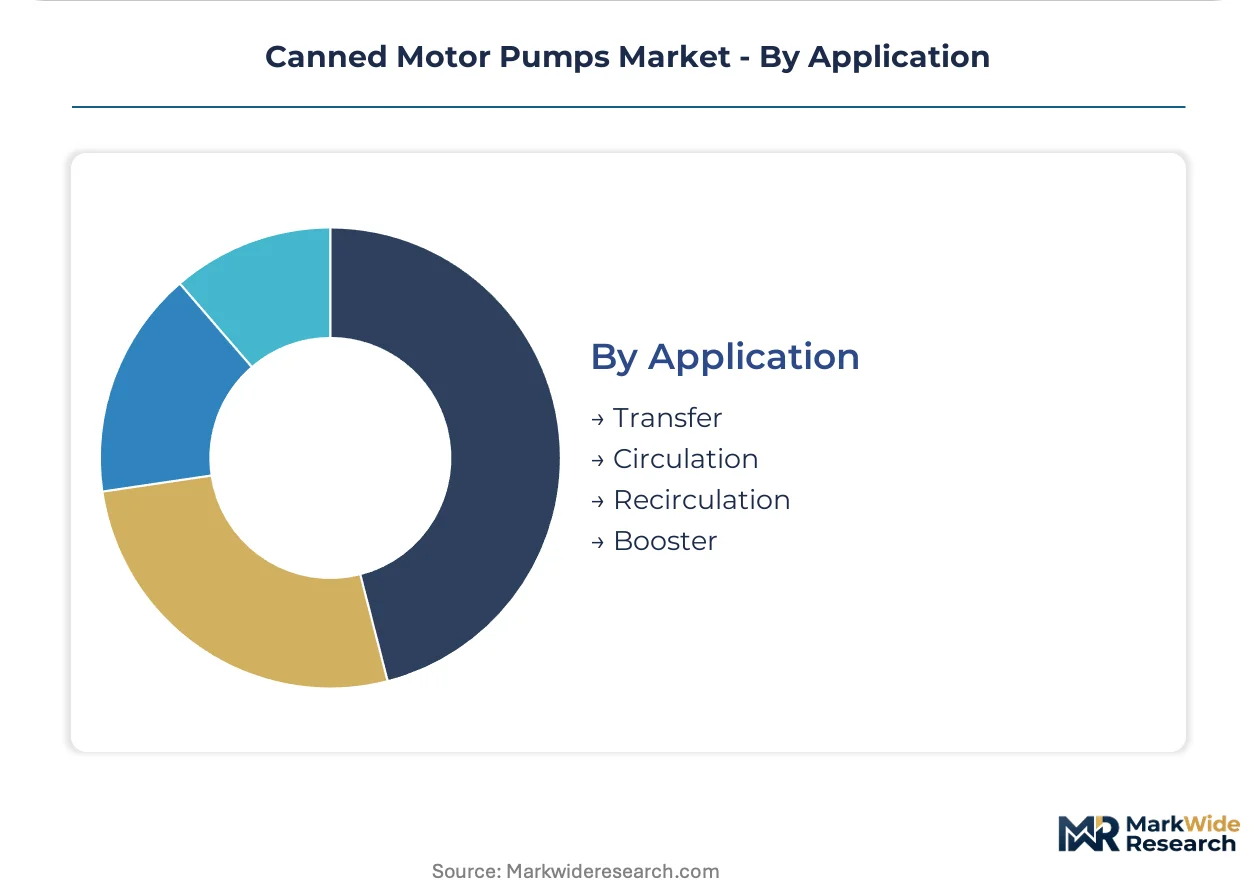
- Transfer:Continuous-duty hydrocarbon or chemical movement between process units. High-pressure specifications exceeding 200 bar differential concentrate in German-engineered horizontal pumps.
- Circulation:Closed-loop thermal management in nuclear reactors and concentrated solar plants. Molten salt and liquid sodium applications demand ceramic-composite stator liners rated beyond 400°C.
- Recirculation:Amine-based carbon capture solvent loops at 120-bar discharge pressures for post-combustion capture systems.
- Booster:Pressure augmentation in pipeline or distribution networks with moderate head requirements.
Transfer applications anchor the installed base; circulation duties are gaining share fastest through small modular reactor deployment and thermal energy storage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese suppliers dominate specialized foundry capacity for corrosion-resistant castings, while Chinese manufacturers narrow supply gaps through Jiangsu and Zhejiang capacity additions. Regulatory enforcement across multiple jurisdictions is redirecting procurement toward sealless architectures.
United States
Gulf Coast refineries are retrofitting crude transfer and coker feed systems with horizontal canned motor pumps to avoid EPA Clean Air Act penalties for volatile organic compound leakage. The EPA leak detection and repair standards now weight fugitive emissions compliance above upfront capital expenditure in vendor selection criteria. Houston and Corpus Christi petrochemical clusters absorb premium units for continuous-duty aromatic transfer loops.
Germany
Chemical processors in Ludwigshafen and Leverkusen specify zero-leakage systems for pyrophoric intermediates under REACH substance restrictions on PTFE liners. ECHA evaluation timelines are forcing reformulation toward ceramic or PEEK stator alternatives. Bavarian pharmaceutical manufacturers now require full material disclosure certificates extending to sub-component suppliers.
China
State-directed refinery upgrades in Jiangsu and Zhejiang provinces absorb premium vertical canned motor units for high-temperature hydrocarbon transfer. MEE volatile organic compound containment rules accelerate domestic adoption in coastal petrochemical clusters. Shanghai and Ningbo manufacturers are expanding capacity to serve nuclear coolant circulation projects.
Japan
Tokyo-based engineering groups anchor Asian nuclear cooling applications with JIS-certified designs for reactor coolant circulation. METI safety protocols mandate vacuum-pressure impregnated stator windings for factory-built nuclear units. Osaka and Nagoya industrial corridors concentrate precision manufacturing expertise for hermetic motor assemblies.
South Korea
Daegu-Gyeongbuk manufacturing zones supply carbon capture solvent circulation pumps for amine-based post-combustion capture systems at 120-bar discharge pressures. Domestic project developers specify ASME III certified packages for small modular reactor deployment. Busan-Ulsan shipyards integrate submersible configurations for offshore platform specifications.
Canned Motor Pumps Market Vendor Landscape
European engineering conglomerates and Asian electrical manufacturers split the market between high-pressure chemical specifications and nuclear-grade certifications. The vendor base concentrates around three strategic archetypes: diversified pump multinationals with full chemical processing portfolios, specialized hermetic pump engineers with zero-leakage expertise, and vertically integrated electrical equipment groups with captive motor manufacturing. Competitive positioning depends on multi-jurisdiction certification sequencing and localized service network depth.
Among diversified pump multinationals, KSB SE & Co. KGaA and Flowserve Corporation occupy positions spanning refinery retrofits and pharmaceutical transfer systems. TEIKOKU ELECTRIC MFG. CO., LTD. exemplifies the electrical equipment archetype with JIS-certified nuclear cooling designs. HERMETIC-Pumpen GmbH represents specialized hermetic engineering for European fine-chemical clients. These anchors illustrate how geographic origin and corporate structure shape certification pathways and customer access.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| TEIKOKU ELECTRIC MFG. CO., LTD. |
| Ebara Corporation |
| Sulzer AG |
| Nikkiso Co., Ltd. |
| Kirloskar Brothers Limited |
| Xylem Inc. |
| HERMETIC-Pumpen GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity in specialized Hastelloy and titanium foundries across Germany and Japan is compressing supplier flexibility and hardening pricing posture for corrosion-resistant pump housings. Buyers now face extended allocation cycles that favor multi-year offtake contracts over spot procurement, while suppliers leverage queue depth to enforce stricter payment terms and resist discounting pressure.
Pricing Analysis
EPA Clean Air Act enforcement dictates the pricing tier structure across the US refinery retrofit segment, where fugitive emissions compliance premiums separate certified sealless architectures from conventional centrifugal alternatives. Pricing stratifies across nuclear-grade, chemical-processing, and standard industrial tiers based on ASME III certification depth and stator liner material specification. Cost compression in standard industrial tiers is intensifying because Chinese manufacturers are expanding Jiangsu and Zhejiang capacity for domestic refinery upgrades. Chemical processing buyers exhibit the lowest price sensitivity due to pyrophoric fluid liability exposure, while water treatment operators retain mechanical seal alternatives that cap premium pricing power.
Supply Chain Analysis
Extended payment terms now stretch to 120 days for European pharmaceutical clients, forcing German suppliers to deploy supply-chain finance facilities to bridge working capital gaps. Foundry capacity concentrates in Germany, Japan, and select Chinese provinces for corrosion-resistant castings, while rare-earth magnet supply draws from Chinese processing clusters and Australian extraction operations. Single-source vulnerability in neodymium magnet supply creates margin volatility that ripples through motor manufacturing cost structures. Distribution runs through authorized service networks rather than distributor intermediaries, with vendors retaining ownership liability under availability-based contracts for offshore platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated service contracts with availability-based payment structures are expanding faster than hardware unit sales, creating a recurring-revenue layer that transforms capital equipment vendors into operational partners. This service-attach dynamic favors suppliers with localized maintenance infrastructure and predictive analytics capabilities over pure manufacturing scale.
For Market Incumbents: Pre-empt Chinese capacity expansion in Jiangsu and Zhejiang by accelerating ceramic-composite and PEEK stator liner qualification cycles before REACH substance restrictions fully phase out PTFE alternatives. Defensive consolidation through backward integration into specialized foundry capacity in Germany or Japan will secure 16-24 week lead time advantages against emerging Asian competitors. Certification investment in hydrogen liquefaction cryogenic ratings represents a moat-building opportunity with limited qualified vendors. For New Entrants and Emerging Players: Pursue carbon capture solvent circulation as the most penetrable white-space target, where amine-based post-combustion systems at 120-bar discharge pressures demand leak-free pump specifications with nascent vendor competition. Brazilian pre-salt offshore developments adopting Norwegian availability-based contracting models offer geographic entry with reduced upfront capital requirements. A go-to-market angle anchored in SiC variable frequency drive integration for motors above 200 kW differentiates on energy efficiency rather than pure hydraulic performance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across nuclear-grade certification pathways, where ASME III and RCC-M approval timelines extend commercialization by 18-30 months and concentrate returns in scaled incumbents. Acquisition targets should prioritize specialized hermetic pump engineers with vacuum-pressure impregnation technician benches and established multi-jurisdiction certification sequencing. The signal to watch is small modular reactor deployment momentum in the US and UK, where factory-built nuclear units standardize coolant circulation packages and favor certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Foundry Capacity | Secures Hastelloy and titanium casting supply against 16-24 week lead time bottlenecks in Germany and Japan. |
| Ceramic-Composite Stator Liner Qualification | Anticipates REACH substance restrictions phasing out PTFE liners in European pharmaceutical applications. |
| Hydrogen Liquefaction Cryogenic Certification | Captures minus 253°C liquid hydrogen transfer specifications with limited qualified vendor competition. |
| SiC Variable Frequency Drive Integration | Reduces switching losses by 40 percent compared to IGBT equivalents for motors above 200 kW. |
| Availability-Based Service Contract Expansion | Aligns with Norwegian and Brazilian offshore platform operator procurement models transferring ownership liability. |
Methodological Framework
The analysis maps vertical, horizontal, submersible, and screw pump configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with chemical processing operators, nuclear facility engineering groups, and offshore platform charterers combined with secondary validation from EPA enforcement databases, ECHA substance evaluation timelines, customs trade records, and ASME certification registries. Bottom-up unit economics triangulated against top-down regulatory-driven demand projections.
Assumptions held fixed include current EPA Clean Air Act penalty structures, REACH substance restriction phase-out schedules, and MEE volatile organic compound containment enforcement intensity across China's coastal petrochemical clusters. Variables included neodymium price trajectory, small modular reactor deployment pace, and hydrogen liquefaction infrastructure buildout timing. Segmentation dimensions modeled encompass product architecture, end-use industry, installation geography, and application duty cycle intensity. CAGRs derived from regression analysis against historical retrofit penetration rates and regulatory compliance deadline clustering.
Sensitivities concentrate around rare-earth magnet cost volatility, multi-jurisdiction certification timeline extensions, and workforce retirement rates for vacuum-pressure impregnation technicians. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and material substitution pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Global Self Priming Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Rotary Pump Market