
 Vehicle Tracking Systems Market | 2026-2036
Vehicle Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Tracking Systems Market Intelligence
Demand from large enterprise fleets is rotating toward small and medium-sized business (SMB) fleet operators, who now seek accessible, scalable solutions. This shift creates opportunities for vendors offering flexible subscription models. Geotab leverages its open platform to cater to a diverse customer base, while Verizon Connect differentiates through its integrated telecommunications and fleet service portfolio. Samsara specializes in a unified platform combining hardware and cloud software for industrial and commercial fleets.
Vehicle tracking systems are integrated hardware and software solutions that use GPS, cellular, or satellite networks to monitor a vehicle's location, speed, and status. These systems often incorporate accelerometers to detect harsh braking or acceleration for driver behavior analysis. Their primary purpose is to enhance fleet security, operational efficiency, and safety. While Real-time Tracking forms the foundational product type, higher-margin growth is found in comprehensive Fleet Management software suites. Technology adoption is moving beyond basic GPS/GSM to include RFID for in-vehicle asset tracking and advanced telematics.
Regulatory frameworks are a significant market catalyst. In the United States, the Federal Motor Carrier Safety Administration's (FMCSA) Electronic Logging Device (ELD) mandate requires commercial trucks to use these systems. Similarly, the EU's General Safety Regulation (GSR) necessitates event data recorders in new vehicles, driving OEM-level integration. The critical decision for fleet operators now involves choosing between basic compliance-level tracking and investing in advanced platforms for predictive maintenance and route optimization.
Market Dynamics
The central force shaping the vehicle tracking systems market is the democratization of fleet management technology. This is driven by a dual mandate: regulatory pressures requiring compliance and operational demands for efficiency from a widening base of small and medium-sized businesses.
Growth Catalysts
- Regulatory Mandates:Government regulations like the Federal Motor Carrier Safety Administration's (FMCSA) Electronic Logging Device (ELD) rule in the United States create non-discretionary demand, compelling commercial vehicle operators to adopt compliant tracking and logging technology.
- E-commerce Logistics Expansion:The rapid growth of e-commerce in countries like Brazil and India fuels intense demand for last-mile delivery optimization, making real-time vehicle tracking essential for efficiency and customer service.
- Technology Integration:The incorporation of advanced telematics, including RFID for tracking tools and equipment inside a vehicle and accelerometers for monitoring driver behavior, expands the value proposition beyond simple location data.
Market Restraints
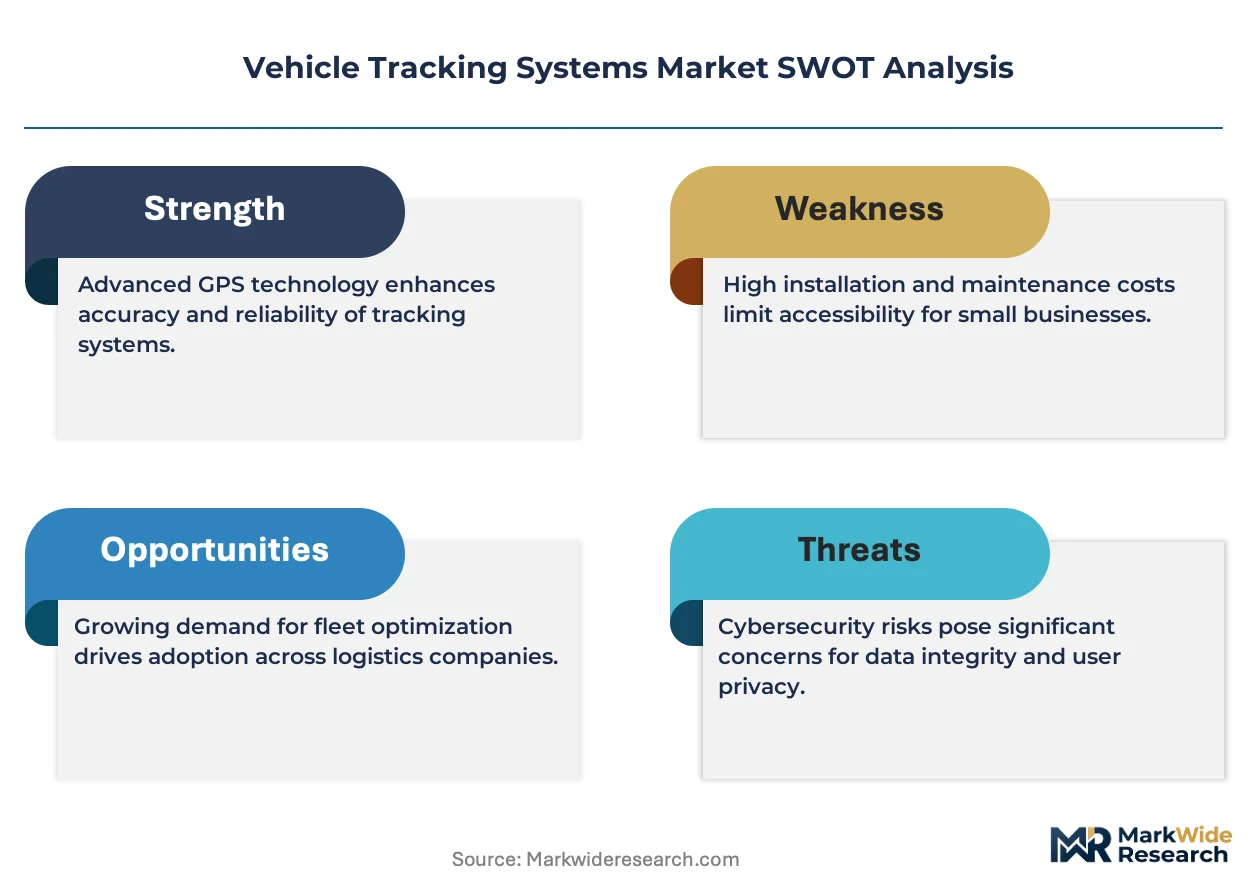
- Initial Cost Barriers:Despite subscription options, the upfront cost of hardware, professional installation, and system integration can remain a significant hurdle for small fleet operators and independent owner-operators with limited capital.
- Connectivity Limitations:System effectiveness depends on consistent network coverage. In rural or geographically remote regions, unreliable cellular and satellite connectivity creates tracking "dead zones," undermining real-time data collection.
- Data Privacy and Security:Growing concerns over data privacy, governed by frameworks like the GDPR in Europe, create compliance complexities and potential driver resistance regarding the continuous monitoring of location and behavior.
Strategic Opportunities
- EV Fleet Management:The commercial fleet transition to electric vehicles creates an opportunity for specialized tracking solutions that integrate with battery management systems to monitor state-of-charge, optimize charging schedules, and mitigate range anxiety.
- Insurance Telematics:Deeper collaboration with the insurance industry to support usage-based insurance (UBI) models represents a significant growth vector, turning telematics data into a tool for risk assessment and premium calculation.
- Underpenetrated Markets:Logistics and transportation sectors in developing economies across Southeast Asia and Africa offer substantial greenfield opportunities as infrastructure improves and businesses seek to formalize operations with tracking technology.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complexity and cost of integrating modern vehicle tracking platforms with a company's existing, often outdated, enterprise resource planning (ERP) or dispatch management software.
- Actionable Data Interpretation:Fleet managers often face a deluge of raw telematics data. The challenge lies in translating this data into actionable business intelligence without dedicated data analysts, leading to underutilization of the system's capabilities.
- Hardware and Software Interoperability:The lack of universal standards for device APIs and data formats complicates efforts by fleet operators to create a unified monitoring dashboard using hardware from multiple vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Tracking Systems Market |
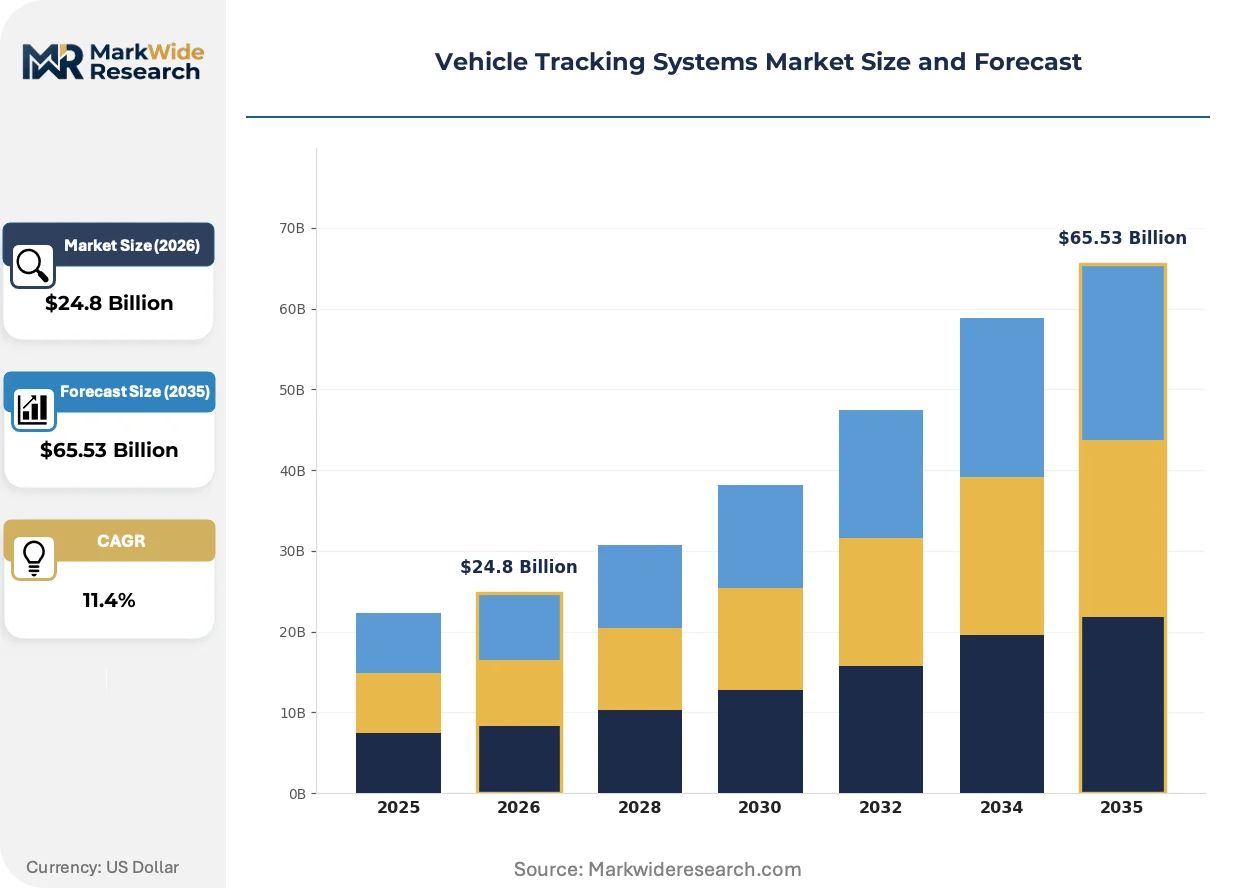
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-time Tracking, Fleet Management, Personal GPS, Vehicle Telematics Technology: GPS, RFID, GSM, Satellite End User: Logistics Firms, Public Transport, Automotive Manufacturers, Fleet Operators Installation: Hardwired, Plug-and-Play, Mobile App, Software-based |
| Companies Covered | Geotab Inc., Verizon Connect, Samsara, TomTom International BV, Cartrack, Continental AG, Teletrac Navman US Ltd, CalAmp, Spireon, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Tracking Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from passive location monitoring to active data utilization. Advanced analytics and AI are transforming vast telematics data streams into predictive insights for safety, maintenance, and operational automation.
AI-powered video telematics combines in-cab and road-facing cameras with machine learning to analyze driving events in real time. Commercial transportation and last-mile delivery fleets are the primary adopters, seeking to reduce accident frequency and validate insurance claims. This fusion of video and sensor data is displacing older, accelerometer-only systems by providing indisputable visual context for safety incidents and driver coaching.
Europe's General Safety Regulation (GSR) mandates features like event data recorders and intelligent speed assistance in all new vehicles. This policy directly forces automotive OEMs to embed advanced telematics hardware and software capabilities at the factory level. The commercial vehicle segment is most impacted, as the regulation accelerates a market-wide transition from aftermarket devices to OEM-native platforms for data access and compliance.
A significant demand-side shift is the embrace of flexible, subscription-based service models, particularly among small and medium-sized fleets. This approach disrupts the traditional hardware-purchase model by replacing high upfront capital expenditures with a scalable monthly operational expense. This trend is most prominent in the competitive North American and European markets, where it lowers entry barriers for smaller operators.
Vehicle Tracking Systems Market Segmentation
Understanding the distinct segments within the vehicle tracking systems market reveals where value is created and captured. Each category responds to specific operational demands and technological advancements, influencing purchasing decisions across diverse end-user profiles. This granular view helps stakeholders identify precise growth opportunities and tailor solutions effectively.
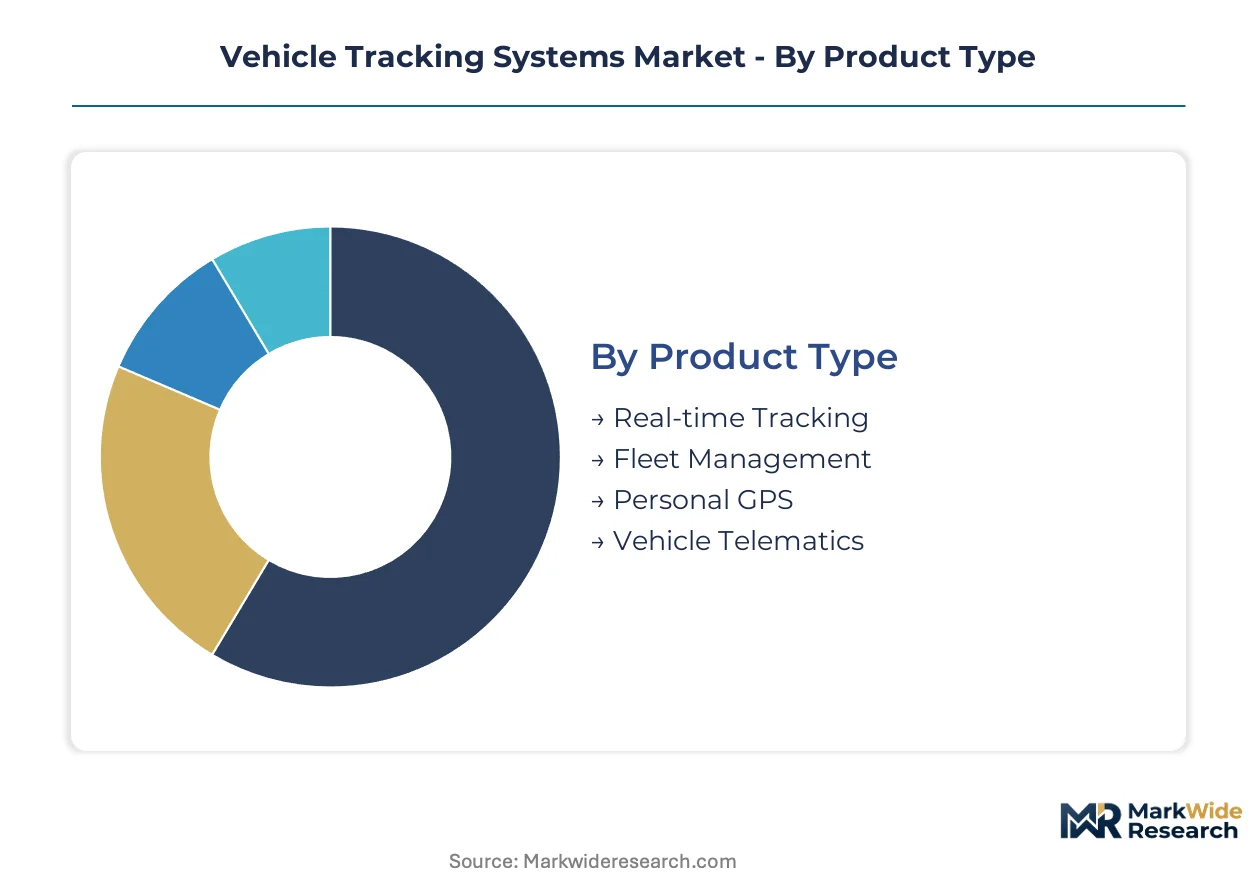
Product Type:
Margin pools within product types are increasingly shifting towards integrated software solutions rather than basic hardware. Advanced analytics and comprehensive features command higher pricing tiers.
- Fleet Management:These comprehensive software suites integrate real-time tracking with features like route optimization, fuel management, driver behavior monitoring, and predictive maintenance. Demand is concentrating among large enterprise fleets in Europe and North America seeking to maximize operational efficiency and reduce total cost of ownership.
- Real-time Tracking:This foundational product provides continuous location updates and basic telematics data using GPS and cellular networks. Logistics firms in high-growth e-commerce markets like India and Brazil rely heavily on real-time tracking for immediate visibility and last-mile delivery coordination.
- Personal GPS:These devices primarily offer location services for individual vehicles or assets, often focused on security and recovery.
- Vehicle Telematics:This segment encompasses the broader collection of data from vehicles, including diagnostics, performance metrics, and driver behavior, often forming the data backbone for other product types.
The dominant share belongs to Real-time Tracking, while Fleet Management is closing the gap fastest.
Technology:
The application of various technologies determines the accuracy, range, and data richness of tracking solutions. Different operational environments necessitate distinct technological approaches.
- GPS:Global Positioning System technology remains the core for accurate outdoor location tracking, providing precise coordinates globally. Regulatory compliance in the United States, such as the ELD mandate, relies heavily on GPS data for logging hours of service.
- GSM:Global System for Mobile communications provides the primary data transmission channel for vehicle tracking systems, enabling real-time communication of location and telematics data. Its widespread availability makes it essential for fleet operators across urban and rural areas.
- RFID:Radio-Frequency Identification systems are increasingly used for tracking specific assets or inventory within a vehicle or depot.
- Satellite:Satellite communication offers reliable tracking in remote areas where cellular networks are unavailable, catering to long-haul transportation or maritime applications.
GPS technology forms the bedrock of most systems, though GSM connectivity enables its practical deployment. RFID is expanding its utility for specialized in-vehicle asset management.
End User:
Customer type dictates the specific feature sets and scalability requirements for vehicle tracking solutions. Solutions are often tailored to address the unique pain points of each end-user group.
- Fleet Operators:This broad category includes commercial businesses managing multiple vehicles for various purposes, from service vans to heavy construction equipment. Operators in the United States prioritize advanced telematics for driver safety and regulatory compliance.
- Logistics Firms:These companies specialize in transportation and supply chain management, requiring robust tracking for route optimization, delivery scheduling, and cargo security. E-commerce growth in emerging markets like Brazil and India drives significant demand from logistics firms.
- Public Transport:Government and private entities operating buses, trains, or other public transit systems use tracking for scheduling adherence, passenger safety, and operational oversight.
- Automotive Manufacturers:OEMs are increasingly integrating tracking and telematics systems directly into new vehicles at the factory level.
Fleet Operators represent the largest customer base, while Logistics Firms are demonstrating the most significant expansion in demand.
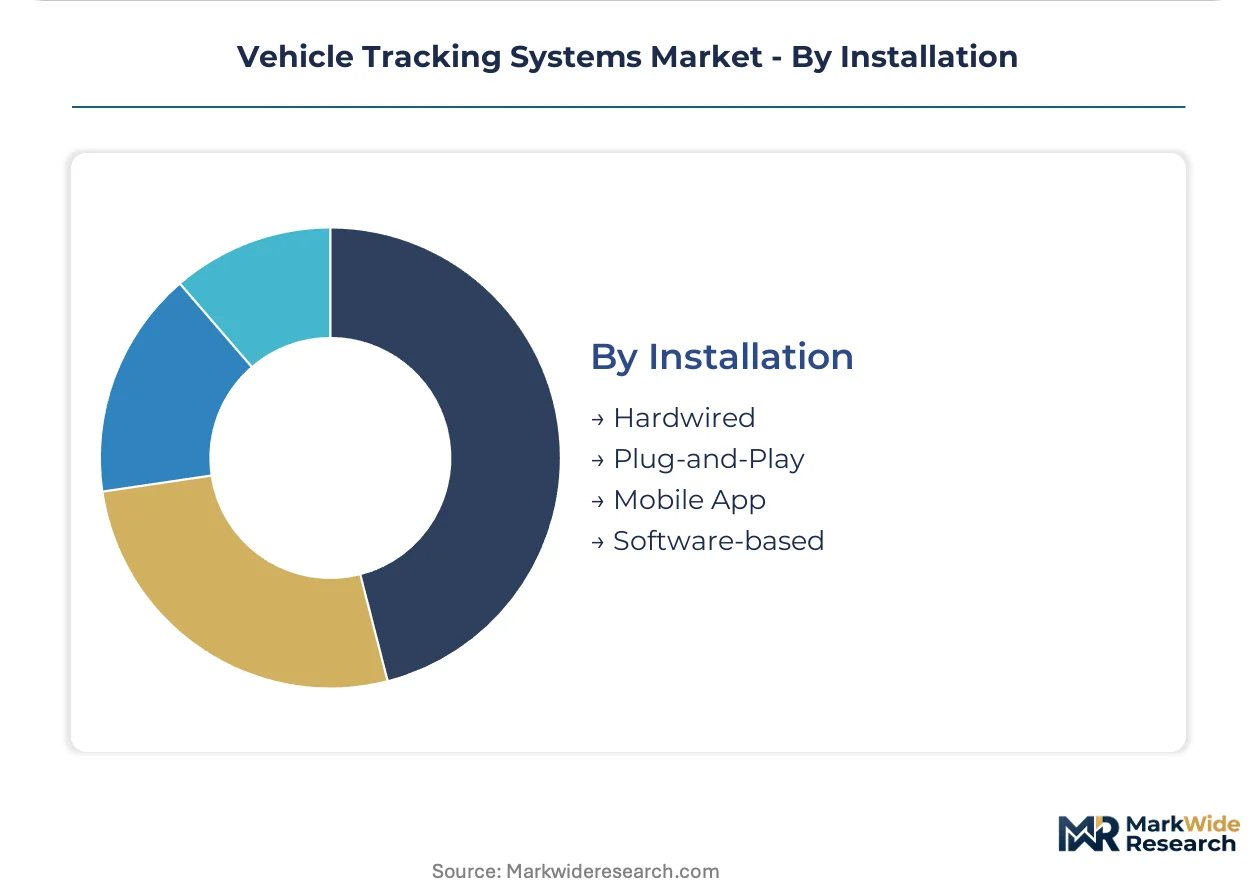
Installation:
The method of installation influences the ease of deployment, cost, and permanence of the tracking system. Flexible installation options cater to different fleet sizes and technical capabilities.
- Hardwired:These systems are permanently installed into a vehicle's electrical system, offering robust security and direct access to vehicle diagnostics. Large commercial fleets favor hardwired solutions for long-term reliability and comprehensive data acquisition.
- Plug-and-Play:These devices connect directly to a vehicle's OBD-II port, offering easy installation and portability without professional assistance. Small and medium-sized businesses in North America and Europe often choose plug-and-play for its low upfront cost and flexibility.
- Mobile App:Software-based tracking through smartphones provides a cost-effective solution for basic location monitoring and driver communication.
- Software-based:This refers to the backend platforms and analytical tools that process and present tracking data, often integrated with various hardware types.
Hardwired installations offer the most comprehensive data, while Plug-and-Play solutions are gaining share due to their ease of deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vehicle tracking systems market exhibits distinct regional dynamics, with technological advancements and regulatory mandates shaping demand profiles. Demand for comprehensive fleet management solutions is concentrating in developed economies. Emerging markets are rapidly expanding their real-time tracking capabilities due to e-commerce growth.
United States
United States demand is primarily driven by the FMCSA's Electronic Logging Device (ELD) mandate, compelling commercial vehicle operators to adopt compliant systems. Fleet operators prioritize advanced telematics for driver safety and operational compliance. Technology development around predictive maintenance and route optimization concentrates in areas like Silicon Valley.
Germany
German commercial fleets are integrating advanced telematics, spurred by the EU's General Safety Regulation (GSR) which mandates features like event data recorders. This regulation accelerates OEM-level integration of tracking hardware. Automotive manufacturing centers in Stuttgart and Munich drive innovation in vehicle telematics systems.
India
India's market expansion is significantly propelled by the rapid growth of e-commerce logistics and last-mile delivery services. Businesses are seeking to formalize operations with robust tracking technology. Demand for real-time visibility and delivery coordination is intense across major e-commerce hubs like Bengaluru and Mumbai.
Brazil
Brazilian demand for vehicle tracking systems stems from its expanding e-commerce sector and the need for logistics optimization. The country's regulatory environment encourages the adoption of technology to enhance supply chain efficiency. Key logistics and e-commerce hubs in São Paulo and Rio de Janeiro are driving significant uptake.
Japan
Japanese vehicle tracking systems are characterized by strong OEM integration and a focus on advanced safety features. National safety standards increasingly drive the embedding of telematics hardware at the factory level. Automotive industry clusters in regions like Toyota City and Tokyo are centers for telematics innovation.
Vehicle Tracking Systems Market Key Industry Players
Concentration sits with integrated telematics providers offering comprehensive fleet management suites, particularly for large enterprise fleets. The market structure is tiered, with established players alongside niche technology specialists and hardware manufacturers. Strategic archetypes include dedicated telematics firms, telecommunications giants, and automotive component manufacturers. Companies are pursuing strategic partnerships and continuous portfolio diversification to enhance their service capabilities and reach new market segments.
On the integrated solutions vector, Geotab Inc. exemplifies a firm leveraging its open platform to cater to a diverse customer base. Verizon Connect represents a provider differentiating through its integrated telecommunications and fleet service portfolio. Samsara, Inc. anchors a position as a specialist in unified hardware and cloud software solutions for industrial and commercial fleets. These entities collectively demonstrate the industry's shift towards comprehensive, scalable offerings for fleet management, from large enterprises to small and medium-sized businesses.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Connect |
| Samsara |
| TomTom International BV |
| Cartrack |
| Continental AG |
| Teletrac Navman US Ltd |
| CalAmp |
| Spireon, Inc. |
| Others |
Cost & Logistics Intelligence
Typical hardware procurement lead times of 8-12 weeks for telematics devices directly influence vendor inventory management and overall system pricing power. This lead time variability shapes how manufacturers structure their supply networks and impacts their ability to offer competitive pricing for rapid deployments.
Pricing Analysis
The Federal Motor Carrier Safety Administration's (FMCSA) ELD mandate dictates the pricing tier structure for compliance-driven solutions, establishing a baseline. The dominant pricing model is subscription-based, often SaaS-tiered, differentiating by feature sets and data analytics capabilities. Price differentiation stems from the customization level of advanced fleet management features and the extent of after-sales service and integration support. Pricing softness exists in basic compliance-level tracking due to increasing commoditization. Small and medium-sized businesses (SMBs) are generally more price-sensitive, while large enterprise fleets prioritize comprehensive features and robust support.
Supply Chain Analysis
Inventory holding periods for core telematics hardware components often reflect global electronics manufacturing cycles, influencing supply chain resilience. Geographic supply concentration centers on China for electronics assembly, Taiwan for specialized semiconductor components, and Germany for high-precision automotive components. The market relies on GPS modules, cellular modems, and accelerometers as critical inputs. Geopolitical tensions impacting semiconductor fabrication pose a structural supply chain risk. Distribution runs primarily through direct sales channels for large enterprise clients and a network of channel partners and resellers for SMBs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle tracking systems market presents a significant service-attach opportunity, with advanced analytics and predictive maintenance software expanding faster than basic hardware sales.
For Market Incumbents: Secure specialized software capabilities through targeted acquisitions to counter margin pressure from basic hardware commoditization. Deepen platform integration with enterprise resource planning systems to enhance stickiness and leverage R&D in AI-powered video telematics. Diversify offerings into specialized segments like EV fleet management to mitigate threats from niche software entrants.
For New Entrants and Emerging Players: Specialized EV fleet management integration represents a service-layer gap where incumbents under-serve. Target SMBs in developing economies like Southeast Asia with tailored, low-cost subscription models for rapid deployment and localized support. Focus on interoperability and API-first designs to facilitate integration with diverse fleet operator systems, gaining market share through ease of use and flexibility.
For Investors and Strategic Acquirers: Long-term, this sits as a data-driven operational efficiency play because regulatory mandates and efficiency demands will continue compelling fleet digitization. Identify software providers with strong AI/ML capabilities for acquisition targets, particularly those specializing in predictive maintenance or route optimization. The signal to watch is increasing M&A activity in AI-powered analytics firms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate data sources for large enterprise fleets, enhancing operational visibility. |
| Strategic Partnership | Leverages telecommunications networks for broader coverage and integrated service delivery. |
| Product Launch | Introduces specialized EV fleet management solutions to address emerging market needs. |
| Geographic Expansion | Captures greenfield opportunities in underpenetrated markets across Southeast Asia. |
| Acquisition of Specialist Firm | Adds advanced AI-powered analytics capabilities to existing fleet management suites. |
Research Approach
A standing panel of fleet managers, telematics engineers, and logistics executives provided ongoing calibration for market dynamics. This involved primary interviews combined with secondary validation from FMCSA data, EU transport reports, and OEM financial filings. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Forecast outputs underwent consistency checks against external industry benchmarks and macroeconomic indicators across the analysis window. The quantitative model segmented the market by product type, technology, end-user, installation method, and vehicle class. Compound annual growth rates were derived from historical trends and projected adoption rates, incorporating regulatory mandate timelines and e-commerce growth projections as key inputs.
Forecasts assume regulatory continuity in the United States and European Union; material policy shifts would require re-modeling. Global supply chain disruptions or unforeseen technological breakthroughs represent risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market