
 Search and Rescue Aircraft Market | 2026-2036
Search and Rescue Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Search and Rescue Aircraft Market Analytics
REACH compliance is shifting material sourcing and certification costs for European-based SAR fleet operators. Airbus Helicopters leverages its integrated avionics ecosystem to sustain long-term service contracts with NATO member states. Sikorsky Aircraft anchors its position through deep rotorcraft expertise in heavy-lift configurations for naval rescue missions. Leonardo Helicopters differentiates via specialized ice-operations variants serving Arctic coast guard units.
Search and rescue aircraft encompass purpose-built or modified aerial platforms engineered for locating, accessing, and extracting personnel from hostile environments, typically featuring operating ceilings above 15,000 feet, extended loiter times exceeding four hours, and integrated hoist or rappelling systems. These assets serve critical functions across civilian emergency response, military extraction, and maritime patrol operations where terrain or weather denies ground access. Helicopters retain the dominant revenue share due to their vertical takeoff capability and precision hover requirements in confined rescue zones. Fixed-wing aircraft command substantial procurement volumes for long-range ocean patrol where endurance exceeds rotorcraft limits. Drones represent the fastest-expanding feature set, particularly thermal-imaging-equipped unmanned platforms that reduce crew risk during initial search phases.
The FAA enforces strict all-weather certification standards that dictate avionics minimums for civilian SAR fleets, while EASA's CS-29 large rotorcraft specifications govern European heavy-lift platform approvals. Military procurement channels operate under distinct airworthiness frameworks administered by national defense ministries, creating parallel compliance pathways for dual-use aircraft. Stakeholders must weigh crewed platform sustainment against unmanned system integration timelines as regulatory bodies finalize beyond-visual-line-of-sight operational rules.
Market Dynamics
FAA all-weather certification mandates are compressing OEM development cycles while forcing simultaneous avionics upgrades across civilian and dual-use SAR fleets, creating a technology refresh imperative that favors integrated platform-ecosystem providers over component specialists.
Growth Catalysts
- Climate-driven emergency protocols:Australia's bushfire response mandates now require dedicated aerial rescue assets on standby during peak hazard seasons, institutionalizing rotary-wing procurement.
- Maritime zone expansion:Asia-Pacific coast guard fleets are widening rotary-wing coverage to encompass extended exclusive economic zones, generating sustained multi-year procurement pipelines.
- REACH material compliance:European operators face recertification requirements for ice-operations variants, accelerating fleet modernization timelines.
Market Restraints
- Avionics cost inflation:FAA all-weather certification standards mandate enhanced sensor suites and redundant flight systems, elevating platform unit economics.
- Specialized aircrew scarcity:Dual-rated pilots qualified for both hoist operations and instrument meteorological conditions command premium compensation, constraining fleet utilization rates.
- CS-29 certification timelines:EASA large rotorcraft approval processes for heavy-lift configurations extend 18-24 months, delaying revenue recognition for European OEMs.
Strategic Opportunities
- Beyond-visual-line-of-sight unmanned integration:Regulatory bodies are finalizing operational rules for thermal-imaging-equipped drones, opening initial search-phase applications.
- Arctic coast guard specialization:Ice-operations variants serve underpenetrated northern maritime patrol requirements with limited incumbent competition.
- NATO long-term service contracting:Integrated avionics ecosystems enable 10-15 year through-life support agreements, capturing recurring revenue streams.
Industry Challenges
- Legacy platform interoperability:New avionics suites must integrate with existing hoist and rappelling systems, extending retrofit timelines.
- Dual-use certification complexity:Military and civilian airworthiness frameworks operate in parallel, forcing redundant testing protocols for exportable platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search and Rescue Aircraft Market |
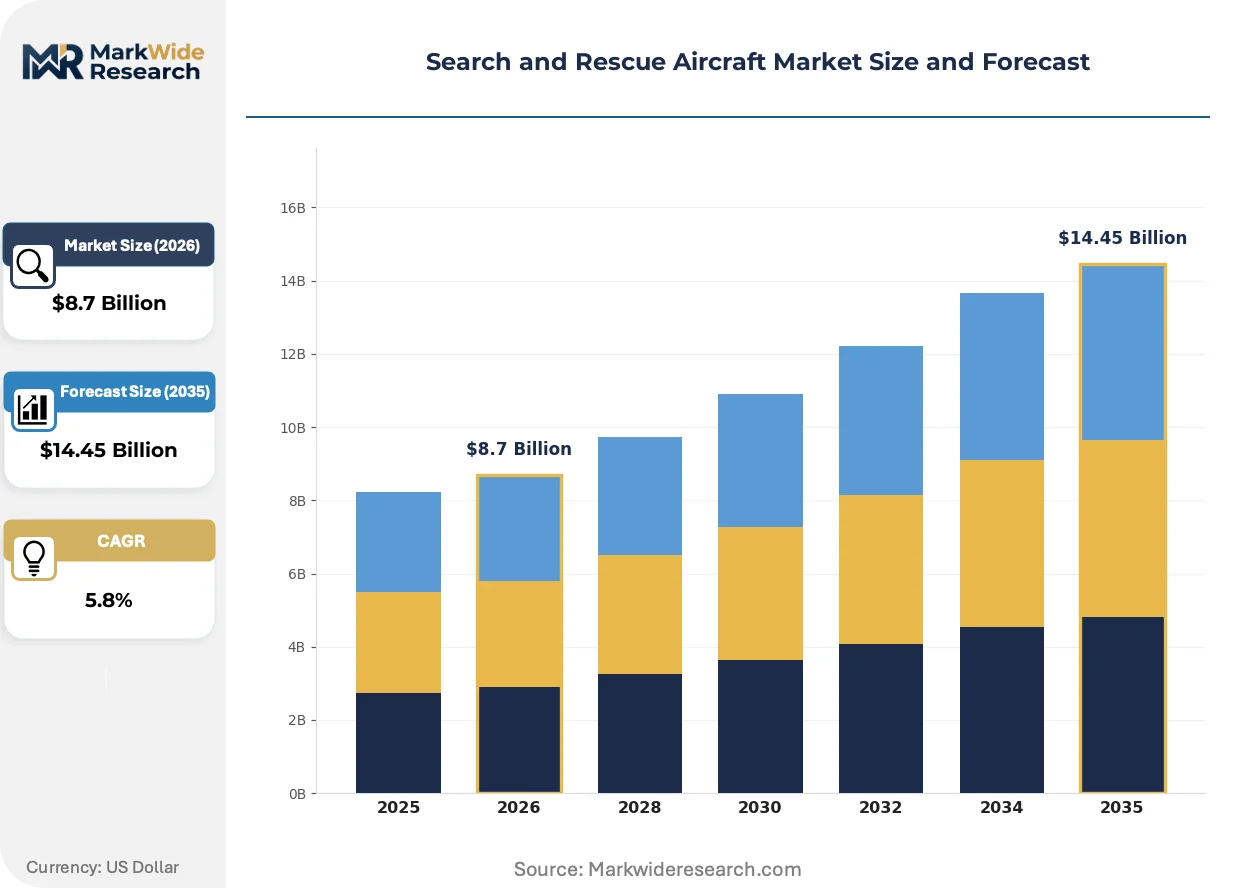
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Helicopters, Fixed-Wing Aircraft, Drones, Unmanned Aerial Vehicles Application: Natural Disasters, Maritime Operations, Emergency Medical Services, Military Operations End User: Government Agencies, Non-Profit Organizations, Private Enterprises, Military Feature: Night Vision, Thermal Imaging, Communication Systems, Payload Capacity |
| Companies Covered | Lockheed Martin, Boeing Defense, Sikorsky Aircraft, Airbus Helicopters, Leonardo Helicopters, Bell Textron, Northrop Grumman, Textron Aviation, General Atomics Aeronautical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search and Rescue Aircraft Market Evolving Landscape
Autonomous systems are penetrating mission profiles previously reserved for crewed platforms, while regulatory convergence between civil aviation and defense procurement is compressing technology transfer timelines.
Thermal-imaging unmanned platforms are converging with artificial intelligence-enabled object recognition to automate initial search phases in hostile terrain. Maritime patrol operators in Norway and Canada are piloting these systems for iceberg-strewn waters. The technology is converging with crewed SAR operations by reducing exposure hours for flight crews during low-visibility reconnaissance.
EU Green Deal aviation sustainability targets are imposing emissions benchmarks on new rotorcraft certifications. EASA is developing specific CO2 measurement protocols for SAR mission profiles. Heavy-lift OEMs serving North Sea oil platform evacuation are responding with hybrid-electric propulsion demonstrators to preserve future market access.
After-sales service unbundling is fragmenting traditional OEM revenue models. Australian state emergency services are disaggregating maintenance contracts from initial platform acquisition, creating openings for third-party MRO specialists. This pattern is most visible in Victoria and New South Wales, where fleet standardization across agencies enables pooled spare inventory arrangements.
Search and Rescue Aircraft Market Segmentation
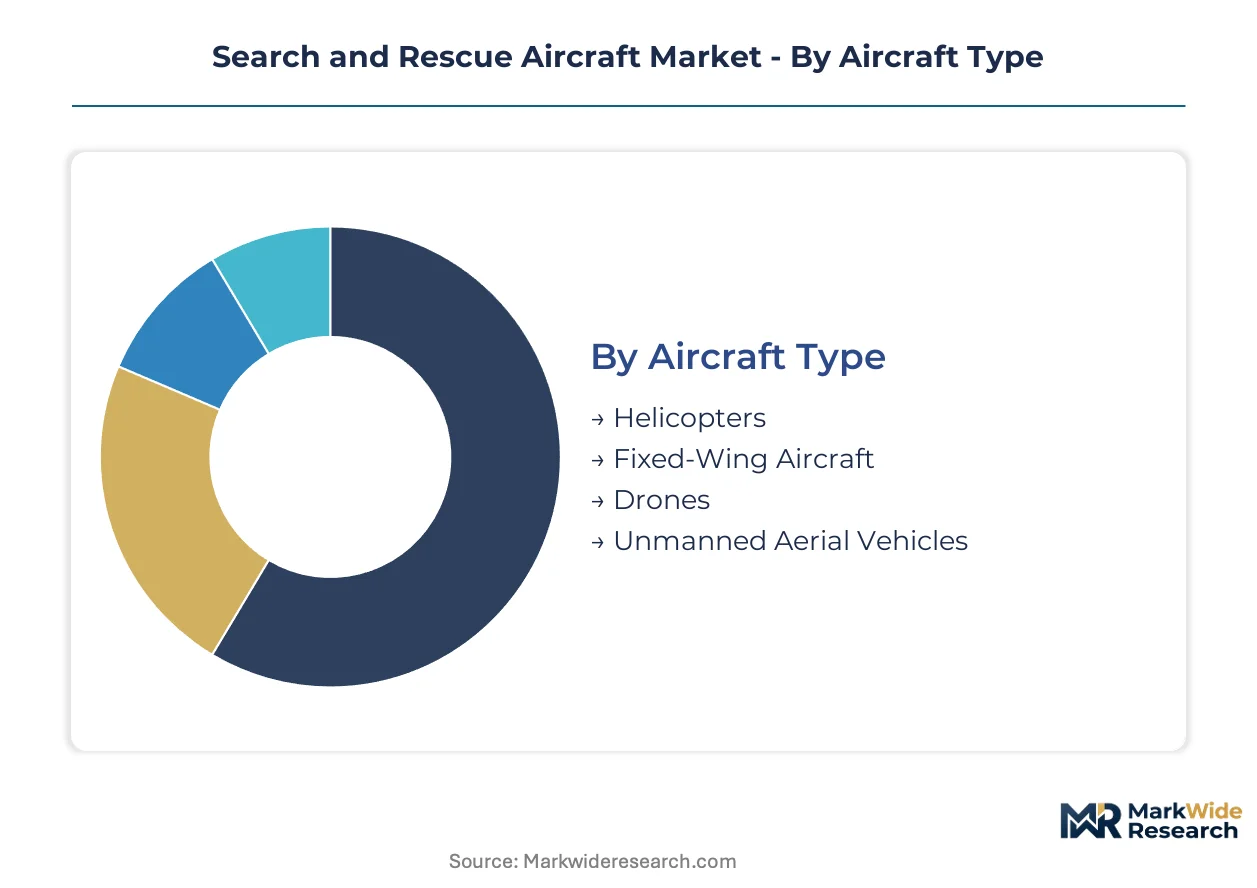
Platform specialization determines procurement priorities across civilian and defense channels. Upgrade cycles vary sharply by airframe age, mission profile intensity, and regulatory recertification deadlines.
Aircraft Type:
Replacement timelines diverge dramatically between rotorcraft and unmanned platforms, with legacy helicopter fleets facing compressed modernization windows under evolving certification mandates.
- Helicopters:Rotary-wing platforms dominate revenue concentration through vertical takeoff capability and precision hover requirements in confined rescue zones. Australia's state emergency services and Asia-Pacific coast guard fleets anchor procurement volumes for medium-lift configurations with integrated hoist systems.
- Fixed-Wing Aircraft:Long-endurance platforms command substantial placement volumes for maritime patrol where loiter requirements exceed rotorcraft fuel limits. Norwegian and Canadian operators prioritize these assets for iceberg-strewn waters and Arctic coastline coverage.
- Drones:Thermal-imaging-equipped unmanned systems reduce crew exposure during initial search phases in hostile terrain.
- Unmanned Aerial Vehicles:Beyond-visual-line-of-sight platforms are gaining operational approvals for low-visibility reconnaissance missions.
Volume placements concentrate in Helicopters; the faster expansion belongs to Drones.
Application:
Mission profile intensity shapes fleet composition, with climate-driven emergency protocols institutionalizing dedicated aerial assets for predictable seasonal hazards.
- Natural Disasters:Bushfire response mandates in Australia's eastern seaboard now require dedicated rotary-wing assets on standby during peak hazard seasons. State-level procurement in Victoria and New South Wales standardizes fleet configurations to enable pooled maintenance arrangements.
- Maritime Operations:Coast guard fleets across the Asia-Pacific rim are expanding rotary-wing coverage to encompass extended exclusive economic zones. Ice-operations variants serve underpenetrated Arctic patrol requirements with specialized de-icing and cold-weather avionics.
- Emergency Medical Services:Helicopter emergency medical services demand all-weather certification under FAA mandates.
- Military Operations:Dual-use platforms face parallel civilian and military airworthiness frameworks.
Procurement volumes cluster in Maritime Operations; Natural Disasters shows the steepest expansion trajectory as climate protocols institutionalize.
End User:
Contracting structures fragment traditional OEM revenue models, with government agencies disaggregating acquisition from through-life support.
- Government Agencies:Australian state emergency services and coast guard fleets anchor multi-year procurement pipelines. These operators increasingly unbundle maintenance contracts from initial platform acquisition, creating openings for third-party MRO specialists.
- Military:NATO member states sustain long-term service agreements through integrated avionics ecosystems. National defense ministries administer distinct airworthiness frameworks that create parallel compliance pathways for exportable platforms.
- Non-Profit Organizations:Mountain rescue and humanitarian operators prioritize cost-efficient refurbished platforms.
- Private Enterprises:North Sea oil platform evacuation contractors face EU Green Deal emissions benchmarks.
Fleet ownership concentrates in Government Agencies; Military contracts capture the longest duration revenue streams.
Feature:
Avionics integration complexity drives cost inflation, with certification mandates forcing redundant sensor suites across new and retrofit platforms.
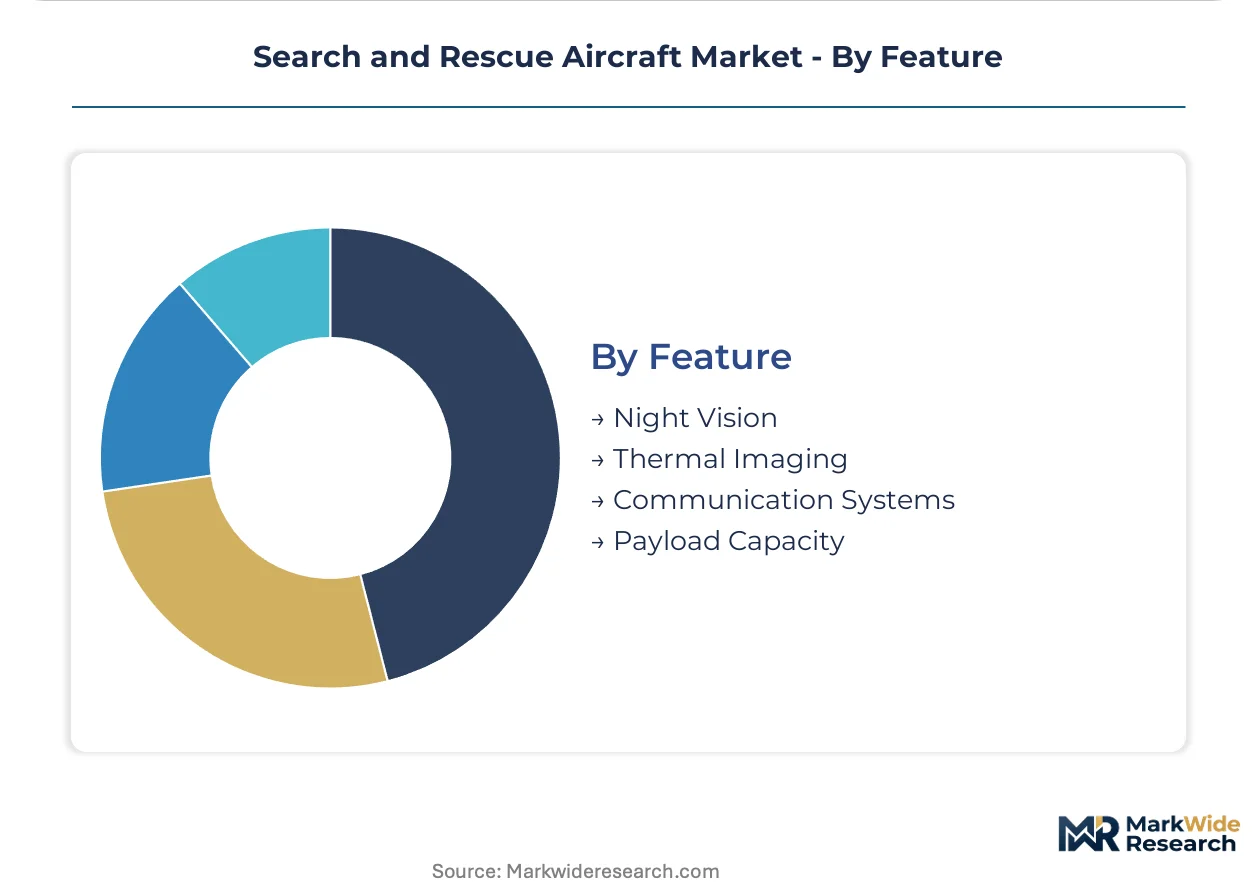
- Thermal Imaging:AI-enabled object recognition automates initial search phases in hostile terrain. Maritime patrol operators in Norway and Canada pilot these systems for iceberg detection and crewed SAR coordination.
- Night Vision:All-weather operational certification under FAA mandates requires enhanced low-light sensor suites. EASA CS-29 large rotorcraft specifications impose parallel requirements for European heavy-lift approvals.
- Communication Systems:Redundant data links support beyond-visual-line-of-sight unmanned operations.
- Payload Capacity:Heavy-lift configurations require extended certification timelines for hoist and rappelling system integration.
Adoption concentrates in Thermal Imaging; Communication Systems are climbing fastest as BVLOS rules finalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for aerospace manufacturing in Toulouse, Hamburg, and Montreal concentrate OEM assembly capacity alongside regulatory certification hubs.
United States
FAA all-weather certification mandates drive avionics upgrade cycles across civilian and dual-use fleets. The agency's enhanced sensor suite requirements elevate platform unit economics for domestic operators. Sikorsky Aircraft anchors heavy-lift rotorcraft production in Connecticut, serving naval rescue mission profiles.
Australia
State-level bushfire response protocols in Victoria and New South Wales institutionalize dedicated aerial rescue assets during peak hazard seasons. The country's emergency services standardize fleet configurations to enable pooled maintenance arrangements. Sydney and Melbourne clusters concentrate rotary-wing procurement for maritime and disaster response coverage.
Norway
Arctic coast guard patrol requirements generate sustained demand for ice-operations variants with specialized de-icing systems. EASA CS-29 large rotorcraft specifications govern heavy-lift platform approvals for North Sea oil platform evacuation contractors. Bergen and Stavanger anchor maritime SAR fleet operations alongside hybrid-electric propulsion demonstrator programs.
Canada
Iceberg-strewn water patrols in northern maritime zones prioritize fixed-wing endurance platforms exceeding rotorcraft fuel limits. Transport Canada coordinates with EASA on emissions benchmarking for SAR mission profiles under EU Green Deal aviation sustainability targets. Halifax and Vancouver clusters support coast guard fleet modernization timelines.
Japan
Coast guard fleets expand rotary-wing procurement to cover extended exclusive economic zones across the Asia-Pacific rim. METI oversees national defense ministry airworthiness frameworks that create parallel compliance pathways for dual-use aircraft. Nagoya and Kobe manufacturing zones concentrate medium-lift configuration assembly for regional export markets.
Search and Rescue Aircraft Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across platform development and through-life service contracting. The vendor base stratifies between integrated avionics ecosystem providers and component-level specialists. Three archetypes dominate: defense-anchored conglomerates with dual-use portfolios, helicopter-specialist OEMs with deep rotorcraft expertise, and unmanned systems integrators capturing beyond-visual-line-of-sight segments. Competitive moves center on long-term service agreement capture and Arctic specialization variants with limited incumbent competition.
Among defense-anchored conglomerates, Lockheed Martin and Northrop Grumman occupy positions spanning crewed and unmanned platform development. Sikorsky Aircraft and Airbus Helicopters exemplify the rotorcraft-specialist tier, anchoring heavy-lift and medium-lift configuration markets respectively. Leonardo Helicopters sits within the specialization-focused segment, represented by ice-operations variant development for underpenetrated northern maritime patrol requirements.
| Leading Market Players |
|---|
| Lockheed Martin |
| Boeing Defense |
| Sikorsky Aircraft |
| Airbus Helicopters |
| Leonardo Helicopters |
| Bell Textron |
| Northrop Grumman |
| Textron Aviation |
| General Atomics Aeronautical Systems |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense conglomerates and family-owned aerospace specialists anchor production capacity in Toulouse, Hamburg, and Montreal, creating supply-side discipline that insulates pricing from commodity volatility while concentrating bargaining power with national procurement agencies.
Pricing Analysis
Premium pricing attaches to short-lead-time delivery slots for ice-operations variants and heavy-lift configurations, while spot inventory of standard medium-lift platforms trades at discounted levels. Contract-based long-term offtake dominates, with price differentiation resting on EASA CS-29 certification tier and integrated avionics ecosystem bundling. Cost compression in retrofit avionics suites is intensifying because FAA all-weather mandates force redundant sensor procurement. Government agencies exhibit highest price sensitivity due to unbundled maintenance contracting, whereas NATO defense ministries demonstrate lowest sensitivity through 10-15 year through-life support agreements.
Supply Chain Analysis
Freight costs for oversized rotorcraft assemblies hinge on specialized air-cargo routing through Hamburg and Montreal, with surface transport limited to fuselage sections below dimensional thresholds. Manufacturing concentration centers on France, Germany, and Canada for final assembly, while critical avionics and de-icing systems draw from US and Japanese component specialists. Single-source vulnerability persists in thermal-imaging sensor supply from sovereign-controlled technology firms. Distribution runs through direct government procurement channels and NATO cooperative acquisition frameworks, bypassing traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The search and rescue aircraft market sits in a technology-transition phase as thermal-imaging unmanned platforms displace crewed assets in initial search phases, compressing replacement cycles and reshaping fleet composition priorities.
For Market Incumbents: Extend integrated avionics ecosystem coverage into through-life support contracting to capture recurring revenue streams threatened by third-party MRO specialists. Deepen certification investment in EASA CS-29 large rotorcraft specifications to defend against emerging unmanned systems integrators in Arctic patrol segments. For New Entrants and Emerging Players: Launch via direct contracting with Australian state emergency services in Victoria and New South Wales, where fleet standardization and pooled maintenance arrangements create entry openings outside incumbent OEM relationships. Target ice-operations variant development for underpenetrated Norwegian and Canadian coast guard requirements, leveraging regulatory specialization gaps against diversified conglomerates. For Investors and Strategic Acquirers: Distressed-cycle entries favor unmanned systems specialists with beyond-visual-line-of-sight operational approvals in US and European regulatory environments, where certification timelines have compressed valuations. Long-term viability across the projection horizon rests on hybrid-electric propulsion demonstrator progress meeting EU Green Deal aviation sustainability benchmarks. Monitor EASA CO2 measurement protocol finalization for SAR mission profiles as the inflection signal for heavy-lift platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Certification Investment | Positions operators for FAA and EASA unmanned operational rule finalization in maritime patrol. |
| Arctic Specialization Variant Development | Captures Norwegian and Canadian coast guard demand with limited incumbent competition in ice-operations. |
| Integrated Avionics Ecosystem Expansion | Enables 10-15 year NATO through-life support agreements with recurring revenue capture. |
| Hybrid-Electric Propulsion Demonstrator | Preserves North Sea oil platform evacuation market access under EU Green Deal emissions benchmarks. |
| Third-Party MRO Capability Acquisition | Responds to Australian state emergency services unbundling maintenance from platform acquisition. |
Research Methodology
Document review covered FAA certification databases, EASA CS-29 approval records, and NATO cooperative procurement filings, complemented by interviews with coast guard fleet managers, rotary-wing OEM program directors, defense ministry acquisition officers, and third-party MRO specialists. Secondary validation drew from customs trade data, national defense budget appropriations, and EU Green Deal aviation sustainability documentation. Bottom-up platform placement counts triangulated against top-down market size estimates derived from government contract award values.
Platform-level forecasts across the analysis window segment by aircraft type, application intensity, end-user contracting structure, and avionics feature integration. CAGRs derive from replacement cycle modeling tied to regulatory recertification deadlines and climate-driven emergency protocol institutionalization. Industry-specific inputs include EASA large rotorcraft approval timelines, FAA all-weather certification mandate compliance costs, and Asia-Pacific exclusive economic zone expansion trajectories.
Regulatory delay in beyond-visual-line-of-sight operational rule finalization, accelerated EU emissions benchmark implementation, and sovereign defense budget reallocation are the dominant revision risks to modeled placement volumes. Stakeholders should weight assumptions against their own operating context and fleet modernization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Regional Jet Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
GCC General Aviation Market
Aircraft
Airship Market
Aircraft
Firefighting Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Special Mission Aircraft Market