
 Airship Market | 2026-2036
Airship Market Size, Share, and Industry Trends Forecast 2026-2036
Airship Market Analysis
Multi-source helium procurement is consolidating around long-term offtake agreements with industrial gas suppliers. Hybrid Air Vehicles anchors British manufacturing through its Airlander program and specialized hybrid-lift intellectual property. Zeppelin Luftschifftechnik sustains German engineering dominance in rigid-frame construction and passenger flight operations. H2 Clipper competes on hydrogen-lift technology for zero-emission cargo corridors over transoceanic routes.
An airship is a lighter-than-air aircraft comprising a gas-filled envelope that generates aerostatic lift, with modern variants achieving lengths exceeding 90 meters and incorporating vectored thrust systems for precision maneuvering. These vessels serve commercial transport, persistent surveillance, and heavy-lift logistics missions where endurance exceeds conventional rotorcraft or fixed-wing alternatives. Rigid and semi-rigid architectures retain structural margins for defense applications demanding all-weather operational reliability. Non-rigid blimp configurations dominate advertising and event deployments where rapid deployment and ground-handling simplicity offset payload limitations. Hybrid designs integrate aerodynamic lift with buoyant force, expanding useful load capacity for cargo transport segments.
The FAA governs U.S. type certification under Part 21 airworthiness standards, while EASA enforces CS-30 specifications across European member states; both frameworks mandate envelope material fire resistance and ground-crew training minima that shape manufacturer design priorities and operator entry costs. China's CAAC imposes domestic route restrictions that channel development toward military and state-utility applications rather than commercial passenger service. Stakeholders must track hydrogen storage safety rulemaking in Germany and France, as regulatory acceptance of H2 lift gas will determine whether next-generation cargo platforms achieve operational scale or remain constrained to helium-dependent economics.
Market Dynamics
Helium supply concentration and stratospheric communications demand are restructuring procurement patterns and platform specifications across military and commercial segments.
Growth Catalysts
- Defense Surveillance Mandates:Persistent aerial reconnaissance requirements from military agencies are expanding procurement budgets for long-endurance platforms that exceed conventional drone loiter times.
- FAA Part 21 Streamlining:Updated U.S. airworthiness criteria for lighter-than-air vehicles compresses certification timelines and reduces manufacturer entry costs.
- Hydrogen Lift Gas Innovation:Zero-emission cargo corridors over transoceanic routes are becoming technically viable as hydrogen storage safety protocols mature in Germany and France.
Market Restraints
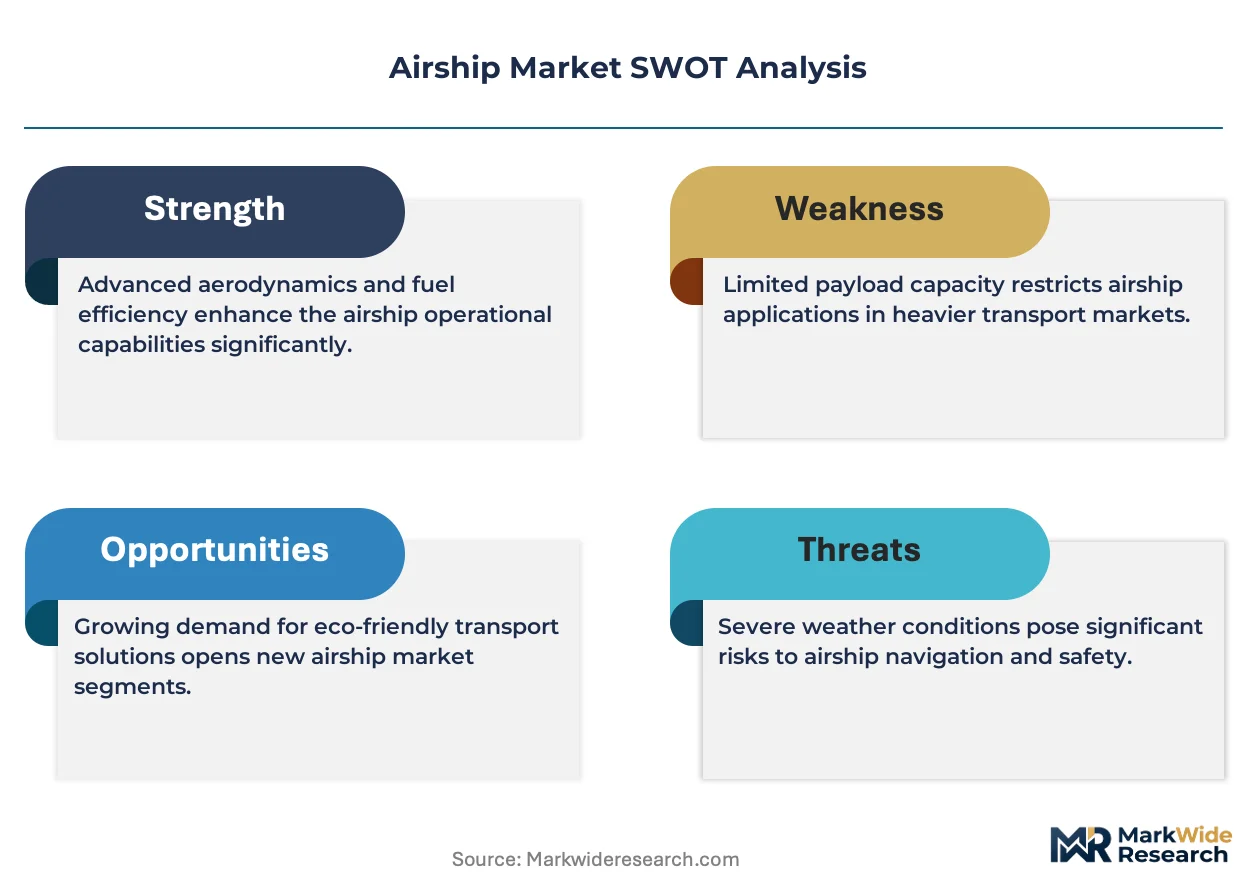
- Helium Supply Concentration:Industrial gas supplier consolidation creates long-term offtake dependency and price volatility for buoyant gas procurement.
- Ground Infrastructure Deficits:Specialized mooring masts and hangar facilities require capital investment that limits operational flexibility outside established bases.
- Weather Sensitivity:Envelope performance degradation in high-wind conditions restricts all-weather reliability for commercial transport missions.
Strategic Opportunities
- Stratospheric Communications Nodes:State-backed programs in China are piloting high-altitude platform stations for rural broadband coverage where satellite economics fail.
- Heavy-Lift Logistics Corridors:Remote mining and energy infrastructure projects in Canada and Australia present payload applications where runway access is absent.
- EU Green Deal Alignment:Hydrogen-lift certification pathways in France and Germany unlock zero-emission cargo incentives under the bloc's sustainable transport frameworks.
Industry Challenges
- Envelope Fabrication Expertise:Laminated gas barrier manufacturing requires specialized polymer handling skills that outpace vocational training pipeline output.
- Multi-Regulatory Certification Burden:FAA Part 21, EASA CS-30, and CAAC divergence forces redundant testing cycles for international operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airship Market |
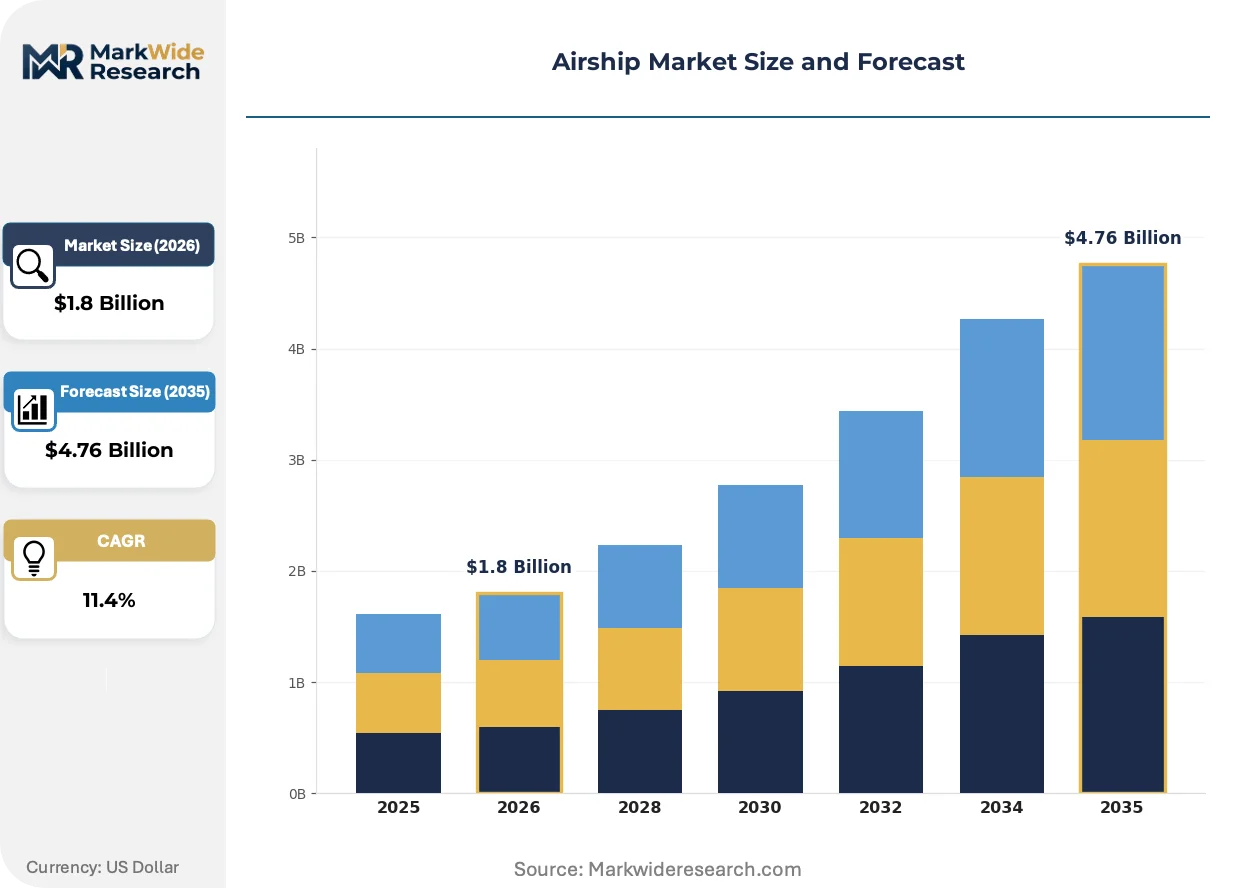
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Semi-Rigid, Non-Rigid, Hybrid End User: Travel & Tourism, Surveillance, Advertising, Cargo Transport Application: Corporate Events, Scientific Research, Disaster Relief, Military Operations Technology: Hybrid Propulsion, Electric Propulsion, Traditional Engine, Autonomous Systems |
| Companies Covered | Goodyear, H2 Clipper, Hybrid Air Vehicles, LTA Research, Airship Industries, Flying Whales, Aviation Industry Corp., Lockheed Martin, Zeppelin Luftschifftechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airship Market Emerging Trajectories
Platform architecture is converging around hybrid-lift systems that merge aerostatic and aerodynamic forces, while regulatory frameworks fragment across hydrogen safety and stratospheric traffic management domains.
Hybrid-lift envelope designs are unifying buoyant and aerodynamic force generation in single airframe structures. Defense agencies in the United States and United Kingdom are accelerating evaluation programs for these platforms. The technology is unifying payload capacity and endurance metrics that previously required trade-offs between blimp and fixed-wing alternatives.
EASA CS-30 specifications and FAA Part 21 standards are diverging on hydrogen lift gas containment requirements. European regulators are advancing draft protocols for cryogenic hydrogen storage in semi-rigid frames while U.S. authorities maintain helium-default positions. Cargo platform developers in Germany face certification pathway uncertainty that channels R&D investment toward stratospheric communications applications instead.
Outcome-based leasing models are displacing traditional platform ownership in commercial surveillance segments. Infrastructure operators in Australia and Canada now contract flight-hour availability rather than acquiring hull assets. Mining and energy verticals in remote geographies are driving this shift as they prioritize operational flexibility over capital deployment on specialized ground infrastructure.
Airship Market Segmentation
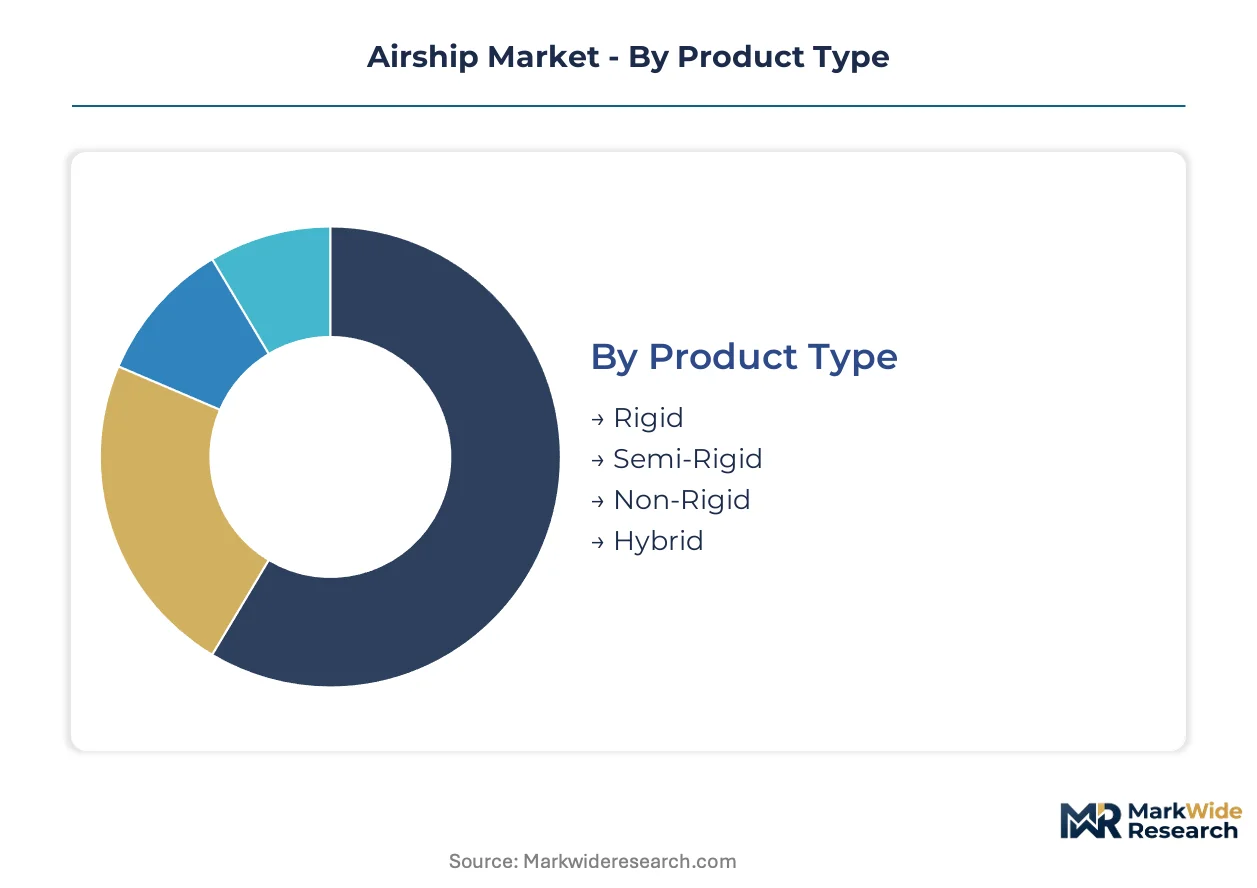
Airship architecture and propulsion configurations determine operational envelopes, regulatory pathways, and customer acquisition costs across defense, commercial, and scientific verticals. Platform selection directly constrains payload capacity, endurance metrics, and ground infrastructure requirements.
Product Type:
Structural rigidity defines manufacturing complexity, envelope material specifications, and all-weather operational thresholds for buoyant lift systems.
- Hybrid:Combines aerostatic buoyancy with aerodynamic wing surfaces to expand useful load beyond pure buoyant limits. Defense agencies in the United States and United Kingdom are accelerating evaluation programs for these platforms as they unify payload capacity and endurance metrics that previously required trade-offs.
- Non-Rigid:Blimp configurations rely entirely on internal gas pressure for structural integrity, enabling rapid deployment and simplified ground handling. Demand concentrates in advertising and event deployments where operational flexibility outweighs payload constraints.
- Rigid:Internal framework maintains envelope shape independent of gas pressure, delivering structural margins for all-weather military applications.
- Semi-Rigid:Keel structure provides partial rigidity, balancing payload capacity with manufacturing cost efficiency for mid-scale commercial operators.
Mature deployment sits with Non-Rigid platforms. Newer deployment is concentrated in Hybrid architectures.
End User:
Customer procurement authority shapes contract scale, certification stringency, and platform lifecycle economics across public and private demand pools.
- Surveillance:Military and border security agencies procure long-endurance platforms for persistent aerial reconnaissance exceeding conventional drone loiter times. Procurement budgets from defense agencies are expanding as persistent aerial reconnaissance requirements drive platform specifications toward rigid and hybrid architectures.
- Cargo Transport:Heavy-lift logistics applications target remote mining and energy infrastructure projects where runway access is absent. Operators in Canada and Australia are piloting outcome-based leasing models that prioritize flight-hour availability over capital deployment on specialized ground infrastructure.
- Travel & Tourism:Passenger flight operations sustain German engineering expertise through specialized route certifications.
- Advertising:Event deployment contracts favor rapid ground-handling simplicity over payload optimization.
Volume leadership belongs to Surveillance. Steepest expansion trajectory is emerging in Cargo Transport.
Application:
Mission profile dictates altitude requirements, sensor integration complexity, and regulatory jurisdiction for flight operations.
- Military Operations:Combat support and reconnaissance missions demand all-weather reliability and electromagnetic hardening. Defense agencies specify rigid-frame architectures with vectored thrust systems for precision maneuvering in contested airspace.
- Disaster Relief:Rapid deployment of communications relay and supply distribution capabilities targets infrastructure collapse scenarios. Humanitarian operators prioritize non-rigid configurations for simplified logistics in austere environments.
- Scientific Research:Atmospheric monitoring and stratospheric sampling missions require specialized sensor integration.
- Corporate Events:Brand visibility and aerial photography contracts emphasize aesthetic envelope design over technical performance.
Established operational density centers on Military Operations. Emerging application intensity is concentrating in Disaster Relief.
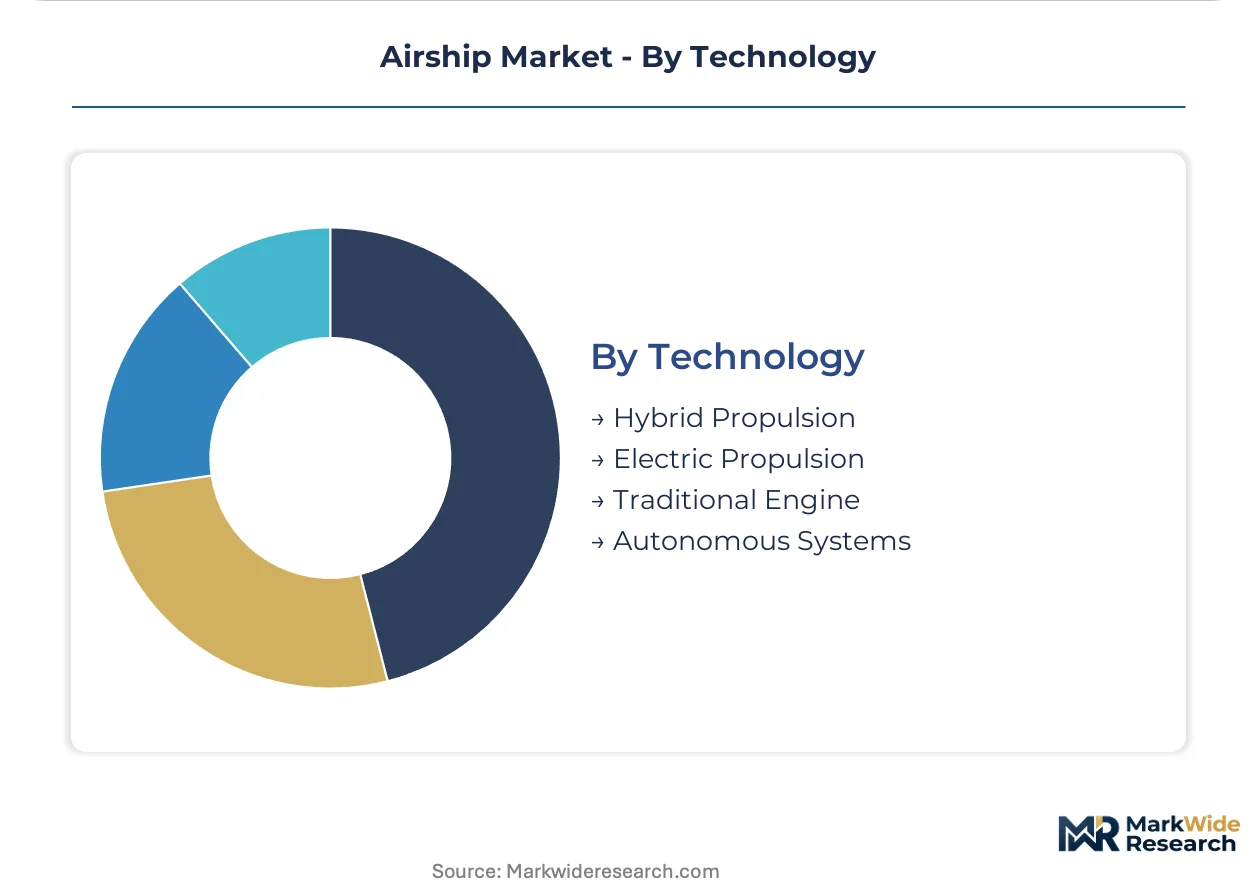
Technology:
Propulsion architecture determines emissions profile, noise signature, and maintenance interval economics for platform operators.
- Hybrid Propulsion:Combines buoyant lift with vectored thrust systems for precision maneuvering and expanded operational envelopes. Defense evaluation programs in the United States and United Kingdom are accelerating as these systems unify payload capacity with endurance metrics.
- Electric Propulsion:Battery-electric or hydrogen fuel cell systems enable zero-emission operations aligned with EU Green Deal transport frameworks. German and French regulators are advancing draft protocols for cryogenic hydrogen storage in semi-rigid frames.
- Traditional Engine:Conventional combustion powerplants retain cost advantages for commercial operators outside stringent emissions jurisdictions.
- Autonomous Systems:Remotely piloted or fully autonomous flight control reduces crew requirements for long-endurance surveillance missions.
Installed base dominance rests with Traditional Engine platforms. Technology transition momentum is gathering in Electric Propulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates state-backed cargo transport pilots and stratospheric communications programs that anchor demand-side procurement. Defense surveillance mandates in the United States and United Kingdom expand procurement budgets for persistent aerial platforms. Germany sustains engineering dominance through specialized passenger flight operations and rigid-frame construction expertise.
United States
Military agencies drive procurement for long-endurance reconnaissance platforms that exceed conventional drone loiter times. The FAA's updated Part 21 airworthiness criteria for lighter-than-air vehicles compresses certification timelines and reduces manufacturer entry barriers. California hosts LTA Research's development programs for next-generation buoyant lift systems targeting defense applications.
China
State utility programs pilot heavy-lift cargo corridors and high-altitude platform stations for rural broadband coverage. The CAAC imposes domestic route restrictions that channel development toward military and state-utility applications rather than commercial passenger service. Aviation Industry Corp. anchors manufacturing concentration in the Yangtze River Delta region.
Germany
Passenger flight operations sustain engineering expertise in rigid-frame construction and envelope fabrication. EASA CS-30 specifications enforce fire resistance standards and ground-crew training minima that shape manufacturer design priorities. Zeppelin Luftschifftechnik anchors industrial concentration in Friedrichshafen, maintaining specialized route certifications for tourism applications.
United Kingdom
Defense evaluation programs accelerate for hybrid-lift platforms that unify payload capacity with endurance metrics. Hybrid Air Vehicles anchors British manufacturing through its Airlander program and specialized hybrid-lift intellectual property. Bedfordshire hosts the primary development cluster for semi-rigid cargo transport prototypes.
France
Regulators advance draft protocols for cryogenic hydrogen storage in semi-rigid frames under EU Green Deal alignment. Flying Whales positions development programs for zero-emission cargo corridors targeting remote mining infrastructure. The Paris-Saclay cluster concentrates R&D investment toward stratospheric communications applications.
Airship Market Vendor Landscape
Technology licensing dominates the current landscape as developers seek regulatory pathway certainty across fragmented certification jurisdictions. The vendor base distributes across rigid-frame traditionalists, hybrid-lift innovators, and hydrogen-lift specialists. Three strategic archetypes have emerged: defense-anchored primes with surveillance platform expertise, European cargo transport specialists pursuing zero-emission corridors, and industrial gas suppliers consolidating helium offtake agreements. Geographic expansion and strategic partnerships constitute the dominant competitive moves as operators seek ground infrastructure partnerships in remote mining geographies.
Within the hybrid-lift innovation tier, Hybrid Air Vehicles and LTA Research exemplify platform developers bridging aerostatic and aerodynamic force generation. Zeppelin Luftschifftechnik occupies a position among rigid-frame traditionalists sustaining passenger operations. H2 Clipper anchors the hydrogen-lift specialist archetype competing on zero-emission cargo economics for transoceanic routes. Goodyear represents the established non-rigid operator maintaining advertising and event deployment contracts where rapid ground-handling simplicity offsets payload constraints.
| Leading Market Players |
|---|
| Goodyear |
| H2 Clipper |
| Hybrid Air Vehicles |
| LTA Research |
| Airship Industries |
| Flying Whales |
| Aviation Industry Corp. |
| Lockheed Martin |
| Zeppelin Luftschifftechnik |
| Others |
Supply Flow & Price Mechanics
Hydrogen lift gas innovation in Germany and France is compressing cost structures for zero-emission cargo platforms while simultaneously concentrating helium procurement around long-term industrial gas offtake agreements. This dual-track transition creates divergent pricing power dynamics across buoyant gas-dependent versus hydrogen-ready supply chains.
Pricing Analysis
Platform availability contracts bundle flight-hour guarantees with ground infrastructure access, while hull-only procurement leaves mooring mast installation and crew certification as unbundled cost centers. Three-tier pricing structure across defense-grade certification, commercial aviation standard, and experimental permit levels separates buyers by regulatory burden. Cost compression in commercial transport tiers is intensifying because outcome-based leasing models displace capital-heavy ownership structures. Mining and energy operators in remote geographies exhibit highest price sensitivity, whereas defense surveillance agencies prioritize mission assurance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle defense procurement volumes, while specialized leasing operators aggregate demand across fragmented mining and energy accounts. Envelope fabrication expertise concentrates in Germany, the United Kingdom, and the United States, where laminated gas barrier manufacturing skills outpace vocational training pipeline output. Raw material dependencies span aerospace-grade polymers for gas barriers, high-tensile alloys for rigid frames, and cryogenic containment systems for hydrogen storage. Single-source vulnerability in helium extraction from natural gas processing in Qatar and the United States creates supply chain risk. Distribution runs through defense prime contractors, regional airship operators, and state-backed aviation conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 21 airworthiness standards erect substantial compliance barriers that protect incumbent certification holders from rapid competitive entry. This regulatory moat rewards early movers who absorbed multi-year approval timelines.
For Market Incumbents: Extend hybrid-lift intellectual property portfolios through specialized patent filings in vectored thrust integration. Secure long-term helium offtake agreements before industrial gas supplier consolidation accelerates. Invest in envelope fabrication training partnerships with German and British technical institutes to preempt capability scarcity in laminated polymer handling. For New Entrants and Emerging Players: Launch via outcome-based leasing models targeting remote mining infrastructure in Canada and Australia where runway absence creates addressable white space. Concentrate initial certification efforts on stratospheric communications platforms under EASA CS-30 pathways, where hydrogen storage safety rulemaking is advancing faster than FAA timelines. Pursue technology licensing arrangements with established envelope fabricators rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of hybrid-lift specialists and industrial gas supplier rollup of helium distribution assets. Long-term viability hinges on regulatory acceptance of hydrogen lift gas across transoceanic cargo corridors. Watch for EASA-FAA convergence on hydrogen containment standards as the critical inflection signal for platform economics normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Lift Certification Investment | FAA Part 21 approval accelerates defense procurement timelines for British and American developers. |
| Helium Offtake Agreement | Long-term industrial gas contracts insulate envelope operators from Qatar supply concentration. |
| Hydrogen Storage Safety Protocol | EASA CS-30 alignment unlocks EU Green Deal incentives for French and German cargo platforms. |
| Outcome-Based Leasing Model | Flight-hour contracts reduce capital barriers for Australian and Canadian mining operators. |
| Envelope Fabrication Training Partnership | German technical institute collaboration addresses laminated polymer skill pipeline gaps. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with airship program directors, FAA certification leads, defense procurement officers, and industrial gas supply managers. FAA Part 21 dockets, EASA CS-30 technical opinions, and CAAC route authorization records provided regulatory trajectory validation. Bottom-up platform deployment tallies across military, commercial, and scientific segments were reconciled with top-down market sizing from aviation manufacturing databases.
Data-stream reconciliation across certification timeline tracking, buoyant gas procurement contract analysis, and end-user budget disclosure triangulation informed the analytical framework. Segmentation modeling spanned structural architecture, propulsion technology, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from platform delivery schedules, helium price trajectory assumptions, and defense budget appropriation patterns. Hydrogen storage safety protocol advancement rates and stratospheric communications pilot program scaling served as industry-specific forecast inputs.
Regulatory divergence between FAA and EASA on hydrogen lift gas, helium supply disruption from natural gas processing economics, and defense budget reallocation toward satellite alternatives are the dominant revision risks. Forecasts reflect assumptions about certification timeline compression, buoyant gas price stability, and hybrid-lift technology maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Amphibious Aircraft Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
UK Aviation Market
Aircraft
North America General Aviation Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Europe Aviation Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
US Aviation Market
Aircraft
Latin America General Aviation Market
Aircraft
Europe General Aviation Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Fixed Wing Aircraft Rivets Market