
 Dried Scallop Market | 2026-2036
Dried Scallop Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Scallop Market Foresight
Sun-dried processing is consolidating share from salt-cured alternatives as producers target lower sodium profiles and cleaner ingredient decks. Gyoren Hokko leverages its Hokkaido drying facilities to sustain year-round supply of Hokkaido-caught specimens. Blue Harvest Fisheries anchors North American distribution through direct relationships with specialty seafood retailers. Lund's Fisheries differentiates via controlled-atmosphere packaging that extends shelf life without chemical preservatives.
Dried scallop denotes the adductor muscle of scallops (primarily Patinopecten yessoensis and Chlamys farreri) dehydrated to moisture levels below 15 percent, yielding a concentrated protein source with pronounced glutamate content valued for broth enhancement and seasoning applications. The product type landscape shows dried scallop granules capturing fastest growth as food manufacturers reformulate instant soup bases and seasoning blends for cleaner labels. Vacuum packs command margin concentration among packaging types by preserving volatile aromatic compounds that degrade in permeable alternatives.
Japan's MHLW enforces residual moisture and heavy-metal thresholds through Food Sanitation Act standards, while China's SAMR mandates traceability coding under revised aquatic product safety regulations. The EU's REACH framework and EFSA contaminant limits govern import eligibility for European-bound shipments. Stakeholders must monitor evolving maximum residue limits for cadmium and mercury, as tightening thresholds in major import jurisdictions will force upstream investment in testing infrastructure and alternative sourcing from cleaner fishing grounds.
Market Dynamics
Sun-dried processing is displacing salt-cured methods as producers respond to sodium-reduction mandates from China's SAMR and Japan's MHLW, while vacuum packaging investments concentrate margin capture among facilities with controlled-atmosphere capabilities.
Growth Catalysts
- Clean-label reformulation:Food manufacturers are replacing synthetic flavor enhancers with dried scallop granules to meet EFSA and FDA guidance on natural ingredient declarations.
- SAMR traceability mandates:China's revised aquatic product safety regulations are accelerating digital origin-verification systems that reduce counterfeit penetration in premium segments.
- Umami extraction technology:Enzymatic hydrolysis methods are unlocking higher glutamate yields from lower-grade raw material, expanding usable supply pools.
Market Restraints
- Input cost volatility:Wild Patinopecten yessoensis landings fluctuate with Hokkaido sea-surface temperatures, compressing processor margins during poor harvest years.
- Heavy-metal thresholds:Japan's Food Sanitation Act and EU REACH cadmium limits are disqualifying scallops from historically productive fishing grounds near industrial estuaries.
- Fresh-frozen substitution:Blast-frozen adductor muscle is capturing share in quick-service broth applications where rehydration time disadvantages dried product.
Strategic Opportunities
- Southeast Asia penetration:Vietnam and Thailand's expanding middle-class dining sectors present underdeveloped channels for premium dried whole scallops beyond traditional Cantonese markets.
- Pharmaceutical-grade collagen:Marine collagen extraction from processing waste aligns with MFDS and TGA cosmetic-ingredient registration pathways.
- Direct-to-chef platforms:Specialty seafood e-commerce is bypassing layered wholesale markups in North American and European urban centers.
Industry Challenges
- Moisture calibration expertise:Achieving sub-15% residual moisture without case-hardening requires skilled kiln operators in short supply across processing regions.
- Multi-jurisdiction testing burdens:Exporters must maintain parallel heavy-metal documentation for FDA, EFSA, and MHLW specifications, stretching laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Scallop Market |
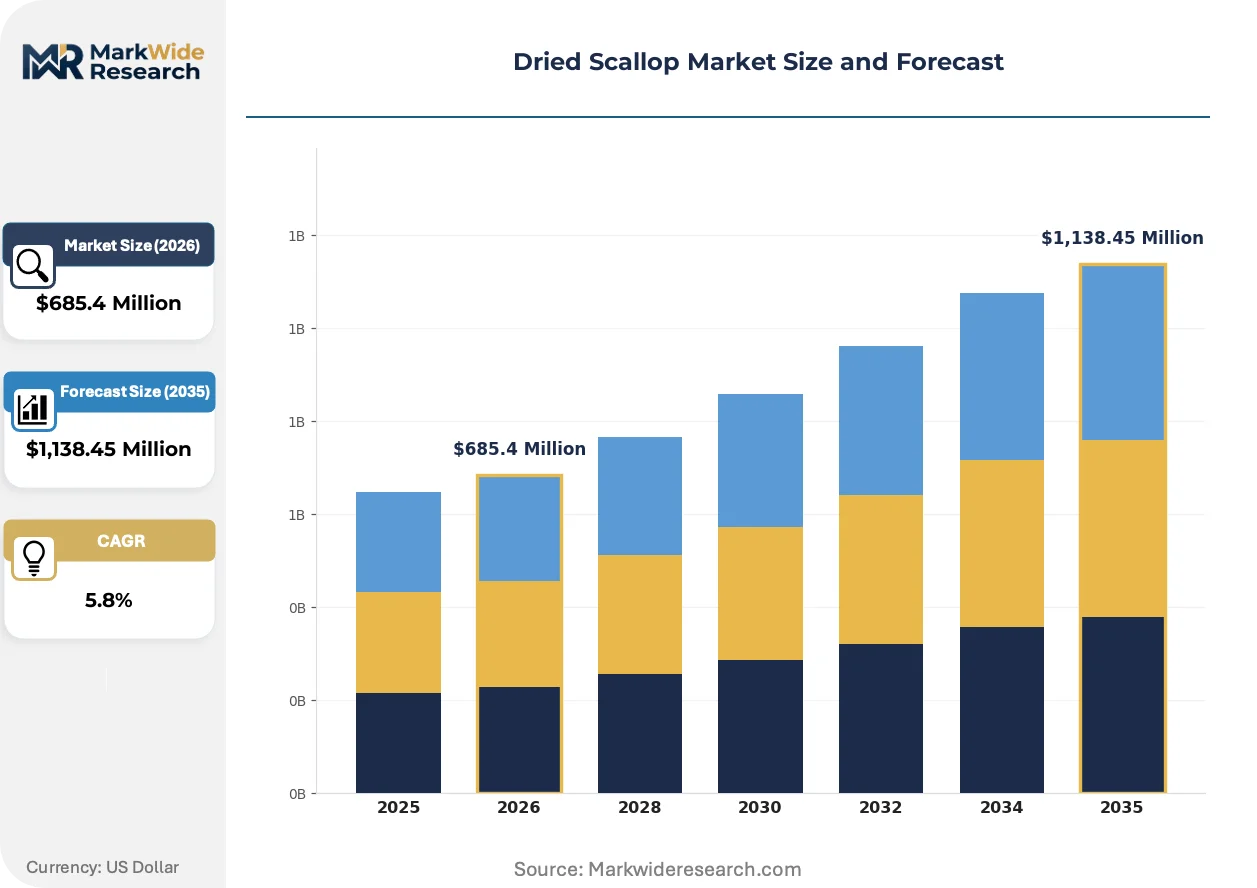
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Whole Scallops, Dried Scallop Meat, Dried Scallop Granules, Dried Scallop Powder End User: Restaurants, Retail Chains, Food Manufacturers, Seafood Distributors Packaging Type: Bags, Jars, Cans, Vacuum Packs Quality Grade: Premium, Standard, Organic, Conventional |
| Companies Covered | Lund's Fisheries, Blue Harvest Fisheries, Gyoren Hokko, Hannaford Bros. Co., LLC, Fruge Seafood Company, WHOLEY'S, Seacore Seafood Inc, HK JEBN, Seng Hong Company (Private) Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Scallop Market Shifts & Advancements
Processing technology and regulatory transparency requirements are restructuring competitive advantage around precision dehydration and blockchain-verified provenance systems.
Solar-assisted drying infrastructure is decentralizing production geography beyond traditional Hokkaido and Dalian processing clusters. Smaller-scale facilities in Vietnam and Indonesia are adopting hybrid solar-thermal kiln designs that reduce fuel dependence. This technology is decentralizing supply concentration that historically favored large coastal processors with consistent grid energy access.
REACH and EFSA are tightening maximum residue limits for cadmium and mercury in marine products destined for European markets. Processors must now source from fishing grounds with documented low-contaminant profiles or invest in upstream testing infrastructure. Premium-grade dried whole scallops face the steepest compliance burden, as these command prices justifying traceability investments that economy grades cannot support.
Gourmet restaurant kitchens are consolidating procurement through specialized seafood purveyors who provide lot-specific origin documentation and sensory consistency guarantees. This channel shift is compressing traditional wholesale auction volumes in favor of contracted direct supply relationships. Guangdong Province's Cantonese fine-dining establishments represent the most visible concentration of this purchasing pattern, though similar structures are emerging in Tokyo's kaiseki sector and San Francisco's upscale Chinese restaurant clusters.
Dried Scallop Market Segmentation
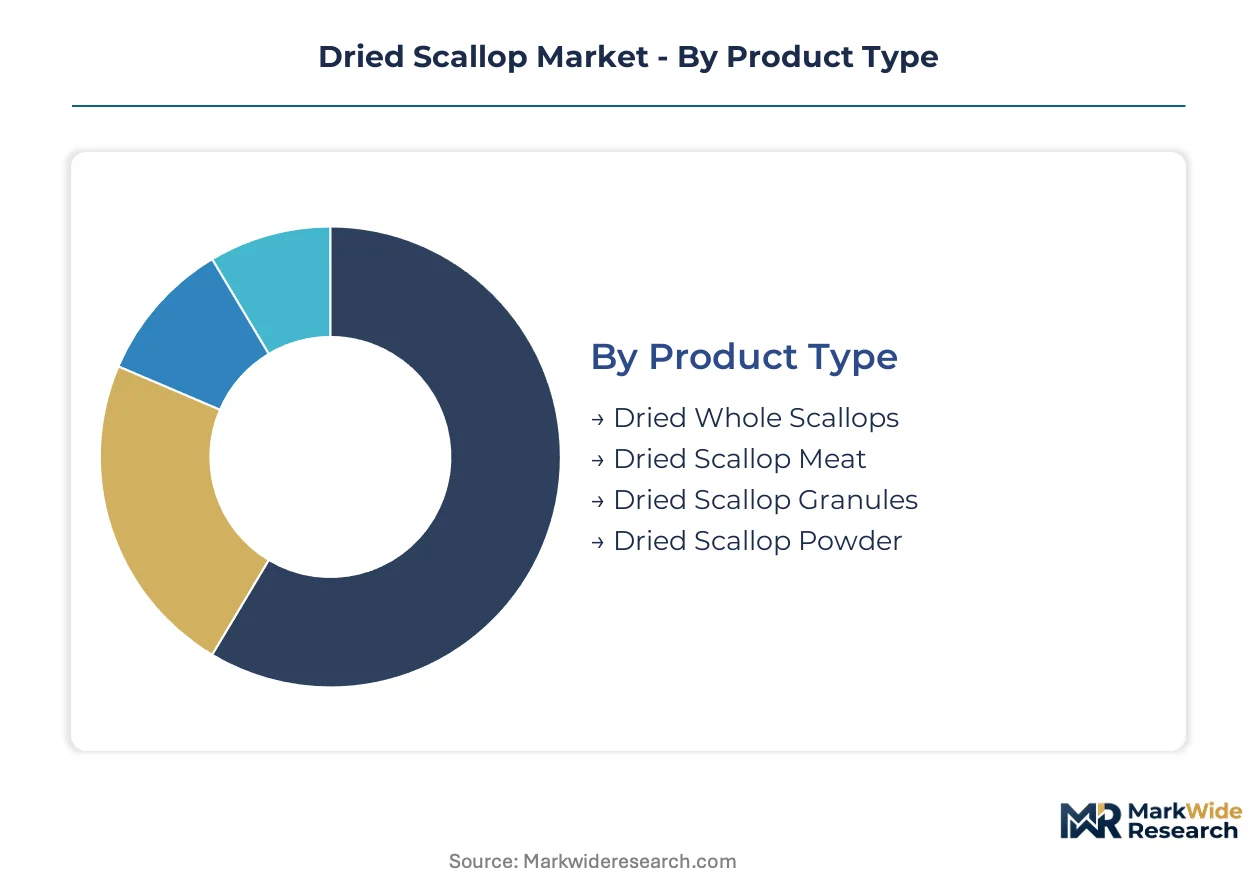
Segmentation in dried scallops reveals how capital deployment, regulatory compliance, and channel economics stratify across product forms and customer tiers. Processing infrastructure requirements and end-use specifications create divergent margin profiles that reward specialized positioning.
Product Type:
Capital intensity varies sharply across dehydration equipment scales, with whole-muscle processing demanding controlled-atmosphere kilns while granule production leverages continuous-flow drying lines at lower unit costs.
- Dried Whole Scallops:Individual adductor muscles dehydrated intact to sub-15% moisture, preserving structural integrity for premium rehydration applications. Cantonese fine-dining establishments in Guangdong Province specify these for ceremonial broth preparations where intact texture signals quality. Hokkaido processors dominate supply through proprietary slow-drying protocols that prevent case-hardening.
- Dried Scallop Granules:Precision-cut fragments optimized for rapid flavor extraction in commercial soup bases and seasoning blends. Food manufacturers targeting clean-label reformulation are consolidating procurement here as EFSA and FDA guidance tightens on synthetic additive declarations. Enzymatic hydrolysis investments are expanding usable raw material pools for this tier.
- Dried Scallop Meat:Sectioned muscle pieces targeting mid-market rehydration applications where whole-scallop presentation is not required. Retail chains in East Asian markets stock these for home cooking segments.
- Dried Scallop Powder:Fine-milled product for industrial flavor systems and nutritional fortification. Pharmaceutical-grade collagen extraction from processing waste is creating secondary value streams for this segment.
Most installed capacity flows through Dried Whole Scallops. Expansion is steepest in Dried Scallop Granules.
End User:
Customer procurement patterns segment by documentation requirements and volume scale, with regulatory traceability mandates filtering supplier eligibility across tiers.
- Restaurants:Direct relationships with specialty seafood purveyors now dominate, with lot-specific origin documentation and sensory consistency guarantees replacing auction-based sourcing. Tokyo kaiseki establishments and San Francisco upscale Chinese clusters are replicating Guangdong's contracted supply model.
- Food Manufacturers:Bulk granule and powder procurement for instant soup base and seasoning blend reformulation. These buyers enforce SAMR traceability coding and EFSA contaminant documentation as table stakes.
- Retail Chains:Packaged whole scallops and meat segments for consumer pantry staples, with vacuum packaging specifications preserving shelf-life claims without chemical preservatives.
- Seafood Distributors:Intermediary layer facing compression as direct-to-chef platforms and manufacturer consolidation bypass traditional wholesale markups.
Procurement is shifting most decisively toward Restaurants. Food Manufacturers are gaining share fastest as clean-label reformulation accelerates.
Packaging Type:
Margin capture concentrates in barrier technologies that preserve volatile aromatic compounds, with vacuum and controlled-atmosphere systems requiring differentiated capital outlays.
- Vacuum Packs:Multi-layer films with oxygen transmission rates below 1 cc/m²/day, preserving glutamate-rich volatile compounds that degrade in permeable alternatives. Premium-grade whole scallops command price premiums justifying this packaging investment.
- Jars:Rigid containment for gift-oriented and ceremonial segments, with moisture-barrier seals meeting Japan's MHLW residual moisture thresholds.
- Bags:Flexible packaging for economy-tier granules and powders where barrier specifications are less stringent and price sensitivity dominates.
- Cans:Metal containment for extended shelf-life requirements in institutional and export logistics, though declining share as flexible barrier films improve.
Production gravity centers on Vacuum Packs. Jars are climbing the fastest as premium positioning intensifies.
Quality Grade:
Certification tiers stratify by contaminant testing burden and origin verification depth, with premium grades absorbing disproportionate compliance costs.
- Premium:Patinopecten yessoensis from documented low-cadmium Hokkaido fishing grounds, with full blockchain-verified provenance and parallel FDA-EFSA-MHLW heavy-metal documentation. These specifications justify traceability investments that economy grades cannot support.
- Organic:Certified cultivation and processing protocols meeting EU organic regulation and Japan's JAS standards, with restricted input specifications and audit trails.
- Standard:Conventional processing meeting baseline regulatory thresholds without premium origin or certification claims, serving price-sensitive institutional channels.
- Conventional:Unspecified sourcing with minimal documentation, facing disqualification from major import jurisdictions as REACH and EFSA cadmium limits tighten.
Testing infrastructure investment concentrates in Premium. Organic is gaining share fastest as certification premiums widen in European and Japanese markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hokkaido's processing corridor dominates dried scallop manufacturing through proprietary slow-drying protocols and year-round supply continuity. Regional differentiation stems from contaminant profiles, traceability infrastructure, and channel access rather than raw volume alone.
China
Guangdong Province's Cantonese fine-dining establishments drive bulk procurement of premium-grade whole scallops for ceremonial broth preparations. SAMR's tightened aquatic product labeling rules now mandate verified origin documentation and moisture content certification for all export-bound shipments. Dalian's coastal processing clusters are consolidating capacity as smaller operators face compliance burdens from digital traceability system investments.
Japan
Tokyo's kaiseki sector and Osaka's upscale restaurant clusters are replicating Guangdong's direct-contract procurement model with specialty seafood purveyors. MHLW's Food Sanitation Act enforces strict residual moisture and heavy-metal thresholds that disqualify scallops from historically productive industrial estuary grounds. Hokkaido's drying facilities sustain year-round supply through controlled-atmosphere kilns that prevent case-hardening in Patinopecten yessoensis processing.
United States
San Francisco's upscale Chinese restaurant clusters and New York's fine-dining establishments are consolidating procurement through direct-to-chef specialty seafood platforms. FDA guidance on natural ingredient declarations is accelerating clean-label reformulation in commercial soup base manufacturing. Blue Harvest Fisheries anchors North American distribution through relationships with specialty seafood retailers in coastal urban markets.
Vietnam
Ho Chi Minh City's expanding middle-class dining sector presents underdeveloped channels for premium dried whole scallops beyond traditional Cantonese market structures. Hybrid solar-thermal kiln adoption is decentralizing production geography as smaller-scale facilities reduce fuel dependence. Solar-assisted drying infrastructure is shifting processing capacity away from traditional large coastal processors with consistent grid energy access.
South Korea
Seoul's restaurant sector and Busan's seafood distribution hubs are developing procurement relationships for pharmaceutical-grade collagen extraction from processing waste. MFDS cosmetic-ingredient registration pathways are creating secondary value streams for fine-milled dried scallop powder. Domestic processors are investing in enzymatic hydrolysis technology to unlock higher glutamate yields from lower-grade raw material inputs.
Dried Scallop Market Competitive Landscape
Global majors compete with regional champions across traceability infrastructure and controlled-atmosphere processing capabilities. The vendor base stratifies between Hokkaido-based drying specialists with proprietary protocols, North American distributors with direct retail relationships, and emerging Southeast Asian facilities adopting solar-assisted infrastructure. Three archetypes dominate: heritage processors with multi-generational drying expertise, scale-driven distributors with refrigerated logistics networks, and technology-forward operators investing in blockchain-verified provenance systems. Competitive moves concentrate on vacuum packaging capacity expansion and digital origin-verification system deployment.
Among Japanese heritage processors, Gyoren Hokko occupies a position exemplifying controlled-atmosphere kiln investment and year-round supply continuity from Hokkaido-caught specimens. North American distribution archetypes include Lund's Fisheries, which represents packaging innovation through shelf-life extension without chemical preservatives, and Blue Harvest Fisheries, which anchors specialty retail channel access. These three companies illustrate the geographic specialization and capability differentiation structuring competitive positioning.
| Leading Market Players |
|---|
| Lund's Fisheries |
| Blue Harvest Fisheries |
| Gyoren Hokko |
| Hannaford Bros. Co., LLC |
| Fruge Seafood Company |
| WHOLEY'S |
| Seacore Seafood Inc |
| HK JEBN |
| Seng Hong Company (Private) Limited |
| Others |
Supply & Pricing Matrix
Hokkaido sea-surface temperature indices governing Patinopecten yessoensis landings cascade through processor margins into three distinct pricing tiers, with poor harvest years compressing mid-market dried scallop meat segments while premium whole-scallop grades absorb volatility through contracted direct supply relationships with Guangdong's Cantonese fine-dining establishments.
Pricing Analysis
Input-cost pass-through from wild-caught raw material volatility stratifies pricing across certification tiers. Three-tier pricing structure across premium, standard, and economy levels reflects heavy-metal documentation burden and blockchain-verified provenance depth. Cost compression in standard-grade segments is intensifying because REACH and EFSA cadmium thresholds are disqualifying historically productive industrial estuary grounds. Food manufacturers purchasing dried scallop granules exhibit highest price sensitivity; kaiseki establishments in Tokyo show lowest sensitivity due to ceremonial broth specifications.
Supply Chain Analysis
China's SAMR aquatic product labeling rules and Japan's MHLW Food Sanitation Act are reshaping sourcing toward documented low-contaminant fishing grounds. Supply concentrates in Hokkaido, Dalian, and emerging Vietnamese solar-assisted facilities. Processing draws from wild Patinopecten yessoensis landings, enzymatic hydrolysis inputs, and vacuum-barrier packaging films. Single-source vulnerability runs through Hokkaido's controlled-atmosphere kiln operators, where skilled labor scarcity limits capacity expansion. Distribution runs through specialty seafood purveyors bypassing traditional wholesale auction layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on solar-assisted drying technology reducing fuel dependence and premium-grade whole scallops capturing widening certification premiums from tightening EFSA and MHLW thresholds.
For Market Incumbents: Lock in Hokkaido drying facility capacity through long-term operator contracts before skilled kiln labor scarcity worsens. Deepen upstream control over low-cadmium fishing ground access as REACH thresholds tighten. Secure vacuum packaging film supply agreements to preserve margin capture in volatile aromatic compound preservation.
For New Entrants and Emerging Players: Blockchain-verified provenance systems offer a technology-first wedge against heritage processors lacking digital traceability infrastructure. Target Ho Chi Minh City's underdeveloped middle-class dining channels beyond traditional Cantonese market structures. Pursue direct-to-chef platform partnerships in San Francisco and New York to bypass layered wholesale markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with Southeast Asian solar-assisted drying facilities combining hybrid kiln technology with proximity to underpenetrated Vietnamese and Thai dining sectors. Five-to-ten-year viability favors processors with parallel FDA-EFSA-MHLW testing infrastructure already deployed. Watch for inflection when Japan's MHLW announces revised cadmium maximum residue limits.
| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Assisted Drying Infrastructure Deployment | Hybrid kiln adoption in Vietnam reduces fuel dependence and decentralizes supply concentration from Hokkaido. |
| Blockchain-Verified Provenance System Integration | Digital origin-verification meets SAMR traceability mandates and commands premium pricing from Guangdong buyers. |
| Enzymatic Hydrolysis Technology Investment | Unlocks higher glutamate yields from lower-grade raw material, expanding usable supply pools for granule production. |
| Controlled-Atmosphere Packaging Capacity Expansion | Vacuum pack investments preserve volatile aromatic compounds that differentiate premium-grade whole scallops. |
| Pharmaceutical-Grade Collagen Extraction Pathway | MFDS and TGA cosmetic-ingredient registration creates secondary value streams from processing waste. |
Research Methodology
Direct dialogue with seafood processing plant managers, specialty seafood purveyor procurement leads, Cantonese fine-dining executive chefs, and regulatory affairs specialists at export-oriented firms grounded qualitative findings. Secondary validation drew from SAMR aquatic product safety filings, Japan MHLW Food Sanitation Act standards, EFSA contaminant limit documentation, customs and trade data, and SEC filings from publicly traded seafood distributors. Bottom-up capacity assessments and top-down demand modeling triangulated segment-level outputs.
Segmented projections across product type, end user, packaging format, quality grade, and regional production hub fed into analytical framework outputs over the projection horizon. CAGRs derived from weighted average growth across modeled segments, with inputs including Hokkaido landing volume variability, solar-assisted drying adoption curves, and clean-label reformulation penetration in commercial soup base manufacturing.
The model holds under stable regulatory threshold assumptions; deviation in MHLW or EFSA heavy-metal limit revisions would shift premium-grade supply availability and pricing tier boundaries. Forecasts reflect documented landing patterns, infrastructure investment pipelines, and channel consolidation trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
North America Frozen and Canned Seafood Market
Seafood
Smoked Salmon Market
Seafood
North America Frozen Seafood Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Europe Lobster Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Carp Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Dry-Packaged Scallops Market
Seafood
Salmon Market
Seafood
United States Seafood Market
Seafood
Tinned Fish Market
Seafood
Shellfish Extract Market
Seafood
Fish Meal Market
Seafood
North America Seafood Market
Seafood
United States Salmon Market