
 Global Smoked Fish Market | 2026-2036
Global Smoked Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smoked Fish Market Outlook
Portion-controlled retail packs and single-serve snack formats is recalibrating buyer choice across retail and food service channels. Thai Union Group leverages its integrated aquaculture-to-retail network to sustain volume leadership in private-label smoked salmon. Marine Harvest ASA anchors its position through captive breeding operations and controlled cold-chain distribution across European markets. Labeyrie Fine Foods differentiates via heritage smoking techniques and premium positioning in French and Belgian retail.
Smoked fish denotes seafood preserved through controlled exposure to wood smoke, typically at temperatures between 80°F for cold smoking and 180°F for hot smoking, yielding shelf-stable protein with distinctive flavor profiles for direct consumption or ingredient use. Salmon dominates value generation due to its oil content and consumer recognition, while cold-smoked preparations command premium positioning against faster-turnover hot-smoked alternatives. Mackerel and herring segments occupy volume-driven niches in Northern European retail and industrial processing channels.
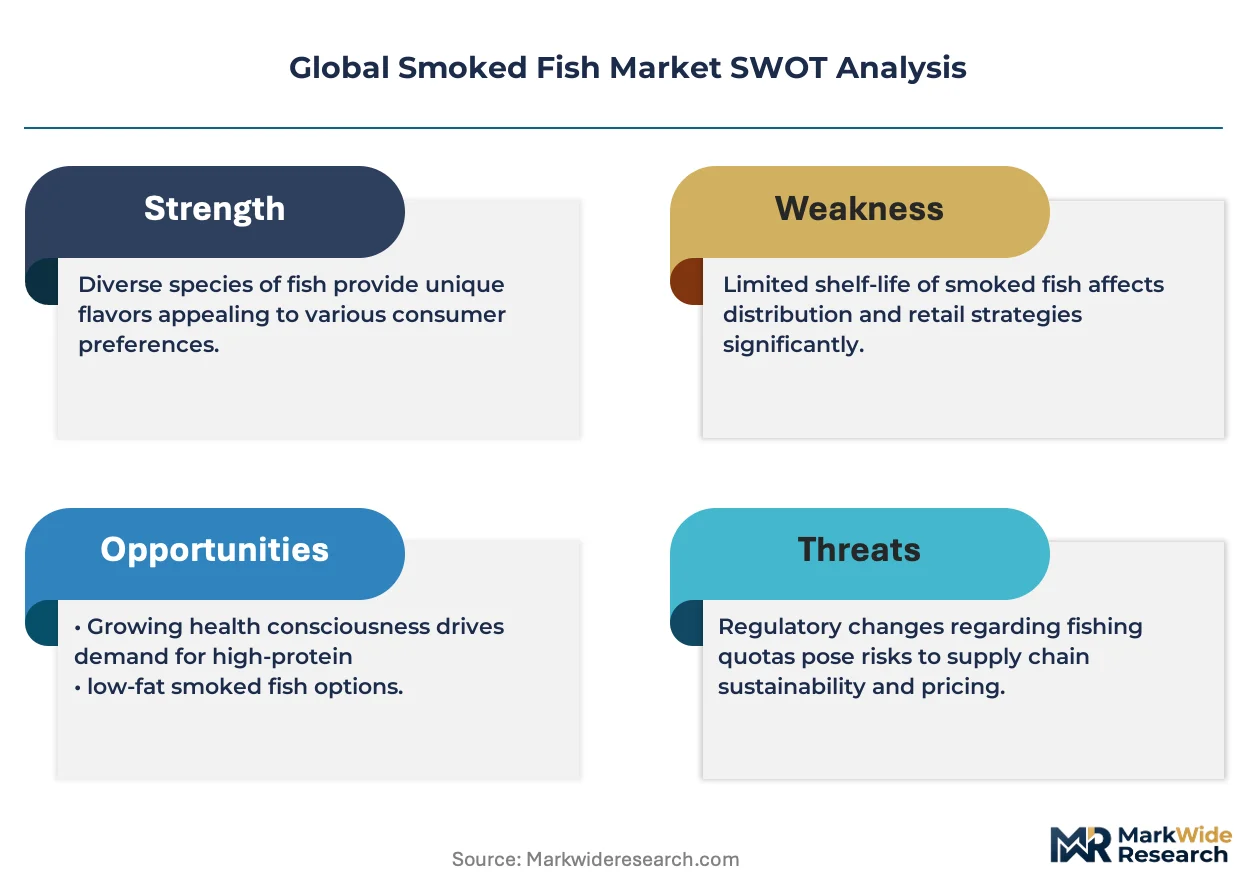
FDA seafood HACCP regulations and EU EFSA hygiene standards govern processing facility certification and cold-chain documentation, raising compliance costs for export-oriented smokers. REACH chemical frameworks and EU Green Deal sustainability criteria are pressuring packaging material selection and waste-water treatment investments. Stakeholders must monitor evolving carbon-accounting requirements for aquaculture feed and smokehouse energy use.
Market Dynamics
EU EFSA hygiene standards and FDA seafood HACCP regulations are tightening cold-chain documentation requirements, forcing capital redeployment toward traceability infrastructure and automated smokehouse monitoring systems across export-oriented processors.
Growth Catalysts
- EU Green Deal sustainability criteria:Carbon-accounting mandates for aquaculture feed and smokehouse energy use are accelerating investments in renewable-powered processing facilities.
- Food service premium menu expansion:North American and European operators are elevating smoked salmon and trout preparations, pulling volume through higher-margin channels.
- Cold-smoking tradition clusters:Norway, Scotland, and the Pacific Northwest of the United States combine aquaculture infrastructure with heritage techniques, anchoring export-oriented production.
Market Restraints
- Input cost volatility:Wood chip and specialty salt prices fluctuate with forestry harvest cycles and energy-intensive evaporation costs.
- Supply concentration risk:Norwegian and Scottish processors dominate premium cold-smoked salmon, creating bottleneck exposure for buyers seeking certified origin.
- Technical shelf-life limitation:Cold-smoked products require uninterrupted refrigeration, constraining distribution reach into emerging markets with weak cold-chain infrastructure.
Strategic Opportunities
- Underpenetrated Southeast Asian retail:Urban middle-class expansion in Vietnam and Indonesia presents white space for portion-controlled snack formats.
- Plant-based hybrid positioning:Convergence of traditional smoking techniques with algae-derived protein substrates opens novel category creation.
- Direct-to-restaurant subscription channels:Chef procurement platforms are bypassing traditional wholesale tiers, enabling margin capture and relationship ownership.
Industry Challenges
- Smokehouse technician scarcity:Mastery of temperature-humidity curves for consistent cold-smoking requires years of apprenticeship, constraining facility expansion.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and national organic approvals extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smoked Fish Market |
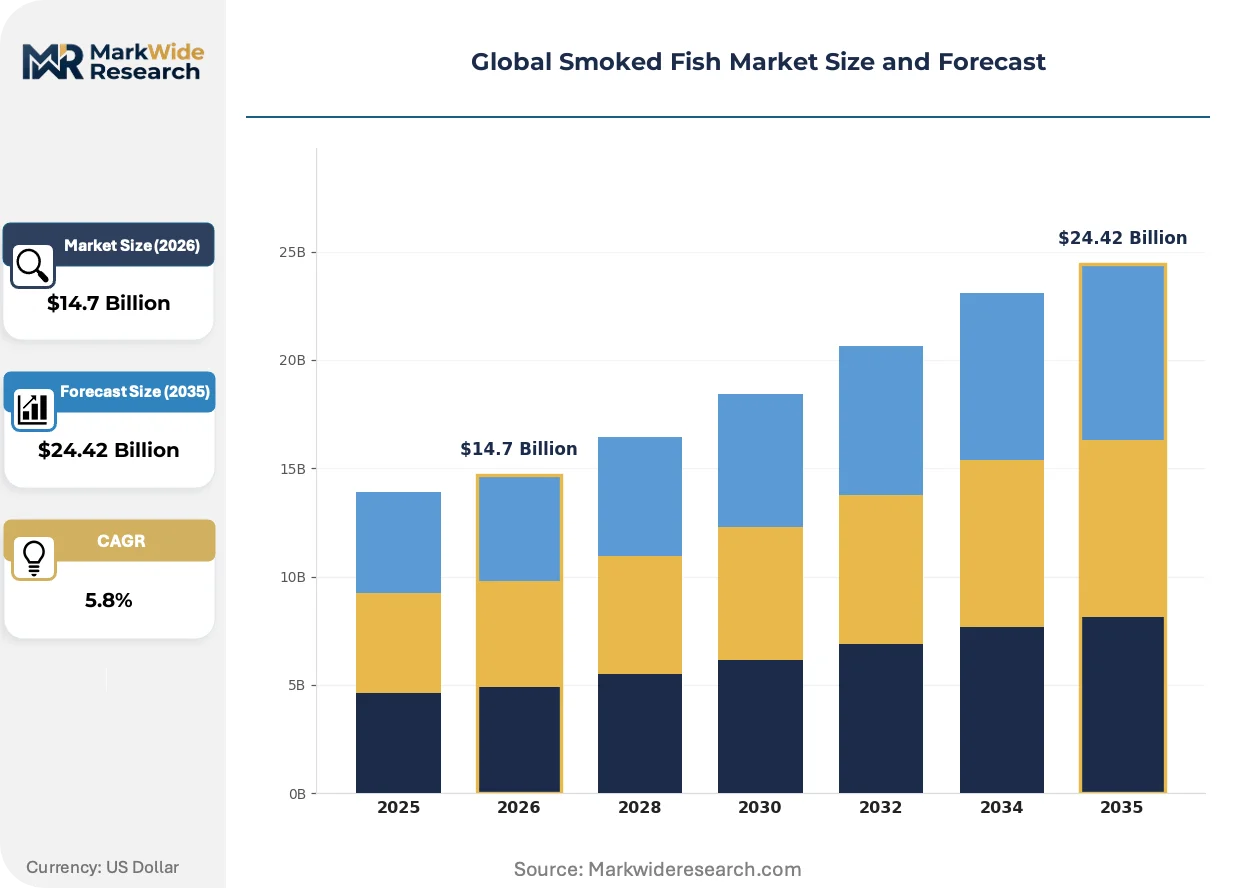
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon, Trout, Mackerel, Herring Processing Method: Hot Smoked, Cold Smoked, Dry Smoked, Liquid Smoked Distribution Channel: Supermarkets, Online Retailers, Fish Markets, Restaurants Consumer Type: Residential, Food Service, Industrial, Catering |
| Companies Covered | Thai Union Group, Marine Harvest ASA, Acme Smoked Fish Corporation, Seabear Smokehouse, Ducktrap River of Maine, Labeyrie Fine Foods, Mowi ASA, Foppen Group BV, Leroy Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smoked Fish Market Strategic Shifts
Smokehouse automation and alternative wood sourcing are compressing traditional craft boundaries, while regulatory carbon tracking and direct-channel procurement are rewriting how value flows from aquaculture to final plate.
Electrochemical smoke generation systems are replacing conventional wood-burning chambers in large-scale facilities. European processors in the Netherlands and Denmark are adopting these units fastest, driven by REACH framework pressure on particulate emissions. This technology is absorbing capital that previously expanded traditional kiln capacity, consolidating processing into fewer automated sites.
REACH chemical frameworks and EU Green Deal sustainability criteria are mandating packaging material audits and wastewater treatment upgrades. Processors must now document polymer composition and effluent particulate loads to maintain export authorization. Smoked salmon exporters to Germany and France face the steepest compliance ramps, with several Scottish facilities retrofitting biological filtration systems.
Chef procurement through specialized seafood platforms is fragmenting traditional wholesale concentration. Independent restaurants in London, New York, and Tokyo now source directly from named smokehouses, bypassing distributor markups. This pattern is most visible in premium cold-smoked segments where origin story and batch-specific flavor profiles command menu placement premiums.
Global Smoked Fish Market Segmentation
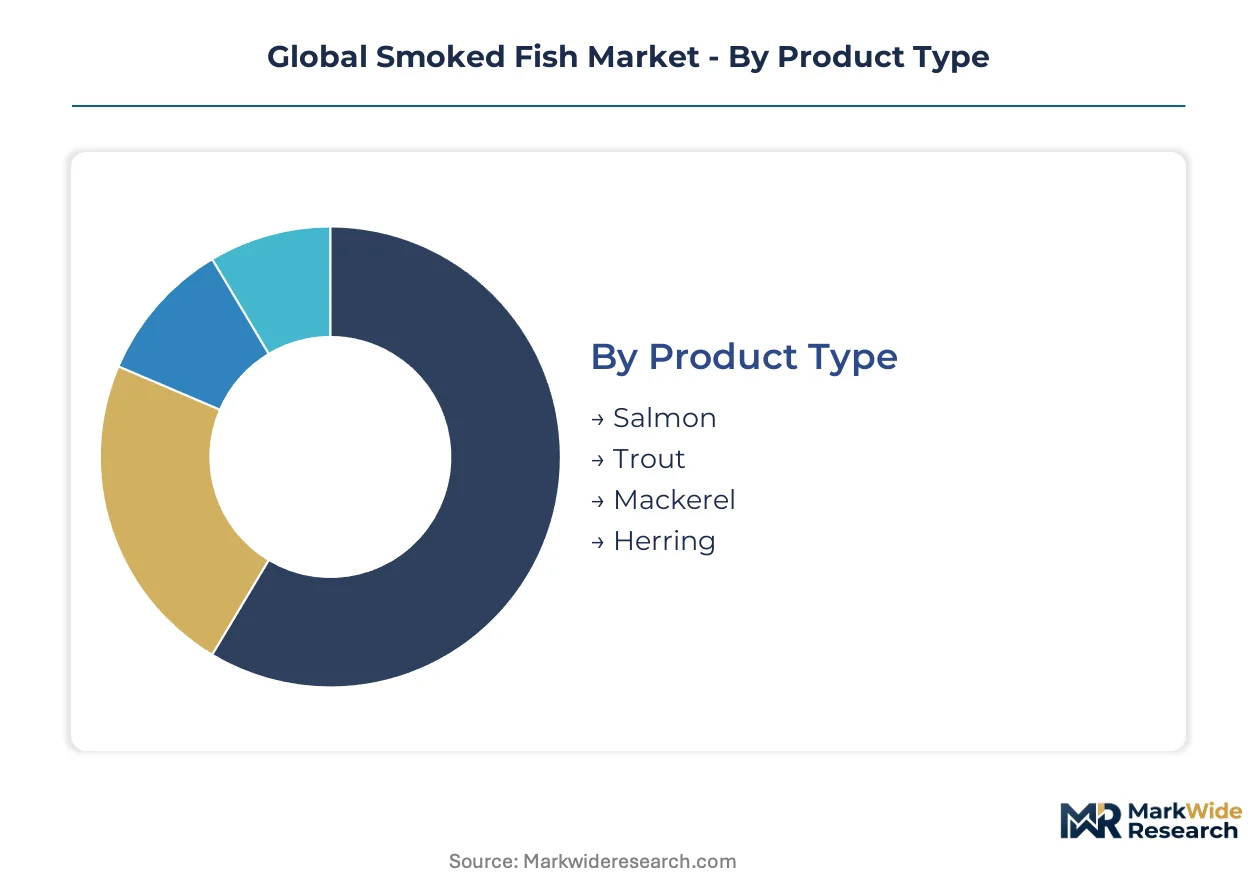
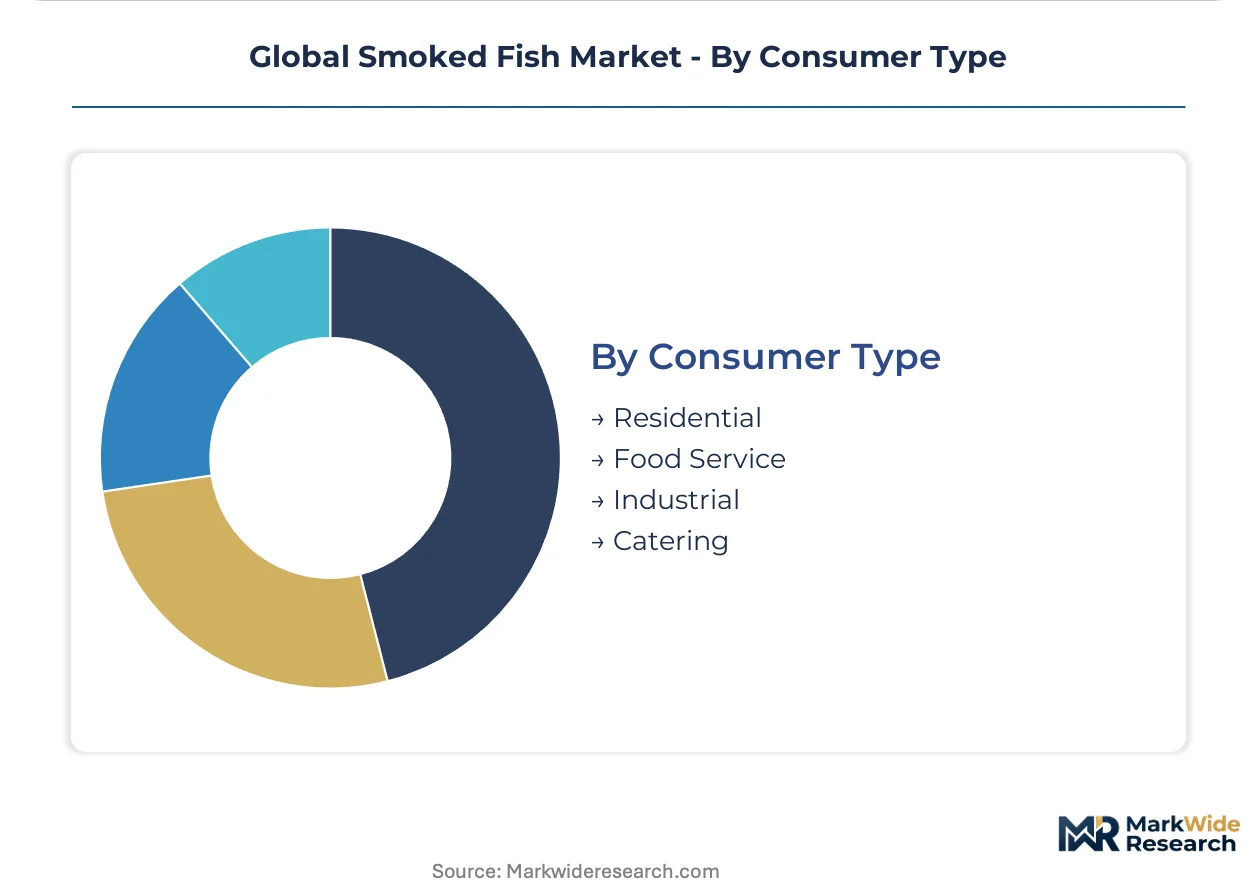
Segmentation in smoked fish markets determines which processing investments, cold-chain specifications, and certification pathways processors must navigate. Each dimension carries distinct regulatory burdens and margin structures that shape competitive positioning.
Product Type:
FDA seafood HACCP and EFSA hygiene standards impose species-specific hazard analysis requirements, with oil-rich varieties demanding more rigorous parasite destruction documentation.
- Salmon:High-fat Atlantic and Pacific species dominate cold-smoked premium tiers. Norwegian and Scottish aquaculture operations supply food service operators in New York, London, and Tokyo with sashimi-grade preparations. EFSA traceability mandates and FDA import alerts on listeria contamination drive batch-level testing investments.
- Trout:Rainbow and steelhead varieties occupy mid-premium positioning with faster farm-to-smokehouse cycles. Danish and Polish processors leverage shorter supply chains to serve German and Benelux retail with fresher-turnover products. EU organic certification requirements concentrate production among integrated aquaculture-smokehouse operations.
- Mackerel:High-turnover hot-smoked formats serve Northern European industrial channels and canned fish processors.
- Herring:Traditional Baltic and North Sea smoking methods supply Eastern European retail and pickled fish manufacturers.
Leading the category by volume: Salmon. Growing fastest: Trout.
Processing Method:
Cost tier stratification separates capital-intensive automated smokehouses from artisan kiln operations, with regulatory compliance costs widening the gap.
- Hot Smoked:Temperatures above 140°F deliver fully cooked proteins with extended ambient shelf stability. Thai and Vietnamese processors supply Southeast Asian retail and street food vendors with lower-price-point formats. Reduced refrigeration requirements open distribution into emerging markets with weak cold-chain infrastructure.
- Cold Smoked:Sub-90°F exposure over 12-48 hours preserves raw texture and commands menu placement premiums. Norwegian, Scottish, and Pacific Northwest smokehouses dominate export supply to US and Japanese premium retail. Continuous refrigeration mandates and FDA listeria monitoring requirements constrain producer entry.
- Dry Smoked:Salt-cure pre-treatment extends shelf life for traditional European retail formats.
- Liquid Smoked:Atomized smoke condensate applications serve industrial ingredient and flavoring markets.
Volume leadership: Hot Smoked. Fastest expansion: Cold Smoked.
Distribution Channel:
Customer type determines packaging specifications, with food service demanding bulk fillets and retail requiring portion-controlled formats with extended label claims.
- Supermarkets:Private-label and branded chilled cases drive volume across UK, French, and German grocery chains. Retailers mandate BRC certification and EU allergen labeling compliance from suppliers. Portion-controlled 100-150g packs with transparent origin claims command shelf positioning premiums.
- Online Retailers:Direct-to-consumer chilled delivery requires insulated packaging and time-temperature logging. UK and Dutch specialists leverage subscription models to bypass wholesale markups. Last-mile refrigeration failures drive return rates and customer acquisition costs.
- Fish Markets:Traditional counter service persists in Southern European and Japanese urban centers with freshness-verification demands.
- Restaurants:Chef procurement platforms fragment traditional distributor concentration in London, New York, and Paris.
Volume concentration: Supermarkets. Fastest channel growth: Online Retailers.
Consumer Type:
Application maturity separates established residential occasions from emerging industrial ingredient demand.
- Residential:Weekend breakfast and entertaining occasions drive premium cold-smoked salmon purchases in UK, US, and Australian households. Retailers respond with smaller-format packs and extended use-by dating. E-commerce penetration accelerates in urban markets with limited traditional fish retail access.
- Food Service:Brunch menu standardization and sushi-grade applications pull volume through higher-margin channels. Independent restaurants in Copenhagen, Melbourne, and San Francisco source named-origin smokehouse products directly. Plate-cost pressures favor hot-smoked alternatives in casual dining tiers.
- Industrial:Flaked and diced formats supply ready-meal manufacturers and sandwich processors.
- Catering:Event and corporate dining demand concentrates in metropolitan clusters with established smoked fish traditions.
Category volume leader: Residential. Steepest expansion trajectory: Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian aquaculture zones and Scottish enterprise areas concentrate cold-smoked salmon capacity through targeted tax incentives and export processing infrastructure. These designated zones attract integrated smokehouse investments with streamlined customs and cold-chain certification support.
Norway
Coastal aquaculture clusters in Bergen and Tromsø supply premium cold-smoked Atlantic salmon to Japanese and US retail channels. The Norwegian Food Safety Authority enforces strict parasite control documentation for export-grade facilities. Trøndelag processing corridors anchor automated smokehouse capacity serving EU and Asian markets.
United States
Pacific Northwest smokehouses in Seattle and Portland draw on regional hatchery networks for steelhead and coho production. FDA seafood HACCP regulations mandate continuous cold-chain monitoring for interstate distribution. Brooklyn-based processors serve Manhattan restaurant demand through direct chef procurement platforms.
United Kingdom
Scottish salmon smokehouses in the Highlands and Islands leverage Protected Geographical Indication status for premium positioning. Food Standards Agency hygiene audits align with EU EFSA residual standards for continental export. Grimsby industrial processors handle volume mackerel and herring for Northern European retail.
Germany
North Sea ports in Hamburg and Bremerhaven import Scandinavian raw material for domestic smoking and redistribution. REACH chemical frameworks restrict packaging polymer composition for retail-bound products. Bavarian specialty retailers drive demand for traditional dry-smoked formats with extended shelf stability.
Japan
Tokyo and Osaka metropolitan clusters consume sashimi-grade cold-smoked salmon through department store delis and sushi chains. Ministry of Health, Labour and Welfare import inspections enforce rigorous listeria and parasite documentation. Hokkaido coastal smokehouses serve domestic markets with Pacific salmon varieties.
Global Smoked Fish Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. The vendor base stratifies between integrated aquaculture-smokehouse operators and standalone processors sourcing raw material on spot markets. Three archetypes dominate: vertically integrated Norwegian-Scottish salmon giants, European heritage-brand specialists, and North American regional smokehouses serving metropolitan restaurant demand. Capacity expansion and direct-to-chef channel development represent the dominant competitive vectors.
Among integrated aquaculture operators, Marine Harvest ASA and Mowi ASA exemplify scale-driven vertical control from breeding through cold-chain distribution. Thai Union Group anchors the diversified conglomerate archetype with private-label volume leadership across retail channels. Labeyrie Fine Foods occupies the heritage-specialist position, leveraging traditional smoking techniques for premium retail placement in French and Belgian markets.
| Leading Market Players |
|---|
| Thai Union Group |
| Marine Harvest ASA |
| Acme Smoked Fish Corporation |
| Seabear Smokehouse |
| Ducktrap River of Maine |
| Labeyrie Fine Foods |
| Mowi ASA |
| Foppen Group BV |
| Leroy Seafood Group |
| Others |
Value Chain & Pricing Dynamics
Electrochemical smoke generation adoption in Dutch and Danish processing facilities is compressing traditional kiln economics while consolidating capacity into fewer automated sites, simultaneously raising capital barriers for artisan competitors and shifting margin capture toward technology-integrated operators. This production-method transition feeds back into supply concentration as REACH framework compliance costs force smaller smokehouses toward contract processing or exit.
Pricing Analysis
Lead-time premiums reward rapid farm-to-smokehouse cycles, with Norwegian and Scottish integrated operators commanding price advantages over spot-market dependent processors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain documentation depth. Cost compression in hot-smoked tiers is intensifying because Southeast Asian processors are scaling volume exports. Food service buyers exhibit lowest price sensitivity, while industrial ingredient purchasers drive aggressive contract negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian aquaculture feed suppliers and Scottish smokehouse technician labor pools, constraining expansion timelines for export-oriented processors. Raw material flows draw from Norwegian Atlantic salmon farms, Scottish hatchery networks, and Pacific Northwest steelhead operations. Tariff exposure looms as EU-UK trade friction disrupts traditional Grimsby redistribution patterns. Distribution runs through integrated cold-chain operators serving supermarket chilled cases and direct-to-chef platforms in London, New York, and Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as multi-jurisdiction certification timelines extend product launch cycles, forcing capital-constrained smokehouses toward acquisition or contract manufacturing arrangements.
For Market Incumbents: Anchor market position through captive breeding operations and automated smokehouse capacity in Trøndelag or Scottish Enterprise zones, defending against emerging electrochemical technology disruptors by locking long-term chef procurement relationships via direct subscription channels. For New Entrants and Emerging Players: Begin with portion-controlled snack formats in Vietnam and Indonesia, where urban middle-class expansion and weak incumbent cold-smoke infrastructure create penetrable white space; leverage algae-derived protein hybrid positioning to bypass traditional aquaculture supply constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated aquaculture-smokehouse operators with EU organic certification and named-origin brand equity; long-term viability favors those with upstream control over breeding stock and downstream direct-channel relationships. Watch FDA import alert frequency on listeria contamination as inflection indicator for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Smokehouse Automation Investment | REACH particulate emission mandates in the Netherlands and Denmark are accelerating electrochemical system adoption. |
| Direct-to-Chef Platform Development | Brooklyn and London restaurant procurement patterns are fragmenting traditional wholesale distributor concentration. |
| EU Organic Certification Pathway | Danish and Polish integrated operations leverage shorter supply chains for German retail premium positioning. |
| Southeast Asian Market Entry | Vietnam and Indonesia urban retail expansion supports portion-controlled format penetration beyond traditional cold-chain limits. |
| Alternative Protein Hybrid R&D | Algae-derived substrates combined with heritage smoking techniques open novel category creation adjacent to traditional aquaculture. |
Study Parameters
Multi-period observation of smokehouse capacity utilization, cold-chain certification timelines, and chef procurement platform penetration anchored the trend analysis, supplemented by interviews with aquaculture breeding directors, smokehouse operations managers, supermarket category buyers, and regulatory affairs specialists at export-oriented processors. Secondary validation drew from FDA seafood HACCP guidance documents, EU EFSA hygiene standard updates, Norwegian Food Safety Authority export statistics, and customs trade flow data. Bottom-up facility capacity modeling and top-down demand segmentation triangulation ensured cross-verification.
Input-output matrices mapped aquaculture feed volumes through smokehouse processing yields to distribution channel offtake across product type, processing method, and consumer application dimensions over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic consumption indicators. Industry-specific forecast inputs included EFSA traceability mandate implementation schedules and REACH chemical framework packaging audit timelines.
Underlying measurement precision varies by segment; cold-smoked salmon and direct-to-chef channel estimates carry tighter precision than emerging market hot-smoked volume projections. Forecasts reflect assumptions about uninterrupted cold-chain infrastructure development and stable EU-UK trade arrangements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global White Shrimp Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Milkfish Market
Seafood
Rainbow Trout Market
Seafood
Surimi Market
Seafood
Smoked Salmon Market
Seafood
Dry-Packaged Scallops Market
Seafood
Fish Oil Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
North America Seafood Market
Seafood
Mackerel Market
Seafood
Europe Shrimp Market
Seafood
Canned Fishery Product Market
Seafood
Fish Protein Concentrate Market
Seafood
Seafood Powders Market