
 South America Canned Seafood Market | 2026-2036
South America Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
South America Canned Seafood Market Analytics
ANVISA Good Manufacturing Practice certification is bifurcating the competitive landscape into compliant exporters and informal domestic packers. Grupo Calvo leverages its vertically integrated Atlantic and Pacific sourcing networks to sustain consistent raw material flows. Jealsa differentiates through specialized tuna product lines that anchor its position in premium retail channels across Brazil and Chile.
Canned seafood comprises thermally stabilized fish or shellfish preserved in hermetically sealed containers through retort processing at temperatures exceeding 121°C, with salt or oil brine maintaining shelf stability for 24 to 60 months. The product serves commercial foodservice procurement, emergency relief stockpiling, and household pantry rotation systems. Tuna dominates volume throughput due to established Pacific and Atlantic purse-seine supply chains feeding Brazilian and Peruvian canneries. Aluminum material formats command structural preference over tinplate as Brazilian supermarkets prioritize lightweight, corrosion-resistant packaging that reduces freight costs from coastal processing zones to inland distribution centers.
ANVISA governs microbiological safety thresholds and additive limits for canned fishery products sold across Brazil, while Chile's Undersecretariat of Fisheries and Aquaculture (SUBPESCA) regulates catch quotas that directly constrain raw material availability for regional canneries. Peru's National Fisheries Health Directorate (SANIPES) certifies export eligibility to MERCOSUR partner states, creating interdependent compliance obligations across the Andean-Pacific production axis. Stakeholders must monitor evolving mercury maximum residue limits and traceability mandates that will determine which processing facilities retain access to Brazil's retail and institutional procurement channels.
Market Dynamics
ANVISA's 2023 labeling modernization for preserved fishery products is compressing compliance timelines and forcing facility upgrades across Brazilian canneries, reshaping competitive access to retail channels.
Growth Catalysts
- Urban pantry rotation systems:São Paulo and Rio de Janeiro households are expanding shelf-stable protein inventories as inflation hedges against fresh seafood price volatility.
- SUBPESCA catch quota frameworks:Chile's volume-based allocation systems are stabilizing raw material flows to Peruvian and Ecuadorian processing facilities serving MERCOSUR markets.
- Aluminum format conversion:Brazilian supermarkets are mandating lightweight corrosion-resistant packaging to reduce inland freight costs from coastal canneries to distribution centers.
Market Restraints
- Skipjack tuna price volatility:Pacific purse-seine landing costs fluctuate with El Niño cycles, compressing margin buffers for Brazilian and Peruvian canneries.
- Mercury residue thresholds:ANVISA's tightening maximum residue limits for predatory species are disqualifying informal packers from formal retail procurement.
- Substitution by frozen fillets:Cold chain infrastructure expansion in Argentina and Uruguay is enabling frozen seafood displacement of canned formats in foodservice.
Strategic Opportunities
- Colombian retail underpenetration:Bogotá and Medellín supermarket chains are expanding shelf space for shelf-stable marine proteins with limited incumbent supplier relationships.
- Emergency relief stockpiling:Brazil's Civil Defense coordination with MERCOSUR partners is creating institutional procurement windows for 24-60 month stability products.
- SANIPES-MERCOSUR certification harmonization:Peru's export eligibility protocols are reducing cross-border compliance friction for Andean-Pacific canneries.
Industry Challenges
- Retort technician scarcity:Brazilian processing facilities face recruitment gaps for thermal stabilization specialists capable of maintaining 121°C sterilization protocols.
- Traceability system integration:Legacy batch-tracking infrastructure at Argentine canneries requires capital-intensive RFID and blockchain overlay deployment to meet ANVISA mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Canned Seafood Market |
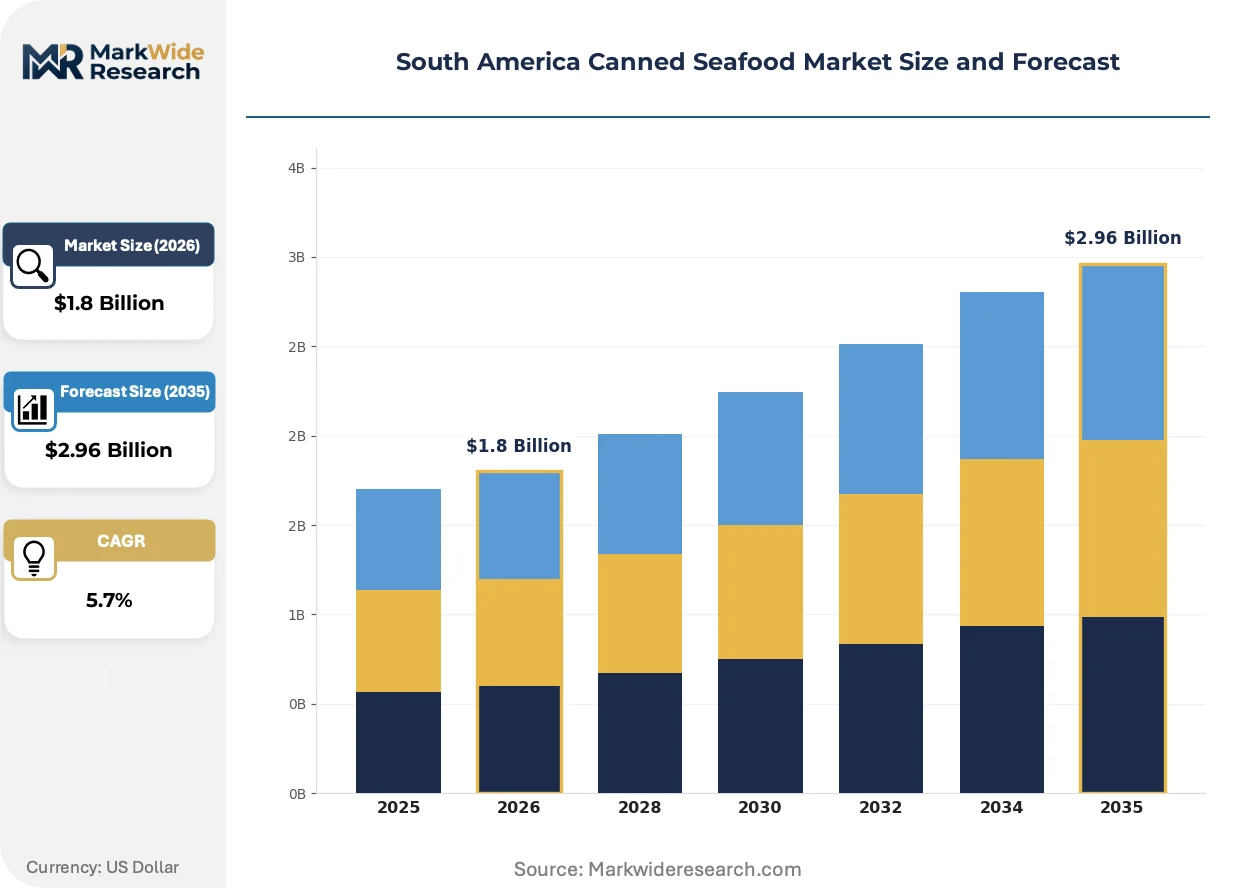
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Salmon, Sardines, Mackerel Material: Aluminum, Glass, Tin, Plastic Packaging Type: Rigid Containers, Flexible Pouches, Cans, Jars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Grupo Calvo, Grupo Camil, Beira Mar Importers Co Ltd, Tri Marine Group, Leal Santos, Pesquera San Jose S A, Jealsa, Trident Seafoods, StarKist Co., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Canned Seafood Market Evolving Landscape
Retort pouch formats and smart labeling systems are compressing traditional can formats while traceability mandates reconfigure supplier-buyer relationships across the Andean-Pacific production axis.
Retort pouch laminates with aluminum oxide barrier layers are displacing cylindrical metal formats in Brazilian premium retail channels. São Paulo-based supermarket chains are accelerating shelf resets for flat-pack tuna and mackerel products that reduce shipping cube by 40 percent. This format shift is miniaturizing warehouse storage requirements and enabling direct-to-shelf merchandising without secondary packaging.
ANVISA's serialized traceability mandate for preserved fishery products takes full effect in 2025. Brazilian canneries must implement lot-level digital tracking from vessel landing through retail distribution. Mid-sized processing facilities in Santa Catarina and Rio Grande do Sul are consolidating to spread compliance system costs across higher throughput volumes.
Foodservice buyers in Argentina are unbundling procurement from frozen seafood distributors and establishing direct relationships with Peruvian canneries certified under SANIPES protocols. Buenos Aires restaurant groups are specifying skipjack origin documentation and harvest dates in purchase orders. This disintermediation is compressing traditional importer margins and rewarding vertically integrated Andean-Pacific suppliers with institutional contract wins.
South America Canned Seafood Market Segmentation
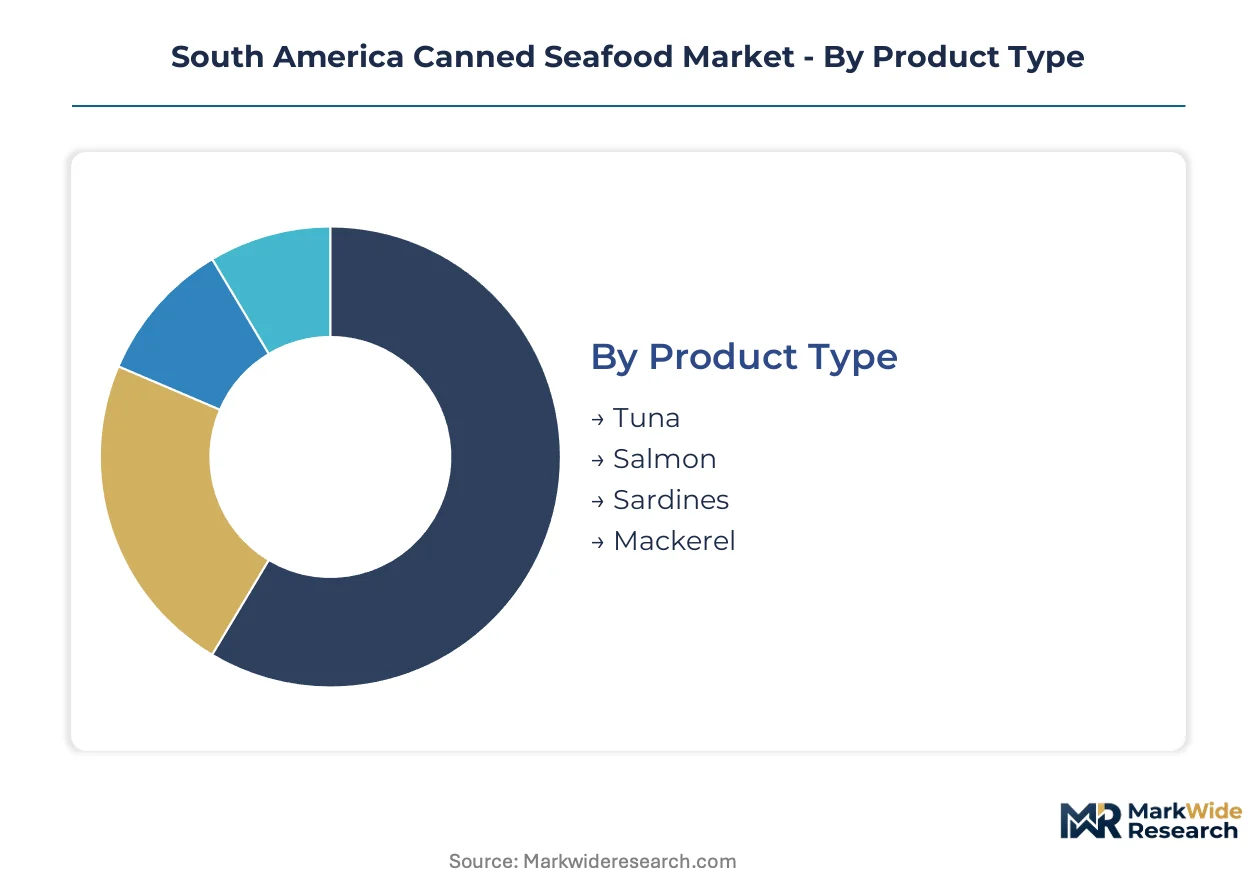
Segmentation in the South America Canned Seafood Market reveals how substitution pressures and channel economics reshape procurement patterns across Brazil, Argentina, and Chile. Understanding where frozen fillets displace shelf-stable formats helps stakeholders allocate manufacturing capacity and compliance investments.
Product Type:
Substitution pressure from frozen seafood alternatives concentrates most intensely on commodity tuna and sardine segments, while premium species maintain defensive positioning through traceability certification.
- Tuna:Skipjack and yellowfin varieties processed through retort sterilization at 121°C dominate Brazilian and Peruvian cannery output. São Paulo supermarket chains specify Pacific purse-seine origin documentation in procurement contracts, tightening supplier qualification thresholds.
- Sardines:Small pelagic species packed in oil or tomato sauce serve price-sensitive household pantry rotation across Rio de Janeiro and Buenos Aires metropolitan zones. Argentine coastal canneries face margin compression from rising Atlantic landing costs.
- Salmon:Farmed Atlantic salmon from Chilean aquaculture operations commands premium shelf positioning in Brazilian retail.
- Mackerel:Seasonal availability from Peruvian and Ecuadorian capture fisheries limits consistent supply to Andean-Pacific processing facilities.
Tuna anchors the volume base while salmon gains share at the steepest rate.
Material:
Freight cost tiering from coastal canneries to inland distribution centers drives material selection, with lightweight formats capturing supermarket procurement preference.
- Aluminum:Two-piece drawn and wall-ironed containers reduce shipping weight by 35 percent versus tinplate equivalents. Brazilian retailers mandate aluminum for private-label tuna lines sourced from Santa Catarina processing zones.
- Tin:Traditional three-piece soldered cans retain foothold in institutional emergency relief procurement for 60-month shelf stability requirements.
- Glass:Premium jar formats serve gift-packaged salmon and marinated seafood assortments in Chilean retail channels.
- Plastic:Retortable polypropylene trays remain niche in foodservice portion-pack applications.
Aluminum dominates new capacity investment while tinplate retains institutional contract share.
Packaging Type:
Channel-specific handling requirements and shelf-reset economics determine format adoption velocity across Brazilian retail networks.
- Cans:Cylindrical metal containers remain the default format for São Paulo and Rio de Janeiro mass-market distribution, with standardized palletization reducing logistics complexity.
- Flexible Pouches:Flat-pack retort pouches with aluminum oxide barrier layers reduce shipping cube by 40 percent, enabling direct-to-shelf merchandising without secondary packaging in premium Brazilian supermarket channels.
- Rigid Containers:Rectangular plastic trays serve foodservice portion-control specifications in Argentine restaurant procurement.
- Jars:Wide-mouth glass containers accommodate whole-fish presentation in Chilean and Peruvian retail gift segments.
Cans sustain volume leadership while flexible pouches expand most quickly in premium retail reset programs.
Distribution Channel:
Customer type segmentation separates household pantry rotation from institutional procurement, with channel-specific compliance requirements filtering supplier participation.
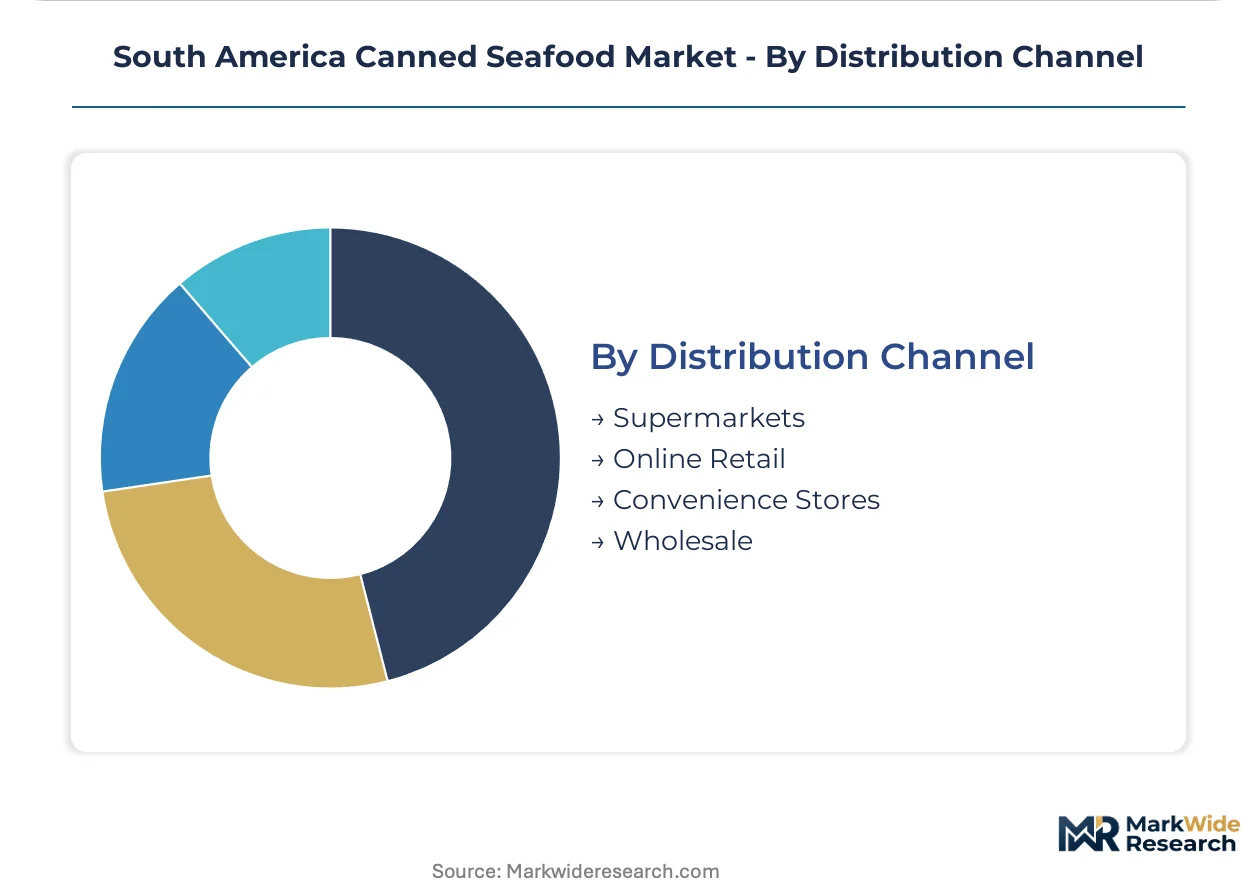
- Supermarkets:Hypermarket and supermarket chains in Brazil's southeastern urban corridor specify ANVISA-certified suppliers with serialized traceability systems. São Paulo-based retailers are consolidating shelf space around three to four core canned seafood suppliers.
- Wholesale:Foodservice distributors in Buenos Aires and Santiago serve restaurant and institutional buyers with case-lot procurement of standard can formats.
- Online Retail:E-commerce platforms in Colombia and Brazil are expanding shelf-stable protein assortments with direct-to-consumer fulfillment from coastal processing zones.
- Convenience Stores:Small-format retail in Brazilian urban peripheries stocks single-serve tuna and sardine portions for immediate consumption.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement managers in Brazil's southeastern urban corridor drive volume allocation decisions, while Chilean and Peruvian canneries compete for MERCOSUR shelf space through SANIPES and ANVISA certification alignment.
Brazil
São Paulo and Rio de Janeiro households stock shelf-stable proteins as inflation hedges against fresh seafood volatility. ANVISA's 2023 labeling modernization compresses compliance timelines for Santa Catarina canneries. Southeastern supermarket chains consolidate shelf space around three to four certified suppliers with serialized traceability systems.
Chile
Farmed Atlantic salmon from aquaculture operations commands premium positioning in Brazilian retail channels. SUBPESCA catch quota frameworks stabilize raw material flows to Peruvian and Ecuadorian processing facilities. Puerto Montt and Los Lagos processing clusters anchor salmon canning capacity serving MERCOSUR markets.
Peru
Pacific purse-seine landing costs fluctuate with El Niño cycles, compressing margin buffers for skipjack-dependent canneries. SANIPES certifies export eligibility to MERCOSUR partner states, creating interdependent compliance obligations. Callao and Chimbote processing zones feed Andean-Pacific supply chains into Brazilian distribution centers.
Argentina
Buenos Aires restaurant groups specify skipjack origin documentation in purchase orders, disintermediating traditional frozen seafood distributors. Rising Atlantic landing costs squeeze margin buffers for coastal sardine canneries. Mar del Plata processing facilities face capital-intensive RFID and blockchain overlay deployment to meet traceability mandates.
Colombia
Bogotá and Medellín supermarket chains expand shelf space for shelf-stable marine proteins with limited incumbent supplier relationships. Cold chain infrastructure gaps sustain canned format preference over frozen alternatives in Andean urban centers. Caribbean coastal processing zones in Barranquilla and Cartagena develop canning capacity for domestic retail penetration.
South America Canned Seafood Market Competitive Landscape
Player mix skews toward vertically integrated Atlantic-Pacific suppliers and specialized premium-product specialists. Tiered concentration separates ANVISA-certified exporters from informal domestic packers disqualified by mercury residue thresholds. Two strategic archetypes dominate: scale-driven purse-seine integrated processors and premium-channel product specialists. Competitive moves center on aluminum format conversion for freight cost reduction and traceability system deployment for retail access retention.
Among Spanish-origin integrated processors, Grupo Calvo and Jealsa occupy positions reflecting Atlantic and Pacific sourcing network control. Grupo Calvo exemplifies the vertically integrated archetype with consistent raw material flow management. Jealsa represents the premium-channel specialist model through differentiated tuna product lines. Trident Seafoods anchors the Pacific-origin supply position serving Brazilian institutional procurement. These three entities illustrate how certification compliance and format innovation separate competitive tiers in MERCOSUR retail access.
| Leading Market Players |
|---|
| Grupo Calvo |
| Grupo Camil |
| Beira Mar Importers Co Ltd |
| Tri Marine Group |
| Leal Santos |
| Pesquera San Jose S A |
| Jealsa |
| Trident Seafoods |
| StarKist Co. |
| Others |
Value Network & Pricing Analysis
Retort sterilization capacity utilization at Brazilian coastal canneries determines regional price floors, with São Paulo supermarket chains extracting volume discounts from facilities running below optimal throughput. Scale concentration in Santa Catarina processing zones anchors supply-side bargaining power while freight cost tiering from coastal landing points to inland distribution centers compresses margin buffers for smaller operators.
Pricing Analysis
Cost-plus contracts indexed to Pacific purse-seine skipjack landing prices dominate procurement between Peruvian canneries and Brazilian retail buyers. Pricing stratifies across ANVISA-certified premium tiers, mercury-tested standard grades, and informal economy segments with limited traceability. Cost compression in the standard tier intensifies as El Niño cycles disrupt raw material availability. Foodservice distributors in Buenos Aires exhibit highest price sensitivity, while Brazilian supermarket private-label buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Panama Canal transit scheduling underwrites delivery reliability for Pacific-origin tuna moving to Brazilian Atlantic ports. Raw material supply concentrates in Peru, Chile, and Ecuador, with skipjack and yellowfin landings feeding Andean-Pacific processing clusters. Brazilian canneries draw from distant-water fleets and regional coastal capture operations, exposing operations to landing price volatility. Single-source vulnerability in specialized retort pouch laminates creates input risk. Distribution runs through São Paulo-based wholesale consolidation points serving southeastern urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA certification fragmentation creates white-space opportunities as compliant suppliers consolidate retail shelf space and informal packers face disqualification. Channel bifurcation between certified institutional procurement and price-driven informal trade enables niche positioning strategies.
For Market Incumbents: Consolidate procurement relationships with SUBPESCA-licensed Chilean salmon aquaculture operations to secure farmed Atlantic raw material flows. Expand aluminum format conversion capacity at Santa Catarina facilities to capture freight cost advantages in supermarket private-label contracts. Defend against frozen fillet substitution by embedding traceability documentation into foodservice direct procurement channels.
For New Entrants and Emerging Players: Lead with Colombian retail penetration in Bogotá and Medellín supermarket chains where incumbent supplier relationships remain limited. Target emergency relief institutional procurement windows created by Brazil's Civil Defense coordination with MERCOSUR partners. Establish SANIPES-certified export eligibility as the go-to-market foundation for Andean-Pacific processing integration.
For Investors and Strategic Acquirers: Mid-tier Peruvian canneries with SANIPES-MERCOSUR certification alignment represent acquisition targets with embedded regulatory access. Long-term viability hinges on traceability system deployment completion and aluminum format conversion execution. Monitor ANVISA serialized tracking mandate enforcement as the inflection indicator separating compliant exporters from disqualified competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Serialized traceability system deployment secures retail channel access for Santa Catarina canneries. |
| Aluminum Format Conversion | Lightweight container adoption reduces inland freight costs from coastal processing zones to São Paulo distribution centers. |
| Direct Foodservice Procurement | Bypassing frozen seafood distributors captures Buenos Aires restaurant group contract specifications for origin documentation. |
| Andean-Pacific Sourcing Integration | Peruvian and Ecuadorian landing point control stabilizes skipjack raw material flows against El Niño disruption. |
| Emergency Relief Contract Positioning | Brazil Civil Defense institutional procurement creates volume anchors for 24-60 month shelf stability products. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, ANVISA regulatory filings, and SUBPESCA catch quota publications. The research incorporated interviews with Brazilian supermarket category buyers, Peruvian cannery operations directors, and Chilean aquaculture procurement managers. Secondary validation drew from SANIPES export certification databases, MERCOSUR trade flow statistics, and coastal processing facility capacity registries. Bottom-up volume modeling triangulated against top-down market sizing from trade association aggregates.
Segmentation dimensions modeled include product type, material format, packaging configuration, and distribution channel across the projection horizon. CAGRs derived from historical trade flow trajectories adjusted for regulatory compliance phase-in schedules and format conversion adoption curves. Forecast inputs incorporated El Niño cycle impact patterns on Pacific purse-seine landing costs and aluminum container substitution rates in Brazilian retail reset programs.
Forecasts assume regulatory continuity in ANVISA labeling mandates and SUBPESCA quota frameworks; material policy shifts would require re-modeling of competitive access scenarios. Mercury residue threshold tightening and traceability mandate enforcement represent specific revision risks. Practitioners should keep alternative scenarios live as certification compliance timelines and cold chain infrastructure expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Octopus Market
Seafood
Salmon Market
Seafood
Cod Fish Market
Seafood
Canned Anchovy Market
Seafood
Smoked Salmon Market
Seafood
North America Seafood Market
Seafood
Fish Fermentation Market
Seafood
Europe Salmon Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Fish Meal Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Striped Bass Market
Seafood
Smoked Whiting Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Processed Seafood Market