
 Fish Protein Concentrate Market | 2026-2036
Fish Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Protein Concentrate Market Analysis
Direct procurement contracts between Peruvian fishmeal processors and European aquafeed compounders is reshaping how concentrate volumes flow across the Atlantic. Omega Protein Corporation leverages vertical integration from Gulf menhaden fleets to protein processing facilities along the US mid-Atlantic coast. Hofseth BioCare ASA anchors its position through patented hydrolysis technology that preserves bioactive peptides for human nutrition applications. Scanbio Marine Group AS specializes in salmon byproduct recovery, converting Norwegian farm waste into high-grade concentrate for domestic feed mills.
Fish protein concentrate denotes a dehydrated, partially defatted protein product derived from whole fish or fish residuals, typically containing 65-85% crude protein with variable fat and ash content depending on processing method and raw material source. Manufacturers employ acid or solvent extraction, enzymatic hydrolysis, or mechanical pressing to achieve target protein purity levels for feed or food-grade specifications. Hydrolysate commands premium positioning in nutraceutical formulations where lower molecular weight peptides enhance bioavailability, while concentrate and isolate grades dominate feed industry procurement due to cost efficiency at scale. Peptide fractions represent the fastest-growing product category as sports supplement brands reformulate with rapid-absorption protein sources.
USDA and FDA oversight governs human-grade fish protein concentrate through food safety and labeling requirements, while EPA regulations on industrial fishing quotas indirectly constrain raw material availability for processors. The EU EFSA and REACH frameworks impose residue limits and chemical safety standards that determine market access for imported concentrate shipments. Stakeholders must monitor evolving marine stewardship certification requirements and aquaculture feed reformulation mandates to anticipate which protein fractions will command procurement priority.
Market Dynamics
Marine stewardship certification requirements and aquaculture feed reformulation mandates are compressing procurement timelines for protein fractions, forcing compounders to pre-qualify suppliers against EFSA residue limits and EU F-Gas Regulation sourcing protocols before volume commitments.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in cold-chain logistics is accelerating investment in alternative preservation technologies for fish protein concentrate shipments bound for European aquafeed mills.
- Sports supplement manufacturers:North American formulators are expanding peptide fraction procurement as rapid-absorption protein sources displace slower-digesting alternatives in pre-workout and recovery products.
- Enzymatic hydrolysis:Advances in controlled peptide cleavage are unlocking bioactive fractions for human nutrition applications, widening addressable market scope beyond traditional feed-grade concentrate.
Market Restraints
- Anchovy biomass volatility:El Niño oscillations off Peru's Pacific coast create raw material availability swings that propagate through Atlantic supply chains to European compounders.
- REACH compliance costs:Chemical safety documentation and residue testing requirements for imported concentrate impose fixed-cost burdens that disadvantage smaller processors lacking in-house regulatory affairs capacity.
- Plant protein substitution:Fermented soybean and algae-derived alternatives are capturing formulation share in salmon feed rations, pressuring fishmeal inclusion rates in Norwegian aquaculture nutrition.
Strategic Opportunities
- Indian aquaculture expansion:Shrimp and freshwater fish farming growth in Andhra Pradesh and Gujarat is creating demand for imported protein concentrate as domestic fishmeal supply falls short of feed mill requirements.
- Marine Stewardship Council tailwinds:Certification premiums for sustainably sourced concentrate are expanding margin pools for processors able to document chain-of-custody from vessel to finished product.
- Direct-to-compounder platforms:Digital procurement channels are disintermediating traditional traders, enabling Peruvian processors to contract directly with European aquafeed manufacturers on specification-matched volumes.
Industry Challenges
- Peptide biochemistry expertise scarcity:Formulators lack sufficient talent to optimize hydrolysate inclusion rates across species-specific feed matrices, slowing adoption of premium protein fractions.
- Marine Stewardship Council certification timelines:The 12-18 month assessment window for chain-of-custody approval delays market access for new concentrate entrants targeting sustainability-premium segments.
- Cold-chain capex intensity:Temperature-controlled storage and transport infrastructure requirements for human-grade concentrate strain working capital for mid-scale processors expanding beyond feed-grade markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Protein Concentrate Market |
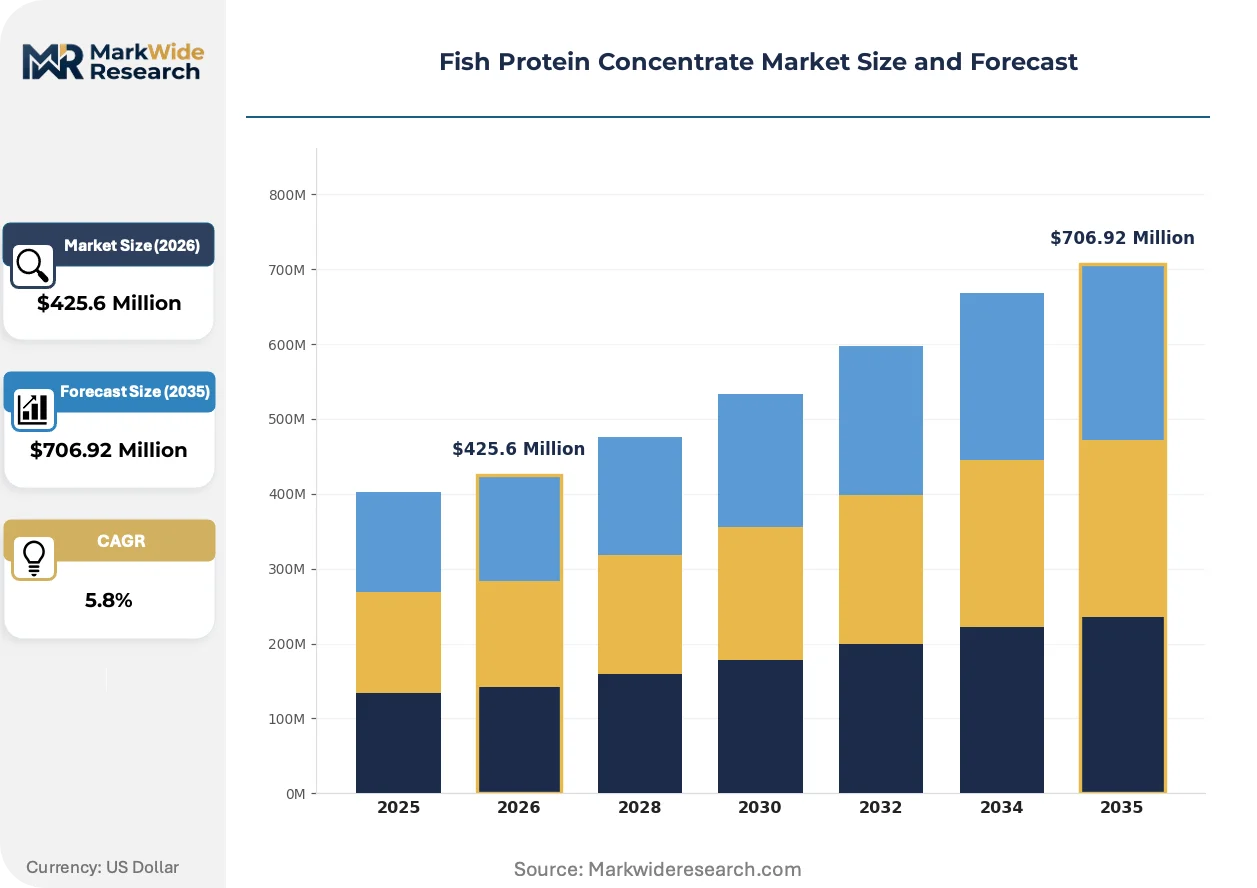
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $706.92 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolysate, Isolate, Concentrate, Peptide End User: Food Industry, Feed Industry, Nutraceuticals, Sports Supplements Source: Wild Caught, Farmed, Bycatch, Marine Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Omega Protein Corporation, Colpex International Inc., Scanbio Marine Group AS, BioOregon Protein Inc., Apelsa Guadalajara S.A. de C.V., Mukka Sea Foods Industries Pvt. Ltd., Janatha Fish Meal & Oil Products, Pelagia AS, Hofseth BioCare ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Protein Concentrate Market Emerging Trajectories
Processing technology convergence and certification-driven procurement protocols are reconfiguring how protein fractions move from raw material recovery to end-use formulation, with implications for equipment investment and supplier qualification workflows.
Membrane filtration systems for peptide fractionation are hybridizing traditional mechanical pressing with precision molecular separation, enabling processors to isolate specific weight-class peptides for nutraceutical applications. Sports nutrition brands in North America are adopting these fractions at accelerating pace for rapid-absorption product lines. The technology is hybridizing cost structures across concentrate grades, compressing price premiums between feed-standard and food-specification products as yield efficiency improves.
REACH framework updates on chemical residue limits are tightening import documentation requirements for concentrate shipments entering European customs territory. EFSA evaluations of process contaminants in hydrolyzed proteins are extending clearance timelines for new supplier qualifications. Norwegian aquafeed compounders are responding by consolidating procurement around pre-approved processors with established dossier libraries, reducing qualified supplier pools.
Buyers are consolidating annual volume commitments into multi-year direct contracts with named processors, displacing spot-market purchasing through commodity traders. European aquafeed manufacturers are leading this transition, locking in specification-matched supply chains against marine biomass volatility. Peru's anchovy processing belt and Norway's salmon byproduct recovery cluster are the primary geographies where this contractual shift is visible, with compounders establishing technical liaison offices at source.
Fish Protein Concentrate Market Segmentation
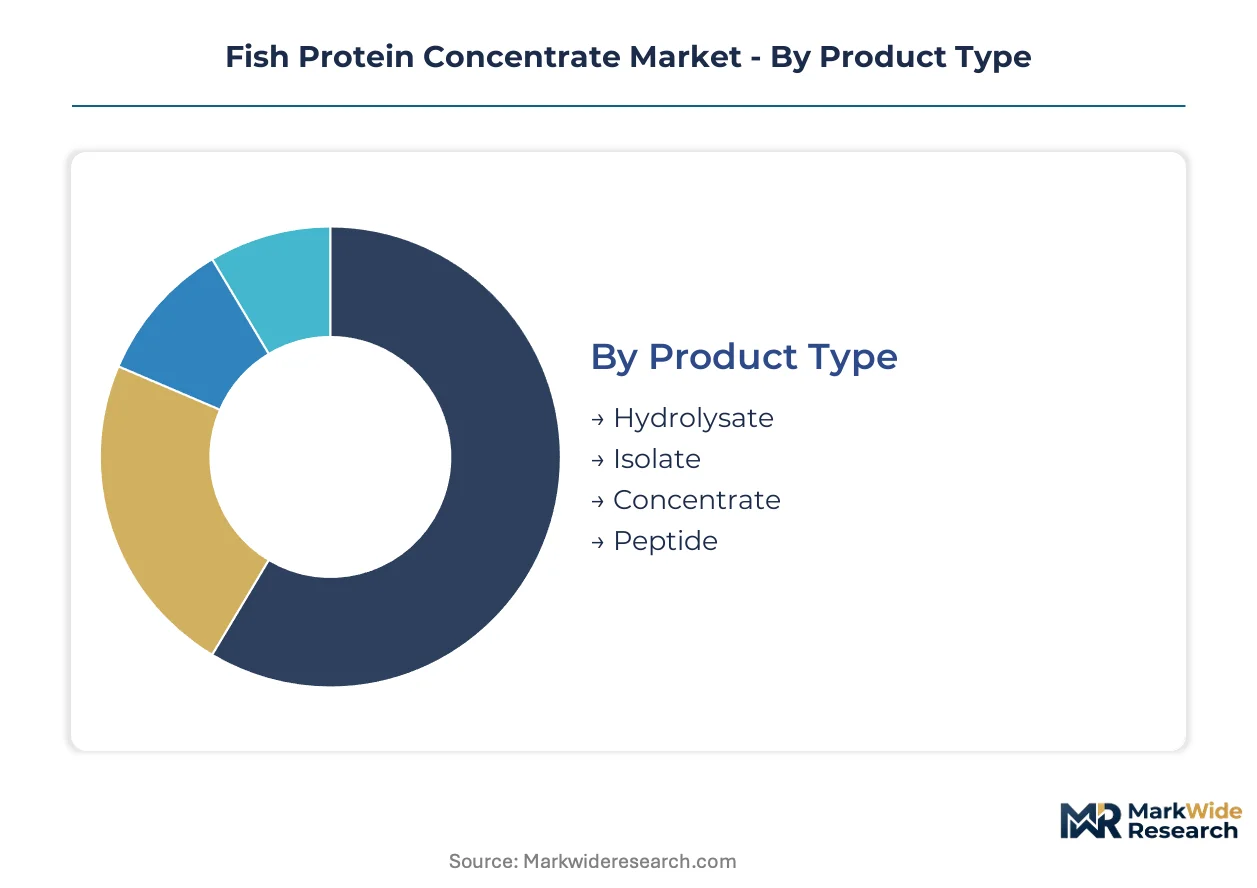
Segmentation in fish protein concentrate markets determines procurement workflows, certification requirements, and margin structures. Product purity grades dictate end-use eligibility while source traceability governs access to premium pricing tiers in European and North American markets.
Product Type:
Mature grades dominate feed procurement volumes while emerging fractions capture nutraceutical premiums.
- Concentrate:Dehydrated, partially defatted protein product containing 65-85% crude protein. Norwegian aquafeed compounders and Peruvian processors anchor procurement around this grade for cost-efficient salmon and shrimp feed formulations.
- Hydrolysate:Enzymatically cleaved protein with preserved bioactive peptides for enhanced bioavailability. Sports supplement manufacturers in the United States and human nutrition specialists in Germany drive demand amid reformulation toward rapid-absorption protein sources.
- Isolate:Higher purity protein fraction achieved through additional processing steps. Specialty nutraceutical applications in Japan and Switzerland utilize isolate grades for medical nutrition products.
- Peptide:Specific molecular weight fractions isolated through membrane filtration. North American functional food brands and South Korean cosmeceutical formulators source peptide fractions for targeted health applications.
Concentrate handles the majority of throughput; peptide is the fastest mover on share.
End User:
Cost tier stratification separates commodity feed buyers from premium human nutrition purchasers.
- Feed Industry:Aquaculture and livestock compounders represent the volume anchor for fish protein concentrate procurement. Norwegian salmon feed manufacturers and Indian shrimp farming operations in Andhra Pradesh source concentrate grades under direct procurement contracts.
- Sports Supplements:Pre-workout and recovery product formulators in the United States and United Kingdom are expanding hydrolysate inclusion rates. Rapid-absorption positioning drives reformulation away from slower-digesting alternatives.
- Food Industry:Processed food manufacturers utilize fish protein concentrate for functional properties including emulsification and water binding. Japanese surimi processors and Spanish canned seafood producers incorporate concentrate into reformulated products.
- Nutraceuticals:Dietary supplement and functional food brands target bioactive peptide fractions for cardiovascular and cognitive health positioning. German and Swiss pharmaceutical-grade manufacturers command premium specifications.
Feed Industry commands the largest volume commitments; Sports Supplements is climbing the fastest on reformulation activity.
Source:
Supply concentration by geography determines certification complexity and cold-chain requirements.
- Wild Caught:Peruvian anchovy fisheries and Gulf menhaden fleets in the United States supply the dominant share of raw material. Marine Stewardship Council certification requirements compress procurement timelines for European buyers.
- Farmed:Norwegian salmon byproduct recovery operations convert processing waste into feed-grade concentrate. Scanbio Marine Group AS and comparable processors specialize in this circular supply model.
- Bycatch:Incidental capture species processed into protein concentrate for non-food applications. Regulatory restrictions on bycatch utilization limit addressable markets to specific feed-grade channels.
- Marine:Broad category encompassing non-specified marine species for commodity concentrate production. Asian aquafeed compounders in Vietnam and Indonesia source marine-origin concentrate on specification-matched spot contracts.
Wild Caught dominates raw material throughput; Farmed is expanding most quickly on circular economy mandates.
Distribution Channel:
Customer type and order scale determine channel selection between digital platforms and traditional intermediaries.
- Direct Sales:Annual volume commitments between Peruvian processors and European aquafeed compounders displace spot-market purchasing. Technical liaison offices at source enable specification-matched contracting.
- Online Retail:Sports supplement and nutraceutical brands in North America procure peptide fractions through specialized ingredient marketplaces. Digital channels reduce qualification overhead for mid-scale formulators.
- Specialty Stores:Human-grade concentrate for small-batch food manufacturers moves through regional ingredient distributors. German and Italian specialty chemical distributors serve artisanal processed seafood producers.
- Supermarkets:Limited presence for finished products containing fish protein concentrate as a functional ingredient. Japanese retail chains stock select surimi and kamaboko products with concentrate fortification.
Direct Sales handles the majority of volume; Online Retail is gaining share fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phasedown and Marine Stewardship Council certification requirements are compressing procurement timelines for European aquafeed compounders. Sports supplement manufacturers in the United States and human nutrition specialists in Germany are expanding peptide fraction procurement. Circular economy mandates in Norway and aquaculture expansion in India are creating divergent demand centers for concentrate grades.
Norway
Salmon aquaculture feed reformulation drives concentrate demand from domestic byproduct recovery operations. The Norwegian Food Safety Authority enforces residue limits that determine import eligibility for non-EU concentrate shipments. Bergen and Trondheim anchor the country's salmon byproduct processing cluster, where Scanbio Marine Group AS converts farm waste into feed-grade protein.
Peru
Anchovy biomass availability swings create raw material volatility that propagates through Atlantic supply chains. The Ministry of Production (PRODUCE) regulates fishing quotas and seasonal closures that constrain processor throughput. Chimbote and Paita form the core anchovy processing belt, where direct procurement contracts with European compounders are displacing spot-market trading.
United States
Sports supplement brands are accelerating hydrolysate inclusion rates in pre-workout and recovery formulations. FDA and USDA oversight governs human-grade concentrate through food safety and labeling requirements. Reedville, Virginia hosts Omega Protein Corporation's integrated menhaden processing complex, linking Gulf fleet operations to protein production.
Germany
Human nutrition specialists command premium specifications for bioactive peptide fractions in medical and functional food applications. EFSA evaluations of process contaminants in hydrolyzed proteins extend clearance timelines for new supplier qualifications. Hamburg and Bremen concentrate import logistics and specialty chemical distribution for artisanal processed seafood producers.
India
Shrimp and freshwater fish farming expansion in coastal states outpaces domestic fishmeal supply. FSSAI standards and DGFT import protocols determine market access for concentrate shipments. Andhra Pradesh and Gujarat host the fastest-growing aquaculture operations, where feed mills are contracting imported protein to cover supply shortfalls.
Fish Protein Concentrate Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated processors with captive raw material access and specialized hydrolysis capabilities. The competitive terrain separates feed-grade volume operators from human nutrition specialists commanding peptide premiums. Three archetypes dominate: integrated fishing-to-protein processors, enzymatic hydrolysis technology licensors, and byproduct recovery specialists serving circular economy mandates. Capacity expansion and direct-to-compounder contracting represent the dominant competitive moves, displacing traditional trader intermediation.
Among North American integrated operators, Omega Protein Corporation exemplifies the fleet-to-facility model with Gulf menhaden sourcing. Hofseth BioCare ASA occupies a position within the Norwegian hydrolysis specialist tier, anchoring human nutrition applications through patented peptide preservation. Scanbio Marine Group AS represents the byproduct recovery archetype, converting Norwegian salmon processing waste into high-grade concentrate for domestic feed mills.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| Colpex International Inc. |
| Scanbio Marine Group AS |
| BioOregon Protein Inc. |
| Apelsa Guadalajara S.A. de C.V. |
| Mukka Sea Foods Industries Pvt. Ltd. |
| Janatha Fish Meal & Oil Products |
| Pelagia AS |
| Hofseth BioCare ASA |
| Others |
Supply Flow & Price Mechanics
Anchovy biomass volatility off Peru's Pacific coast compresses pricing spreads between feed-grade concentrate and peptide fractions while simultaneously forcing European compounders to diversify sourcing geography. This single-source dependency for Atlantic aquafeed supply chains creates tiered cost structures that reward pre-qualified processors with multi-year contract premiums.
Pricing Analysis
Certification level (Marine Stewardship Council chain-of-custody) creates the primary spread between commodity feed-grade concentrate and premium human nutrition hydrolysates. Three-tier pricing structure across MSC-certified premium, standard-grade feed, and economy spot-market tiers reflects documentation burden and residue testing depth. Cost compression in the standard tier is intensifying because plant protein substitution in Norwegian salmon feed rations pressures inclusion rates. Feed industry compounders exhibit highest price sensitivity due to volume procurement and formula cost targets, while German nutraceutical formulators accept premium positioning for bioactive peptide fractions.
Supply Chain Analysis
Upstream feedstock availability hinges on Peruvian anchovy fisheries, Gulf menhaden fleets in the United States, and Norwegian salmon byproduct recovery operations. Raw material flows draw from whole fish landings, processing residuals, and enzymatic hydrolysis outputs. Single-source vulnerability concentrates in the Chimbote-Paita processing belt where El Niño oscillations disrupt throughput. Distribution runs through direct procurement contracts between named processors and European aquafeed compounders, displacing traditional commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around pre-qualified processor pools as Norwegian compounders reduce qualified supplier lists, fragmenting access for new concentrate entrants.
For Market Incumbents: Harden supply chain resilience through backward integration into Peruvian anchovy quota holdings or Norwegian salmon byproduct offtake agreements. Defensive positioning requires MSC certification investment to capture sustainability premiums as European procurement mandates tighten. Capacity addition in the US mid-Atlantic menhaden corridor diversifies raw material exposure against Pacific climate volatility. For New Entrants and Emerging Players: Build out peptide fraction capabilities targeting North American sports supplement brands reformulating toward rapid-absorption protein sources. Indian aquafeed expansion in Andhra Pradesh and Gujarat offers the most penetrable geography where domestic fishmeal shortfalls force imported concentrate adoption. Digital procurement platforms enable direct-to-compounder contracting without trader intermediation overhead. For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown reshapes the acquisition landscape toward processors with alternative cold-chain preservation technology. Long-term viability centers on hydrolysis patent portfolios and captive raw material access rather than toll-processing models. The signal to watch is MSC certification timeline compression as sustainability premiums harden into procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Patent Acquisition | Secures bioactive peptide preservation technology for human nutrition premium positioning. |
| Peruvian Quota Backward Integration | Captures anchovy biomass access against El Niño supply volatility for Atlantic compounders. |
| MSC Chain-of-Custody Certification | Unlocks sustainability premium pricing in EU aquafeed procurement mandates. |
| Direct-to-Compounder Digital Platform | Disintermediates commodity traders for specification-matched volume contracting. |
| Norwegian Byproduct Recovery Capacity | Converts salmon farm waste into circular feed-grade concentrate under domestic circular economy mandates. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with aquafeed procurement directors, peptide formulators at sports nutrition brands, regulatory affairs specialists at EFSA, and Peruvian anchovy processor operations managers; and secondary validation through customs trade data, Marine Stewardship Council certification registries, SEC processor filings, and EU F-Gas Regulation implementation reports. Bottom-up volume modeling triangulated against top-down market sizing across concentrate grades.
Forecast inputs considered product type segmentation across concentrate, hydrolysate, isolate, and peptide fractions; end-use splits between feed industry, sports supplements, food processing, and nutraceuticals; and source traceability from wild-caught, farmed, and bycatch origins. CAGRs were derived from regression analysis of historical procurement volumes against aquaculture feed reformulation trends and human nutrition peptide adoption curves. Anchovy biomass oscillation patterns and REACH compliance cost trajectories anchored scenario testing.
Stress conditions across El Niño intensity bands, plant protein substitution rates in Norwegian salmon feed, and EFSA residue limit tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline compression and direct procurement adoption curves. Cross-checking against FAO fishery landings statistics and EU aquafeed production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
European Frozen Seafood Market
Seafood
Surimi by-Product Market
Seafood
Salmon Market
Seafood
Dried Scallop Market
Seafood
Lobster Market
Seafood
Alaskan Salmon Market
Seafood
Organic Seafood Market
Seafood
Krill Meal Market
Seafood
Fresh Fish Market
Seafood
Organic Salmon Market
Seafood
Striped Bass Market
Seafood
Sea Bass Market
Seafood
Global Commercial Fishing Market
Seafood
Canned Salmon Market
Seafood
Global Shrimp Market
Seafood
Europe Seafood Market