
 Frozen Seafood Market | 2026-2036
Frozen Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Seafood Market Intelligence
Norway's expansion of aquaculture processing and freezing capacity is reshaping competitive positioning for Atlantic salmon and cod. Mowi leverages its significant aquaculture assets to control supply, while Trident Seafoods dominates the North American market through its extensive fishing and processing infrastructure. Thai Union Frozen Products competes on a global scale, specializing in high-volume processing of shrimp and tuna.
Frozen seafood encompasses fish and shellfish preserved by freezing processes, typically below -18°C (0°F), to inhibit microbial growth and enzymatic activity. This preservation method, often involving flash-freezing techniques like Individual Quick Freezing (IQF), maintains texture and nutritional value for extended periods. Shrimp and salmon consistently lead the product type segments in value, supported by strong consumer preference in retail. Within distribution channels, online retailers are gaining share from traditional supermarkets, particularly for premium and specialty items.
Market access is governed by stringent food safety protocols, including the FDA's HACCP requirements in the United States and the European Union's traceability mandates overseen by the EFSA. In China, imported products must comply with inspection and quarantine standards set by the SAMR, impacting trade flows. Future profitability depends on navigating disparate country-of-origin labeling laws and managing supply chain volatility from climate-related disruptions to fisheries.
Market Dynamics
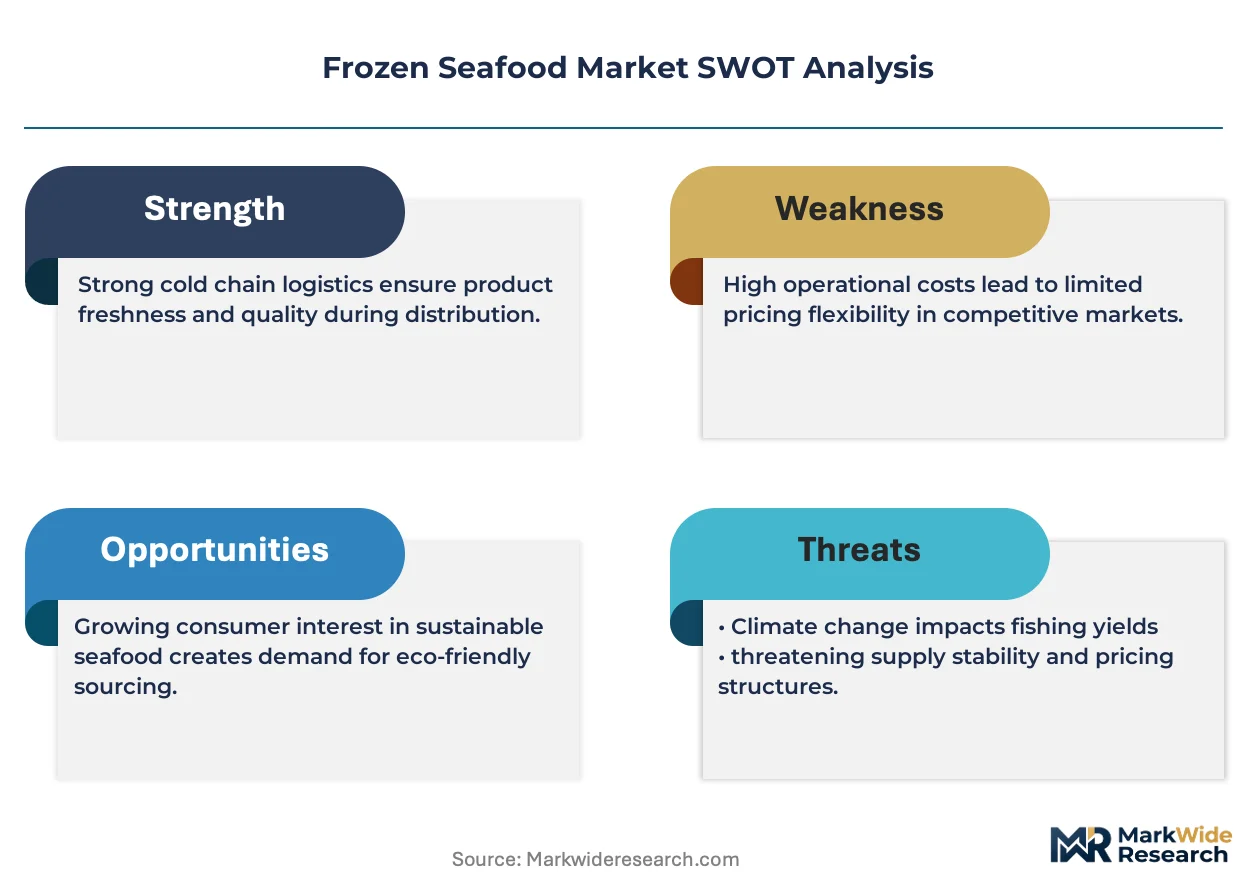
The market's structure is defined by rising consumer and regulatory demands for full supply chain traceability. This pressure for transparency, from fishery to freezer, directly conflicts with the fragmented and often opaque nature of sourcing in key production regions.
Growth Catalysts
- Advanced Freezing Technology:Individual Quick Freezing (IQF) improves product quality and extends shelf life, meeting higher consumer expectations in retail and foodservice.
- Foodservice Demand:The need for portion-controlled and ready-to-cook items in the foodservice sector drives significant volume for consistent, easy-to-prepare seafood.
- Export Processing Growth:Vietnam's expanding role as a processing hub, aligned with EU and US import regulations, strengthens its position in global supply.
Market Restraints
- Energy Cost Volatility:The energy-intensive nature of cold storage exposes processors to electricity price fluctuations, directly compressing operational margins.
- Wild-Catch Supply Instability:Climate change and strict fishing quotas on species like cod create supply unpredictability and sourcing challenges for processors.
- Fragmented Labeling Rules:Disparate country-of-origin labeling laws across the EU and US create significant compliance burdens and trade friction for exporters.
Strategic Opportunities
- Inland Market Expansion:Developing cold chain logistics in inland regions of India and Brazil creates new retail channels away from coastal population centers.
- Value-Added Product Lines:Moving into seasoned and marinated items offers higher margins and brand differentiation beyond unprocessed commodity fish and shellfish.
- Direct-to-Consumer Sales:Online platforms and subscription models provide a direct channel to market premium items like wild salmon to end-consumers.
Industry Challenges
- HACCP and Traceability Compliance:Maintaining rigorous documentation for food safety systems like the FDA's HACCP and the EU's traceability rules requires continuous investment and training.
- Skilled Labor Shortages:Processing facilities face persistent shortages of skilled labor for tasks such as filleting and quality control, impacting throughput and operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Seafood Market |
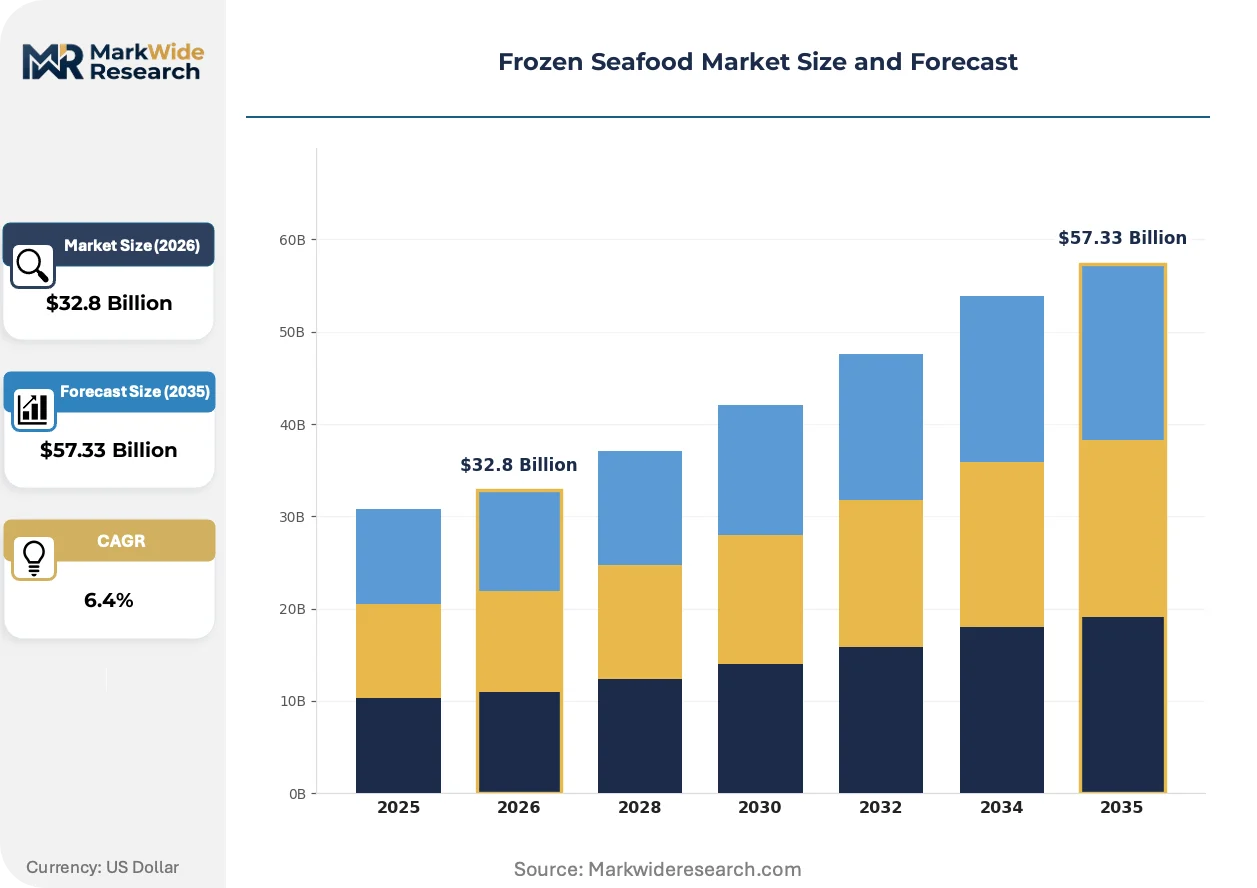
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrimp, Tuna, Salmon, Cod, Squid, Crab Packaging Type: Vacuum Packed, Tray Packed, Bag Packed, Box Packed, Bulk Packed Distribution Channel: Supermarkets, Wholesalers, Foodservice Providers, Online Retailers, Specialty Stores End User: Restaurants, Hotels, Catering Services, Food Processors |
| Companies Covered | High Liner Foods, Trident Seafoods, Mowi (Marine Harvest), Sysco Corporation, American Seafoods Group, Thai Union Frozen Products, Iglo Group, North Coast Seafoods, Leroy Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Seafood Market Strategic Shifts & Innovations
A convergence of digital traceability platforms and consumer demand for sustainable sourcing is fundamentally altering product development and supply chain verification. Innovations are now centered on proving provenance and improving preservation from harvest to final sale.
High-Pressure Processing (HPP) utilizes intense water pressure at cold temperatures to neutralize pathogens and extend refrigerated shelf life without using heat. Premium brands are adopting HPP for ready-to-eat items like shrimp cocktail, ensuring food safety. This technology is rendering obsolete the reliance on chemical preservatives for certain high-value products, meeting clean-label demands from consumers.
European Union traceability mandates, overseen by the EFSA, require comprehensive documentation for all seafood products from catch to retail. This regulation forces exporters in nations like Thailand to adopt digital systems that verify harvest location and processing data. The shrimp and tuna import segments are most affected, now investing in blockchain platforms to meet these strict compliance requirements.
Consumer purchasing is shifting toward products with sustainability certifications from bodies like the Marine Stewardship Council (MSC). Major supermarkets in North America and Europe are consequently prioritizing certified seafood, displacing non-certified suppliers from premium shelf space. This trend is most prominent in retail markets like Germany and the United Kingdom, where sustainability labels are a key differentiator.
Frozen Seafood Market Segmentation
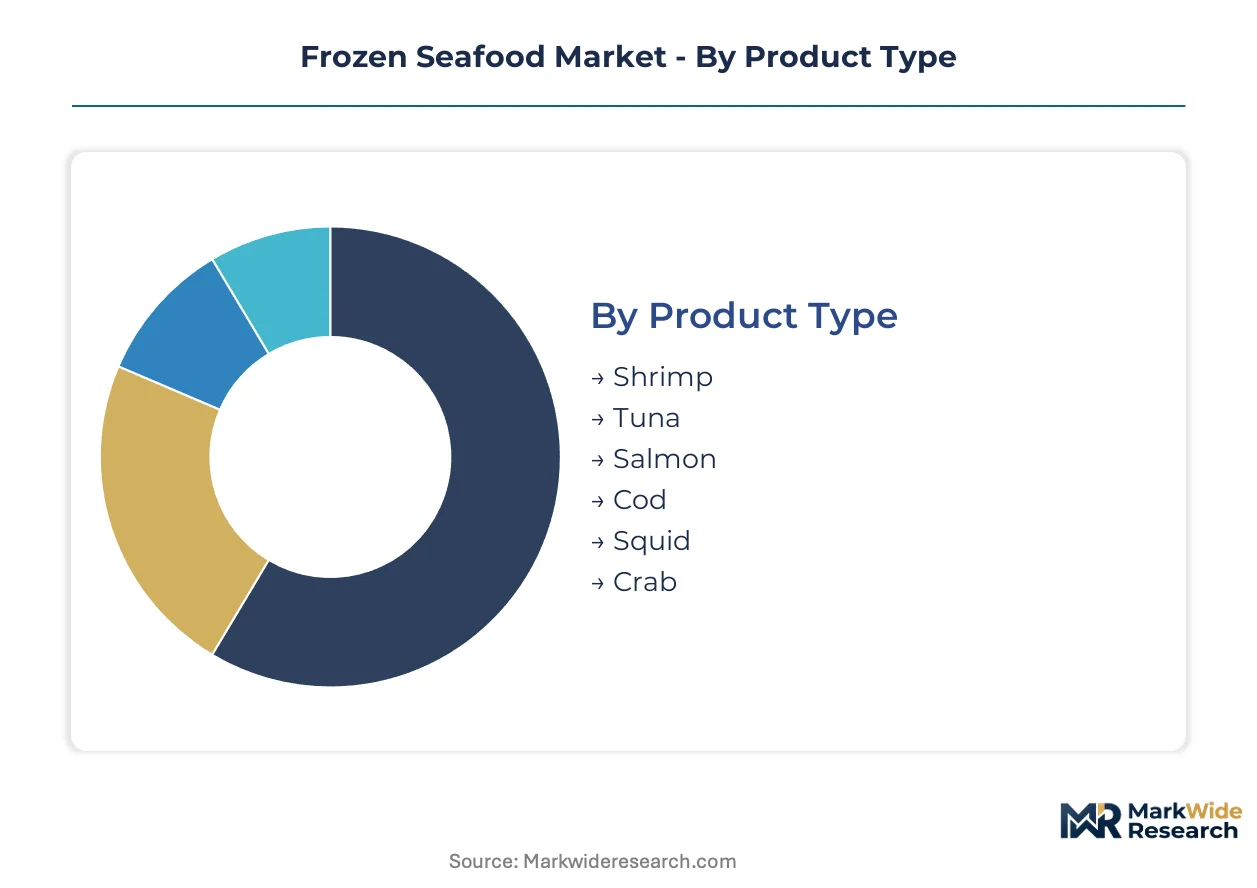
Understanding the varied segments within the frozen seafood market illuminates distinct demand patterns and supply chain dynamics. This granular analysis helps stakeholders identify specific growth pockets and tailor product offerings to diverse consumer preferences and industrial requirements, optimizing resource allocation across the value chain.
Product Type:
The product type spectrum ranges from high-volume commodity fish to premium shellfish, each serving different culinary applications and consumer price points.
- Shrimp:This segment comprises various species like Vannamei and Black Tiger, often processed into peeled, deveined, or cooked forms. Strong consumer preference in retail and foodservice drives consistent demand across North America and Europe.
- Salmon:Atlantic salmon and wild-caught Pacific varieties dominate this category, valued for their nutritional profile and versatility. Demand from online retailers for premium, sustainable options significantly influences the market in Germany and the United Kingdom.
- Tuna:Primarily sold as fillets or steaks, tuna products cater to both direct consumption and further processing into canned goods.
- Cod:North Atlantic cod is a staple in many markets, often sold as fillets for traditional dishes or fish and chips.
- Squid:This product type sees demand in specific regional cuisines and as a versatile ingredient for various prepared meals.
- Crab:Premium crab meat, often frozen as claws or whole sections, commands higher prices in specialty markets.
Established volume favors Shrimp; emerging adoption favors Salmon.
Packaging Type:
Packaging solutions address varying needs for preservation, convenience, and bulk handling, directly impacting product shelf life and presentation.
- Vacuum Packed:This method removes air to prevent oxidation and freezer burn, significantly extending the shelf life of premium fish fillets and shellfish. Consumers prioritize vacuum-packed items for maintaining texture and flavor.
- Bulk Packed:Large-format packaging, often in industrial boxes or bags, is designed for efficient storage and transport to foodservice providers and food processors. Cost efficiency and volume capacity drive adoption in the catering sector.
- Tray Packed:Convenient for retail, tray-packed products offer portion control and visual appeal for supermarket shoppers.
- Bag Packed:Flexible bag packaging is common for smaller, loose items like shrimp or squid rings, offering easy storage.
- Box Packed:This packaging type provides structural integrity for delicate items and is frequently used for retail and wholesale distribution.
Efficiency in cold chain logistics is often optimized by Box Packed formats, while consumer convenience drives demand for Tray Packed options.
Distribution Channel:
The distribution landscape is evolving, with traditional retail channels adapting to the growing influence of specialized and online platforms.
- Foodservice Providers:This channel includes restaurants, hotels, and institutional catering, demanding portion-controlled and ready-to-cook frozen seafood items. Consistency and ease of preparation are critical for large-scale operations.
- Online Retailers:E-commerce platforms are gaining significant share, particularly for premium and specialty frozen seafood, leveraging direct-to-consumer models. Digital traceability platforms enhance consumer trust for these purchases.
- Supermarkets:Traditional grocery stores remain a primary channel for mainstream frozen seafood products, offering wide accessibility and variety.
- Wholesalers:These entities supply bulk frozen seafood to smaller retailers, restaurants, and other commercial buyers.
- Specialty Stores:Boutique seafood markets and gourmet food shops cater to discerning consumers seeking unique or high-quality frozen selections.
Volume distribution concentrates through Supermarkets, whereas Online Retailers are expanding most quickly.
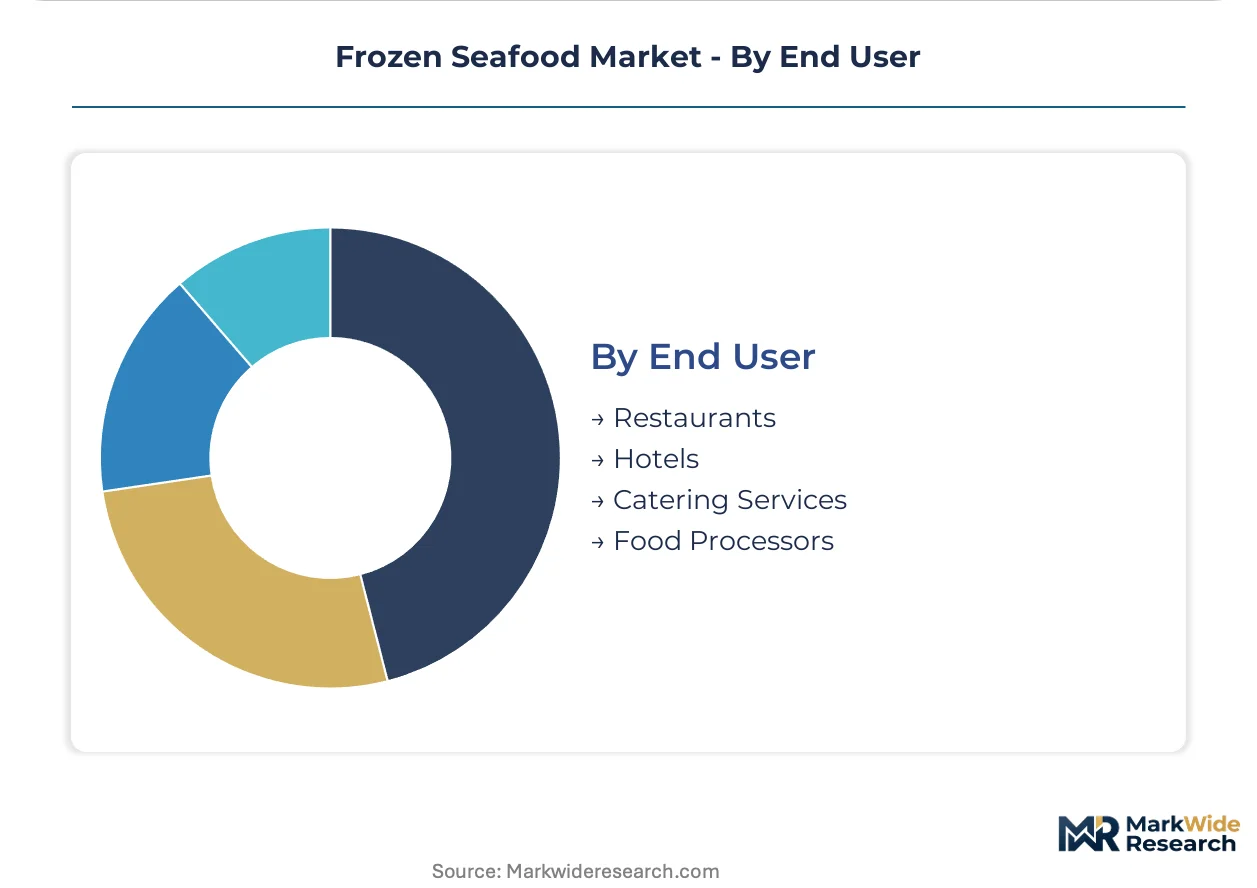
End User:
End-user segments reflect distinct preparation requirements and consumption patterns, from individual consumers to large-scale food manufacturers.
- Restaurants:Commercial kitchens require consistent quality and specific portion sizes for their menu offerings, often sourcing through foodservice distributors. The demand for ready-to-cook items minimizes prep time for chefs.
- Food Processors:These manufacturers utilize frozen seafood as raw material for further value-added products like ready meals, fish sticks, or seafood salads. Compliance with HACCP standards is paramount for these industrial buyers.
- Hotels:Hotels integrate frozen seafood into diverse dining options, from breakfast buffets to fine dining, balancing cost and quality.
- Catering Services:Catering operations depend on reliable supply and easy-to-manage products for events of varying scales.
Large-scale procurement favors Food Processors; direct culinary application drives demand from Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cold chain infrastructure, particularly specialized port facilities, underwrites regional market dynamics for frozen seafood. These logistical hubs enable efficient import and export flows, connecting major processing centers to consumer markets. Demand patterns vary significantly across continents, influenced by local culinary traditions and regulatory frameworks.
United States
Demand for portion-controlled and ready-to-cook frozen seafood items drives US market volume. The FDA's HACCP requirements mandate stringent food safety compliance for all seafood imports. Major processing and distribution centers in Seattle, Washington, facilitate extensive trade with Pacific fisheries.
Germany
German consumers increasingly prioritize sustainable and premium frozen salmon, boosting demand in retail channels. EFSA's traceability mandates ensure comprehensive documentation from catch to final sale within the EU. Hamburg serves as a critical port for frozen seafood imports, distributing products across Central Europe.
Vietnam
Vietnam's robust export processing industry for shrimp and pangasius fuels significant frozen seafood production. Compliance with EU and US import regulations has strengthened its global trade position. Processing clusters in the Mekong Delta specialize in high-volume, value-added seafood products.
China
Rising domestic consumption and an expanding foodservice sector contribute to China's frozen seafood growth. Imported products must comply with SAMR inspection and quarantine standards, influencing trade flows. Dalian, a major port city, acts as a primary entry point for global frozen seafood into the Chinese market.
India
Expanding cold chain logistics in India's inland regions creates new retail channels for frozen seafood. The FSSAI regulates food safety and quality standards for both domestic and imported seafood products. Coastal states like Kerala and Andhra Pradesh are developing processing hubs to cater to both export and internal demand.
Frozen Seafood Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the frozen seafood market. The industry structure exhibits consolidation among multinational food companies and a fragmented landscape of regional and niche processors. Strategic archetypes include vertically integrated aquaculture giants, large-volume wild-catch processors, and premium value-added product manufacturers. Companies frequently engage in strategic partnerships for distribution and pursue portfolio diversification to enhance their market reach across different consumer segments.
At the scale-driven end, Trident Seafoods exemplifies a major North American processor, leveraging extensive fishing and processing infrastructure to serve diverse markets. This company's operational footprint anchors significant wild-catch volume and processing capacity. Mowi, a Norwegian company, represents a leading aquaculture-focused entity, controlling supply through significant farming assets and global distribution networks. Its presence underscores the importance of integrated production for species like Atlantic salmon. Thai Union Frozen Products, a Thai-based corporation, occupies a position as a global high-volume processor specializing in shrimp and tuna products for worldwide consumption. The company's operations highlight the strategic importance of Southeast Asian processing hubs.
| Leading Market Players |
|---|
| High Liner Foods |
| Trident Seafoods |
| Mowi (Marine Harvest) |
| Sysco Corporation |
| American Seafoods Group |
| Thai Union Frozen Products |
| Iglo Group |
| North Coast Seafoods |
| Leroy Seafood Group |
| Others |
Cost & Logistics Intelligence
Underutilized cold storage capacity in emerging markets like India and Brazil drives both supplier behavior and pricing posture, as processors seek to leverage existing infrastructure for new market penetration. This dynamic influences investment in distribution networks and impacts regional price competitiveness.
Pricing Analysis
The FDA's HACCP requirements dictate the pricing tier structure for imported frozen seafood, emphasizing compliance costs. Commodity spot pricing dominates for high-volume items like shrimp, while contract-based long-term offtake agreements secure supply for large foodservice providers. Price differentiation stems from quality grade, such as IQF processing, and sustainability certifications like MSC. Pricing pressure stems from energy cost volatility in cold storage, compressing operational margins. Foodservice providers exhibit higher price sensitivity for bulk purchases, whereas online retailers catering to premium segments tolerate higher prices.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the fragmented sourcing network for frozen seafood, particularly in Southeast Asia. Geographic supply concentration centers on Vietnam and Thailand for shrimp and tuna, alongside Norway for Atlantic salmon and cod. Raw material dependencies include specific wild-catch species and farmed aquaculture outputs like Vannamei shrimp. Supply chain risk arises from climate-related disruptions to fisheries, creating sourcing unpredictability. Distribution runs through a hybrid model, combining large wholesalers for foodservice with direct channels for online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen seafood market presents a defensive-moat story, primarily justified by the regulatory entrenchment of food safety and traceability mandates across key import regions.
For Market Incumbents:
Build regulatory moats through continuous investment in digital traceability platforms that meet EFSA and FDA standards. Deepen vertical integration into aquaculture assets to control supply and mitigate wild-catch instability. Expand cold chain logistics in underpenetrated inland regions like India to counter margin pressure from energy cost fluctuations. Leverage advanced freezing technologies like HPP to differentiate premium value-added products against emerging competitors.
For New Entrants and Emerging Players:
Pursue niche opportunities within premium, sustainably certified frozen seafood, targeting direct-to-consumer sales channels. Focus on value-added product lines, such as seasoned or marinated items, to command higher price points beyond commodity offerings. The online retail channel in Germany and the United Kingdom offers a penetrable segment for specialty items. A go-to-market angle emphasizing provenance and clean-label attributes resonates strongly with discerning consumers.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across cold chain logistics and advanced processing technologies, signaling a shift towards more capital-intensive, integrated operations. The market exhibits long-term viability, driven by consistent consumer demand for convenient protein sources, but requires significant investment in compliance infrastructure. Target acquisition profiles include vertically integrated aquaculture firms with strong environmental certifications or specialized cold chain logistics providers. Digital traceability platform integration serves as a critical signal to watch for operational efficiency and regulatory adherence.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IQF Processing Capacity | Enhances product quality and extends shelf life, meeting stricter consumer expectations for frozen seafood. |
| Invest in Digital Traceability Systems | Ensures compliance with stringent EU and US import regulations, building consumer trust. |
| Develop Value-Added Product Lines | Captures higher margins and differentiates offerings beyond unprocessed commodity fish and shellfish. |
| Strengthen Cold Chain Logistics Networks | Facilitates market expansion into inland regions and improves efficiency for global distribution. |
| Acquire Aquaculture Assets | Secures consistent supply of key species like salmon and shrimp, mitigating wild-catch volatility. |
Research Approach
Desk research of industry reports, government publications, and company financial statements preceded structured interviews with aquaculture farm managers, seafood processors, foodservice procurement managers, and retail category buyers. This approach combined primary insights with secondary validation, employing both bottom-up and top-down triangulation. Key secondary data sources included FDA filings, EFSA reports, customs trade data, and FAO fisheries statistics, providing a comprehensive market view.
The forecast framework assumed stable global economic growth and consistent regulatory environments across the analysis window. Segmentation dimensions modeled included product type, packaging type, distribution channel, end user, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected future demand, considering factors like seafood consumption trends and cold chain infrastructure investment. This allowed for a granular projection of market evolution.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or energy prices would shift the trajectory. Forecasts reflect assumptions regarding climate change impacts on fisheries and geopolitical trade relations. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Asia-Pacific Seafood Market
Seafood
Fresh Fish Market
Seafood
Global Seafood Market
Seafood
South America Canned Seafood Market
Seafood
Sea Bream Market
Seafood
North America Salmon Market
Seafood
Canned Fishery Product Market
Seafood
Japan Frozen Seafood Market
Seafood
Asian Sea Bass Market
Seafood
Surimi Market
Seafood
Canned Seafood Market
Seafood
Carp Market
Seafood
Fish Oil Market
Seafood
Mussels Market
Seafood
Surimi by-Product Market
Seafood
Canned Tuna Market