
 Carp Market | 2026-2036
Carp Market Size, Share, and Industry Trends Forecast 2026-2036
Carp Market Intelligence
The expansion of direct-to-consumer online sales channels is recalibrating the end-use mix, shifting focus from traditional wholesale markets. Major producers like Baiyang Investment Group Inc. leverage large-scale aquaculture operations in Asia to meet volume demand. In contrast, Priory Fishery Ltd specializes in high-quality coarse fish for recreational angling markets in the UK. Anhui Fuhuang Sungem Foodstuff Group Co. Ltd. differentiates through its focus on processed carp products for export.
Carp refers to various species of oily freshwater fish from the family Cyprinidae, widely cultivated for food and ornamental purposes. These species are characterized by their adaptability to diverse aquatic environments and efficient feed conversion ratios. Farmed sources dominate supply over wild-caught, with Common Carp and Grass Carp representing the largest volume by species type due to rapid maturation. The wholesale channel is the primary distribution path, although direct-to-consumer online platforms are gaining market share.
Global trade and aquaculture practices are governed by standards including food safety regulations from the US FDA and the EU's EFSA. Environmental regulations, such as China's MEE guidelines on water quality and discharge from aquaculture farms, shape production methods. Producers must navigate these divergent regulatory landscapes while managing biosecurity risks to ensure both market access and operational sustainability.
Market Dynamics
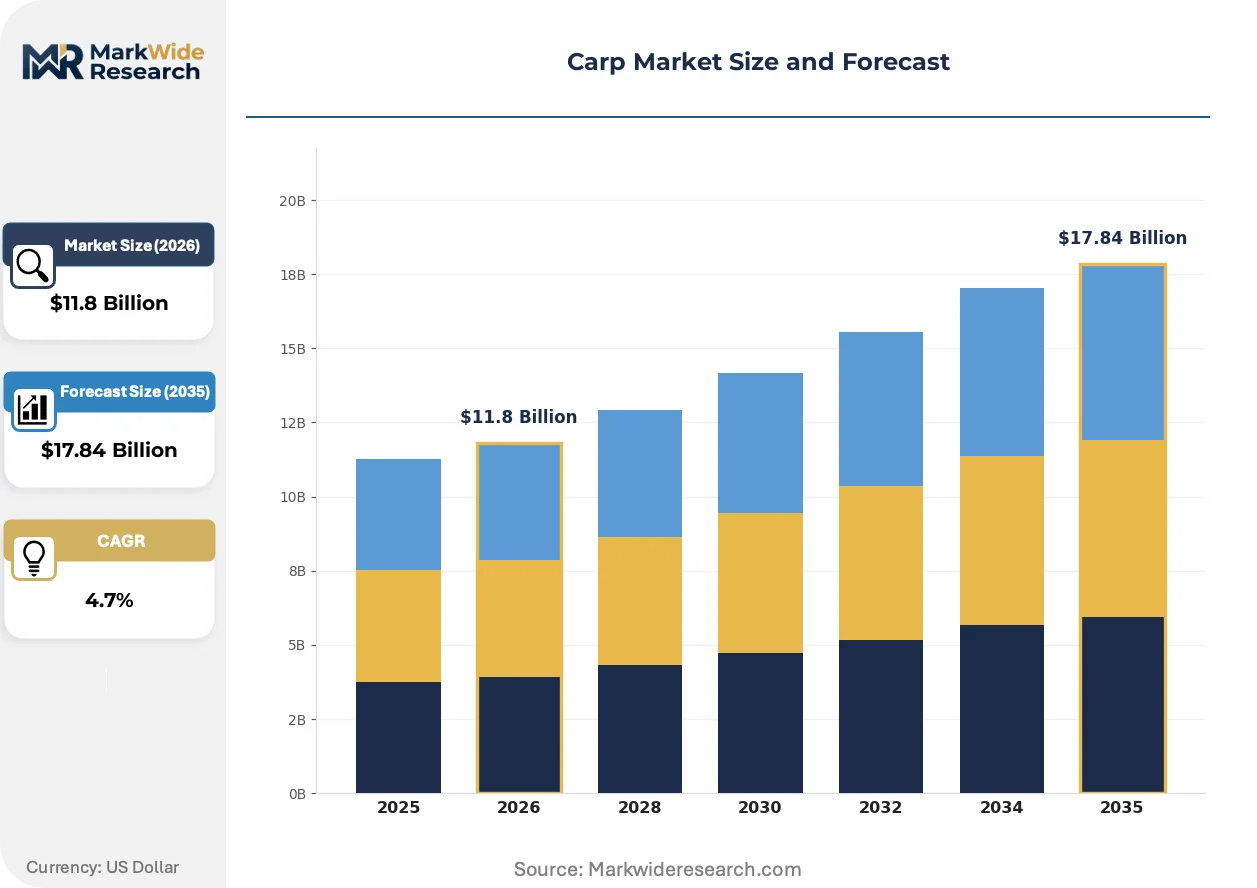
The central force shaping the carp market is the industrialization of aquaculture, driven by recirculating aquaculture systems (RAS) and selective breeding programs. This technological shift enables higher production density and greater control over environmental variables, directly addressing sustainability and food security concerns.
Growth Catalysts
- Rising Food Service Demand:Increased consumption of carp in restaurants and catering services, particularly in Asia, provides a consistent volume driver for producers. This is supported by the fish's versatility in various culinary preparations.
- Aquaculture Technology:Advancements in Recirculating Aquaculture Systems (RAS) are improving yield, reducing water usage, and minimizing environmental impact. This technology enables production in regions with limited water resources.
- Government Food Security Policies:National policies in countries like China and India promote aquaculture development to ensure a stable domestic supply of affordable protein, providing a supportive framework for farm expansion.
Market Restraints
- Feed Cost Volatility:The profitability of carp farming is highly sensitive to fluctuations in the prices of key feed components, such as soy and fishmeal, which constitute a major operational expense.
- Stringent Environmental Regulations:Strict regulations on water quality and effluent discharge, such as China's MEE guidelines and the EU's Water Framework Directive, increase compliance costs and operational complexity for aquaculture farms.
- Competition from Substitutes:Carp faces significant competition from other low-cost freshwater fish, notably tilapia, which has a similar price point and wide consumer acceptance in many global markets.
Strategic Opportunities
- Value-Added Processing:There is a significant opportunity in developing processed and value-added products, such as frozen fillets, smoked carp, and ready-to-cook meals, to target export markets and modern retail channels.
- Recreational Angling Markets:Expanding sales of coarse fish to specialized recreational angling markets in North America and continental Europe offers a high-margin niche beyond traditional food consumption.
- Sustainability Certification:Achieving certifications from bodies like the Aquaculture Stewardship Council (ASC) allows producers to access premium retail segments and cater to environmentally conscious consumers in Europe and North America.
Industry Challenges
- Biosecurity Management:Preventing and controlling disease outbreaks in high-density farming operations remains a constant operational challenge, requiring significant investment in monitoring, veterinary care, and biosecurity protocols to avoid catastrophic stock losses.
- Fragmented Regulatory Compliance:Producers exporting globally must navigate the complex and often divergent food safety standards set by authorities like the US FDA and the EU's EFSA, creating compliance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carp Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Species Type: Common Carp, Grass Carp, Butterfly Carp, Koi Carp Source: Wild-Caught, Farmed, Aqua-therapeutic, Organic Size: Small, Medium, Large, Jumbo Distribution Channel: Retail, Wholesale, Direct-to-Consumer, Online |
| Companies Covered | Priory Fishery Ltd, Hampshire Carp Hatcheries, Quintons Orchard Fish Farm, VS Fisheries, Anhui Fuhuang Sungem Foodstuff Group Co. Ltd., Baiyang Investment Group Inc., Coarse Fish UK, Greenwater Fish Farm, Dahu Aquaculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carp Market Strategic Shifts & Innovations
Intensification of production through technology is the primary theme transforming the carp market. Data analytics and advanced biological sciences are being integrated into traditional farming to optimize feed conversion, improve health outcomes, and enhance traceability from farm to table.
Selective breeding programs that use genetic markers are improving key traits like growth rate and disease resistance. Large-scale aquaculture operators, particularly in Asia, are rapidly adopting these techniques to boost productivity and secure a more predictable harvest. This advanced breeding science is converging with automated sensor-based water quality monitoring to create highly controlled and efficient production environments.
The European Green Deal's "Farm to Fork" strategy is creating new compliance imperatives for global aquaculture. This policy framework demands greater supply chain transparency and a lower environmental footprint for all food products sold in the EU. Producers in key exporting nations must now document and verify sustainable practices, including water management and feed sourcing, to maintain access to this critical market.
A distinct shift toward direct-to-consumer (DTC) online sales is altering the traditional distribution model. This approach allows producers to bypass wholesale intermediaries, thereby retaining greater margin and building a direct brand relationship with end-users. The trend is most advanced in major urban centers across China, where consumers use mobile applications to order fresh carp directly from farms for home delivery.
Carp Market Segmentation
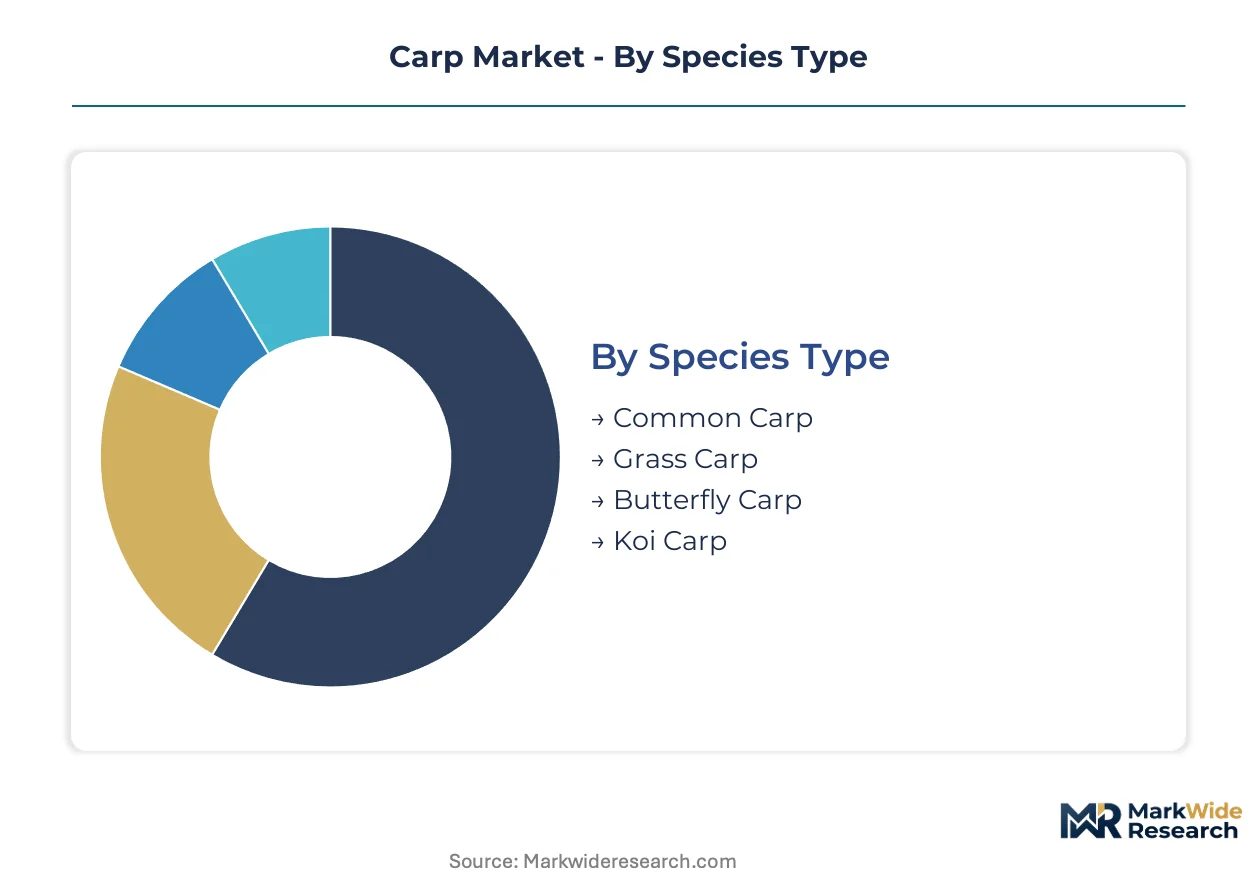
Understanding the Carp Market through detailed segmentation reveals distinct value propositions and operational models across its diverse ecosystem. This analysis highlights how species biology, cultivation methods, and distribution strategies collectively define market access and profitability. Producers must align their offerings with specific end-user requirements to optimize their market position.
Species Type:
The biological characteristics and growth rates of different carp species directly influence their commercial viability and market penetration.
- Common Carp:This adaptable omnivorous freshwater fish, *Cyprinus carpio*, exhibits rapid growth and efficient feed conversion. Demand concentrates in Asian food service, particularly China, driven by its culinary versatility and consistent aquaculture supply.
- Grass Carp:*Ctenopharyngodon idella*, a herbivorous species, is valued for aquatic vegetation control and lean white flesh. Its primary market is the Asian food sector, where government policies in India promote its aquaculture.
- Butterfly Carp:Ornamental common carp varieties, distinguished by elongated fins and vibrant coloration. They serve specialized aquarist and pond keeper markets globally.
- Koi Carp:Highly prized ornamental fish, Koi are selectively bred common carp with distinct patterns and cultural significance in Japan. These premium fish command high prices.
Common Carp leads on scale; Grass Carp leads on momentum due to its increasing cultivation in developing aquaculture regions.
Source:
Supply concentration within the carp market varies significantly based on the method of procurement, impacting consistency and cost structures.
- Farmed:Aquaculture operations cultivate carp in controlled environments, using technologies like RAS for consistent supply and environmental management. This source dominates global supply, especially in China, meeting high volume food demand.
- Wild-Caught:Carp harvested from natural lakes and rivers represent a smaller, seasonal market portion. This source faces increasing regulatory constraints on fishing quotas, including China's MEE guidelines.
- Aqua-therapeutic:Carp raised for therapeutic applications like ichthyotherapy, forming a niche market. These operations require stringent biosecurity.
- Organic:Carp produced under certified organic standards, adhering to specific feed and water quality guidelines. This segment targets premium retail channels in Europe.
Farmed sources provide the foundational volume for the market, while organic production represents a growing premium segment.
Size:
The physical dimensions of carp dictate their suitability for various culinary preparations and processing applications, influencing market value.
- Large:Carp weighing several kilograms, preferred for whole fish presentation in restaurants and processing into fillets. These specimens are sought after in Asian food service for their substantial yield.
- Medium:Fish within a moderate weight range, suitable for individual servings or smaller household consumption. This size category maintains broad appeal across wholesale and direct-to-consumer channels.
- Small:Smaller carp, often juveniles, find use in specialized dishes or as baitfish for recreational angling.
- Jumbo:Exceptionally large carp, sometimes ornamental or trophy fish, command premium prices in niche markets. These are sold to specialized angling centers.
Larger carp drive significant value in food service, while medium-sized fish offer broad consumer accessibility across various channels.
Distribution Channel:
Customer type and margin expectations significantly shape the primary routes through which carp products reach their end-users.
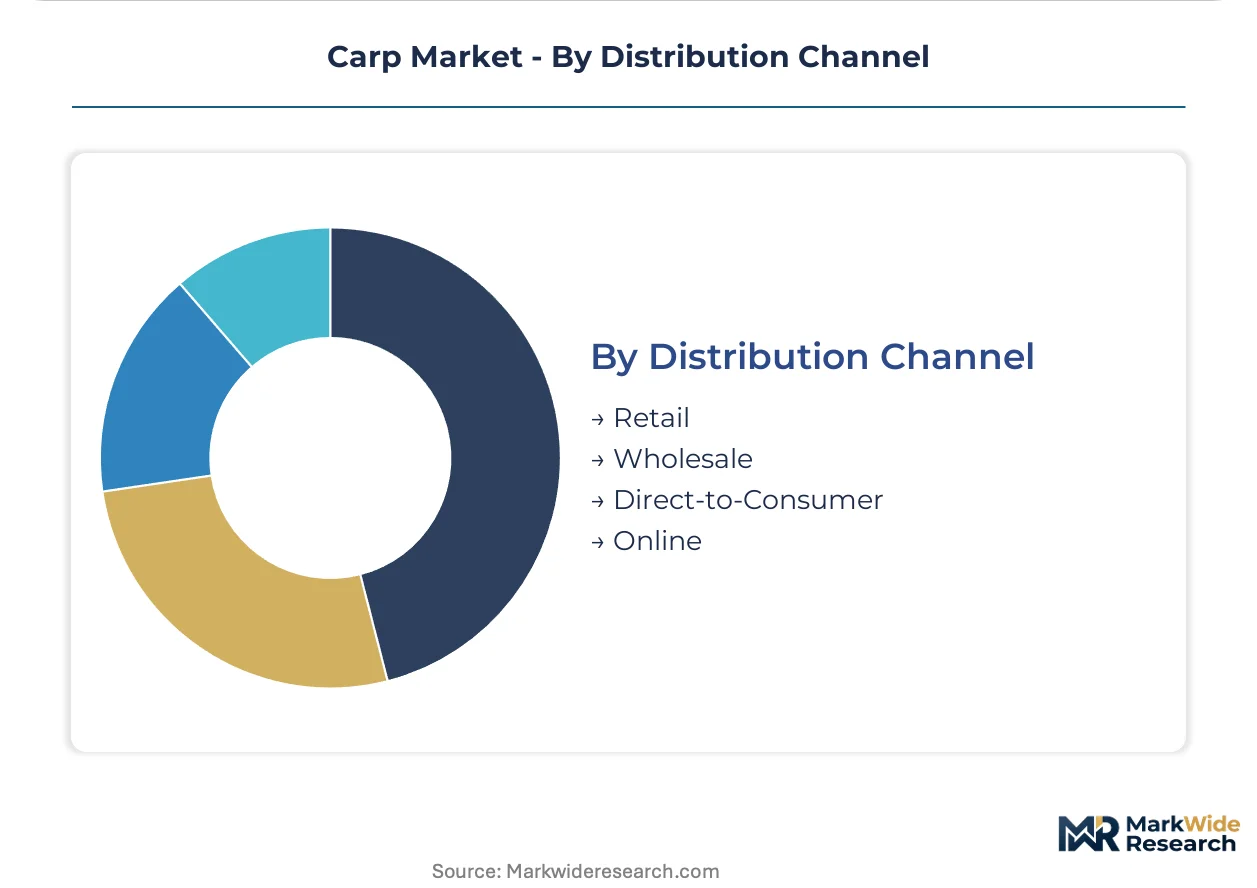
- Wholesale:This traditional channel involves large-volume transactions between producers and distributors, supplying restaurants, supermarkets, and smaller retailers. It remains the dominant distribution path for bulk carp in Asia.
- Direct-to-Consumer:Producers sell directly to individual consumers, often via online platforms or farm-gate sales, bypassing intermediaries. This channel allows higher margin retention and direct brand building, gaining traction in urban China.
- Retail:Sales through conventional supermarkets, hypermarkets, and specialty fish stores, offering fresh or processed carp to household consumers. This channel requires adherence to EU EFSA food safety standards.
- Online:E-commerce platforms facilitate carp sales, from fresh fish to processed products, delivered directly to consumers. This channel expands market reach.
Wholesale channels ensure volume distribution, while direct-to-consumer models capture higher margins and foster brand loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aquaculture infrastructure drives significant carp market volume, fueled by long-standing culinary traditions. This concentration influences global production patterns and trade flows. Government initiatives supporting food security further solidify its market position.
China
Chinese culinary traditions create sustained demand for carp across the food service sector. The Ministry of Ecology and Environment (MEE) guidelines on water quality shape aquaculture practices. The Yangtze River Delta region hosts extensive carp farming operations, supplying major urban centers.
India
Rising protein demand in India supports consistent carp consumption, particularly in rural areas. Government food security policies promote aquaculture development to ensure affordable protein supply. States like Andhra Pradesh and West Bengal are significant production hubs for Grass Carp.
United Kingdom
Recreational angling markets in the United Kingdom create specialized demand for high-quality coarse fish. Environmental standards from the Environment Agency influence fishery management and biosecurity protocols. Rural areas with dedicated coarse fisheries, such as those near Priory Fishery, cater to this niche.
Germany
European consumers increasingly seek sustainably sourced carp for food consumption, especially in Germany. The EU's Water Framework Directive imposes strict regulations on water quality and effluent discharge for aquaculture operations. Bavaria and Brandenburg are key regions for carp farming, focusing on both food and stocking markets.
United States
Demand for carp in the United States primarily stems from niche food markets and ornamental purposes. The US FDA regulates food safety standards for imported and domestically produced carp products. Midwest states, particularly Arkansas, maintain significant carp production for various end-uses.
Carp Market Key Industry Players
Capacity expansion dominates the current landscape, driven by technological advancements in aquaculture. The market exhibits a tiered structure, with large-scale producers, niche specialists, and value-added processors. Strategic partnerships and portfolio diversification are key competitive moves for market players.
Large-scale aquaculture operators like Baiyang Investment Group Inc. anchor high-volume production, primarily serving Asian markets. Priory Fishery Ltd. exemplifies niche specialization, providing high-quality coarse fish for the recreational angling sector in the UK. Anhui Fuhuang Sungem Foodstuff Group Co. Ltd. occupies a distinct position by focusing on processed carp products for export channels.
| Leading Market Players |
|---|
| Priory Fishery Ltd |
| Hampshire Carp Hatcheries |
| Quintons Orchard Fish Farm |
| VS Fisheries |
| Anhui Fuhuang Sungem Foodstuff Group Co. Ltd. |
| Baiyang Investment Group Inc. |
| Coarse Fish UK |
| Greenwater Fish Farm |
| Dahu Aquaculture |
| Others |
Cost & Logistics Intelligence
The EU's "Farm to Fork" strategy demands greater supply chain transparency and lower environmental footprints. This mandate directly gates access for sustainably certified carp products to premium European retail segments.
Pricing Analysis
Retailer markups significantly influence consumer prices for processed carp products. Transactional, per-unit pricing dominates, particularly in wholesale channels for fresh carp. Quality grade, often linked to Aquaculture Stewardship Council (ASC) certification, and geographic delivery costs are key differentiators. Pricing softness in the common carp segment stems from intense competition with other low-cost freshwater fish like tilapia. Food service buyers in Asia are highly price-sensitive for bulk volume, while recreational angling markets in the UK are least sensitive, valuing specialized coarse fish.
Supply Chain Analysis
Adherence to US FDA food safety standards and EU EFSA guidelines gates market access for carp products. Supply concentrates in China, India, and Vietnam for farmed carp. The industry relies on soy and fishmeal for feed components. Commodity price volatility for feed constitutes a major structural risk. Wholesale channels remain the dominant downstream distribution structure for global volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carp market functions as a geographic-arbitrage play, leveraging lower production costs in Asian aquaculture hubs against premium pricing opportunities for sustainably certified products in European retail.
For Market Incumbents:
To counter intense price competition from tilapia, large-scale carp producers must invest in selective breeding programs for faster growth and disease resistance. Expanding value-added processing capabilities allows for product differentiation and higher margin capture in export markets. Focus on achieving Aquaculture Stewardship Council (ASC) certification also enhances market access to premium segments.
For New Entrants and Emerging Players:
Capture underpenetrated recreational angling markets in North America and continental Europe by specializing in high-quality coarse fish. Developing niche products like ornamental Koi Carp for specialized aquarist markets offers higher margins. A direct-to-consumer online sales model allows for brand building and bypassing traditional wholesale intermediaries.
For Investors and Strategic Acquirers:
Valuations sit cheapest among fragmented, mid-sized aquaculture operations lacking modern RAS technology or export certifications. Long-term viability rests on consolidation and technological upgrades for efficiency and sustainability, aligning with global food security mandates. Acquisition targets should include firms with established processing infrastructure or strong regional distribution networks. The signal to watch is accelerating adoption of advanced aquaculture technologies, particularly RAS.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion via RAS Technology | Increases production density and resource efficiency while reducing environmental impact in key aquaculture regions. |
| Value-Added Product Development | Diversifies revenue streams and accesses premium retail and export markets beyond traditional fresh fish sales. |
| Sustainability Certification (ASC) | Unlocks access to environmentally conscious consumer segments and premium retail channels in Europe and North America. |
| Direct-to-Consumer Channel Investment | Enhances margin retention and builds direct brand relationships with end-users, especially in urban centers. |
| Biosecurity Protocol Implementation | Mitigates disease outbreak risks in high-density farming, ensuring consistent supply and operational stability. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and proprietary databases — were reconciled to build a comprehensive view of the carp market. Stakeholders included aquaculture farm managers, food service procurement leads, regulatory affairs specialists, and retail buyers. Secondary data sources comprised government aquaculture reports, trade association statistics, and academic research. This approach enabled robust bottom-up and top-down triangulation for market sizing.
Historical market performance was cross-referenced with expert panel input to establish the forecast framework across the analysis window. Segmentation dimensions modeled included species type, source, size, and distribution channel, alongside regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived from a multi-variant regression analysis. Key forecast inputs included projected protein demand and aquaculture technology adoption rates.
Regulatory shifts, feed cost volatility, and disease outbreaks are the dominant revision risks for carp market forecasts. These forecasts reflect assumptions regarding sustained consumption patterns and technological advancements. A model refresh is warranted upon material change in global trade policies or aquaculture biosecurity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Global Frozen and Canned Seafood Market
Seafood
Organic Seafood Market
Seafood
Canned Mackerel Market
Seafood
Alaskan Salmon Market
Seafood
Caviar Market
Seafood
Krill Meal Market
Seafood
Surimi Market
Seafood
Canned Fishery Product Market
Seafood
Smoked Salmon Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Canned Sardines Market
Seafood
Sea Bass Market
Seafood
Crayfish Market
Seafood
Tuna Market
Seafood
Sea Bream Market
Seafood
Mussel Extract Market