
 Automotive Carbon Fiber Materials Market | 2026-2036
Automotive Carbon Fiber Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Fiber Materials Market Analytics
The EU Green Deal's CO2 fleet emission targets is shifting procurement priorities across European OEMs toward mass-reduction architectures. Toray Industries Inc. leverages its precursor-to-composite vertical integration to anchor supply security for high-volume programs. Hexcel Corporation competes through aerospace-derived resin formulations adapted for automotive curing cycles. SGL Carbon SE specializes in automotive-specific chopped fiber compounds for injection-molded structural brackets.
Automotive carbon fiber materials comprise polyacrylonitrile-derived or pitch-based filaments with tensile modulus exceeding 230 GPa, engineered into reinforced polymers or prepregs to achieve strength-to-weight ratios superior to aluminum alloys. Continuous fiber dominates structural load paths in premium vehicle architectures where crash performance per kilogram dictates material selection. Thermoplastic processing is displacing thermosetting in high-cycling applications as OEMs seek sub-60-second forming times for body panel production. OEM direct procurement is concentrating volume among platforms exceeding 50,000 units annually, compressing tier-1 supplier margins.
The EPA's fuel economy standards, NHTSA's crashworthiness protocols, and REACH chemical compliance collectively shape material qualification timelines and regional sourcing strategies. ECHA substance restrictions on epoxy hardeners are forcing reformulation investments across European supply chains. Stakeholders must monitor thermoplastic recycling infrastructure buildout and second-life fiber recovery economics as circularity requirements tighten.
Market Dynamics
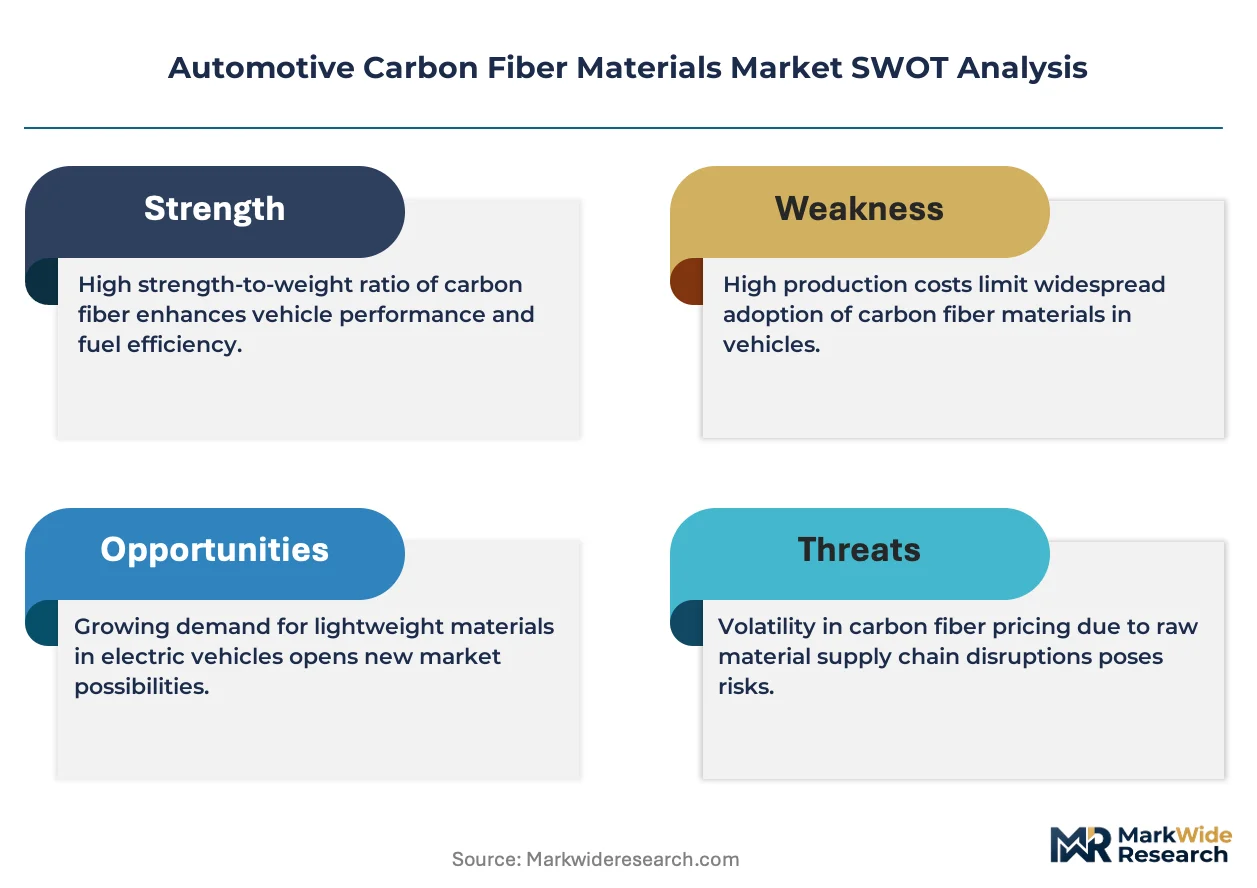
Thermoplastic processing cycles are compressing forming times below sixty seconds, forcing incumbent suppliers to retool or exit high-volume automotive programs as OEMs prioritize throughput over legacy qualification advantages.
Growth Catalysts
- EU Green Deal CO2 mandates:Fleet emission targets are mandating mass-reduction architectures across European OEM platforms, accelerating substitution of aluminum-intensive body structures.
- BMW and Audi EV platforms:Battery enclosure and structural monocoque applications are anchoring demand for continuous fiber architectures in premium electric vehicle segments.
- Toray Industries' precursor verticality:Captive supply of polyacrylonitrile precursors is securing feedstock access for high-volume automotive programs amid raw material volatility.
Market Restraints
- Acrylonitrile feedstock concentration:Precursor production clusters in Asian petrochemical corridors expose European and North American converters to supply disruption and currency fluctuation.
- ECHA epoxy hardener restrictions:REACH substance limitations on amine curing agents are forcing multi-year reformulation investments across established thermoset supply chains.
- Aluminum 7000-series substitution:Advanced high-strength aluminum alloys retain cost advantage in non-structural applications below fifty thousand unit annual volumes.
Strategic Opportunities
- Second-life fiber recovery:Thermoplastic recycling infrastructure buildout is creating circular supply economics for chopped fiber compounds in injection-molded brackets.
- China dual carbon goals:Domestic NEV production quotas are opening qualification pathways for foreign carbon fiber suppliers in battery tray and motor housing applications.
- Sub-60-second thermoforming:High-cycling press technology convergence with automated fiber placement is enabling body panel production at aluminum-comparable takt times.
Industry Challenges
- Automotive curing cycle expertise:Aerospace-trained process engineers lack proficiency in high-throughput resin transfer molding for sub-one-minute cycle targets.
- OEM direct procurement compression:Volume concentration among platforms exceeding fifty thousand units annually is squeezing tier-one supplier margins and fragmenting qualification accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Fiber Materials Market |
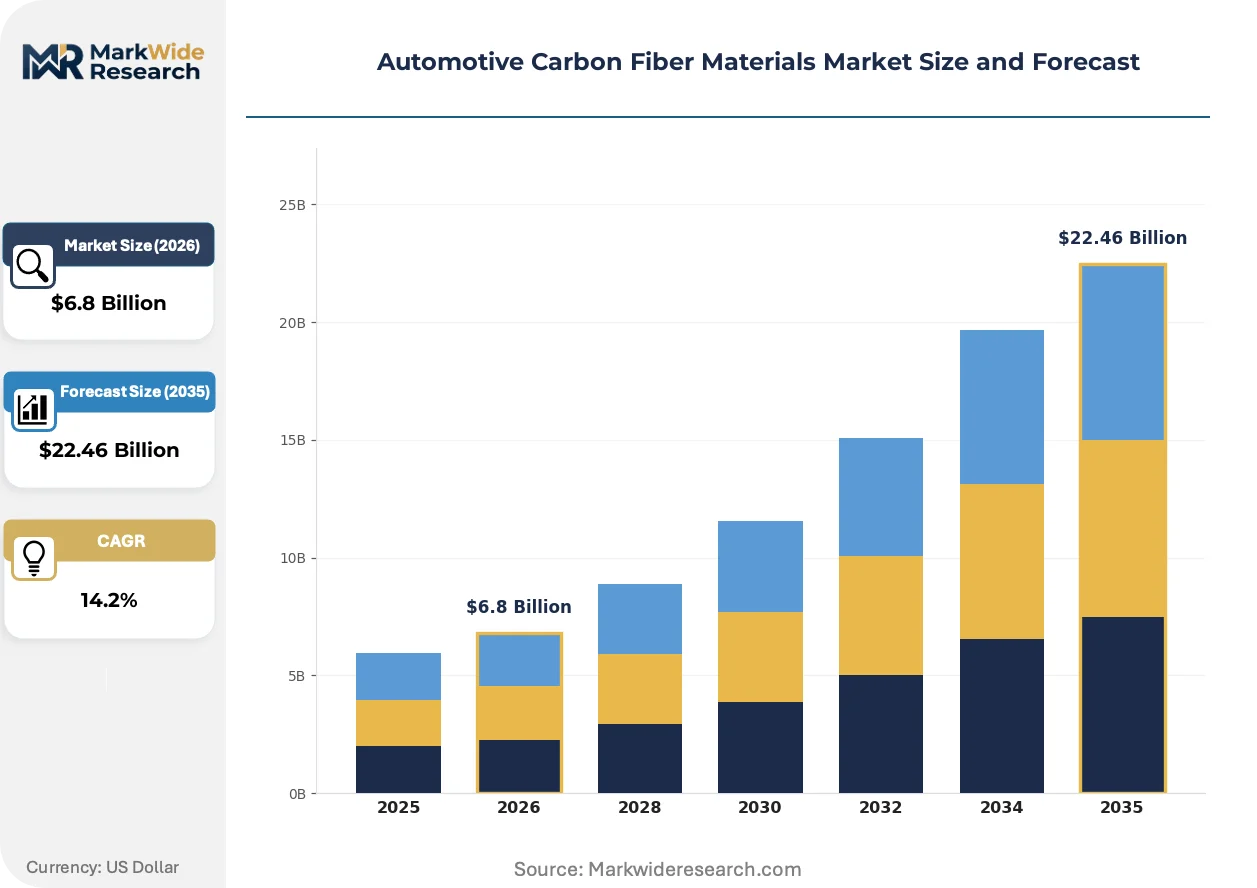
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Short Fiber, Fabric, Composite Technology: Thermoplastic, Thermosetting, Resin Transfer Molding, Pultrusion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body Panels, Interior Components, Structural Parts, Chassis |
| Companies Covered | Toray Industries Inc., Hexcel Corporation, SGL Carbon SE, Teijin Limited, Mitsubishi Chemical Corporation, BASF SE, Solvay SA, Hyosung Advanced Materials, Nippon Graphite Fiber Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Fiber Materials Market Evolving Landscape
Material-process pairing decisions are migrating from tier suppliers to OEM engineering centers, collapsing traditional specification hierarchies and accelerating in-house composite capability development.
Thermoplastic carbon fiber reinforced polymers are absorbing crash energy management functions previously assigned to metallic substructures. BMW's i-series architectures and Audi's e-tron platforms are qualifying these materials for battery enclosure side-impact protection. The shift is absorbing capital from thermoset prepreg operations and redirecting it toward automated tape laying and press-forming equipment.
EPA fuel economy standards and NHTSA crashworthiness protocols are tightening concurrently, creating conflicting material selection pressures in North American vehicle development. OEMs must satisfy fleet-average efficiency targets while maintaining structural performance under frontal and side-impact testing. The tension is most acute in light truck platforms where payload requirements resist mass reduction.
Direct OEM procurement of carbon fiber preforms is displacing tier-one converter relationships in high-volume programs. Engineering teams at Stuttgart and Munich are establishing captive specifications for structural monocoque elements, bypassing traditional supply chain intermediaries. The pattern is visible across German premium OEMs and is propagating through their joint-venture operations in China.
Automotive Carbon Fiber Materials Market Segmentation
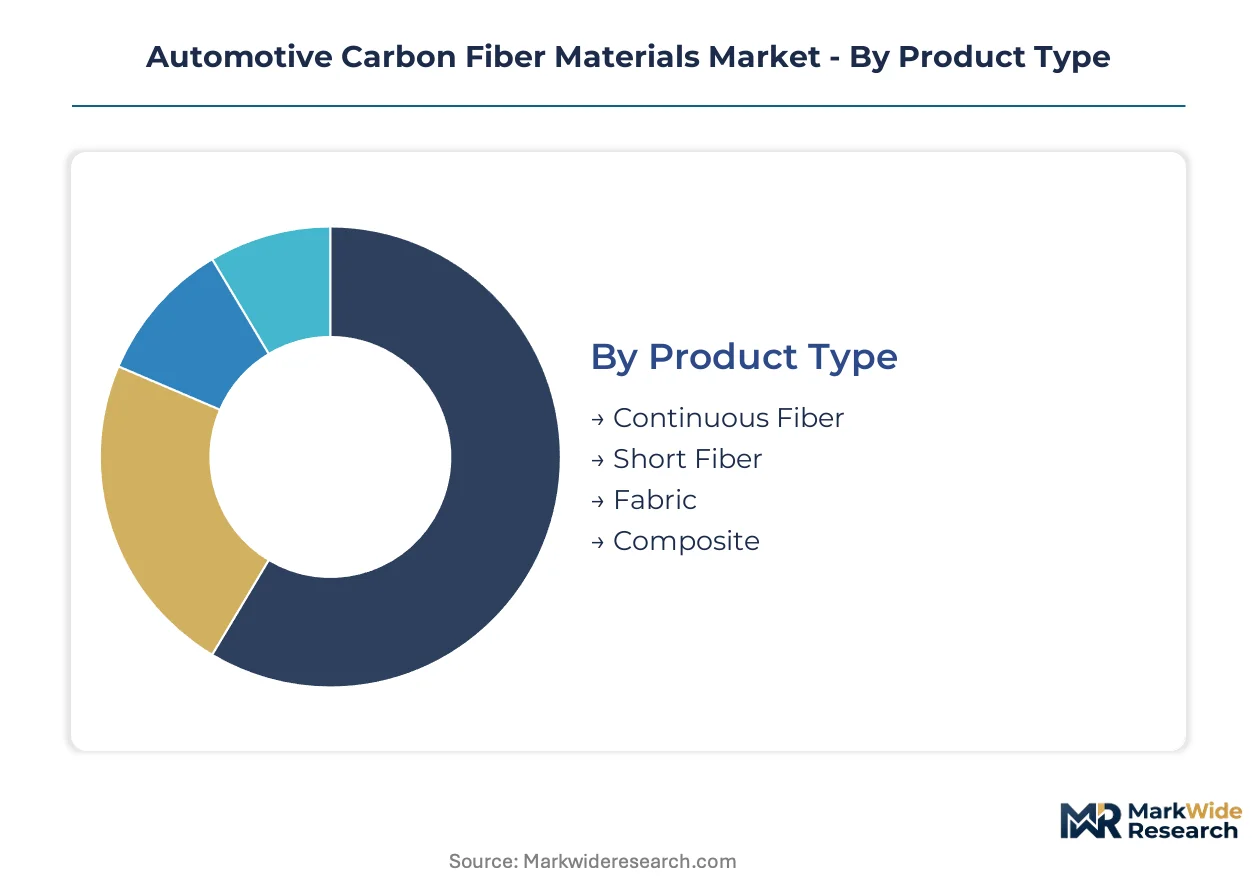
Material-process pairing in automotive carbon fiber hinges on qualification timelines and regulatory burden. Each segment carries distinct certification requirements from NHTSA crash protocols, EPA fuel economy validation, and REACH substance compliance.
Product Type:
REACH substance restrictions and NHTSA crashworthiness protocols impose divergent certification burdens across fiber architectures, with continuous filament requiring extended homologation cycles versus chopped compounds.
- Continuous Fiber:Unidirectional or woven tow configurations with tensile modulus exceeding 230 GPa. BMW and Audi EV platforms anchor demand in battery enclosure side-impact protection, where crash energy absorption per kilogram dictates specification. EPA fuel economy credits reward the mass reduction enabled by these architectures.
- Short Fiber: Chopped filaments 3-50mm in length compounded for injection molding. SGL Carbon SE specializes in automotive-specific compounds for structural brackets, qualifying under faster cycle times than continuous alternatives. ECHA epoxy hardener restrictions affect these formulations less severely than thermoset prepregs.
- Fabric: Woven textile preforms for draping complex geometries. German OEM engineering centers in Stuttgart specify these for monocoque elements, bypassing traditional tier-one relationships.
- Composite: Pre-impregnated or commingled resin-fiber systems. Thermoplastic variants face shorter automotive qualification paths than thermosetting alternatives.
Continuous Fiber sits at the top of the volume ranking, with Short Fiber climbing the fastest as injection-molded bracket applications expand.
Technology:
Cost tier separation between high-cycling press-forming and capital-intensive resin injection systems determines supplier viability at different OEM volume thresholds.
- Thermoplastic:Matrix systems enabling sub-60-second forming cycles through automated tape laying and press consolidation. BMW i-series architectures absorb crash energy management functions previously assigned to metallic substructures, redirecting capital from thermoset operations. The technology circumvents REACH amine curing agent restrictions entirely.
- Thermosetting: Epoxy and vinyl ester systems with established aerospace heritage. Hexcel Corporation competes through resin formulations adapted for automotive curing cycles, though ECHA substance limitations force multi-year reformulation investments.
- Resin Transfer Molding: Closed-mold infusion processes for complex structural geometries. Cycle time compression below one minute remains the critical barrier for high-volume adoption.
- Pultrusion: Continuous profile extrusion for linear structural elements. The process achieves consistent fiber alignment but struggles with geometric complexity demanded by modern vehicle architectures.
Thermoplastic commands the premium cost tier for body panel applications, while Resin Transfer Molding gains share fastest as cycle time targets relax in lower-volume EV platforms.
End User:
Customer type dictates margin structure and qualification accountability, with direct OEM procurement compressing traditional tier-one economics.
- OEMs:Stuttgart and Munich engineering centers establish captive specifications for structural monocoque elements, concentrating volume among platforms exceeding fifty thousand units annually. Direct procurement bypasses tier-one intermediaries and fragments accountability.
- Tier-1 Suppliers: Traditional converter relationships facing margin compression as volume concentrates. Aerospace-trained process engineers within these organizations lack proficiency in high-throughput resin transfer molding targets.
- Aftermarket Providers: Specialty applications for performance vehicle modifications. Qualification burdens from NHTSA and EPA apply differentially versus OEM-integrated programs.
- Vehicle Assemblers: Joint-venture operations in China propagating German premium OEM specifications. Domestic NEV production quotas under China's dual carbon goals open qualification pathways for foreign carbon fiber suppliers.
OEMs sit at the top of the volume ranking, with Vehicle Assemblers climbing the fastest as Chinese joint-venture localization accelerates.
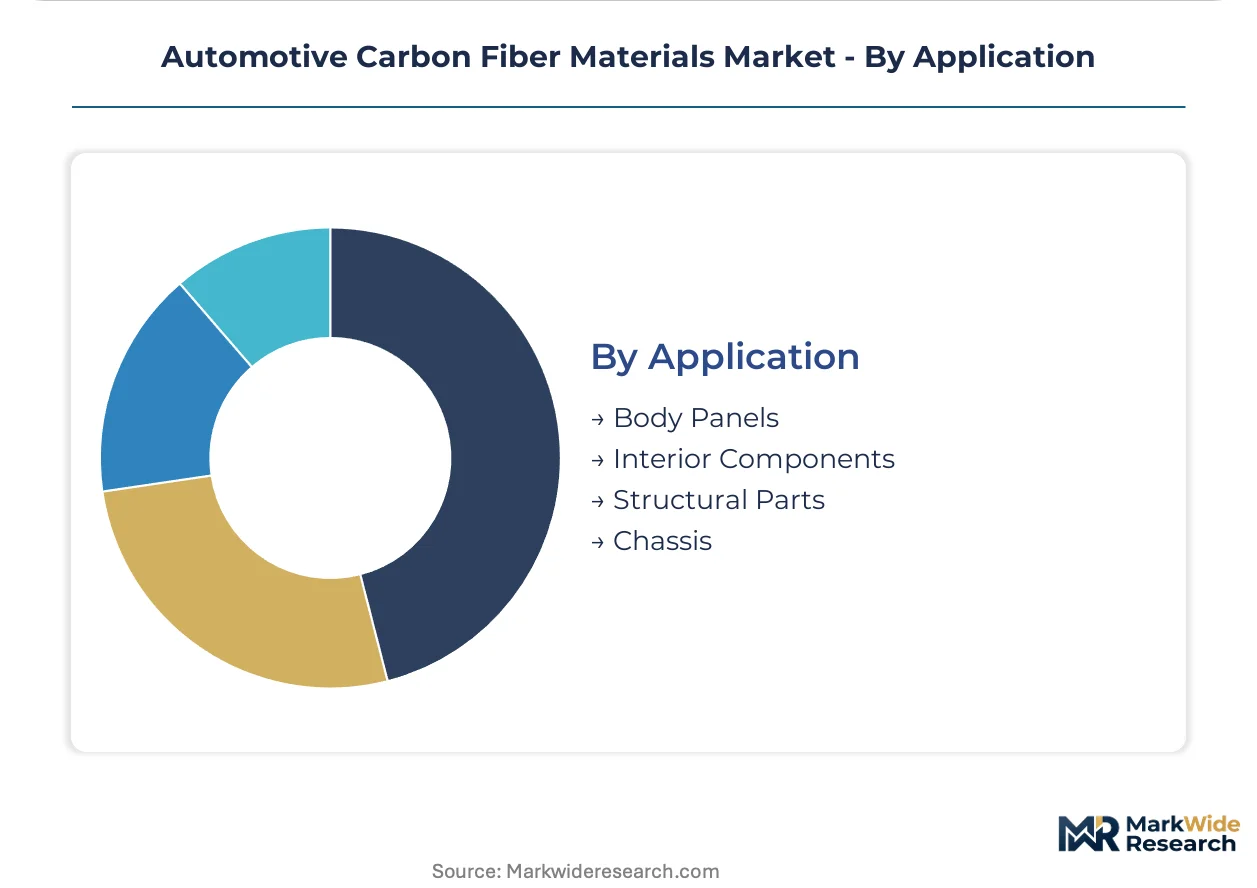
Application:
Application maturity correlates with crash performance validation history, with structural elements carrying the heaviest NHTSA protocol burden versus interior cosmetic components.
- Structural Parts:Load-bearing elements including monocoque nodes and crash management systems. Audi e-tron platforms qualify thermoplastic materials for battery enclosure side-impact protection, absorbing capital from metallic substructure programs.
- Body Panels: Exterior closures where Class A surface finish requirements intersect with mass reduction targets. Sub-60-second thermoforming press technology convergence enables aluminum-comparable takt times.
- Chassis: Suspension attachment points and subframe elements. Aluminum 7000-series substitution retains cost advantage in annual volumes below fifty thousand units.
- Interior Components: Cosmetic and semi-structural cabin elements. Reduced crash validation burden accelerates qualification versus exterior structural applications.
Structural Parts sit at the top of the volume ranking, with Body Panels climbing the fastest as thermoplastic forming cycle targets are achieved.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive carbon fiber materials industry traces its commercial origins to Japanese precursor chemistry development in the 1960s, with German automotive engineering subsequently scaling structural applications through premium vehicle architectures.
Germany
BMW and Audi EV platforms anchor European demand through battery enclosure and structural monocoque programs. The EU Green Deal's CO2 fleet emission targets mandate mass-reduction architectures across premium OEM lineups. Engineering centers in Stuttgart and Munich establish captive specifications for continuous fiber elements, bypassing traditional tier-one intermediaries.
United States
EPA fuel economy standards and NHTSA crashworthiness protocols create dual compliance pressures for domestic OEMs. The tension intensifies in light truck platforms where payload requirements resist mass reduction. Aerospace-trained process engineers in Michigan and California lack proficiency in high-throughput resin transfer molding targets below one minute.
China
Domestic NEV production quotas under dual carbon goals open qualification pathways for foreign carbon fiber suppliers in battery tray applications. Joint-venture operations propagate German premium OEM specifications through localized engineering. MIIT production mandates concentrate demand in Yangtze River Delta battery manufacturing corridors.
Japan
Precursor-to-composite vertical integration originated here with Toray Industries' captive polyacrylonitrile supply securing feedstock access. METI industrial policy supported early automotive qualification programs. Nagoya and Tokyo industrial clusters maintain process engineering expertise for high-modulus fiber architectures.
Automotive Carbon Fiber Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification timeline and automotive-specific curing expertise. The supplier base stratifies into three tiers: aerospace heritage converters with adapted resin formulations, petrochemical-integrated precursor producers, and automotive-focused chopped fiber compounders. Consolidation pressure intensifies as OEM direct procurement concentrates volume among platforms exceeding fifty thousand units annually, squeezing tier-one converter economics.
Within the precursor-integrated tier, Toray Industries Inc. and Mitsubishi Chemical Corporation exemplify backward control over polyacrylonitrile feedstock. Among aerospace-adapted specialists, Hexcel Corporation occupies a position bridging aviation heritage with automotive cycle time requirements. SGL Carbon SE represents the automotive-native archetype through specialization in injection-molded structural compounds.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Hexcel Corporation |
| SGL Carbon SE |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Solvay SA |
| Hyosung Advanced Materials |
| Nippon Graphite Fiber Corporation |
| Others |
Value Network & Pricing Analysis
OEM direct procurement of continuous fiber preforms for battery enclosure programs is compressing tier-one converter margins and forcing supply base consolidation around high-volume qualified suppliers. This buyer-side concentration is reshaping how precursor producers negotiate long-term offtake terms and where compounders invest automotive-specific capacity.
Pricing Analysis
Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade levels dominates transaction structures. Price differentiation rests on carbon fiber modulus grade and REACH-compliant resin formulation certification. Cost compression in automotive-certified tiers is intensifying because OEMs are consolidating volume among platforms exceeding fifty thousand units annually. Aftermarket performance vehicle modifiers show highest price tolerance, while injection-molded bracket compounders face severe margin pressure from aluminum substitution.
Supply Chain Analysis
End-of-life thermoplastic recovery flows are creating circular supply economics for chopped fiber compounds, though infrastructure gaps limit scale. Geographic production clusters center on Japan, Germany, and China for precursor and conversion capacity. Raw material supply draws from acrylonitrile petrochemical corridors, polyacrylonitrile precursor production, and epoxy resin formulation. Single-source vulnerability concentrates in Asian precursor supply for European converters. Distribution runs through OEM direct procurement channels for high-volume programs and tier-one converters for lower-volume specialty applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU Green Deal CO2 mandates enforce mass-reduction architectures across premium vehicle lineups. Regulatory compliance creates durable demand visibility for qualified suppliers.
For Market Incumbents: Deepen backward integration into precursor supply to defend against acrylonitrile feedstock volatility and Asian supply disruption. Secure captive polyacrylonitrile access through long-term petrochemical partnerships. Invest in sub-60-second thermoforming press capacity to outpace thermoset competitors facing REACH epoxy hardener reformulation delays. For New Entrants and Emerging Players: Capture qualification pathways in China's Yangtze River Delta battery manufacturing corridors where domestic NEV production quotas under dual carbon goals create demand. Target thermoplastic recycling infrastructure partnerships for second-life fiber recovery economics. Lead with automated tape laying equipment partnerships to bypass aerospace-culture cycle time limitations. For Investors and Strategic Acquirers: Asymmetric upside sits with automotive-native compounders possessing injection-molded structural bracket expertise and established OEM qualification history. Five-to-ten-year viability favors suppliers with proven crash performance validation under NHTSA protocols. Monitor ECHA substance restriction expansion timelines as inflection indicators for thermoset supplier distress and thermoplastic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries' captive polyacrylonitrile production secures feedstock access amid raw material volatility. |
| Thermoplastic Press Capacity Expansion | Sub-60-second forming cycles enable body panel production at aluminum-comparable takt times for BMW i-series. |
| REACH-Compliant Resin Reformulation | Hexcel Corporation adapts aerospace-derived formulations to circumvent ECHA amine curing agent restrictions. |
| Second-Life Fiber Recovery Infrastructure | Thermoplastic recycling buildout creates circular supply economics for SGL Carbon's injection-molded compounds. |
| China Joint-Venture Localization | German premium OEM specifications propagate through MIIT-mandated NEV production corridors in Yangtze Delta. |
Research Methodology
Multiple input streams — primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings; plus technical literature on curing cycle parameters — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs on qualification timeline compression and thermoplastic substitution rates. Segmentation dimensions modeled include fiber architecture, matrix technology, end-user procurement type, and application crash performance tier. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA fuel economy credit values and EU CO2 penalty structures.
Acrylonitrile price volatility, ECHA regulatory expansion scope, and Chinese NEV subsidy phase-out schedules are the dominant revision risks to modeled outputs. Practitioners should monitor these triggers for early signals of demand trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Composite Materials Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Core Material for Composites Market
Composite Materials
Structural Core Materials Market
Composite Materials
Composite Process Material Kits Market
Composite Materials
FRP Reactor Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Composite Drums Market
Composite Materials
Structural Composites Market
Composite Materials
Case Material Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Europe Composites Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Pulp Moulding Tooling Market