
 Mechanical Hand Tools Market | 2026-2036
Mechanical Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Hand Tools Market Outlook
Professional automotive technicians are unwinding decades of dominance by casual DIY consumers in premium hand tool purchasing. Stanley Black & Decker Inc. leverages its multi-channel distribution to sustain brand visibility across both segments. Snap-On Incorporated dominates the mobile tool van model that controls access to high-margin professional workshops. Apex Tool Group LLC specializes in industrial-grade wrenches and pliers that anchor its position in aerospace maintenance contracts.
Mechanical hand tools are manually operated implements—typically forged from alloy steel with hardness ratings between 40 and 60 HRC—designed to apply torque, grip, cut, or fasten components without external power sources. These instruments serve as indispensable assets in assembly lines, field service operations, and infrastructure maintenance where precision control and portability outweigh automated alternatives. Wrenches and sockets lead product type revenue due to their ubiquity across automotive and construction end users, while titanium and composite materials represent the fastest-expanding material category as operators seek weight reduction for repetitive tasks. The repair application segment commands durable margin pools because downtime-critical industries prioritize tool reliability over upfront cost.
The US Occupational Safety and Health Administration mandates hand tool inspection protocols that shape replacement cycles and liability exposure for employers. The EU's REACH regulation and F-Gas Directive restrict certain surface treatments and coating chemistries, compelling manufacturers to reformulate corrosion-resistant finishes. Japan's Ministry of Economy, Trade and Industry enforces JIS standards that create non-tariff barriers for imported hand tools seeking precision-market entry. Stakeholders must monitor how evolving material certification requirements and carbon-border adjustment mechanisms reshape supplier qualification criteria and sourcing geography decisions.
Market Dynamics
Professional automotive repair shops are consolidating tool procurement around certified-grade inventories as vehicle electrification and ADAS complexity force technicians toward precision-calibrated equipment over general-purpose alternatives.
Growth Catalysts
- EU Green Deal compliance mandates:Chrome-free plating requirements under REACH are accelerating manufacturer retooling toward recycled steel alloys and low-carbon surface treatments.
- Aviation maintenance, repair, and overhaul (MRO):Commercial fleet expansion and aging aircraft inspections are driving demand for torque-calibrated wrenches and non-sparking tools in hangar operations.
- Germany's industrial corridor concentration:Precision assembly operations in Baden-Württemberg and Bavaria are anchoring premium hand tool consumption for automotive and machinery OEM supply chains.
Market Restraints
- Alloy steel price volatility:Nickel and chromium input cost swings compress margin predictability for forged tool manufacturers operating on annual contract pricing.
- Chinese forging capacity dominance:Concentrated upstream supply of hammer-forged blanks creates single-source vulnerability for mid-tier assemblers lacking captive foundry operations.
- Power tool substitution in construction:Cordless impact drivers and battery-powered ratchets are eroding manual socket demand in residential building applications.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods are attracting tool makers to establish forging and finishing facilities in Gujarat and Tamil Nadu industrial zones.
- Composite material convergence:Carbon fiber reinforced polymer handles paired with titanium alloy heads are opening aerospace and defense maintenance contracts previously locked by steel-only specifications.
- Mobile van distribution expansion:Direct-to-bay tool trucks are penetrating independent repair shops in secondary US metro markets underserved by traditional industrial distributors.
Industry Challenges
- Metrology technician scarcity:Calibration laboratories lack sufficient personnel to certify torque tools against ISO 6789 standards within required turnaround windows.
- REACH reformulation timelines:Alternative corrosion coatings require 18-24 month validation cycles that delay product recertification and inventory turnover.
- Legacy ERP integration friction:Tool tracking systems for ISO 9001 audit trails face compatibility gaps with shop floor maintenance software in multi-site fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Hand Tools Market |
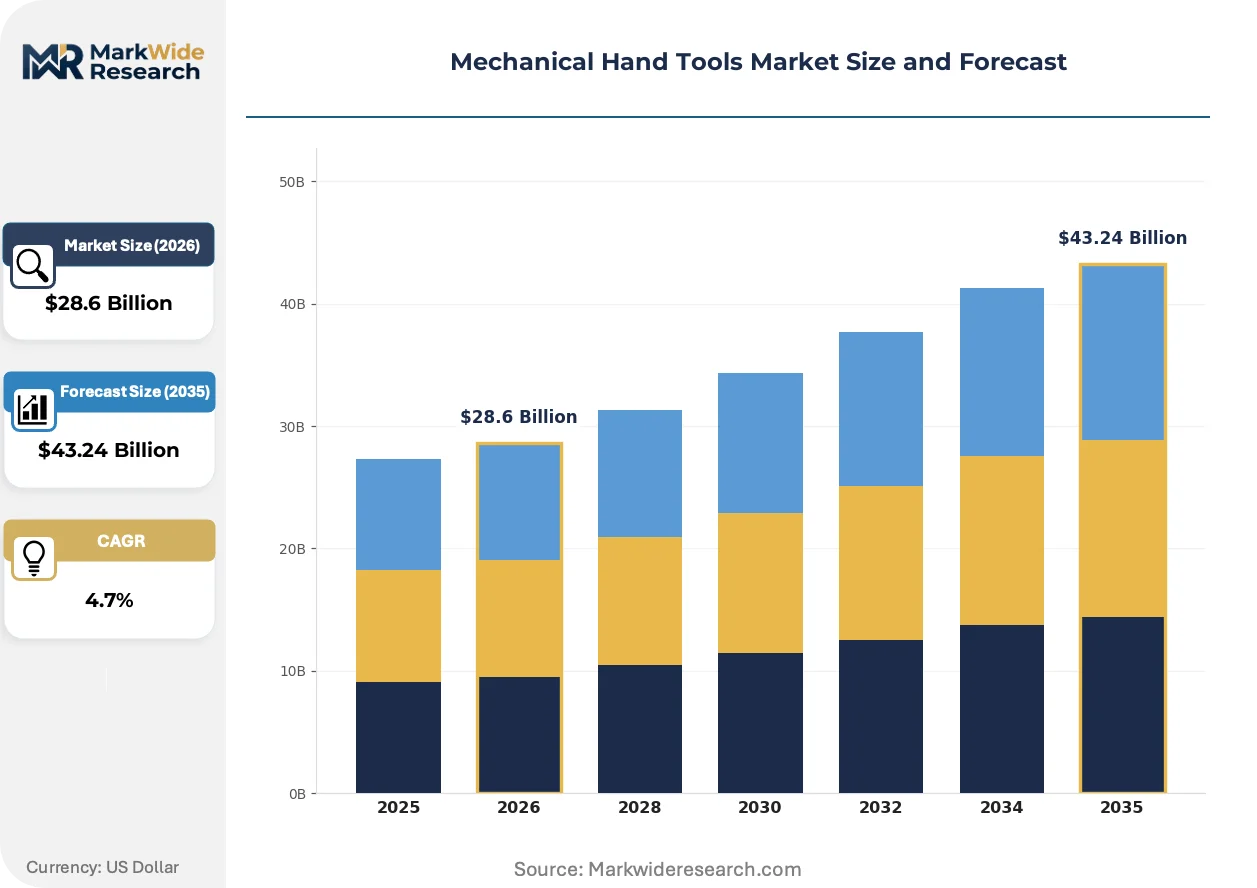
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrenches, Pliers, Sockets, Screwdrivers End User: Construction, Automotive, HVAC, Electrical Material: Steel, Aluminum, Titanium, Composite Application: Repair, Maintenance, Assembly, Fabrication |
| Companies Covered | Apex Tool Group LLC, Makita Corporation, Stanley Black & Decker Inc., Emerson Electric Co., Atlas Copco AB, Snap-On Incorporated, Techtronic Industries Co. Ltd., Matco Tools, The Bosch Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Hand Tools Market Strategic Shifts
Titanium and composite material systems are actively compressing traditional steel-dominated product hierarchies as weight reduction becomes a specified procurement criterion rather than a secondary preference.
Titanium alloy hand tools with density 40% below chrome-vanadium steel are supplanting conventional forged wrenches in repetitive assembly environments where operator fatigue drives injury rates and throughput variance. Automotive OEMs in Germany and Japan are specifying titanium torque instruments for final assembly lines. The shift is compressing mid-grade steel product margins while expanding certified lightweight tool rental pools.
REACH F-Gas Directive restrictions on hexavalent chromium plating are forcing manufacturers to adopt trivalent chrome and ceramic-based alternatives for corrosion resistance. Surface treatment reformulation adds 8-12% to finishing costs but unlocks EU market access. Aerospace maintenance contracts with EU-registered operators are the first segment requiring documented chrome-free coating certificates.
Professional technicians are consolidating purchases through integrated supplier contracts that bundle hand tools, calibration services, and digital inventory tracking. Independent mobile tool distributors are losing share to platform-based procurement systems at multi-location fleet operators. The concentration is most visible in US commercial trucking and municipal vehicle maintenance networks where procurement standardization reduces audit complexity.
Mechanical Hand Tools Market Segmentation
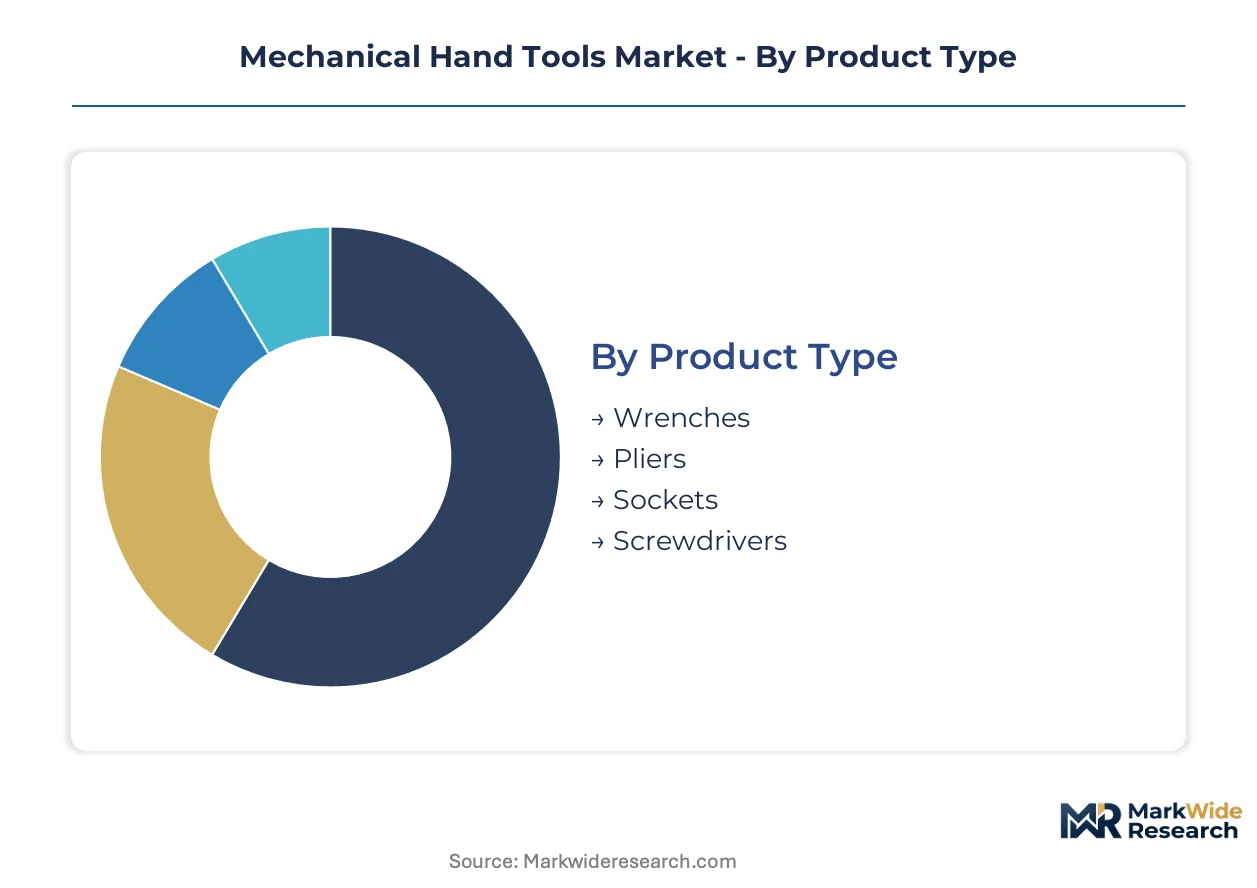
Mechanical hand tools segment along four intersecting dimensions that determine procurement patterns, margin structures, and regulatory exposure. Product type and material composition anchor technical specifications, while end user and application dictate channel strategy and replacement cycles.
Product Type:
German and Japanese manufacturers dominate export-led premium segments, while domestic-focused producers in India and Vietnam concentrate on standardized wrenches and screwdrivers for regional construction markets.
- Wrenches:Open-end, box-end, and adjustable configurations forged from chrome-vanadium or titanium alloys serve torque-critical fastening operations. Automotive OEM assembly lines in Stuttgart and Toyota City specify calibrated wrench sets for final tightening sequences where torque variance voids warranty coverage.
- Pliers:Lineman's, needle-nose, and locking variants with induction-hardened jaws grip, bend, and cut wire in confined electrical compartments. German industrial distributors stock certified plier inventories for REACH-compliant maintenance contracts in chemical processing facilities.
- Sockets:Six-point and twelve-point drive configurations mate with ratchet handles for repetitive bolt cycling. Construction fleets in Texas and Florida standardize on impact-rated socket sets for infrastructure steel erection.
- Screwdrivers:Phillips, slotted, and Torx tip profiles with acetate or composite handles transmit manual torque to threaded fasteners. Electronics assemblers in Shenzhen and Penang specify ESD-safe screwdriver kits for circuit board work.
Wrenches hold the largest share; momentum sits with sockets as cordless impact driver compatibility becomes a specified procurement criterion.
End User:
Cost tier stratification separates certified-grade procurement in automotive and aerospace from price-sensitive construction purchasing.
- Construction:Framing crews and concrete formwork teams consume high-volume, replaceable hand tool inventories where theft and jobsite loss accelerate turnover. Residential builders in US Sun Belt states favor multi-tool sets from big-box retailers over specialized distributor relationships.
- Automotive:OEM assembly plants and franchised dealerships specify torque-calibrated instruments with ISO 6789 traceability for warranty compliance. EV battery pack assembly in Nevada and South Carolina is driving demand for insulated hand tools rated to 1000V.
- HVAC:Refrigeration technicians and ductwork installers manipulate sheet metal and copper tubing with dedicated crimpers, swaging tools, and tube cutters. EPA Section 608 certification requirements shape tool procurement for refrigerant handling operations.
- Electrical:Lineworkers and panel builders require insulated tools rated to IEC 60900 standards for energized circuit work. Utility cooperatives in the Midwest consolidate purchases through GSA-schedule distributors.
Automotive commands premium pricing tiers; HVAC is expanding most quickly as heat pump retrofits accelerate across North American and European housing stock.
Material:
Volume concentration in steel contrasts with margin expansion in lightweight alloys targeting repetitive-motion injury reduction.
- Steel:Chrome-vanadium and chrome-molybdenum alloys heat-treated to 40-60 HRC deliver strength-to-cost ratios that dominate general-purpose applications. Chinese forging clusters supply hammer-forged blanks to mid-tier assemblers worldwide.
- Titanium:Ti-6Al-4V alloy tools at 40% lower density than steel reduce operator fatigue in aircraft assembly and high-repetition manufacturing cells. Boeing and Airbus maintenance manuals now specify titanium torque instruments for certain fastener categories.
- Aluminum:Cast and forged aluminum handles with steel inserts provide intermediate weight reduction for non-torque-critical applications. Plumbing and irrigation contractors favor aluminum pipe wrenches for overhead work.
- Composite:Carbon fiber reinforced polymer handles paired with alloy steel heads dampen vibration transmission in impact applications. Offshore wind turbine technicians specify composite-handled tools for nacelle maintenance in corrosive salt-air environments.
Steel retains volume leadership; titanium claims the steepest expansion trajectory as ergonomic specifications harden into procurement mandates.
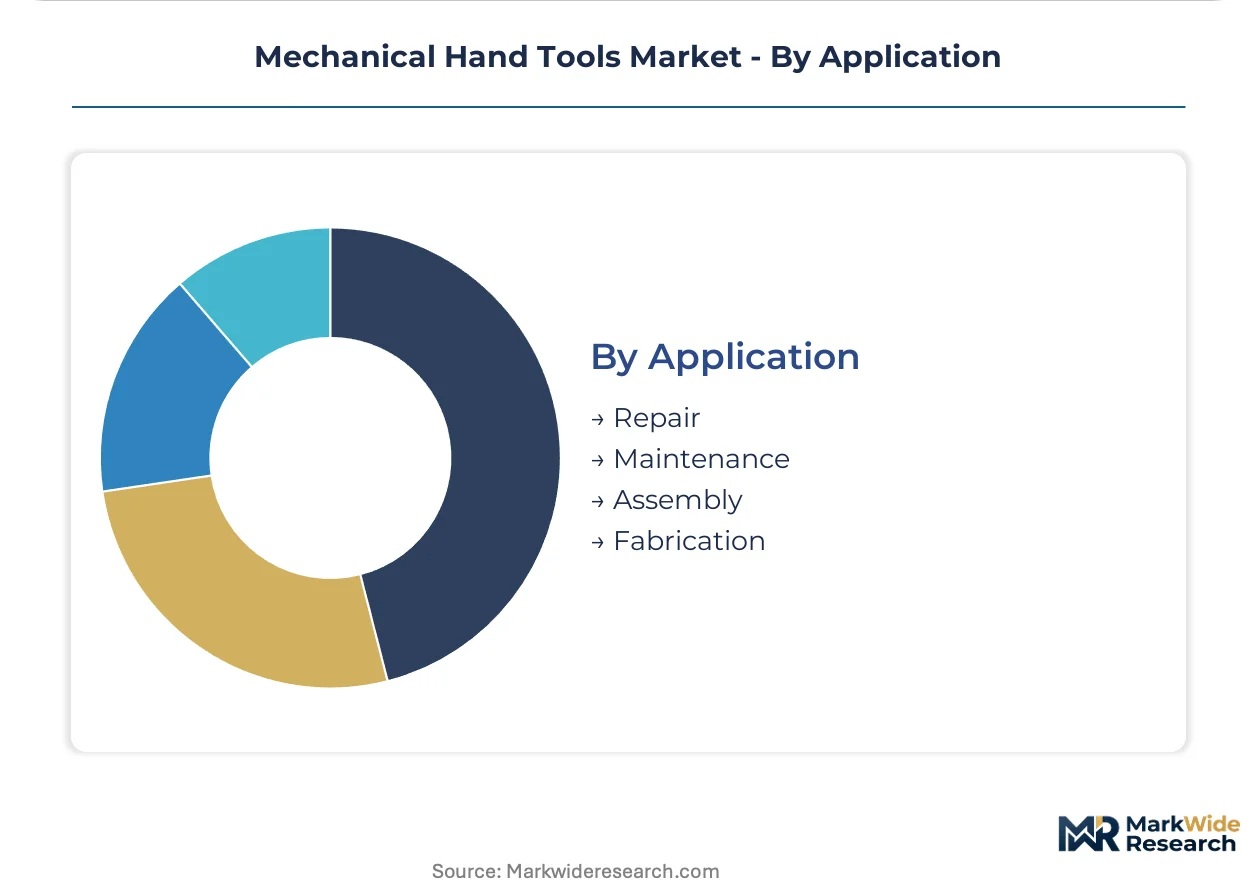
Application:
Customer type divides between downtime-critical repair operations and planned maintenance with scheduled tool access.
- Repair:Unscheduled breakdown response demands tool reliability where failure extends equipment outage costs. Mining operations in Western Australia and Chile maintain redundant certified tool inventories for 24-hour repair readiness.
- Maintenance:Periodic inspection and component replacement follow predetermined schedules with tool pre-positioning. Commercial aviation MRO facilities in Singapore and Frankfurt rotate calibrated torque sets through metrology labs on fixed cycles.
- Assembly:Production line fastening requires ergonomic tools matched to takt time and operator anthropometry. German automotive final assembly specifies color-coded tool shadow boards to prevent foreign object debris.
- Fabrication:Metalworking shops combine cutting, bending, and joining operations with general-purpose tool sets. Job shops in India's Coimbatore and Rajkot clusters serve domestic agricultural equipment manufacturers.
Repair captures durable margin pools; assembly is gaining share fastest as reshoring initiatives expand domestic manufacturing footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tool exports flow primarily into automotive assembly plants across Eastern Europe and North America, establishing a trade corridor that shapes procurement standards in destination markets.
United States
Commercial vehicle fleet operators and independent repair shops drive certified-grade tool demand as vehicle electrification mandates technician upskilling. OSHA inspection protocols enforce replacement cycles that sustain aftermarket volume. Tool distribution concentrates in Michigan's automotive corridor and Texas energy infrastructure zones where maintenance operations require calibrated torque instruments.
Germany
Precision assembly operations in Baden-Württemberg and Bavaria anchor premium hand tool consumption for automotive OEM supply chains. EU Green Deal REACH compliance mandates chrome-free plating reformulation across supplier networks. Stuttgart's industrial cluster hosts metrology laboratories certifying torque tools to ISO 6789 standards for export-qualified manufacturing.
China
Domestic construction activity and export-oriented forging capacity sustain hammer-forged blank production for mid-tier assemblers worldwide. MIIT industrial standards and GB certification requirements shape product specifications for domestic circulation. Zhejiang and Jiangsu provinces concentrate forging clusters supplying alloy steel tool components to global distributors.
India
PLI scheme incentives for capital goods manufacturing attract forging and finishing facility investments in Gujarat and Tamil Nadu industrial zones. BIS standards enforcement creates compliance thresholds for organized sector procurement. Coimbatore and Rajkot clusters serve agricultural equipment manufacturers with fabrication-grade tool sets adapted to domestic maintenance practices.
Japan
Aerospace maintenance contracts and automotive final assembly specify titanium torque instruments for repetitive fastening operations. METI-enforced JIS standards create non-tariff barriers for imported precision tools seeking market entry. Toyota City and Nagoya industrial zones maintain certified tool inventories aligned to OEM warranty compliance protocols.
Mechanical Hand Tools Market Competitive Environment
Listed leaders compete with private specialists across distribution model differentiation, creating a tiered structure where scale advantages clash with service proximity. Publicly traded entities leverage multi-channel reach and brand recognition, while private operators dominate mobile van networks and regional industrial distributor relationships. Three archetypes define competitive positioning: diversified conglomerates with tool divisions, pure-play professional tool specialists, and industrial equipment manufacturers with hand tool adjacencies. Consolidation through bolt-on acquisitions and captive forging capacity expansion represent the dominant competitive moves reshaping supplier tiers.
Within the diversified conglomerate tier, Stanley Black & Decker Inc. and Emerson Electric Co. exemplify scale-driven positioning across consumer and professional segments. Apex Tool Group LLC and Snap-On Incorporated occupy specialized positions anchored in industrial-grade certification and direct-to-bay service models respectively. Techtronic Industries Co. Ltd. represents the Asia-Pacific manufacturing base archetype, leveraging production scale for global private-label and branded distribution.
| Leading Market Players |
|---|
| Apex Tool Group LLC |
| Makita Corporation |
| Stanley Black & Decker Inc. |
| Emerson Electric Co. |
| Atlas Copco AB |
| Snap-On Incorporated |
| Techtronic Industries Co. Ltd. |
| Matco Tools |
| The Bosch Limited |
| Others |
Value Chain & Pricing Dynamics
Recycled steel alloys displacing virgin chrome-vanadium feedstock simultaneously redraws forging geography toward EU-compliant foundries and compresses margin structures for legacy electroplating operations. This substitution dynamic concentrates pricing power with certified-grade producers while forcing mid-tier assemblers toward volume-driven contract manufacturing.
Pricing Analysis
Steel-generation pricing gaps separate legacy chrome-vanadium instruments from REACH-compliant trivalent chrome alternatives and emerging titanium alloy premium tiers. Pricing stratifies across premium certified-grade, standard industrial, and economy replacement tiers, with differentiation anchored in ISO 6789 calibration traceability and chrome-free coating certificates. Cost compression in economy-tier forged blanks intensifies because Chinese forging clusters compete on undifferentiated hammer-forged output. Fleet procurement managers at multi-location operators exhibit lowest price sensitivity due to bundled calibration and digital tracking requirements, while residential construction crews remain most sensitive to upfront unit cost.
Supply Chain Analysis
China, Germany, and India anchor global forging capacity, with Zhejiang and Jiangsu provinces supplying hammer-forged blanks, Stuttgart's industrial corridor hosting precision finishing operations, and Gujarat emerging under PLI scheme incentives. The supply chain draws from nickel and chromium ore inputs, alloy steel billets, and ceramic-based coating chemistries. Single-source vulnerability concentrates in Chinese hammer-forged blank production for mid-tier assemblers lacking captive foundry operations. Distribution runs through mobile van networks for professional automotive workshops, industrial distributors for OEM supply chains, and big-box retail for construction end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs procurement consolidation as integrated supplier contracts bundle hand tools, calibration services, and digital inventory tracking into unified subscription structures. This interoperability shift rewards ecosystem orchestrators over standalone product vendors.
For Market Incumbents: Compound channel control through captive metrology laboratory investments that shorten ISO 6789 certification turnaround windows. Deepen backward integration into recycled steel alloy forging to secure REACH-compliant feedstock against raw material volatility. Mobile van distribution networks face erosion from platform-based procurement systems at multi-location fleet operators.
For New Entrants and Emerging Players: Lead with composite material specialization targeting aerospace maintenance contracts where titanium and carbon fiber specifications are displacing steel-only procurement mandates. India's PLI scheme zones in Gujarat and Tamil Nadu offer the most penetrable geography for forging and finishing facility establishment. Pursue direct qualification with German automotive OEM supply chains as the decisive go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive forging capacity and certified metrology infrastructure. Long-term viability favors suppliers positioned at the intersection of lightweight material innovation and regulatory compliance automation. Watch for inflection signals in chrome-free coating certificate adoption rates among EU-registered aerospace operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Capacity Expansion | Backward integration into recycled steel alloy production secures REACH-compliant feedstock against Chinese supply concentration. |
| Metrology Laboratory Acquisition | In-house ISO 6789 certification capability compresses turnaround windows for torque instrument recalibration services. |
| Composite Material R&D Partnership | Carbon fiber and titanium alloy development unlocks aerospace maintenance contracts with stringent weight specifications. |
| Platform-Based Procurement Integration | Digital inventory tracking bundles hand tools with calibration services for multi-location fleet operator contracts. |
| PLI Scheme Facility Establishment | Production-linked incentives in Gujarat and Tamil Nadu reduce landed cost for export-oriented forging operations. |
Study Parameters
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads and secondary sources including customs trade data, SEC filings, industry association reports, and production databases anchors the qualitative findings. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down supply-side capacity assessments across forging clusters and finishing operations.
Sensitivity analysis around alloy steel price volatility, REACH compliance timeline delays, and power tool substitution rates stress-tests base case projections across the modeling period. The analytical framework segments by product type, material composition, end user industry, and application mode, with CAGRs derived from regression analysis against industrial production indices and automotive assembly volumes. Forecast inputs incorporate vehicle electrification penetration curves and aviation fleet expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained OEM assembly reshoring, stable nickel-chromium input costs, or unaltered REACH enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding technician certification requirements and coating reformulation validation cycles. Recalibration cycles align with material shifts in EU carbon-border adjustment mechanisms and aviation maintenance contract award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Yard Scraper Market
Tools
Auger Drill Bits Market
Tools
Europe Power Tools Market
Tools
Indexable Inserts Market
Tools
Tool Pliers Market
Tools
China Power Tools and Hand Tools Market
Tools
Spindle Shaper Market
Tools
Portable Tools Market
Tools
Power Drill Market
Tools
Diamond Hole Saw Market
Tools
Nail Gun Market
Tools
Screwdriver Market
Tools
Europe Woodworking Power Tools Market
Tools
Wood-Sanding Machine Market
Tools
Metal Forming Tools Market
Tools
Fixed Cutter Bits Market