
 Canada Food Acidulants Market | 2026-2036
Canada Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Acidulants Market Outlook
Modular acidulant blending is hardening as a preferred procurement model among mid-sized Canadian food processors. Cargill Inc leverages its Prairie grain-processing infrastructure to anchor domestic citric acid supply chains. Jungbunzlauer Suisse AG competes through specialized fermentation-derived acidulant portfolios tailored to clean-label specifications. Bartek Ingredients Inc dominates crystalline malic acid niches for confectionery applications in southern Ontario manufacturing corridors.
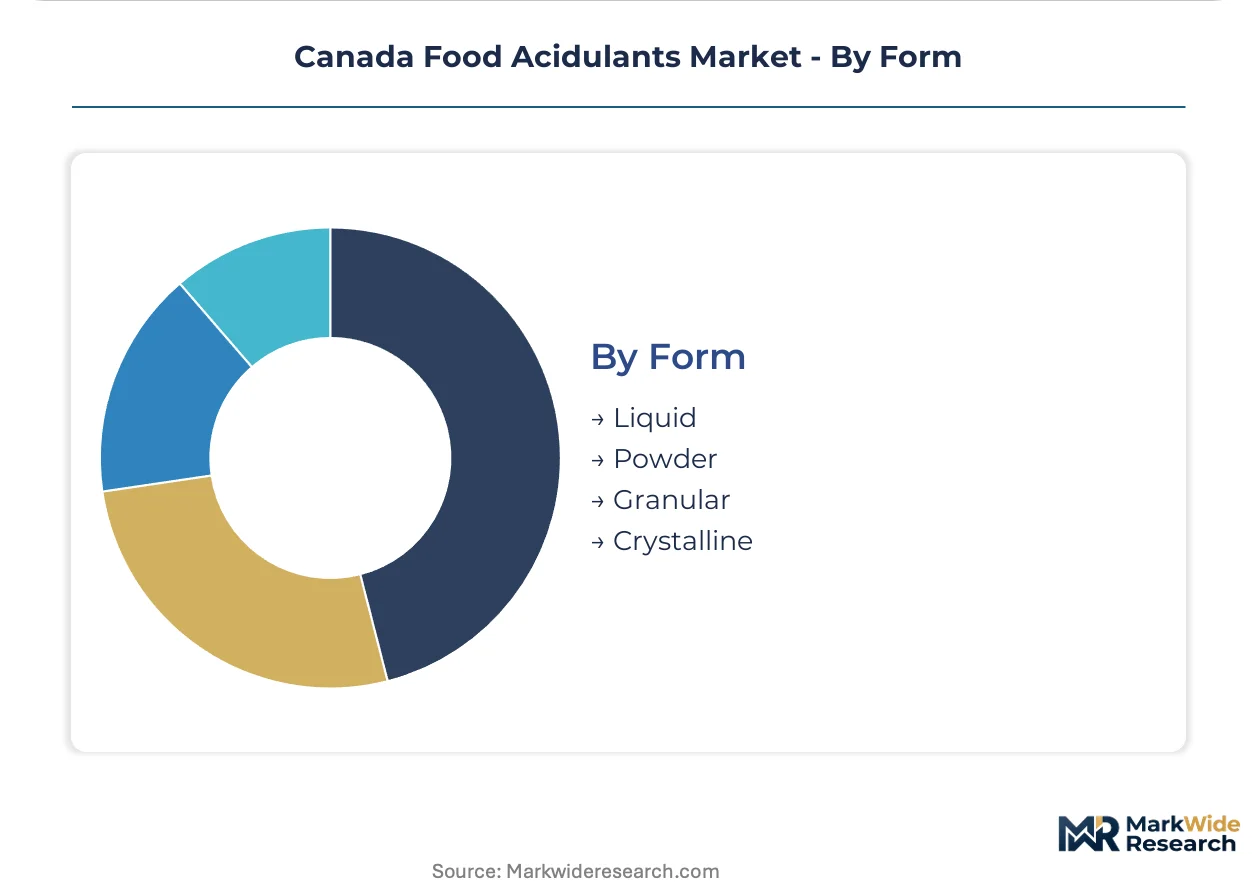
Canada food acidulants comprise organic acids and their salts, typically manufactured through fermentation of carbohydrate substrates or chemical synthesis, with purity grades ranging from food-grade to pharmaceutical-grade specifications; these compounds primarily lower pH, enhance flavor profiles, inhibit microbial spoilage, and stabilize color in processed foods. Citric acid occupies the largest volume share among product types due to its versatility across beverage and dairy matrices, while lactic acid registers the fastest structural growth driven by fermented plant-protein expansion. Powder and granular forms command premium positioning in bakery and confectionery end users where precise dosing and extended shelf stability determine procurement decisions.
Health Canada enforces acidulant safety and labeling through the Food and Drugs Act and the Food and Drugs Regulations, with the Canadian Food Inspection Agency conducting compliance verification for imported acidulant shipments at ports of entry. The Safe Food for Canadians Regulations impose preventive control requirements on acidulant handlers, elevating documentation burdens for cross-border suppliers. Stakeholders must monitor evolving maximum permitted levels for tartaric acid in infant formulations and anticipate potential alignment with Codex Alimentarius revisions on acidulant additive categories.
Market Dynamics
Clean-label disclosure mandates from Health Canada are compressing formulation cycles for Ontario and Quebec beverage processors, forcing acidulant buyers to validate supply chain documentation against tightening Food and Drugs Regulations additive transparency requirements.
Growth Catalysts
- Fermentation-Derived Lactic Acid:Plant-based dairy alternatives in Toronto and Montreal manufacturing corridors require pH regulation without synthetic buffers, pulling demand for bio-based acidulant portfolios.
- Health Canada Labeling Rules:Tightened disclosure requirements under the Food and Drugs Regulations compel processors to source acidulants with verifiable non-GMO carbohydrate feedstock documentation.
- Quebec Confectionery Cluster:Crystalline malic acid demand concentrates in southern Ontario where precision-dosing bakery operations require extended shelf-stable powder formats.
Market Restraints
- Feedstock Volatility:Prairie grain price swings directly compress margins for domestic citric acid fermentation operations dependent on local corn and wheat starch supplies.
- Import Concentration Risk:Cross-border acidulant shipments face Canadian Food Inspection Agency port inspections that extend lead times for US and European suppliers.
- Technical Limitation:Tartaric acid substitution in infant formulations encounters maximum permitted level caps under evolving Health Canada guidelines.
Strategic Opportunities
- Western Canada Expansion:Alberta and British Columbia plant-protein processing facilities remain underpenetrated for localized acidulant blending services.
- Modular Blending Services:Mid-sized processors across the Prairie provinces seek on-site acidulant formulation partnerships to reduce inventory carrying costs.
- Safe Food for Canadians Alignment:Preventive control documentation requirements create first-mover advantage for suppliers with integrated traceability systems.
Industry Challenges
- Fermentation Specialist Shortage:Bio-based acidulant production requires microbial strain optimization expertise scarce in Canadian food technology programs.
- Legacy System Integration:ERP upgrades for acidulant lot-tracking compliance impose capital burdens on family-owned Ontario processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Acidulants Market |
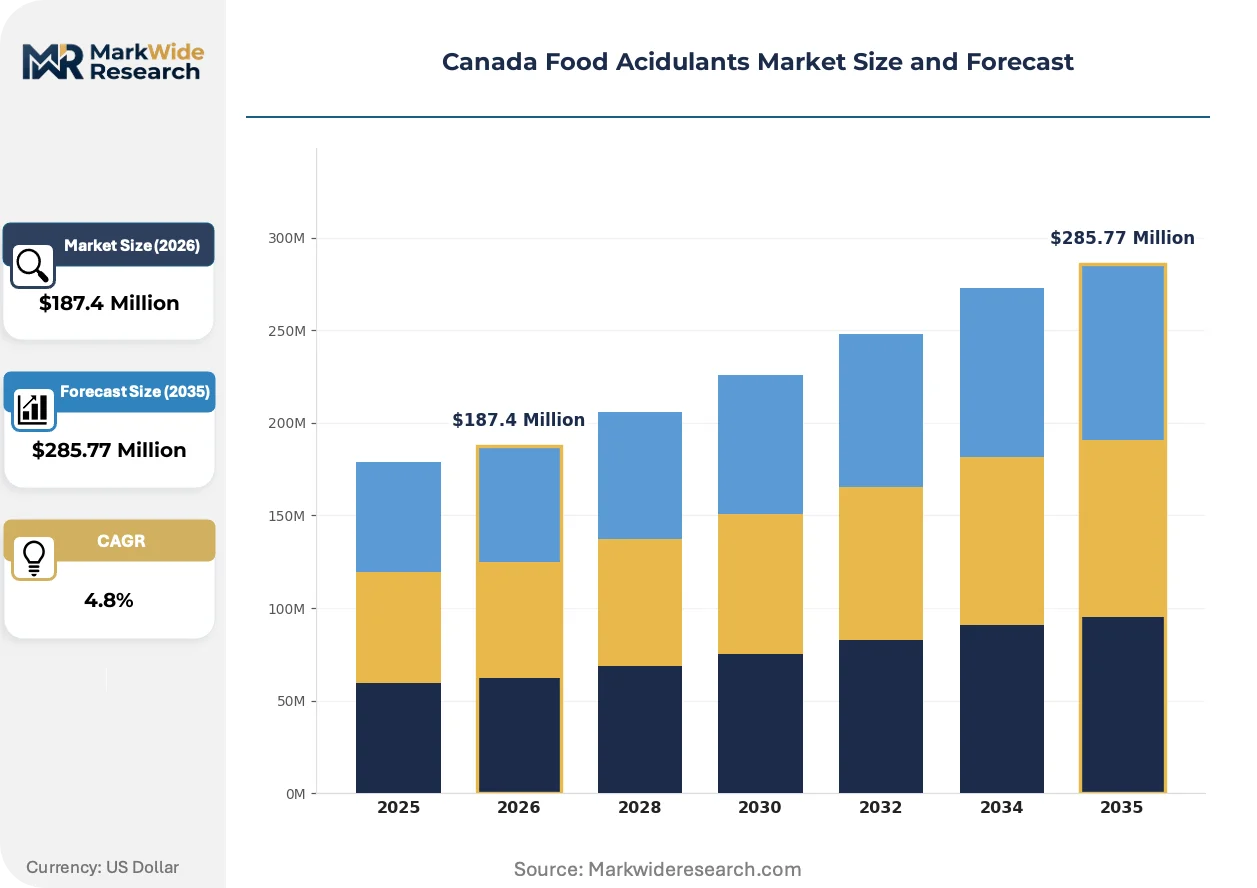
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Acetic Acid, Tartaric Acid End User: Confectionery, Dairy, Beverages, Bakery Application: Preservation, Flavoring, pH Regulation, Nutritional Enhancement Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Archer Daniels Midland Company, Brenntag North America Inc, Cargill Inc, Jungbunzlauer Suisse AG, Corbion N.V., Bartek Ingredients Inc, Tate & Lyle plc, Merko Group LL, Brenntag Canada Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Acidulants Market Strategic Shifts
Acidulant procurement patterns across Canadian food manufacturing are pivoting toward integrated formulation services that compress R&D timelines and embed regulatory compliance directly into supplier relationships.
Precision fermentation platforms are unifying carbohydrate-to-acid conversion pathways, enabling single-step production of custom acidulant salt blends. Clean-label beverage formulators in Toronto adopt these platforms at pilot scale. The technology is unifying what previously required separate citric, malic, and lactic acid procurement contracts into consolidated supply agreements.
Health Canada's Safe Food for Canadians Regulations now mandate preventive control plans for all acidulant handlers, elevating documentation burdens for importers. Domestic suppliers with integrated lot-tracking systems capture volume from cross-border competitors. Ontario dairy-alternative processors respond by qualifying local fermentation-derived acidulant sources ahead of enforcement phase-ins.
Acidulant buyers in Quebec and Ontario are consolidating supplier relationships around full-service formulation partnerships. Mid-sized confectionery manufacturers abandon spot-market purchasing for annual blending contracts with embedded technical support. This pattern is most visible in southern Ontario manufacturing corridors where precise pH control determines product consistency.
Canada Food Acidulants Market Segmentation
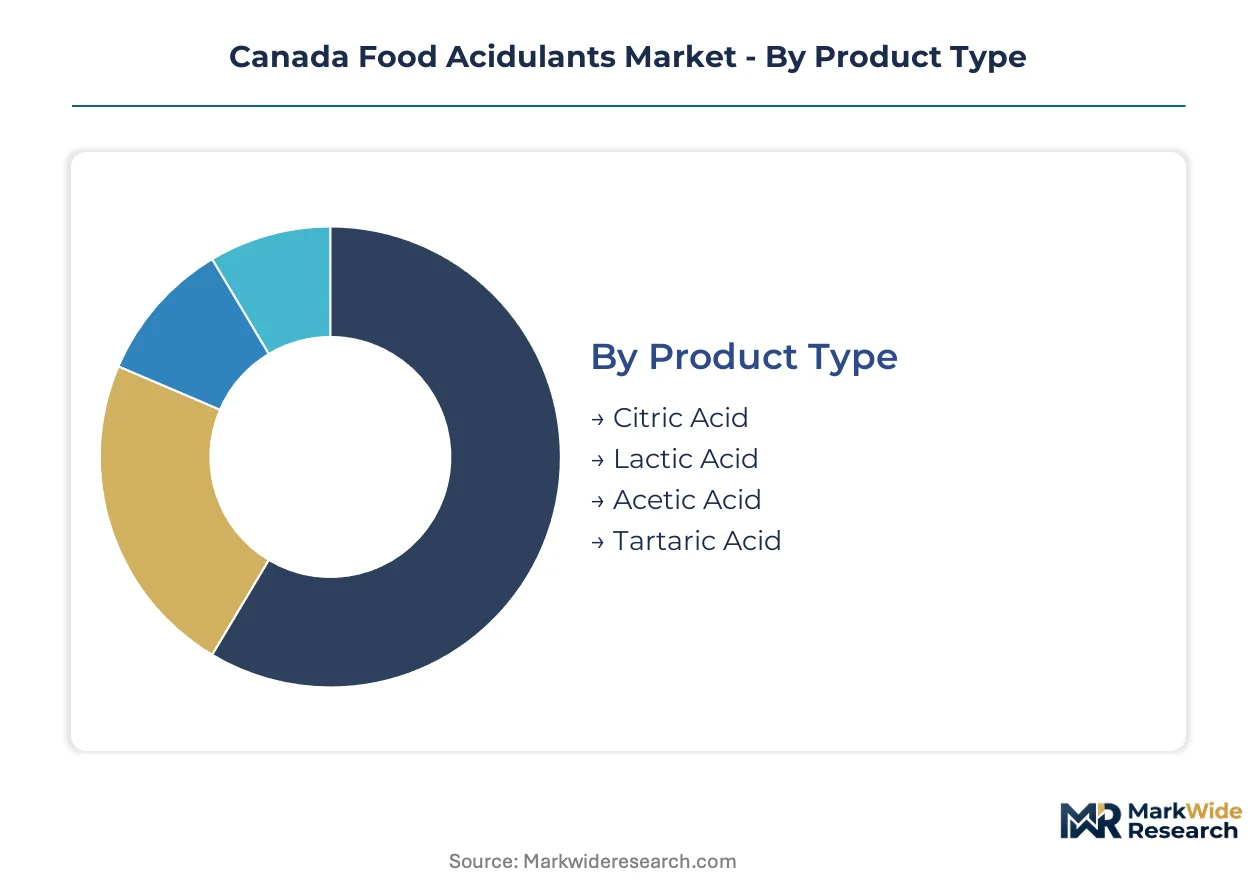
Acidulant procurement across Canadian food manufacturing fragments along functional, application, and physical dimensions. Each segmentation axis carries distinct supply chain implications for Ontario and Quebec processors navigating Health Canada's tightening additive disclosure mandates.
Product Type:
Supply concentration for fermentation-derived acidulants centers on Prairie grain-processing infrastructure, with carbohydrate feedstock proximity determining domestic production economics.
- Citric Acid:Manufactured through Aspergillus niger fermentation of corn or wheat starch, this tricarboxylic acid delivers versatile pH reduction across beverage and dairy matrices. Demand concentrates in Toronto-area beverage processors seeking clean-label alternatives to synthetic buffers under tightened Food and Drugs Regulations disclosure rules.
- Lactic Acid:Produced via Lactobacillus fermentation of carbohydrate substrates, this alpha-hydroxy acid enables precise pH modulation in plant-based dairy alternatives. Montreal and Toronto manufacturing corridors pull bio-based volumes as fermented protein processors abandon synthetic buffering systems.
- Acetic Acid:Derived from bacterial oxidation of ethanol, this monocarboxylic acid serves preservation applications in condiment and pickle manufacturing.
- Tartaric Acid:Naturally occurring in grapes, this dicarboxylic acid faces maximum permitted level constraints in infant formulations under evolving Health Canada guidelines.
Today's leader: Citric acid. Tomorrow's challenger: Lactic acid.
End User:
Cost tier differentiation separates precision-dosing confectionery operations from bulk liquid acidulant users in beverage processing.
- Confectionery:Crystalline malic acid demand concentrates in southern Ontario manufacturing corridors where precise dosing determines product consistency. Extended shelf-stable powder formats command premium positioning for hard candy and sour confection applications.
- Beverages:pH regulation requirements for clean-label carbonated and still drinks drive fermentation-derived acidulant qualification in Toronto and Montreal facilities. Health Canada labeling mandates compress formulation cycles, forcing validation of non-GMO carbohydrate feedstock documentation.
- Dairy:Plant-based dairy alternatives require acidulant blends that displace synthetic buffers without compromising protein stability.
- Bakery:Powder and granular acidulants enable precise leavening control in chemically leavened products.
Confectionery commands premium pricing. Beverages drive volume expansion.
Application:
Volume concentration aligns with pH regulation functionality, where precise acidity control underpins multiple secondary performance attributes.
- pH Regulation:Primary functional driver across dairy alternatives and beverages, where tartaric and lactic acid blends displace synthetic buffering systems. Toronto plant-protein processors prioritize bio-based acidulants with verifiable fermentation documentation.
- Preservation:Antimicrobial acidification extends shelf life in processed foods through pH reduction and undissociated organic acid activity.
- Flavoring:Tartness enhancement and flavor profile modification in confectionery and beverage applications.
- Nutritional Enhancement:Mineral absorption facilitation and metabolic pathway support in fortified food matrices.
pH regulation anchors current procurement. Preservation applications gain regulatory attention.
Form:
Customer type segmentation separates bulk liquid users from precision-dosing powder and crystalline buyers with distinct inventory and handling requirements.
- Powder:Extended shelf stability and precise dosing capability position this format for bakery and confectionery end users. Southern Ontario manufacturing corridors favor powder acidulants where humidity-controlled storage infrastructure supports inventory management.
- Granular:Intermediate flow properties enable automated dosing systems in mid-scale processing operations.
- Liquid:Bulk tanker delivery reduces handling costs for high-volume beverage processors with integrated storage infrastructure.
- Crystalline:Highest purity grade serves pharmaceutical-adjacent food applications and premium confectionery segments.
Powder dominates bakery and confectionery procurement. Liquid captures beverage volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acidulant manufacturing in Canada traces its scale to Prairie grain-processing infrastructure established in the 1970s, when fermentation-based citric acid production first leveraged domestic corn and wheat starch supplies. Health Canada's evolving Food and Drugs Regulations now reshape procurement geography across provincial manufacturing corridors.
Ontario
Toronto-area beverage processors drive fermentation-derived acidulant demand as plant-based dairy alternatives displace synthetic buffers. Health Canada's tightened additive disclosure rules compress formulation validation cycles for clean-label products. The southern Ontario manufacturing corridor concentrates crystalline malic acid procurement for precision-dosing confectionery operations.
Quebec
Montreal's fermented protein processing facilities pull bio-based lactic acid volumes for pH regulation in dairy alternatives. The Safe Food for Canadians Regulations impose preventive control documentation burdens that favor domestic suppliers with integrated traceability. Quebec's food technology cluster accelerates acidulant blending service partnerships among mid-sized processors.
Alberta
Calgary and Edmonton plant-protein processing facilities remain underpenetrated for localized acidulant blending services. Prairie grain price volatility directly compresses margins for citric acid fermentation operations dependent on local feedstock. The province's emerging alternative protein sector creates demand for modular on-site acidulant formulation partnerships.
British Columbia
Vancouver's clean-label beverage startups qualify fermentation-derived acidulants with verifiable non-GMO carbohydrate documentation. Health Canada port inspections at Vancouver and Prince Rupert extend lead times for cross-border acidulant shipments. The province's specialty food manufacturing base favors powder and granular acidulant formats for humidity-controlled storage infrastructure.
Prairie Provinces
Saskatchewan and Manitoba corn and wheat starch supplies anchor domestic citric acid fermentation economics. The Canadian Food Inspection Agency's compliance verification for imported acidulant shipments elevates procurement preference for Prairie-based production. Regional mid-sized processors seek inventory cost reduction through on-site acidulant blending partnerships.
Canada Food Acidulants Market Competitive Environment
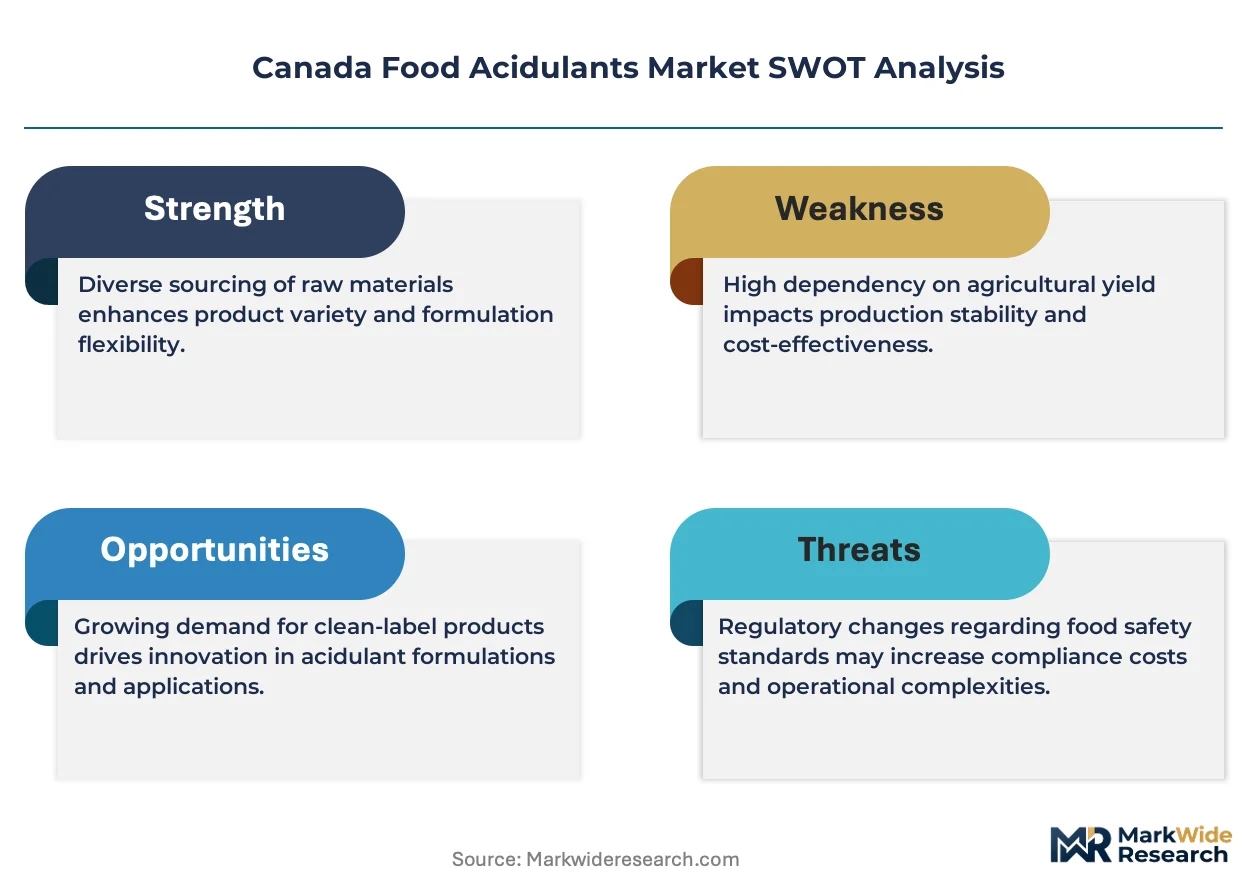
The competitive structure tilts toward integrated fermentation specialists with captive carbohydrate feedstock access. Domestic players leverage Prairie grain-processing proximity against European and US importers facing extended port inspection timelines. Three archetypes dominate: fermentation-scale operators with upstream grain assets, specialized crystalline acidulant producers, and modular blending service providers. Capacity expansion and strategic formulation partnerships constitute the primary competitive vectors as Health Canada's disclosure mandates compress R&D cycles.
Among North American integrated processors, Cargill Inc anchors the fermentation-scale tier through Prairie infrastructure control. Jungbunzlauer Suisse AG occupies the specialized fermentation-derived portfolio position with clean-label specifications. Bartek Ingredients Inc exemplifies the crystalline acidulant specialist archetype concentrated in southern Ontario manufacturing corridors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Brenntag North America Inc |
| Cargill Inc |
| Jungbunzlauer Suisse AG |
| Corbion N.V. |
| Bartek Ingredients Inc |
| Tate & Lyle plc |
| Merko Group LL |
| Brenntag Canada Inc |
| Others |
Value Chain & Pricing Dynamics
Prairie corn and wheat starch price indices cascade directly through Canadian citric acid fermentation economics, compressing margins for domestic producers while elevating procurement preference for crystalline malic acid and lactic acid tiers with cleaner feedstock documentation. Health Canada's tightening additive disclosure rules under the Food and Drugs Regulations force Ontario and Quebec processors to validate supply chain documentation against non-GMO carbohydrate sourcing, creating price stratification between verifiable fermentation-derived acidulants and commodity-grade imports.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade crystalline, food-grade powder, and bulk liquid economy levels separates precision-dosing confectionery buyers from high-volume beverage processors. Price differentiation hinges on certification grade against Health Canada purity specifications and volume scale of annual blending contracts. Cost compression in the bulk liquid tier intensifies because Prairie grain price volatility feeds directly into domestic citric acid fermentation margins. Mid-sized Ontario processors show highest price sensitivity due to capital constraints for ERP lot-tracking upgrades, while Quebec's fermented protein facilities prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale beverage demand in Toronto and Montreal, while distributor-mediated routes serve mid-sized Prairie confectionery operations with fragmented procurement patterns. Geographic supply concentration centers on Canada, the United States, and Switzerland, with Jungbunzlauer's fermentation-derived portfolios and Cargill's Prairie infrastructure anchoring domestic availability. Raw material dependencies draw from Prairie corn starch, European beet sugar, and imported fermentation cultures. Single-source vulnerability runs through Health Canada port inspection bottlenecks at Vancouver and Toronto, where cross-border shipments face extended Canadian Food Inspection Agency compliance verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada food acidulants market represents a late-cycle quality story as clean-label beverage formulators shift procurement toward fermentation-derived acidulants with verifiable non-GMO documentation. This specification premium rewards domestic suppliers with integrated traceability systems over commodity importers.
For Market Incumbents: Extend formulation partnership offerings to embed technical support and regulatory compliance directly into annual contracts, countering modular blending service entrants. Deepen Prairie grain-processing infrastructure control through backward integration into carbohydrate feedstock sourcing, insulating margins against commodity price swings. Prioritize certification investment for pharmaceutical-grade crystalline production to capture premium tier pricing in southern Ontario confectionery corridors. For New Entrants and Emerging Players: Precision fermentation platforms for custom acidulant salt blends offer technology-first entry into Toronto-area clean-label beverage pilot programs. Alberta and British Columbia plant-protein processing facilities present the most penetrable geography, with localized on-site blending partnerships as the optimal go-to-market angle. Target mid-sized Prairie processors seeking inventory cost reduction through embedded formulation services rather than spot-market procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with modular blending service providers possessing integrated lot-tracking systems aligned to Safe Food for Canadians Regulations preventive control mandates. The five-to-ten year viability window favors acquisition of fermentation-scale operators with captive Prairie grain assets over import-dependent distributors. Watch for Health Canada alignment with Codex Alimentarius revisions on acidulant additive categories as the signal for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Grain Supply | Cargill's existing infrastructure anchors domestic citric acid cost competitiveness against European imports. |
| Precision Fermentation Platform Deployment | Toronto clean-label beverage startups consolidate citric, malic, and lactic acid procurement into single-supplier agreements. |
| Modular Blending Service Expansion | Alberta plant-protein processors reduce inventory carrying costs through on-site acidulant formulation partnerships. |
| Pharmaceutical-Grade Certification Investment | Bartek's crystalline malic acid positioning captures premium pricing in southern Ontario confectionery manufacturing. |
| Integrated Traceability System Implementation | Domestic suppliers with lot-tracking capabilities capture volume from cross-border competitors facing extended port inspections. |
Study Parameters
Multiple input streams — primary interviews with fermentation plant managers, acidulant procurement leads at Ontario beverage processors, Health Canada regulatory affairs specialists, and Prairie grain supply coordinators — were reconciled against secondary validation from Canadian Food Inspection Agency compliance bulletins, Health Canada Food and Drugs Regulations amendments, and industry trade data. Bottom-up volume modeling across citric, lactic, malic, and tartaric acid product tiers was cross-checked against top-down market sizing derived from Prairie grain-processing capacity disclosures and cross-border import documentation.
Historical consumption patterns were cross-referenced against panel input from Quebec confectionery technical directors and Toronto plant-protein formulators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include acidulant product type, end-use application, physical form, and provincial manufacturing corridor. CAGRs were derived from elasticity-adjusted demand curves incorporating fermentation capacity expansion timelines and Health Canada enforcement phase-in schedules for preventive control documentation.
The model holds under stable Prairie grain supply conditions and continued Health Canada disclosure rule tightening; deviation in Codex Alimentarius alignment timelines or feedstock price volatility would shift volume trajectories between domestic fermentation and import-dependent tiers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Monk Fruit Ingredient Market