
 Olestra Market | 2026-2036
Olestra Market Size, Share, and Industry Trends Forecast 2026-2036
Olestra Market Analytics
Food manufacturer demand for fat replacement ingredients is hardening as reformulation targets intensify across processed food portfolios. Cargill Inc. leverages its global ingredient supply network to sustain olestra distribution reach into multiple food processing verticals. DuPont de Nemours Inc. anchors its position through deep R&D investment in specialty carbohydrate chemistry. Archer Daniels Midland Company competes on manufacturing scale, operating production assets that service bulk ingredient procurement from North American snack food producers.
Olestra is a sucrose polyester synthesized from sucrose and vegetable oil fatty acids, functioning as a non-caloric fat substitute that passes through the digestive tract unabsorbed due to its steric configuration blocking lipase enzyme action. The compound serves primary commercial purpose in reduced-calorie and reduced-fat food formulations where it replicates the mouthfeel and cooking performance of conventional triglycerides. Snack foods occupy the dominant application position among product type segments, while fat replacement leads application categories as food manufacturers pursue calorie reduction targets without sacrificing sensory attributes. Powdered and granular forms command attention from industrial buyers seeking precise dosing control in continuous manufacturing environments.
FDA oversight governs olestra labeling mandates and health claim restrictions in the United States, while EFSA evaluations shape market access conditions across European jurisdictions. The USDA and FSSAI additionally influence ingredient approval pathways and food safety standards in their respective territories. Stakeholders must monitor evolving regulatory postures toward fat substitute health claims and reformulation incentive programs that could redirect R&D investment priorities.
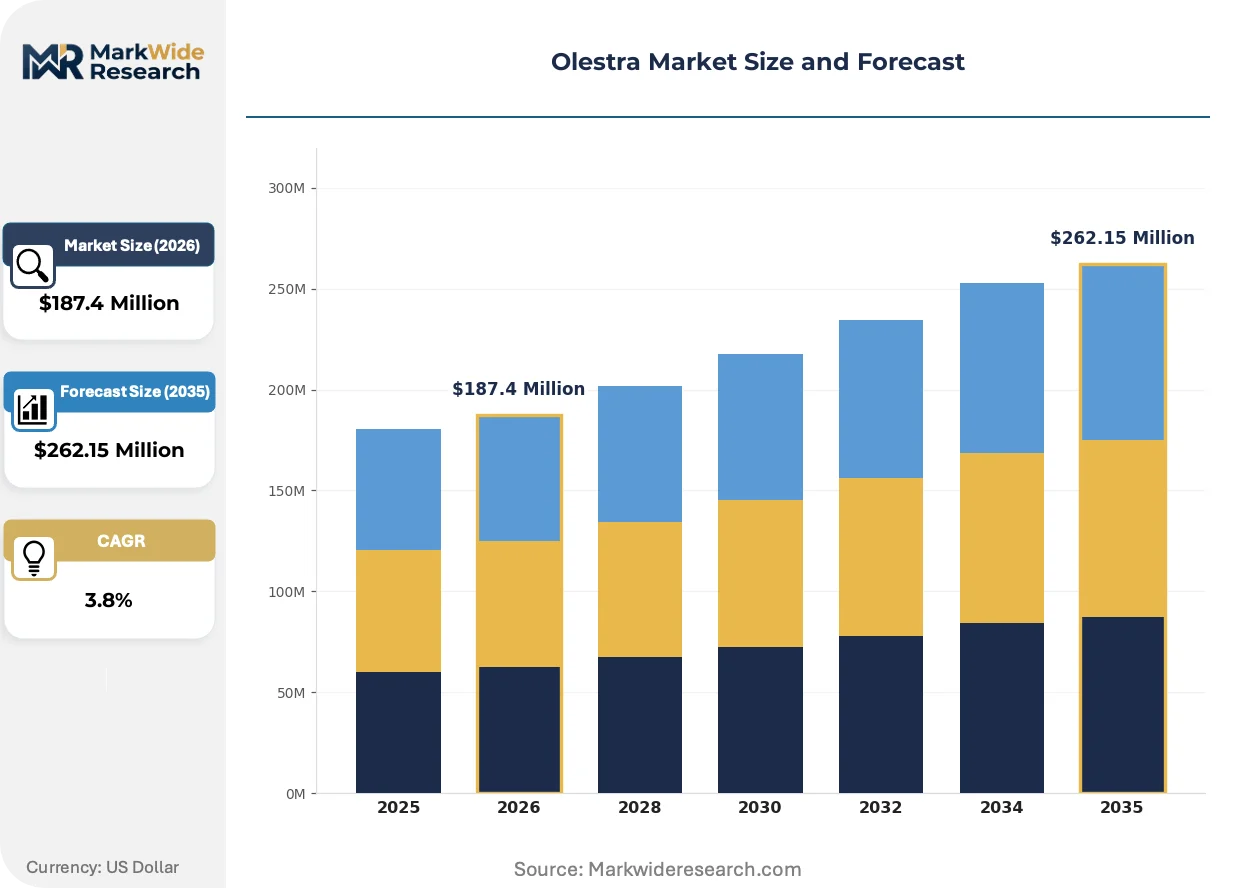
Market Dynamics
Calorie-reduction mandates from institutional foodservice buyers and retail chains are forcing snack manufacturers to reformulate at scale, converting olestra from a niche ingredient into a portfolio staple for processed food R&D teams.
Growth Catalysts
- US FDA labeling pathways:The agency's established framework for fat substitute health claims reduces regulatory uncertainty for reformulation projects, accelerating adoption timelines.
- Bakery segment expansion:Commercial bakers now specify olestra for reduced-fat pastries and bread products, extending application beyond traditional snack channels.
- Midwest manufacturing concentration:Corn belt processing infrastructure provides proximate feedstock access for sucrose polyester synthesis, lowering input logistics costs.
Market Restraints
- Sucrose feedstock volatility:Sugar commodity price swings directly compress olestra production margins, creating cost pass-through friction with food manufacturer contracts.
- Single-supplier concentration:Specialty esterification catalyst production centers on German chemical suppliers, exposing buyers to geopolitical supply interruption risk.
- Digestive tolerance ceiling:Individual consumer sensitivity to olestra's laxative effect at high intake levels caps permissible dosage in single-serve packaged foods.
Strategic Opportunities
- India FSSAI approval pathway:Pending regulatory clearance would unlock access to a processed snack market with expanding modern retail penetration.
- Plant-based meat analogues:Fat replacement in extruded protein products represents an emerging application where olestra's thermal stability differentiates against water-based alternatives.
- Direct-to-manufacturer digital platforms:Ingredient marketplaces bypass traditional distributor markups for mid-sized food producers seeking reformulation inputs.
Industry Challenges
- Lipid chemistry specialization gap:Food science programs produce fewer graduates with sucrose polyester formulation expertise than industry replacement demand requires.
- GRAS self-determination documentation:Manufacturers face escalating legal costs to defend generally recognized as safe status against litigation challenging olestra's digestive effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olestra Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Foods, Fried Foods, Desserts, Salad Dressings End User: Household Consumers, Food Manufacturers, Restaurants, Health Food Stores Form: Ready-to-Eat, Powdered, Liquid, Granular Application: Fat Replacement, Calorie Reduction, Ingredient Substitution, Texture Enhancement |
| Companies Covered | Cargill Inc., DuPont de Nemours Inc., FMC Corporation, Grain Processing Corporation, Archer Daniels Midland Company, Advanced Food Systems Inc., Ashland Inc., CP Kelco, Penford Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olestra Market Evolving Landscape
Reformulation science is advancing beyond simple fat replacement toward multi-functional ingredient systems that combine calorie reduction with texture optimization and clean-label positioning.
Microencapsulation technology is expanding into olestra delivery systems, enabling food manufacturers to mask the compound's characteristic mouthfeel while preserving its non-caloric properties in fried and baked applications. Snack producers in the United States are piloting these systems for next-generation potato chip lines. The technology is expanding into premium product tiers previously closed to fat substitutes due to sensory quality requirements.
EFSA's 2023 re-evaluation of sucrose polyester toxicology data is tightening purity specifications for European market entry, forcing suppliers to upgrade filtration and quality control infrastructure. French and German food safety authorities are aligning inspection protocols with the new standards. Bakery applications in Western Europe face the steepest compliance timeline pressure as reformulation deadlines approach.
Long-term supply agreements are displacing spot purchasing for olestra procurement, as food manufacturers seek price stability amid volatile sucrose markets. North American snack food conglomerates now contract directly with esterification facilities for multi-year volumes. This shift concentrates negotiation leverage among buyers with sufficient volume to justify dedicated production runs.
Olestra Market Segmentation
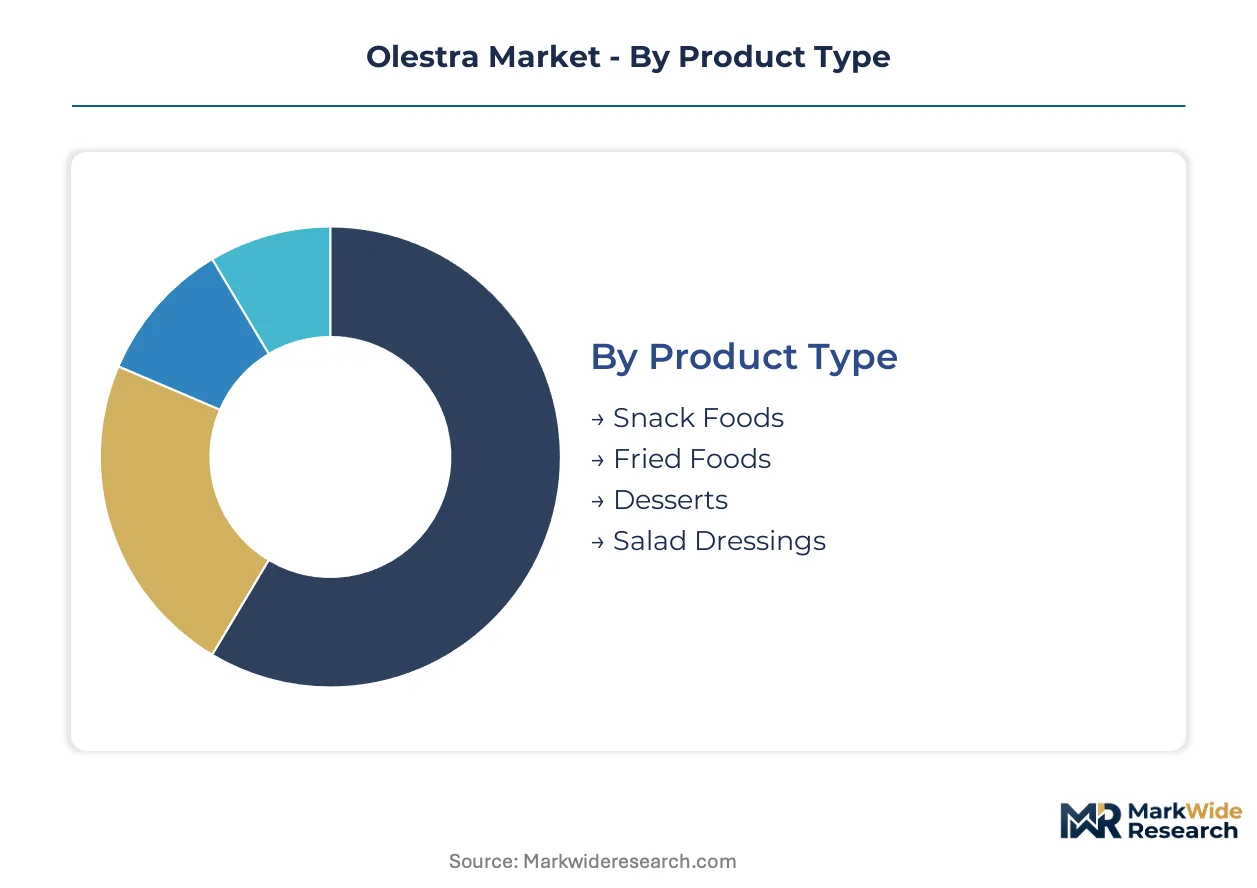
Olestra's commercial viability hinges on matching its sucrose polyester chemistry to specific processing requirements across food manufacturing verticals. Segmentation reveals where formulation investments concentrate and which approval burdens determine market access.
Product Type:
Snack Foods carry FDA GRAS self-determination documentation obligations, while Fried Foods face additional acrylamide co-regulation from state health departments. Desserts and Salad Dressings navigate simpler additive notification pathways.
- Snack Foods:Potato chips and extruded puffs represent the primary commercial deployment, with olestra replicating triglyceride mouthfeel in high-temperature frying. Reformulation mandates from retail chains in the United States and Mexico are accelerating specification rates for reduced-fat lines.
- Fried Foods:Breaded poultry and seafood applications require thermal stability above 180°C, a performance threshold where olestra differentiates against water-based fat replacers. Fast-casual chains in Texas and California are piloting olestra-fried proteins for menu calorie transparency.
- Desserts:Frozen dairy and baked goods incorporate olestra for fat reduction without ice crystal formation.
- Salad Dressings:Emulsion stability requirements favor liquid olestra formulations in pourable and spoonable variants.
Snack Foods sits at the top of the volume ranking, with Fried Foods climbing the fastest.
End User:
Procurement scale separates the cost tiers, with Food Manufacturers commanding bulk pricing through multi-year supply agreements while Health Food Stores absorb distributor markups.
- Food Manufacturers:North American snack conglomerates and commercial bakeries drive industrial demand, operating continuous production lines that require precise olestra dosing and validated supplier quality systems. Direct sourcing from esterification facilities is displacing traditional ingredient distributors.
- Household Consumers:Packaged goods availability at mass retail determines exposure, with consumer awareness concentrated in calorie-conscious demographic segments. Digestive tolerance education remains a purchase barrier at the point of sale.
- Restaurants:Foodservice adoption lags retail manufacturing due to fryer oil change logistics and staff training requirements.
- Health Food Stores:Premium positioning targets clean-label seekers, though olestra's synthetic classification limits placement in this channel.
Food Manufacturers dominates procurement volumes, with Restaurants expanding most quickly as fryer-compatible formulations mature.
Form:
Manufacturing integration complexity varies sharply, with Powdered and Granular forms enabling automated dosing while Liquid requires heated storage infrastructure.
- Powdered:Free-flowing sucrose polyester particles suit pneumatic conveying systems in high-throughput snack plants. Midwest corn belt processing facilities favor this form for integration with existing bulk handling infrastructure.
- Granular:Coarse particle size reduces dust generation during manual handling, supporting mid-sized bakeries without full automation. French and German industrial buyers specify this grade for EFSA-compliant reformulation projects.
- Ready-to-Eat:Pre-compounded blends with flavor masking agents accelerate product development timelines.
- Liquid:Pumpable olestra suits sauce and dressing manufacturers with jacketed mixing equipment.
Powdered leads form-factor shipments, with Granular gaining share fastest among European compliance-driven buyers.
Application:
Functional performance requirements stratify R&D investment, with Fat Replacement demanding the deepest lipid chemistry expertise while Texture Enhancement tolerates broader formulation latitude.
- Fat Replacement:Complete triglyceride substitution in fried and baked systems requires precise control of olestra's fatty acid chain distribution to match target melting profiles. Snack producers in the United States specify this application for 1:1 calorie reduction claims.
- Calorie Reduction:Partial fat substitution blends olestra with conventional oils to hit label targets while managing digestive tolerance thresholds. Bakery segment expansion into reduced-fat pastries relies on this hybrid approach.
- Ingredient Substitution:Reformulation to replace other fat replacers with olestra's superior thermal stability.
- Texture Enhancement:Secondary functionality improving crispness retention in extended shelf-life products.
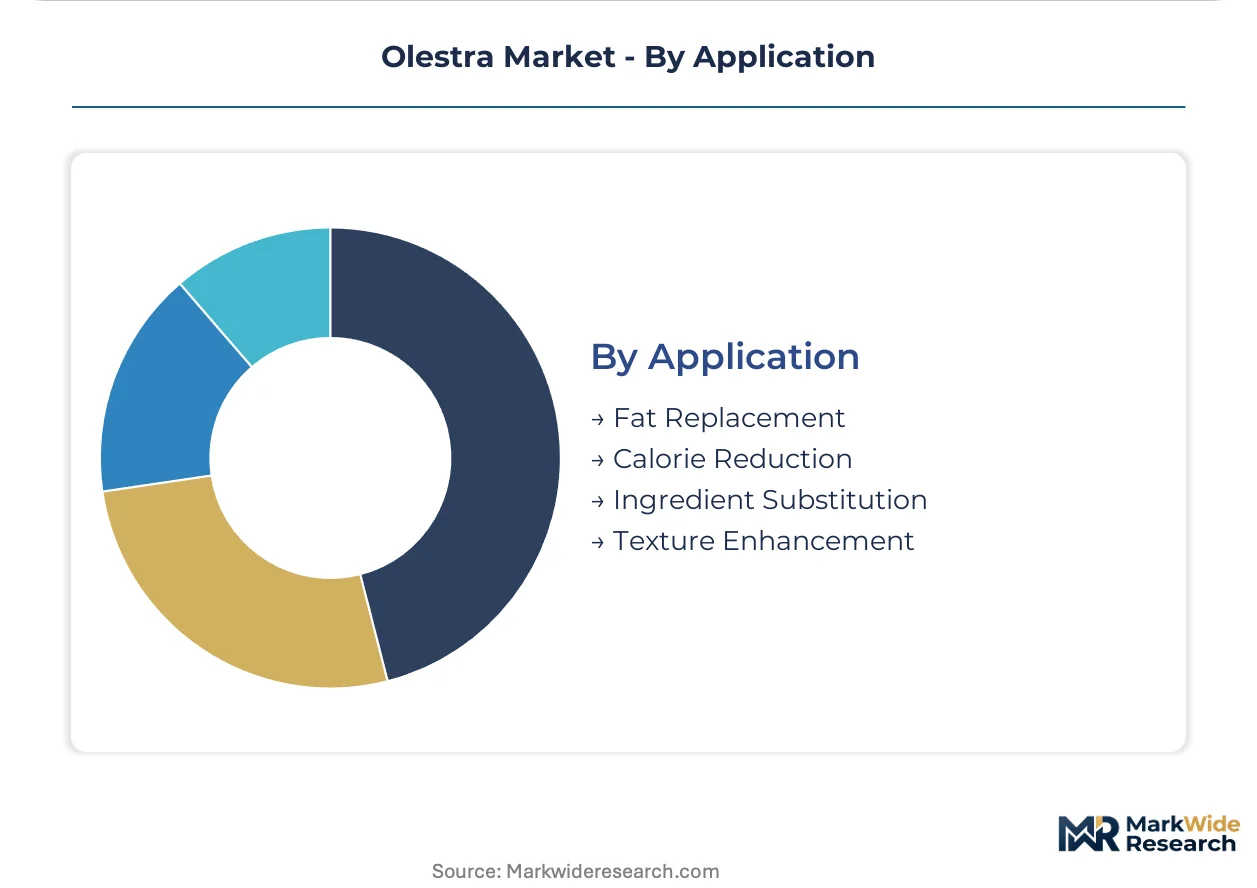
Fat Replacement anchors commercial volumes, with Calorie Reduction expanding most quickly as partial-substitution recipes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping olestra manufacturing footprints as producers seek jurisdictions with streamlined fat-substitute approval pathways and lower compliance documentation burdens. Production capacity is migrating toward regions with established GRAS-equivalent frameworks and proximate feedstock access.
United States
Snack food conglomerates in the Midwest corn belt drive industrial demand through continuous production lines requiring validated olestra supply systems. FDA labeling mandates and GRAS self-determination documentation shape formulation timelines for reduced-fat product launches. Chicago and Minneapolis processing corridors host the densest concentration of esterification facilities serving North American food manufacturers.
Germany
Specialty chemical producers in the Rhine-Ruhr industrial cluster supply critical esterification catalysts to global olestra manufacturers. EFSA purity specifications from the 2023 toxicology re-evaluation are forcing filtration infrastructure upgrades across German processing assets. Frankfurt and Ludwigshafen chemical parks anchor the European supply chain for sucrose polyester synthesis inputs.
India
Processed snack manufacturers in Maharashtra and Gujarat await FSSAI regulatory clearance to unlock olestra formulation for expanding modern retail channels. Pending approval timelines are redirecting R&D investment toward alternative fat replacers with established safety dossiers. Mumbai-Pune industrial corridors position domestic producers for rapid scale-up once regulatory barriers lift.
France
Bakery segment reformulation in Île-de-France and Auvergne-Rhône-Alpes faces compressed compliance deadlines under aligned EFSA inspection protocols. ANSM enforcement of tightened olestra purity standards is accelerating supplier qualification processes for industrial buyers. Lyon food technology clusters are piloting microencapsulation systems to mask sensory characteristics in premium pastry applications.
Canada
Health Canada and PMRA coordinated review pathways are streamlining fat-substitute approval for cross-border product launches with US manufacturers. Toronto and Montreal food processing hubs leverage proximity to Midwest US feedstock sources while maintaining distinct regulatory documentation requirements. Prairie province agriculture infrastructure supports regional sucrose supply security for domestic esterification operations.
Olestra Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agribusiness conglomerates commanding bulk procurement relationships while specialty ingredient houses capture premium formulation niches. The vendor base organizes around three archetypes: diversified agricultural processors with captive oilseed crushing and sucrose sourcing, specialty chemical firms with deep lipid chemistry R&D capabilities, and regional distributors with localized technical service networks. Dominant competitive moves include backward integration into feedstock production and multi-year supply agreements that lock in volume commitments from snack food manufacturers.
Within the diversified agricultural processor tier, Cargill Inc. and Archer Daniels Midland Company occupy positions anchored by Midwest corn belt infrastructure and established food manufacturer relationships. DuPont de Nemours Inc. represents the specialty chemical archetype with R&D-intensive positioning in sucrose polyester chemistry. These three entities exemplify the competitive structure where scale-driven procurement leverage confronts formulation expertise as distinct value propositions.
| Leading Market Players |
|---|
| Cargill Inc. |
| DuPont de Nemours Inc. |
| FMC Corporation |
| Grain Processing Corporation |
| Archer Daniels Midland Company |
| Advanced Food Systems Inc. |
| Ashland Inc. |
| CP Kelco |
| Penford Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into Midwest corn belt sucrose sourcing anchors pricing power for North American olestra producers, locking in feedstock cost predictability while distant competitors absorb commodity volatility through spot market exposure. This captive supply structure lets integrated manufacturers undercut contract bids from non-integrated rivals during sugar price spikes.
Pricing Analysis
Distributor margin layers compress as food manufacturers migrate toward direct esterification facility contracts, eliminating traditional ingredient house markups. Three-tier pricing structure across premium EFSA-compliant, standard FDA-grade, and economy non-certified levels differentiates quotes. Pricing pressure stems from sucrose commodity swings that squeeze production margins. Mid-sized bakeries show highest price sensitivity, while multinational snack conglomerates absorb cost fluctuations through volume-locked multi-year agreements.
Supply Chain Analysis
Dual-sourcing requirements from North American snack producers mandate qualified backup suppliers for both German specialty esterification catalysts and domestic sucrose polyester synthesis capacity. Supply concentrates in United States corn belt processing corridors, German Rhine-Ruhr chemical clusters, and pending Indian FSSAI-cleared facilities. Raw material dependencies center on sugar beet and cane feedstocks, vegetable oil fatty acids, and proprietary metal-organic catalysts. Single-source catalyst vulnerability from German suppliers creates geopolitical interruption risk. Distribution runs through direct manufacturer-to-producer channels displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Olestra manufacturing economics favor locating esterification assets in jurisdictions with streamlined GRAS-equivalent frameworks and proximate feedstock access, exploiting regulatory cost differentials between FDA-cleared US operations and pending FSSAI pathways in India.
For Market Incumbents: Extend formulation service capabilities beyond commodity olestra supply to capture R&D outsourcing budgets from mid-sized food manufacturers lacking in-house lipid chemistry expertise. Deepen backward integration into regional sugar processing to defend margin position against sucrose price volatility. Lock in multi-year volume commitments from expanding bakery segment buyers before specialty carbohydrate competitors scale alternative fat replacer production. For New Entrants and Emerging Players: Begin with microencapsulation technology licensing to premium snack producers seeking sensory-masked olestra systems for clean-label positioning. Target French and German bakery reformulation projects facing compressed EFSA compliance deadlines. Pursue white-label manufacturing partnerships with established esterification facilities rather than greenfield capacity investment. For Investors and Strategic Acquirers: Roll-up economics work for regional olestra distributors with localized technical service networks because snack manufacturer procurement teams prioritize validated supplier relationships over pure price competition. Five-to-ten year viability hinges on FSSAI approval unlocking Indian processed snack market access. Monitor FSSAI regulatory clearance timelines as the critical inflection signal for redirecting capacity expansion capital toward South Asian manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Production | Captive sucrose supply from Midwest corn belt processing insulates margins against commodity volatility. |
| Microencapsulation Technology Licensing | Sensory masking systems open premium product tiers previously closed to fat substitute inclusion. |
| Multi-Year Supply Agreement Negotiation | Volume-locked contracts with North American snack conglomerates displace spot purchasing patterns. |
| EFSA Compliance Infrastructure Upgrade | Enhanced filtration systems meet tightened 2023 purity specifications for European market entry. |
| Direct-to-Manufacturer Digital Platform Launch | Ingredient marketplaces bypass distributor markups for mid-sized food producer procurement. |
Research Methodology
Bottom-up food manufacturer demand modeling reconciled against top-down esterification capacity tracking forms the analytical core, combining primary interviews with snack food R&D directors, commercial bakery procurement leads, olestra plant managers, and specialty chemical distribution channel partners with secondary validation from FDA GRAS notification filings, EFSA toxicology re-evaluation documents, FSSAI approval dockets, and USDA sugar production statistics.
Input-output matrices map sucrose feedstock availability against esterification throughput across product type, application, form factor, and end-user segmentation dimensions. CAGRs derive from trend extrapolation of reformulation mandate intensity and regulatory approval timelines. Forecast inputs incorporate snack food manufacturer capital expenditure plans and EFSA inspection protocol alignment schedules.
Several conditions sit outside the modeled scope, including unannounced FSSAI regulatory decisions, breakthrough alternative fat replacer commercialization, and abrupt sugar commodity price shocks. Deviation in Indian regulatory clearance timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market