
 Atopic Dermatitis Treatment Market | 2026-2036
Atopic Dermatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Atopic Dermatitis Treatment Market Intelligence
EU MDR is realigning the cost-of-entry calculus for device-drug combination products in dermatology, forcing manufacturers to rebuild clinical evidence packages around biocompatibility and post-market surveillance. Sanofi leverages its immunology infrastructure to sustain Dupixent's position across multiple indications beyond atopic dermatitis. Regeneron Pharmaceuticals anchors its competitive stance through deep antibody engineering capabilities and co-development economics with Sanofi. AbbVie differentiates via Rydapt's mechanism diversity and its broader inflammation portfolio cross-selling potential.
Atopic dermatitis treatment encompasses pharmacological and non-pharmacological interventions targeting type 2 inflammation, skin barrier dysfunction, and pruritus pathways, with biologics typically requiring cold-chain distribution at two to eight degrees Celsius and subcutaneous administration every two to four weeks. The primary purpose is to interrupt the IL-4, IL-13, and JAK-STAT signaling cascades that perpetuate eczematous inflammation while restoring epidermal integrity. Biologics command the deepest margin pools due to manufacturing complexity and patent exclusivity, while topical corticosteroids remain the volume backbone across mild disease segments. Injectable therapy is gaining structural share in severe atopic dermatitis as patient self-administration training programs expand, though topical application still dominates pediatric and maintenance settings where caregiver compliance shapes prescribing patterns.
FDA, EMA, and Japan's PMDA each enforce distinct evidentiary standards for biologic approval in chronic inflammatory skin disease, with the FDA emphasizing long-term safety databases for JAK inhibitors and EMA requiring enhanced pharmacovigilance for immunosuppressive mechanisms. These divergent pathways fragment launch sequencing and label claims, compelling developers to architect region-specific regulatory strategies from Phase II forward. Stakeholders must monitor how payer consolidation and step-therapy mandates in dermatology reshape access dynamics for novel mechanisms against entrenched generic topicals.
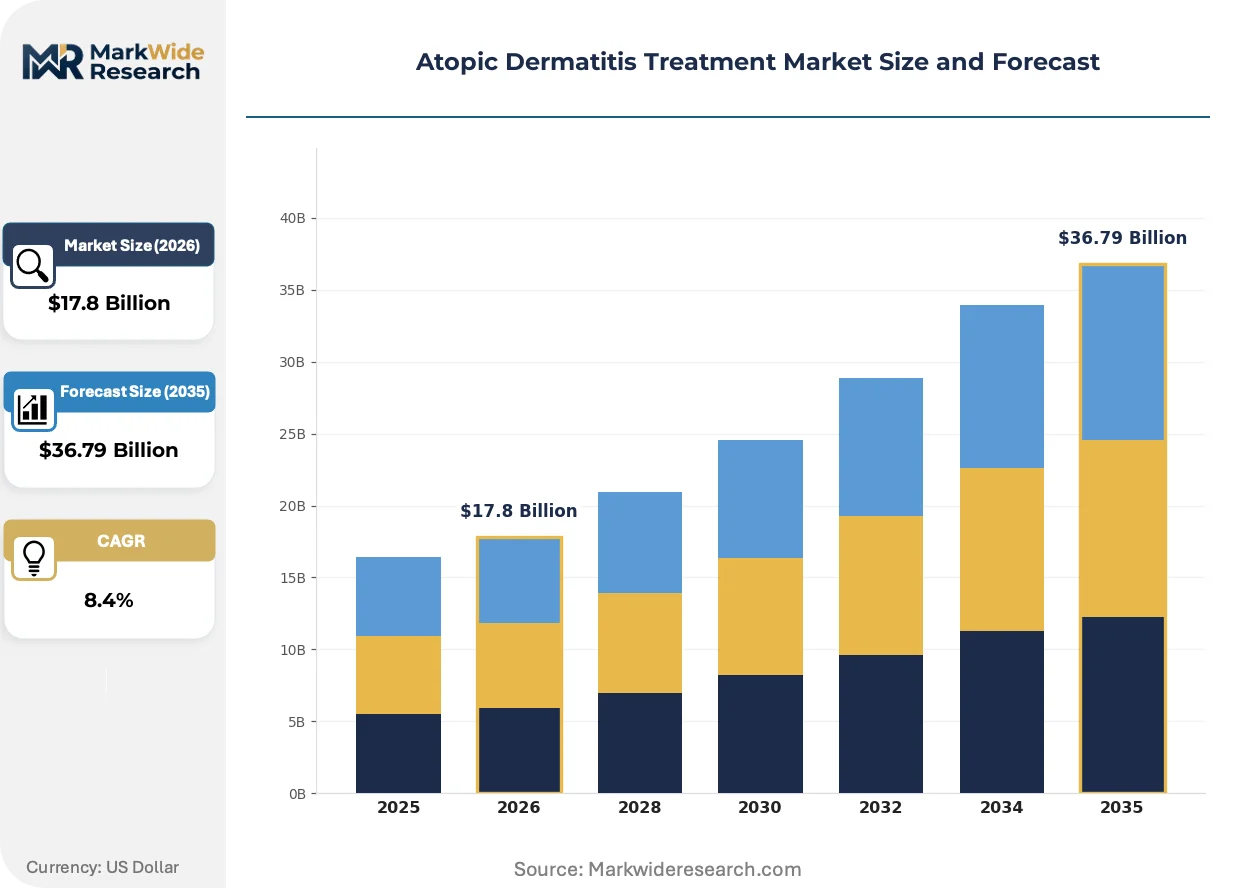
Market Dynamics
The FDA's evolving guidance on JAK inhibitor safety databases is compressing clinical trial timelines while expanding post-market surveillance obligations, forcing developers to architect parallel regulatory strategies across multiple geographies from early-phase development.
Growth Catalysts
- Biologics cold-chain infrastructure:Specialty pharmacy networks in the United States have built out two-to-eight-degree Celsius distribution capabilities that now reach patient homes, eliminating hospital-based infusion requirements and expanding addressable severe disease populations.
- EU MDR device-drug convergence:The Medical Device Regulation's clarified pathways for combination products in dermatology are accelerating development of topical delivery systems with embedded biologic actives, creating new formulation categories.
- Pediatric indication expansion:Regulatory incentives for juvenile atopic dermatitis trials are pulling biologic developers into younger age brackets, opening maintenance therapy segments previously dominated by topical corticosteroids.
Market Restraints
- API manufacturing concentration:Monoclonal antibody production for IL-4/IL-13 inhibitors concentrates in single-source contract manufacturing organizations in Ireland and Singapore, creating supply vulnerability for originator and biosimilar programs alike.
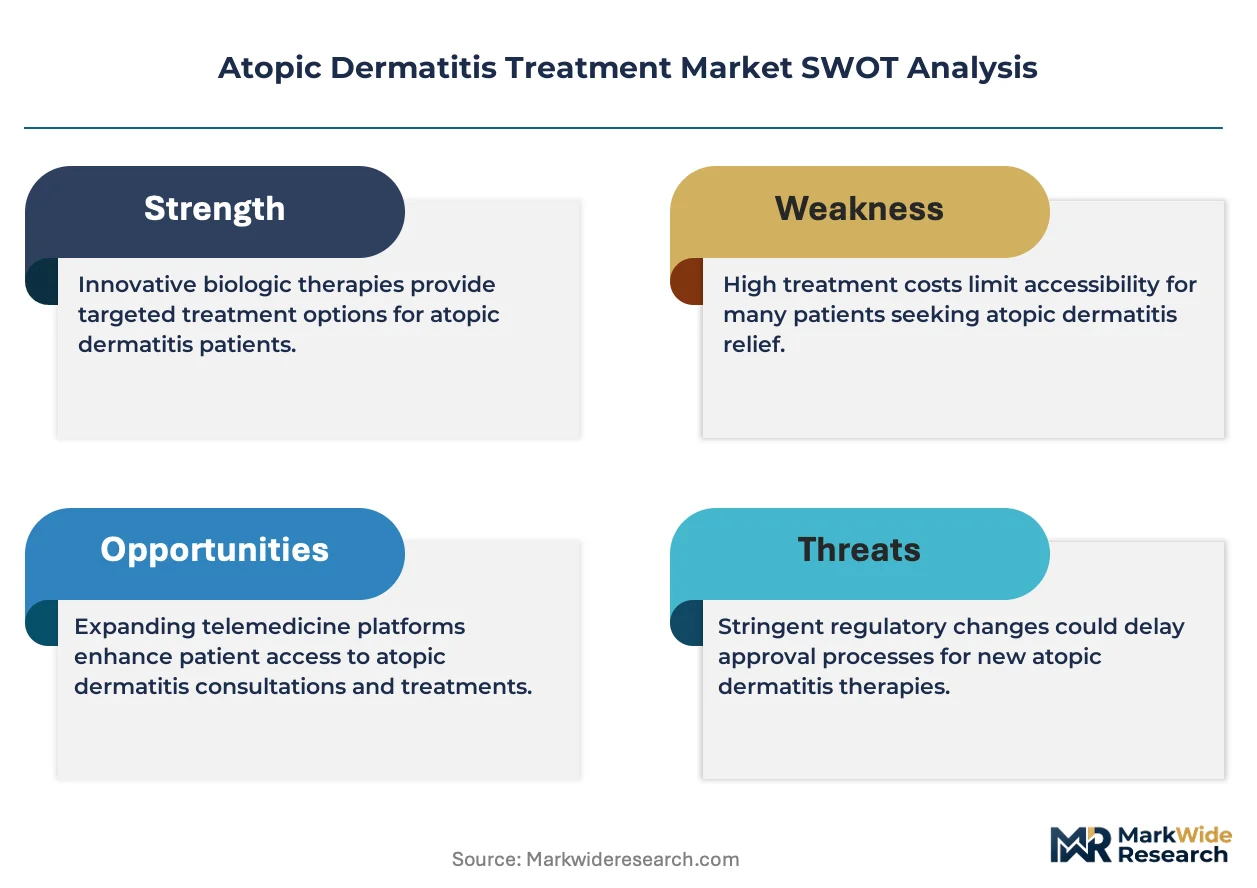
- JAK inhibitor safety surveillance:The FDA's boxed warning requirements for oral JAK inhibitors in inflammatory conditions have extended to topical formulations, compressing prescriber comfort and payer coverage for this mechanism class.
- Topical corticosteroid substitution:Generic triamcinolone and mometasone formulations retain formulary preference in mild-to-moderate disease, limiting price realization for novel non-steroidal topicals.
Strategic Opportunities
- Japan's PMDA Sakigake pathway:Conditional early approval for pediatric biologics creates a launch sequencing option that generates real-world evidence ahead of EMA and FDA filings.
- Telemedicine prescribing platforms:Digital health platforms in Germany and the United Kingdom are enabling remote dermatology consultations with e-prescription fulfillment, bypassing traditional specialty clinic bottlenecks.
- Microbiome-targeted therapeutics:Convergence of skin microbiome sequencing and live biotherapeutic product manufacturing is opening a mechanism space distinct from both immunosuppression and barrier repair.
Industry Challenges
- Patient self-injection training scale:Subcutaneous biologic administration requires certified nursing support for pediatric and elderly populations, straining specialty pharmacy staffing models.
- Real-world evidence harmonization:Divergent data collection standards across FDA's Sentinel system, EMA's EudraVigilance, and Japan's PMDA post-market surveillance create fragmented safety signal detection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atopic Dermatitis Treatment Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Calcineurin Inhibitors, Biologics, Antihistamines, Emollients Therapy Area: Mild Atopic Dermatitis, Moderate Atopic Dermatitis, Severe Atopic Dermatitis, Infantile Dermatitis End User: Dermatology Clinics, Pediatric Clinics, Specialized Skin Centers, Homecare Settings Delivery Mode: Topical Application, Oral Medication, Injectable Therapy, Phototherapy |
| Companies Covered | Eli Lilly and Company, LEO Pharma, Sanofi, Incyte Corporation, Galderma, AbbVie, Regeneron Pharmaceuticals, GlaxoSmithKline, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atopic Dermatitis Treatment Market Strategic Shifts & Innovations
Next-generation atopic dermatitis therapeutics are converging on precision targeting of type 2 inflammation while delivery technologies erode the historical divide between systemic and topical administration paradigms.
Topical JAK inhibitors are absorbing development resources previously directed toward oral systemic formulations, with dermatology-focused pharmaceutical developers reformulating small-molecule inhibitors for epidermal penetration rather than gastrointestinal absorption. Pediatric and facial-sensitive subpopulations are adopting these non-steroidal topicals fastest, compressing the addressable market for mid-potency corticosteroids in maintenance settings.
EMA's enhanced pharmacovigilance requirements for immunosuppressive dermatology products are mandating fifteen-year post-authorization safety studies for novel biologics, extending regulatory liability windows well beyond patent expiry. Developers are responding by building dedicated patient registries in Germany and France at launch, treating longitudinal safety data as a competitive asset rather than compliance burden.
Step-therapy mandates from United States commercial payers are forcing prescribing patterns through topical corticosteroid and calcineurin inhibitor trials before biologic authorization, extending time-to-adequate-therapy for moderate-to-severe patients. This administrative friction is most visible in Texas and Florida, where prior authorization denial rates for dupilumab and tralokinumab exceed national averages by substantial margins.
Atopic Dermatitis Treatment Market Segmentation
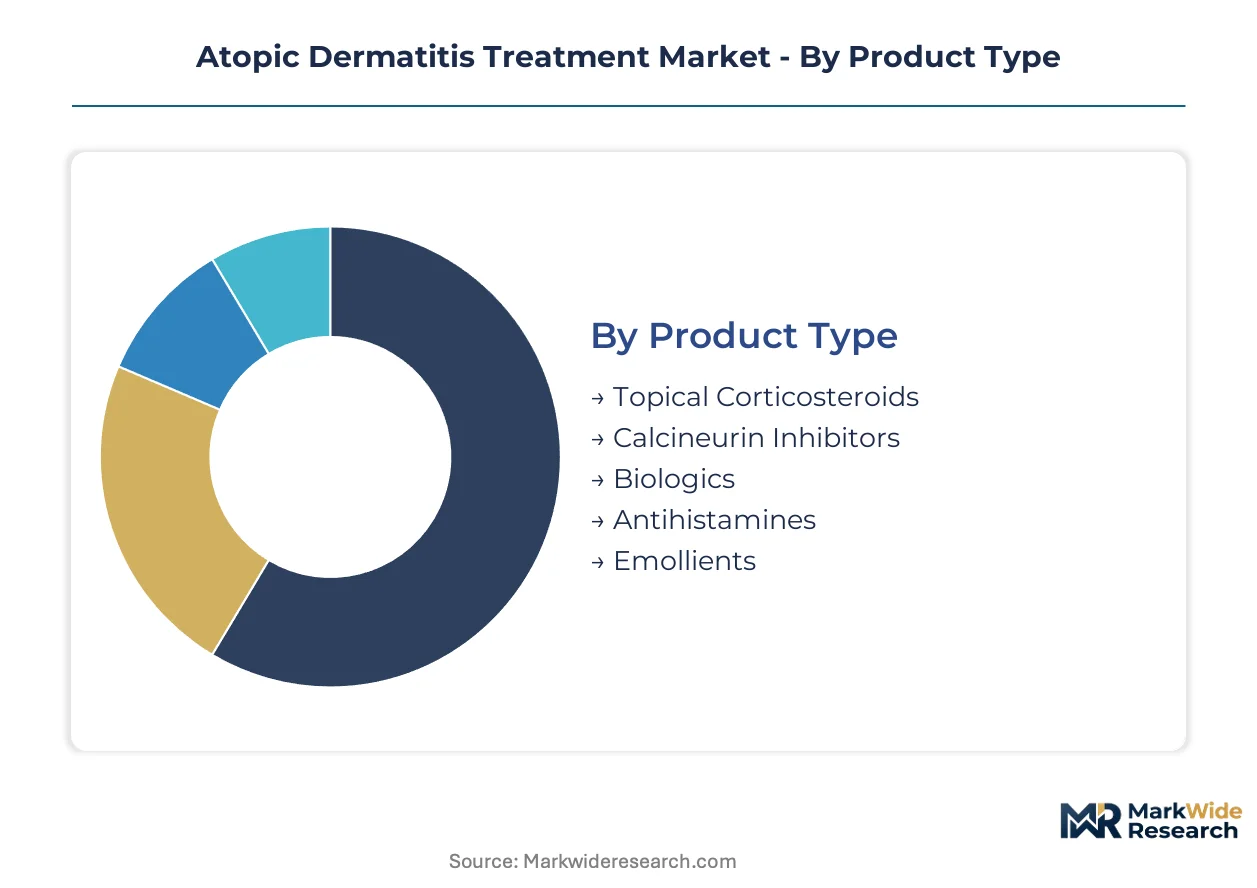
Atopic dermatitis treatment segments diverge sharply by regulatory burden and reimbursement complexity. Biologics demand cold-chain validation and FDA/EMA immunogenicity protocols, while topicals navigate simpler stability testing but face intense generic competition.
Product Type:
FDA's evolving JAK inhibitor guidance and EMA's fifteen-year post-authorization surveillance requirements create tiered compliance costs across mechanism classes.
- Topical Corticosteroids:Hydrocortisone through clobetasol formulations span potency classes I through VII. United States Medicaid formularies favor generic triamcinolone and mometasone, compressing branded pricing power in mild disease maintenance.
- Calcineurin Inhibitors:Tacrolimus and pimecrolimus macrolactams offer steroid-sparing mechanisms for facial and intertriginous application. Pediatric and sensitive-skin subpopulations in Germany and France adopt these fastest, though prior authorization requirements in Texas and Florida delay access.
- Biologics:Monoclonal antibodies targeting IL-4 and IL-13 require EMA enhanced pharmacovigilance and FDA long-term safety databases.
- Antihistamines:Oral and topical histamine receptor antagonists address pruritus without modifying underlying inflammation.
- Emollients:Barrier-repair formulations with ceramide or filaggrin components serve foundational maintenance roles.
Leading the category by volume: Topical Corticosteroids. Growing fastest: Biologics.
Therapy Area:
Severity stratification determines prescriber channel and mechanism selection, with severe disease concentrating in specialty clinics and mild cases dispersing through primary care.
- Mild Atopic Dermatitis:Emollient-first protocols with intermittent low-potency corticosteroid rescue dominate primary care prescribing in the United Kingdom and Germany.
- Moderate Atopic Dermatitis:Calcineurin inhibitor maintenance and topical JAK inhibitor escalation bridge the gap between generic topicals and biologic authorization. Step-therapy mandates from United States commercial payers concentrate demand here, extending time-to-adequate-therapy.
- Severe Atopic Dermatitis:IL-4/IL-13 inhibitor biologics require cold-chain distribution and subcutaneous administration every two to four weeks. Specialty pharmacy networks in the United States have built home delivery capabilities at two-to-eight degrees Celsius, eliminating hospital infusion requirements.
- Infantile Dermatitis:Regulatory incentives for juvenile trials pull developers into younger age brackets. Japan's PMDA Sakigake pathway enables conditional early approval, generating real-world evidence ahead of EMA and FDA filings.
Volume concentrates in Moderate Atopic Dermatitis. Steepest expansion trajectory: Infantile Dermatitis.
End User:
Site-of-care economics and prior authorization infrastructure reshape prescribing authority across channel types.
- Dermatology Clinics:Academic medical centers and private dermatology groups control biologic initiation and maintenance monitoring. Prior authorization denial rates for dupilumab and tralokinumab in Texas and Florida exceed national averages, creating regional access friction.
- Pediatric Clinics:Certified nursing support requirements for subcutaneous biologic administration strain staffing models. EU MDR device-drug combination pathways accelerate development of topical delivery systems with embedded actives for this channel.
- Specialized Skin Centers:Phototherapy units and multidisciplinary atopic dermatitis programs concentrate severe disease referrals.
- Homecare Settings:Telemedicine prescribing platforms in Germany and the United Kingdom enable remote consultations with e-prescription fulfillment, bypassing traditional specialty clinic bottlenecks.
Dominant by patient volume: Dermatology Clinics. Expanding most quickly: Homecare Settings.
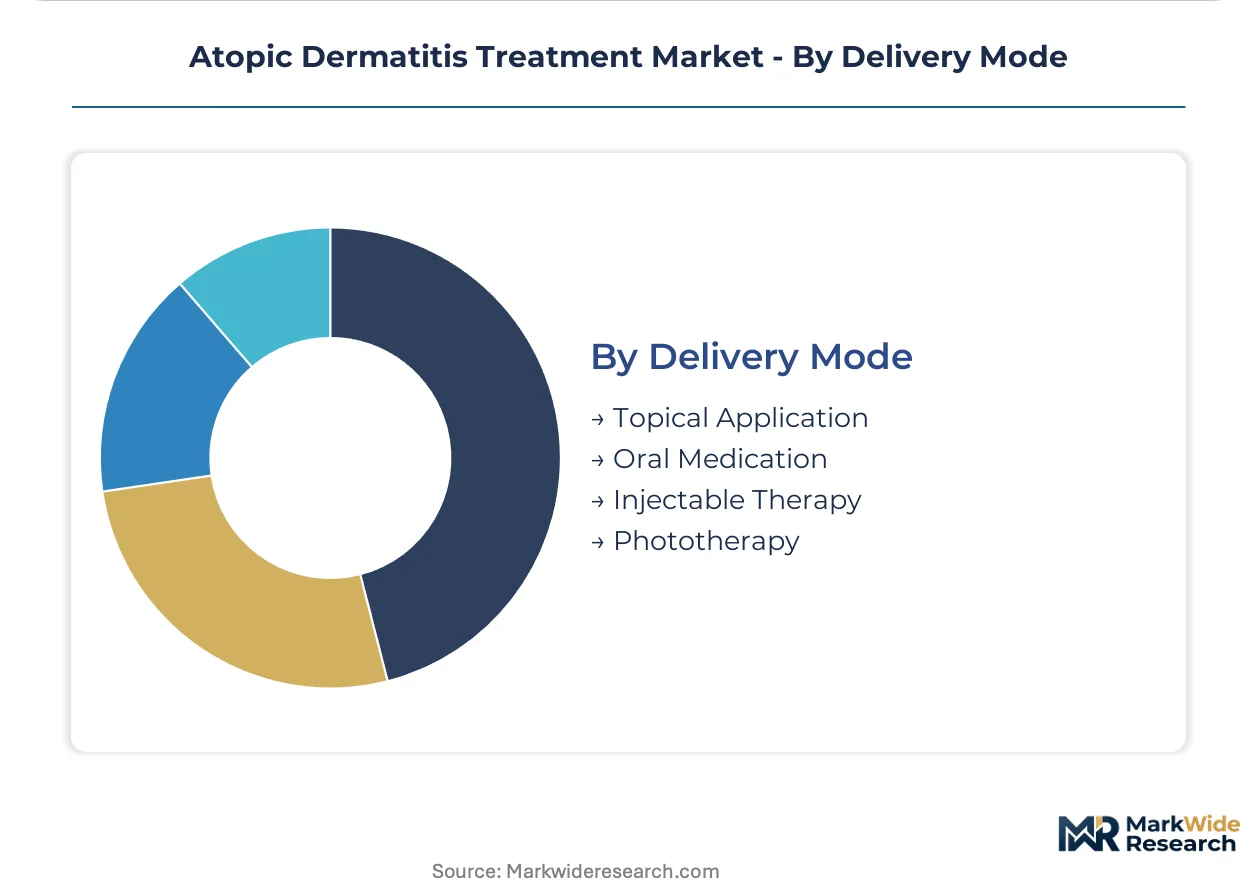
Delivery Mode:
Administration paradigm determines manufacturing complexity, distribution infrastructure, and patient compliance requirements.
- Topical Application:Cream, ointment, lotion, and gel formulations dominate pediatric and maintenance settings where caregiver compliance shapes prescribing patterns. EU MDR biocompatibility requirements for device-drug combinations are rebuilding clinical evidence packages for advanced delivery systems.
- Oral Medication:Systemic corticosteroids, JAK inhibitors, and antihistamines face FDA boxed warning requirements that have extended from oral to topical JAK formulations, compressing prescriber comfort.
- Injectable Therapy:Subcutaneous biologic administration every two to four weeks requires patient self-injection training programs. Monoclonal antibody production concentrates in single-source contract manufacturing organizations in Ireland and Singapore, creating supply vulnerability.
- Phototherapy:Narrowband UVB and UVA1 protocols require specialized equipment and clinical supervision, limiting scalability.
Highest volume: Topical Application. Gaining share fastest: Injectable Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial payers concentrate demand for novel mechanism drugs through prior authorization pathways that favor biologics over legacy topicals. Specialty dermatology networks in Texas and Florida exhibit elevated denial rates for IL-4/IL-13 inhibitors, creating regional access friction that shapes prescriber behavior.
United States
Step-therapy mandates from commercial insurers extend time-to-adequate-therapy for moderate-to-severe patients. The FDA's boxed warning requirements for JAK inhibitors compress prescriber comfort for oral and topical formulations alike. Boston and San Francisco anchor biologic clinical trial infrastructure, with academic medical centers controlling initiation protocols for pediatric populations.
Germany
Telemedicine prescribing platforms enable remote dermatology consultations with e-prescription fulfillment, bypassing traditional specialty clinic bottlenecks. EMA enhanced pharmacovigilance requirements mandate fifteen-year post-authorization safety studies for novel biologics. Frankfurt and Munich concentrate contract research organizations supporting EU MDR device-drug combination development.
Japan
PMDA's Sakigake pathway generates conditional early approval for pediatric biologics ahead of EMA and FDA filings. Regulatory incentives for juvenile atopic dermatitis trials pull developers into younger age brackets. Osaka and Tokyo host monoclonal antibody manufacturing facilities serving domestic and export markets.
United Kingdom
NHS formularies favor generic triamcinolone and mometasone in mild-to-moderate disease, compressing branded pricing power for non-steroidal topicals. Digital health platforms enable remote consultations with e-prescription fulfillment. London's specialty pharmacy networks have built home delivery capabilities at two-to-eight degrees Celsius for biologic therapies.
India
CDSCO's evolving biosimilar guidelines attract contract manufacturing investment for monoclonal antibody production. Domestic demand concentrates in metropolitan dermatology clinics for moderate-to-severe cases. Hyderabad and Bangalore anchor active pharmaceutical ingredient synthesis for topical corticosteroid formulations serving export markets.
Atopic Dermatitis Treatment Market Key Industry Players
United States biopharmaceutical anchors hold the systemic therapy tier; European dermatology specialists control topical formulation development. Market structure concentrates around three to five entities with approved biologics, while mid-scale developers fragment across non-steroidal topical segments. Strategic archetypes include immunology platform extenders, dermatology-focused formulation houses, and JAK inhibitor mechanism diversifiers. Dominant competitive moves center on pediatric indication expansion and EU MDR device-drug combination pathways.
Within the immunology platform tier, Sanofi and Regeneron Pharmaceuticals exemplify co-development economics that sustain multi-indication positioning. AbbVie occupies a position among mechanism diversifiers with inflammation portfolio cross-selling potential. These three entities represent distinct strategic postures: antibody engineering depth, commercial infrastructure leverage, and therapeutic area breadth respectively.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| LEO Pharma |
| Sanofi |
| Incyte Corporation |
| Galderma |
| AbbVie |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| Pfizer |
| Others |
Cost & Logistics Intelligence
Captive biologics manufacturing in Ireland and Singapore anchors supply positioning and pricing power for IL-4/IL-13 inhibitors, concentrating production economics in single-source contract manufacturing organizations that command premium unit economics through cold-chain validation and immunogenicity protocol compliance.
Pricing Analysis
Volume concentrates in generic topical corticosteroids while margin pools deepen around biologics with cold-chain requirements. Three-tier pricing structure across premium biologics, standard calcineurin inhibitors, and economy generic topicals reflects potency classification and distribution complexity. Cost compression in the mid-potency corticosteroid tier intensifies because Medicaid formularies favor generic triamcinolone and mometasone. Pediatric clinics and specialty dermatology networks exhibit lowest price sensitivity due to prior authorization infrastructure and patient self-administration training investments.
Supply Chain Analysis
Regional distribution centers at two-to-eight degrees Celsius in Boston, Frankfurt, and Tokyo enable hub-and-spoke patterns for biologic therapies. Monoclonal antibody production draws from contract manufacturing organizations in Ireland and Singapore, with active pharmaceutical ingredient synthesis anchored in Hyderabad and Bangalore. Single-source vulnerability for IL-4/IL-13 inhibitor fill-finish creates exposure for originator and biosimilar programs alike. Distribution runs through specialty pharmacy networks with home delivery capabilities that bypass hospital-based infusion requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable biologics are displacing oral systemic formulations as the standard-of-care anchor for moderate-to-severe disease, compressing development resources previously directed toward topical JAK inhibitors and repositioning formulation houses around subcutaneous delivery technologies.
For Market Incumbents: To counter biosimilar entry and EU MDR compliance cost escalation, deepen cold-chain infrastructure partnerships in Germany and France while building dedicated patient registries that treat fifteen-year post-authorization safety data as competitive assets rather than regulatory burdens. For New Entrants and Emerging Players: Launch via telemedicine prescribing platforms in the United Kingdom and Germany that enable remote dermatology consultations with e-prescription fulfillment, targeting infantile dermatitis segments where regulatory incentives for juvenile trials create label expansion pathways ahead of EMA and FDA filings. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by immunology infrastructure holders, with long-term viability hinging on pediatric indication breadth and device-drug combination capabilities under EU MDR. Watch FDA JAK inhibitor guidance evolution as the inflection signal for mechanism class reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | EMA and PMDA regulatory incentives pull developers into younger age brackets with accelerated approval pathways. |
| Cold-Chain Distribution Scale-Up | Specialty pharmacy networks in the United States eliminate hospital infusion requirements through home delivery capabilities. |
| EU MDR Device-Drug Combination Development | Frankfurt and Munich contract research organizations support biocompatibility validation for topical delivery systems with embedded actives. |
| Patient Registry Investment | Fifteen-year post-authorization safety studies in Germany and France convert regulatory liability into longitudinal data assets. |
| Telemedicine Platform Integration | Digital health infrastructure in the United Kingdom and Germany bypasses traditional specialty clinic bottlenecks for maintenance therapy. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with formulary database audits and payer access policy documentation. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated mechanism-class adoption curves and prior authorization friction points. Bottom-up and top-down triangulation reconciled patient population estimates with manufacturer shipment data.
Bottom-up modeling anchored volume projections to severity-stratified patient populations, treatment line progression rates, and regional regulatory cluster adoption curves. Top-down validation checked aggregate manufacturer revenue patterns against cold-chain distribution capacity expansion. Segmentation dimensions included therapy area, delivery mode, end-user channel, and regional payer archetype. CAGRs derived from mechanism-class growth differentials and pediatric indication expansion trajectories.
Regulatory guidance shifts, biosimilar approval timelines, and payer consolidation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around JAK inhibitor safety surveillance evolution and EU MDR implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Folliculitis Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Rosacea Treatment Market
Dermatology
Australia Skin Treatment Market
Dermatology
Microdermabrasion Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Acne Vulgaris Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Microneedling Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Global Dermatitis Herpetiformis Market