
 Biomimetic Materials Market | 2026-2036
Biomimetic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Biomimetic Materials Market Intelligence
The performance gap between high-purity, clinical-grade materials and lower-cost research-grade compounds is recalibrating competitive dynamics. Zimmer Biomet specializes in biocompatible materials for orthopedic and dental applications, focusing on long-term in-vivo stability. Meanwhile, BASF SE leverages its vast chemical production scale to supply foundational polymers for a wide range of biomimetic formulations. DuPont de Nemours, Inc. competes with advanced polymer blends for medical device manufacturing.
Biomimetic materials are synthetic substances engineered to replicate the structure, properties, and functions of natural biological materials. These materials often feature hierarchical structures, such as self-assembling hydrogels or nanocomposites, designed for specific biological interactions in medical settings. Within applications, tissue engineering and drug delivery represent the most significant areas of research and commercial investment. Electrospinning and 3D bioprinting are the leading technologies, enabling precise control over scaffold architecture and cell integration.
Market access for medical applications is governed by stringent regulatory bodies, including the FDA in the United States and the EMA in Europe. These agencies, along with China's NMPA, mandate extensive biocompatibility and safety testing, influencing material selection and development timelines. Future success for material developers depends on navigating this complex regulatory landscape while demonstrating clear clinical or performance advantages over existing solutions.
Market Dynamics
The central dynamic shaping the biomimetic materials market is the tension between rapid fabrication technology advancements, like 3D bioprinting, and the necessarily deliberate pace of regulatory validation required for clinical use in humans.
Growth Catalysts
- Advanced Fabrication Technologies:The proliferation of electrospinning and 3D bioprinting enables the creation of intricate, hierarchical scaffolds that mimic natural tissue architecture, a critical requirement for successful tissue engineering applications.
- Orthopedic and Dental Demand:An increasing clinical need for more durable and biocompatible orthopedic and dental implants, particularly within the advanced healthcare systems of Germany and Japan, drives investment in novel material formulations.
- Regulatory Incentives:Programs like the FDA's Breakthrough Devices Program can expedite the development and review of novel biomimetic devices that offer significant advantages over existing treatments, encouraging innovation.
Market Restraints
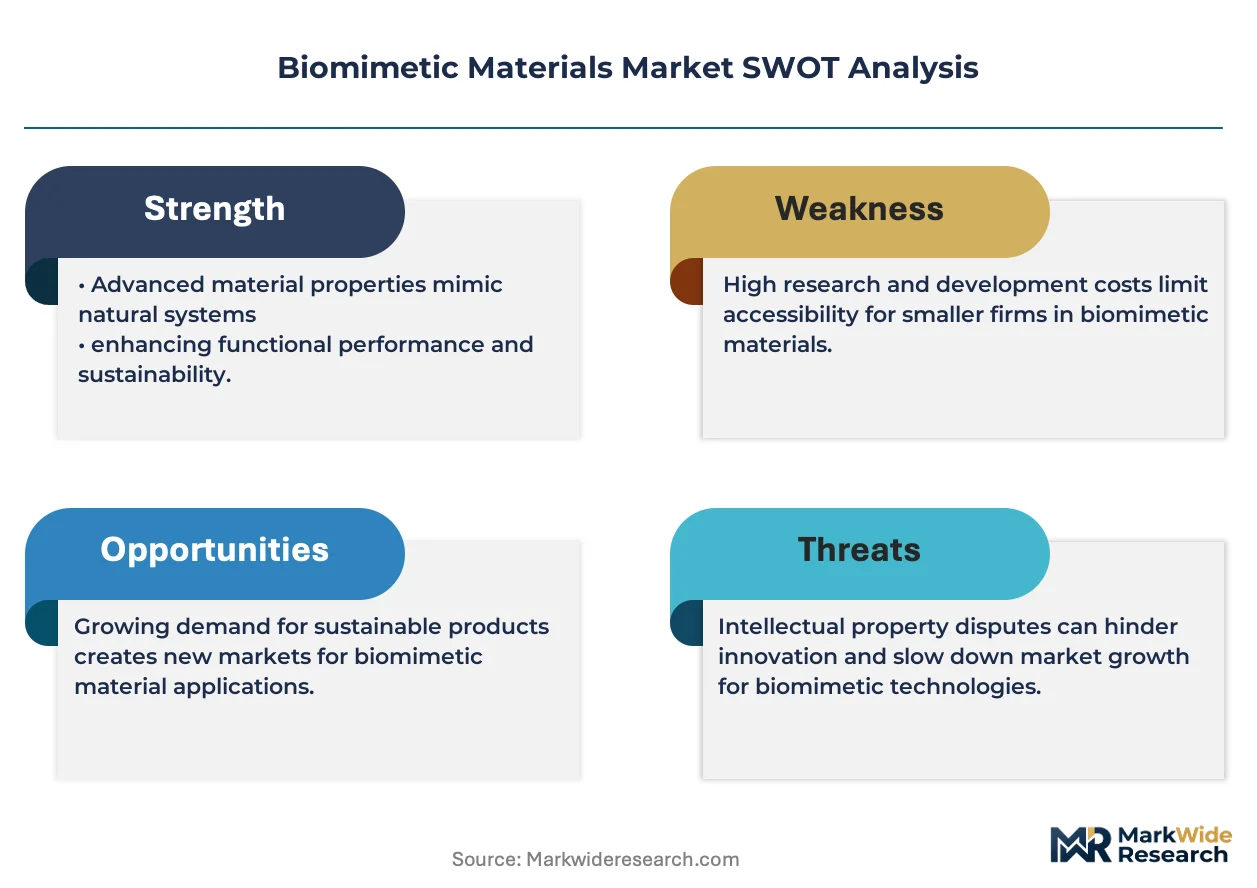
- High Material Costs:The significant price premium for clinical-grade, high-purity polymers and hydrogels, compared to research-grade equivalents, limits their use in early-stage development and constrains academic research budgets.
- Stringent Regulatory Hurdles:Extensive and costly biocompatibility testing mandated by agencies such as the EMA and China's NMPA creates high barriers to entry and extends product development timelines by several years.
- Biocompatibility Challenges:Achieving long-term in-vivo stability and avoiding chronic inflammatory responses or immune rejection remains a primary technical barrier for many advanced nanocomposites and self-assembling materials.
Strategic Opportunities
- Targeted Drug Delivery:Developing advanced hydrogel systems that respond to specific biological cues for controlled, localized drug release represents a significant opportunity beyond structural tissue repair.
- Smart Implants:The integration of micro-sensors with biomimetic materials can create next-generation implants capable of monitoring physiological conditions, such as healing progress or infection, and transmitting data.
- Geographic Expansion:Targeting markets with strong medical research infrastructure but less saturation, such as South Korea and Australia, offers a pathway for growth outside the primary clusters of the US, Germany, and Japan.
Industry Challenges
- Lack of Standardization:Divergent testing protocols and material characterization standards between regulatory bodies like the FDA and EMA complicate the design of global clinical trials and hinder international market access.
- Interdisciplinary Talent Scarcity:A shortage of professionals with combined expertise in material science, cellular biology, and regulatory affairs creates a bottleneck in translating lab-scale innovations into commercial products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomimetic Materials Market |
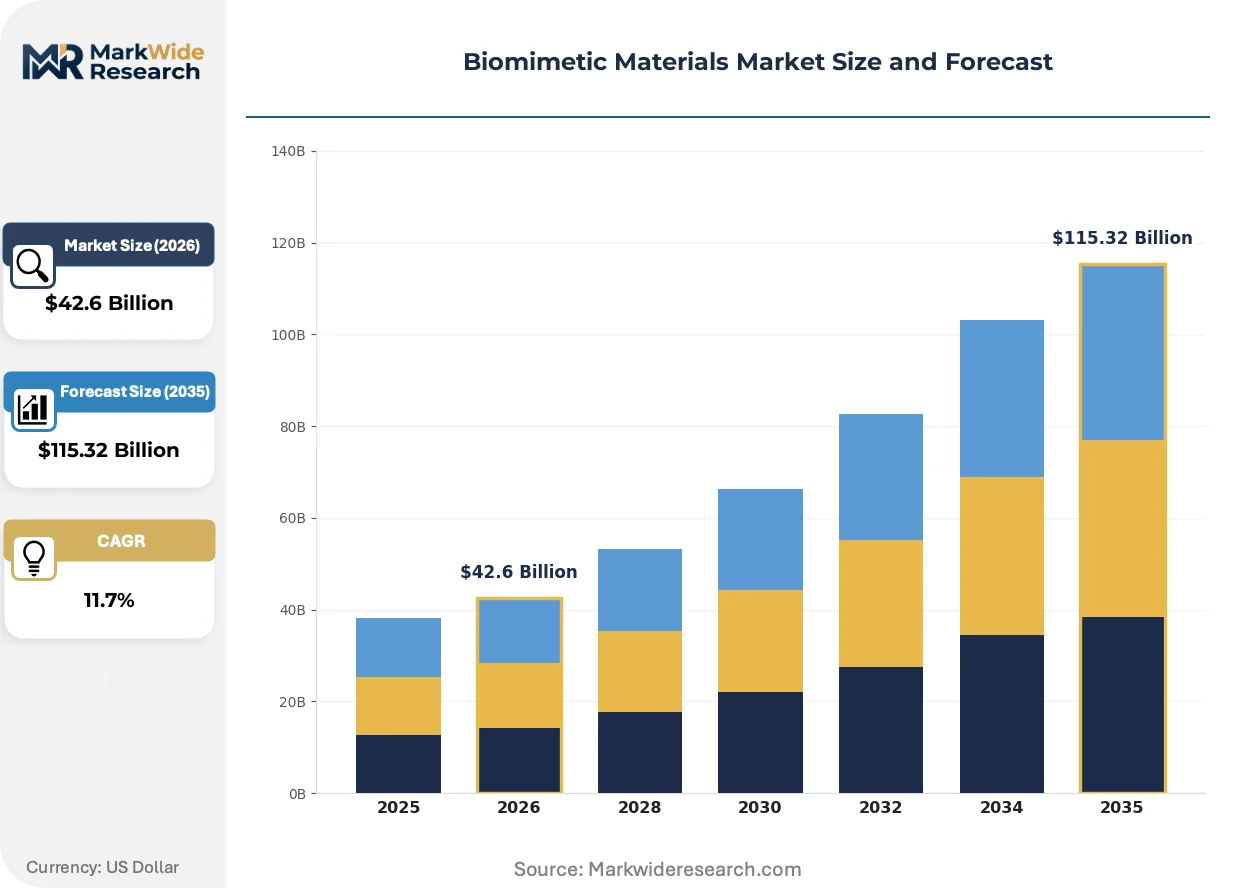
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $115.32 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Hydrogels, Nanocomposites, Polymer Blends, Bioadhesives, Bioceramics Technology: Electrospinning, 3D Bioprinting, Self-Assembly, Molecular Imprinting, Surface Modification Application: Tissue Engineering, Drug Delivery, Wound Healing, Dental Restoration, Prosthetics End User: Research Institutes, Contract Manufacturers, Medical Device Producers, Pharmaceutical Companies, Academic Labs |
| Companies Covered | Evonik Industries AG, DSM Engineering Plastics, BASF SE, Zimmer Biomet, Kyocera Corporation, Covestro AG, 3M Company, CeramTec GmbH, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomimetic Materials Market Strategic Shifts & Innovations
A fundamental shift from passive biocompatibility toward active bio-integration defines the market's innovation trajectory. New materials are engineered not just to be tolerated by the body, but to actively direct and participate in biological processes like tissue regeneration and healing.
Four-dimensional (4D) bioprinting creates structures that can change their shape or function over time in response to physiological stimuli. This technology is being explored by advanced R&D teams for creating dynamic scaffolds for complex tissue regeneration. 4D bioprinting is absorbing the limitations of static 3D-printed constructs, enabling materials that can mature and adapt in sync with host tissue post-implantation.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on the entire lifecycle of medical products. This regulation requires manufacturers to provide more extensive clinical evidence and conduct rigorous post-market surveillance for implantable devices. Material developers targeting the EU now face longer validation cycles and must generate more comprehensive long-term safety data, directly impacting project costs and timelines.
A clear preference shift is underway within specialized medical device research clusters towards prioritizing long-term clinical outcome data over initial material cost. This model disrupts procurement based on simple material specifications, favoring suppliers who provide comprehensive datasets on in-vivo performance and biocompatibility. The trend is most visible in the development of next-generation orthopedic and dental implants in the United States and Germany.
Biomimetic Materials Market Segmentation
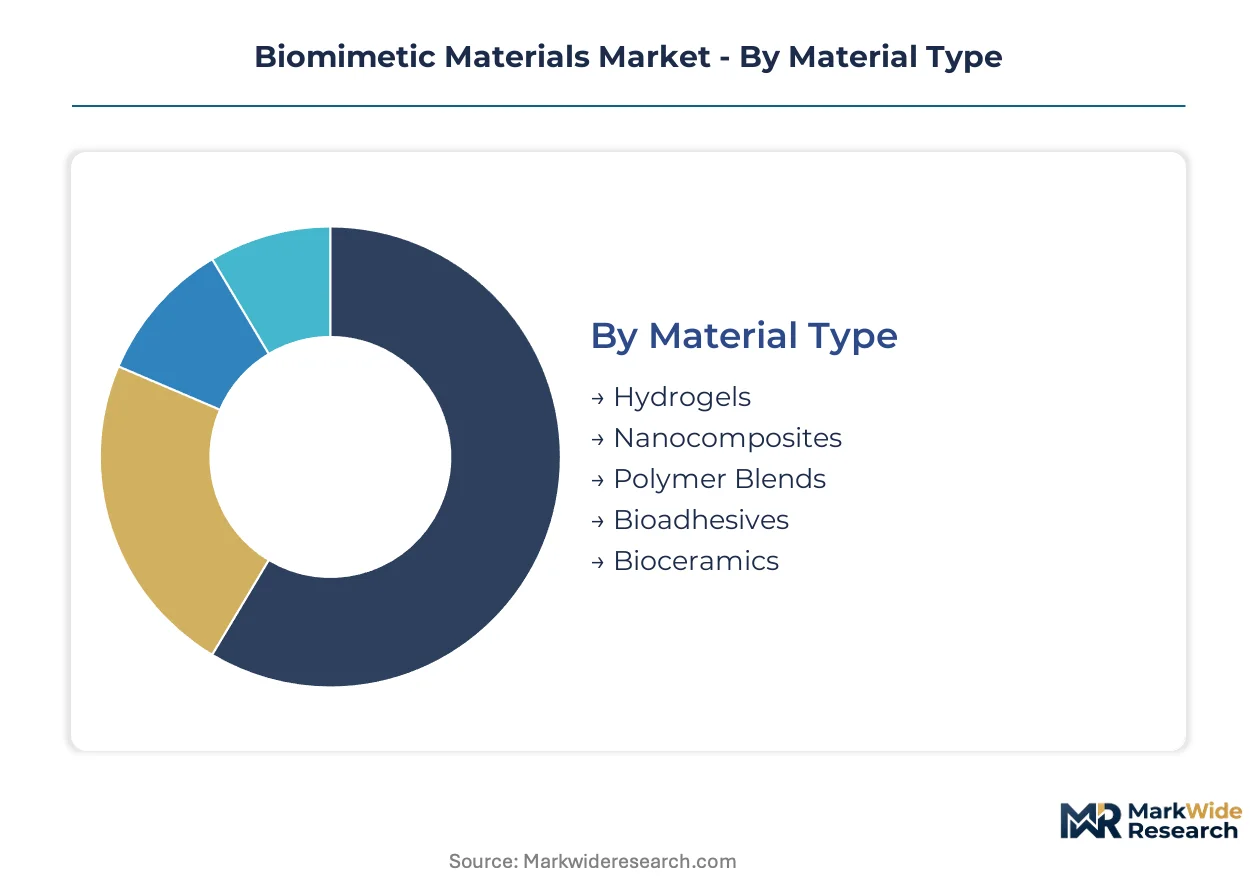
The biomimetic materials market segments across distinct material types, enabling technologies, diverse applications, and varied end-user profiles. Understanding these segments is critical for manufacturers to align product development with regulatory pathways and commercial opportunities. Each category exhibits unique performance characteristics and market dynamics.
Material Type:
Material types face varying certification burdens, with some requiring extensive biocompatibility data for FDA, EMA, or NMPA approval. High-purity compounds often undergo more stringent testing cycles than foundational polymers.
- Hydrogels:These highly hydrated polymer networks mimic natural extracellular matrices, providing a soft, flexible scaffold for cell growth and drug encapsulation. Demand concentrates within tissue engineering in the United States, driven by research into regenerative medicine.
- Nanocomposites:Combining nanoscale fillers with polymer matrices, nanocomposites offer enhanced mechanical properties and bioactivity for demanding applications. Germany's orthopedic implant sector heavily invests in these materials for improved long-term in-vivo stability.
- Polymer Blends:Mixtures of two or more polymers, these materials allow for tailored properties like strength, flexibility, and degradation rates. They find use in a broad range of medical devices, balancing performance with manufacturing feasibility.
- Bioadhesives:Designed to bond biological tissues, bioadhesives offer alternatives to sutures and staples in surgical settings. These materials require specific regulatory clearance for direct patient contact.
- Bioceramics:Inorganic, non-metallic materials like calcium phosphates or alumina, bioceramics are known for their high strength and excellent biocompatibility. They are extensively used in dental and orthopedic implants due to their bone-like properties.
Leading the category by volume: Polymer Blends. Growing fastest: Nanocomposites.
Technology:
The cost tier for biomimetic material fabrication technologies varies significantly, from high-precision, capital-intensive methods to more accessible, lower-cost surface modification techniques.
- 3D Bioprinting:This additive manufacturing technique precisely deposits biomaterials and living cells layer-by-layer to create complex 3D tissue structures. Demand is increasing in advanced research institutions in Japan for organoid development.
- Electrospinning:Electrospinning produces ultrafine fibers from polymer solutions, creating scaffolds that mimic the fibrous structure of natural extracellular matrices. This technology supports wound healing applications in Europe.
- Self-Assembly:Materials spontaneously organize into ordered structures at the molecular or supramolecular level, offering a pathway to hierarchical designs. This approach is gaining traction for creating responsive drug delivery systems.
- Molecular Imprinting:This technique creates polymer matrices with recognition sites complementary to a target molecule, enabling selective binding. Molecular imprinting supports advanced sensor development.
- Surface Modification:Altering the surface properties of materials to enhance biocompatibility or bioactivity without changing bulk properties. This method is crucial for improving implant integration.
Materials produced by electrospinning hold substantial market share. 3D bioprinting technology expands most quickly.
Application:
Supply concentration for biomimetic materials varies across applications, with established medical device sectors exhibiting more mature supply chains than nascent regenerative medicine fields.
- Tissue Engineering:This application focuses on creating functional tissues and organs using cells, scaffolds, and growth factors to repair, replace, or enhance biological function. Commercial investment is highest in the United States and Germany.
- Drug Delivery:Biomimetic materials are engineered to encapsulate and release therapeutic agents at controlled rates or in response to specific physiological cues. This area represents a significant research focus for pharmaceutical companies.
- Wound Healing:Biomimetic dressings and scaffolds promote faster and more effective healing of acute and chronic wounds by mimicking the skin's natural regenerative processes. This application sees consistent demand in healthcare systems globally.
- Dental Restoration:Materials like bioceramics and specialized polymers are used to repair or replace damaged teeth, offering biocompatibility and aesthetic properties. Japan maintains strong demand for advanced dental solutions.
- Prosthetics:Biomimetic materials enhance the functionality and comfort of prosthetic limbs and implants by improving the interface with biological tissues. This segment benefits from ongoing material science advancements.
Tissue engineering accounts for a large portion of material consumption. Drug delivery applications are gaining share fastest.
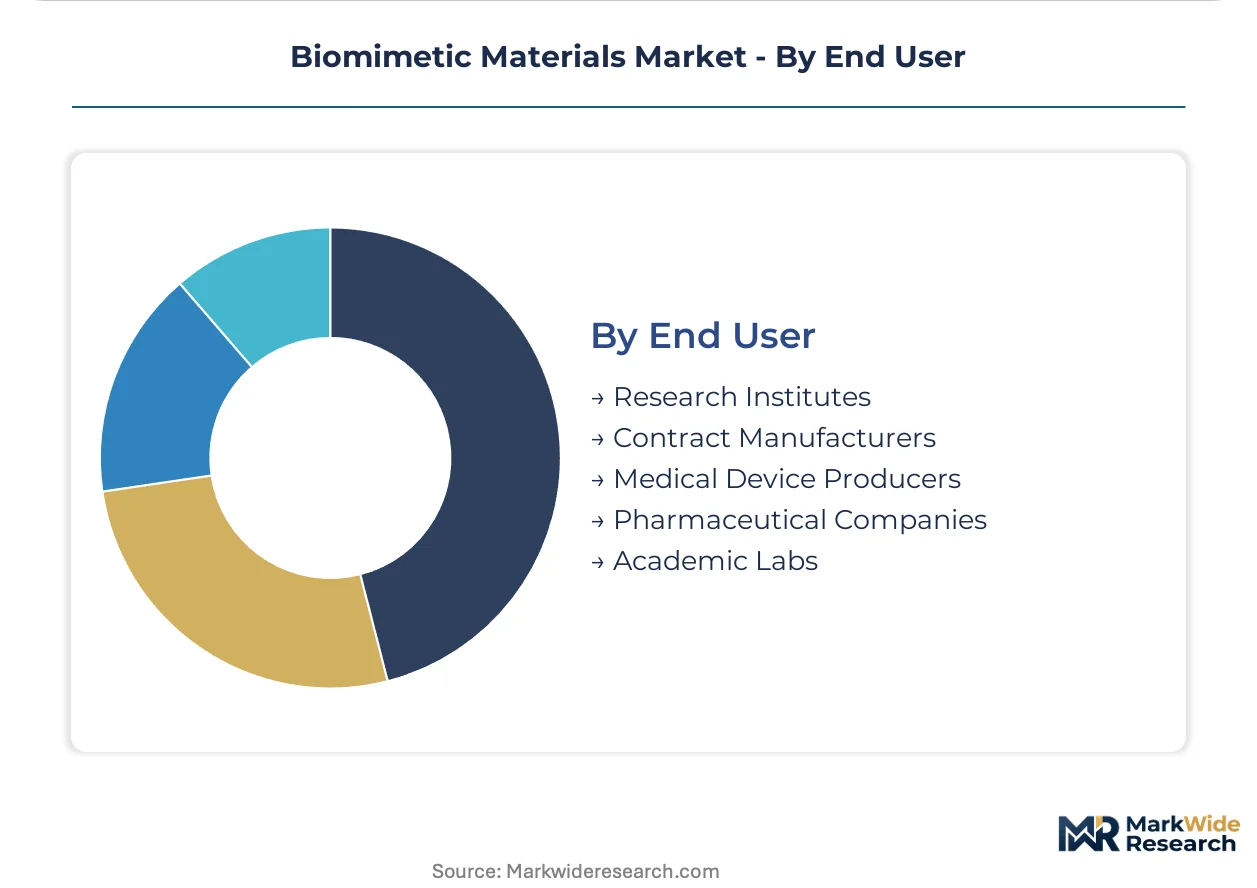
End User:
Different end-user types drive distinct procurement patterns, with medical device producers prioritizing clinical-grade materials and academic labs focusing on research-grade compounds.
- Medical Device Producers:These companies develop and manufacture a wide array of implantable and external medical devices, requiring biomimetic materials that meet stringent regulatory and performance standards. Their procurement focuses on certified, high-purity compounds.
- Pharmaceutical Companies:Focused on drug discovery, development, and manufacturing, these firms use biomimetic materials primarily for advanced drug delivery systems and in-vitro testing platforms. They seek materials for controlled release and biocompatibility.
- Research Institutes:Academic and government-funded research centers explore novel biomimetic material formulations and applications, often requiring research-grade materials for early-stage experimentation. They drive fundamental scientific advancements.
- Contract Manufacturers:These firms produce components or finished devices for other companies, often managing complex supply chains for specialized biomimetic materials. They require scalable and consistent material supply.
- Academic Labs:University laboratories conduct basic and applied research into biomaterials, contributing to the foundational knowledge base. Their material needs are diverse, supporting various experimental setups.
Medical device producers represent the largest customer type. Pharmaceutical companies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston medical technology hub drives significant biomimetic materials innovation, particularly in advanced hydrogel systems. This concentration of research institutions and biotech firms fosters a dynamic environment for new material development. Global demand for biomimetic solutions concentrates within established and emerging medical device clusters.
United States
The United States generates substantial demand for tissue engineering applications and regenerative medicine research. The FDA's Breakthrough Devices Program expedites review for novel biomimetic solutions offering clinical advantages. Boston's prominent medical technology hub actively develops advanced hydrogel systems for complex biological interactions.
Germany
Germany's advanced healthcare system requires durable and biocompatible orthopedic and dental implants. The European Union's Medical Device Regulation (MDR) governs material validation and market access. Munich's biomedical research parks specialize in nanocomposite innovation for improved long-term in-vivo stability and performance.
Japan
Japan maintains strong demand for advanced dental solutions and organoid development within its leading research institutions. The PMDA offers accelerated review pathways for innovative medical devices. Osaka's vibrant life science clusters lead advancements in 3D bioprinting technology for complex tissue structures.
South Korea
South Korea's robust biomedical research infrastructure fuels demand for smart implant development and active bio-integration materials. The MFDS actively supports biomaterial innovation through various national initiatives. Seoul's leading research institutions focus on responsive drug delivery systems and next-generation implantable devices.
Australia
Australia presents an emerging market with strong medical research infrastructure, seeking less saturated growth pathways. The TGA streamlines approval processes for novel medical technologies, encouraging early market entry. Melbourne's bio-innovation precincts develop advanced wound healing applications and regenerative scaffolds.
Biomimetic Materials Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the biomimetic materials market, influencing supply chain dynamics. The market structure exhibits a tiered consolidation, with large chemical conglomerates providing foundational polymers for various applications. Strategic archetypes include diversified chemical suppliers, specialized medical device component manufacturers, and advanced material blend providers. Key competitive moves involve strategic partnerships for application development and portfolio diversification into high-purity clinical grades to meet stringent regulatory demands.
Within the specialized medical implant archetype, Zimmer Biomet represents a key player, focusing on biocompatible materials for orthopedic and dental applications demanding long-term in-vivo stability. BASF SE, a German-based chemical conglomerate, exemplifies a foundational polymer supplier, leveraging its vast chemical production scale to supply a wide range of biomimetic formulations. DuPont de Nemours, Inc., an American multinational, occupies a position as a provider of advanced polymer blends for medical device manufacturing, competing with tailored solutions for specific medical applications.
| Leading Market Players |
|---|
| Evonik Industries AG |
| DSM Engineering Plastics |
| BASF SE |
| Zimmer Biomet |
| Kyocera Corporation |
| Covestro AG |
| 3M Company |
| CeramTec GmbH |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
The specialized medical device research clusters' preference for long-term clinical outcome data over initial material cost forces suppliers to provide comprehensive in-vivo performance datasets, which in turn influences pricing models for advanced biomimetic compounds.
Pricing Analysis
Value-based pricing, anchored to clinical outcome data and long-term in-vivo stability, characterizes the market for high-purity biomimetic materials. Price differentiation stems from rigorous certification levels, such as FDA or EMA approval, and the depth of proprietary clinical performance data. Pricing pressure emerges from the high R&D and validation costs associated with these advanced materials, alongside competition from lower-cost research-grade compounds. Academic labs typically exhibit the most price sensitivity, while medical device producers prioritize certified, high-performance materials.
Supply Chain Analysis
Supply of foundational polymers and specialized chemical precursors primarily draws from Germany, the United States, and Japan. Key material dependencies include high-purity hydrogels, specialized nanocomposite fillers, and biocompatible bioceramics. A structural supply chain risk arises from the stringent and often divergent regulatory hurdles mandated by agencies like the FDA, EMA, and China's NMPA, which can delay market entry. Distribution runs through direct sales channels to medical device producers and pharmaceutical companies, complemented by specialized distributors serving research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates in a technology-transition phase, with 4D bioprinting beginning to displace static 3D-printed constructs for complex tissue regeneration.
For Market Incumbents: Anticipate continued regulatory tightening by investing proactively in comprehensive clinical evidence generation and long-term post-market surveillance capabilities. Deepen strategic partnerships with specialized medical device research clusters in Germany and the United States to co-develop next-generation orthopedic and dental implants. Diversify portfolios into high-purity clinical grades to meet stringent regulatory demands, countering emerging threats from less validated, lower-cost alternatives. Focus R&D on active bio-integration materials.
For New Entrants and Emerging Players: Academic labs seeking cost-effective research-grade materials for novel applications represent an underserved buyer archetype. Target less saturated geographic markets like South Korea and Australia, which possess strong medical research infrastructure. Focus on developing advanced hydrogel systems for targeted drug delivery, leveraging a go-to-market strategy centered on specific, high-value niche applications with clearer regulatory pathways. Explore smart implant integration with micro-sensors.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized medical device component manufacturers given the market's shift towards active bio-integration and demand for long-term clinical outcome data. Long-term viability favors companies demonstrating clear clinical or performance advantages over existing solutions in regulated medical settings. The successful navigation of the European Union's Medical Device Regulation for novel implantable devices serves as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Acceleration | Streamlines market access for novel biomimetic devices in key regions like the United States. |
| Advanced Fabrication Technology Investment | Enables creation of complex, functional structures mimicking natural tissue architecture. |
| Clinical Outcome Data Generation | Establishes material credibility and performance differentiation for medical device producers. |
| Geographic Market Expansion | Captures new demand in high-growth regions with developing medical research infrastructure. |
| Targeted Drug Delivery System Development | Unlocks new revenue streams beyond structural tissue repair for pharmaceutical companies. |
Research Approach
FDA filings, EMA submissions, NMPA guidelines, and peer-reviewed academic journals formed the secondary backbone of this market analysis. This data was then triangulated with insights from primary interviews conducted with biomaterial scientists, medical device engineers, regulatory affairs specialists, and clinical researchers. A robust bottom-up and top-down approach ensured comprehensive market sizing and validation across all segments.
The analytical framework applied a bottom-up approach, aggregating market data from material type, technology, application, and end-user segments. This was cross-referenced with a top-down validation against overall industry trends and macroeconomic factors across the analysis window. Compound annual growth rates were derived from historical data and projected future demand, incorporating industry-specific inputs such as R&D spending in regenerative medicine and new medical device approvals.
Revisions become necessary when unforeseen regulatory changes, breakthroughs in competing technologies, or significant shifts in material costs materialize. Forecasts reflect assumptions documented at the time of publication, acknowledging inherent market uncertainties. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Hydroxyapatite Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Biomaterial in Surgical Mesh Market
Biomaterials
Global Medical Grade Collagen Market
Biomaterials
Chitosan-Based Biomaterials Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Bone and Joints Ingredients Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
United Kingdom Collagen Market
Biomaterials
Biodegradable Bone Graft Polymers Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Global Polymeric Biomaterials Market
Biomaterials
Crocodile Peptide Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Europe Collagen Market