
 Polyarylsulfone (PAS) Market | 2026-2036
Polyarylsulfone (PAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyarylsulfone (PAS) Market Analytics
High-performance polymer substitution for metal components in minimally invasive surgical tools is rewriting design paradigms across medical device engineering. Solvay leverages its vertically integrated sulfone chemistry platform to sustain cost advantages in virgin resin production. BASF SE anchors European supply through specialized compounding operations in Ludwigshafen. SABIC competes via differentiated high-heat formulations targeting aerospace ducting applications.
Polyarylsulfone denotes a family of amorphous thermoplastics containing aryl sulfone linkages, with glass transition temperatures typically exceeding 180 degrees Celsius and inherent flame resistance without additives, serving primarily as metal replacements in applications demanding repeated steam sterilization cycles. Medical device applications command the deepest margin pools given regulatory qualification barriers and long product lifecycles. Filtration membranes represent the fastest-growing application vector as membrane bioreactor deployments expand in municipal water treatment. Injection molding technology dominates volume throughput, though 3D printing is gaining traction for patient-specific surgical guides and prototype iterations.
The FDA enforces biocompatibility testing under ISO 10993 for permanent implant contact applications, while the EU MDR requires renewed technical documentation for legacy devices incorporating PAS components. REACH restrictions on certain plasticizers and flame retardants indirectly steer formulators toward inherently halogen-free sulfone chemistries. Stakeholders must monitor evolving PFAS regulatory proposals in the European Union, as precursor chemistries in some fluorinated processing aids face potential restriction that could disrupt established extrusion compound formulations.
Market Dynamics
The EU MDR's tightened biocompatibility documentation requirements are forcing medical device manufacturers to requalify legacy PAS components, compressing supplier switching costs and consolidating procurement toward vertically integrated resin producers with in-house regulatory affairs capabilities.
Growth Catalysts
- Steam sterilization mandates:Healthcare facilities in Germany and Switzerland are mandating reusable instrument cycles exceeding 1000 autoclave exposures, favoring PAS over polycarbonate alternatives that craze under hydrothermal stress.
- REACH plasticizer restrictions:ECHA's sunset dates for phthalate-based flexibilizers in 2025-2027 are redirecting formulators toward inherently flexible sulfone copolymers that require no external plasticizer loading.
- Membrane bioreactor deployments:Municipal water authorities in Singapore and Saudi Arabia are specifying PAS hollow-fiber membranes for anaerobic digestion processes, creating specification pull-through for high-purity resin grades.
Market Restraints
- Monomer supply concentration:Bisphenol S and 4,4'-dichlorodiphenyl sulfone production clusters in China's Jiangsu province expose compounders to single-source risk and freight rate volatility on Asia-Europe routes.
- Polyetherimide substitution:SABIC's Ultem formulations are capturing socket and connector applications below 170°C service temperatures where PAS properties exceed requirements and cost premiums cannot be justified.
- EU PFAS restriction proposals:ECHA's 2023 restriction dossier on per- and polyfluoroalkyl substances threatens fluorinated processing aids used in PAS extrusion, forcing reformulation trials that extend qualification timelines by 18-24 months.
Strategic Opportunities
- Patient-specific surgical guides:Fused filament fabrication using medical-grade PAS filaments is enabling hospital-based 3D printing labs in the US and Germany to produce sterilizable drill guides without centralized molding infrastructure.
- India PLI scheme alignment:The country's production-linked incentive scheme for medical devices is attracting contract manufacturers to set up PAS conversion facilities in Andhra Pradesh and Gujarat to serve domestic orthopedic implant demand.
- CE-MDR technical file consolidation:Specialist polymer distributors in the Netherlands and Denmark are building regulatory documentation libraries that reduce OEM burden for legacy device recertification, capturing margin through value-added services.
Industry Challenges
- ISO 10993-18 testing backlog:Contract laboratories in the US and EU are reporting 9-12 month queues for chemical characterization of PAS extractables, delaying new device submissions and freezing R&D pipelines.
- Compounding asset specificity:Twin-screw extrusion lines configured for PAS require corrosion-resistant barrel metallurgy and devolatilization stages that cannot be redeployed to commodity polymers, stranding capital during demand troughs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyarylsulfone (PAS) Market |
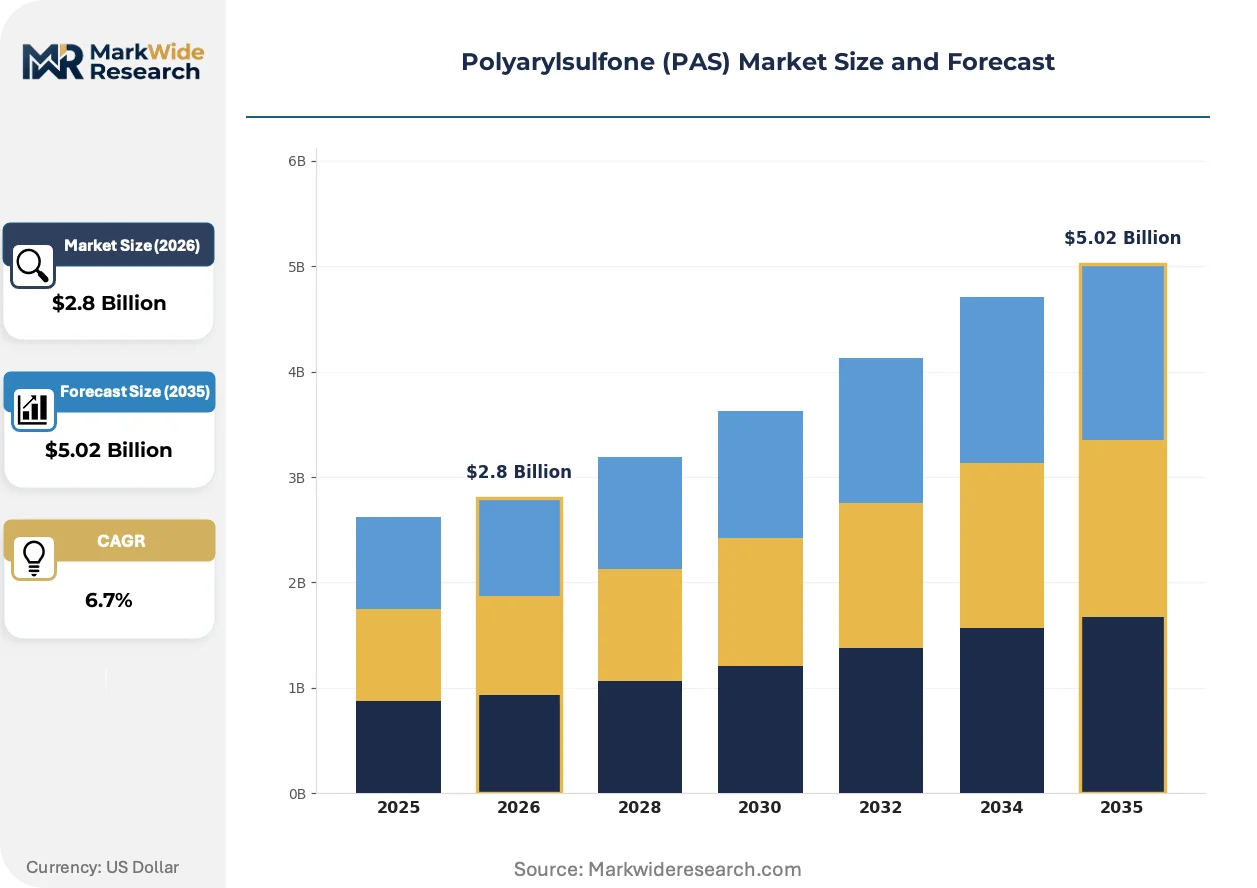
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Pellets, Sheets, Films End User: Aerospace, Automotive, Electronics, Healthcare Application: Filtration, Medical Devices, Insulation, Coatings Technology: Injection Molding, 3D Printing, Extrusion, Thermoforming |
| Companies Covered | Solvay, BASF SE, SABIC, Sumitomo Chemical Co., Ltd., Evonik Industries AG, Mitsubishi Chemical Advanced Materials, Ensinger, RTP Company, Quadrant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyarylsulfone (PAS) Market Evolving Landscape
Additive manufacturing workflows are collapsing the traditional tooling-to-production timeline for surgical instrument prototypes, enabling same-week design iterations that were previously gated by 12-week injection mold fabrication cycles.
High-heat laser sintering of PAS powders is collapsing the minimum viable production threshold for complex geometries like multi-lumen suction-irrigation tools, allowing device startups in Massachusetts and Baden-Württemberg to bypass capital-intensive mold investments entirely. Hospital procurement committees are accepting printed instruments for sterilization validation trials that previously required 10,000-unit molded samples.
REACH authorization requirements for di(2-ethylhexyl) phthalate are forcing compounders to eliminate external flexibilizers from medical-grade formulations. The regulation is compressing the approved substance list for implantable device contact, driving reformulation toward inherently ductile sulfone copolymers with 40% higher raw material costs. German notified bodies are prioritizing technical file reviews for halogen-free PAS variants that preempt future restriction expansions.
Buying committees at US hospital networks are consolidating polymer specifications across instrument lines to reduce sterilization validation burden, displacing fragmented supplier relationships with single-source PAS contracts covering 15-20 SKUs. Group purchasing organizations in the Midwest are awarding multi-year agreements to resin producers with captive compounding and regulatory documentation capabilities, squeezing independent distributors from the value chain.
Polyarylsulfone (PAS) Market Segmentation
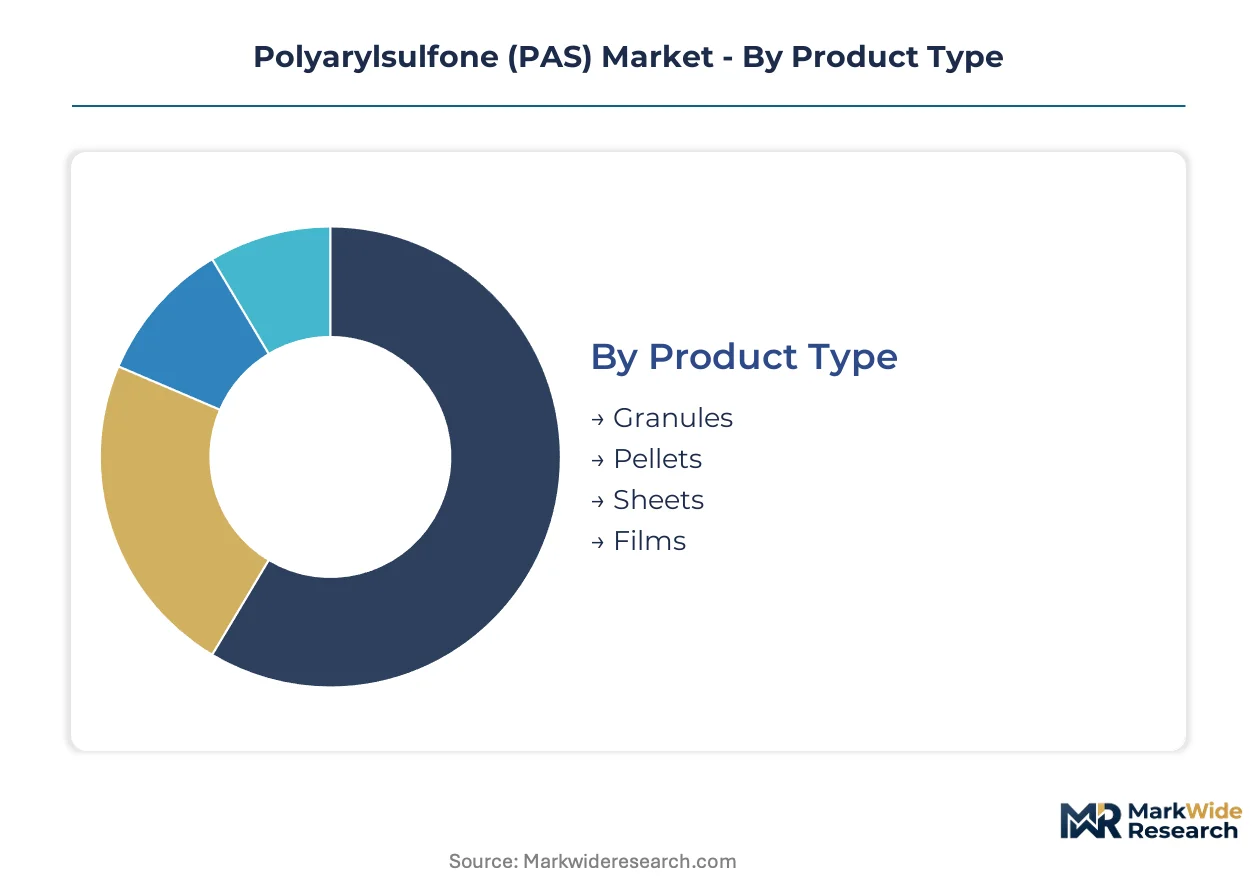
Segmentation in the PAS market reveals distinct margin pools tied to regulatory qualification intensity and processing technology barriers. Medical-grade specifications command premium positioning, while industrial applications compete on thermal performance and lot-to-lot consistency.
Product Type:
Mature formats dominate current procurement volumes, though emerging geometries are reshaping specification workflows across device engineering teams.
- Granules:Virgin resin supplied in bulk granular form serves high-volume injection molding operations with stringent lot traceability requirements. German medical device manufacturers in the Freiburg corridor specify granules for reusable surgical instrument production, driven by EU MDR documentation mandates for raw material genealogy.
- Pellets:Compounded pellets incorporate colorants, radiopaque fillers, or impact modifiers prior to conversion. Demand concentrates in US orthopedic implant housings where FDA biocompatibility testing under ISO 10993-18 necessitates pre-validated masterbatch integration.
- Sheets:Compression-molded sheet stock enables thermoformed instrument trays and sterilization containers. Swiss hospital procurement networks specify sulfone sheet grades for autoclave-compatible case systems.
- Films:Thin-gauge extruded films serve membrane bioreactor applications and flexible medical packaging. Singaporean water authorities drive specification pull-through for hollow-fiber membrane substrates.
Granules retain volume leadership; films hold the steepest expansion curve.
End User:
Application-driven cost tiers separate implant-grade qualifications from industrial thermal management specifications.
- Healthcare:Permanent implant contact applications demand ISO 10993-5 cytotoxicity clearance and extractables characterization. Freiburg and Tuttlingen device clusters anchor European demand for steam-sterilizable instrument grades.
- Aerospace:Ducting and interior components require FAA flammability compliance (25.853) combined with 180°C continuous service capability. Saudi Arabian airline retrofit programs specify high-heat PAS formulations for cabin air management systems.
- Automotive:Under-hood electrical connectors and sensor housings compete against polyetherimide on cost-performance metrics. German EV battery module manufacturers evaluate sulfone copolymers for thermal runaway barriers.
- Electronics:Connector bodies and circuit board hardware prioritize dimensional stability across reflow soldering temperatures. Japanese semiconductor equipment builders specify low-outgassing grades for vacuum chamber components.
Healthcare commands the deepest margin tier; aerospace delivers the most stable specification pull-through.
Application:
Volume concentration diverges sharply between regulatory-locked medical devices and infrastructure-scale filtration deployments.
- Medical Devices:Reusable surgical instruments, implantable component housings, and sterilization cases require repeated autoclave exposure exceeding 1000 cycles. FDA enforcement of biocompatibility testing timelines has compressed supplier qualification windows to 18-24 months.
- Filtration:Membrane bioreactor hollow fibers and pharmaceutical process filtration cartridges represent the application category gaining share fastest. Municipal water authorities in Saudi Arabia and Singapore specify PAS membranes for anaerobic digestion and desalination pretreatment.
- Insulation:Wire and cable jacketing for high-temperature industrial environments competes with fluoropolymer alternatives on halogen-free positioning. REACH restrictions on flame-retardant additives steer formulators toward inherently fire-resistant sulfone chemistries.
- Coatings:Powder and liquid formulations for corrosion protection in chemical processing equipment remain a niche specification. German chemical plant operators specify sulfone-based coatings for sulfuric acid handling infrastructure.
Medical devices retain revenue concentration; filtration is expanding most quickly.
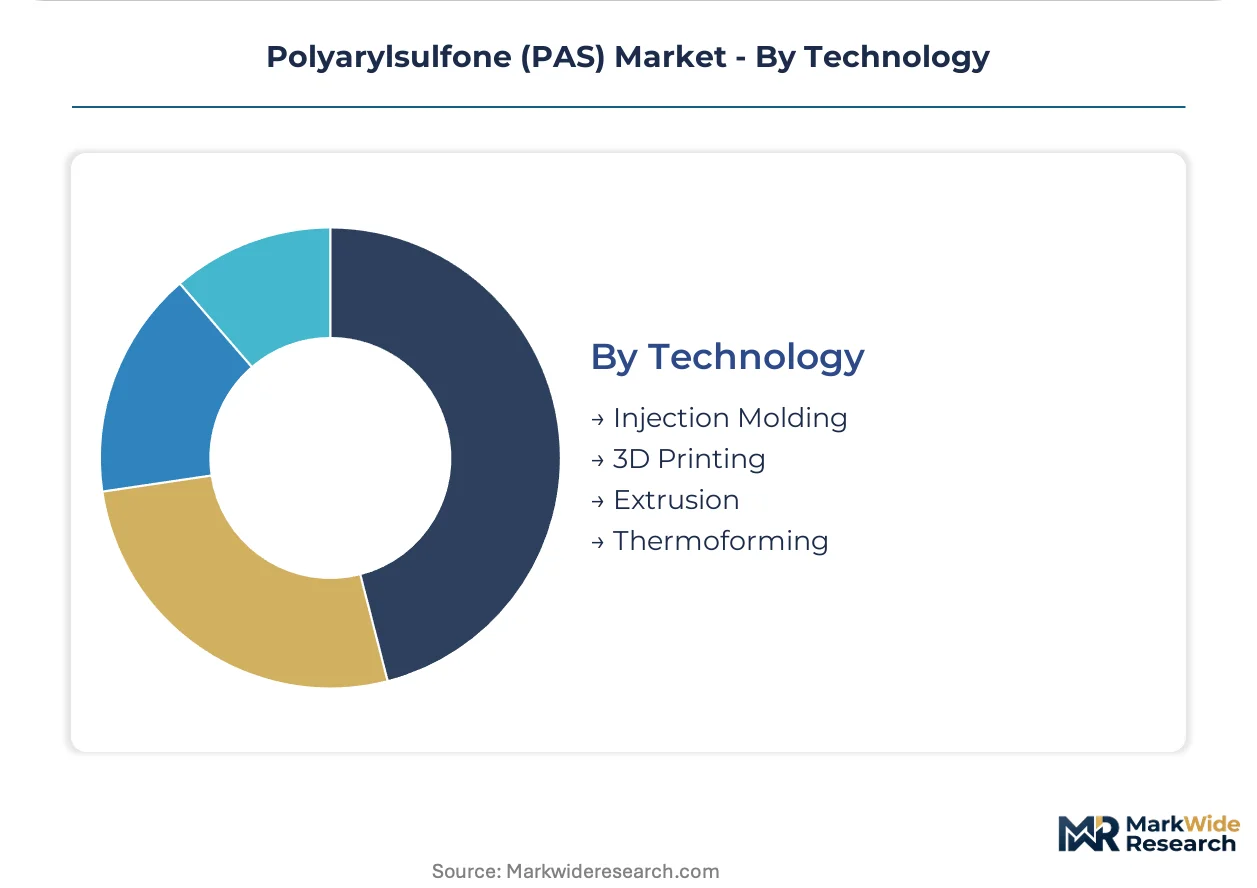
Technology:
Processing method selection locks in capital equipment specificity and determines minimum viable production scale.
- Injection Molding:High-pressure molding of granules and pellets dominates medical device throughput, with tool steel requirements for sulfone processing limiting mold fabrication to specialized suppliers. Twin-screw compounding lines configured for PAS require corrosion-resistant barrel metallurgy that cannot be redeployed to commodity polymers.
- Extrusion:Profile, sheet, and film extrusion serves filtration membrane substrates and electrical insulation. ECHA's PFAS restriction proposals threaten fluorinated processing aids used in PAS extrusion, forcing 18-24 month reformulation trials.
- 3D Printing:Fused filament fabrication and laser sintering enable patient-specific surgical guides without centralized molding infrastructure. Hospital-based printing labs in Massachusetts and Baden-Württemberg bypass 12-week mold fabrication cycles.
- Thermoforming:Sheet-based forming of sterilization trays and instrument cases serves mid-volume device lines. Swiss healthcare procurement committees accept thermoformed cases for validation trials that previously required injection-molded samples.
Injection molding retains volume leadership; 3D printing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu province exports bisphenol S and 4,4'-dichlorodiphenyl sulfone monomers to European compounders, creating a concentrated Asia-to-Europe trade corridor that exposes downstream processors to freight volatility and single-source risk.
United States
FDA enforcement of ISO 10993-18 chemical characterization timelines has compressed supplier qualification windows to 18-24 months for implantable device applications. Hospital procurement committees in the Midwest are consolidating polymer specifications across instrument lines, awarding multi-year agreements to resin producers with captive compounding capabilities. Massachusetts device startups leverage 3D printing workflows to bypass traditional mold fabrication cycles.
Germany
EU MDR documentation mandates for raw material genealogy drive granule specifications from Freiburg and Tuttlingen medical device clusters. ECHA's REACH sunset dates for phthalate-based flexibilizers redirect formulators toward inherently flexible sulfone copolymers. Baden-Württemberg hospital-based printing labs produce patient-specific surgical guides without centralized molding infrastructure.
Switzerland
Swissmedic oversight of biocompatibility testing aligns with EU MDR technical file requirements for steam-sterilizable instrument grades. Healthcare procurement networks specify sulfone sheet grades for autoclave-compatible case systems. Swiss hospital committees accept thermoformed cases for validation trials that previously required injection-molded samples.
Singapore
Municipal water authorities specify PAS hollow-fiber membranes for anaerobic digestion and desalination pretreatment processes. The country's national standards body coordinates with membrane bioreactor deployers to establish high-purity resin grade specifications. Advanced manufacturing parks host filtration module assembly operations serving Southeast Asian infrastructure projects.
Saudi Arabia
Airline retrofit programs specify high-heat PAS formulations for cabin air management systems under national aviation authority guidance. Municipal water authorities deploy membrane bioreactor systems with PAS hollow-fiber substrates for anaerobic digestion. Industrial cities in the Eastern Province evaluate sulfone-based coatings for chemical processing infrastructure.
Polyarylsulfone (PAS) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Vertically integrated resin producers with in-house regulatory affairs capabilities capture procurement consolidation from hospital group purchasing organizations. Mid-scale compounders occupy specification-driven niches requiring corrosion-resistant extrusion assets. Distributors building technical documentation libraries capture margin through value-added services. Competitive moves center on M&A to secure monomer supply and capacity expansion in medical-grade compounding.
Among European chemical conglomerates, Solvay and BASF SE exemplify the integrated-resin-producer archetype with captive sulfone chemistry platforms. SABIC represents the differentiated-formulation specialist competing via high-heat grades for thermal management applications. These three anchors demonstrate how geographic concentration of production assets and regulatory documentation capabilities determine procurement access in medical device supply chains.
| Leading Market Players |
|---|
| Solvay |
| BASF SE |
| SABIC |
| Sumitomo Chemical Co., Ltd. |
| Evonik Industries AG |
| Mitsubishi Chemical Advanced Materials |
| Ensinger |
| RTP Company |
| Quadrant AG |
| Others |
Value Network & Pricing Analysis
Jiangsu province's bisphenol S and 4,4'-dichlorodiphenyl sulfone production clusters dictate downstream pricing leverage for European compounders, with freight volatility on Asia-Europe routes amplifying margin pressure during demand surges. Hospital group purchasing organizations exploit this concentration by awarding multi-year contracts to vertically integrated resin producers with captive regulatory documentation capabilities.
Pricing Analysis
Injection-molded granule pricing diverges sharply from 3D-printed filament and laser-sintered powder tiers, with medical-grade specifications commanding substantial premiums over industrial thermal management grades. Three-tier pricing structure across premium implant-grade, standard instrument-grade, and economy industrial-grade levels reflects ISO 10993-18 testing burden and lot traceability investments. Cost compression in standard instrument-grade segments is intensifying because polyetherimide substitutes capture sub-170°C applications. Orthopedic implant manufacturers exhibit lowest price sensitivity due to regulatory qualification lock-in, while automotive connector buyers drive hardest bargain comparisons against Ultem formulations.
Supply Chain Analysis
Extended payment terms from German medical device manufacturers strain working capital for mid-scale compounders lacking supply-chain finance facilities. Raw material sourcing draws from China's Jiangsu province for monomers, Belgium for specialized catalysts, and Germany for compounding equipment. Bisphenol S supply concentration in Jiangsu creates single-source vulnerability exacerbated by Asia-Europe freight rate volatility. Distribution runs through specialized polymer distributors in the Netherlands and Denmark building regulatory documentation libraries, bypassing traditional merchant resin channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical file consolidation services and sterilization validation support contracts expand faster than virgin resin volumes, transforming procurement relationships from transactional supply to embedded regulatory partnerships.
For Market Incumbents: Entrench position through backward integration into bisphenol S monomer production and capacity expansion in Freiburg-Tuttlingen corridor to serve EU MDR requalification waves. Polyetherimide substitution below 170°C threatens standard-grade margins; defend through captive compounding assets and pre-validated masterbatch integration that accelerates OEM qualification timelines. For New Entrants and Emerging Players: India's Andhra Pradesh and Gujarat medical device manufacturing zones offer underpenetration for PAS conversion facilities aligned with PLI scheme incentives. Target membrane bioreactor hollow-fiber substrates for Singaporean and Saudi Arabian municipal water authorities, where specification pull-through creates entrée without competing against entrenched instrument-grade incumbents. Lead with regulatory documentation partnerships rather than price undercutting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with orphaned sulfone chemistry platforms lacking medical-grade regulatory affairs investment. Five-to-ten-year viability hinges on PFAS restriction outcomes and steam sterilization mandate expansion beyond German-speaking Europe. Monitor ECHA restriction dossier implementation timelines as inflection indicator for processing aid reformulation costs and qualification timeline extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Jiangsu supply concentration creates acquisition rationale for bisphenol S asset control. |
| Medical-Grade Compounding Capacity Expansion | Freiburg corridor demand absorbs dedicated corrosion-resistant extrusion line investments. |
| Regulatory Documentation Library Buildout | Netherlands and Denmark distributors capture CE-MDR technical file consolidation margins. |
| 3D Printing Filament Qualification | Massachusetts and Baden-Württemberg hospital labs bypass mold fabrication capital barriers. |
| Halogen-Free Formulation Preemptive Launch | German notified bodies prioritize technical file reviews for REACH-aligned sulfone variants. |
Research Methodology
Cross-validation between primary interviews with resin plant managers, medical device procurement leads, and biomedical engineers and secondary validation through FDA 510(k) filings, ECHA restriction dossiers, and customs trade data anchors the qualitative findings. Bottom-up triangulation across injection molding throughput estimates, extrusion line capacity utilization, and 3D printing filament shipment volumes reconciles with top-down healthcare expenditure allocation models.
Calibration against historical qualification timeline compression and steam sterilization cycle durability benchmarks shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end-use industry, application category, and processing technology. CAGRs derive from installed base replacement dynamics and specification pull-through coefficients for membrane bioreactor deployments. Forecast inputs incorporate EU MDR transition completion rates and ECHA PFAS restriction implementation scenarios.
Practitioners should monitor monomer supply disruptions, freight rate volatility spikes, and notified body capacity constraints for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Asia Pacific Waterproofing Membrane Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membranes Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Global Ion Exchange Membrane Market