
 Global Processed Pork Meat Market | 2026-2036
Global Processed Pork Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Processed Pork Meat Market Foresight
Subscription-based cold-chain monitoring and software-defined shelf-life tracking is broadening what processors sell beyond the physical cut. WH Group Limited leverages captive hog farming across multiple continents to control raw material flow. JBS SA anchors its position through massive slaughter and processing scale in Brazil and the United States. Tyson Foods Inc. differentiates via integrated feed-to-retail operations that compress cost structures.
Processed pork meat encompasses muscle tissue from swine that has undergone curing, smoking, fermentation, thermal processing, or mechanical restructuring to achieve extended shelf stability, standardized portioning, or flavor profiles; typical formulations specify maximum moisture-to-protein ratios and residual nitrite levels below regulatory ceilings. The primary commercial purpose centers on converting perishable fresh pork into storable, transportable products for distant retail and foodservice deployment. Bacon and sausages occupy the largest revenue pools due to breakfast menu ubiquity and grab-and-go retail penetration, while salami commands premium margins through artisan positioning and extended aging protocols. Flexible pouches and vacuum packs are displacing rigid trays as brands chase logistics efficiency and reduced plastic tonnage per unit shipped.
FDA hazard analysis mandates and USDA pathogen reduction standards govern American processing facilities, while EFSA residue limits and EU Green Deal methane benchmarks constrain European operations. China's SAMR enforces GB standards for additive use and labeling transparency, tightening market access for unverified imports. Stakeholders must monitor diverging carbon accounting rules across the United States, European Union, and China as these frameworks increasingly embed into procurement contracts and trade eligibility criteria.
Market Dynamics
Dual carbon mandates from China's MEE and the EU Green Deal are forcing processors to reconfigure energy-intensive curing and smoking operations, while cold-chain digitization creates new service revenue layers beyond physical product sales.
Growth Catalysts
- Quick service restaurant expansion:Fast-casual chains in Brazil and Southeast Asia are diversifying breakfast and all-day protein menus, driving contract volumes for pre-cooked bacon and portion-controlled sausage links.
- EU Green Deal methane benchmarks:These standards accelerate biogas capture investments at slaughter facilities, lowering Scope 1 emissions for integrated processors and unlocking preferential procurement terms with European retail banners.
- High-pressure processing (HPP):This non-thermal pasteurization technology extends refrigerated shelf life without nitrite spikes, opening clean-label positioning for premium deli meats in North American natural channel retail.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with Black Sea supply disruptions, compressing margins for non-integrated processors lacking captive feed milling operations.
- Brazilian slaughter concentration:Three southern states dominate hog processing capacity, creating logistics bottlenecks and regional price dislocation when plant downtime occurs.
- Plant-based protein substitution:Mycoprotein and pea-protein breakfast strips are capturing shelf space in UK and German retail, pressuring mid-tier processed pork pricing in those markets.
Strategic Opportunities
- Subscription cold-chain monitoring:IoT sensor-as-a-service models let processors sell temperature-integrity data to retail and foodservice buyers, creating recurring revenue independent of commodity cut prices.
- Vietnam foodservice penetration:Underdeveloped cold-chain infrastructure in secondary Vietnamese cities creates first-mover advantage for processors building localized curing and distribution partnerships.
- USDA BioPreferred procurement mandates:Federal foodservice contracts now require bio-based packaging percentages, favoring processors with compostable casing and tray investments.
Industry Challenges
- HACCP system revalidation timelines:FDA hazard analysis updates require 18-24 month documentation overhauls at multi-plant operators, diverting technical resources from line optimization projects.
- Legacy ERP integration with blockchain traceability:Batch-level genealogy systems for EFSA compliance demand middleware development that strains IT budgets at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Processed Pork Meat Market |
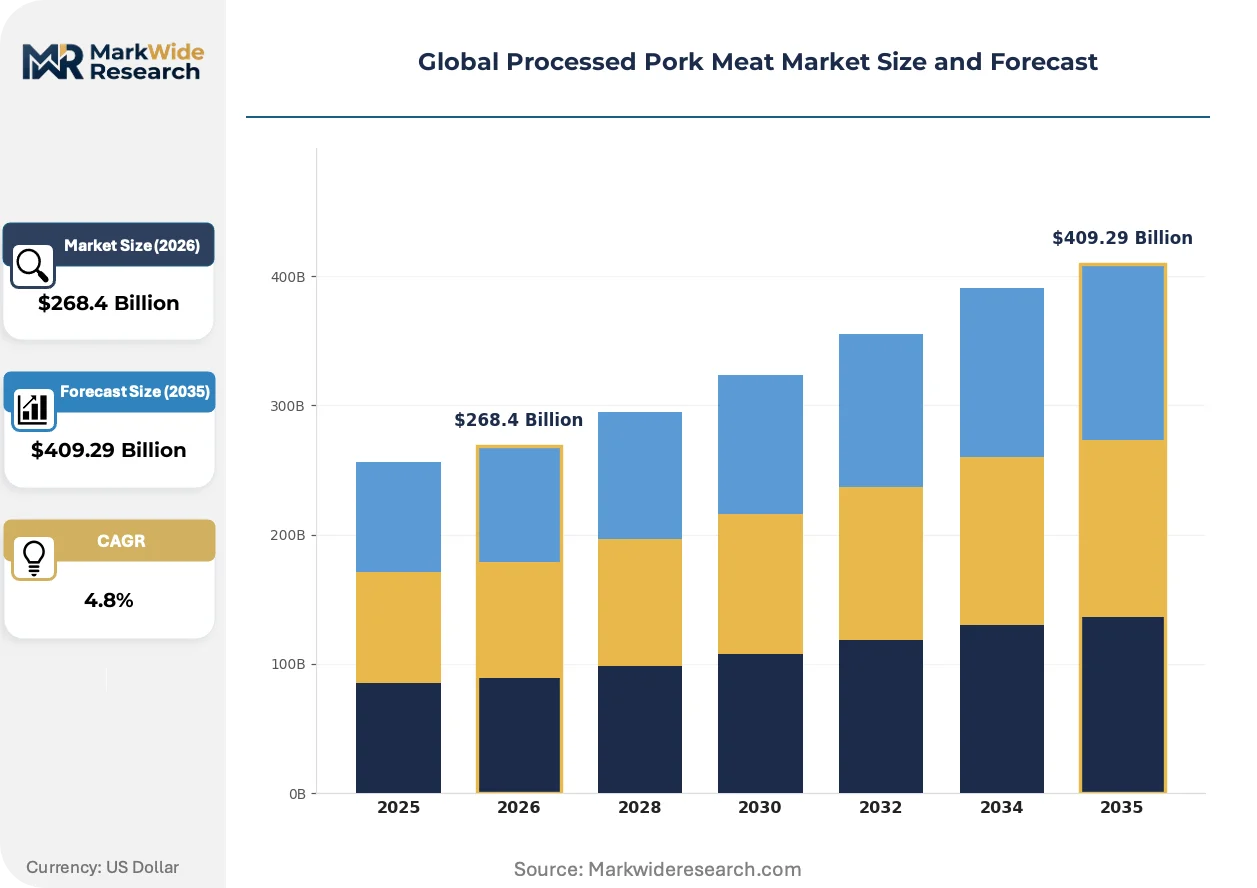
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $409.29 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacon, Sausages, Ham, Luncheon Meat, Salami, Meatballs Packaging Type: Vacuum Packs, Cans, Trays, Flexible Pouches, Jarred, Wrapped End User: Food Service, Retail Chains, Meat Processors, Caterers, Institutions, Quick Service Restaurants Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Wholesale Markets, Foodservice Distributors |
| Companies Covered | WH Group Limited, JBS SA, Tyson Foods Inc., Danish Crown A/S, Hormel Foods Corporation, Smithfield Foods Inc., Sysco Corporation, Clemens Food Group, COFCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Processed Pork Meat Market Shifts & Advancements
Digital shelf-life prediction and automated portioning are compressing waste metrics while regulatory carbon accounting forces transparency through the value chain.
Machine vision grading systems are integrating with robotic cutting cells to standardize lean-to-fat ratios in real time. Brazilian and US packers deploying this technology report yield improvements of several percentage points. The structural consequence is that quality consistency is integrating with labor cost reduction, enabling smaller plants to compete on specification precision previously requiring massive scale.
China's SAMR is tightening GB standard enforcement for residual nitrite labeling, requiring third-party laboratory verification for all imported processed pork. This policy compresses market access timelines for exporters lacking pre-certified documentation. European artisan salami producers are responding by establishing dedicated Chinese-label product lines with reduced nitrite formulations and Mandarin-compliant packaging.
Foodservice distributors are unbundling procurement from logistics, allowing independent restaurants to source processed pork directly from regional processors while paying separately for last-mile cold-chain delivery. This disintermediation is most visible in South Korean urban clusters, where cloud-kitchen density supports micro-batch ordering patterns that bypass traditional broadline warehouse networks.
Global Processed Pork Meat Market Segmentation
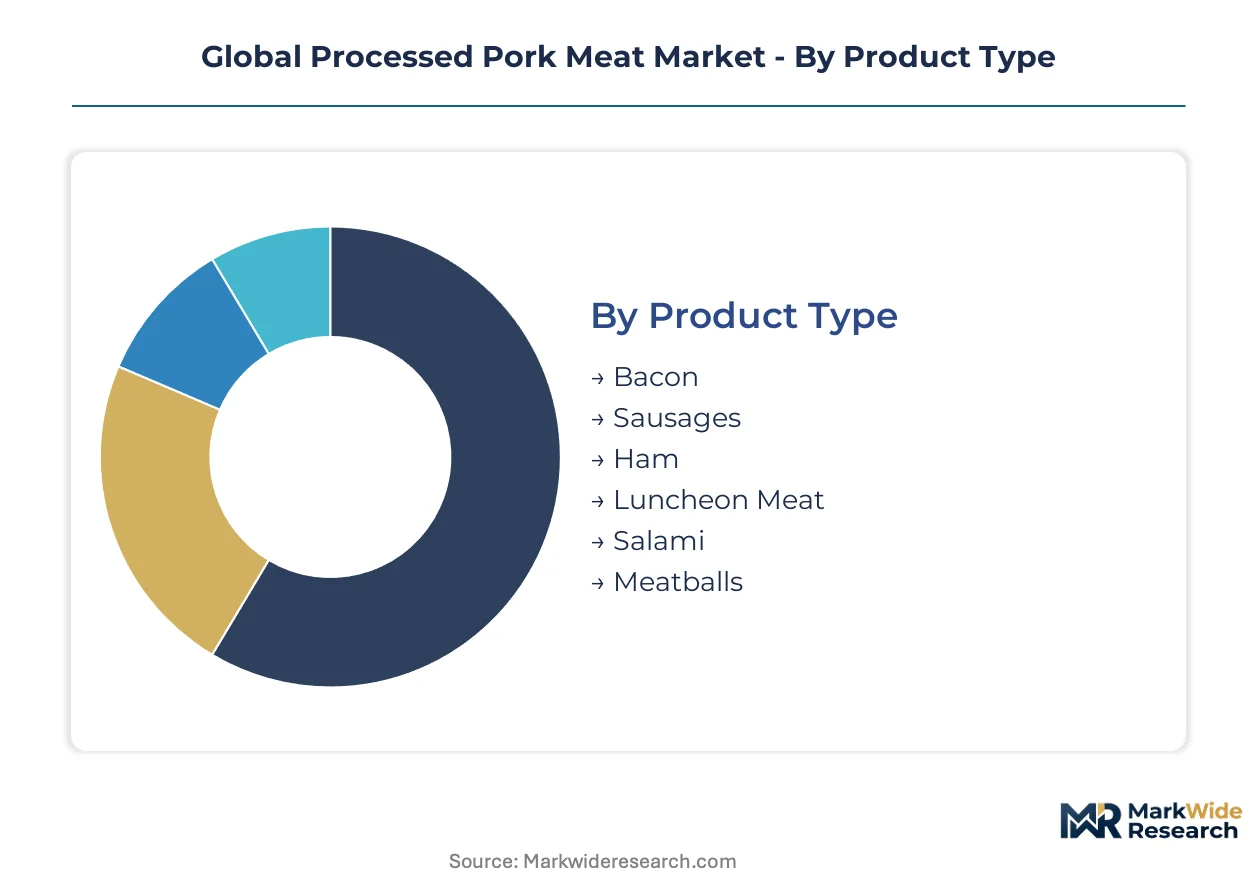
Processed pork meat segmentation reveals how curing methods, portioning formats, and channel economics split value capture across the supply chain. Product type determines margin structure while packaging and distribution choices shape logistics cost profiles and shelf-life positioning.
Product Type:
Volume leaders dominate breakfast and sandwich applications while premium segments command aging-intensive production cycles and specialized retail placement.
- Bacon:Cured and smoked belly strips standardized for foodservice portioning and retail breakfast positioning. Quick service restaurants in Brazil and the United States drive contract volumes for pre-cooked formats with consistent slice counts.
- Sausages:Ground pork emulsions stuffed into natural or collagen casings, ranging from fresh breakfast links to fermented dry varieties. German and Polish retail banners sustain demand for traditional coarse-ground formulations despite plant-based substitution pressure.
- Ham:Cured whole-muscle products from pork leg, available as bone-in, boneless, or restructured deli slices. Institutional procurement in South Korean schools and hospitals favors low-sodium injected hams meeting MFDS sodium reduction guidelines.
- Luncheon Meat:Emulsified and canned pork products with extended ambient shelf stability. Southeast Asian convenience stores in Vietnam and the Philippines move high volumes of single-serve pouches for on-premise consumption.
- Salami:Fermented and dried sausages requiring controlled humidity aging for flavor development. Italian and Spanish producers capture premium positioning through Protected Designation of Origin certifications and extended curing protocols.
- Meatballs:Ground and formed pork spheres, often blended with beef or extenders, for foodservice and ready-meal integration. Swedish and Norwegian retail chains source frozen bulk packs for in-store hot counter and home cooking segments.
Today's leader: Bacon. Tomorrow's challenger: Salami.
Packaging Type:
Cost-to-performance tradeoffs in barrier properties and automation compatibility segment the market between commodity formats and premium convenience solutions.
- Vacuum Packs:Multi-layer barrier films evacuated to extend refrigerated shelf life and suppress oxidative rancidity. North American deli counter operators prefer vacuum-sliced logs for labor-efficient portioning and reduced shrink.
- Cans:Metal containers with hermetic seals enabling ambient distribution without cold-chain dependency. Military and emergency relief procurement in the United States and Japan sustues demand for shelf-stable luncheon meats and hams.
- Trays:Rigid polystyrene or PET structures with overwrap film for retail meat case presentation. UK and German supermarkets are phasing out black plastic trays in response to EFSA circular economy packaging directives.
- Flexible Pouches:Lightweight laminated films reducing plastic tonnage per unit shipped and enabling vertical retail display. Brazilian processors report logistics cost savings of 15-20 percent versus rigid alternatives on export routes.
- Jarred:Glass containers with brine or oil preservation for artisan positioning and gift market applications. Portuguese and Spanish producers package premium chorizo and morcilla in decorative jars for duty-free and specialty retail.
- Wrapped:Simple film or paper overwrap for immediate consumption formats and traditional butcher counter presentation. French charcuterie retailers maintain wrapped whole-muscle displays to emphasize craft provenance and custom slicing.
Flexible pouches are gaining share fastest as sustainability metrics embed into retail procurement scorecards.
End User:
Customer scale and technical specification requirements split demand between price-sensitive commodity buyers and premium positioning seekers.
- Food Service:Independent restaurants, hotels, and contract caterers sourcing portion-controlled formats for menu cost management. Italian and Spanish hospitality clusters demand consistent fat-to-lean ratios for carbonara and tapas applications.
- Retail Chains:Supermarket and hypermarket private-label programs requiring volume scale and promotional flexibility. Carrefour and Auchan in France specify nitrite-reduced formulations for own-brand premium lines.
- Meat Processors:Secondary processors purchasing raw cured materials for further value-added transformation. Polish and Romanian facilities blend imported hams with domestic pork for regional sausage specialties.
- Caterers:Event and institutional food providers needing ambient-stable or frozen formats for off-site service. Indian wedding caterers in Delhi and Mumbai import canned luncheon meats for vegetarian-adjacent buffet options.
- Institutions:Hospitals, schools, and prisons with strict nutritional and safety compliance requirements. South Korean and Japanese public sector tenders specify HACCP certification and antibiotic residue testing protocols.
- Quick Service Restaurants:Fast-casual and fast-food chains with standardized menu specifications and national distribution needs. McDonald's and Burger King procurement in Brazil and Mexico drives demand for pre-cooked bacon strips with defined crispiness metrics.
Quick service restaurants are climbing fastest as breakfast menu expansion accelerates across Latin American and Southeast Asian markets.
Distribution Channel:
Channel control and margin retention vary sharply between self-service retail and assisted-service foodservice routes.
- Supermarkets & Hypermarkets:Full-service retail with dedicated meat counters and refrigerated self-service cases. Walmart and Tesco in the United States and United Kingdom negotiate annual volume contracts with processor-direct pricing.
- Convenience Stores:Small-format urban retail prioritizing grab-and-go packaging and extended shelf-life formats. 7-Eleven and Lawson in Japan and Thailand stock vacuum-packed sausage slices and luncheon meat for immediate consumption.
- Online Retail:Direct-to-consumer and platform-mediated sales requiring insulated packaging and cold-chain integrity guarantees. JD.com and Tmall in China enforce SAMR temperature logging requirements for fresh and chilled pork deliveries.
- Specialty Stores:Butcher shops, delicatessens, and ethnic food retailers emphasizing provenance and craft positioning. Italian salumerias and German Metzgereien command price premiums through whole-muscle display and custom slicing.
- Wholesale Markets:Traditional bulk trading halls serving small retailers and foodservice operators in emerging markets. São Paulo's CEAGESP and Mexico City's La Nueva Viga handle unbranded cured pork for independent taquerias and lanchonetes.
- Foodservice Distributors:Broadline and specialty distributors managing last-mile cold-chain delivery to restaurants and institutions. Sysco and US Foods in North America and Bidfood in Europe bundle processed pork with protein category management services.
Foodservice distributors remain the volume anchor. Online retail shows steepest expansion trajectory as cold-chain infrastructure matures in Chinese and Indian urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon mandates and Brazil's export processing expansion demonstrate how regulatory pressure and capacity investment reshape regional trajectories differently. The United States maintains integrated feed-to-retail dominance while European operations navigate methane benchmarks. Southeast Asian foodservice penetration creates localized growth corridors.
United States
Quick service restaurant procurement drives contract volumes for pre-cooked bacon and portion-controlled sausage links. USDA pathogen reduction standards and FDA hazard analysis mandates govern multi-plant compliance documentation. Iowa and North Carolina slaughter clusters anchor domestic processing capacity with biogas capture investments lowering Scope 1 emissions.
China
Domestic consumption recovery and cold-chain infrastructure expansion support processed pork demand in tier-two cities. SAMR enforces GB standards for additive use and labeling transparency, tightening market access timelines for unverified imports. Shandong and Henan provinces concentrate curing and smoking operations adapting to MEE dual carbon energy efficiency protocols.
Brazil
Export processing capacity climbs alongside domestic foodservice menu diversification in São Paulo and Rio de Janeiro urban clusters. ANVISA sanitary regulations align with EU Green Deal methane benchmarks for preferential European retail procurement terms. Santa Catarina and Paraná states dominate hog slaughter capacity, creating logistics bottlenecks during plant downtime events.
Germany
Traditional coarse-ground sausage formulations sustain retail demand despite plant-based substitution pressure in Berlin and Munich metropolitan areas. EFSA residue limits and EU Green Deal methane benchmarks constrain energy-intensive curing operations. Bavaria and North Rhine-Westphalia processing regions accelerate biogas capture investments to unlock preferential Carrefour and Auchan procurement contracts.
Vietnam
Underdeveloped cold-chain infrastructure in secondary cities creates first-mover advantage for localized curing and distribution partnerships. The country's national food safety regulator tightens import documentation requirements for processed meat shelf-life verification. Ho Chi Minh City and Hanoi foodservice clusters drive demand for single-serve luncheon meat pouches in convenience retail channels.
Global Processed Pork Meat Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated processors commanding procurement contracts through captive supply chains while regional curing houses capture artisan positioning. The vendor base concentrates around three strategic archetypes: multinational protein conglomerates with slaughter-to-retail integration, national champions leveraging domestic distribution density, and specialized salumi producers exploiting protected designation certifications. Competitive moves center on M&A-driven capacity consolidation in Brazil and the United States, plus backward integration into captive hog farming to compress feed cost volatility exposure.
Among multinational protein conglomerates, WH Group Limited and JBS SA exemplify scale-driven archetypes with multi-continent slaughter and processing footprints. Tyson Foods Inc. occupies a position within the integrated feed-to-retail tier, representing cost-structure compression through in-house production of raw materials. Danish Crown A/S anchors the cooperative-owned segment, sitting within European premium positioning through protected designation origin certifications and extended aging protocols. These three entities collectively demonstrate how geographic diversification and supply chain control differentiate competitive positioning across regulatory environments.
| Leading Market Players |
|---|
| WH Group Limited |
| JBS SA |
| Tyson Foods Inc. |
| Danish Crown A/S |
| Hormel Foods Corporation |
| Smithfield Foods Inc. |
| Sysco Corporation |
| Clemens Food Group |
| COFCO Corporation |
| Others |
Supply & Pricing Matrix
High-pressure processing adoption in North American facilities is compressing per-unit production costs while concentrating premium positioning among early adopters. This technology shift simultaneously reduces nitrite-dependent curing expenses and widens margin spreads between clean-label tier and conventional product lines.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for commodity bacon and sausage formats. Three-tier pricing structure across premium, standard, and economy levels separates artisan salami with protected designation certifications from private-label retail programs and institutional bulk procurement. Pricing pressure stems from feed grain cost volatility transmitted through non-integrated processors. Quick service restaurants exhibit highest price sensitivity due to menu cost engineering requirements, while specialty retailers absorb premium markups for provenance-positioned cuts.
Supply Chain Analysis
Direct-to-foodservice channels handle hyperscale quick service restaurant demand through contract slaughter and portioning agreements. Brazil, the United States, and China anchor global processing capacity, with Santa Catarina and Iowa clusters feeding export and domestic routes respectively. Raw material flows draw from captive hog farming operations, corn-soybean feed milling, and imported breeding stock genetics. Single-source vulnerability concentrates in Brazilian southern state slaughter capacity where plant downtime triggers regional dislocation. Distribution runs through cold-chain distributors bundling last-mile temperature integrity with protein category management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs and Brazilian ANVISA-aligned export capacity, with methane benchmark differentials creating procurement cost spreads of material scale.
For Market Incumbents: Hedge feed cost volatility through backward integration into captive hog farming across multiple continents. WH Group Limited's multi-territory farming footprint demonstrates this lever. Defend margin position against plant-based substitution by accelerating clean-label certification investments for premium deli formats. Channel control through direct quick service restaurant contracts protects volume visibility. For New Entrants and Emerging Players: Launch via subscription cold-chain monitoring services targeting Vietnamese and Indonesian foodservice distributors lacking temperature-integrity infrastructure. White-space sits in secondary Vietnamese cities where localized curing partnerships bypass incumbent broadline networks. Go-to-market angle emphasizes IoT sensor-as-a-service recurring revenue independent of commodity cut pricing. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional processors lacking digital shelf-life tracking capabilities. Long-term viability favors integrated operators with biogas capture infrastructure securing preferential European retail procurement terms. Target acquisition archetype: Brazilian processors with ANVISA certification and latent export capacity expansion potential. Signal to watch: SAMR pre-certification documentation timelines compressing market access for unverified imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Hog Farming | WH Group Limited's multi-continent farming footprint compresses feed cost exposure and secures raw material flow. |
| Biogas Capture Infrastructure Investment | EU Green Deal methane benchmarks unlock preferential Carrefour and Auchan procurement contracts for compliant processors. |
| Subscription Cold-Chain Monitoring Launch | IoT sensor-as-a-service models create recurring revenue layers beyond physical product sales in emerging markets. |
| Clean-Label Certification Acceleration | HPP technology enables nitrite-reduced positioning for premium North American natural channel retail penetration. |
| Localized Curing Partnership Formation | Vietnamese secondary city infrastructure gaps create first-mover advantage for regional distribution control. |
Research Methodology
Coverage spans the United States, Brazil, China, Germany, and Vietnam, with primary inputs from each market cluster. The approach combines interviews with slaughter facility operations managers, quick service restaurant procurement directors, cold-chain logistics coordinators, and retail category buyers with secondary validation from USDA pathogen reduction filings, ANVISA sanitary regulation updates, SAMR GB standard enforcement notices, and EFSA residue limit documentation. Bottom-up capacity modeling triangulates against top-down consumption estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include curing method, portioning format, packaging barrier technology, and channel control structure. CAGRs derive from trend extrapolation of quick service restaurant contract volumes, cold-chain infrastructure buildout curves, and regulatory compliance cost trajectories. Industry-specific inputs incorporate feed grain futures volatility indices and biogas capture investment deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea supply disruption scenarios and SAMR documentation requirement acceleration. Projections reflect assumptions regarding dual carbon mandate enforcement intensity and plant-based substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Poultry Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Organic Chicken Market
Meat Products
Canned Chicken Market
Meat Products
Beef Fat Powder Market
Meat Products
Beef Fat Market
Meat Products
Pepperoni Foods Market
Meat Products
Bacon Slicers Market
Meat Products
Europe Meat Products Market
Meat Products
United States Red Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Pork Belly Meat Market
Meat Products
Meat Market
Meat Products
Saudi Arabia Edible Meat Market