
 Binders and Scaffolders for Meat and Meat Substitutes Market | 2026-2036
Binders and Scaffolders for Meat and Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Binders and Scaffolders for Meat and Meat Substitutes Market Analysis
Plant-based meat startups are collapsing the historical procurement gap with conventional processors, forcing ingredient suppliers to serve dual customer archetypes with divergent technical specifications. Cargill leverages its integrated protein supply chain to offer binders validated across both animal and plant applications. Ingredion Incorporated anchors its position through deep starch and hydrocolloid portfolios optimized for extruded meat analogues. Tate & Lyle competes on clean-label positioning, emphasizing non-GMO and organic-certified binding systems for European retail channels.
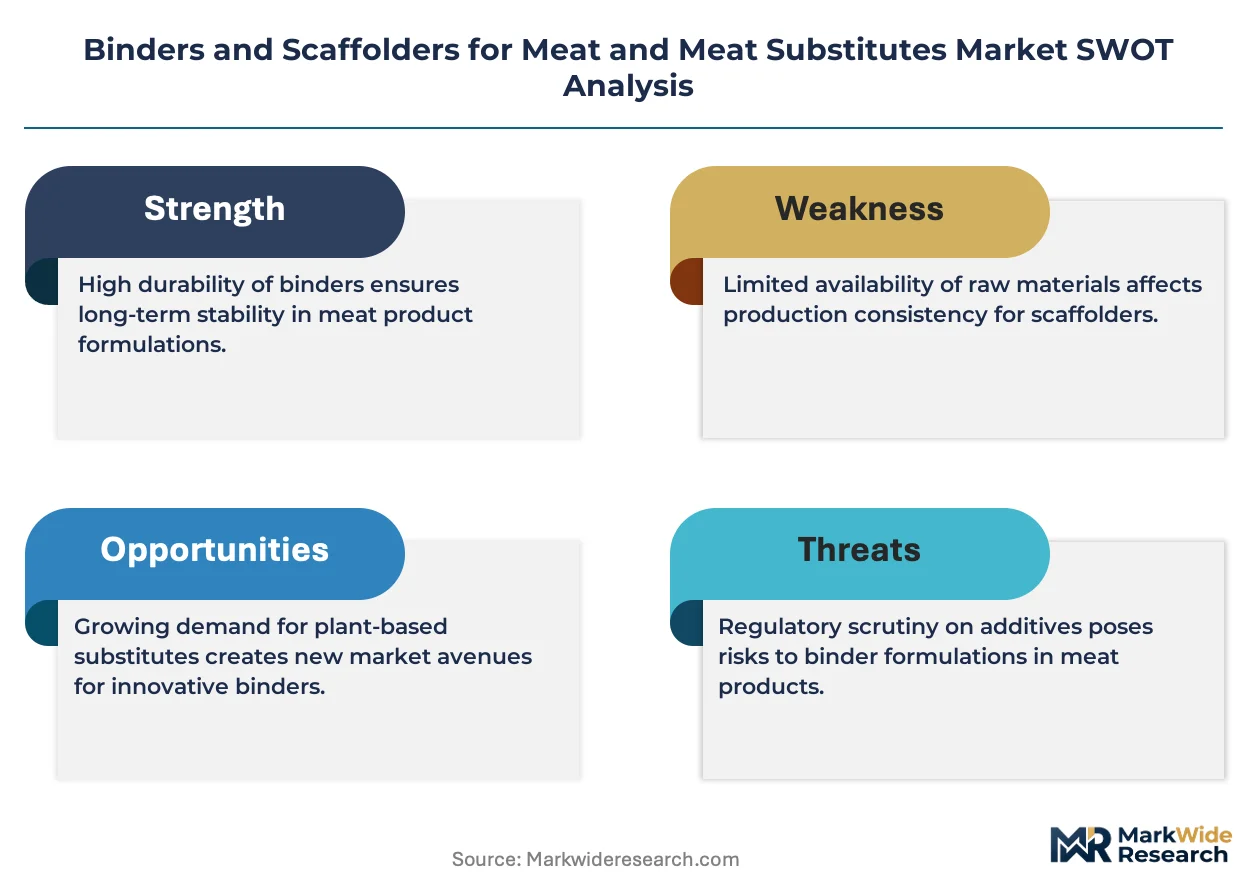
Binders and scaffolders for meat and meat substitutes encompass functional ingredients that provide structural integrity, water retention, and texture modulation through protein cross-linking, polysaccharide gelation, or fiber entanglement at dosage rates typically ranging from 0.5% to 5% by weight. These systems enable processors to achieve target cook yields, sliceability, and mouthfeel in products ranging from emulsified sausages to whole-muscle analogues. Hydrocolloids dominate current volume demand due to their versatility across temperature and pH ranges, while fermented source types represent the fastest-expanding margin pool as precision fermentation startups commercialize animal-free collagen and elastin mimics. Application concentration in processed meats sustains near-term revenue stability, though plant-based proteins command premium pricing for custom scaffold architectures.
FDA's Generally Recognized as Safe determinations and USDA-FSIS labeling requirements jointly shape which binding innovations achieve rapid commercial scale in the United States. EFSA's novel food assessments and the EU's clean-label regulatory momentum are elevating scrutiny of synthetic and animal-derived scaffolders across European markets. Stakeholders must monitor which regulatory pathways for fermented proteins achieve equivalence status first, as this will determine where capital deploys for capacity expansion.
Market Dynamics
Clean-label expectations are collapsing the traditional formulation hierarchy, forcing binders and scaffolders suppliers to revalidate hydrocolloid portfolios against enzymatic and fermented alternatives that satisfy EFSA novel food pathways.
Growth Catalysts
- EFSA Novel Food Approvals:Fermented protein platforms gain commercial traction as regulatory equivalence determinations accelerate capital deployment toward animal-free collagen mimics.
- Plant-Based Meat Analogues:Extruded whole-muscle architectures demand custom scaffold systems that hydrocolloid suppliers are engineering for texture fidelity.
- Germany:Alt-meat startups and conventional processors compete for technical ingredient supply, concentrating procurement volume in Central European distribution hubs.
Market Restraints
- Input Cost Volatility:Seaweed-derived hydrocolloids face supply interruptions from marine ecosystem disruptions and climate-driven harvest variability.
- Technical Limitation:Current enzymatic cross-linking systems fail to replicate heat-stable gelation across the full pH range required for emulsified processed meats.
- Regulatory Friction:USDA-FSIS labeling requirements for binders in meat products create compliance timelines that delay plant-based scaffold introductions.
Strategic Opportunities
- Precision Fermentation Convergence:Microbial chassis engineering combined with AI-guided protein design enables custom scaffold architectures with tunable mechanical properties.
- EU Green Deal Incentives:Carbon footprint reduction mandates redirect public and private R&D funding toward bio-based binding systems.
- Direct-to-Processor Channels:Ingredient suppliers bypass traditional distributors to capture margin and accelerate technical service response times.
Industry Challenges
- Formulation Talent Scarcity:Protein chemistry and extrusion engineering expertise concentrates in legacy meat science programs that lack plant-based curriculum integration.
- Dual-Validation Capex Burden:Suppliers must maintain parallel R&D streams for animal and plant applications without guaranteed volume commitments from either segment.
- IP Licensing Complexity:Patent thickets around enzymatic cross-linking mechanisms force costly freedom-to-operate analyses before commercial scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binders and Scaffolders for Meat and Meat Substitutes Market |
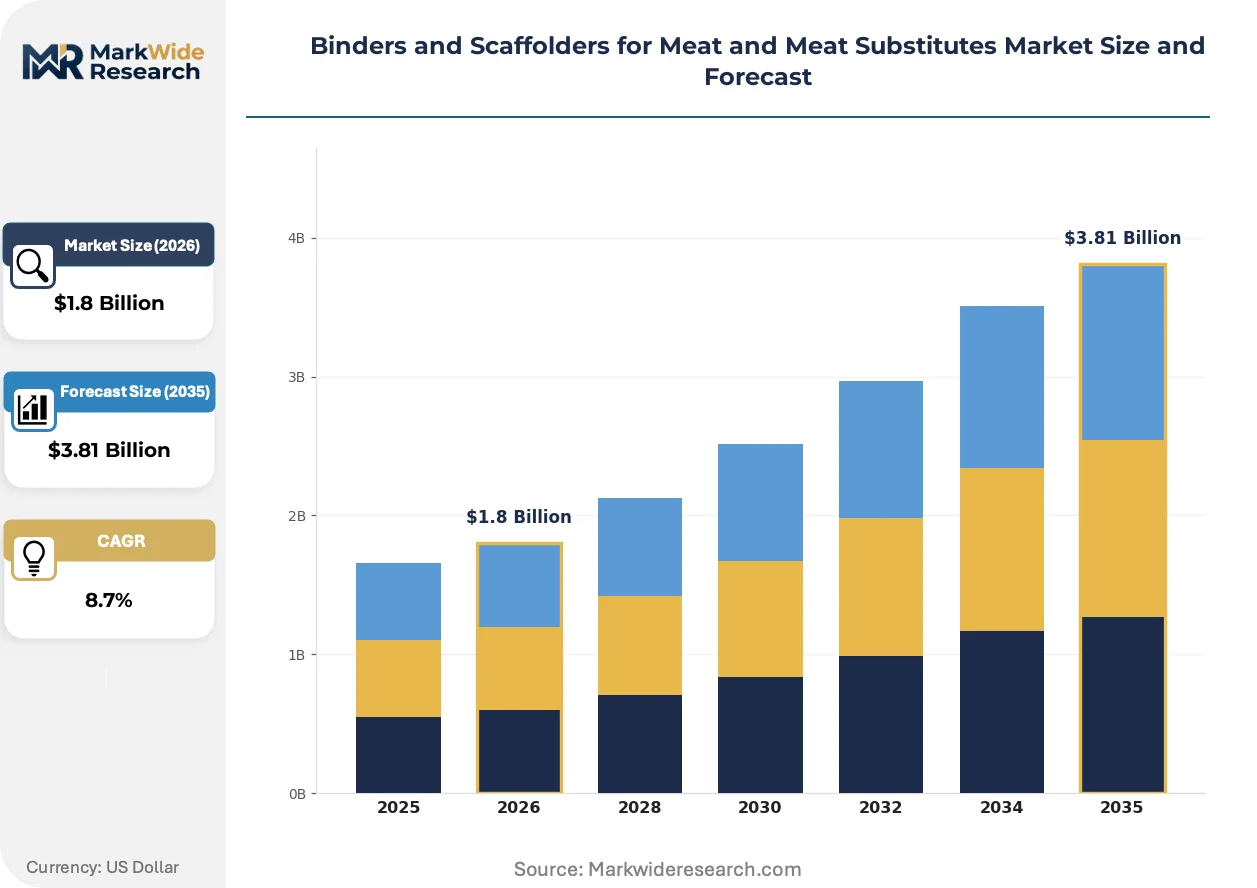
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Scaffolders, Emulsifiers, Hydrocolloids Source Type: Plant-Based, Animal-Based, Synthetic, Fermented Application: Processed Meats, Plant-Based Proteins, Ready-to-Eat Meals, Snacks Delivery Mode: Dried, Liquid, Paste, Gel |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion Incorporated, DuPont, Roquette Freres, Tate & Lyle, CP Kelco, Gelita, Avebe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binders and Scaffolders for Meat and Meat Substitutes Market Emerging Trajectories
Fermentation-derived scaffolders are rewriting competitive positioning by decoupling functional performance from agricultural commodity cycles. Three interconnected developments are reshaping how processors source structural ingredients.
Enzymatic transglutaminase alternatives are supplanting traditional microbial sources in clean-label formulations. European alt-meat manufacturers are adopting these systems at pilot scale ahead of retail certification deadlines. This substitution is compressing incumbent supplier margins while opening premium pricing tiers for fermentation startups with validated EFSA dossiers.
EFSA's evolving novel food assessment timelines are redirecting R&D investment toward enzymatic platforms with established safety profiles. Processors face reformulation costs if fermented protein approvals stall, prompting dual-track development strategies. German contract manufacturers are most affected, accelerating partnerships with ingredient suppliers holding pre-submitted regulatory packages.
Ingredient sourcing decisions now hinge on carbon intensity disclosures required by EU CSRD reporting obligations. Large meat processors are unbundling traditional supplier relationships to audit Scope 3 emissions from hydrocolloid supply chains. This behavioral shift is most visible in Netherlands-based facility expansions, where renewable energy certificates influence binder procurement awards.
Binders and Scaffolders for Meat and Meat Substitutes Market Segmentation
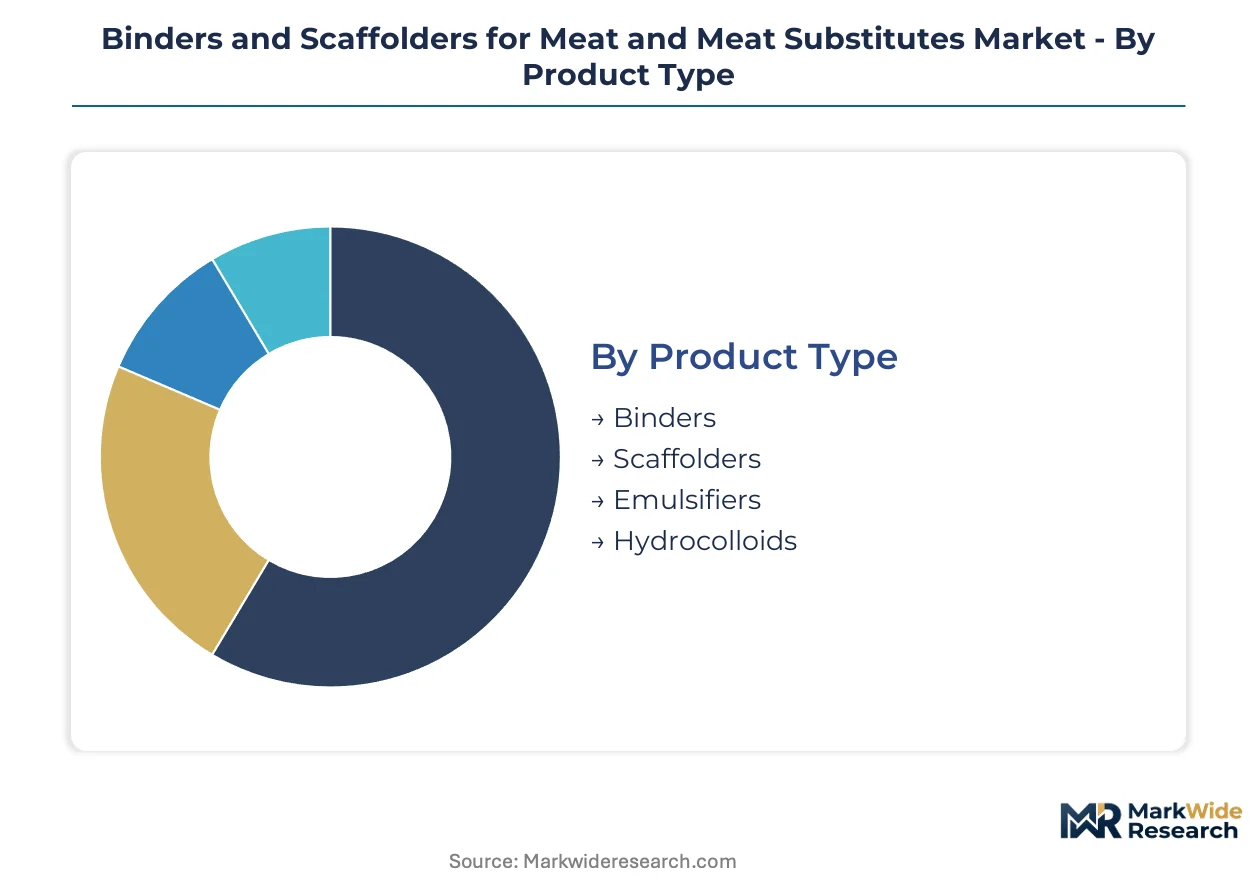
Binders and scaffolders for meat and meat substitutes segment across four functional dimensions that determine formulation strategy, regulatory pathway, and procurement economics. Each category carries distinct margin profiles and technical service requirements that reshape supplier-customer relationships.
Product Type:
Premium margin pools concentrate in scaffold architectures engineered for whole-muscle analogues, while commodity binders face pricing pressure from starch and protein alternatives.
- Binders:Protein cross-linking systems and carbohydrate-based binding agents deliver structural integrity at 0.5-3% dosage rates. Demand concentrates in German sausage processors reformulating for clean-label retail certification under EFSA guidance.
- Scaffolders:Three-dimensional matrices—collagen mimics, cellulose frameworks, and precision-fermented protein lattices—enable fibrous texture in extruded whole-muscle products. Alt-meat startups in Netherlands pilot facilities drive procurement volume for custom architectures with tunable mechanical properties.
- Emulsifiers:Phosphates and modified starches stabilize fat-protein interfaces in emulsified processed meats.
- Hydrocolloids:Carrageenan, alginate, and pectin systems dominate current volume through versatility across pH and temperature ranges.
The dominant share belongs to Hydrocolloids, while Scaffolders is closing the gap fastest.
Source Type:
Cost tier stratification runs from commodity agricultural extracts through precision-fermented proteins commanding technical premiums.
- Plant-Based:Starches, legume proteins, and seaweed-derived hydrocolloids supply the bulk of current volume. EU Green Deal carbon accounting requirements are redirecting R&D funding toward bio-based binding systems with verified Scope 3 disclosures.
- Fermented:Microbial chassis engineering produces animal-free collagen and elastin mimics with programmable mechanical properties. German contract manufacturers accelerate partnerships with suppliers holding pre-submitted EFSA novel food dossiers.
- Animal-Based:Traditional collagen, gelatin, and blood plasma binders retain share in conventional processed meats.
- Synthetic:Chemically modified cellulose and petrochemical-derived emulsifiers face clean-label displacement pressure.
Plant-Based retains volume leadership, though Fermented climbs the fastest as regulatory equivalence determinations accelerate.
Application:
Customer type segmentation separates legacy meat processors with established supplier relationships from alt-meat startups demanding rapid technical iteration.
- Processed Meats:Emulsified sausages, whole-muscle hams, and restructured products sustain near-term revenue stability through reformulation cycles. USDA-FSIS labeling requirements create compliance timelines that delay novel binder introductions in US facilities.
- Plant-Based Proteins:Extruded analogues, cultivated meat scaffolds, and hybrid products command premium pricing for custom architectures. Netherlands-based facility expansions prioritize renewable energy certificates in procurement awards.
- Ready-to-Eat Meals:Shelf-stable and chilled prepared foods require moisture management and texture retention through distribution.
- Snacks:Jerky, protein bars, and extruded puffs utilize binding systems for chew texture and structural integrity.
Processed Meats anchors current revenue, while Plant-Based Proteins expands most quickly through premium pricing tiers.
Delivery Mode:
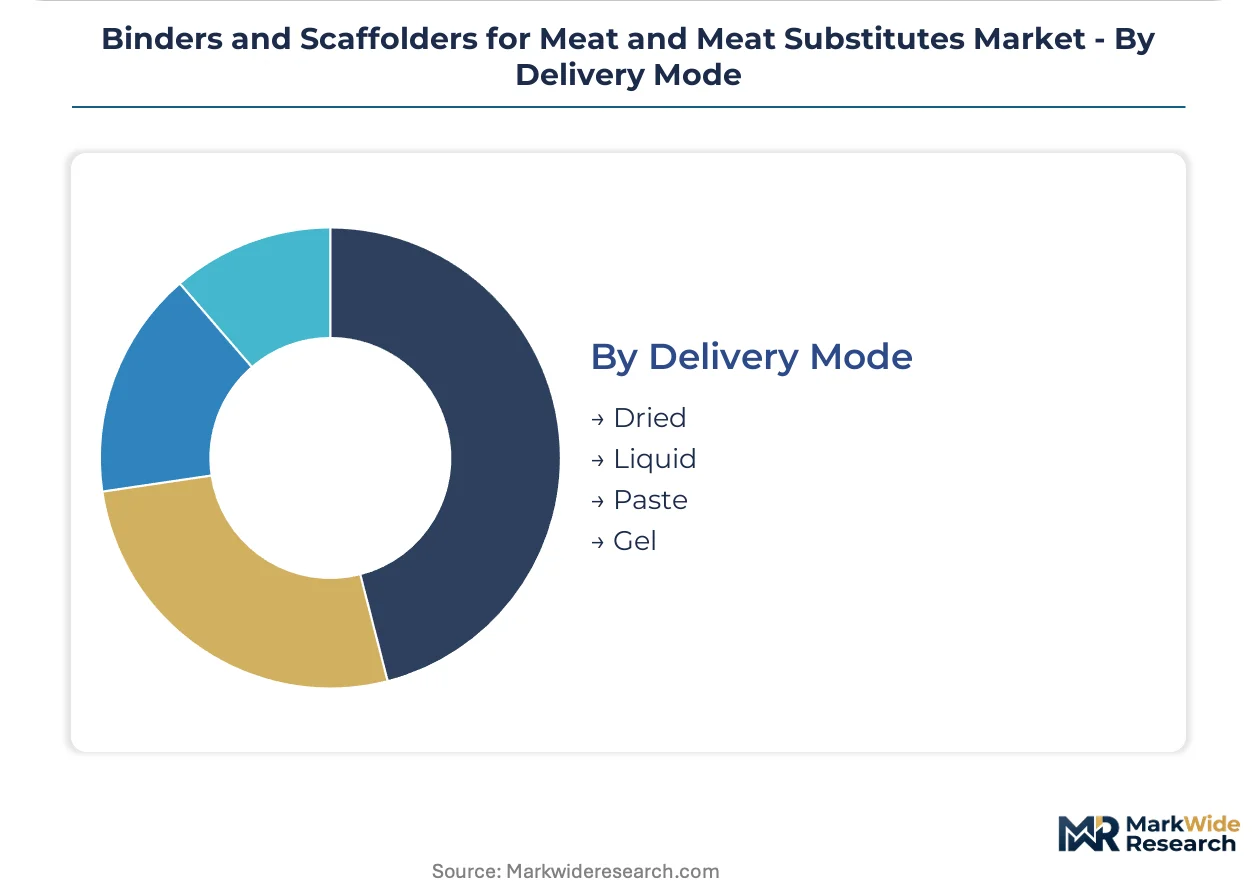
Supply concentration favors dried formats with established distribution infrastructure, though liquid and gel systems gain traction in continuous processing lines.
- Dried:Powders and granules dominate procurement through extended shelf stability and freight efficiency. German distribution hubs concentrate inventory for Central European meat and alt-meat processors competing for technical ingredient supply.
- Liquid:Pumpable suspensions and solutions integrate directly into high-throughput extrusion and injection systems. Pilot-scale alt-meat manufacturers in Netherlands adopt liquid hydrocolloid concentrates to reduce hydration time and batch variability.
- Paste:Semi-solid preparations suit small-batch artisanal processors and specialty sausage applications.
- Gel:Pre-hydrated matrices serve cultivated meat bioreactor seeding and precision scaffold deployment.
Dried holds the installed base advantage, while Liquid gains share fastest through continuous processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-fermented scaffold systems to Dutch and Belgian alt-meat processors, establishing a Central European trade corridor that concentrates technical ingredient procurement in Rotterdam and Hamburg distribution hubs.
United States
USDA-FSIS labeling requirements for binders in meat products create compliance timelines that delay novel scaffold introductions. FDA's Generally Recognized as Safe determinations shape which binding innovations achieve rapid commercial scale. Chicago-based meat processors maintain established supplier relationships while California alt-meat startups demand rapid technical iteration.
Germany
Alt-meat startups and conventional processors compete for technical ingredient supply, concentrating procurement volume in Central European distribution hubs. EFSA's evolving stance on novel ingredient approvals redirects R&D investment toward fermented and enzymatic platforms. Berlin-Brandenburg contract manufacturers accelerate partnerships with suppliers holding pre-submitted regulatory dossiers.
Netherlands
Carbon intensity disclosures required by EU CSRD reporting obligations unbundle traditional supplier relationships. Renewable energy certificates influence binder procurement awards in facility expansions. Wageningen-based research clusters drive pilot-scale adoption of liquid hydrocolloid concentrates for extruded whole-muscle architectures.
China
Domestic meat processors reformulate for cost-optimized binding systems in emulsified sausage production. SAMR food additive regulations govern hydrocolloid usage levels in processed meat applications. Shandong Peninsula manufacturing bases source seaweed-derived hydrocolloids amid climate-driven harvest variability concerns.
United Kingdom
Post-Brexit regulatory divergence from EFSA novel food pathways creates dual-track compliance costs for multinational suppliers. Clean-label retail certification demands reshape formulation requirements for domestic sausage processors. Midlands-based meat manufacturers navigate parallel validation streams for EU and UK market access.
Binders and Scaffolders for Meat and Meat Substitutes Market Vendor Landscape
Listed leaders compete with private specialists across regulatory dossier capabilities, creating a tiered structure where scale advantages in hydrocolloid production coexist with precision-fermentation startups commanding technical premiums. The vendor base clusters around three archetypes: integrated protein traders with validated cross-application portfolios, starch and hydrocolloid specialists optimizing extrusion performance, and fermentation startups commercializing animal-free collagen mimics. Dominant competitive moves include direct-to-processor channel expansion to capture margin and accelerate technical service response times, plus strategic partnerships with contract manufacturers holding pre-submitted EFSA packages.
Within the integrated protein tier, Cargill leverages supply chain breadth across animal and plant applications. Ingredion Incorporated anchors the starch and hydrocolloid specialist position through extrusion-optimized portfolios. Tate & Lyle occupies the clean-label positioning vector for European retail channels. These three exemplify how divergent technical specifications from dual customer archetypes force parallel R&D investment without guaranteed volume commitments from either segment.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont |
| Roquette Freres |
| Tate & Lyle |
| CP Kelco |
| Gelita |
| Avebe |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German precision-fermentation facilities sets price floors for animal-free collagen mimics, compressing margins for commodity hydrocolloid suppliers while elevating premiums for validated scaffold architectures. This scale dynamic concentrates procurement power among alt-meat startups with offtake commitments, forcing traditional processors into longer contract terms to secure volume allocation.
Pricing Analysis
Next-generation fermented scaffolders command technical premiums over enzymatic cross-linking systems and legacy hydrocolloid binders. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA novel food dossier status and carbon intensity disclosure grade. Cost compression in commodity starch and seaweed-derived hydrocolloids is intensifying because of climate-driven harvest variability and substitute protein availability. Alt-meat startups with pilot-scale operations exhibit highest price sensitivity, while multinational meat processors with reformulation deadlines show lowest sensitivity.
Supply Chain Analysis
Inventory cycles for dried hydrocolloid powders extend 8-12 weeks, while liquid concentrate lead times compress to 3-5 weeks for Dutch continuous-processing lines. Supply concentrates in Germany, Netherlands, and China, with German facilities anchoring precision-fermented protein output and Shandong Peninsula sites dominating seaweed-derived inputs. Raw material dependencies include marine biomass, legume starches, and microbial chassis feedstocks. Single-source vulnerability runs through seaweed harvest zones exposed to marine ecosystem disruption. Distribution runs through Rotterdam and Hamburg hubs serving Central European meat and alt-meat processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EFSA novel food approvals for fermented proteins unlock formulation substitution across European processed meat applications. Precision fermentation capacity buildout represents the primary adoption tailwind accelerating commercial scale.
For Market Incumbents: Shield hydrocolloid market share by accelerating backward integration into seaweed cultivation assets and securing renewable energy certificates for Dutch facility carbon disclosures. Defend against enzymatic cross-linking substitution by pre-submitting EFSA dossiers for clean-label reformulations. Prioritize direct-to-processor channel control to capture margin from distributors serving German alt-meat startups.
For New Entrants and Emerging Players: Lead with precision-fermented scaffold architectures targeting Netherlands pilot-scale alt-meat manufacturers demanding tunable mechanical properties. White-space concentration sits in custom collagen mimics for whole-muscle extrusion, with German contract manufacturers representing the most penetrable customer archetype. Go-to-market execution should anchor in technical service partnerships with Wageningen-based research clusters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation startups with validated EFSA packages over commodity hydrocolloid incumbents facing margin compression. Long-term viability across the projection horizon rests on regulatory equivalence determinations accelerating capital deployment toward animal-free protein platforms. Acquisition target archetype: precision-fermentation specialists with pre-submitted novel food dossiers and microbial chassis IP. Signal to monitor: first EFSA equivalence determination for fermented collagen mimics.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Submission | Pre-submitted regulatory packages accelerate German contract manufacturer partnerships and procurement awards. |
| Backward Integration into Marine Biomass | Captive seaweed cultivation secures supply against climate-driven harvest variability in Shandong Peninsula zones. |
| Direct-to-Processor Channel Expansion | Bypassing distributors captures margin and compresses technical service response times for Dutch alt-meat pilots. |
| Renewable Energy Certificate Procurement | Carbon intensity disclosures under EU CSRD influence binder procurement awards in Netherlands facility expansions. |
| Precision Fermentation Capacity Buildout | Microbial chassis engineering enables custom scaffold architectures with programmable mechanical properties. |
Methodological Framework
A standing panel of formulation scientists at German meat processors, procurement leads at Netherlands alt-meat startups, EFSA regulatory affairs specialists, and extrusion engineering directors provided ongoing calibration across primary fieldwork. Secondary validation drew from EFSA novel food registers, EU CSRD disclosure databases, customs trade data for hydrocolloid imports, and SEC filings of listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled segmentation across product type, source type, application, and delivery mode throughout the forecast period. CAGRs derived from trajectory analysis of historical substitution patterns and regulatory approval timelines. Industry-specific forecast inputs included EFSA novel food assessment velocity and carbon intensity disclosure adoption curves.
Forecasts assume regulatory continuity in EFSA novel food pathways and USDA-FSIS labeling requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Reconstituted Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Beef Liver Market
Meat Products
India Edible Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Europe Bacon Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
North America Bacon Market
Meat Products
Europe Poultry Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Global Duck Meats Market
Meat Products
Germany Meat Products Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Organic Eggs Market
Meat Products
India Animal Protein Market