
 US Meat Market | 2026-2036
US Meat Market Size, Share, and Industry Trends Forecast 2026-2036
US Meat Market Analysis
Cell-cultured protein technology is fragmenting traditional livestock supply chains as bioreactor-based production competes with conventional harvesting for shelf space and consumer acceptance. Tyson Foods leverages its protein R&D division to pilot hybrid products blending plant and cultivated inputs. JBS USA Holdings anchors its position through backward integration into cattle feeding and hide processing. Cargill Incorporated sustains margin capture across grain trading, feed formulation, and protein processing.
US meat encompasses muscle tissue from cattle, swine, poultry, and ovine species, processed under Hazard Analysis Critical Control Point protocols with internal temperature thresholds of 145°F for whole cuts and 160°F for ground formulations, serving as a primary dietary protein source and industrial ingredient for food manufacturing. Poultry leads volume throughput due to feed conversion efficiency and shorter production cycles, while Prime and Choice grades command concentrated margin pools in white-tablecloth and premium retail channels. Frozen packaging dominates export logistics, though vacuum-sealed formats gain traction in direct-to-consumer subscription models.
USDA's Agricultural Marketing Service administers quality grading standards, while FSIS enforces pathogen reduction performance standards under the Humane Methods of Slaughter Act; OSHA separately governs processing line speeds and worker safety thresholds in packing plants. The FDA coordinates with USDA on cell-cultured protein oversight through a formal agreement on jurisdiction. Stakeholders must monitor how state-level animal confinement ballot measures in California and Massachusetts propagate through interstate commerce litigation.
Market Dynamics
Cell-cultured protein technology is fragmenting traditional livestock supply chains as bioreactor-based production competes with conventional harvesting for shelf space and consumer acceptance.
Growth Catalysts
- USDA Grading Modernization:Updated quality standards for marbling and yield are expanding premium grade availability, allowing processors to extract higher margins from Prime and Choice categories.
- Texas-Oklahoma-Kansas Feeding Corridor:Concentrated packing capacity and feedlot density in this region creates procurement gravity that reduces logistics costs for beef processors.
- Bioreactor Scale-Up:Advances in perfusion systems and growth media formulation are driving unit cost reductions in cultivated meat production.
Market Restraints
- Feed Grain Price Volatility:Corn and soybean meal input costs swing with drought cycles in the Corn Belt, compressing feedlot margins and forcing processor contract renegotiations.
- Packing Concentration Risk:Four firms control over 80 percent of US beef processing capacity, creating systemic vulnerability to plant disruptions or labor stoppages.
- FSIS Inspection Bottlenecks:Federal inspector staffing shortages at slaughter facilities limit line speeds and extend processing schedules.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Vacuum-sealed premium cuts shipped from regional processors are bypassing traditional retail distribution.
- California and Massachusetts Ballot Measures:State-level animal confinement regulations are creating compliance arbitrage opportunities for producers with certified supply chains.
- Hybrid Protein Formulations:Blending plant-based and cultivated inputs offers a regulatory pathway through FDA-USDA joint oversight while building consumer familiarity.
Industry Challenges
- HACCP Specialist Shortage:Qualified food safety plan developers and verification officers are scarce, slowing plant certifications and expansions.
- Legacy Equipment Integration:Conventional slaughter lines require substantial retrofitting to handle precision-cut portions for e-commerce fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Meat Market |
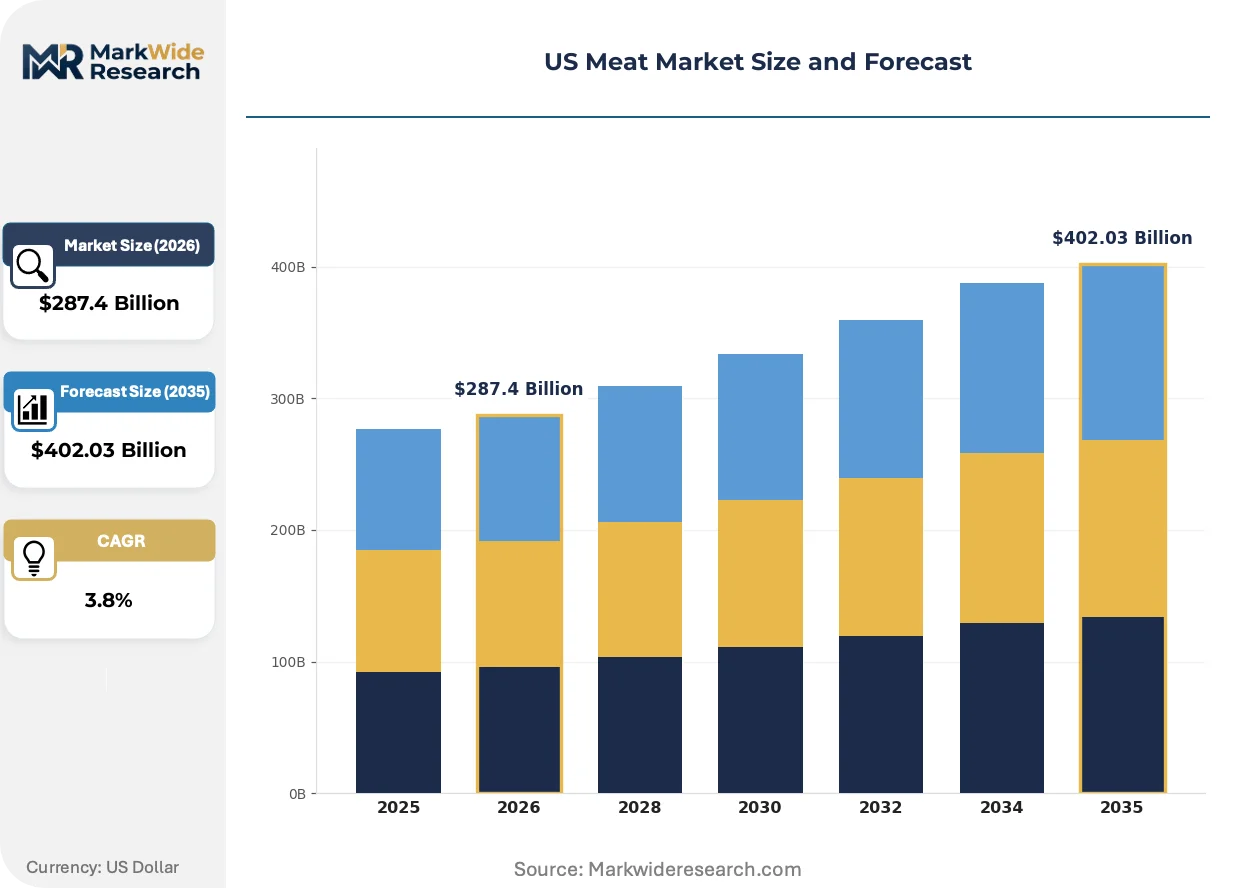
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $402.03 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Sales Channel: Retail, Wholesale, Direct-to-Consumer, E-commerce Packaging Type: Vacuum Sealed, Canned, Fresh, Frozen Quality Grade: Prime, Choice, Select, Standard |
| Companies Covered | Smithfield Foods Inc., National Beef Packing Company, Tyson Foods Inc., OSI Group, Marfrig Global Foods, JBS USA Holdings, Hormel Foods Corporation, Conagra Brands Inc., Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Meat Market Emerging Trajectories
Protein sourcing is bifurcating between consolidated commodity supply and fragmented premium channels, with technology and regulation determining which pathway captures margin.
Blockchain-enabled traceability systems are digitizing the documentation of cattle provenance, feed inputs, and processing conditions. Large foodservice distributors and retail chains with ESG commitments are mandating supplier adoption within 24-month rollout windows. This transparency infrastructure is digitizing compliance verification and compressing the timeline for quality dispute resolution.
The FDA-USDA formal agreement on cell-cultured protein jurisdiction is clarifying inspection protocols and label approval pathways. Dual-agency oversight requires facilities to satisfy both biologics manufacturing standards and meat processing sanitation rules. Early movers in the cultivated segment are structuring operations to accommodate simultaneous FDA facility registration and FSIS grant of inspection.
Foodservice operators are unbundling protein procurement from broadline distribution contracts, establishing direct relationships with regional packers for specific grade certifications. Quick-service chains with premium menu tiers are sourcing Prime beef outside traditional commodity channels. This disintermediation is most visible in the Texas Panhandle and Nebraska regions where mid-size packers have invested in branded programs.
US Meat Market Segmentation
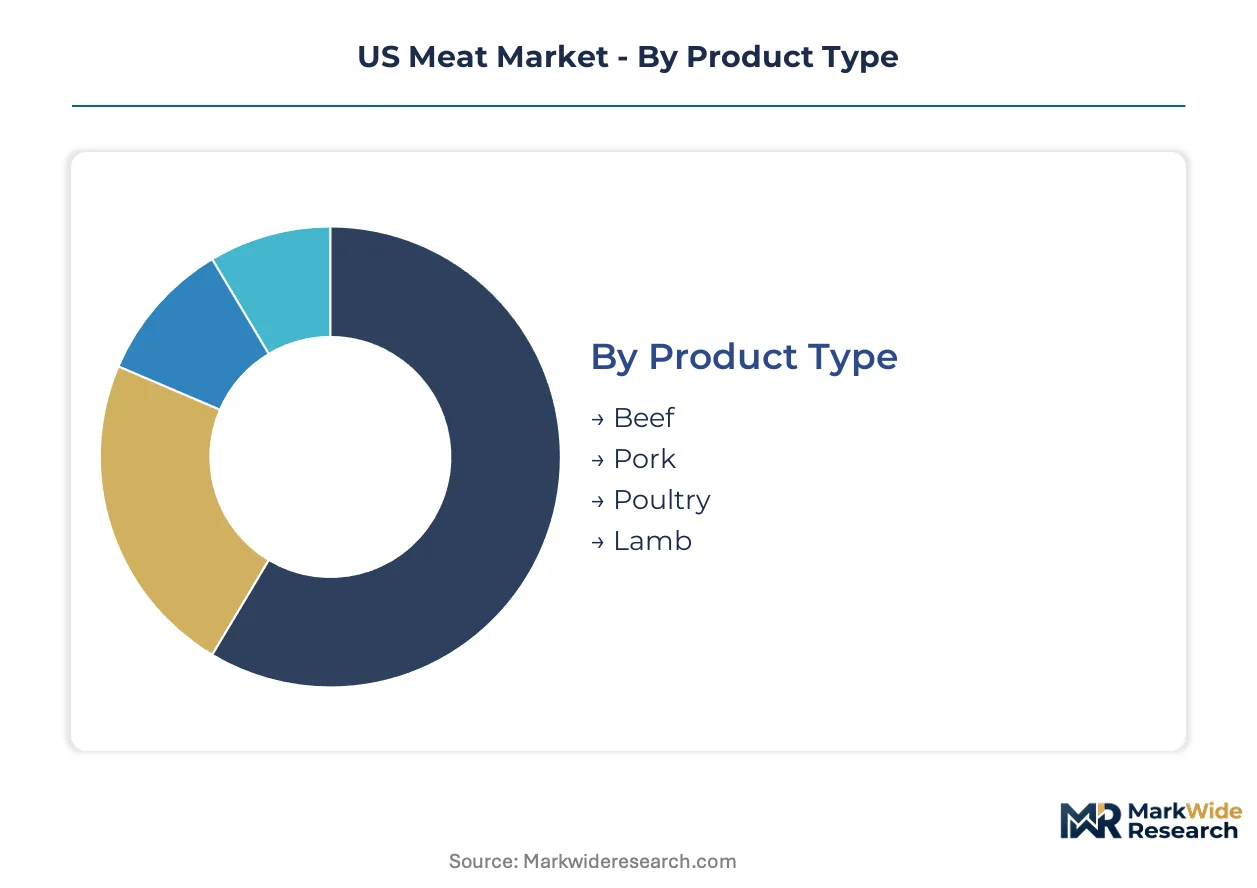
Segmentation in the US meat market determines procurement strategies across diverging supply chains. Each dimension—species, channel, packaging, and grade—carries distinct margin profiles and regulatory requirements that reshape processor investment priorities.
Product Type:
Mature categories dominate volume throughput while emerging alternatives capture speculative investment from cultivated protein ventures.
- Beef:Derived from cattle finished in feedlots across the Texas-Oklahoma-Kansas corridor, graded under USDA marbling standards. Demand concentrates in white-tablecloth restaurants and premium retail cases where Prime and Choice certifications command price premiums; packing concentration and feed grain cost volatility constrain margin stability.
- Pork:Processed from swine raised in confinement operations concentrated in Iowa and North Carolina, valued for carcass utilization across fresh cuts and processed applications. Foodservice operators and export markets absorb the majority of volume; processor backward integration into genetics and nutrition reduces input cost exposure.
- Poultry:Broiler and turkey production characterized by vertical coordination between integrators and contract growers. Feed conversion efficiency and shortened production cycles sustain volume leadership in commodity protein.
- Lamb:Niche segment sourced from range-fed operations in Colorado and Texas, plus imported supply from Australia and New Zealand. Ethnic foodservice and holiday retail drive concentrated demand windows.
Poultry retains volume leadership; beef holds the steepest expansion curve in premium channel penetration.
Sales Channel:
Cost tier differentiation separates high-touch service models from automated fulfillment infrastructure.
- Retail:Supermarkets and club stores with full-service meat counters and self-service cases. Grocery chains with ESG commitments are mandating blockchain traceability adoption within compressed rollout timelines.
- Wholesale:Broadline distributors serving foodservice accounts from institutional cafeterias to independent restaurants. Distributor consolidation is forcing regional packers into direct relationships with end-users.
- Direct-to-Consumer:Vacuum-sealed subscription boxes shipped from regional processors bypassing traditional retail distribution. Texas Panhandle and Nebraska mid-size packers have invested in branded programs for this channel.
- E-commerce:Third-party marketplace listings and proprietary brand storefronts with cold-chain logistics partnerships. Platform fee structures and last-mile refrigeration requirements compress net margins.
Wholesale retains volume leadership; direct-to-consumer holds the steepest expansion curve.
Packaging Type:
Application requirements dictate shelf-life extension versus sensory preservation trade-offs.
- Vacuum Sealed:Modified atmosphere packaging extending retail case life while preserving color stability. E-commerce subscription models and premium retail channels are driving adoption.
- Canned:Thermally processed products for emergency preparedness and military supply. Stable demand from institutional stockpiling programs with limited margin expansion potential.
- Fresh:Unfrozen product distributed through refrigerated supply chains with 7-14 day shelf life. Foodservice operators with rapid turnover prioritize fresh delivery for texture and flavor integrity.
- Frozen:Blast-frozen cuts and commodity portions for export logistics and long-term storage. Export markets and institutional procurement rely on frozen formats for inventory flexibility.
Frozen retains volume leadership; vacuum sealed holds the steepest expansion curve.
Quality Grade:
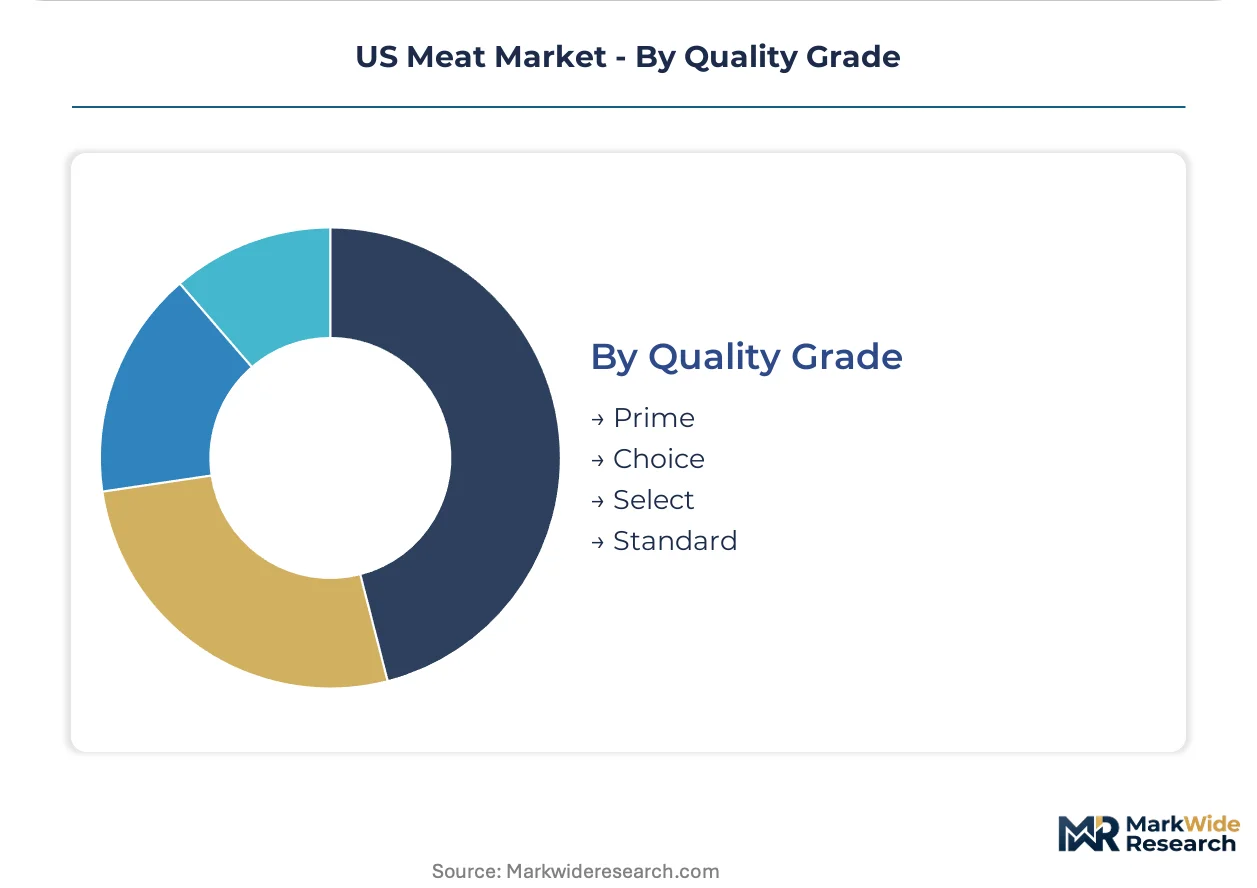
Margin stratification follows USDA certification tiers with pronounced price differentiation between adjacent grades.
- Prime:Highest marbling scores from young cattle, representing limited supply availability. White-tablecloth chains and premium retail cases compete for scarce allocation; grading modernization is expanding availability.
- Choice:Moderate marbling with broad availability across retail and foodservice. Quick-service chains with premium menu tiers are sourcing outside traditional commodity channels.
- Select:Leaner profiles positioned for health-conscious consumers and price-sensitive foodservice. Limited margin pool constrains processor investment in dedicated programs.
- Standard:Ungraded or utility product for further processing into ground formulations and prepared foods. Commodity pricing and thin margins concentrate volume in integrated processor operations.
Choice retains volume leadership; Prime holds the steepest expansion curve in per-unit margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement teams concentrate in metropolitan clusters with cold-chain infrastructure and direct packer access. Buyer archetypes span quick-service chains seeking volume commitments, white-tablecloth operators chasing grade certifications, and institutional accounts prioritizing price stability.
Texas Panhandle
Feedlot density and packing capacity create procurement gravity for beef processors. USDA FSIS inspection protocols govern slaughter operations while OSHA regulates line speeds in Amarillo and Lubbock facilities. Mid-size packers here have invested in branded programs for direct-to-consumer subscription channels.
Nebraska
Cattle feeding operations supply Choice and Prime grades to premium foodservice accounts. State environmental regulations on confined animal feeding operations interact with federal Clean Water Act permits. The Omaha-Lincoln corridor hosts distributor consolidation points for institutional procurement.
Iowa
Swine confinement operations concentrate in the state's northwest counties, supplying pork processors with integrated genetics and nutrition programs. The Department of Agriculture and Land Stewardship coordinates with EPA on manure management regulations. Sioux City and Des Moines serve as logistics hubs for export-bound frozen cuts.
North Carolina
Poultry integrators coordinate contract grower networks across the coastal plain. State environmental regulators enforce waste management permits under delegated federal authority. The Sandhills region anchors processing capacity for domestic retail and export markets.
California
Proposition 12 compliance requirements reshape procurement for operators serving the state's foodservice and retail channels. The Department of Food and Agriculture administers additional animal confinement standards beyond federal baselines. Los Angeles and San Francisco metropolitan areas concentrate demand for certified supply chains.
US Meat Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement relationships. Four firms dominate beef packing capacity, creating systemic vulnerability to disruption. Strategic archetypes include integrated protein conglomerates with feed-to-retail operations, mid-size regional packers with branded programs, and diversified food manufacturers with meat portfolios. Competitive moves center on backward integration into cattle feeding and strategic partnerships with foodservice distributors.
Within the integrated conglomerate tier, Tyson Foods Inc., JBS USA Holdings, and Cargill Incorporated exemplify scale-driven positioning. These entities represent the channel-control archetype through captive supply chains and direct foodservice relationships. Mid-size specialists occupy positions in premium grade procurement and direct-to-consumer fulfillment.
| Leading Market Players |
|---|
| Smithfield Foods Inc. |
| National Beef Packing Company |
| Tyson Foods Inc. |
| OSI Group |
| Marfrig Global Foods |
| JBS USA Holdings |
| Hormel Foods Corporation |
| Conagra Brands Inc. |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Feed grain concentration in the Corn Belt concentrates margin pressure on cattle feeders and processors, pushing pricing power downstream toward packers with captive supply chains and branded distribution channels. The Texas-Oklahoma-Kansas corridor anchors procurement gravity, while corn and soybean meal volatility propagates through contract structures to end-user pricing.
Pricing Analysis
Cost-plus contracts with Chicago Mercantile Exchange live cattle futures indexation dominate processor-producer agreements. Three-tier pricing structure across Prime, Choice, and Select grades captures marbling-based price differentiation, with white-tablecloth operators absorbing premium tier increases. Pricing pressure stems from feed grain cost compression in the Corn Belt during drought cycles. Institutional cafeterias and ground-beef manufacturers demonstrate highest price sensitivity, while premium foodservice accounts show inelastic demand for certified Prime allocation.
Supply Chain Analysis
JBS USA Holdings, Tyson Foods, Cargill, and National Beef Packing concentrate over 80 percent of fed cattle processing capacity across the Texas Panhandle, Nebraska, and Kansas. The supply chain draws from Iowa and North Carolina swine operations, Colorado and Texas range-fed lamb, and vertically integrated poultry integrators in the Southeast. Single-source vulnerability concentrates in the four-firm beef packing tier, where plant disruptions cascade through protein procurement. Distribution runs through broadline foodservice distributors, though direct-to-consumer subscription channels bypass traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified HACCP plan developers and verification officers are scarce, slowing plant certifications and creating bottlenecks for expansion-ready mid-size packers. This capability gap rewards early investment in food safety infrastructure.
For Market Incumbents: Entrench procurement relationships through backward integration into cattle feeding operations in the Texas-Oklahoma-Kansas corridor. Lock in Prime and Choice grade allocation through long-term contracts with feedlots before USDA grading modernization expands premium availability. Defend against cell-cultured protein entrants by accelerating hybrid product development through protein R&D divisions. For New Entrants and Emerging Players: The California and Massachusetts animal confinement compliance markets offer underpenetrated white-space for certified supply chain operators. Target direct-to-consumer subscription channels with vacuum-sealed premium cuts from regional processors in Nebraska and the Texas Panhandle. Build go-to-market positioning around Proposition 12 compliance arbitrage for foodservice operators serving West Coast metropolitan demand clusters. For Investors and Strategic Acquirers: Capital is best deployed toward mid-size regional packers with branded programs and existing FSIS grants of inspection. Long-term viability across the analysis window favors operators with simultaneous FDA facility registration readiness for cell-cultured protein pivot capacity. Monitor FDA-USDA joint oversight rulemaking progress as the inflection signal for hybrid protein formulation regulatory clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Feeding | JBS USA Holdings anchors margin capture through captive supply chains in the Texas Panhandle. |
| Hybrid Protein Product Launch | Tyson Foods pilots blended plant-cultivated formulations under FDA-USDA joint oversight protocols. |
| Blockchain Traceability Adoption | Retail chains with ESG commitments mandate supplier digitization within compressed rollout timelines. |
| Direct-to-Consumer Channel Expansion | Nebraska and Texas Panhandle packers bypass broadline distribution through vacuum-sealed subscription models. |
| HACCP Specialist Recruitment | Food safety plan developer scarcity constrains plant certification velocity for expansion-ready processors. |
Methodological Framework
Operator-level perspectives from beef procurement directors, poultry integrator contract managers, FSIS inspection personnel, and foodservice distributor category buyers anchored the qualitative base. Secondary validation drew from USDA Agricultural Marketing Service grading data, FSIS enforcement reports, EPA Clean Water Act permit disclosures, and SEC 10-K filings from publicly traded protein processors. Bottom-up volume modeling triangulated against top-down industry association estimates to reconcile segmentation outputs.
Scenario-bracketing around feed grain price volatility, labor stoppage probability, and cell-cultured protein scale-up pace bounded the projection range across the analysis window. Segmentation dimensions spanned species type, sales channel, packaging format, and USDA quality grade. CAGRs derived from trend extrapolation of historical throughput data adjusted for regulatory intervention timelines and technology substitution curves. Forecast inputs incorporated packing capacity utilization rates and feedlot placement cycles.
Practitioners should monitor drought severity indices in the Corn Belt, FSIS inspector staffing levels, and state-level animal confinement ballot measure litigation for early signals of forecast revision. Quarterly review of cattle futures spreads, plant disruption frequency, and cell-cultured protein unit cost trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Animal Protein Market
Meat Products
Low-Fat Ham Market
Meat Products
Mexico Meat Products Market
Meat Products
Ham Slicers Market
Meat Products
Beef Fat Market
Meat Products
Emulsified Meat Market
Meat Products
Beef Jerky Market
Meat Products
Organic Chicken Market
Meat Products
South Africa Processed Meat Market
Meat Products
North America Poultry Meat Market
Meat Products
United States Bacon Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
North America Canned Meat Market
Meat Products
North America Bacon Market
Meat Products
Canned Chicken Market
Meat Products
Meat Flavors Market