
 North America Poultry Meat Market | 2026-2036
North America Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Poultry Meat Market Analytics
Poultry processing labor availability is bifurcating the competitive landscape across the region. Tyson Foods Inc. leverages its vertically integrated network to secure workforce stability in high-volume plants. Perdue Farms differentiates through antibiotic-free and organic product lines that command premium positioning. Koch Foods anchors significant capacity in the Midwest, sustaining volume throughput despite regional labor tightness.
North America poultry meat encompasses avian species raised for human consumption, typically processed to achieve specific fat-to-protein ratios, moisture retention parameters, and shelf-life thresholds through controlled chilling, aging, and packaging protocols. Broilers dominate volume due to feed conversion efficiency and shorter grow-out cycles, while turkey segments retain stronger margin pools tied to seasonal demand and further-processed deli applications. Frozen processing methods lead distribution scale, though fresh product lines capture expanding supermarket and online retail channels seeking shorter supply chains.
USDA Food Safety and Inspection Service standards govern slaughter and processing compliance, while FDA oversight extends to feed additives and pharmaceutical residues, collectively elevating capital requirements for market entry. The EPA regulates wastewater and rendering emissions from processing facilities, shaping plant location and upgrade cycles. Stakeholders must monitor evolving state-level cage-free and slow-growth mandates as these standards proliferate across California, Massachusetts, and similar jurisdictions, forcing portfolio recalibration ahead of compliance deadlines.
Market Dynamics
USDA's updated poultry inspection modernization rules are compressing processing compliance timelines while labor scarcity in southeastern plants forces automation adoption ahead of depreciation cycles.
Growth Catalysts
- Food service menu expansion:Operators across the United States and Canada are broadening poultry-centric offerings as a lower-cost protein alternative to beef and pork, driving volume throughput in quick-service and casual dining channels.
- Antibiotic-free certification protocols:Premium positioning through USDA Process Verified and third-party organic standards is opening margin pools in supermarket retail and direct-to-consumer channels.
- Southeastern production clusters:Integrated grow-out and processing infrastructure in Georgia, Alabama, and Arkansas delivers feed cost advantages and shortened logistics legs to eastern population centers.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with drought cycles in the Midwest, compressing processor margins during El Niño weather patterns.
- Processing labor concentration risk:Dependence on immigrant workforce pools in rural Arkansas and Mississippi plants creates operational vulnerability during immigration enforcement surges.
- Rendering facility emissions caps:EPA wastewater and air quality standards for feather meal and blood processing operations limit plant siting flexibility and extend permitting timelines.
Strategic Opportunities
- Canadian prairie expansion:Underdeveloped broiler capacity in Manitoba and Saskatchewan offers greenfield sites with lower regulatory density and access to Asian export channels through Vancouver ports.
- Cell-cultured hybrid products:Convergence of traditional whole-muscle processing with cultivated fat tissue blending creates novel texture profiles for food service R&D pipelines.
- Direct-to-restaurant distribution:Bypassing traditional broadline distributors through proprietary cold-chain delivery to independent restaurants captures margin and demand data.
Industry Challenges
- Automated deboning technician scarcity:Maintenance and calibration of robotic thigh and breast separation systems requires mechatronics skills absent in legacy slaughter floor workforces.
- State-level cage-free mandate fragmentation:California Proposition 12 and Massachusetts Question 3 compliance timelines force SKU proliferation and supply chain segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Poultry Meat Market |
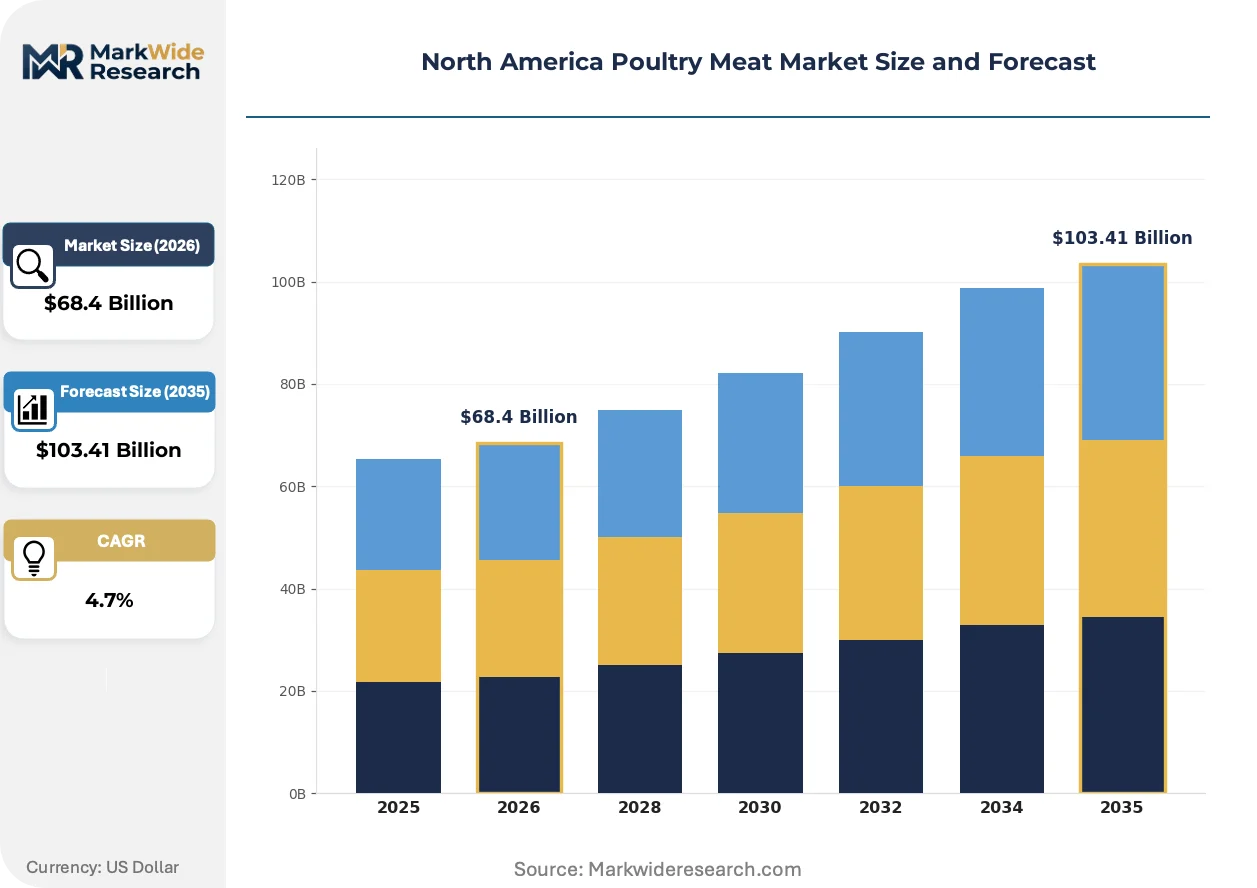
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Turkeys, Ducks, Geese Processing Method: Fresh, Frozen, Canned, Cooked Distribution Channel: Supermarkets, Wholesalers, Online Retail, Convenience Stores End User: Households, Food Service, Retailers, Exporters |
| Companies Covered | Perdue Farms, Koch Foods, Tyson Foods Inc., Wayne Farms LLC, Foster Farms, Cargill Inc., Sanderson Farms Inc., Maple Leaf Foods Inc., Pilgrim's Pride Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Poultry Meat Market Evolving Landscape
Digital traceability systems and alternative protein blending are compressing traditional processing workflows while regulatory pressure on animal welfare accelerates capital deployment into monitoring infrastructure.
Computer vision grading systems are bifurcating quality control operations across the North American poultry sector. High-volume plants in Georgia and Alabama are deploying real-time carcass inspection cameras that detect bruising and trim defects at line speeds exceeding 140 birds per minute. This automation is bifurcating the competitive landscape between capital-intensive operators achieving USDA compliance with reduced labor headcount and smaller processors facing stranded asset risk.
California Proposition 12 and Massachusetts Question 3 are mandating minimum space requirements for egg-laying hens and breeding sows with compliance deadlines cascading into broiler supply chain audits. These state-level animal welfare statutes are forcing national processors to segregate inventory streams and maintain dual certification documentation. The fresh retail segment in New England and Pacific Coast markets bears the highest compliance cost burden, passing through shelf price premiums of eight to twelve percent.
Restaurant procurement teams are consolidating supplier relationships around vertically integrated partners capable of delivering spec-consistent breast meat across twelve-month contracts. Independent operators and regional chains are abandoning spot market purchasing in favor of formula pricing tied to Chicago Mercantile Exchange grain futures. This consolidation is most pronounced in the southeastern United States, where Tyson Foods and Perdue Farms capture expanding share of food service volume through dedicated distribution agreements.
North America Poultry Meat Market Segmentation
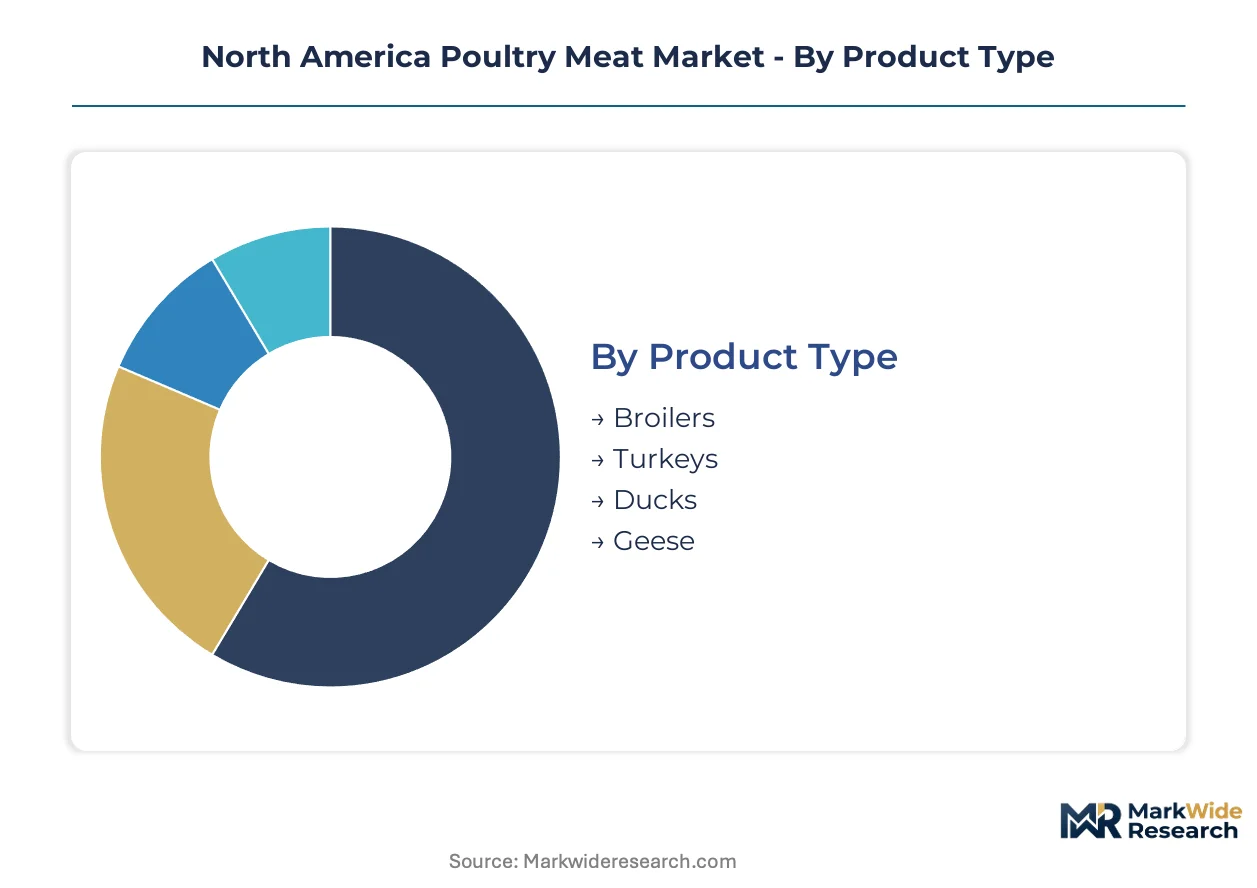
Segmentation in North American poultry meat reveals how regulatory pressure, processing economics, and channel dynamics allocate value across distinct product streams. Understanding these divisions exposes where capital requirements, compliance burdens, and margin capture concentrate for processors and distributors.
Product Type:
USDA grading standards and state-level animal welfare mandates create divergent compliance pathways across avian species, reshaping capital allocation and facility certification requirements.
- Broilers:Young chickens optimized for feed conversion efficiency deliver standardized breast and thigh cuts to quick-service restaurant specifications. Georgia and Alabama processing clusters supply eastern U.S. population centers through dedicated cold-chain logistics. Established volume favors broilers; emerging adoption favors turkeys.
- Turkeys:Heavier carcasses with elongated grow-out cycles serve seasonal whole-bird demand and year-round deli further-processing applications. Minnesota and North Carolina production anchors supply to Thanksgiving retail and food service contract channels.
- Ducks:Niche protein with higher fat content targets Asian-American demographic concentrations and fine-dining duck breast applications. California and New York distribution networks handle specialized slaughter and packaging protocols.
- Geese:Limited commercial volume concentrated in holiday specialty markets and ethnic food service procurement. Quebec and upstate New York maintain small-scale processing infrastructure for this segment.
Broilers dominate throughput economics; turkeys retain premium positioning through seasonal scarcity and further-processing value capture.
Processing Method:
Chilling protocols and shelf-life engineering determine distribution radius, inventory risk, and the regulatory density of FDA versus USDA jurisdiction boundaries.
- Fresh:Refrigerated product with abbreviated shelf windows demands rapid turnover through supermarket meat counters and direct-to-restaurant distribution. Shorter supply chains concentrate in southeastern production zones proximate to eastern seaboard consumption centers.
- Frozen:Blast-frozen carcasses and cuts enable national distribution, export staging, and inventory buffering against feed cost volatility. Midwest and Mid-Atlantic cold storage infrastructure supports this method's scale economics.
- Canned:Retort-processed poultry targets emergency preparedness retail and institutional feeding programs with extended stability requirements. Oklahoma and Arkansas canneries serve military and school nutrition procurement.
- Cooked:Ready-to-eat segments face stringent Listeria prevention protocols under USDA-FSIS post-lethality guidance, elevating plant sanitation capital requirements. Deli counter and food service prepared foods drive this segment's expansion.
Frozen processing commands volume scale; fresh product lines capture margin through supply chain compression and retail premium positioning.
Distribution Channel:
Channel selection dictates cold-chain infrastructure investment, payment terms, and the granularity of demand data available to upstream processors.
- Supermarkets:Corporate meat department buyers negotiate volume contracts with specification consistency requirements, favoring vertically integrated suppliers with dedicated case-ready operations. Kroger and Albertsons banners in Texas and California set procurement standards.
- Wholesalers:Broadline distributors aggregate fragmented food service demand, absorbing inventory risk and credit exposure for independent restaurants. Sysco and US Foods route poultry through regional redistribution centers.
- Online Retail:Direct-to-consumer subscription and meal-kit channels require portion-controlled packaging and last-mile cold-chain integrity. Instacart and Amazon Fresh partnerships reshape fulfillment economics.
- Convenience Stores:Grab-and-go prepared chicken segments demand smaller pack sizes and extended shelf-life engineering through modified atmosphere packaging. 7-Eleven and Circle K procurement concentrates in rotisserie and fried applications.
Supermarket consolidation favors scale suppliers; online retail channels expand fastest through data-capture advantages and subscription retention models.
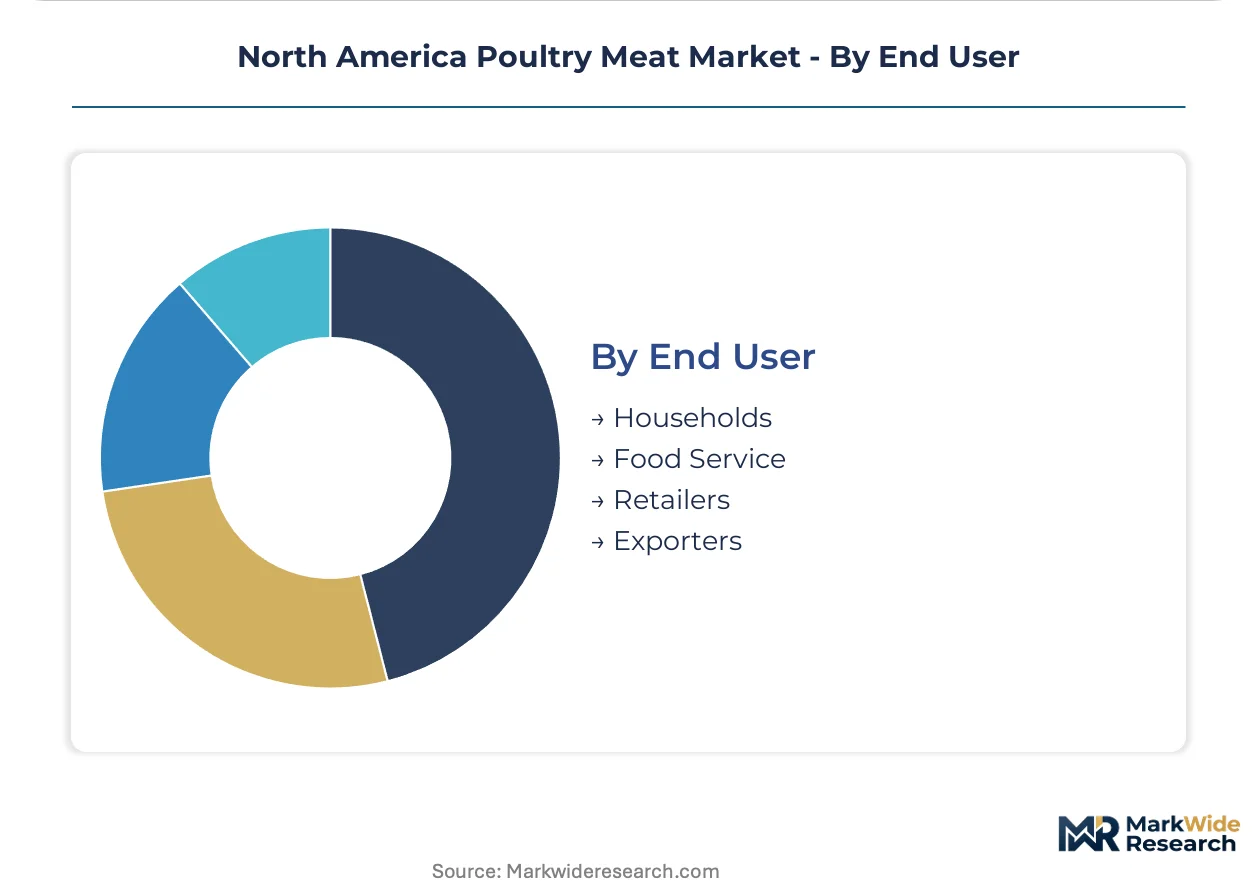
End User:
Final demand composition determines product form, certification requirements, and the pricing power available across contract versus spot market negotiations.
- Households:Retail consumers select on price-per-pound, organic certification badges, and convenience attributes like pre-trimmed or marinated offerings. Suburban and exurban demographics in Sun Belt states drive volume.
- Food Service:Quick-service chains and casual dining operators prioritize spec-consistent breast meat with predictable yield for portion control. McDonald's and Chick-fil-A procurement teams enforce supplier audit protocols.
- Retailers:Private-label development by supermarket banners requires co-manufacturing partnerships with processors capable of dual-brand production lines. Trader Joe's and Costco specifications illustrate this demand.
- Exporters:Mexican and Asian market access depends on USDA export certification and phytosanitary compliance with destination country requirements. Port infrastructure at Houston and Savannah supports this trade.
Food service procurement commands contract discipline; household consumption provides demand stability through recession-resistant protein substitution patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA inspection protocols anchor production economics across the United States, while Health Canada and PMRA standards govern Canadian feed additive compliance. Mexico's SENASICA certification requirements shape cross-border trade flows through the southeastern processing corridor.
United States
Quick-service restaurant procurement and supermarket consolidation drive volume concentration in Georgia, Alabama, and Arkansas processing clusters. USDA-FSIS updated inspection modernization rules compress compliance timelines for high-volume plants. Tyson Foods and Perdue Farms anchor integrated operations across these southeastern states, securing workforce stability through captive grow-out networks.
Canada
Asian export channel access through Vancouver ports and underdeveloped prairie broiler capacity attract greenfield investment in Manitoba and Saskatchewan. Health Canada feed additive regulations and CFIA slaughter inspection standards elevate capital requirements for market entry. Maple Leaf Foods maintains processing infrastructure in Ontario and Alberta, serving domestic retail and selective export segments.
Mexico
Cross-border live bird shipments and further-processed product flows respond to SENASICA phytosanitary certification and USDA export equivalence agreements. Domestic consumption growth in Mexico City and Monterrey metro areas supports regional processing expansion. Northern border states concentrate feed milling and grow-out operations tied to US supply chain integration.
North America Poultry Meat Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North American poultry meat market. Tyson Foods, Pilgrim's Pride, and Sanderson Farms occupy the consolidated top tier through captive feed milling, hatchery, and processing networks. Mid-scale specialists differentiate through antibiotic-free certification and organic product lines. Competitive moves concentrate on backward integration into feed grain sourcing and geographic expansion into underdeveloped Canadian prairie capacity.
Among US-based integrated processors, Tyson Foods Inc., Perdue Farms, and Koch Foods exemplify distinct strategic archetypes. Tyson Foods represents scale-driven vertical coordination across southeastern production clusters. Perdue Farms occupies premium positioning through Process Verified antibiotic-free and organic certification protocols. Koch Foods anchors volume throughput in the Midwest despite regional labor tightness, sustaining capacity utilization through dedicated food service contracts.
| Leading Market Players |
|---|
| Perdue Farms |
| Koch Foods |
| Tyson Foods Inc. |
| Wayne Farms LLC |
| Foster Farms |
| Cargill Inc. |
| Sanderson Farms Inc. |
| Maple Leaf Foods Inc. |
| Pilgrim's Pride Corporation |
| Others |
Value Network & Pricing Analysis
Soybean meal substitution for fishmeal in grower diets redraws feed sourcing maps across the Midwest while compressing protein input costs for processors in Georgia and Alabama. This input swap simultaneously weakens coastal rendering facility economics and strengthens inland crush plant throughput, redistributing margin capture between feed mills and integrated poultry operators.
Pricing Analysis
Georgia-to-Chicago price spreads for breast meat cuts widen during Midwest harvest season when local supply peaks. Contract-based long-term offtake dominates food service procurement, with price differentiation resting on USDA Process Verified certification and volume scale commitments. Pricing pressure stems from feed grain cost volatility during El Niño cycles. Quick-service chains exhibit highest price sensitivity; premium organic retail channels remain least elastic.
Supply Chain Analysis
Mississippi River barge chokepoints during low-water episodes constrain corn and soybean meal flows to southeastern feed mills. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on Midwest corn, Brazilian soybean imports, and domestic rendering byproducts. Single-source vulnerability runs through concentrated hatchery genetics suppliers. Distribution feeds from processor-owned cold storage through broadline redistributors to food service endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-level animal welfare mandate fragmentation splinters procurement specifications, creating white-space openings for certified-specialist processors that national volume players cannot efficiently serve.
For Market Incumbents: Compound captive grow-out network coverage in Arkansas and Mississippi to lock in workforce-accessible capacity ahead of USDA inspection modernization deadlines. Deepen backward integration into feed grain origination to buffer margin compression during drought cycles. Prioritize antibiotic-free certification line extensions to defend shelf space against emerging organic specialists. For New Entrants and Emerging Players: USDA Process Verified fast-track certification opens supermarket private-label doors without requiring decade-long brand equity investment. Target underpenetrated Canadian prairie broiler capacity in Manitoba and Saskatchewan where regulatory density lags US southeastern clusters. Lead with direct-to-restaurant distribution bypassing Sysco and US Foods markups to capture demand data and margin simultaneously. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale antibiotic-free specialists with established certification documentation and underutilized plant capacity. Long-term viability hinges on portfolio exposure to state-level compliance divergence rather than pure volume scale. Watch California Proposition 12 audit enforcement intensity as the signal for accelerated national SKU segmentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Grain Origination | Captures margin from Midwest corn and soybean meal cost swings during drought cycles. |
| Antibiotic-Free Certification Line Extension | Opens premium retail channels in California and Massachusetts compliance jurisdictions. |
| Direct-to-Restaurant Cold-Chain Distribution | Bypasses broadline distributor markups while capturing food service demand data. |
| Canadian Prairie Greenfield Capacity Buildout | Accesses Asian export channels through Vancouver with lower regulatory density. |
| Automated Deboning Equipment Deployment | Reduces labor headcount exposure in Arkansas and Mississippi processing plants. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with poultry procurement directors at quick-service chains, plant operations managers in Georgia and Alabama processing clusters, feed mill procurement leads, and USDA-FSIS compliance officers. Secondary validation drew from USDA poultry slaughter reports, EPA rendering facility emissions filings, Chicago Mercantile Exchange grain futures data, and state-level animal welfare regulatory filings. Bottom-up volume modeling triangulated against top-down industry association estimates.
Across the analysis window, forecasts reflect segment-level modeling across product type, processing method, distribution channel, and end-user category dimensions. CAGRs were derived from historical volume trajectories adjusted for feed cost elasticity and regulatory compliance cost pass-through assumptions. Industry-specific inputs included hatchery capacity expansion pipelines and state-level cage-free mandate implementation timelines.
Underlying assumptions cover stable corn and soybean meal supply availability, with deviation risk concentrated in El Niño drought severity and immigration enforcement surges affecting southeastern plant labor pools. Practitioners should keep alternative scenarios live as California Proposition 12 audit protocols and Massachusetts Question 3 enforcement standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Kosher Beef Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Global Beef Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Beef Fat Market
Meat Products
Raw Chicken Feet Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Smokehouse Market
Meat Products
Meat Tenderizer Market
Meat Products
Pork Meat Market
Meat Products
United States Animal Protein Market
Meat Products
Low-Fat Ham Market
Meat Products
Qatar Poultry Meat Market