
 United States Animal Protein Market | 2026-2036
United States Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Animal Protein Market Analytics
The EPA's concentrated animal feeding operation discharge rules is hardening compliance costs for large-scale processors. Tyson Foods dominates beef and poultry slaughter capacity across the southern Plains. Cargill leverages its grain-to-meat supply chain to control feed costs and finished protein margins. Darling Ingredients specializes in rendering and upcycling byproducts into higher-value protein meals.
United States animal protein encompasses the commercial production, processing, and distribution of muscle tissue and edible co-products from cattle, poultry, swine, and sheep, typically graded by USDA quality systems for marbling, maturity, and yield. The category serves as the primary dietary protein source for American consumers and as a functional ingredient base for processed foods. Beef occupies the premium price tier in retail and foodservice channels, while poultry sustains the highest volume throughput due to feed conversion efficiency and shorter production cycles. Frozen packaging leads in institutional and export channels, though chilled vacuum packs capture expanding supermarket shelf space.
USDA Food Safety and Inspection Service mandates daily microbial testing and hazard controls at all federally inspected plants. The FDA oversees feed additive approvals and veterinary drug residue limits under its animal food jurisdiction. State agriculture departments supplement federal rules with branded beef certification programs and interstate shipment health certificates. Stakeholders must track how California's Proposition 12 implementation and similar state-level confinement standards reshape sourcing requirements across integrated supply chains.
Market Dynamics
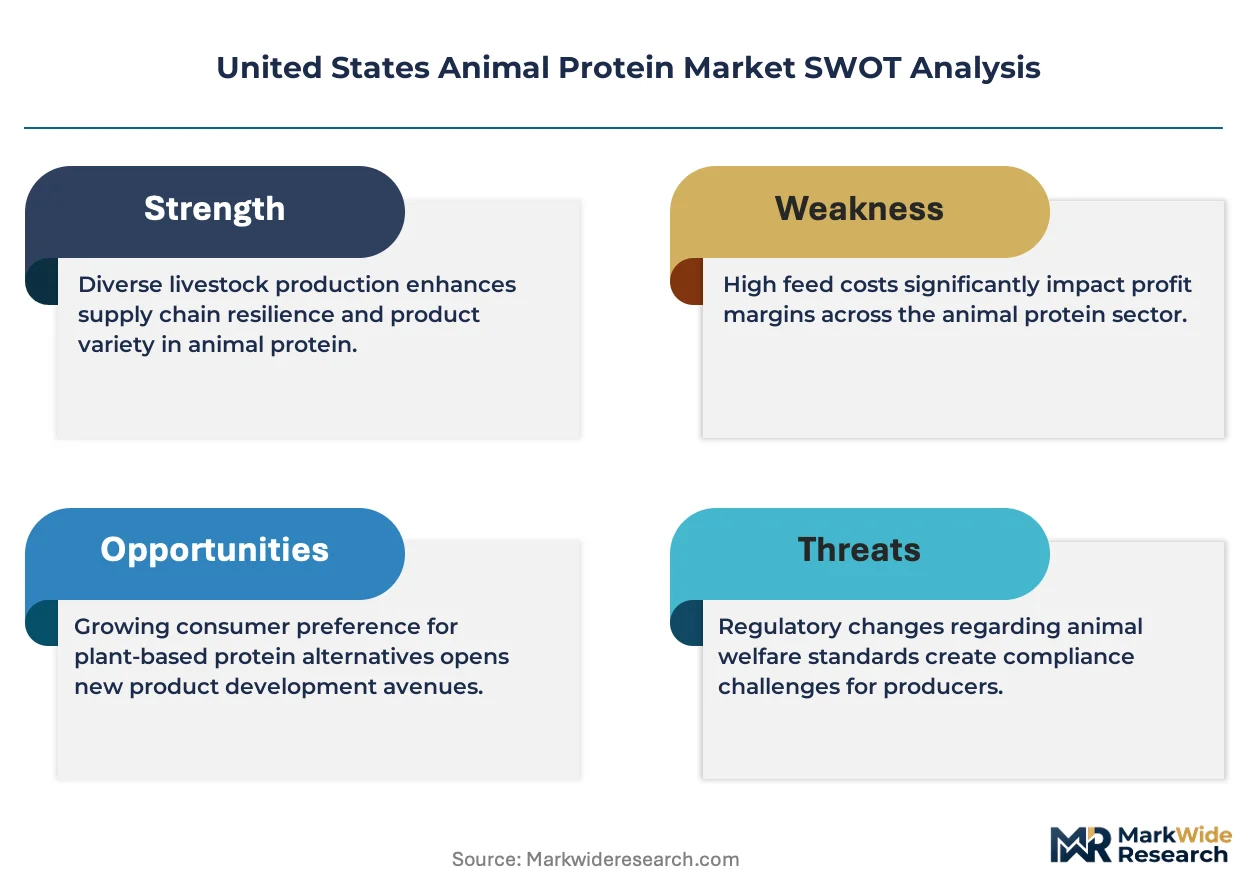
USDA's tightened pathogen testing protocols are forcing processors to rebuild slaughter-line configurations and cold-chain verification systems, compressing margins while accelerating automation adoption across federally inspected plants.
Growth Catalysts
- Proposition 12 compliance infrastructure:California's confinement standards are triggering barn retrofits across Iowa-Minnesota pork operations, creating demand for penning systems and veterinary oversight services.
- Feed conversion efficiency gains:Poultry integrators in the Delmarva Peninsula are deploying precision nutrition algorithms that shorten grow-out cycles and reduce per-pound feed input.
- Rendering upcycling economics:Darling Ingredients and independent renderers are expanding capacity to convert slaughter byproducts into pet food proteins and aquaculture meals.
Market Restraints
- EPA discharge compliance costs:Concentrated animal feeding operations face six-figure wastewater system upgrades under revised Clean Water Act enforcement, particularly in the Texas Panhandle.
- Feed grain price volatility:Corn and soybean meal inputs swing with drought cycles in the Corn Belt, compressing processor margins during El Niño years.
- Slaughter capacity concentration:Four firms control over 80 percent of federally inspected beef kill capacity, creating chokepoints during plant downtime or labor disputes.
Strategic Opportunities
- Cell-cultured protein co-manufacturing:USDA-FSIS joint oversight frameworks are opening inspected plant space for cultivated meat startups seeking licensed slaughter alternatives.
- Direct-to-processor rancher contracts:Grass-fed and branded beef programs in the Northern Plains are bypassing commodity auction systems through vertical marketing agreements.
- Precision fermentation feed additives:Methane-reducing supplements for cattle are gaining FDA Center for Veterinary Medicine approvals, creating new input categories for feed mills.
Industry Challenges
- Veterinary pathologist shortages:USDA-FSIS requires daily ante-mortem inspection coverage that rural slaughter communities struggle to staff, delaying plant certifications.
- Legacy ERP integration with traceability mandates:Federal lot-tracking requirements are forcing mid-sized processors to replace decades-old inventory systems without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Animal Protein Market |
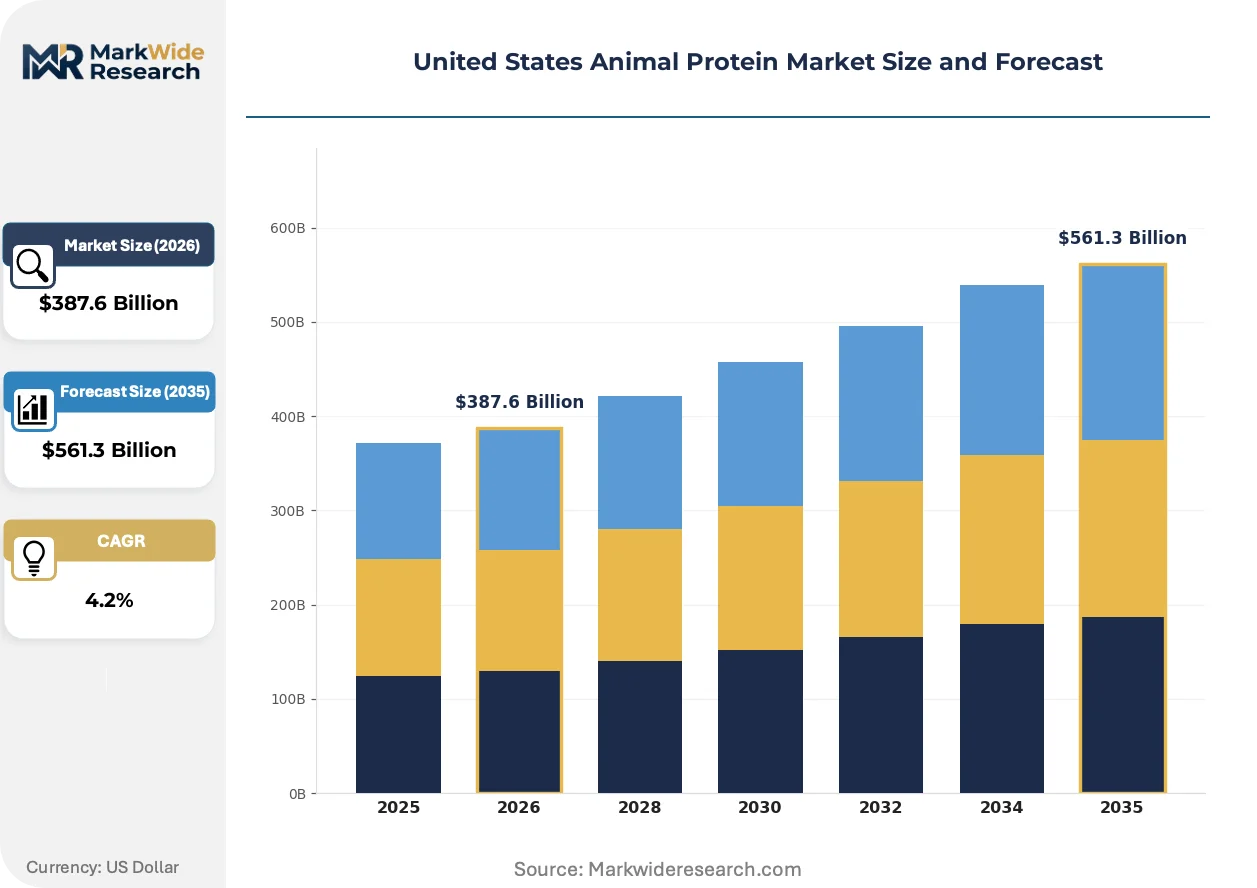
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Lamb End User: Restaurants, Retailers, Food Processors, Households Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Packaging Type: Vacuum Packs, Canned, Frozen, Chilled |
| Companies Covered | Glanbia PLC, Arla Foods amba, Darling Ingredients Inc., Fonterra Co-operative Group Limited, Kerry Group PLC, Cargill, Inc., Archer Daniels Midland Company, Tyson Foods, Inc., Royal FrieslandCampina, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Animal Protein Market Evolving Landscape
Automation and alternative protein technologies are compressing traditional slaughter economics while reshaping how processors defend margin positions across beef, pork, and poultry channels.
Vision-guided robotic carcass splitting is consolidating labor-dependent tasks at beef and pork plants. JBS and Cargill installations in Nebraska and Colorado are achieving 95 percent yield consistency on hindquarter breakdowns, reducing skilled knife-work roles by 40 percent while accelerating line speeds during peak cattle receipts.
USDA-FSIS and FDA are harmonizing oversight frameworks for cell-cultured meat production, creating dual-jurisdiction inspection protocols that require HACCP modifications at co-manufacturing facilities. This regulatory convergence is forcing traditional processors to reconfigure plant layouts for segregated production lines, with pilot facilities in California and Texas absorbing the earliest compliance costs.
Foodservice distributors are consolidating procurement through contracted specification programs rather than spot commodity purchases. Sysco and US Foods are locking multi-year volume commitments with processors who can guarantee consistent marbling scores and delivery windows, shifting pricing power toward buyers with national warehouse networks and compressing regional processor margins in the Southeast and Southwest.
United States Animal Protein Market Segmentation
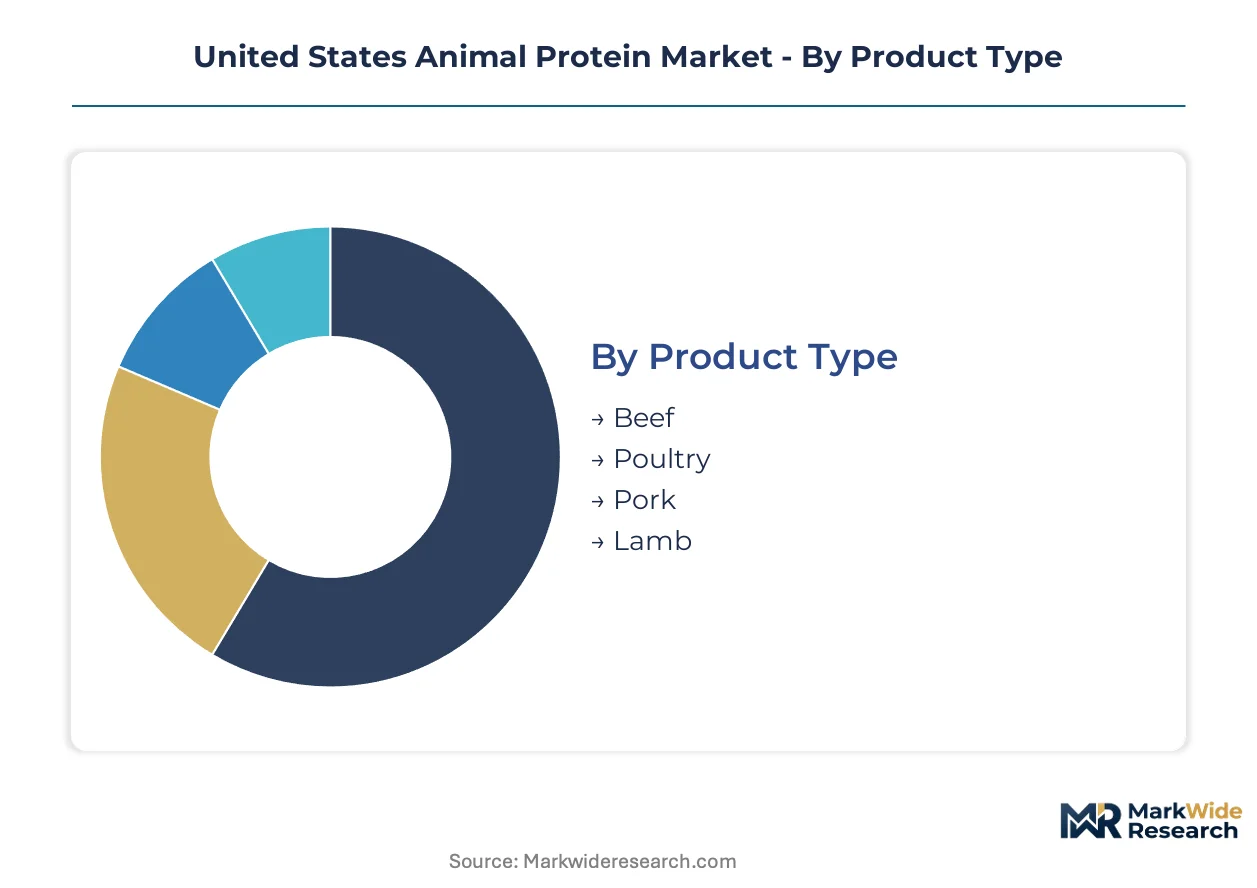
Protein procurement patterns across the United States fragment sharply by product chemistry, buyer operational requirements, and cold-chain infrastructure availability. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape processor investment priorities.
Product Type:
Upgrade cycles in breeding genetics and feed formulation chemistry are accelerating species-specific capacity investments across federally inspected plants.
- Beef:USDA-graded muscle tissue from cattle, distinguished by marbling scores and maturity classifications that determine premium retail positioning. Demand concentrates in the Texas-Oklahoma cattle corridor, where drought-resistant genetics and grain-finishing capacity support branded program growth despite feed cost volatility.
- Poultry:Broiler and turkey muscle tissue with superior feed conversion ratios and compressed grow-out cycles versus red meat alternatives. Volume leadership in the Delmarva Peninsula reflects integrator control over hatchery-to-processing vertical coordination, with precision nutrition algorithms shortening production timelines.
- Pork:Swine-derived protein graded by lean yield percentages and processed into fresh cuts, cured products, and rendering inputs. Iowa-Minnesota operations dominate slaughter capacity, though California Proposition 12 compliance is forcing barn retrofit investments across the Corn Belt.
- Lamb:Smaller-volume ovine protein serving ethnic foodservice channels and specialty retail, with production concentrated in Rocky Mountain and Northern Plains grazing operations.
Poultry sits at the top of the volume ranking, with beef climbing the fastest on per-pound value expansion in branded and grass-fed channels.
End User:
Cost tier differentiation separates commodity spot buyers from contracted specification programs that demand consistent quality documentation.
- Restaurants:Foodservice operators ranging from independent operators to national chains requiring portion-controlled cuts and specified fat content. Quick-service chains in the Southeast are locking multi-year supply agreements to secure price stability against feed grain volatility.
- Retailers:Supermarket chains and club stores demanding case-ready packaging, private label programs, and traceability documentation for E. coli and Salmonella compliance. Chilled vacuum packs are displacing frozen alternatives in perimeter meat cases.
- Food Processors:Manufacturers of prepared meals, sausages, and further-processed items requiring standardized trim specifications and lot-level pathogen testing certificates.
- Households:Direct-to-consumer channels including farmers markets, community-supported agriculture programs, and online subscription services for specialty proteins.
Restaurants command the largest procurement volume, with retailers gaining share fastest through private label expansion and case-ready format adoption.
Distribution Channel:
Geographic concentration of cold-storage infrastructure determines channel viability for temperature-sensitive protein formats.
- Supermarkets:Traditional grocery retail with dedicated meat counter service and self-service case-ready sections. Chilled distribution networks in the Midwest and Northeast support same-day replenishment cycles.
- Convenience Stores:Limited-assortment retail focused on grab-and-go prepared proteins and frozen commodity items for immediate consumption.
- Online Retail:Direct-to-door delivery platforms requiring insulated packaging and last-mile cold-chain integrity, expanding fastest in coastal metropolitan markets.
- Wholesalers:Broadline distributors serving institutional accounts, independent restaurants, and export consolidators with frozen bulk formats and specification purchasing.
Supermarkets retain volume leadership, with online retail expanding most quickly on subscription model adoption and urban delivery density improvements.
Packaging Type:
Margin structure varies sharply by packaging technology investment requirements and shelf-life extension capabilities.
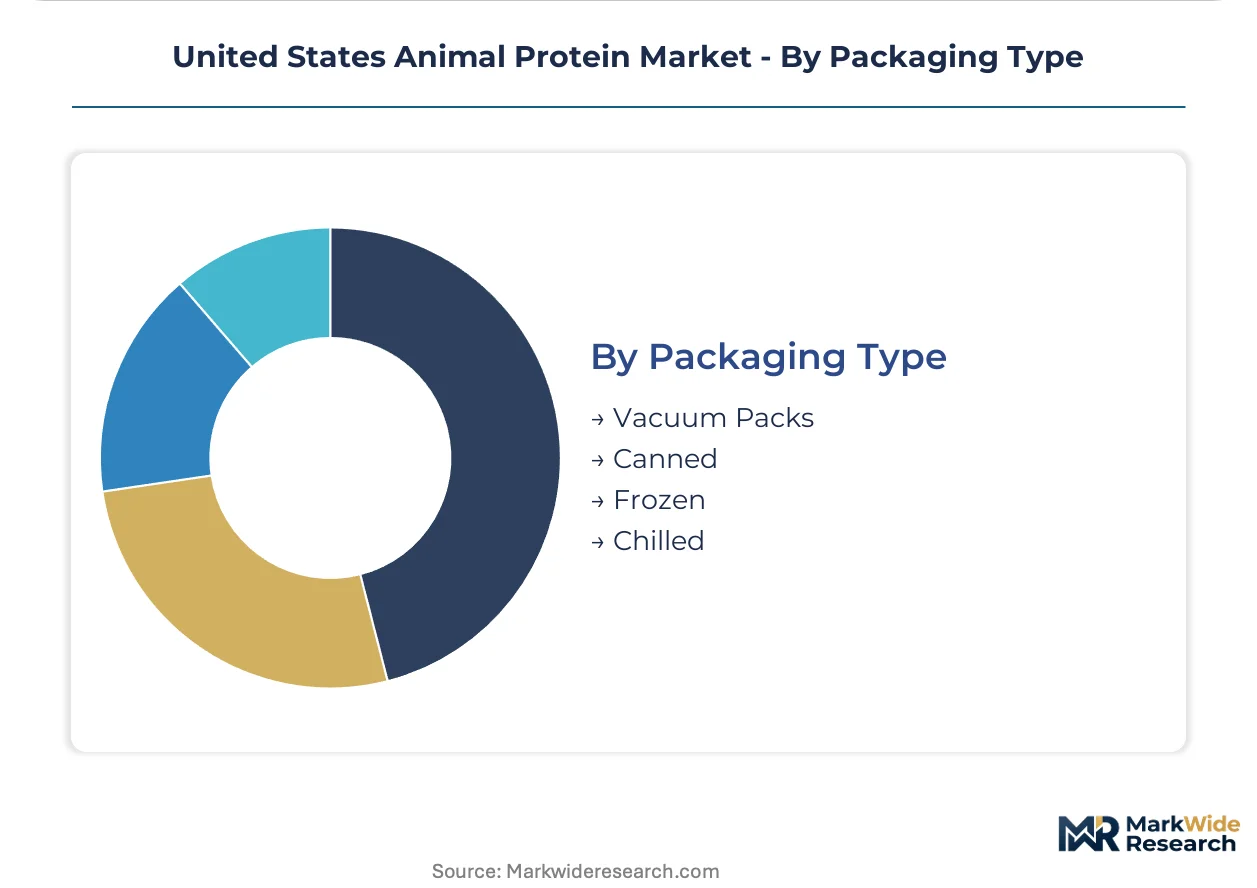
- Vacuum Packs:Modified-atmosphere packaging removing oxygen to extend retail case life and reduce shrink. Chilled vacuum packs are capturing expanding supermarket shelf space in the Northeast and West Coast.
- Canned:Thermally processed protein in shelf-stable containers serving emergency preparedness, military, and international aid channels with minimal cold-chain requirements.
- Frozen:Blast-frozen muscle tissue preserved at sub-zero temperatures for institutional and export channels with extended storage timelines. Frozen packaging leads in export shipments to Pacific Rim markets.
- Chilled:Refrigerated fresh product with limited shelf life demanding continuous cold-chain maintenance from plant to retail case.
Frozen formats dominate export and institutional volume, with vacuum packs gaining share fastest on retail premium positioning and waste reduction metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States animal protein industry traces its modern scale to post-war vertical integration in the Midwest and Southern Plains, where grain surplus and rail infrastructure enabled feedlot concentration. Today's regional map reflects that legacy, with processing capacity clustering near corn supply and interstate logistics corridors.
Texas-Oklahoma Cattle Corridor
Feedlot operators here manage the nation's largest concentration of grain-finished cattle, drawing on High Plains groundwater and Panhandle grain elevators. EPA discharge enforcement under revised Clean Water Act rules is forcing six-figure wastewater upgrades in the Texas Panhandle. Amarillo and Lubbock anchor rendering and packing capacity that ships boxed beef to Pacific Rim export terminals.
Iowa-Minnesota Pork Belt
Swine slaughter capacity concentrates in this Corn Belt heartland, with integrators controlling farrow-to-finish operations across rural counties. California Proposition 12 compliance is triggering barn retrofits for gestation penning systems and expanded veterinary oversight. Sioux Falls and Des Moines processing plants are reconfiguring line layouts to accommodate slower-throughput welfare-compliant handling.
Delmarva Peninsula Poultry Cluster
Broiler integrators exploit the Chesapeake Bay watershed's grain delivery position and mid-Atlantic port access for export loading. Precision nutrition algorithms are shortening grow-out cycles while reducing per-pound feed input across Sussex County operations. Salisbury and Georgetown processing complexes supply case-ready product to Northeast retail chains.
Nebraska-Colorado Beef Processing
High-capacity slaughter plants here benefit from proximity to Northern Plains grazing and Central Plains grain finishing. USDA-FSIS daily microbial testing mandates are accelerating automation adoption for carcass splitting and cold-chain verification. Greeley and Grand Island facilities are deploying vision-guided robotics to reduce skilled knife-work roles by 40 percent.
California Protein Innovation Corridor
The state's confined animal feeding rules are reshaping sourcing requirements for integrated supply chains serving West Coast consumers. USDA-FSIS and FDA dual-jurisdiction frameworks for cell-cultured meat are opening inspected plant space for cultivated protein startups. Sacramento Valley pilot facilities are absorbing earliest compliance costs for segregated production line reconfiguration.
United States Animal Protein Market Competitive Landscape
Premium-margin players sit above commodity-margin players across branded program and private-label channels, with the former capturing value through certification documentation and the latter competing on throughput scale. Four firms control over 80 percent of federally inspected beef kill capacity, creating structural chokepoints during plant downtime. Strategic archetypes span integrated grain-to-meat conglomerates, specialist renderers and upcyclers, and precision nutrition technology vendors. Dominant competitive moves include backward integration into feed milling and captive cattle procurement, plus co-manufacturing partnerships with cell-cultured protein startups seeking licensed slaughter alternatives.
Within the integrated conglomerate tier, Tyson Foods and Cargill exemplify scale-driven positioning across beef and poultry channels, while Darling Ingredients occupies a specialist role in rendering and byproduct upcycling. These three anchors demonstrate how protein procurement strategy fragments between volume throughput optimization and higher-margin circular economy models.
| Leading Market Players |
|---|
| Glanbia PLC |
| Arla Foods amba |
| Darling Ingredients Inc. |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Cargill, Inc. |
| Archer Daniels Midland Company |
| Tyson Foods, Inc. |
| Royal FrieslandCampina |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between USDA Prime branded programs and commodity Select beef creates divergent margin architectures that reshape procurement patterns across the Texas-Oklahoma corridor and Corn Belt finishing operations. Premium tiers command captive supply chains with verified genetics and documented welfare protocols, while commodity channels compete on throughput scale and feed cost arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transactions in federally inspected plants, with USDA quality grades and branded program certifications as the primary price differentiation drivers. Pricing pressure stems from feed grain volatility during drought cycles, compressing processor margins in the Texas Panhandle. Quick-service chains exhibit the highest price sensitivity through contracted volume commitments, while specialty retailers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from USDA-FSIS and FDA oversight frameworks mandate segregated production line qualifications for cell-cultured meat co-manufacturing in California and Texas pilot facilities. Geographic supply concentration centers on the United States Corn Belt for feed grains, the Texas-Oklahoma corridor for cattle finishing, and the Delmarva Peninsula for broiler integration. Raw material dependencies include corn and soybean meal for feed formulation, veterinary pharmaceuticals for health protocols, and packaging materials for cold-chain integrity. Single-source vulnerability concentrates in four-firm beef slaughter control, creating chokepoints during plant downtime. Distribution runs through national broadline distributors with regional cold-storage networks serving retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States animal protein market functions as a stable compounder anchored by irreplaceable dietary protein demand and continuous efficiency gains in poultry feed conversion. Structural consolidation and regulatory compliance investments reinforce incumbent positions while creating selective entry points for specialized operators.
For Market Incumbents: Lock in backward integration into captive cattle procurement and feed milling capacity across the Northern Plains to defend against margin compression from grain price volatility. Accelerate automation deployment for USDA-FSIS microbial testing compliance, replacing legacy ERP systems with traceability-enabled platforms before federal mandates harden. For New Entrants and Emerging Players: Capture white-space opportunity in precision fermentation feed additives for methane reduction, securing FDA Center for Veterinary Medicine approvals ahead of incumbent R&D cycles. Target direct-to-processor rancher contracts in grass-fed and branded beef programs, bypassing commodity auction systems through vertical marketing agreements with Northern Plains grazing operations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialist renderers and upcycling operators converting slaughter byproducts into pet food proteins and aquaculture meals. The five-to-ten-year viability window favors acquisition targets with circular economy positioning and regulatory-compliant infrastructure. Watch for USDA-FSIS pilot facility certifications for cell-cultured meat co-manufacturing as the inflection signal indicating licensed slaughter alternative viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Cargill and Tyson Foods control grain-to-meat supply chains, insulating margins from corn price volatility. |
| Automation Deployment for Pathogen Testing | JBS installations in Nebraska achieve 95 percent yield consistency while reducing skilled labor roles. |
| Proposition 12 Compliance Infrastructure | Barn retrofits across Iowa-Minnesota operations create demand for penning systems and veterinary oversight services. |
| Cell-Cultured Protein Co-Manufacturing | USDA-FSIS and FDA dual-jurisdiction frameworks open inspected plant space for cultivated meat startups. |
| Rendering and Upcycling Capacity Expansion | Darling Ingredients converts slaughter byproducts into higher-value protein meals for pet food and aquaculture. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at federally inspected facilities, procurement leads at broadline distributors, feed mill operations directors, and USDA-FSIS compliance officers with secondary validation. Secondary sources included USDA production and price reporting databases, EPA discharge enforcement records, FDA veterinary drug approval filings, and state agriculture department health certificate registries. Bottom-up capacity modeling and top-down consumption estimates were triangulated against trade flow data.
Comparable-period anchoring tied projection assumptions to historical feed conversion efficiency trends, pathogen testing compliance cost trajectories, and regional slaughter capacity utilization patterns across the analysis window. Segmentation dimensions modeled included species type, USDA quality grade tier, distribution channel format, and end-user procurement specification level. CAGRs were derived from trend extrapolation of poultry integrator volume growth, beef branded program premium capture, and pork export demand elasticity. Industry-specific inputs incorporated El Niño drought cycle frequency and Proposition 12 barn retrofit completion timelines.
Feed grain price shocks, EPA enforcement intensity variations, and veterinary pathologist availability constraints are the dominant revision risks to modeled outcomes. Deviation in drought severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Hams Market
Meat Products
Low Fat Beef Market
Meat Products
Canned Beef Market
Meat Products
Meat Products Market
Meat Products
Meat Emulsions Market
Meat Products
Organic Meat Market
Meat Products
Bacon Slicers Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Europe Meat Products Market
Meat Products
Organic Lamb Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Brisket Market
Meat Products
United States Bacon Market
Meat Products
North America Poultry Meat Market
Meat Products
Middle East Edible Meat Market