
 US Restaurant Point of Sale Solution Market | 2026-2036
US Restaurant Point of Sale Solution Market Size, Share, and Industry Trends Forecast 2026-2036
US Restaurant Point of Sale Solution Market Intelligence
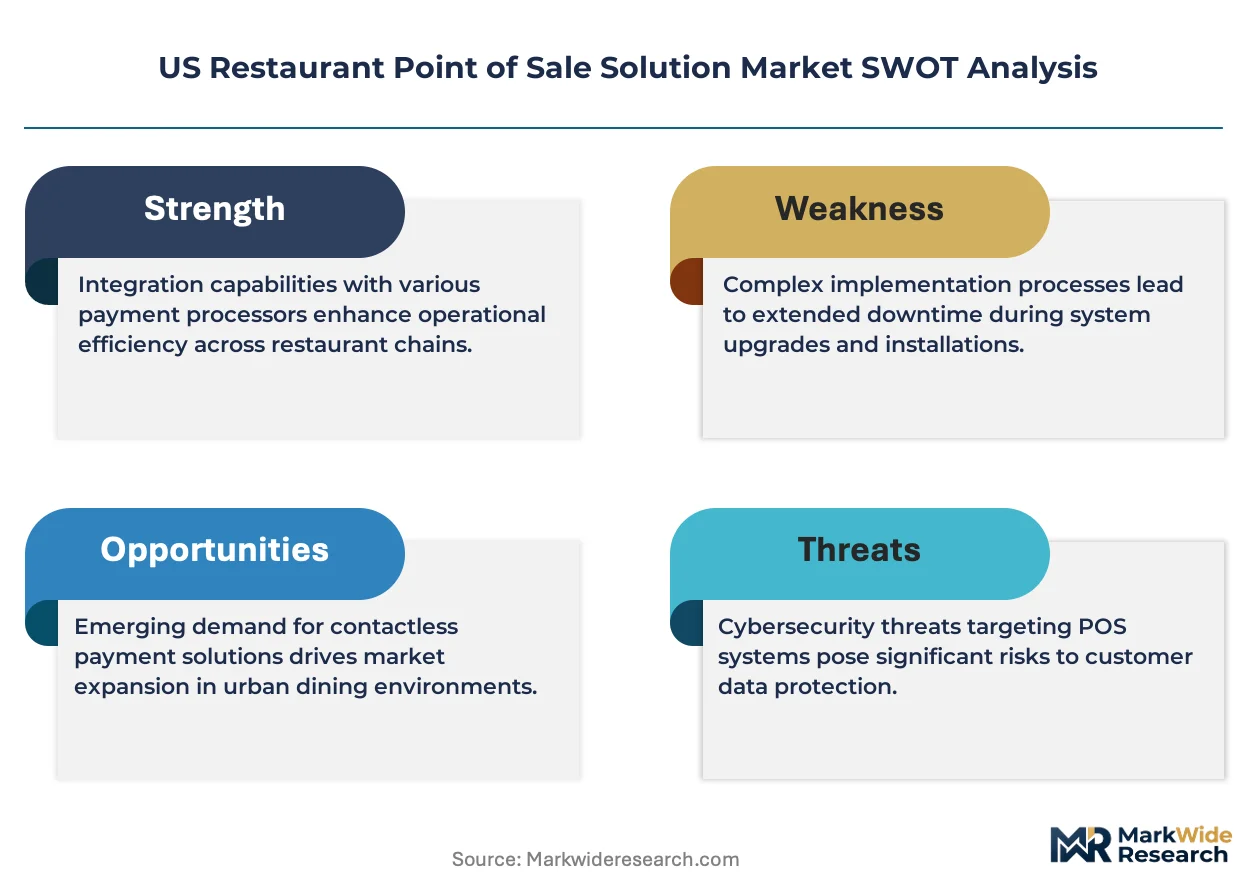
The split between integrated premium stacks and stripped-down commodity hardware is hardening across the US restaurant technology landscape. Toast Inc. leverages its native payroll and inventory modules to anchor full-service deployments, while Square Inc. competes aggressively on onboarding speed for independent operators. NCR Corporation sustains its position through decades-long relationships with franchise chains and durable service infrastructure.
A restaurant point of sale solution constitutes an integrated hardware-software system that processes transactions, manages order flows, and coordinates kitchen operations through touchscreen terminals, mobile tablets, or cloud-connected peripherals with sub-second latency requirements. Cloud-based POS deployments are capturing the fastest expansion as operators prioritize remote management and real-time menu synchronization across locations. Terminal systems remain the largest revenue pool, though kiosk systems are carving out dedicated demand among quick service restaurants labor costs pressure counter operations. Contactless payment technology has shifted from differentiator to baseline expectation, compressing upgrade timelines for legacy EMV-noncompliant estates.
The Federal Trade Commission monitors payment processing transparency, while PCI DSS standards govern cardholder data security architecture across all deployed devices. State-level biometric privacy laws in Illinois and California are reshaping how facial recognition and fingerprint authentication features ship in next-generation terminals. Stakeholders must weigh total cost of ownership against modular upgrade paths as hardware refresh cycles compress and software subscription models deepen vendor lock-in dynamics.
Market Dynamics
The migration from on-premise terminal estates to cloud-native architectures is compressing hardware refresh cycles and redistributing vendor power toward software-centric platforms with integrated payment processing.
Growth Catalysts
- PCI DSS 4.0 compliance deadlines:The updated cardholder data security standard mandates encryption-at-rest for all stored transaction records, forcing legacy EMV-noncompliant operators into terminal replacement programs.
- Quick service restaurant labor automation:Kiosk-based ordering systems reduce counter staffing requirements while increasing average ticket size through algorithmic upsell prompts at the point of decision.
- California and Texas metropolitan corridor expansion:Multi-unit operators in these high-density markets prioritize unified technology stacks that enable real-time menu synchronization and centralized reporting across dispersed locations.
Market Restraints
- Hardware margin compression:Commoditized Android tablet terminals from Asian contract manufacturers erode pricing power for domestic equipment suppliers.
- Payment processor concentration:Three national acquirers control over 70 percent of restaurant card processing volume, extracting interchange-plus pricing leverage from POS platform providers.
- Biometric authentication regulatory friction:Illinois Biometric Information Privacy Act and California Consumer Privacy Act impose strict consent and retention requirements on fingerprint and facial recognition features.
Strategic Opportunities
- Mid-market full-service penetration:Independent restaurants with 50-150 seats remain underpenetrated by integrated payroll-inventory-loyalty bundles, presenting white space between Toast's premium positioning and Square's independent focus.
- Voice-activated kitchen display systems:Convergence of natural language processing with IoT-connected prep stations enables hands-free order modification during high-volume service windows.
- State-level data privacy harmonization:Emerging legislative frameworks in New York and Colorado create compliance service revenue streams for platforms that build privacy-by-design architectures.
Industry Challenges
- EMV certification timeline compression:Payment brand mandate acceleration leaves limited runway for terminal firmware validation, squeezing engineering resources at smaller hardware vendors.
- Legacy system integration complexity:Decades-old property management system and accounting software architectures resist API-native connectivity, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Restaurant Point of Sale Solution Market |
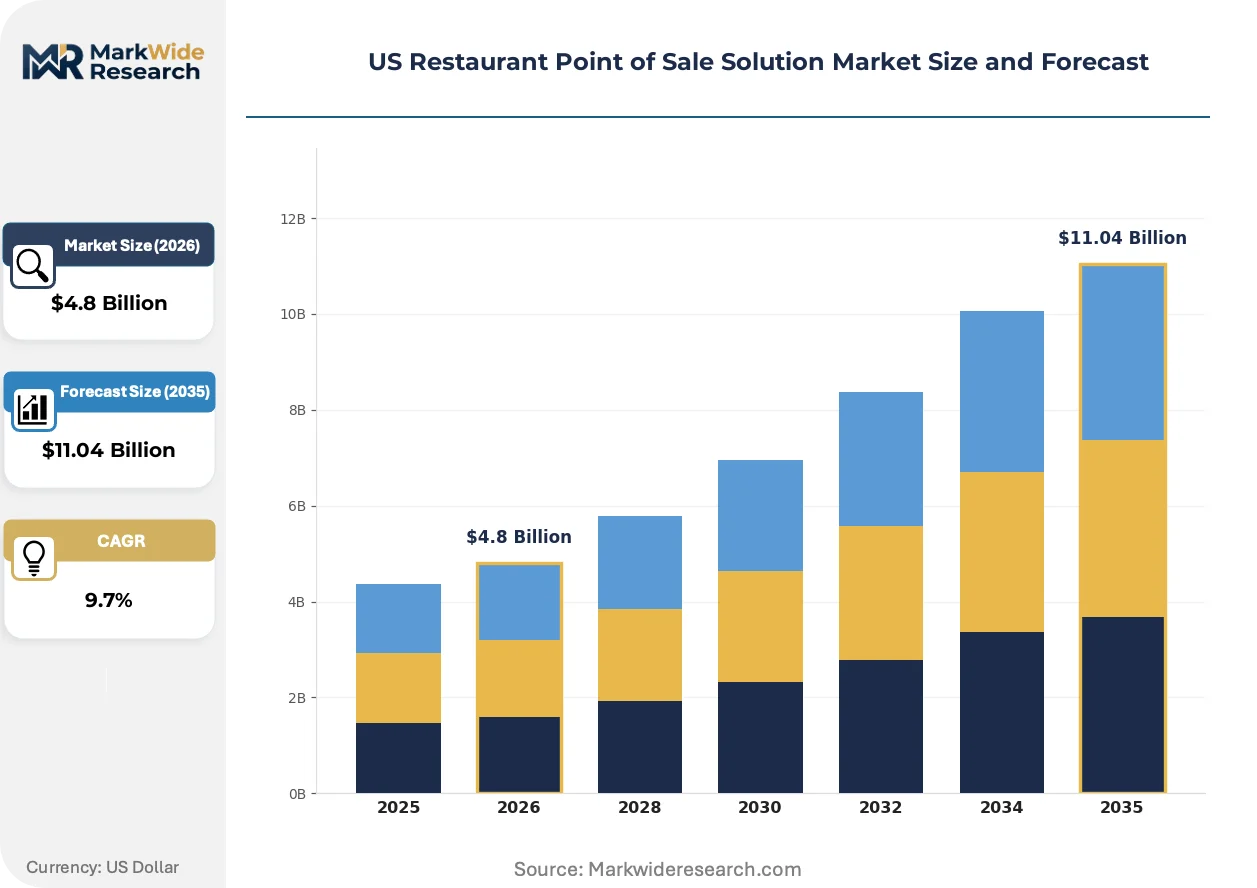
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal Systems, Mobile POS, Kiosk Systems, Cloud-Based POS Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Customer Type: Independent Restaurants, Franchise Chains, Food Trucks, Quick Service Restaurants Technology: Contactless Payments, EMV Compliance, Inventory Management, Analytics Tools |
| Companies Covered | Toast Inc., Square Inc., NCR Corporation, Clover Network Inc., Lightspeed POS Inc., Revel Systems Inc., SpotOn Transact Inc., Shift4 Payments LLC, PAR Technology Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Restaurant Point of Sale Solution Market Strategic Shifts & Innovations
Payment architecture, authentication protocols, and procurement models are undergoing simultaneous transformation, with cloud connectivity serving as the common substrate enabling each shift.
Software-defined POS terminals running on hardened Android distributions is overtaking proprietary embedded operating systems in new deployments. Quick service chains with 50-plus locations are adopting these platforms at the fastest clip, replacing five-to-seven-year hardware cycles with subscription-based refresh programs. This transition is overtaking the traditional capital expenditure model and compressing vendor selection criteria toward API extensibility and third-party integration depth.
The FTC's intensifying scrutiny of payment processing transparency is reshaping how platforms disclose effective rates and interchange pass-throughs to merchant customers. This enforcement posture elevates compliance costs for vertically integrated providers while creating differentiation opportunities for interchange-plus pricing advocates. Full-service independent operators in California and New York metropolitan markets are responding most aggressively, demanding itemized fee breakdowns before contract execution.
Subscription-based SaaS pricing has displaced perpetual license models across the mid-market segment, unbundling hardware acquisition from software access. Regional franchise chains with 10-40 units are driving this transition, prioritizing predictable monthly outlays over capital-intensive upfront investments. This pattern is most visible in Texas and Florida, where private-equity-backed rollups favor operational expenditure structures that preserve leverage capacity for acquisition activity.
US Restaurant Point of Sale Solution Market Segmentation
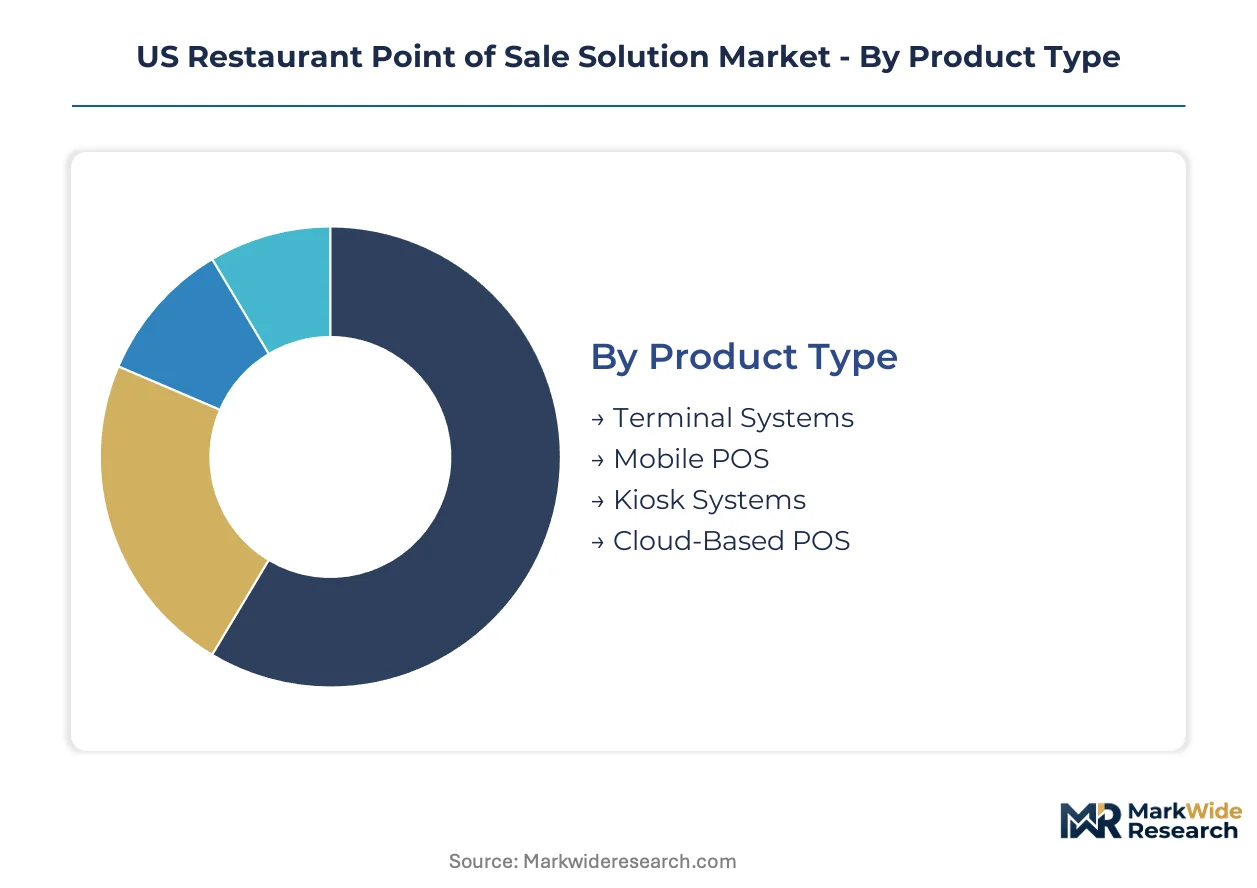
POS procurement decisions in the US restaurant sector hinge on operational scale, regulatory exposure, and labor automation priorities. The four segmentation dimensions reveal how technology stacks align with distinct buyer archetypes across the $4.8 billion market base.
Product Type:
Capital intensity and counter labor requirements drive product selection across full-service and quick service formats.
- Terminal Systems:Fixed touchscreen workstations with hardened Android or proprietary embedded operating systems process transactions through PCI DSS-certified hardware. Demand concentrates among full-service independents in California and New York metropolitan corridors where durability expectations extend five-to-seven years. FTC disclosure requirements on payment processing fees elevate buyer scrutiny of terminal-integrated pricing structures.
- Cloud-Based POS:Browser-native platforms running on commodity tablets enable real-time menu synchronization across dispersed locations. Multi-unit operators in Texas and Florida corridor expansions prioritize these systems for centralized reporting and subscription-based operational expenditure treatment. PCI DSS 4.0 encryption-at-rest mandates accelerate migration from legacy terminal estates.
- Mobile POS:Handheld tablets or smartphones with card readers serve tableside payment and curbside pickup workflows.
- Kiosk Systems:Self-service ordering terminals with algorithmic upsell modules reduce counter staffing in high-volume quick service environments.
Volume sits with Terminal Systems; growth tilts toward Cloud-Based POS.
Deployment:
IT resource availability and data sovereignty concerns shape infrastructure architecture decisions.
- Cloud-Based:Fully managed SaaS platforms eliminate local server maintenance and enable remote access for franchise oversight. Regional chains with 10-40 units in Texas and Florida private-equity rollups favor predictable monthly subscriptions over capital-intensive on-premise builds. State-level biometric privacy laws in Illinois and California impose consent architecture requirements on cloud-stored authentication data.
- Hybrid:Local transaction processing with cloud synchronization balances latency requirements with centralized analytics. Full-service operators in high-density California markets deploy hybrid stacks to maintain service continuity during connectivity interruptions while enabling corporate-level menu control.
- On-Premise:Dedicated server installations with perpetual software licenses persist among legacy franchise systems with customized integrations.
- Managed Services:Outsourced infrastructure operations with bundled support contracts appeal to resource-constrained independents.
Adoption momentum clusters with Cloud-Based deployments; Hybrid architectures retain share among connectivity-sensitive operators.
Customer Type:
Scale economics and standardization mandates create divergent technology requirements across ownership structures.
- Quick Service Restaurants:High-volume chains with standardized menus prioritize kiosk integration and kitchen display system synchronization. Labor automation pressures in California and Texas metropolitan markets drive algorithmic upsell deployment and contactless payment baseline requirements. PCI DSS compliance deadlines compress refresh cycles for EMV-noncompliant legacy estates.
- Franchise Chains:Corporate technology mandates enforce unified stacks across dispersed locations with centralized reporting obligations. Multi-unit operators in New York and Texas expansion corridors demand API extensibility for third-party delivery platform integration.
- Independent Restaurants:Owner-operated establishments with 50-150 seats seek modular bundles without enterprise complexity.
- Food Trucks:Mobile operators require ruggedized hardware with offline transaction capability and cellular connectivity.
Revenue concentration aligns with Franchise Chains; expansion velocity favors Quick Service Restaurants.
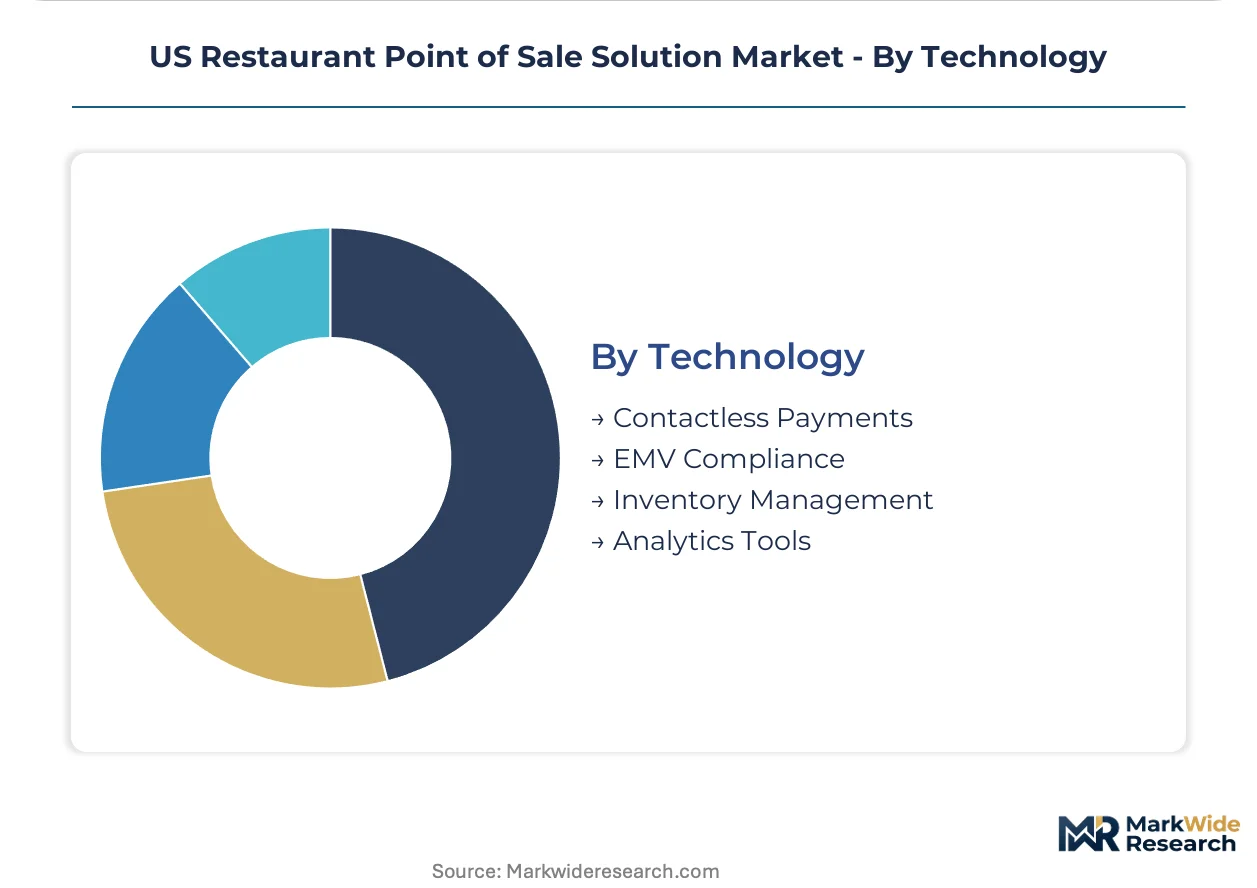
Technology:
Regulatory mandates and operational efficiency imperatives determine feature prioritization in procurement evaluations.
- Contactless Payments:NFC-enabled terminals supporting tap-to-pay cards and mobile wallets have shifted from competitive differentiator to baseline market entry requirement. California and New York metropolitan operators responded most aggressively to pandemic-accelerated consumer preference shifts, compressing upgrade timelines for legacy EMV-noncompliant hardware.
- EMV Compliance:Chip card authentication standards mandated by payment brands govern terminal certification requirements. Smaller hardware vendors face engineering resource constraints from accelerated certification timelines and firmware validation demands.
- Inventory Management:Real-time ingredient tracking and automated purchasing integration reduce waste in full-service operations.
- Analytics Tools:Sales velocity and labor optimization dashboards enable data-driven scheduling and menu engineering.
Deployment breadth sits with Contactless Payments; compliance urgency centers on EMV Compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan corridors anchor US restaurant POS deployment density, with Los Angeles and San Francisco Bay Area operators driving cloud-native platform adoption and PCI DSS 4.0 compliance refresh cycles.
California
Multi-unit operators in Los Angeles and San Francisco prioritize unified technology stacks with real-time menu synchronization. The California Consumer Privacy Act imposes strict biometric data retention requirements on fingerprint-enabled terminals. Silicon Valley software vendors and Orange County franchise headquarters concentrate R&D investment in API-native architectures.
Texas
Private-equity-backed restaurant rollups in Dallas-Fort Worth and Houston demand subscription-based operational expenditure models. The Texas Business and Commerce Code governs payment processing disclosure requirements for merchant contracts. Austin's technology corridor hosts emerging POS platform development labs serving mid-market chains.
New York Metro
Full-service independents in Manhattan and Brooklyn lead demand for itemized fee transparency in payment processing. The New York SHIELD Act mandates data breach notification protocols for cloud-stored customer records. Queens and Long Island food service clusters drive kiosk system deployment for labor cost reduction.
Florida
Quick service expansion in Miami-Dade and Orlando corridors accelerates contactless payment baseline requirements. The Florida Information Protection Act governs cardholder data security for multi-location operators. Tampa Bay franchise development zones concentrate EMV-compliant terminal replacement programs.
Illinois
Chicago metropolitan operators face the nation's strictest biometric authentication constraints. The Illinois Biometric Information Privacy Act requires explicit consent protocols for fingerprint and facial recognition features. Suburban franchise corridors in Cook and DuPage counties drive demand for privacy-by-design terminal architectures.
US Restaurant Point of Sale Solution Market Key Industry Players
Premium-margin players sit above commodity-margin players across the integration depth spectrum, with full-stack providers commanding higher lifetime value per merchant than hardware-centric vendors. The market structure consolidates around three tiers: vertically integrated platforms with captive payment processing, modular software vendors with open API ecosystems, and contract-manufactured hardware suppliers competing on unit economics. Dominant competitive moves include strategic partnerships with national payment acquirers and portfolio diversification into adjacent workforce management tools.
Within the full-stack integration tier, Toast Inc. and Square Inc. exemplify divergent positioning strategies, while NCR Corporation anchors the legacy enterprise segment. Toast leverages native payroll and inventory modules to deepen merchant relationships, Square competes aggressively on onboarding velocity for independent operators, and NCR sustains decades-long franchise chain relationships through durable service infrastructure. Clover Network Inc. and Lightspeed POS Inc. occupy modular positions emphasizing third-party integration depth.
| Leading Market Players |
|---|
| Toast Inc. |
| Square Inc. |
| NCR Corporation |
| Clover Network Inc. |
| Lightspeed POS Inc. |
| Revel Systems Inc. |
| SpotOn Transact Inc. |
| Shift4 Payments LLC |
| PAR Technology Corp. |
| Others |
Cost & Logistics Intelligence
Android tablet processor costs from Taiwanese fabs cascade through three pricing tiers: premium integrated-stack vendors anchor above commodity hardware suppliers, while subscription-based SaaS models compress upfront capital requirements for mid-market buyers.
Pricing Analysis
Transaction throughput uptime anchors value-based pricing for cloud-native platforms, with PCI DSS 4.0 certification tier separating premium-stack providers from uncertified commodity alternatives. Price differentiation rests on native payroll-inventory bundling depth and API extensibility. Cost compression in terminal hardware intensifies because Asian contract manufacturers flood the market with hardened Android tablets. Independent operators with 50-150 seats exhibit highest price sensitivity; multi-unit franchise chains with centralized procurement show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying tablet processors and Chinese contract manufacturers producing hardened Android terminals. Raw material dependencies include NAND flash memory, touch panel controllers, and EMV-certified secure elements. Supply chain risk centers on tariff exposure for Chinese-assembled hardware entering US distribution channels. Distribution runs through national payment acquirers bundling terminal provisioning with merchant processing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around software-centric platforms as PCI DSS 4.0 compliance deadlines force weaker hardware-only vendors into acquisition or exit.
For Market Incumbents: To counter commoditized Android tablet erosion, deepen captive payment processing share through interchange-plus transparency tools and in-house production of kitchen display system peripherals. Certification investment in Illinois BIPA-compliant biometric architectures creates channel control leverage against modular competitors. For New Entrants and Emerging Players: The California Consumer Privacy Act in the Western US opens a window for privacy-by-design terminal architectures targeting mid-market full-service independents. White space concentrates in 50-150 seat restaurants between premium-stack and stripped-down independent offerings. Go-to-market through private-equity-backed Texas rollups favors subscription-based operational expenditure positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular API-native platforms in Texas and Florida corridor expansion zones with fragmented multi-unit operator bases. Long-term viability hinges on software subscription retention rates exceeding hardware replacement margins. Watch PCI DSS 4.0 certification timeline compression as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native payroll-inventory-loyalty bundling deepens merchant lifetime value beyond transaction processing. |
| Strategic Partnership | Interchange-plus pricing alliances with national acquirers differentiate against vertically integrated competitors. |
| Geographic Expansion | Texas and Florida private-equity rollup corridors offer concentrated mid-market acquisition targets. |
| Product Launch | Illinois BIPA-compliant biometric terminals unlock enterprise accounts in Chicago metropolitan markets. |
| Acquisition of Specialist Firm | Kitchen display system voice-activation specialists add natural language processing capabilities to core stacks. |
Research Approach
Multi-period observation of terminal replacement cycles and SaaS subscription retention anchored the trend analysis, supplemented by interviews with POS platform executives, restaurant franchise technology officers, payment processor partnership leads, and independent operator owners. Secondary validation drew from FTC payment processing disclosure filings, PCI SSC certification databases, state-level biometric privacy legislation records, and SEC 10-K software revenue disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing across deployment models.
Input-output matrices mapped hardware refresh velocity against software subscription attach rates across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, customer scale tier, and metropolitan corridor regulatory exposure. CAGRs derived from terminal shipment unit trajectories and average revenue per merchant expansion curves. Forecast inputs incorporated PCI DSS 4.0 compliance deadline acceleration and cloud-native platform adoption elasticity.
The model assumes a particular technology adoption path; alternative pathways for voice-activated kitchen display systems would alter the outlook. Forecasts reflect assumptions about franchise chain standardization mandates and state-level privacy law harmonization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Food Service Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Gas Fryers Market
Food Service
United States Full Service Restaurants Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Spain Food Service Market
Food Service
Online Food Delivery Market
Food Service
United States Cafes & Bars Market
Food Service
Pasteurized Eggs Market
Food Service
Food Service Disposables Market
Food Service
Restaurant Takeout Market
Food Service
Australia Foodservice Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Halal Food and Beverages Market