
 Asia Pacific Airline Catering Services Market | 2026-2036
Asia Pacific Airline Catering Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Airline Catering Services Market Insights
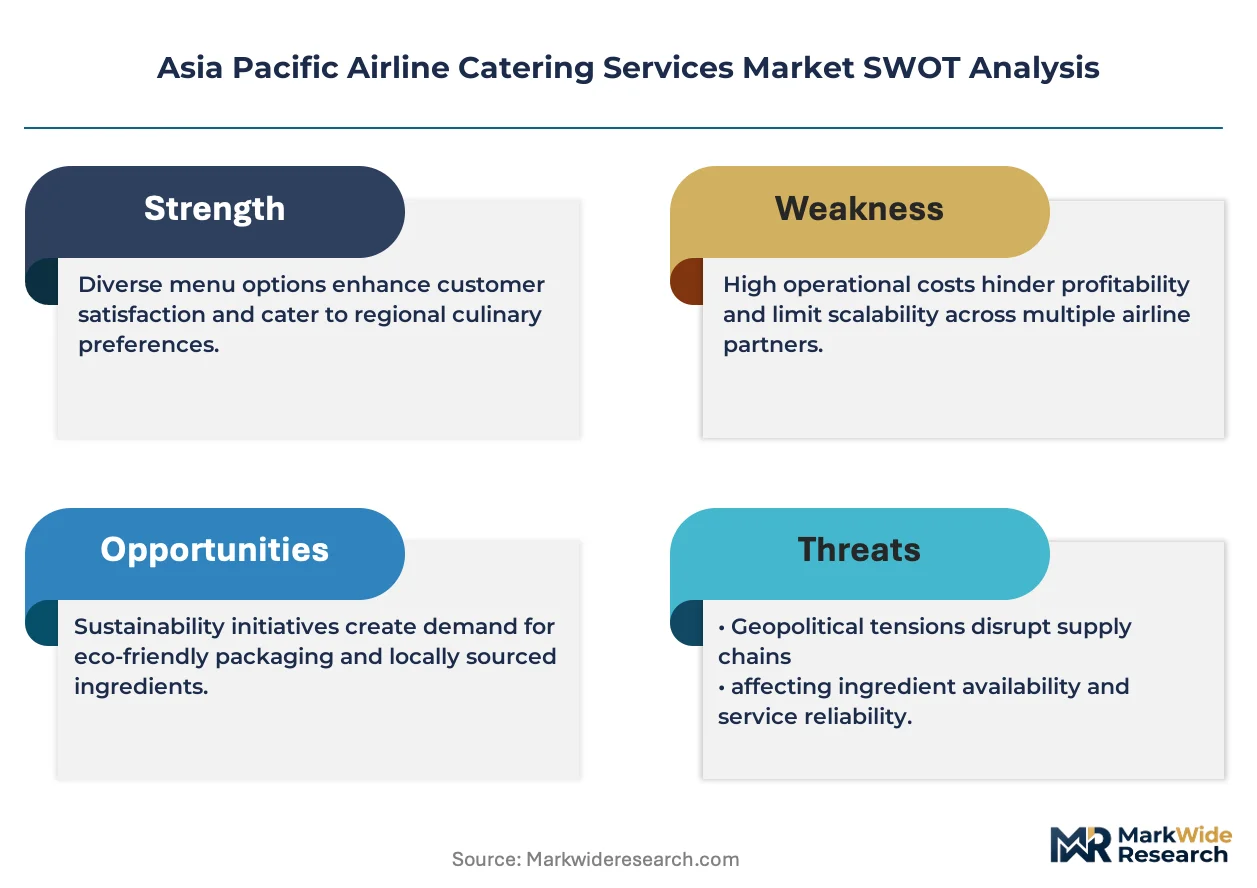
Buyer concentration among full-service carriers is decoupling from the fragmented expansion of low-cost and charter operators across Southeast Asia. SATS Ltd. leverages its Changi hub infrastructure to control procurement scale across multiple airline contracts. Gate Gourmet competes through specialized halal and ethnic meal production lines serving Middle East-Asia routes. DO & CO Aktiengesellschaft differentiates via chef-driven premium concepts for first-class and business cabins.
Asia Pacific airline catering services encompass the centralized production, assembly, and logistics of meals, beverages, and retail items delivered to aircraft under strict cold-chain protocols maintaining temperatures between 0°C and 5°C through loading. These operations synchronize with narrow turnaround windows, typically 45-90 minutes, to ensure food safety compliance and on-time performance. In-flight meals anchor the value pool given their labor-intensive preparation and perishable inventory management, while special meals represent the fastest-expanding segment as dietary accommodation becomes a competitive differentiator. Commercial airlines sustain the dominant end-user position, though private jets command disproportionate margin per seat due to bespoke menu requirements and lower volume predictability.
CEA guidelines on airport energy consumption influence central kitchen location decisions, while FSSAI standards in India mandate nutritional labeling and allergen traceability for all exported in-flight food. EASA-equivalent frameworks adopted by Singapore and Australia enforce HACCP certification across supplier tiers, raising compliance costs for smaller local producers. Stakeholders must weigh capital allocation between automation-driven central kitchens and distributed satellite facilities as passenger traffic patterns shift across secondary airports.
Market Dynamics
Low-cost carriers across Southeast Asia are expanding meal service tiers to capture ancillary revenue, forcing full-service carriers to defend yield through premium differentiation. TRAI's in-flight connectivity guidelines and digital ordering platforms are reshaping passenger touchpoints and procurement workflows simultaneously.
Growth Catalysts
- TRAI Connectivity Framework:India's in-flight connectivity guidelines enable real-time pre-ordering systems that reduce waste and improve load planning accuracy for caterers.
- Halal Certification Infrastructure:Southeast Asian hub airports are building dedicated halal production zones to serve Middle East-Asia routes with compliant meal volumes.
- Metro Airport Clustering:India's Delhi-Mumbai-Bangalore corridor concentrates 60% of international departure volume, creating procurement scale for centralized kitchen investments.
Market Restraints
- Perishable Input Volatility:Fresh protein and produce costs fluctuate with monsoon patterns across South and Southeast Asian sourcing regions, compressing margin predictability.
- Supplier Concentration Risk:Cold-chain logistics capacity concentrates in Singapore and Bangkok hubs, creating single-point vulnerability for secondary airport coverage.
- FSSAI Export Compliance:India's nutritional labeling and allergen traceability mandates raise documentation burden for smaller regional producers serving international routes.
Strategic Opportunities
- Secondary Airport Satellites:Vietnam's Da Nang and Indonesia's Denpasar lack dedicated catering infrastructure, creating first-mover advantage for modular kitchen deployments.
- CEA Energy Incentives:India's airport energy consumption guidelines reward solar-powered central kitchens with preferential lease terms and accelerated permitting.
- AI-Driven Demand Forecasting:Machine learning platforms that integrate booking data with historical consumption patterns are reducing overproduction waste by double-digit percentages.
Industry Challenges
- HACCP Certification Pipeline:EASA-equivalent frameworks adopted by Singapore and Australia require tiered supplier certification, creating 12-18 month onboarding delays for new entrants.
- Turnaround Window Compression:Narrow-body fleet expansion at budget terminals is squeezing loading windows below 45 minutes, demanding robotic trolley handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Airline Catering Services Market |
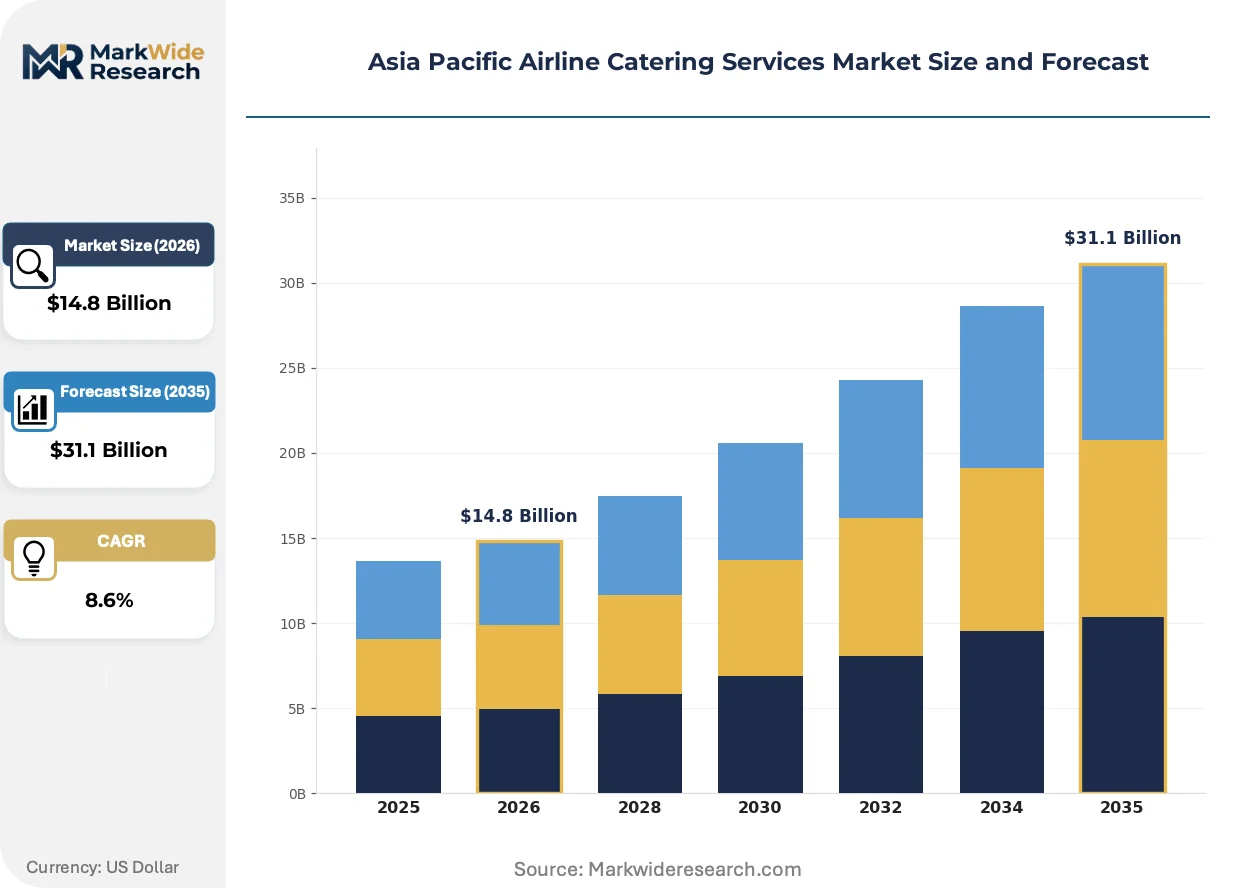
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-flight Meals, Beverages, Snack Boxes, Special Meals End User: Commercial Airlines, Charter Airlines, Cargo Airlines, Private Jets Distribution Channel: Direct Supply, Third-party Vendors, Local Producers, Catering Companies Menu Type: Vegetarian, Non-Vegetarian, Vegan, Halal |
| Companies Covered | SATS Ltd., Cathay Pacific Catering Services (H.K.) Limited, LSG Sky Chefs (LSG Group), Gate Gourmet (gategroup), dnata, Emirates Flight Catering, Newrest, Flying Food Group, DO & CO Aktiengesellschaft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Airline Catering Services Market Trends and Innovations
Automation and digital integration are compressing traditional kitchen-to-cabin workflows while regulatory pressure on sustainability and traceability rewrites procurement specifications across the region.
Robotic meal tray assembly systems is consolidating production labor into centralized facilities serving multiple airlines from single locations. Full-service carriers in Singapore and Australia are adopting these platforms fastest, driven by union pressure and wage inflation. The technology is consolidating smaller satellite kitchens into hub-and-spoke operating models that sacrifice flexibility for unit cost reduction.
FSSAI's allergen traceability mandate and Singapore's HACCP-equivalent enforcement are forcing ingredient documentation back to farm-level sourcing. Industrial consequence includes mandatory blockchain pilot programs for premium cabin protein tracking. First-class and business segments absorb compliance costs most acutely, passing specifications upstream to protein suppliers in Australia and New Zealand.
Airlines are unbundling meal pre-selection from ticket purchase, shifting toward à-la-carte digital ordering 48-72 hours pre-departure. Low-cost carriers pioneered this model; full-service airlines now replicate it to reduce no-show meal waste. The pattern is most visible in India's metro airport clusters where smartphone penetration supports app-based ordering penetration above regional averages.
Asia Pacific Airline Catering Services Market Segmentation
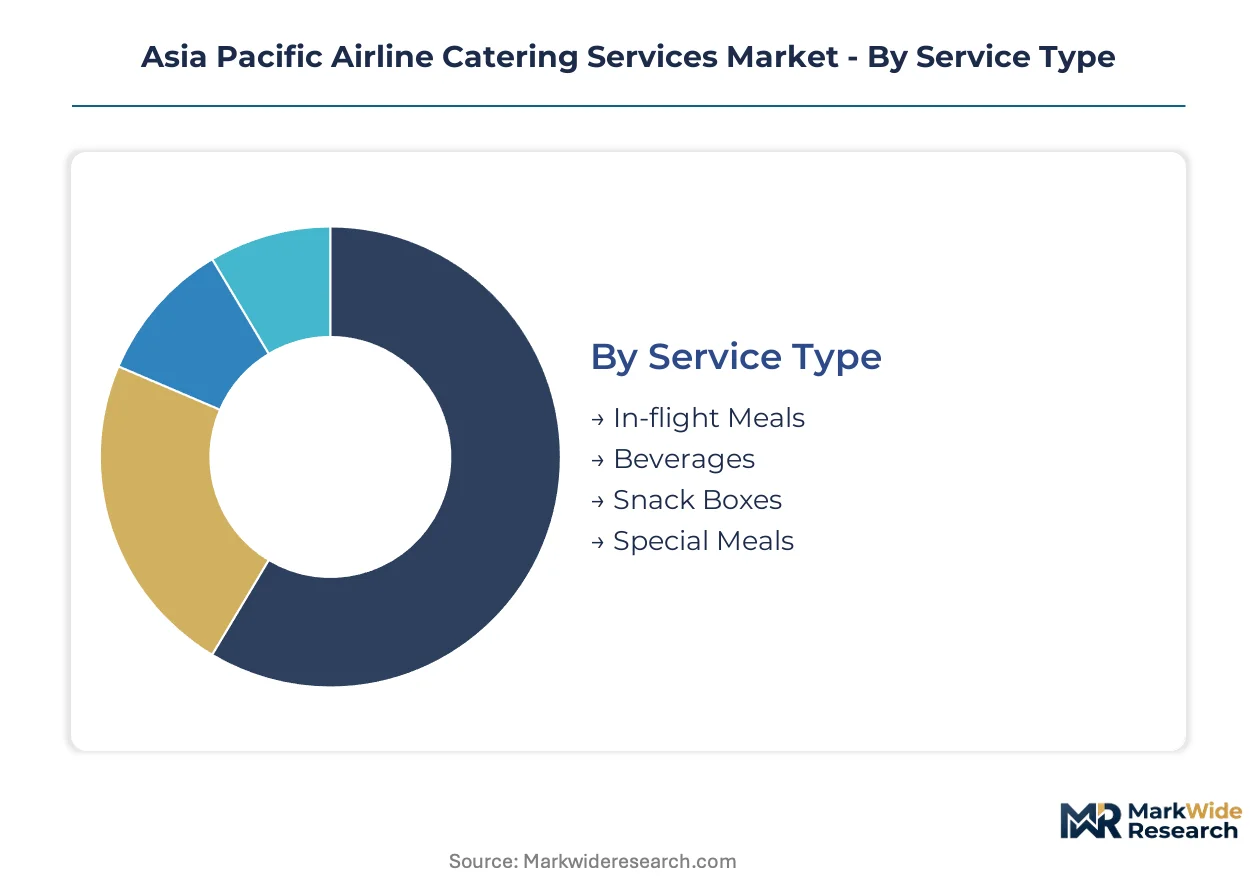
Asia Pacific airline catering services fragment across four distinct dimensions that determine procurement scale, margin structure, and regulatory exposure. Each segmentation axis reveals divergent growth trajectories shaped by carrier business models, airport infrastructure maturity, and evolving passenger dietary preferences across the region.
Service Type:
Volume concentration sits with high-turnover meal categories, while premium tiers command disproportionate margin through customization intensity.
- In-flight Meals:Complete hot and cold meal sets requiring centralized kitchen production under HACCP-equivalent protocols adopted by Singapore and Australia. Demand clusters in India's Delhi-Mumbai-Bangalore corridor where 60% of international departures concentrate procurement scale for centralized investments.
- Special Meals:Dietary-specific offerings including allergen-free, medical, and religious-compliant preparations with mandatory farm-to-cabin traceability under FSSAI export guidelines. India's metro airport clusters and Australia's trans-Pacific hub routes show steepest expansion trajectory as full-service carriers defend yield through premium differentiation.
- Beverages:Alcoholic and non-alcoholic drink provisioning with temperature-controlled logistics from regional bottling hubs.
- Snack Boxes:Pre-packaged retail-format items favored by low-cost carriers expanding ancillary revenue tiers across Southeast Asia.
Today's leader: In-flight Meals. Tomorrow's challenger: Special Meals.
End User:
Customer type determines order predictability, menu complexity, and contract duration across the procurement spectrum.
- Commercial Airlines:Scheduled carriers operating fixed routes with volume-contracted catering needs and narrow turnaround windows of 45-90 minutes. Full-service and low-cost segments split on premium differentiation versus ancillary unbundling strategies.
- Private Jets:Bespoke charter and fractional ownership fleets requiring customized menus with lower volume predictability and disproportionate margin per seat. Australia's trans-Pacific hub routes and India's emerging business aviation clusters drive regional demand.
- Charter Airlines:Seasonal and pilgrimage route operators with fluctuating catering volumes tied to religious and event calendars.
- Cargo Airlines:Flight crew provisioning for freighter operations with standardized meal requirements and minimal special meal complexity.
Commercial Airlines anchor procurement volume. Private Jets reshape margin benchmarks.
Distribution Channel:
Channel structure reflects cold-chain capability concentration versus regulatory compliance burden across supplier tiers.
- Direct Supply:Airline-owned or captive catering operations with full control over quality specifications and loading logistics. Singapore's Changi hub infrastructure exemplifies this model's procurement scale advantages.
- Third-party Vendors:Independent catering specialists competing through halal certification infrastructure and ethnic meal production lines serving Middle East-Asia routes.
- Catering Companies:Multi-airline service providers with hub-and-spoke kitchen networks consolidating production labor through robotic assembly systems.
- Local Producers:Smaller regional suppliers facing 12-18 month HACCP certification delays under EASA-equivalent frameworks adopted across Singapore and Australia.
Direct Supply dominates at primary hubs. Third-party Vendors penetrate secondary airports.
Menu Type:
Dietary accommodation intensity determines ingredient sourcing complexity and certification overhead across protein categories.
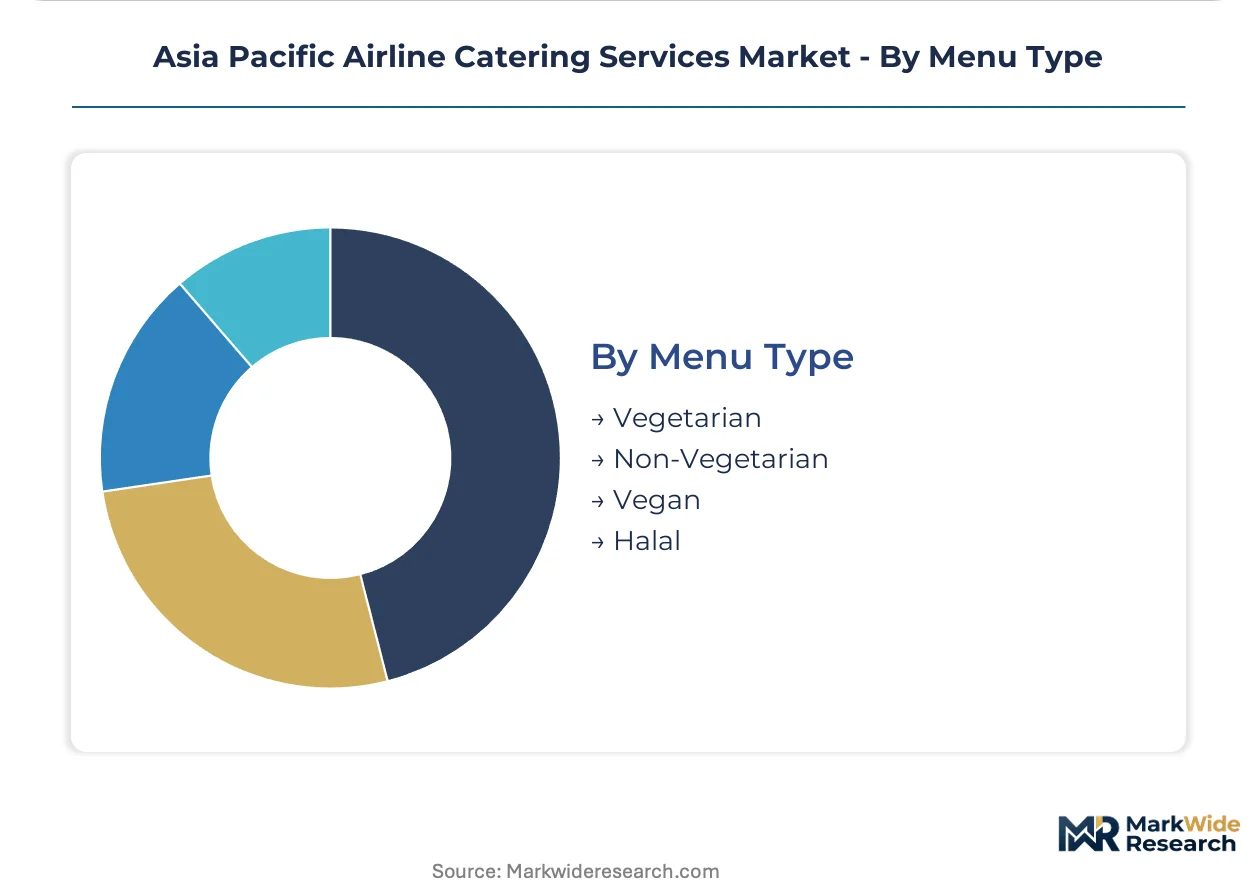
- Halal:Islamically-compliant meal production requiring dedicated kitchen zones and supply chain segregation. Southeast Asian hub airports are building specialized infrastructure to serve Middle East-Asia route volumes.
- Vegetarian:Plant-based meal categories with concentrated demand in India's domestic and international routes reflecting passenger demographic composition.
- Vegan:Strict plant-based preparations excluding all animal derivatives with emerging traction among premium cabin segments in Singapore and Australia.
- Non-Vegetarian:Conventional protein-inclusive meals with blockchain pilot programs for premium cabin protein tracking mandated by farm-level traceability requirements.
Halal leads certification-driven investment. Vegan climbs fastest on premium cabin demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates international departure volume along its Delhi-Mumbai-Bangalore corridor, while Australia anchors trans-Pacific hub connectivity with distinct cold-chain infrastructure requirements. These two markets illustrate divergent growth trajectories within the broader regional expansion pattern.
India
TRAI's in-flight connectivity guidelines enable real-time pre-ordering systems that reduce waste and improve load planning accuracy for caterers. FSSAI standards mandate nutritional labeling and allergen traceability for all exported in-flight food, raising documentation burdens for regional producers. The Delhi-Mumbai-Bangalore corridor concentrates 60% of international departure volume, creating procurement scale for centralized kitchen investments.
Australia
Trans-Pacific hub routes drive disproportionate demand for premium cabin catering with bespoke menu requirements. EASA-equivalent frameworks enforce HACCP certification across supplier tiers, raising compliance costs for smaller local producers. Sydney and Melbourne anchor cold-chain logistics capacity serving secondary airport coverage throughout the region.
Singapore
Changi hub infrastructure enables procurement scale across multiple airline contracts through centralized production facilities. EASA-equivalent HACCP enforcement requires tiered supplier certification, creating 12-18 month onboarding delays for new entrants. The city-state's dedicated halal production zones serve Middle East-Asia route volumes with compliant meal infrastructure.
Vietnam
Da Nang lacks dedicated catering infrastructure, creating first-mover advantage for modular kitchen deployments at secondary airports. Low-cost carriers expanding meal service tiers to capture ancillary revenue drive demand for snack box and à-la-carte provisioning. The country's central coastal position supports hub-and-spoke distribution models for Southeast Asian route networks.
Indonesia
Denpasar and other secondary airports face infrastructure gaps that favor distributed satellite facilities over centralized kitchen models. Halal certification infrastructure investments at Jakarta's Soekarno-Hatta International Airport serve domestic and international route compliance requirements. Bali's tourism-driven route density creates seasonal demand volatility for charter and pilgrimage operators.
Asia Pacific Airline Catering Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement scale and customization intensity vectors. Hub-based operators leverage Changi and Sydney infrastructure for multi-airline contract consolidation, while regional specialists penetrate secondary airports through modular deployment. Two strategic archetypes dominate: scale-driven central kitchen operators and chef-driven premium concept providers. Competitive moves concentrate on automation-driven capacity expansion and halal certification infrastructure partnerships.
Within the hub-operator tier, SATS Ltd. and Gate Gourmet occupy positions exemplifying procurement scale advantages, while DO & CO Aktiengesellschaft represents the chef-driven premium archetype. SATS Ltd. leverages its Singapore base for multi-contract consolidation. Gate Gourmet competes through specialized production line differentiation. DO & CO Aktiengesellschaft, structured as an Austrian Aktiengesellschaft, anchors the premium cabin customization segment. These three companies illustrate the structural split between volume efficiency and margin intensity strategies.
| Leading Market Players |
|---|
| SATS Ltd. |
| Cathay Pacific Catering Services (H.K.) Limited |
| LSG Sky Chefs (LSG Group) |
| Gate Gourmet (gategroup) |
| dnata |
| Emirates Flight Catering |
| Newrest |
| Flying Food Group |
| DO & CO Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
Fresh protein and produce costs fluctuate with monsoon patterns across South and Southeast Asian sourcing regions, compressing margin predictability for caterers serving India's Delhi-Mumbai-Bangalore corridor and Australia's trans-Pacific routes. This input volatility cascades through three-tier pricing structures across premium, standard, and economy cabin tiers, with full-service carriers absorbing compliance premiums while low-cost operators unbundle meal selections to defend yield.
Pricing Analysis
Capacity additions in Singapore and Bangkok are reshaping price floors for standardized meal production, forcing regional competitors toward premium-mid-economy pricing differentiation based on halal certification grade and customization intensity. Cost compression in economy-tier snack boxes is intensifying because of robotic assembly adoption at Changi-scale hubs. Charter operators show highest price sensitivity due to seasonal volume unpredictability, while private jet clients demonstrate least sensitivity given bespoke menu requirements.
Supply Chain Analysis
Dual-sourcing requirements from full-service carriers mandate multi-supplier qualification for cold-chain logistics, with Singapore, Thailand, and Australia anchoring regional capacity. Protein inputs draw from New Zealand and Australian farm-level suppliers under FSSAI traceability mandates, while packaging materials hinge on Malaysian and Indonesian manufacturing clusters. Single-point vulnerability concentrates in Bangkok and Singapore cold-chain hubs, with distribution running through hub-and-spoke kitchen networks to secondary airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific airline catering services function as a stable compounder anchored by structural ancillary revenue expansion among low-cost carriers and premium cabin yield defense by full-service operators.
For Market Incumbents: Anticipate margin compression from robotic assembly consolidation at Changi and Sydney hubs by accelerating halal certification infrastructure investments and securing preferential lease terms under CEA energy guidelines. Channel control through captive satellite kitchen networks at India's secondary airports offers defensive positioning against SATS Ltd. procurement scale advantages. For New Entrants and Emerging Players: Enter via modular kitchen deployments at Vietnam's Da Nang and Indonesia's Denpasar, where infrastructure gaps create first-mover advantage for à-la-carte digital ordering integration. The most penetrable segment sits with low-cost carrier snack box provisioning, using TRAI-enabled pre-order platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale halal-certified specialists because EASA-equivalent HACCP enforcement creates 12-18 month onboarding barriers that protect acquired cash flows. Target facilities with existing airline contracts and solar-powered central kitchen credentials. Watch for inflection in India's secondary airport passenger traffic as the signal for satellite facility valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Infrastructure | Dedicated production zones at Jakarta and Kuala Lumpur serve Middle East-Asia route volumes under EASA-equivalent protocols. |
| Robotic Assembly Deployment | Automated tray systems at Singapore and Sydney hubs consolidate multi-airline production labor into centralized facilities. |
| Satellite Kitchen Expansion | Modular deployments at Da Nang and Denpasar capture low-cost carrier ancillary revenue growth with lower capital intensity. |
| Digital Pre-Order Integration | TRAI-compliant platforms reduce waste and improve load planning accuracy for caterers across India's metro clusters. |
| Farm-Level Traceability Programs | Blockchain pilots for premium cabin protein tracking satisfy FSSAI export mandates and Singapore HACCP enforcement. |
Research Methodology
Multiple input streams — executive interviews with catering operations directors, procurement leads at full-service and low-cost carriers, airport concession managers, and cold-chain logistics specialists; trade data from customs records and airport authority filings; and regulatory documentation from FSSAI, TRAI, and CEA — were reconciled through bottom-up facility capacity modeling and top-down route demand estimation.
Data-stream reconciliation applied across the projection horizon incorporated service type segmentation by meal category and special dietary preparation intensity, end-user splits between commercial airlines and private aviation, and distribution channel differentiation by hub-versus-satellite operating models. CAGRs emerged from passenger traffic growth assumptions tied to metro airport clustering patterns and ancillary revenue expansion trajectories, with sensitivity testing around monsoon-driven input cost volatility.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time low-cost carrier yield data and private jet charter volume introduce uncertainty bands around premium cabin segment projections. Deviation in India's secondary airport traffic growth or Australia's trans-Pacific route recovery would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Australia Foodservice Market
Food Service
India Online Grocery Market
Food Service
Europe Inflight Catering Market
Food Service
Global Dark Store Market
Food Service
Turkey Food Service Market
Food Service
Steam Tables and Food Well Market
Food Service
Kuwait Food Service Market
Food Service
China Inflight Catering Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Wok Market
Food Service
Canada Food Service Market
Food Service
North America Online Food Delivery Market
Food Service
Chinese Takeout Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Online Catering Market
Food Service
Food Service Market