
 Connected Wearable Patches Market | 2026-2036
Connected Wearable Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Wearable Patches Market Intelligence
The application for chronic patient management within formal healthcare settings is broadening the market beyond its initial base of fitness enthusiasts, placing a premium on clinical accuracy and data security. Medtronic leverages its established presence in medical technology to offer integrated monitoring solutions. iRhythm Technologies specializes in cardiac arrhythmia detection with its biosensor patches. Abbott Laboratories sustains a leading position in continuous glucose monitoring, a key sub-segment.
Connected wearable patches are skin-adherent electronic devices that integrate biosensors for physiological data capture and wireless transceivers for real-time communication. These devices typically use biocompatible adhesives and operate on low-power connectivity protocols like Bluetooth to transmit data to a smartphone or a dedicated hub. Biosensor patches for health monitoring constitute the largest product segment, driven by demand from healthcare providers. Within technology, Bluetooth dominates due to its ubiquity in consumer electronics and low energy consumption.
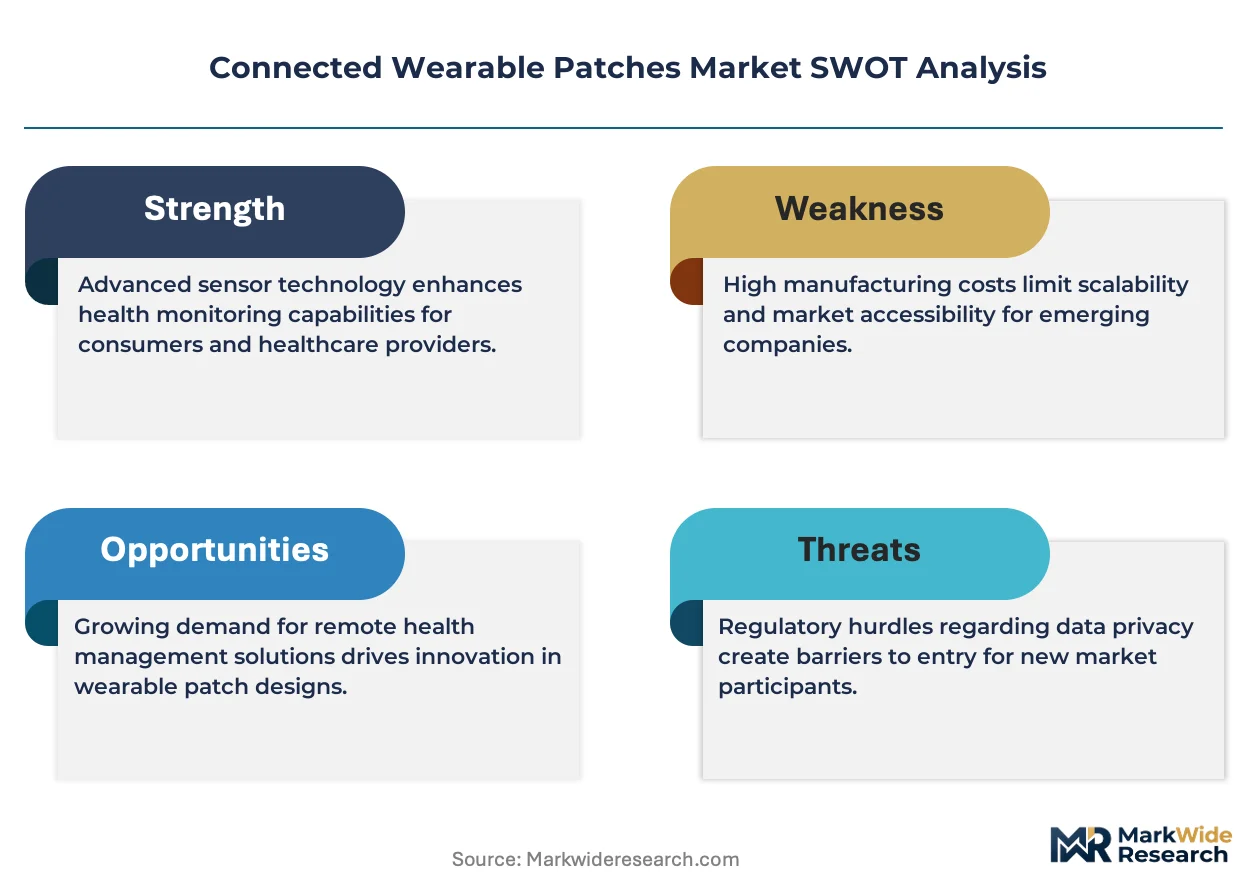
Market access is governed by stringent medical device regulations that vary by jurisdiction. In the United States, the FDA requires premarket approval or 510(k) clearance, while in Europe, compliance with the Medical Device Regulation (MDR) and obtaining a CE mark are mandatory. These frameworks mandate rigorous clinical validation and data privacy standards. Stakeholders must therefore prioritize investment in regulatory compliance and cybersecurity infrastructure to ensure market viability and build trust with patients and providers.
Market Dynamics
The market's pivot from consumer wellness to clinical-grade remote patient monitoring is the central structural force. This shift intensifies the need for regulatory compliance under frameworks like the FDA's 510(k) and Europe's MDR, concentrating demand within formal healthcare systems.
Growth Catalysts
- Chronic Disease Prevalence:Rising incidence of chronic conditions like cardiac arrhythmias and diabetes in the United States and Germany drives provider demand for continuous, remote monitoring solutions to improve patient outcomes and manage healthcare costs.
- Technological Ubiquity:The integration of low-power Bluetooth connectivity in nearly all smartphones simplifies data transmission, lowering the barrier for incorporating wearable patches into telehealth platforms and existing patient care workflows without requiring proprietary hardware.
- Regulatory Frameworks:Europe's Medical Device Regulation (MDR) mandates higher standards for clinical evidence, which favors established manufacturers capable of conducting rigorous validation for chronic disease management applications and solidifies their market position.
Market Restraints
- Component Costs:The high cost of specialized components, including medical-grade biocompatible adhesives and miniaturized, high-fidelity biosensors, creates a significant financial barrier to entry and puts pressure on device reimbursement rates from healthcare payers.
- Power Management:Limited battery life and the need for frequent patch replacement or recharging pose a key technical restraint. This creates patient compliance challenges and introduces potential gaps in the stream of continuous physiological data.
- Regulatory Fragmentation:Navigating disparate and lengthy clinical validation pathways between jurisdictions, such as the FDA in the US and notified bodies under the EU's MDR, delays market access and substantially increases product development costs.
Strategic Opportunities
- Geographic Expansion:Japan's rapidly aging population presents a significant opportunity, as its regulatory body, the PMDA, shows increasing receptiveness to digital health technologies for elder care and remote management of chronic conditions.
- Application Diversification:Moving beyond the established cardiac and glucose monitoring segments into niche neurological applications, such as for ambulatory epilepsy or sleep disorder monitoring, represents a key area for future growth and product differentiation.
- On-Device Intelligence:Integrating edge AI and machine learning algorithms directly onto the patch offers a strategic advantage. This enables preliminary data analysis, reduces data transmission loads, and can provide real-time alerts to clinicians or patients.
Industry Challenges
- System Interoperability:Integrating data streams from wearable patches with the wide variety of disparate Electronic Health Record (EHR) systems used across different hospital networks presents a significant interoperability challenge, hindering seamless clinical workflow automation.
- Data Security and Privacy:Ensuring robust compliance with data privacy mandates like HIPAA in the United States and GDPR in Europe for sensitive patient health information requires constant, significant investment in cybersecurity infrastructure to counter evolving threats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Wearable Patches Market |
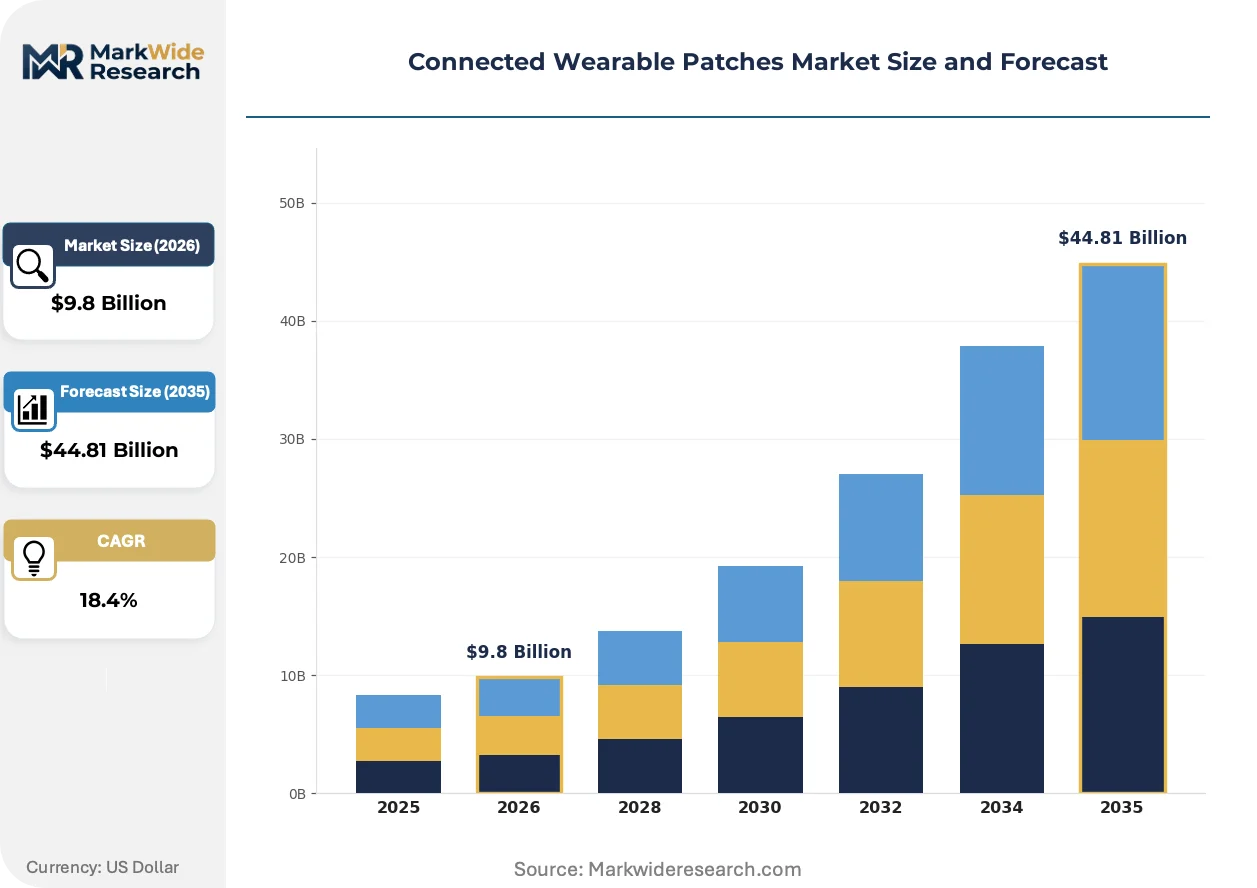
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $44.81 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Patches, Biosensor Patches, Drug Delivery Patches, Monitoring Patches Technology: Bluetooth, NFC, RFID, Wi-Fi End User: Healthcare Providers, Fitness Enthusiasts, Chronic Patients, Research Institutions Functionality: Health Monitoring, Drug Administration, Data Collection, Remote Tracking |
| Companies Covered | Koninklijke Philips, Medtronic, Sensium Healthcare, Proteus Digital Health, Chrono Therapeutics, iRhythm Technologies, Dexcom, Preventice Solutions, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Wearable Patches Market Strategic Shifts & Innovations
Innovation in the connected wearable patch market is driven by the convergence of clinical-grade sensor accuracy with consumer-friendly design. This trend is accelerating development in biocompatible materials and on-device analytics to meet both patient expectations and stringent regulatory requirements.
Flexible, printed electronics on substrates like polyurethane enable thinner, more comfortable patches with multi-parameter sensing. Healthcare providers are adopting these for complex post-operative and chronic care monitoring. This evolution in form factor is absorbing the functions of multiple, bulkier devices into a single skin-adherent patch.
The FDA's Digital Health Software Precertification (Pre-Cert) Program signals a shift towards a streamlined regulatory process for trusted manufacturers. This initiative favors an organizational excellence approach to quality over per-product reviews. Companies with strong quality management systems are most affected, potentially gaining faster market access for software-driven patch innovations.
A notable shift in acquisition is moving from capital expenditure to subscription-based "monitoring-as-a-service" models. This disrupts the traditional device sales channel with service contracts bundling the patch, data platform, and analytics. The trend is most visible in United States and German hospitals managing operational budgets.
Connected Wearable Patches Market Segmentation
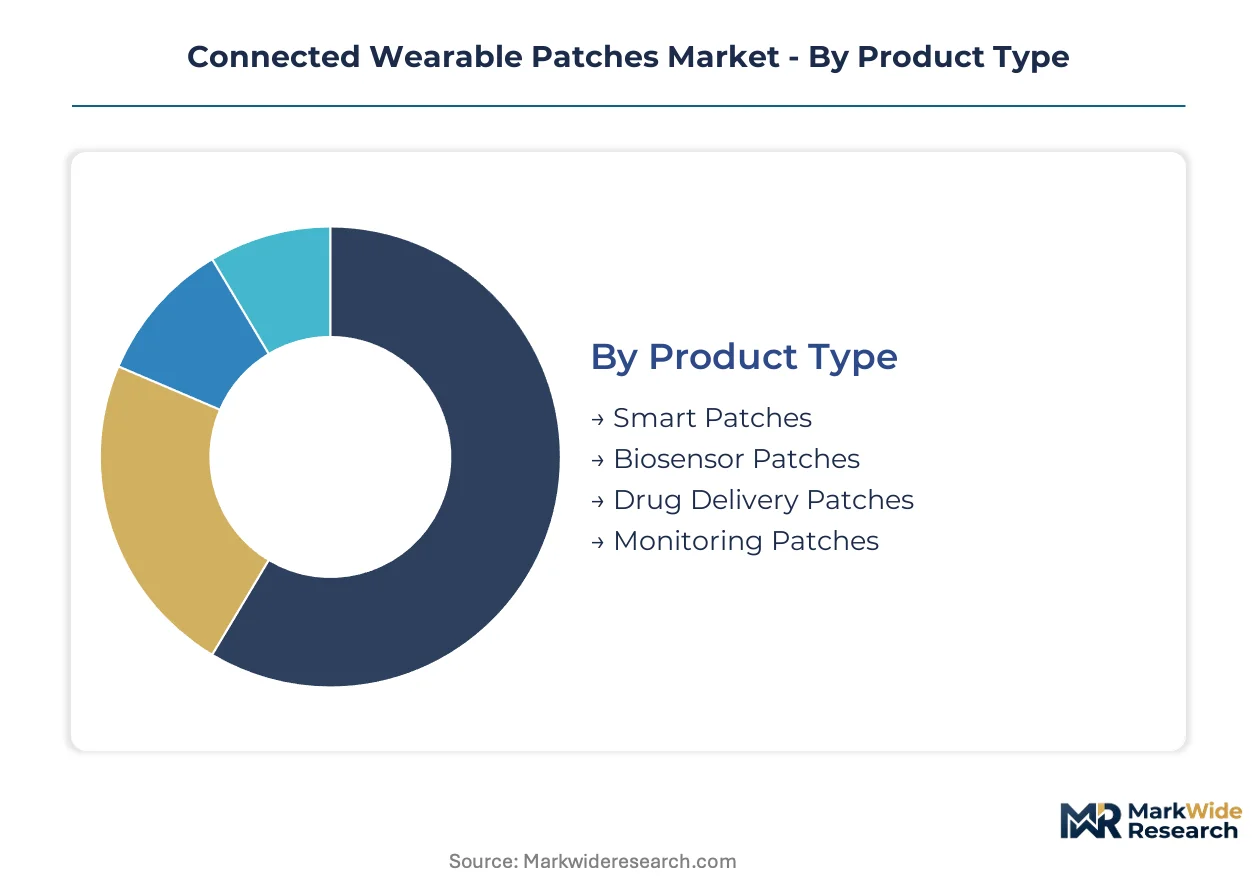
Connected wearable patches feature diverse product types, technologies, end users, and functionalities. This segmentation analysis delineates the market's structural components, highlighting the varied demands and technical specifications that drive product development and market access strategies. Understanding these distinctions clarifies the competitive landscape.
Product Type:
Supply concentration in connected wearable patches primarily rests with manufacturers capable of integrating advanced biosensors and biocompatible materials into their devices.
- Biosensor Patches:These devices integrate specialized sensors to detect and measure physiological parameters such as heart rate, temperature, and glucose levels. Demand concentrates in formal healthcare systems, especially in the United States and Germany, driven by chronic disease management.
- Smart Patches:Smart patches combine multiple functionalities, often integrating biosensing with drug delivery or advanced data processing capabilities. Healthcare providers increasingly demand these for comprehensive remote patient monitoring, enhancing clinical decision-making.
- Drug Delivery Patches:These patches administer medication transdermally, often incorporating micro-needles or iontophoresis for controlled release.
- Monitoring Patches:Primarily focused on continuous tracking of vital signs, these devices provide data for long-term health trends or acute event detection.
Biosensor Patches absorb the bulk of installed capacity; Smart Patches are expanding most quickly.
Technology:
Application requirements dictate the choice of connectivity technology, balancing data throughput needs with power consumption constraints for wearable patches.
- Bluetooth:Bluetooth Low Energy (BLE) protocols enable short-range, low-power wireless data transmission from patches to connected devices like smartphones. Its ubiquity in consumer electronics and energy efficiency drives its widespread adoption for remote patient monitoring.
- Wi-Fi:Wi-Fi offers higher bandwidth for data transfer over longer ranges, suitable for devices requiring more extensive data uploads or real-time streaming. Healthcare providers use Wi-Fi for patches in clinical settings where a stable network infrastructure is available.
- NFC:Near Field Communication enables ultra-short-range data exchange, primarily for authentication or quick data syncs with minimal power.
- RFID:Radio-Frequency Identification tags allow for passive tracking and identification of patches, often used in inventory management or asset tracking.
Demand is strongest for Bluetooth connectivity due to its low power consumption; Wi-Fi is gaining traction for high-data-volume applications.
End User:
Customer type significantly influences product design and regulatory compliance, with formal healthcare entities demanding stringent validation and data security.
- Healthcare Providers:Hospitals, clinics, and remote monitoring services utilize patches for continuous patient surveillance, diagnostic support, and chronic disease management. Stricter regulatory frameworks like the FDA's 510(k) and Europe's MDR drive demand for clinically validated devices.
- Chronic Patients:Individuals managing long-term conditions like diabetes or cardiac arrhythmias use patches for personal health tracking and data sharing with clinicians. The rising prevalence of chronic diseases in the United States and Germany fuels the need for convenient, continuous monitoring.
- Fitness Enthusiasts:These users employ patches for performance tracking, activity monitoring, and basic physiological data collection during exercise.
- Research Institutions:Academic and pharmaceutical research organizations use specialized patches for clinical trials, physiological studies, and new sensor development.
Healthcare Providers account for the largest share of connected wearable patch utilization; Chronic Patients represent a significant growth area for personal monitoring.
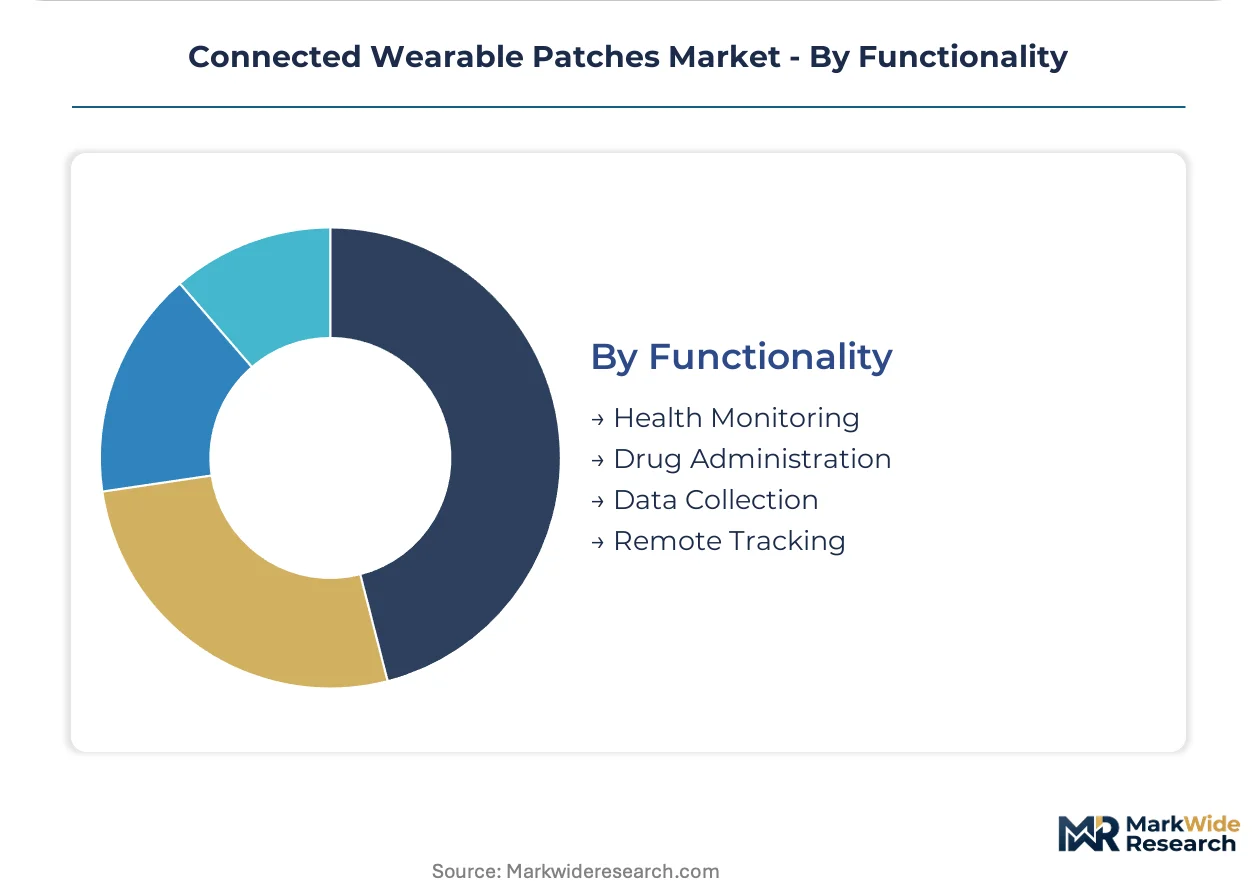
Functionality:
Volume of data and critical nature of outcomes determine the functionality requirements for connected wearable patches.
- Health Monitoring:This functionality involves continuous or intermittent measurement of vital signs, biomarkers, and activity levels for diagnostic or preventive purposes. The growing need for remote patient monitoring in countries like the United States and Germany underpins this segment's expansion.
- Drug Administration:Patches deliver controlled doses of medication transdermally, often integrating smart features for precise timing and dosage adjustments. This functionality addresses patient adherence and reduces the need for frequent clinical visits, especially for chronic conditions.
- Data Collection:This refers to the primary function of gathering raw physiological data from the wearer for subsequent analysis or transmission.
- Remote Tracking:Patches enable real-time location and activity monitoring, crucial for elderly care, lone workers, or specific clinical studies.
Health Monitoring dominates the market in terms of deployed units, and Drug Administration shows the most promising value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina, a prominent hub for medical technology innovation, exemplifies how targeted economic zones drive market concentration for connected wearable patches. These strategic areas foster collaboration between academia, industry, and government, accelerating both product development and regulatory pathways. Investment within these zones underpins the market's expansion, particularly in high-value clinical applications.
United States
The United States leads demand for connected wearable patches, driven by the high prevalence of chronic diseases and a robust healthcare expenditure. The FDA's 510(k) clearance process mandates rigorous clinical validation, ensuring device reliability for patient care. Major medical technology clusters in Boston and Silicon Valley continue to innovate in biosensor technology and remote patient monitoring solutions.
Germany
Germany's advanced healthcare system and aging population create significant demand for continuous, remote patient monitoring via wearable patches. Compliance with the European Medical Device Regulation (MDR) and CE mark requirements is essential for market access. The Medicon Valley region, spanning parts of Germany and Denmark, fosters strong collaboration in biotech and medical device development.
Japan
Japan's rapidly aging demographic presents a substantial opportunity for connected wearable patches, especially for elder care and chronic condition management. The PMDA, Japan's pharmaceutical and medical device agency, is increasingly receptive to digital health technologies. Innovation clusters in Tokyo and Kyoto focus on miniaturization and biocompatible materials for discreet monitoring devices.
China
China's vast patient population and government initiatives to expand healthcare access are fueling the adoption of connected wearable patches. The NMPA regulates medical devices, with evolving standards for digital health solutions. The Yangtze River Delta region, particularly Shenzhen, is a hub for electronics manufacturing and medical device innovation, supporting scalable production.
India
India's growing burden of chronic diseases, including diabetes and cardiovascular conditions, drives the need for affordable and accessible remote monitoring solutions. The CDSCO, India's central drug authority, oversees medical device approvals, with a focus on local manufacturing and affordability. Bengaluru and Hyderabad are emerging as key centers for health tech startups developing innovative patch solutions.
Connected Wearable Patches Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the connected wearable patches market. The market exhibits a tiered structure, with established medical technology firms dominating clinical-grade applications requiring stringent regulatory compliance. Smaller, agile innovators often focus on niche segments or partner with larger players for distribution. Strategic partnerships and targeted M&A activity are common competitive moves, reflecting the need for both specialized technology and broad market access.
Specialists in cardiac monitoring, such as iRhythm Technologies, exemplify firms focused on specific physiological data capture and diagnostic solutions. Medtronic, a global medical technology company, represents the archetype of an established player integrating connected wearable patches into broader healthcare ecosystems for chronic disease management. Abbott Laboratories anchors the continuous glucose monitoring segment, showcasing how large pharmaceutical and medical device companies leverage existing market presence and regulatory expertise to drive patch adoption. These prominent companies demonstrate diverse approaches to market penetration, from niche specialization to comprehensive platform offerings, shaping the competitive dynamics across different application areas.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Medtronic |
| Sensium Healthcare |
| Proteus Digital Health |
| Chrono Therapeutics |
| iRhythm Technologies |
| Dexcom |
| Preventice Solutions |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Healthcare Providers' concentrated demand for clinically validated devices favors long-term, contract-based pricing models for connected wearable patches. This approach bundles hardware, data platforms, and analytics into service agreements.
Pricing Analysis
Premium pricing for rapid deployment reflects the critical need for immediate patient monitoring solutions in acute care settings. The dominant model is "monitoring-as-a-service," bundling hardware, data platforms, and analytics. Price differentiation stems from rigorous regulatory compliance, such as FDA 510(k) and EU MDR certifications, and integrated data security features. Pricing pressure intensifies from healthcare payers' reimbursement rates, making Chronic Patients more price-sensitive than institutional Healthcare Providers.
Supply Chain Analysis
Dual-sourcing requirements for critical components like medical-grade adhesives and biosensors mitigate single-point failure risks for connected wearable patch manufacturers. Geographic supply concentration for these specialized inputs centers on China for electronics, Germany for advanced materials, and Japan for miniaturization expertise. The supply chain relies on miniaturized, high-fidelity biosensors and low-power Bluetooth modules. A structural risk involves single-source vulnerability for highly specialized biosensors, while distribution runs primarily through direct sales channels to healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connected wearable patches market presents a supply-constrained narrative, with pricing propped by the limited availability of clinically validated, miniaturized biosensors. Meeting demand requires significant investment in specialized manufacturing capacity and regulatory expertise.
For Market Incumbents: Hedge against emerging entrant archetypes offering novel sensor technologies by acquiring specialized firms with intellectual property in flexible electronics. Deepen regulatory expertise to navigate evolving mandates like the EU MDR, ensuring continued market access and trust. Invest in advanced biocompatible materials R&D to enhance patient comfort and extend wear time, reducing potential compliance issues. Consolidate market share through strategic partnerships with large hospital systems, securing long-term service contracts.
For New Entrants and Emerging Players: Underserved chronic patients in niche neurological applications, such as ambulatory epilepsy monitoring, represent a significant white-space opportunity for new entrants. Focus on application diversification beyond cardiac and glucose monitoring, addressing unmet clinical needs. The elder care segment in Japan, with its receptive regulatory environment (PMDA), offers a highly penetrable geography. Adopt a "monitoring-as-a-service" go-to-market angle, reducing upfront capital expenditure for providers.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with deep pockets and a long-term vision for integrated healthcare solutions. This market retains strong viability over the next 5-10 years, driven by chronic disease prevalence and remote monitoring needs. Target specialized biosensor manufacturers or AI-driven analytics platforms that enhance on-device intelligence. The signal to watch is the broader expansion and adoption of the FDA's Digital Health Software Precertification program, indicating regulatory streamlining.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biocompatible Adhesives R&D | Enhances patient comfort and extends wear time, reducing compliance challenges for chronic patients. |
| Pursue FDA Digital Health Pre-Cert Program | Accelerates market access for software-driven patch innovations by leveraging organizational excellence for trusted manufacturers. |
| Expand "Monitoring-as-a-Service" Models | Disrupts traditional device sales, offering bundled solutions that appeal to United States and German hospitals managing operational budgets. |
| Target Niche Neurological Applications | Diversifies beyond established cardiac and glucose monitoring, opening new growth areas for product differentiation. |
| Secure Multi-Jurisdictional Regulatory Approvals | Ensures broad market access across the United States (FDA) and Europe (MDR), critical for clinical-grade devices. |
Research Approach
Document review covered FDA filings, EMA submissions, clinical trial databases, and industry association reports, complemented by interviews with key stakeholders. Primary research involved discussions with clinicians, hospital purchasing committees, biomedical engineers, and regulatory affairs leads across major markets. This approach facilitated bottom-up data collection, validated through top-down market sizing and competitive intelligence. The analysis triangulated insights from diverse sources to ensure data robustness.
Cross-referencing historical market performance with expert panel input established the foundational data points for the forecast framework. The analytical framework modeled key segmentation dimensions including product type, technology, end user, functionality, and regional regulatory clusters across the analysis window. Compound annual growth rates were derived from a multi-factor analysis considering chronic disease prevalence and healthcare expenditure trends. This approach projects market trajectory over the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and component supply disruptions. These forecasts reflect a set of current market assumptions. Deviation in reimbursement policy shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Plastic Films and Sheets Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Baking Paper Market
Others
Bamboo Straws Market
Others
Global Personal Care Packaging Market
Others
Gym Wipes Market
Others
5G Tester Market
Others
Global Automotive LED Lighting Market
Others
Global Video Processing Platform Market
Others
Global Extruded Plastics Market
Others
Global Multi Domain Controller Market
Others
Underwater Lighting Market
Others
Social Media Engagement Applications Market
Others
Fabric Based Computing Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Automatic Barriers and Bollards Market