
 Compound Coating Market | 2026-2036
Compound Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Coating Market Outlook
Performance-based maintenance contracts and software-monitored application services is recalibrating how compound coating value gets captured across the supply chain. Cargill leverages its integrated raw material position to secure captive supply of specialty resins for industrial coating formulations. Barry Callebaut sustains formulation leadership through dedicated R&D facilities focused on temperature-stable coating systems. Fuji Oil anchors its competitive position with manufacturing scale across Southeast Asian production hubs.
Compound coatings are multi-layer protective systems comprising polymer binders, curing agents, and functional additives applied to substrates for corrosion resistance, electrical insulation, or aesthetic finishing; epoxy formulations achieve adhesion strengths exceeding 20 MPa on pretreated metal surfaces. Polyurethane coatings dominate margin pools in automotive refinishing where durability specifications command premium pricing. Water-based technology leads growth trajectory as manufacturers reformulate to meet tightening volatile organic compound limits across major industrial jurisdictions. Powder coating occupies a mature position in appliance and architectural metal finishing with established application infrastructure.
EPA regulates hazardous air pollutant emissions from coating operations through Maximum Achievable Control Technology standards, while REACH restricts specific chemical substances in formulations sold within the European Economic Area. China's MEE enforces GB standards limiting VOC content in industrial coatings used at manufacturing facilities. Stakeholders must monitor evolving substance restriction schedules and application technology substitutions that determine which formulation platforms retain market access.
Market Dynamics
Water-based formulation technology is compressing solvent-borne capacity as REACH Phase 2 substance restrictions and China's GB 30981-2020 VOC limits force automotive OEMs and electronics contract manufacturers to retool application lines.
Growth Catalysts
- REACH substance restrictions:German automotive OEMs are accelerating water-based procurement timelines to meet 2026 SVHC sunset dates for chromium-based pretreatment chemicals.
- East Asian electronics clusters:Printed circuit board assemblers in Shenzhen and Ho Chi Minh City are specifying low-VOC coating systems to satisfy brand-owner sustainability scorecards.
- Dual carbon targets:China's MEE enforcement of GB standards is forcing industrial coating users toward powder and water-based platforms with lower embodied carbon.
Market Restraints
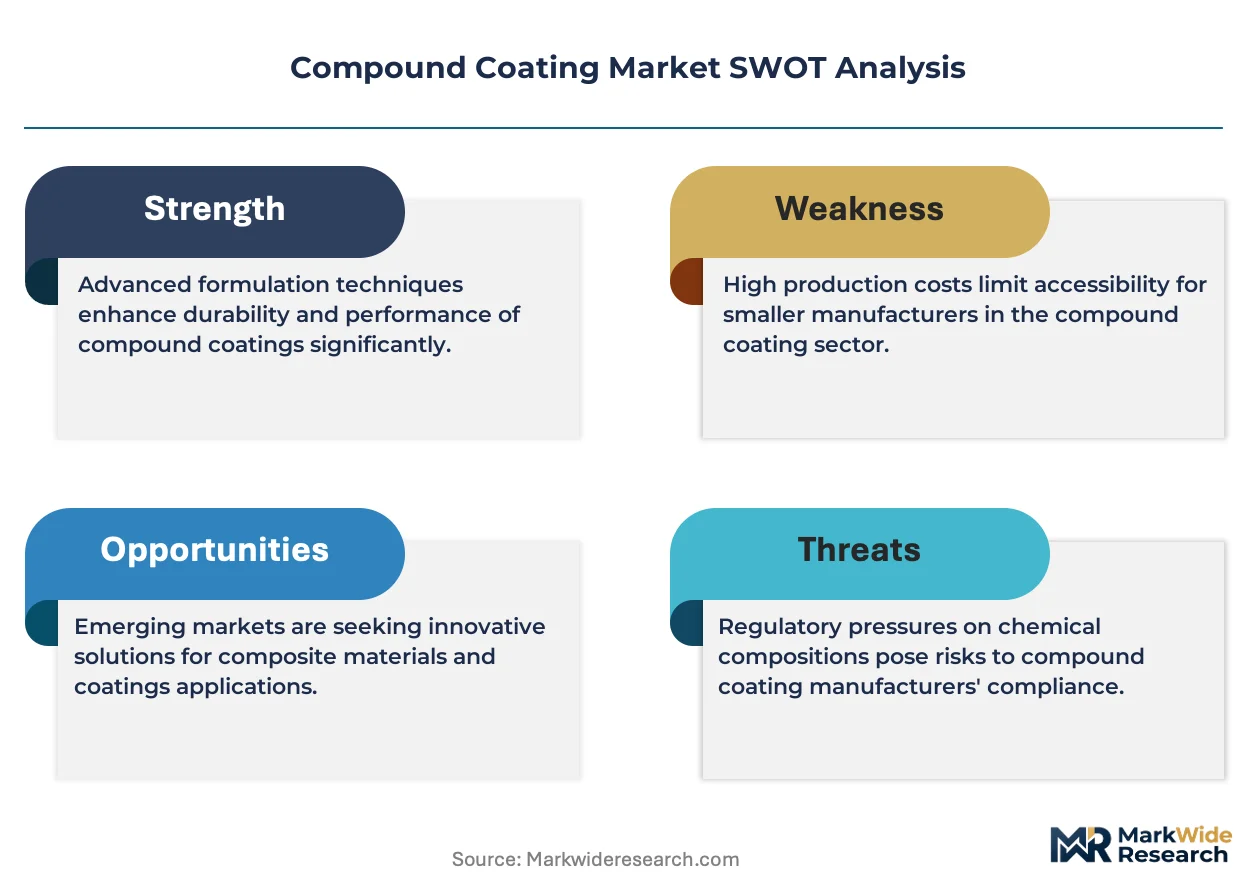
- Epoxy resin supply concentration:Bisphenol A and epichlorohydrin feedstock availability concentrates with integrated petrochemical complexes in the US Gulf Coast and Northeast Asia.
- Application equipment capex:Water-based systems require humidity-controlled spray booths and forced-dry ovens that triple initial capital outlay versus conventional solvent lines.
- Curing time penalties:Ambient-cure water formulations extend tack-free intervals from 4 hours to 24 hours, constraining high-volume automotive refinishing throughput.
Strategic Opportunities
- India PLI scheme:Electronics manufacturing incentives are attracting contract assemblers to Gujarat and Tamil Nadu, creating virgin demand for conformal coating specifications.
- UV-LED curing convergence:Photoinitiator chemistry advances are enabling instant cure of acrylate-based compounds, opening medical device and flexible electronics applications.
- Direct-to-manufacturer channels:Industrial coating formulators are bypassing traditional distributor networks to capture service revenue through on-site technical support contracts.
Industry Challenges
- Formulation chemist scarcity:Expertise in rheology modification and film-forming additive selection concentrates with aging technical workforces at established European and Japanese suppliers.
- Multi-jurisdiction certification lag:Securing simultaneous EPA NESHAP compliance, REACH registration, and China NMPA filing extends new product introduction cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Coating Market |
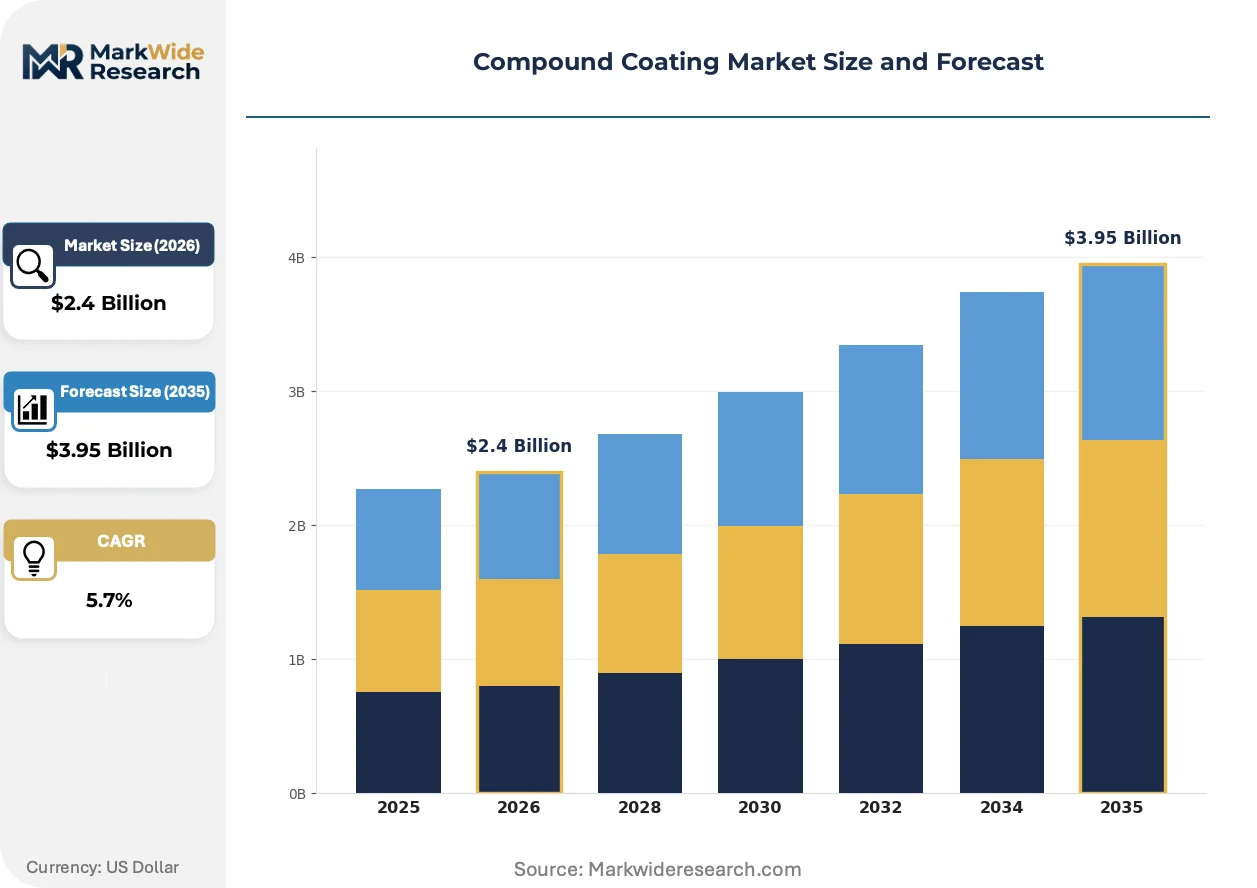
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings Application: Automotive, Aerospace, Electronics, Industrial Equipment Technology: Solvent-Based, Water-Based, Powder Coating, UV-Cured End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | Cargill, Barry Callebaut, Fuji Oil, Wilmar International, AAK, Bunge, Cargill Cocoa & Chocolate, Olam International, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Coating Market Strategic Shifts
Formulation science is pivoting from incremental VOC reduction toward functional performance differentiation, with temperature stability, electrical insulation grade, and application automation compatibility becoming primary specification drivers.
Self-healing polymer networks incorporating microencapsulated healing agents are absorbing damage-repair functionality previously delivered through thicker film builds or sacrificial topcoats. Aerospace component suppliers and wind turbine blade manufacturers are piloting these systems at limited scale. The technology is absorbing margin from conventional maintenance coating cycles by extending service intervals.
EPA's 2024 updates to Maximum Achievable Control Technology standards for coating operations are tightening hazardous air pollutant emission limits for metal furniture and appliance finishing facilities. Industrial users in Ohio and North Carolina are retrofitting thermal oxidizers or converting to powder coating to maintain operating permits. Automotive OEM paint shops face the most stringent compliance timelines and are consolidating supplier bases to secure formulation continuity.
Specification authority is migrating from purchasing departments to environmental health and safety teams armed with lifecycle assessment tools and Scope 3 emission accounting requirements. Tier-one automotive suppliers are disintermediating commodity coating distributors to engage directly with formulators capable of certifying carbon footprint per kilogram applied. This pattern concentrates in German and Japanese manufacturing supply chains where OEM sustainability audits are most advanced.
Compound Coating Market Segmentation
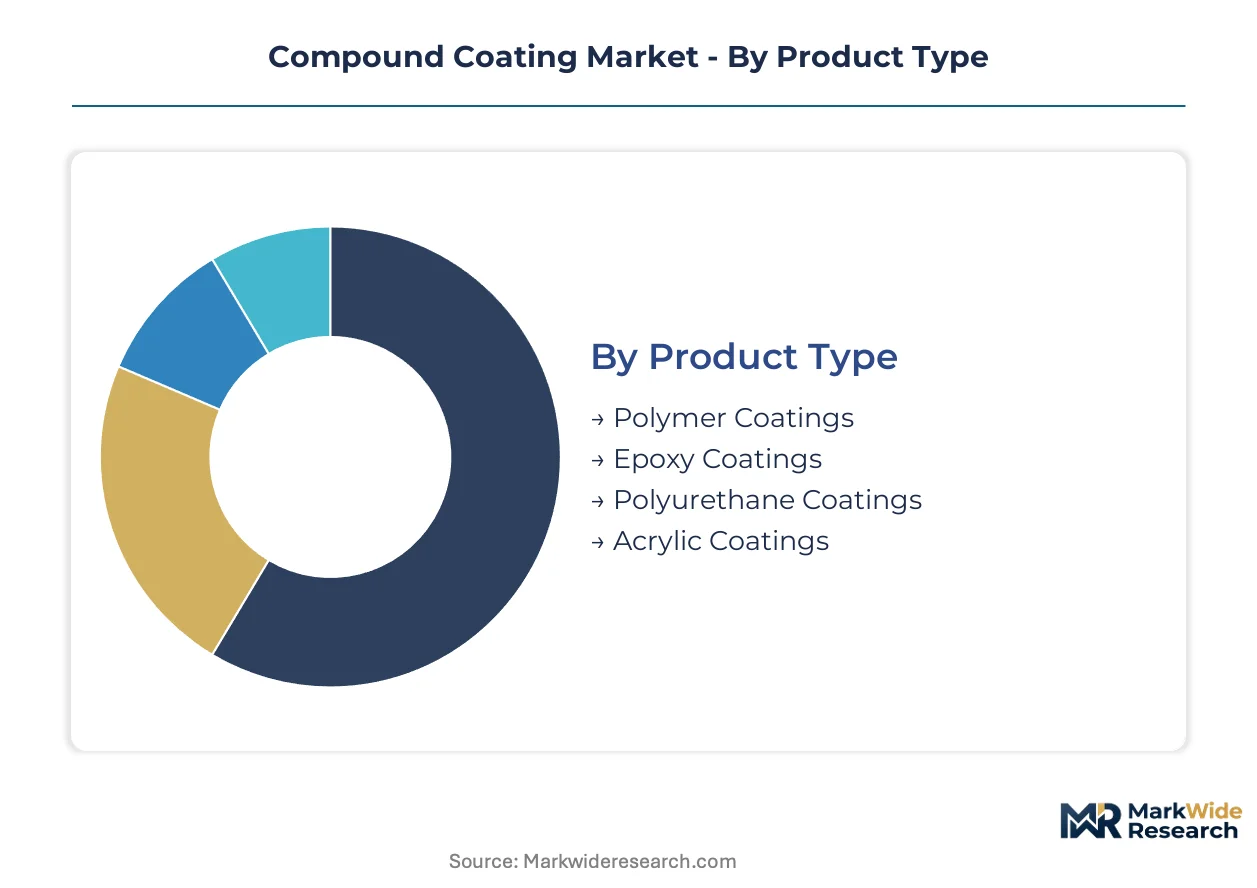
Compound coating procurement decisions pivot on formulation chemistry, application method, and end-use performance requirements. Specification authority concentrates with environmental health and safety teams who balance VOC compliance against adhesion strength and cure speed mandates.
Product Type:
Polymer chemistry determines adhesion strength, chemical resistance, and thermal stability across industrial applications.
- Polymer Coatings:Multi-resin systems blend acrylics, polyesters, and fluoropolymers to achieve tailored barrier properties for architectural metal finishing. German automotive OEMs specify these formulations for underbody corrosion protection where stone-chip resistance and salt-spray performance dominate procurement criteria.
- Epoxy Coatings:Two-part thermosetting systems achieve adhesion strengths exceeding 20 MPa on pretreated substrates through covalent crosslinking of bisphenol A diglycidyl ether with amine curing agents. Marine and offshore infrastructure operators in the US Gulf Coast specify high-build epoxy formulations for submerged steel protection where cathodic disbondment resistance determines specification.
- Polyurethane Coatings:Aliphatic isocyanate-cured systems deliver UV-stable glossy finishes with abrasion resistance for automotive refinishing. Premium pricing pools concentrate here due to durability specifications that command margin over commodity alternatives.
- Acrylic Coatings:Thermoplastic or thermosetting resin systems offer rapid dry-to-touch properties and exterior durability for architectural applications. Water-borne acrylic emulsions are gaining formulation share as VOC limits tighten across North American and European jurisdictions.
Mature deployment sits with epoxy systems in heavy industrial corrosion protection. Newer deployment is concentrated in water-borne acrylic emulsions for architectural and light industrial finishing.
Application:
End-use performance specifications drive formulation selection, cure technology, and film thickness requirements.
- Automotive:OEM paint shops and refinishing operations specify coatings meeting OEM gloss retention, chip resistance, and repairability standards. Water-based basecoat-clearcoat systems are displacing solvent-borne capacity as EPA NESHAP compliance deadlines approach for assembly facilities in Ohio and Michigan.
- Aerospace:Chromate-free pretreatment and primer systems must satisfy FAA airworthiness directives and OEM qualification protocols. Boeing and Airbus tier suppliers in Wichita and Toulouse are qualifying sol-gel and rare-earth conversion coatings to replace hexavalent chromium.
- Electronics:Conformal coatings for printed circuit boards require dielectric strength, moisture insulation resistance, and thermal cycling durability. Contract manufacturers in Shenzhen specify low-VOC acrylic and polyurethane conformal coatings to satisfy brand-owner sustainability scorecards.
- Industrial Equipment:Agricultural machinery, construction equipment, and material handling systems demand abrasion-resistant finishes with field repairability. Powder coating dominates this segment due to established application infrastructure and zero-VOC compliance.
Specification complexity peaks in aerospace where qualification cycles extend 24-36 months. Volume concentration centers on automotive OEM and refinishing channels.
Technology:
Application method determines capital equipment requirements, energy consumption, and regulatory compliance pathway.
- Solvent-Based:Conventional alkyd, epoxy, and polyurethane systems dissolved in aromatic hydrocarbons deliver rapid cure and excellent flow characteristics. REACH Phase 2 SVHC restrictions and China's GB 30981-2020 VOC limits are compressing capacity as automotive OEMs accelerate water-based procurement timelines.
- Water-Based:Acrylic, polyurethane, and epoxy dispersions achieve compliance with tightening VOC regulations while maintaining performance parity through advanced coalescing agent technology. Humidity-controlled spray booths and forced-dry ovens triple capital outlay versus solvent lines, constraining adoption at smaller contract finishers.
- Powder Coating:Thermosetting epoxy, polyester, and hybrid powders applied electrostatically deliver zero-VOC finishes with high transfer efficiency. Appliance and architectural metal finishing in North Carolina and Ohio retain mature powder infrastructure despite slower color change capabilities versus liquid alternatives.
- UV-Cured:Acrylate oligomer and monomer systems photoinitiated by UV-LED arrays achieve instant cure for heat-sensitive substrates. Medical device manufacturers and flexible electronics assemblers are piloting these systems where thermal damage risk excludes conventional thermal cure.
Regulatory pressure is forcing substitution fastest in solvent-borne automotive coatings. UV-LED curing represents the steepest expansion trajectory as photoinitiator chemistry advances enable broader substrate compatibility.
End User:
Channel structure determines technical support intensity, inventory carrying cost, and margin capture mechanism.
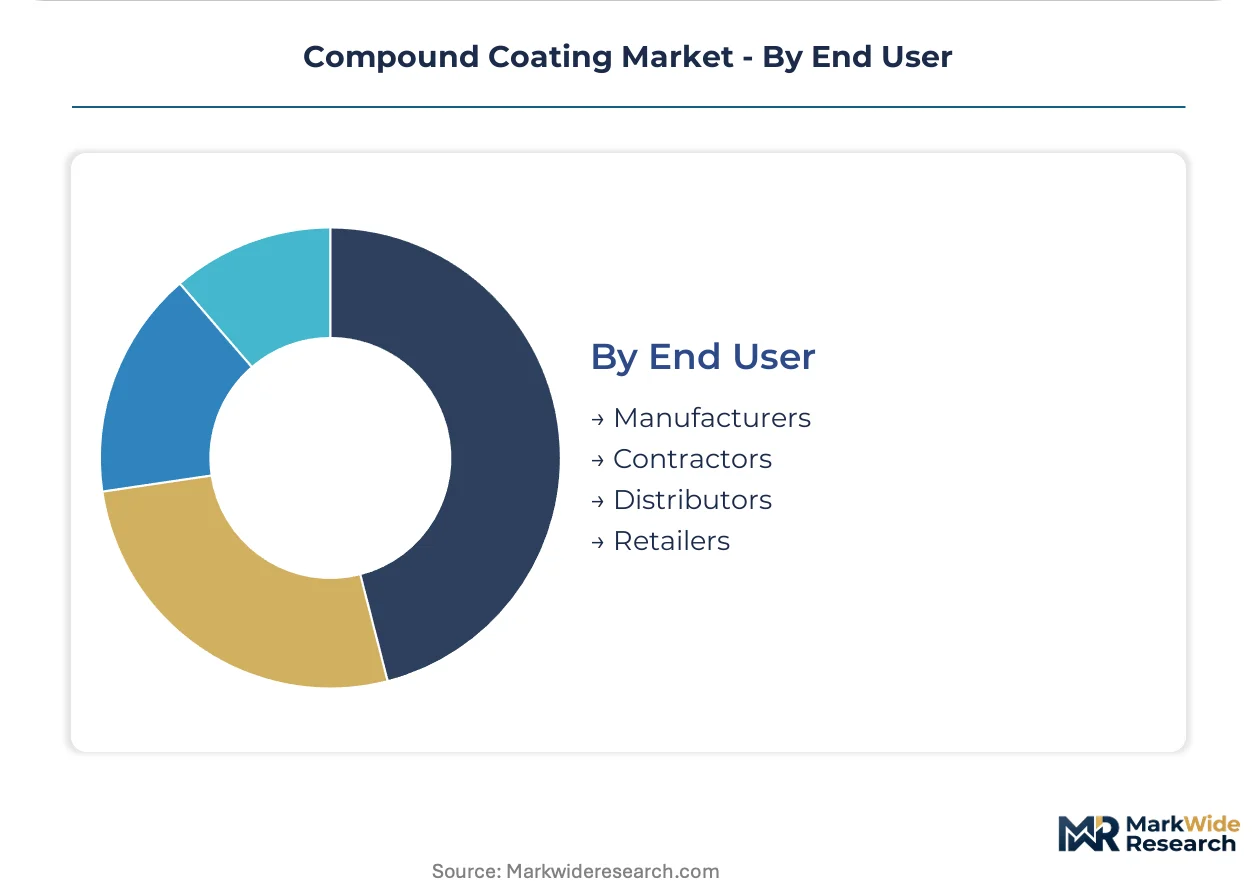
- Manufacturers:OEM captive paint shops and coating operations specify formulations directly with technical service contracts. Tier-one automotive suppliers in Germany and Japan are disintermediating distributors to engage formulators capable of certifying carbon footprint per kilogram applied.
- Contractors:Independent applicators serving maintenance, repair, and overhaul markets purchase through distributor networks with job-site technical support. Application equipment financing and waste disposal services determine supplier selection.
- Distributors:Regional and national coating distributors inventory commodity formulations while providing color matching and logistics services. Consolidation among industrial distribution channels is reducing formulation brand fragmentation.
- Retailers:Consumer and light commercial coating sales through home improvement and automotive aftermarket channels. Water-based DIY formulations are displacing solvent-borne alternatives as consumer VOC awareness rises.
Direct manufacturer engagement concentrates in automotive and aerospace where sustainability auditing is most advanced. Distributor dependency persists in maintenance contracting where geographic coverage and emergency response capability dominate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in integrated petrochemical corridors while consumption clusters around automotive assembly and electronics manufacturing hubs. East Asia dominates formulation output through captive resin supply chains. European and North American markets function as technology incubators where regulatory pressure accelerates water-based adoption.
United States
Automotive OEMs in Ohio and Michigan are retrofitting paint shops to meet EPA NESHAP compliance deadlines for hazardous air pollutant emissions. The EPA's Maximum Achievable Control Technology standards are forcing thermal oxidizer installations or powder coating conversions at metal furniture facilities. Industrial coating demand concentrates in the Midwest manufacturing belt where appliance finishing operations maintain mature powder application infrastructure.
Germany
Automotive OEM procurement teams are accelerating water-based coating timelines to satisfy REACH Phase 2 SVHC sunset dates for chromium-based pretreatments. ECHA substance restrictions are compressing solvent-borne capacity as KBA vehicle certification protocols tighten environmental audit requirements. Bavarian automotive suppliers are disintermediating distributors to engage directly with formulators capable of certifying carbon footprint per kilogram applied.
China
Electronics contract manufacturers in Shenzhen specify low-VOC conformal coatings to satisfy brand-owner sustainability scorecards. MEE enforcement of GB 30981-2020 VOC limits is forcing industrial coating users toward powder and water-based platforms. Yangtze River Delta manufacturing clusters are absorbing the fastest capacity expansion as dual carbon targets reshape procurement specifications.
Japan
Automotive OEMs are expanding procurement of water-based compound coatings as domestic environmental standards tighten formulation requirements. METI industrial policy is accelerating qualification of chromate-free pretreatment systems for aerospace tier suppliers. Nagoya-area manufacturing hubs concentrate specification authority with environmental health and safety teams armed with lifecycle assessment tools.
India
Electronics manufacturing incentives under the PLI scheme are attracting contract assemblers to Gujarat and Tamil Nadu, creating virgin demand for conformal coating specifications. BIS standards for industrial coatings are evolving toward VOC alignment with European benchmarks. Chennai and Ahmedabad industrial corridors are emerging as qualification sites for automotive and electronics coating applications.
Compound Coating Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct value capture models in the compound coating sector. Integrated agribusiness conglomerates with captive oleochemical supply chains occupy upstream positions while specialized formulation houses concentrate on application technology and technical service contracts. The market structures around three archetypes: integrated raw material suppliers, dedicated coating formulators, and diversified food-ingredient conglomerates with industrial coating divisions. Consolidation pressure is intensifying through backward integration moves and direct-to-manufacturer channel expansion.
Within the integrated supply tier, Cargill leverages its global oleochemical footprint to anchor resin supply security for industrial formulations. Barry Callebaut and Fuji Oil exemplify the dedicated R&D-intensive archetype, with the former sustaining formulation leadership through temperature-stable coating systems and the latter anchoring competitive position with manufacturing scale across Southeast Asian production hubs. These three entities represent distinct strategic postures: upstream integration, technical differentiation, and regional manufacturing density.
| Leading Market Players |
|---|
| Cargill |
| Barry Callebaut |
| Fuji Oil |
| Wilmar International |
| AAK |
| Bunge |
| Cargill Cocoa & Chocolate |
| Olam International |
| ADM |
| Others |
Value Chain & Pricing Dynamics
REACH Phase 2 substance restrictions gate qualified supply access and premium-tier pricing power, forcing automotive OEMs in Germany to pay formulation premiums for SVHC-compliant water-based systems while compressing margins on legacy solvent-borne capacity.
Pricing Analysis
Margin tightening in water-based formulations reflects humidity-controlled spray booth capex burdens and extended curing cycles. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified chromate-free systems from automotive refinishing grades and commodity industrial maintenance coatings. Cost-down pressure on solvent-borne tiers accelerates because REACH sunset dates and China's GB 30981-2020 limits are shuttering qualified demand. Contract finishers serving automotive aftermarket channels exhibit highest price sensitivity, while aerospace tier suppliers absorbing 24-36 month qualification cycles demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Japanese automotive assembly plants, while distributor networks serve fragmented maintenance contractors. Bisphenol A and epichlorohydrin feedstock availability concentrates with integrated petrochemical complexes in the US Gulf Coast, Northeast Asia, and Germany. Epoxy resin supply is anchored in naphtha cracking corridors with limited geographic diversification. Single-source vulnerability in specialty amine curing agents sourced from Belgian and Japanese chemical producers creates formulation continuity risk. Distribution runs through regional coating distributors consolidating inventory positions for commodity architectural and industrial maintenance grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound coating procurement functions as a cost-of-compliance market where REACH registration investment and EPA NESHAP certification create barrier-to-entry moats for incumbent formulators with established regulatory dossiers.
For Market Incumbents: Cement formulation continuity advantages by securing captive resin supply through backward integration into specialty epichlorohydrin derivatives or long-term offtake agreements with US Gulf Coast petrochemical complexes. Accelerate water-based capacity expansion in East Asian manufacturing clusters to preempt emerging local competitors serving Shenzhen electronics assemblers. Chromate-free pretreatment qualification delays at Boeing and Airbus tier suppliers present consolidation opportunity for compliant players.
For New Entrants and Emerging Players: The premium-to-economy price gap in conformal coatings for Indian electronics manufacturing offers white-space entry around BIS-aligned VOC specifications. Target Gujarat and Tamil Nadu contract assemblers attracted by PLI scheme incentives with technical service contracts bundling application equipment financing and on-site formulation support. UV-LED curing systems for medical device and flexible electronics applications represent fastest-penetrable technology segment given limited incumbent qualification.
For Investors and Strategic Acquirers: Accelerated water-based procurement timelines at German automotive OEMs is the leading indicator that formulation R&D capabilities will concentrate among players with integrated resin positions and REACH registration depth. Five-to-ten year viability favors backward-integrated specialists over asset-light distributors. Acquisition target archetype: European or Japanese formulators with aging technical workforces and established chromate-free aerospace qualifications but limited succession planning. Signal to watch: consolidation of distributor networks in North American industrial maintenance channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Cargill's oleochemical footprint secures captive epoxy feedstock supply for industrial formulations. |
| Water-Based Capacity Expansion | New humidity-controlled spray booths in Yangtze River Delta clusters serve Shenzhen electronics assemblers. |
| Chromate-Free Qualification Investment | Sol-gel and rare-earth conversion coatings replace hexavalent chromium at Boeing and Airbus tier suppliers. |
| Direct-to-Manufacturer Channel Development | Bavarian automotive suppliers disintermediate distributors to engage formulators certifying carbon footprint per kilogram. |
| UV-LED Curing Technology Partnership | Photoinitiator chemistry advances enable instant cure for medical device and flexible electronics applications. |
Study Parameters
Multi-period observation of formulation technology shifts, regulatory compliance timelines, and procurement pattern changes anchored the trend analysis, supplemented by interviews with coating formulator R&D directors, automotive OEM procurement leads, electronics contract manufacturer quality managers, and industrial distributor channel heads. Secondary validation drew from EPA NESHAP regulatory filings, ECHA REACH registration databases, China MEE GB standard enforcement reports, and SEC 10-K disclosures from integrated chemical producers. Bottom-up demand modeling across end-use segments triangulated against top-down petrochemical feedstock availability assessments.
Segment-weighting approaches applied polymer chemistry, application method, and end-use performance requirements as primary dimensions, with regional regulatory cluster intensity as a cross-cutting modifier. CAGRs were derived through extrapolation of technology substitution curves and compliance-driven retooling cycles across the projection horizon. Industry-specific forecast inputs included automotive OEM paint shop conversion timelines and electronics manufacturing incentive scheme uptake rates.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time contract manufacturer procurement data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding REACH Phase 2 enforcement consistency and China dual carbon target implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Coating Pre-Treatment Market
Coatings
South Africa Protective Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Stain Resistance Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Coating Market
Coatings
Mexico Protective Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
2K Protective Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Japan Automotive OEM Coatings Market