
 Argentina Oil and Gas Upstream Market | 2026-2036
Argentina Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Oil and Gas Upstream Market Outlook
Performance-based drilling contracts is rebalancing how operators procure upstream services in Argentina. YPF S.A. anchors the unconventional segment through its dominant Vaca Muerta lease position. Tecpetrol differentiates via vertical integration into pressure pumping and completion services. Chevron Argentina S.R.L. competes through its Loma Campana joint venture scale and operational continuity.
Argentina oil and gas upstream encompasses exploration, drilling, and extraction of crude oil and natural gas from conventional reservoirs, shale formations, and offshore blocks, with hydraulic fracturing and horizontal drilling now comprising the dominant technical approach for Vaca Muerta development. Unconventional production leads total output growth as shale wells deliver sustained initial production rates exceeding conventional decline curves. Enhanced oil recovery applications remain concentrated in mature Neuquén Basin fields where waterflooding and gas injection extend reservoir life. Horizontal drilling technology captures expanding capital allocation as longer laterals improve per-well economics across the Vaca Muerta and Los Molles shales.
ENARGAS, Argentina's national gas regulator, shapes producer behavior through export quota allocations and domestic price band mechanisms that influence investment pacing. The Secretary of Energy's hydrocarbon transport concession framework determines pipeline access priority and tariff structures for new field developments. Operators and service contractors must monitor fiscal regime stability and peso-dollar exchange rate volatility as these variables directly impact project returns and equipment import costs.
Market Dynamics
Horizontal drilling with extended laterals is compressing per-well breakeven costs across the Vaca Muerta shale, concentrating capital deployment in Neuquén Province while marginalizing conventional field investments elsewhere in Argentina.
Growth Catalysts
- Gas-fired power expansion:Argentine utilities are adding turbine capacity to offset hydroelectric reliability declines, pulling incremental gas demand from upstream producers.
- ENARGAS export quota flexibility:Adjusted permit frameworks allow producers to access international price benchmarks when domestic supply obligations are met.
- Pressure pumping localization:In-house service capacity in Neuquén Province reduces equipment import delays and dollar-denominated cost exposure.
Market Restraints
- Peso-dollar exchange rate volatility:Unhedged currency swings inflate project return uncertainty and equipment import costs for operators with dollar-denominated debt.
- Domestic price band compression:ENARGAS-administered gas tariffs sit below international benchmarks, constraining reinvestment rates in marginal acreage.
- Import dependency for specialty steel:Premium OCTG and directional drilling equipment sourcing concentrates in North American and Asian suppliers, exposing Argentine projects to supply chain bottlenecks.
Strategic Opportunities
- Los Molles shale extension:Deeper formation testing in Mendoza Province offers untested resource potential with analogous geochemistry to Vaca Muerta.
- LNG export infrastructure:Bahía Blanca regasification reversal projects could unlock Atlantic basin pricing for Neuquén Basin producers.
- Carbon capture co-development:Industrial CO2 offtake agreements from cement and steel plants create enhanced oil recovery feedstock for mature Neuquén fields.
Industry Challenges
- Directional drilling specialist scarcity:Geosteering and MWD/LWD technician shortages in Argentina force reliance on expatriate crews and extended training timelines.
- Multi-pad completion coordination:Simultaneous operations across stacked laterals demand precise logistics sequencing that local service supply chains struggle to execute at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Oil and Gas Upstream Market |
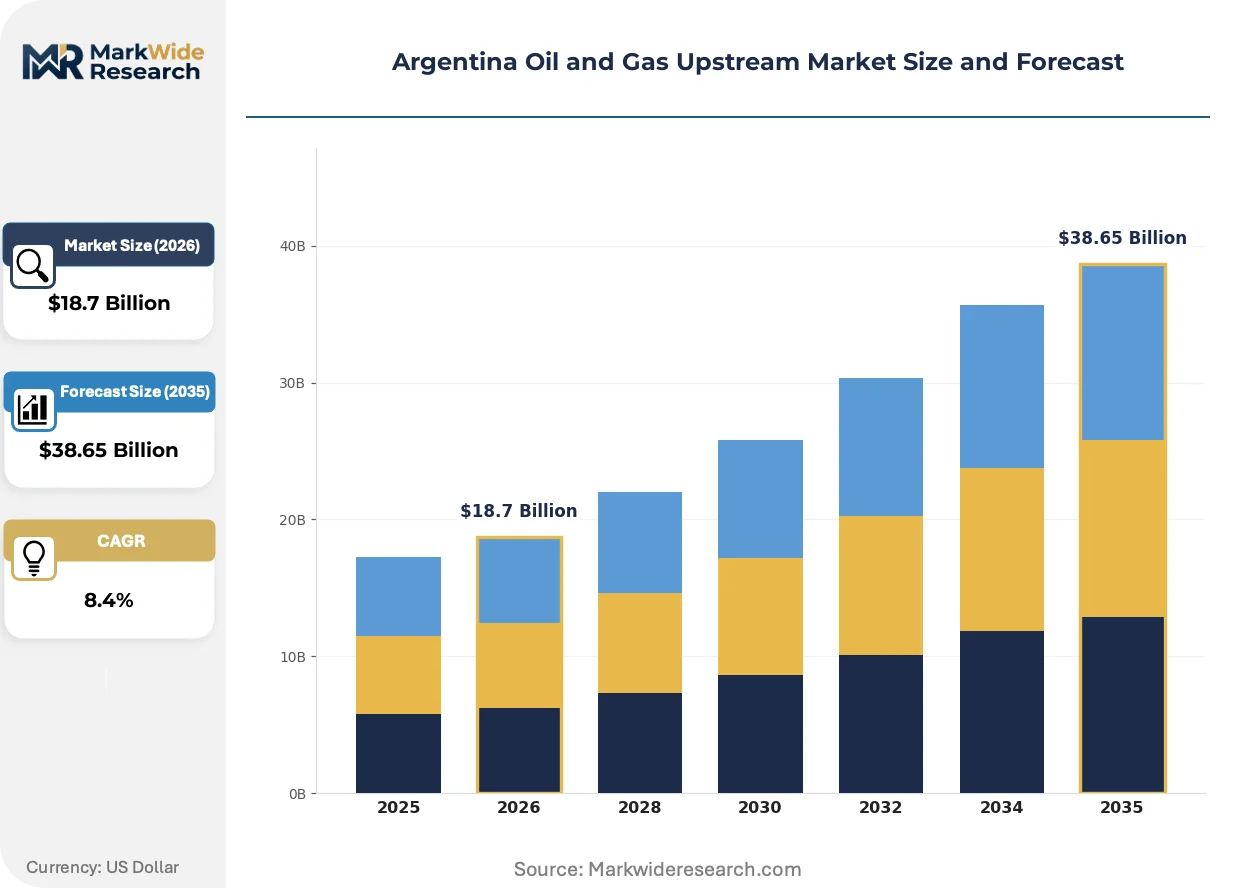
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Unconventional, Offshore, Onshore Production Stage: Exploration, Drilling, Extraction, Completion Technology: Hydraulic Fracturing, Horizontal Drilling, Well Logging, Enhanced Oil Recovery Operational Role: Operators, Contractors, Service Providers, Equipment Manufacturers |
| Companies Covered | Equinor ASA, Pampa Energía, YPF S.A., Pluspetrol, Tecpetrol, Chevron Argentina S.R.L., Tullow Oil PLC, TotalEnergies SE, ExxonMobil Exploration Argentina S.R.L., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Oil and Gas Upstream Market Strategic Shifts
Digital subsurface characterization and automated rig controls are compressing drilling cycle times while regulatory frameworks adapt to unconventional production scale.
Geosteering with real-time gamma ray and resistivity logging is converging with automated drawworks control to enable continuous wellbore adjustment without surface intervention. YPF and joint venture partners are deploying these integrated systems across Vaca Muerta multi-pad developments. The convergence is reducing non-productive time and enabling longer lateral extensions that improve per-section economics.
The Secretary of Energy's hydrocarbon transport concession framework is revising pipeline access priority rules to accommodate shale production volume swings. New entrants in Neuquén Basin development face tariff structures that favor committed shipper contracts over interruptible access. Midstream operators are responding by pre-selling firm capacity to anchor field development financing.
Integrated drilling and completion service contracting is displacing discrete vendor procurement across major Vaca Muenta joint ventures. Operators now bundle directional drilling, pressure pumping, and wireline services under single-provider agreements with performance guarantees. This consolidation is most advanced in Loma Campana and neighboring blocks where joint venture governance favors simplified vendor management.
Argentina Oil and Gas Upstream Market Segmentation
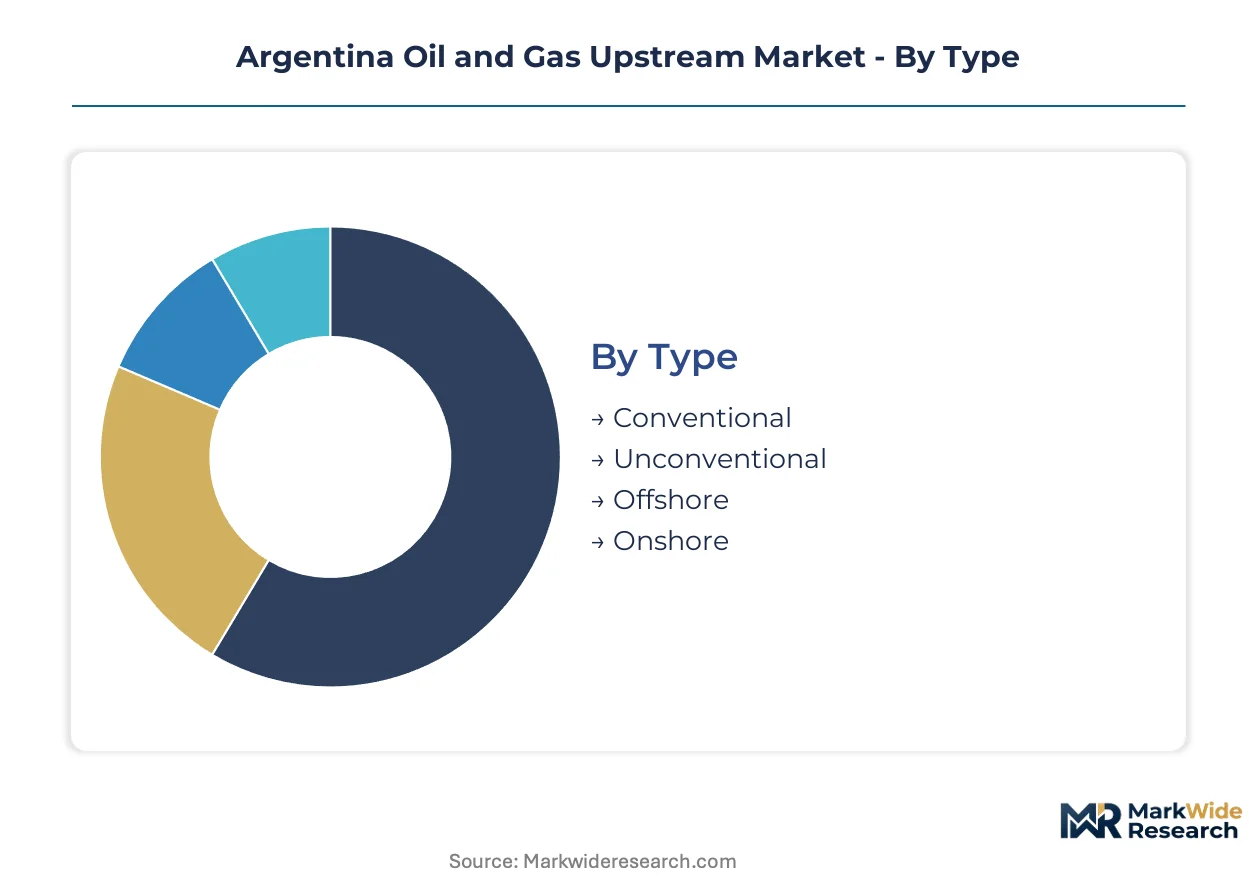
Segmentation in Argentina's upstream market reveals how capital allocation splits between mature conventional assets and unconventional shale developments. Understanding these divisions clarifies where ENARGAS regulatory frameworks, Neuquén Basin infrastructure, and service contractor specialization create competitive advantages for specific operational profiles.
Type:
Standardized extraction methods dominate conventional and offshore categories, while unconventional development demands customized well designs calibrated to Vaca Muerta's variable pay zones.
- Unconventional:Shale reservoirs in Neuquén Province require horizontal drilling with extended laterals and multi-stage hydraulic fracturing. Vaca Muerta formation development concentrates investment here as operators chase EUR improvements through longer laterals and tighter stage spacing.
- Conventional:Mature sandstone and carbonate reservoirs across the Neuquén, Cuyo, and Austral basins employ vertical wells with artificial lift. Declining production profiles limit new capital allocation outside of enhanced recovery projects in legacy fields.
- Offshore:Limited activity concentrates in the Argentine continental shelf with jack-up and semi-submersible rig deployment. Malvinas Basin exploration remains constrained by infrastructure distance and jurisdictional complexity.
- Onshore:Encompasses both conventional and unconventional terrestrial development across Argentina's producing provinces. Pipeline connectivity and road infrastructure determine economic viability for marginal conventional acreage.
Leading the category by volume: Unconventional. Expanding most quickly: Unconventional.
Production Stage:
Front-loaded capital intensity in exploration contrasts with recurring operational expenditure patterns in extraction and completion.
- Drilling:Directional drilling with geosteering capabilities commands premium dayrates in Vaca Muerta multi-pad developments. Rig availability and specialist crew scarcity create bottlenecks during activity upswings.
- Completion:Multi-stage hydraulic fracturing and perforation operations determine ultimate recovery in shale wells. Pressure pumping localization in Neuquén Province reduces equipment import delays and dollar-denominated cost exposure.
- Exploration:Seismic acquisition and wildcat drilling targets untested formations in Los Molles shale and deeper Vaca Muerta benches. High failure rates and capital intensity limit participation to well-capitalized operators.
- Extraction:Artificial lift, surface facility operations, and production optimization sustain output from producing wells. Mature field operations concentrate on minimizing opex per barrel through automation and workforce rationalization.
Highest capital absorption: Drilling. Steepest expansion trajectory: Completion.
Technology:
Proprietary technology differentiation separates integrated service providers from commodity equipment suppliers.
- Hydraulic Fracturing:High-pressure fluid injection creates conductive fracture networks in low-permeability shale. Sand and ceramic proppant sourcing from regional suppliers reduces import dependency for Neuquén Basin operators.
- Horizontal Drilling:Directional control systems enable lateral extensions exceeding 2,500 meters in Vaca Muerta targets. Real-time geosteering with gamma ray and resistivity logging improves landing precision in thin pay zones.
- Well Logging:Wireline and logging-while-drilling services characterize formation properties for completion design. Open-hole and cased-hole logging runs provide petrophysical data for reserve estimation.
- Enhanced Oil Recovery:Waterflooding, gas injection, and chemical EOR extend productive life of mature Neuquén Basin fields. Carbon dioxide sourcing from industrial emitters creates co-development opportunities with cement and steel plants.
Widest deployment: Horizontal Drilling. Gaining share fastest: Hydraulic Fracturing.
Operational Role:
Margin capture concentrates with asset-owning operators while contractors absorb execution risk and capital intensity.
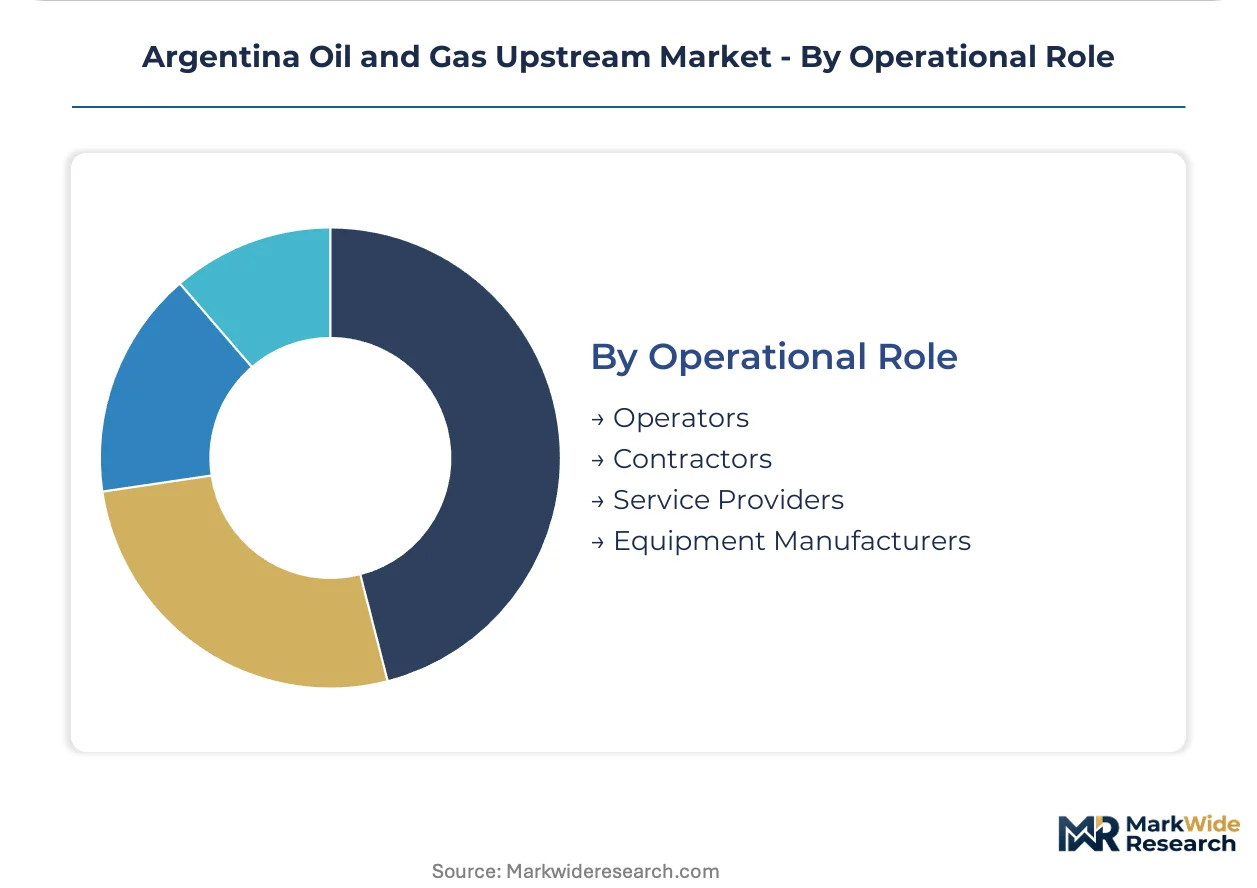
- Operators:YPF S.A. and joint venture partners hold mineral rights and production sharing contracts. ENARGAS export quota allocations and domestic supply obligations shape investment pacing for license holders.
- Service Providers:Directional drilling, wireline, and pressure pumping contractors deliver specialized technical services. Performance-based contracting with integrated service bundles displaces discrete vendor procurement across major Vaca Muerta developments.
- Contractors:Drilling contractors supply rigs and crews under dayrate or turnkey arrangements. Rig availability constraints during activity peaks force reliance on imported equipment and expatriate crews.
- Equipment Manufacturers:OCTG, pumps, and pressure control equipment producers face import dependency for premium specialty steel. Local fabrication capacity expansion targets standard pressure pumping equipment to reduce dollar-denominated procurement.
Controlling capital allocation: Operators. Growing fastest: Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's domestic gas production lags behind thermal power generation requirements, forcing utilities to contract incremental supply from Neuquén Basin shale operators. ENARGAS export quota frameworks attempt to balance this deficit against producer incentives for international sales.
Neuquén Province
Vaca Muerta shale development concentrates drilling permits and pressure pumping capacity in this Patagonian jurisdiction. The provincial hydrocarbon secretariat administers local environmental clearances for multi-pad unconventional operations. Añelo and Rincón de los Sauces anchor the service contractor ecosystem where horizontal drilling specialists cluster around YPF-operated joint ventures.
Buenos Aires Province
Bahía Blanca petrochemical complexes and LNG regasification terminals create demand pull for Neuquén Basin gas transport. The national Secretary of Energy's pipeline concession framework prioritizes firm shipper contracts from this Atlantic port cluster. Mar del Plata offshore exploration blocks remain underdeveloped due to infrastructure distance and jurisdictional complexity with the Malvinas Basin.
Mendoza Province
Los Molles shale testing targets deeper formation potential with analogous geochemistry to Vaca Muerta. The provincial energy ministry coordinates with ENARGAS on exploratory drilling permits for untested benches. Uspallata and Malargüe host conventional legacy fields where enhanced oil recovery projects extend productive life through waterflooding operations.
Chubut Province
Austral Basin conventional gas fields supply regional industrial demand through dedicated pipeline spurs. The national hydrocarbon regulator adjusts transport tariffs for this southern corridor to maintain marginal field economics. Comodoro Rivadavia maintains offshore supply base infrastructure for jack-up rig mobilization to southern exploration blocks.
Argentina Oil and Gas Upstream Market Competitive Environment
Top-tier vendors anchor unconventional shale development, while mid-tier independents concentrate on conventional asset optimization and marginal field rehabilitation. State-linked operators hold mineral rights across the most productive Vaca Muerta blocks, constraining entry for unaffiliated producers. Strategic archetypes separate into integrated state enterprises, international joint venture partners, and domestic independent operators. Competitive moves center on performance-based drilling contracts and in-house pressure pumping localization to reduce dollar-denominated cost exposure.
Among state-affiliated operators, YPF S.A. occupies the dominant leaseholder position across Neuquén Basin shale acreage. Chevron Argentina S.R.L. and ExxonMobil Exploration Argentina S.R.L. represent the international joint venture archetype, anchoring capital-intensive horizontal drilling programs through partnership structures with the national operator.
| Leading Market Players |
|---|
| Equinor ASA |
| Pampa Energía |
| YPF S.A. |
| Pluspetrol |
| Tecpetrol |
| Chevron Argentina S.R.L. |
| Tullow Oil PLC |
| TotalEnergies SE |
| ExxonMobil Exploration Argentina S.R.L. |
| Others |
Value Chain & Pricing Dynamics
Directional drilling specialist scarcity in Neuquén Province widens pricing spreads between integrated service bundles and discrete vendor procurement, compressing margins for operators unable to secure captive pressure pumping capacity.
Pricing Analysis
Cost-down pressure on unconventional well services accelerates as ENARGAS-administered domestic gas tariffs sit below international benchmarks, forcing operators to extract savings from drilling and completion contractors. Three-tier pricing structure across integrated performance-based contracts, standalone dayrate arrangements, and spot-market equipment leasing separates YPF-led joint ventures from mid-tier independents. Price differentiation traces to localization depth—operators with in-house pressure pumping capture 15-20% cost advantages over import-dependent competitors. Buyer price sensitivity concentrates among marginal acreage developers in Mendoza and Chubut provinces, while Vaca Muerta core operators prioritize execution certainty over rate negotiation.
Supply Chain Analysis
Premium OCTG and directional drilling equipment sourcing rests on North American and Asian specialty steel producers, exposing Argentine projects to supply chain bottlenecks during activity upswings. Sand and ceramic proppant draw from regional Neuquén Basin suppliers, reducing import dependency for hydraulic fracturing operations. Rig availability constraints during peak drilling windows create single-source vulnerability for automated drawworks and geosteering systems. Distribution runs through Añelo and Rincón de los Sauces service contractor clusters, with pipeline access priority determined by firm shipper contracts under the Secretary of Energy's hydrocarbon transport concession framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's upstream market operates as a supply-constrained system where directional drilling crew scarcity props pricing for integrated service providers and compresses returns for equipment-import-dependent operators.
For Market Incumbents: Anticipate peso-dollar exchange rate volatility by securing long-term equipment lease structures and expanding captive pressure pumping localization in Neuquén Province. Defensive consolidation through performance-based drilling contract standardization will neutralize mid-tier competitors unable to match integrated service bundling. Priority lever: backward integration into proppant sourcing and OCTG inventory management.
For New Entrants and Emerging Players: Digital-channel service marketplaces for surplus rig capacity and spot equipment leasing offer low-friction entry paths without capital-intensive fleet ownership. Los Molles shale exploratory drilling in Mendoza Province presents the most penetrable white space, with analog Vaca Muerta geochemistry and limited incumbent leaseholder concentration. Go-to-market angle: specialized geosteering and MWD/LWD technician training programs addressing the sector's critical human capital bottleneck.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated service providers with established Neuquén Basin logistics footprints and ENARGAS relationship history. Long-term viability hinges on exposure to Vaca Muerta core development rather than marginal conventional asset rehabilitation. Signal to watch: ENARGAS export quota expansion announcements indicating producer pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Pumping Localization | Captive equipment capacity in Neuquén Province insulates operators from dollar-denominated import cost swings. |
| Performance-Based Drilling Contracts | Integrated service bundling with YPF joint ventures displaces discrete vendor procurement across Vaca Muerta blocks. |
| LNG Export Infrastructure Development | Bahía Blanca regasification reversal unlocks Atlantic basin pricing for Neuquén Basin gas producers. |
| Carbon Capture Co-Development | Industrial CO2 offtake agreements from cement plants feed enhanced oil recovery in mature Neuquén fields. |
| Multi-Pad Completion Coordination | Simultaneous stacked lateral operations demand precision logistics sequencing that local supply chains struggle to execute. |
Study Parameters
Independent corroboration across operator drilling executives, ENARGAS regulatory affairs leads, pressure pumping procurement managers, and directional drilling contractors underwrites the qualitative findings in this study. Secondary validation draws from Secretary of Energy hydrocarbon transport concession filings, ENARGAS export quota allocation records, provincial hydrocarbon secretariat environmental clearance databases, and rig availability tracking services. Bottom-up well count and completion stage estimates triangulate against top-down production volume disclosures from Neuquén Basin joint ventures.
Rate-of-change decomposition across the analysis window separates volume growth from price realization effects in the unconventional segment. Segmentation dimensions modeled include reservoir type, production stage, technology deployment, and operational role, with provincial regulatory framework clusters as an Argentina-specific overlay. CAGRs derive from production capacity buildout schedules, drilling permit issuance patterns, and infrastructure commissioning timelines. Forecast inputs incorporate ENARGAS domestic supply obligation enforcement intensity and peso-dollar exchange rate assumption bands.
Inputs from operator production reports and provincial hydrocarbon secretariat filings were available through the study window; gaps in real-time drilling cost data and private joint venture contract terms introduce uncertainty bands around service provider margin estimates. Forecasts reflect documented assumptions regarding Vaca Muerta well productivity trends and export quota trajectory. Regulatory framework stability, currency volatility, and specialty equipment import lead times warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market