
 Saudi Arabia Defense Market | 2026-2036
Saudi Arabia Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Defense Market Outlook
Integrated logistics support and long-term sustainment contracts is recalibrating how defense value gets captured in the Kingdom. SAMI anchors domestic manufacturing partnerships across air and land domains. Lockheed Martin leverages its F-15 sustainment footprint to extend service revenue streams. BAE Systems competes through Eurofighter Typhoon support infrastructure and in-country training academies.
Saudi Arabia defense encompasses military platforms, subsystems, and services designed to national specifications for threat environments across air, land, sea, and cyber domains, with operational requirements typically demanding desert-hardened thermal management and extended mean-time-between-failures. The primary purpose centers on territorial defense, regional power projection, and internal security under centralized command structures. Air Defense platforms command priority allocation given ballistic missile threats from Yemen and Iran, while Cybersecurity Solutions represent the fastest-expanding budget line as critical infrastructure protection mandates tighten. Maintenance services generate recurring revenue with higher margin stability than initial platform sales, particularly for imported systems requiring certified spare parts pipelines.
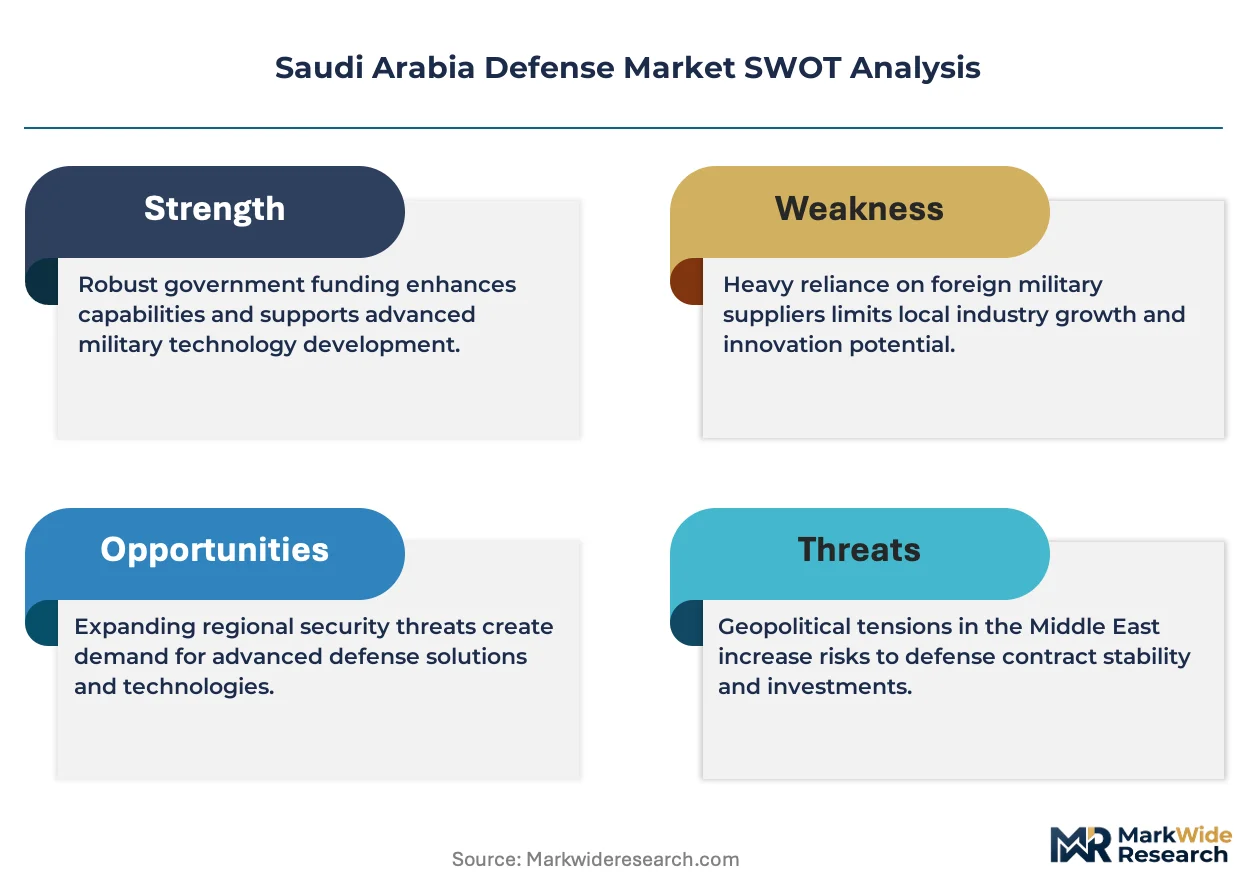
SFDA oversees occupational health standards for defense manufacturing facilities, while the General Authority for Military Industries enforces local content quotas and licensing for foreign suppliers. These frameworks compel joint ventures and technology disclosure as conditions for contract eligibility. Stakeholders must weigh localization commitments against intellectual property exposure when structuring partnership terms with Saudi entities.
Market Dynamics
Vision 2030 localization mandates are compressing procurement timelines and forcing foreign suppliers into technology transfer agreements as a condition of contract eligibility.
Growth Catalysts
- Ballistic missile threat environment:Iranian and Houthi missile programs are accelerating procurement of integrated air defense architectures and layered radar networks across Saudi Arabia's eastern and southern borders.
- GAMI certification regime:The General Authority for Military Industries mandates local content quotas that compel joint ventures and in-country manufacturing, expanding domestic industrial capacity.
- Desert-hardened platform specifications:Thermal management requirements for 50°C+ operating environments are driving specialized engineering partnerships and captive supply chain development.
Market Restraints
- Technology transfer friction:GAMI's intellectual property disclosure requirements create structural hesitation among Tier-1 suppliers protecting sensitive avionics and guidance systems.
- Skilled technician scarcity:Domestic workforce gaps in precision machining and systems integration extend platform delivery schedules and inflate training costs.
- Spare parts pipeline concentration:US and European certified component suppliers dominate sustainment networks, creating single-source vulnerability for imported fighter and missile systems.
Strategic Opportunities
- King Salman Military Industries City:The Taif cluster offers greenfield infrastructure for ammunition, armored vehicle, and aerospace component manufacturing with dedicated logistics corridors.
- Cyber-physical convergence:Integration of operational technology security with traditional military platforms creates demand for sovereign cybersecurity architectures protecting critical infrastructure.
- Long-term sustainment contracting:Performance-based logistics agreements spanning 15-20 years are displacing transactional spare parts procurement, locking in recurring revenue streams.
Industry Challenges
- SFDA occupational compliance:Defense manufacturing facilities must navigate dual oversight from military industrial regulators and health safety inspectors, extending facility certification timelines.
- Legacy platform integration:F-15 and Eurofighter Typhoon fleets operate on disparate data architectures, complicating unified command-and-control system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Defense Market |
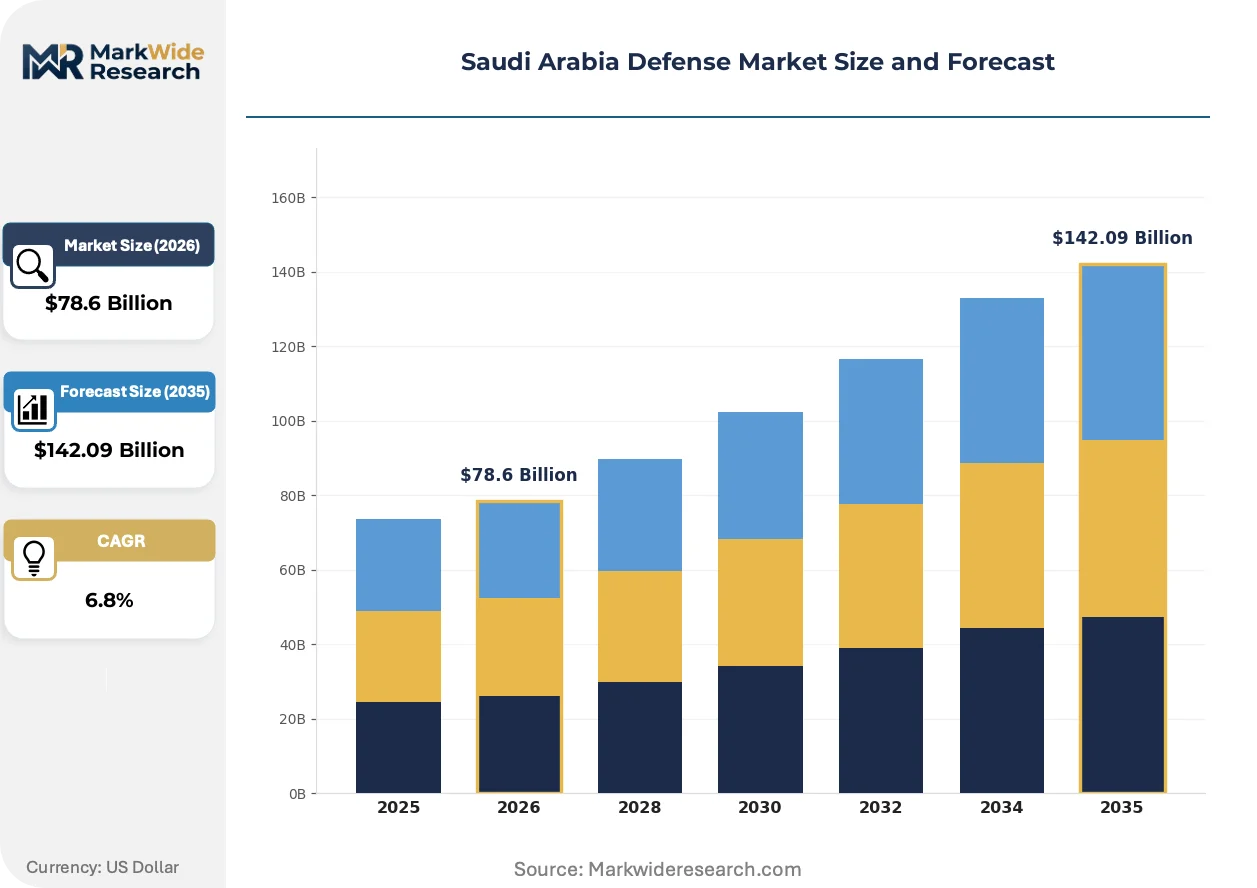
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Systems, Air Defense, Naval Systems, Cybersecurity Solutions End User: Armed Forces, Government Agencies, Defense Contractors, Security Forces Technology: AI & Automation, Advanced Weapon Systems, Surveillance Technology, Communication Systems Service Type: Manufacturing, Maintenance, Training, Logistics |
| Companies Covered | RTX Corporation, Northrop Grumman Corporation, Saudi Arabian Military Industries (SAMI), Leonardo S.p.A., General Dynamics Corporation, Lockheed Martin Corporation, BAE Systems, L3Harris Technologies, The Boeing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Defense Market Strategic Shifts
Digital thread architectures are collapsing design-to-field timelines while sovereign capability mandates are reshaping supplier partnership structures across the Kingdom's defense industrial base.
Modular open systems architectures are unifying previously siloed avionics, sensor, and weapon systems across fighter and ground-based air defense platforms. The Royal Saudi Air Force is mandating MOSA compliance in new procurement specifications to enable rapid capability upgrades without vendor lock-in. This convergence is compressing technology refresh cycles from decade-long platform replacements to incremental software-defined enhancements.
GAMI's local content certification framework is tightening enforcement thresholds for foreign suppliers seeking contract eligibility. Industrial offset agreements now require measurable technology transfer milestones rather than nominal joint venture structures. Air and missile defense platforms face the steepest compliance burden given their strategic priority within Saudi procurement portfolios.
Integrated product support contracts are bundling training, spare parts, and depot maintenance into single long-term agreements. The Royal Saudi Land Forces and Air Force are consolidating vendor relationships to reduce administrative overhead and improve fleet availability metrics. This consolidation is most visible in combat aircraft sustainment, where OEMs compete on lifetime cost guarantees rather than flyaway unit pricing.
Saudi Arabia Defense Market Segmentation
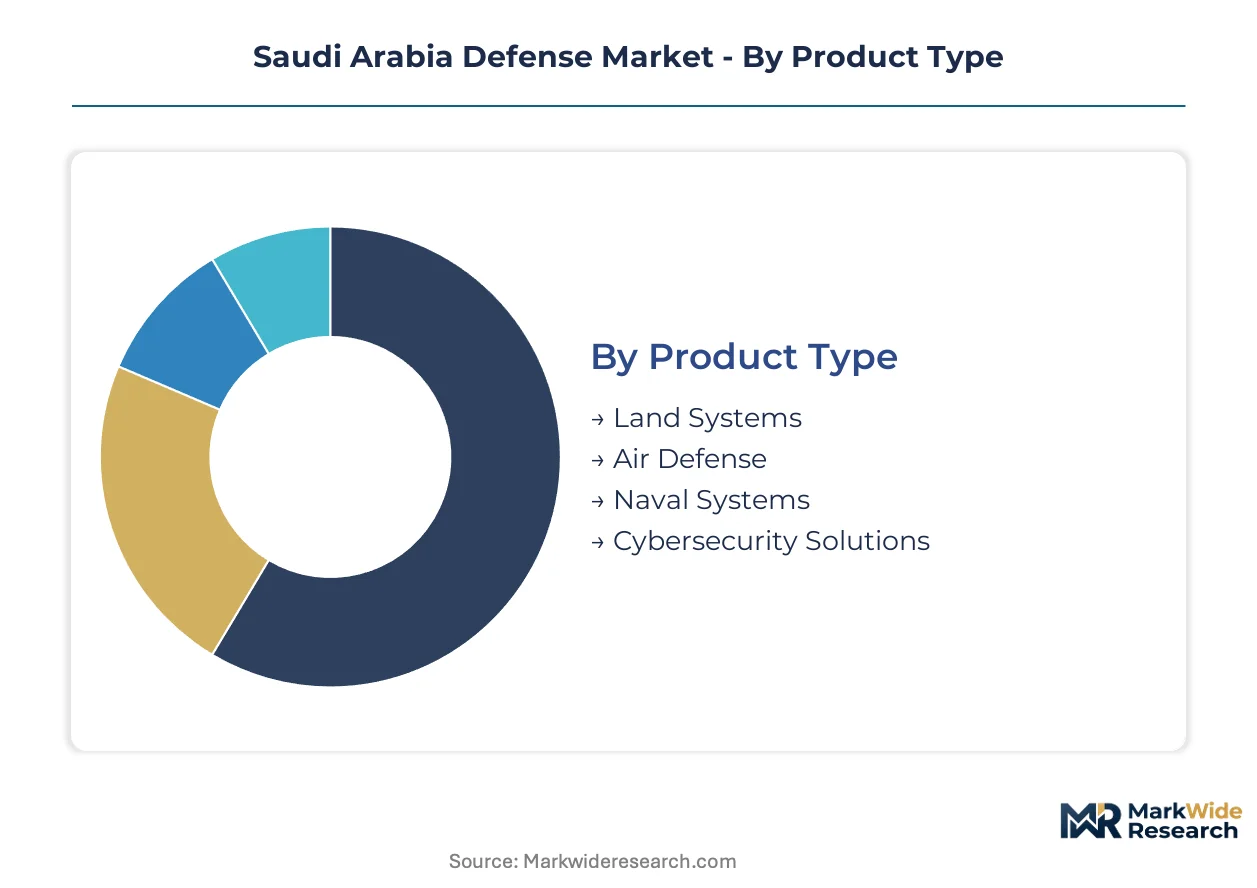
Segmentation in the Saudi defense market reveals how Vision 2030 localization mandates and threat-specific procurement priorities reshape supplier strategies. Each dimension exposes different pressure points for technology transfer compliance, sovereign capability development, and long-term sustainment economics.
Product Type:
Upgrade cycles vary dramatically by domain, with air and missile systems demanding faster refresh rates than naval platforms due to evolving threat signatures.
- Air Defense:Layered radar networks and interceptor batteries designed for ballistic missile threats from Yemen and Iran. Procurement concentrates in Riyadh's defense cluster and the King Salman Military Industries City near Taif, driven by GAMI certification requirements for local component integration.
- Land Systems:Armored vehicles, artillery platforms, and tactical mobility solutions hardened for desert thermal conditions exceeding 50°C. Demand centers on the Royal Saudi Land Forces modernization program, constrained by domestic precision machining capacity gaps that extend delivery schedules.
- Naval Systems:Frigate and patrol vessel platforms for Red Sea and Gulf maritime security.
- Cybersecurity Solutions:Critical infrastructure protection architectures for energy and military networks.
Volume placements concentrate in Air Defense; the faster expansion belongs to Cybersecurity Solutions.
End User:
Customer type determines contract structure, with armed forces driving platform procurement and security forces expanding service-based spending.
- Armed Forces:The Royal Saudi Air Force and Land Forces dominate capital expenditure on fighter aircraft, missile systems, and armored vehicles. Procurement flows through centralized command structures with strict GAMI local content enforcement.
- Defense Contractors:SAMI and joint venture partners absorb technology transfer obligations and in-country manufacturing commitments. Revenue stability depends on 15-20 year performance-based logistics agreements rather than transactional sales.
- Government Agencies:Border guard and interior ministry units procuring surveillance and internal security platforms.
- Security Forces:Critical infrastructure protection units requiring cyber-physical security integration.
Contract value concentrates with Armed Forces; the steepest expansion trajectory belongs to Defense Contractors as localization mandates deepen.
Technology:
Technology tier shapes intellectual property exposure, with AI and automation systems facing the steepest GAMI disclosure requirements.
- AI & Automation:Autonomous targeting, predictive maintenance algorithms, and command-and-control optimization tools. Development partnerships concentrate in Riyadh's technology corridor, constrained by foreign supplier hesitation over sovereign data architecture requirements.
- Advanced Weapon Systems:Precision-guided munitions, directed energy research, and hypersonic defense components. Demand anchors on Royal Saudi Air Force F-15 and Eurofighter Typhoon fleet modernization, with modular open systems architecture compliance now mandatory.
- Surveillance Technology:Satellite reconnaissance, signals intelligence, and persistent aerial platforms.
- Communication Systems:Secure tactical networks and satellite link infrastructure.
Platform integration concentrates in Advanced Weapon Systems; the fastest technology transfer friction sits with AI & Automation.
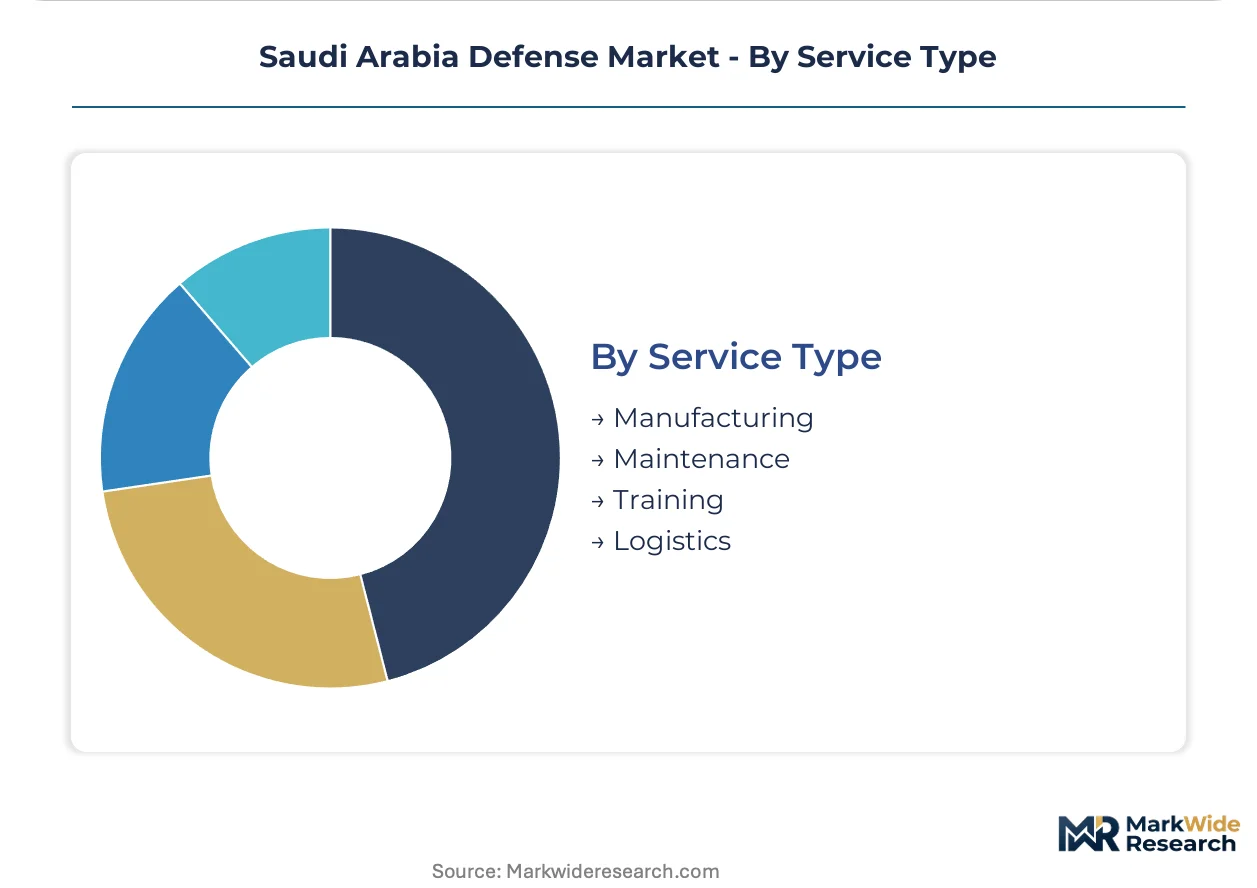
Service Type:
Service margins exceed hardware sales, with maintenance and training generating recurring revenue streams that offset platform procurement cyclicality.
- Maintenance:Depot-level repair, certified spare parts pipelines, and fleet availability guarantees for imported fighter and missile systems. Revenue concentrates with OEM sustainment footprints like Lockheed Martin's F-15 infrastructure and BAE Systems' Eurofighter support networks.
- Training:Pilot conversion courses, technician certification programs, and simulator-based instruction. Demand clusters at King Salman Air Base and in-country training academies, driven by workforce localization targets under Vision 2030.
- Manufacturing:Domestic assembly of ammunition, armored components, and aerospace subsystems.
- Logistics:Integrated supply chain management and theater distribution networks.
Revenue stability concentrates in Maintenance; the fastest margin expansion belongs to Training as workforce substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes the bulk of regional defense output while domestic production capacity lags behind operational requirements. The Kingdom imports advanced platforms from US and European suppliers, then localizes assembly through GAMI-certified joint ventures. This production-consumption gap drives technology transfer negotiations and shapes procurement timelines.
Riyadh
The capital anchors Saudi Arabia's defense industrial cluster through SAMI headquarters and the King Abdullah City for Atomic and Renewable Energy. GAMI enforces local content quotas that compel foreign OEMs to establish engineering centers here. The Riyadh cluster concentrates on aerospace component manufacturing and systems integration for fighter sustainment.
Eastern Province
Critical infrastructure protection demands dominate this region, with Aramco facilities and Gulf coastline driving cybersecurity and maritime security procurement. SFDA oversees occupational health compliance at defense manufacturing sites in Dammam and Jubail. The King Fahd Industrial Port enables heavy equipment import for armored vehicle assembly partnerships.
Taif
The King Salman Military Industries City offers greenfield infrastructure for ammunition production and aerospace manufacturing with dedicated logistics corridors. Vision 2030 localization mandates prioritize this cluster for land systems and missile component fabrication. Foreign suppliers partner here to satisfy GAMI certification requirements for domestic assembly quotas.
Western Region
Red Sea maritime security and proximity to Yemen shape procurement priorities for naval patrol vessels and coastal radar networks. Jeddah hosts maintenance facilities for imported fighter fleets and technician training academies. The region absorbs sustainment contracts that Lockheed Martin and BAE Systems structure around lifetime availability guarantees.
Saudi Arabia Defense Market Competitive Environment
Capital-heavy platform producers compete with asset-light systems integrators for contract eligibility under GAMI's localization framework. The vendor base concentrates around US and European OEMs with established sustainment footprints, while Saudi entities absorb technology transfer through joint venture structures. Two strategic archetypes dominate: full-service OEMs bundling platforms with long-term logistics, and specialized subsystem suppliers capturing niche certification requirements. Competitive positioning hinges on GAMI partnership credentials and performance-based logistics contract structures.
Among US-based defense conglomerates, RTX Corporation, Northrop Grumman Corporation, and Lockheed Martin Corporation exemplify the full-service archetype through fighter aircraft and missile system franchises. These entities anchor technology transfer negotiations with Saudi counterparts. European competitors including BAE Systems and Leonardo S.p.A. occupy parallel positions through Eurofighter and rotorcraft platforms. Saudi Arabian Military Industries represents the domestic consolidation play, absorbing joint venture equity and localization mandates across air and land domains.
| Leading Market Players |
|---|
| RTX Corporation |
| Northrop Grumman Corporation |
| Saudi Arabian Military Industries (SAMI) |
| Leonardo S.p.A. |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| BAE Systems |
| L3Harris Technologies |
| The Boeing Company |
| Others |
Value Chain & Pricing Dynamics
Captive supply chain development for thermal management components and certified spare parts pipelines anchors both procurement economics and supplier pricing power in Saudi defense contracting. Foreign OEMs with established F-15 and Eurofighter sustainment footprints command premium positioning through integrated logistics bundles, while GAMI-mandated local content quotas compress margins for non-compliant vendors.
Pricing Analysis
Margin tightening in platform procurement reflects GAMI's enforcement of technology transfer milestones as contract eligibility conditions. Pricing stratifies across performance-based logistics agreements, transactional spare parts procurement, and bundled training-manufacturing packages, with certification grade and after-sales service depth as primary differentiation drivers. Cost-down pressure on imported fighter systems accelerates as SAMI joint ventures capture assembly work. Armed Forces buyers exhibit lowest price sensitivity due to threat urgency; defense contractors face highest sensitivity given localization investment requirements.
Supply Chain Analysis
Dual-sourcing requirements for ballistic missile defense components mandate US and European supplier qualification, creating qualified vendor pools concentrated in Lockheed Martin's Arizona production lines and BAE Systems' UK manufacturing centers. The supply chain draws from precision-machined components in Germany, radar subsystems in the United States, and propulsion elements in the United Kingdom. Single-source vulnerability dominates certified avionics pipelines. Distribution runs through King Fahd Industrial Port and Riyadh's defense cluster with SFDA-compliant logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GAMI certification operates as a cost-of-compliance moat, with intellectual property disclosure requirements filtering out suppliers unwilling to absorb technology transfer obligations. Only entities with sovereign partnership structures and in-country manufacturing commitments secure contract eligibility.
For Market Incumbents: To counter SAMI's absorption of joint venture equity and localization mandates, Lockheed Martin and BAE Systems should deepen captive supply of F-15 and Eurofighter depot-level maintenance through 15-20 year performance-based logistics extensions. Certification investment in King Salman Military Industries City infrastructure represents the critical defensive lever against domestic competitor capture.
For New Entrants and Emerging Players: Modular open systems architecture compliance offers a technology-first wedge for subsystem suppliers seeking platform integration roles without full OEM scale. Cyber-physical security convergence presents the most penetrable white-space, with critical infrastructure protection units at Aramco facilities demanding sovereign cybersecurity architectures. Go-to-market positioning should anchor on GAMI partnership credentialing through Riyadh engineering center establishment.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by SAMI or full-service OEMs seeking GAMI-compliant manufacturing capacity. Long-term viability hinges on 5-10 year sustainment contract backlogs rather than transactional platform sales. The signal to watch is GAMI's tightening of local content enforcement thresholds for air and missile defense platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| GAMI Certification Investment | Establishes contract eligibility through local content quota compliance and technology transfer milestones. |
| Performance-Based Logistics Agreement | Locks in 15-20 year recurring revenue with Royal Saudi Air Force fleet availability guarantees. |
| King Salman Military Industries City Partnership | Captures greenfield infrastructure access for ammunition and aerospace component manufacturing. |
| Modular Open Systems Architecture Compliance | Enables rapid capability upgrades without vendor lock-in across F-15 and Eurofighter platforms. |
| Cyber-Physical Security Integration | Addresses fastest-expanding budget line for critical infrastructure protection at Aramco and military networks. |
Study Parameters
Defense industry databases, GAMI regulatory filings, and customs import records formed the secondary backbone, supplemented by primary interviews with Royal Saudi Air Force procurement officers, SAMI joint venture executives, SFDA compliance leads, and Lockheed Martin sustainment directors. Bottom-up and top-down triangulation validated platform delivery schedules, localization quota achievement rates, and sustainment contract values across the analysis window.
Bottom-up modeling aggregated segment-level procurement flows by product type, end user, and technology tier, while top-down verification cross-checked against consolidated defense budget allocations. Segmentation dimensions included air defense versus land systems, armed forces versus defense contractor spend, and AI-enabled versus conventional platforms. CAGRs derived from historical delivery trajectories and announced modernization program timelines, with thermal management specifications and desert-hardening requirements as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including classified threat environment developments, bilateral defense agreement renegotiations, and workforce localization achievement rates. Deviation in GAMI enforcement intensity or ballistic missile incident frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Europe Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market