
 Asia-Pacific Small Satellite Market | 2026-2036
Asia-Pacific Small Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
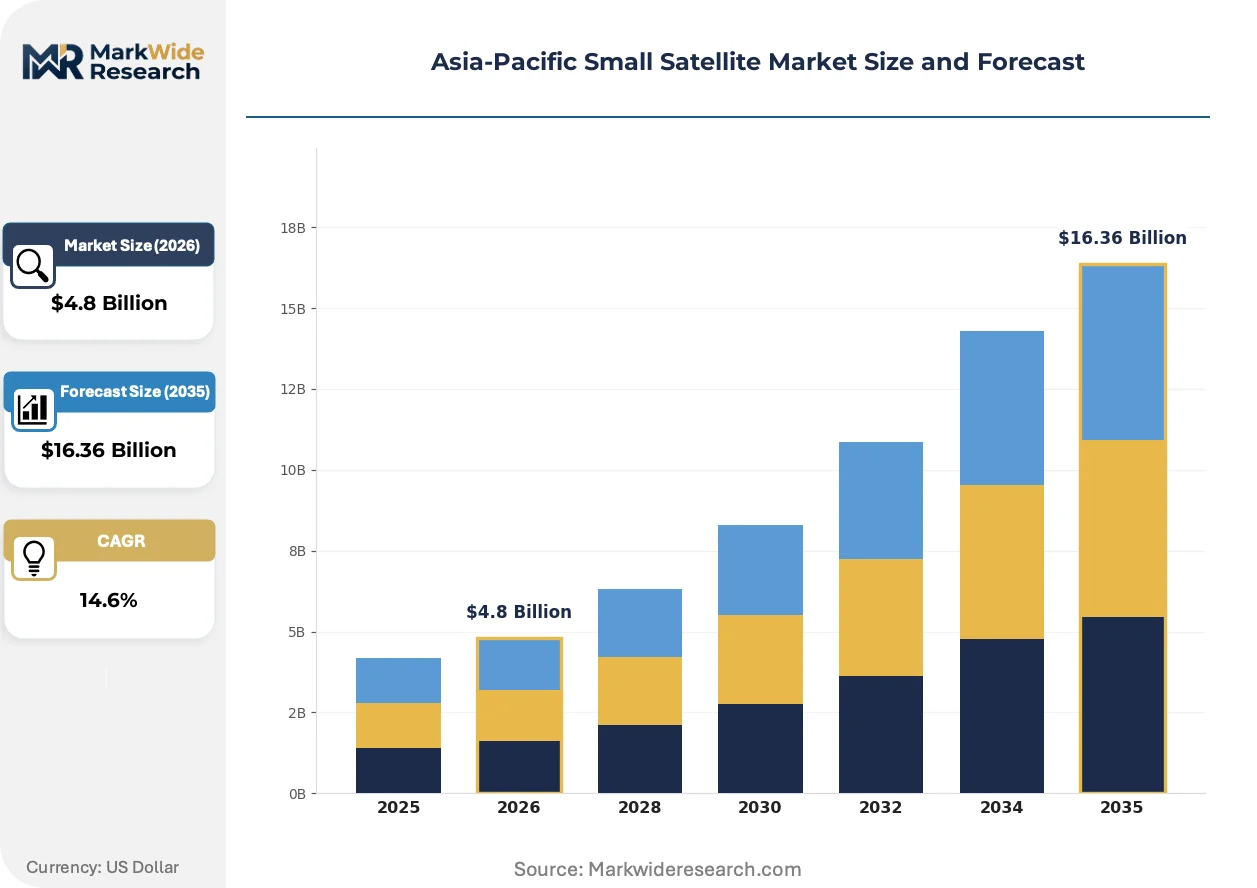
Asia-Pacific Small Satellite Market Outlook
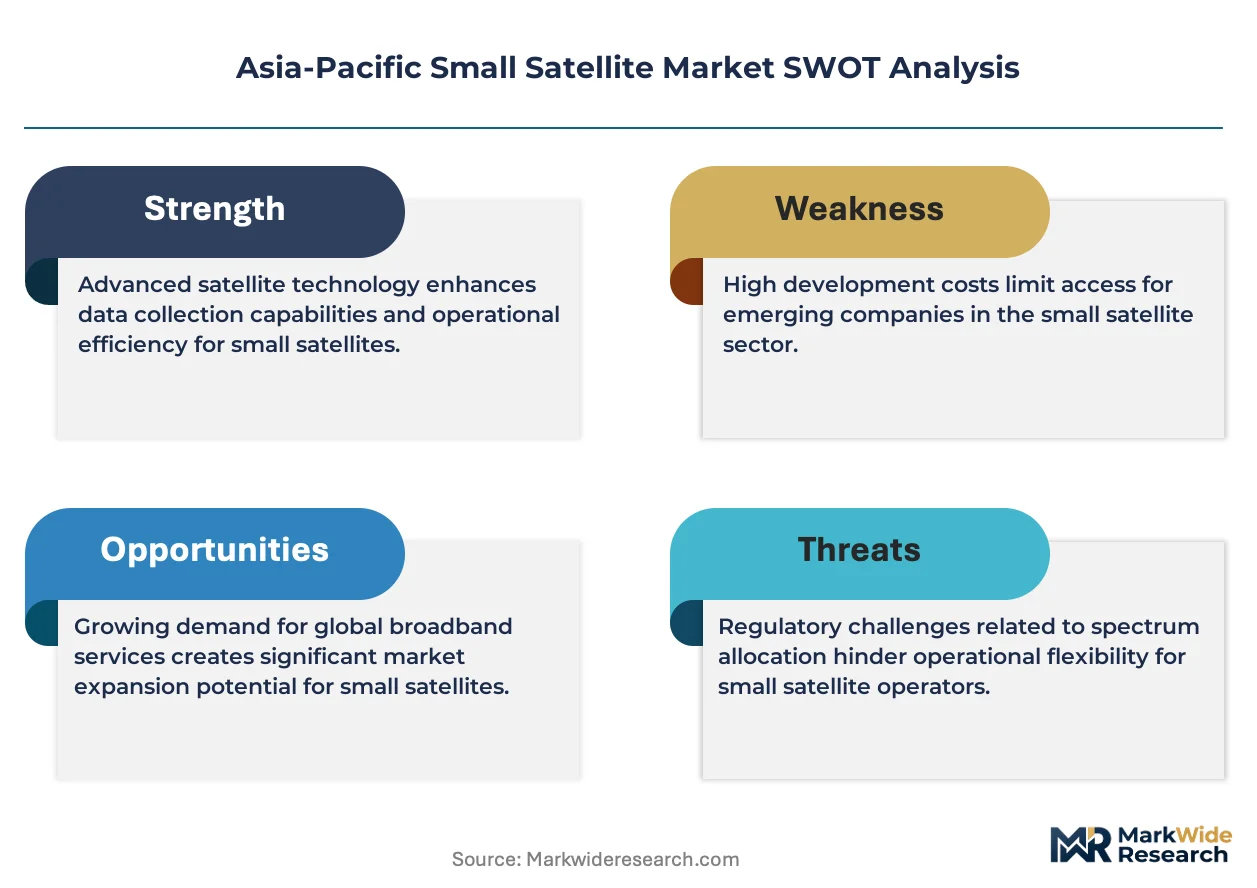
Defense procurement concentration across Southeast Asian militaries is pivoting toward sovereign small satellite constellations for maritime domain awareness. China Aerospace Science and Technology Corporation anchors its position through captive launch access and state-backed constellation deployment. Spacety Aerospace Co. competes on rapid manufacturing cycles for commercial remote sensing payloads. NEC Corporation differentiates through integrated ground-segment software tied to its satellite platforms.
Asia-Pacific small satellites are spacecraft with wet mass below 500 kilograms, typically employing standardized CubeSat form factors with aluminum alloy frames and photovoltaic power generation for low-Earth orbit operations. These systems enable cost-effective Earth imaging, communications relay, and technology validation for public and private operators. Nanosatellite platforms lead volume production due to rideshare launch economics and shortened development timelines. Earth Observation applications capture sustained investment as agricultural insurers and disaster response agencies demand higher revisit frequencies. Military end users represent the fastest-expanding customer pool as regional navies seek sovereign space-based surveillance.
Japan's METI sets domestic manufacturing standards for commercial satellite components, while India's ISRO governs launch authorization and frequency coordination through its national space act. Australia's Space Activities Amendment regulations shape liability frameworks for commercial operators deploying from Woomera. Stakeholders must track evolving spectrum allocation rulings and debris mitigation mandates as national space legislatures across the region draft licensing requirements for private constellation operators.
Market Dynamics
Sovereign constellation programs across Southeast Asian navies are compressing procurement cycles and forcing manufacturers to reconfigure supply chains for classified payload integration. This defense-driven demand concentration is restructuring vendor qualification requirements and accelerating domestic manufacturing mandates.
Growth Catalysts
- India's PLI scheme for space manufacturing:Domestic component vendors gain accelerated qualification pathways, reducing import dependency for satellite subsystems. ISRO's vendor certification timelines compress from 18 months to 9 months for qualified applicants.
- Maritime domain awareness requirements:Regional navies in Indonesia, Vietnam, and the Philippines deploy dedicated reconnaissance constellations for exclusive economic zone monitoring. Sovereign satellite ownership displaces commercial imagery purchasing.
- Standardized CubeSat form factors:Rideshare launch economics enable universities and research institutes to access orbital deployment at sub-million-dollar price points. Nanosatellite production volumes scale through aluminum alloy frame standardization.
Market Restraints
- Launch capacity concentration:China's state-backed launch providers control 60% of regional orbital access, creating supply vulnerability for non-Chinese constellation operators. Alternative launch infrastructure remains underdeveloped in Southeast Asia.
- Frequency coordination bottlenecks:ITU filing backlogs and national spectrum allocation disputes delay commercial authorization. India's TRAI and Australia's ACMA maintain incompatible domestic licensing frameworks.
- Photovoltaic cell supply volatility:Triple-junction solar cell production concentrates in US and European defense contractors, exposing Asia-Pacific manufacturers to export control disruptions and 12-18 month order backlogs.
Strategic Opportunities
- Vietnam's emerging space program:The country's first domestically manufactured satellite launches in 2024, creating demand for ground segment software, tracking stations, and domestic component sourcing partnerships.
- Disaster response agency procurement:Pacific island nations aggregate satellite imagery purchasing through regional consortiums, opening subscription-based Earth observation service models with guaranteed revisit commitments.
- Agricultural insurance technology convergence:Synthetic aperture radar and multispectral imaging fusion enables all-weather crop monitoring. Indian and Australian insurers pilot parametric payout systems triggered by satellite-derived yield estimates.
Industry Challenges
- Radiation-hardened electronics talent scarcity:Asia-Pacific universities produce insufficient qualified engineers for space-grade component design. Recruitment competition intensifies with semiconductor and automotive sectors.
- Debris mitigation compliance complexity:Japan's METI and Australia's Space Agency impose divergent post-mission disposal requirements. Constellation operators face conflicting 25-year versus 5-year deorbit mandates across jurisdictions.
- Classified payload integration certification:Defense agencies demand facility security clearances that commercial manufacturers lack. Dual-use technology export controls fragment supply chain coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small Satellite Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanosatellite, Microsatellite, Minisatellite, Femtosatellite Application: Earth Observation, Communication, Scientific Research, Technology Demonstration End User: Government, Commercial, Educational, Military Launch Vehicle: Polar Satellite Launch Vehicle, Falcon 9, Electron, Soyuz |
| Companies Covered | Spacety Aerospace Co., NEC Corporation, China Aerospace Science and Technology Corporation (CASC), MinoSpace Technology, Guodian Gaoke, Axelspace Corporation, Mitsubishi Electric Corporation, Pixxel, Chang Guang Satellite Technology Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small Satellite Market Strategic Shifts
Artificial intelligence inference at the edge is compressing data transmission requirements and enabling real-time decision-making from orbital platforms. This capability shift is restructuring ground segment economics and opening new service categories for time-sensitive applications.
On-board machine learning processors are automating target detection and change recognition directly on satellite payloads. Agricultural insurers in Australia and Japan deploy these systems to flag crop stress within hours of image capture, eliminating ground station processing delays. The technology is automating the entire value chain from raw imagery to actionable alerts, collapsing traditional 24-48 hour delivery windows.
Japan's METI revised domestic manufacturing standards for commercial satellite components in 2023, mandating traceability documentation for aluminum alloy sourcing and photovoltaic cell efficiency testing. The regulation forces component suppliers to reconfigure quality management systems. Commercial Earth observation operators in Japan absorb compliance costs through premium pricing for government-certified imagery products.
Defense procurement agencies across Southeast Asia consolidate satellite imagery purchasing through national security frameworks, displacing fragmented agency-level contracting. Indonesia's defense ministry centralizes all maritime surveillance satellite tasking through a single command structure. This concentration accelerates procurement decisions but reduces commercial operator access to defense-adjacent revenue streams.
Asia-Pacific Small Satellite Market Segmentation
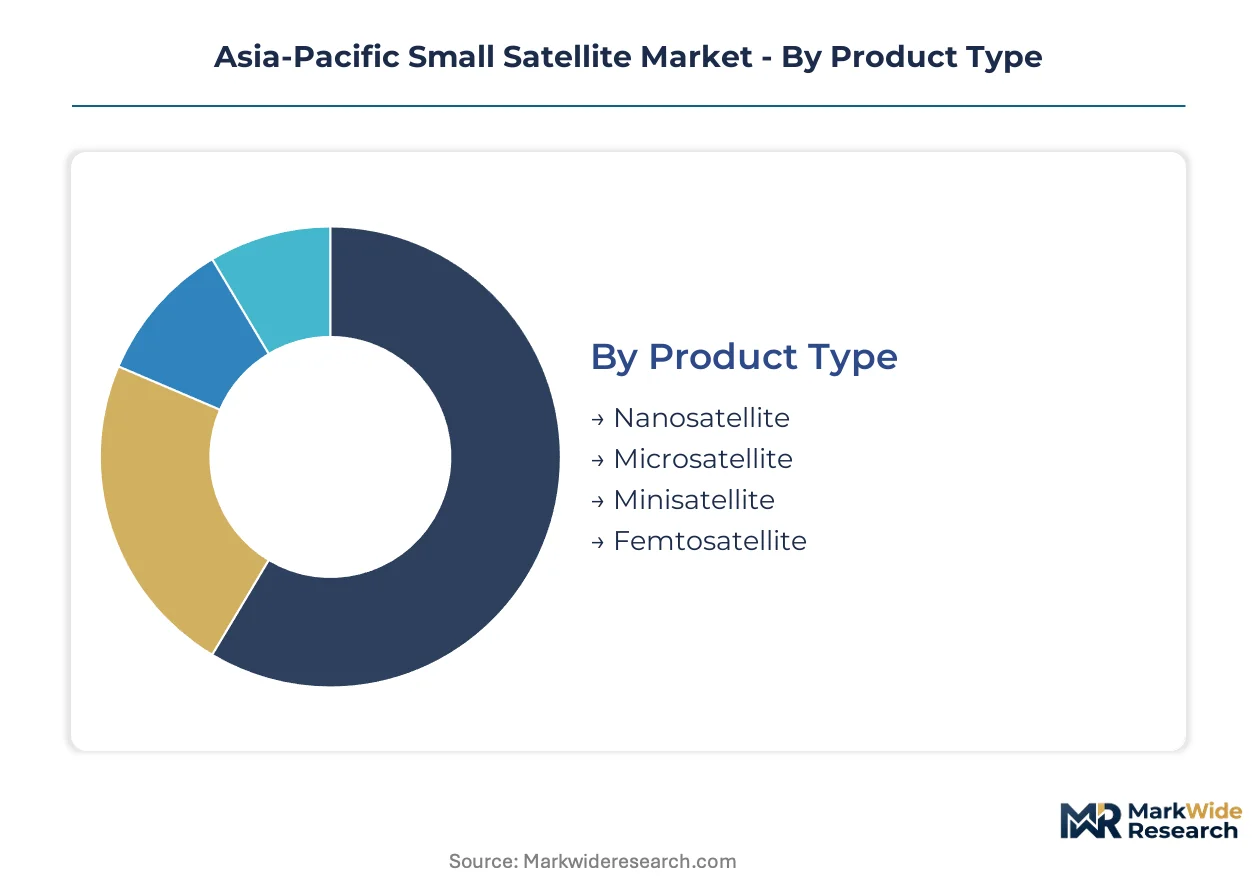
Segmentation in the Asia-Pacific small satellite market reveals how procurement priorities diverge across defense, commercial, and institutional buyers. Each dimension—mass classification, orbital purpose, customer identity, and launch access—shapes vendor qualification requirements and pricing structures differently.
Product Type:
Mass classification determines development timelines, rideshare eligibility, and per-unit economics for constellation operators.
- Nanosatellite:CubeSat-standard platforms with wet mass below 10 kilograms deploy through aggregated rideshare missions. Universities across Japan and Australia access orbital deployment at sub-million-dollar price points through standardized aluminum alloy frames and commercial off-the-shelf components.
- Microsatellite:Spacecraft ranging 10-100 kilograms balance payload capacity with launch flexibility. Commercial Earth observation operators in India deploy these platforms for agricultural monitoring constellations, capitalizing on ISRO's Polar Satellite Launch Vehicle rideshare economics.
- Minisatellite:100-500 kilogram platforms accommodate synthetic aperture radar and multispectral imaging payloads. Defense agencies in Indonesia and Vietnam specify these for sovereign maritime surveillance constellations.
- Femtosatellite:Sub-100 gram platforms serve technology validation and educational missions. Research institutes in South Korea deploy these for rapid orbital prototyping.
Nanosatellites lead on scale; microsatellites lead on momentum.
Application:
Orbital purpose dictates payload specifications, revisit frequency requirements, and data processing architectures.
- Earth Observation:Multispectral, hyperspectral, and synthetic aperture radar payloads capture surface imagery for agricultural insurers and disaster response agencies. Australian and Japanese operators fuse these sensors for all-weather crop monitoring and parametric insurance payouts.
- Communication:Narrowband and broadband relay payloads serve maritime, aviation, and remote terrestrial connectivity. Pacific island nations aggregate demand through regional consortiums for guaranteed service coverage.
- Scientific Research:Atmospheric sensing, space weather monitoring, and astronomy payloads support institutional missions. India's ISRO and Japan's JAXA fund university-led science missions through standardized CubeSat deployment programs.
- Technology Demonstration:On-orbit validation of novel components, propulsion systems, and software architectures. Commercial manufacturers in China and India use these missions to accelerate qualification for operational constellations.
Earth observation commands current investment; communication applications are climbing the fastest.
End User:
Customer identity shapes security requirements, procurement channels, and pricing tolerance.
- Government:Civilian agencies deploy satellites for meteorology, cartography, and environmental monitoring. India's Ministry of Earth Sciences and Japan's JAXA operate dedicated constellations with sovereign ground segment control.
- Commercial:Private operators sell imagery, communications, and data analytics services. Agricultural insurers and commodity traders in Australia purchase subscription-based Earth observation products with guaranteed revisit commitments.
- Educational:Universities and research institutes access space for workforce development and technology validation. Japan's Kyushu Institute of Technology and India's IIT Bombay operate prolific CubeSat programs.
- Military:Defense agencies procure classified reconnaissance and secure communications capabilities. Southeast Asian navies in Indonesia, Vietnam, and the Philippines deploy sovereign constellations for exclusive economic zone surveillance.
Commercial users dominate volume; military end users are gaining share fastest.
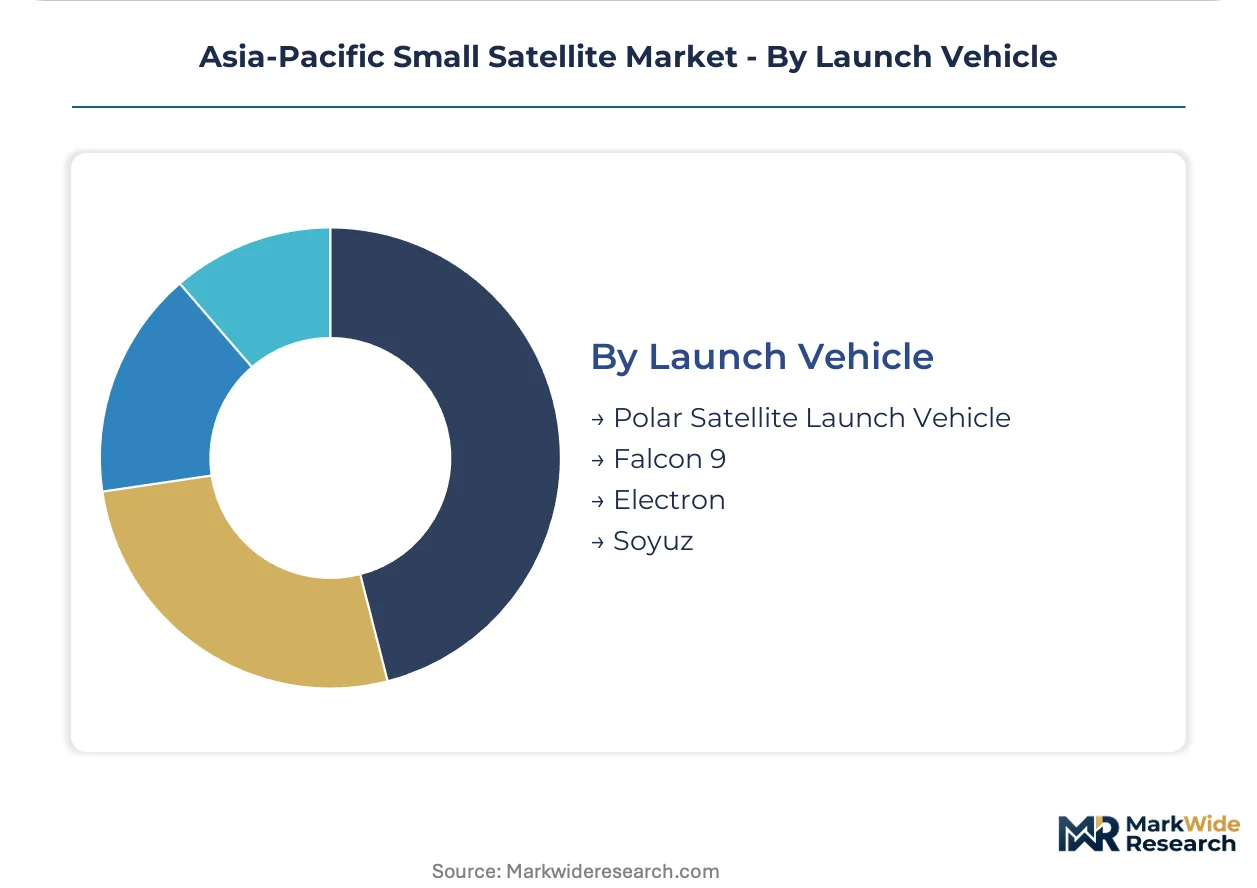
Launch Vehicle:
Orbital access economics and scheduling reliability constrain constellation deployment timelines.
- Polar Satellite Launch Vehicle:ISRO's workhorse launcher offers cost-effective rideshare deployment to sun-synchronous orbit. Indian and Southeast Asian operators prioritize this vehicle for Earth observation constellations.
- Falcon 9:SpaceX's reusable platform provides high-cadence launch capacity and competitive pricing. Commercial operators across the Asia-Pacific contract dedicated rideshare missions through this vehicle.
- Electron:Rocket Lab's small-lift vehicle enables dedicated orbital insertion for single-satellite or small-constellation missions. Precision deployment suits technology demonstration payloads requiring specific orbital planes.
- Soyuz:Russian-derived launch capacity serves operators with established procurement relationships and compatible payload interfaces.
Polar Satellite Launch Vehicle anchors regional access; Falcon 9 shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's ISRO trains approximately 500 aerospace engineers annually through its academic partnerships, creating a talent pipeline that feeds domestic satellite manufacturing clusters. Japan's Kyushu Institute of Technology operates one of Asia's most prolific CubeSat programs, graduating specialized spacecraft designers into commercial and defense sectors.
China
China Aerospace Science and Technology Corporation anchors regional launch capacity through captive Long March vehicle production and state-backed constellation deployment. The country's MIIT governs satellite manufacturing standards and spectrum allocation for commercial operators. Changchun's optical valley cluster concentrates precision imaging payload development for remote sensing platforms.
Japan
Commercial Earth observation services drive demand as agricultural insurers and disaster response agencies seek higher revisit frequencies. METI revised domestic manufacturing standards in 2023, mandating traceability documentation for aluminum alloy sourcing and photovoltaic testing. Tokyo's Kanto region hosts integrated ground-segment software development tied to satellite platform manufacturing.
India
ISRO's PLI scheme accelerates domestic vendor qualification, compressing certification timelines from 18 months to 9 months for qualified applicants. The Department of Space governs launch authorization and frequency coordination through India's national space act. Bengaluru's aerospace corridor concentrates satellite subsystem manufacturing and ground station operations.
Australia
Pacific island nations aggregate satellite imagery purchasing through regional consortiums, opening subscription-based Earth observation service models. The Space Activities Amendment regulations shape liability frameworks for commercial operators deploying from Woomera. South Australia's Adelaide hosts emerging small satellite manufacturing facilities serving defense and civil applications.
Vietnam
The country's first domestically manufactured satellite launched in 2024, creating demand for ground segment software and domestic component sourcing partnerships. The Vietnam National Space Center coordinates frequency coordination with regional regulators. Ho Chi Minh City's technology parks attract foreign satellite component suppliers establishing local qualification partnerships.
Asia-Pacific Small Satellite Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific small satellite value chain. State-backed aerospace groups anchor launch and large-platform manufacturing, while venture-funded startups compress development cycles for commercial remote sensing payloads. Two strategic archetypes dominate: integrated defense contractors with captive government demand, and agile commercial operators selling imagery-as-a-service. Competitive intensity concentrates on manufacturing cycle compression and ground-segment software integration.
Within the state-backed tier, China Aerospace Science and Technology Corporation exemplifies vertical integration from launch vehicles to constellation operations. Spacety Aerospace Co. and NEC Corporation represent contrasting commercial archetypes—rapid manufacturing specialists versus integrated platform-software providers. These three anchors illustrate how geographic proximity to launch infrastructure and regulatory familiarity shape competitive positioning across the region.
| Leading Market Players |
|---|
| Spacety Aerospace Co. |
| NEC Corporation |
| China Aerospace Science and Technology Corporation (CASC) |
| MinoSpace Technology |
| Guodian Gaoke |
| Axelspace Corporation |
| Mitsubishi Electric Corporation |
| Pixxel |
| Chang Guang Satellite Technology Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Radiation-hardened electronics talent scarcity in Bengaluru and Tokyo creates labor-cost differentials that widen pricing-tier spreads between premium defense-grade platforms and commercial off-the-shelf alternatives. India's PLI scheme compresses vendor certification timelines, enabling domestic manufacturers to undercut imported subsystems by 15-20% while METI's traceability mandates in Japan force premium pricing for certified components.
Pricing Analysis
Bundled ground-segment software and launch services dominate pricing structures, though unbundled component-only transactions persist for university and research institute buyers. Three-tier pricing structure across premium, standard, and economy levels separates defense agencies with sovereign payload requirements from agricultural insurers demanding subscription-based revisit guarantees. Pricing pressure stems from rideshare launch economics compressing deployment costs below one million dollars for nanosatellite platforms. Commercial Earth observation operators exhibit highest price sensitivity, while defense procurement agencies absorb premiums for classified payload integration and security-cleared manufacturing facilities.
Supply Chain Analysis
India's domestic-content mandates under the PLI scheme and Japan's METI traceability requirements are reshaping sourcing patterns for aluminum alloy frames and photovoltaic cells. Triple-junction solar cell production concentrates in US and European defense contractors, while precision imaging payload development clusters in Changchun and Bengaluru. Supply chain risk centers on export control disruptions for radiation-hardened electronics and 12-18 month order backlogs for space-grade components. Distribution runs through ISRO's vendor certification network for Indian operators and METI-registered suppliers for Japanese commercial missions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific small satellite market functions as a stable compounder, with sovereign constellation programs across Southeast Asian navies providing durable demand visibility that smooths cyclicality in commercial Earth observation services.
For Market Incumbents: To counter launch capacity concentration in Chinese state-backed providers, incumbent manufacturers should secure alternative access through Rocket Lab's Electron and ISRO's PSLV while deepening backward integration into aluminum alloy frame production and ground-segment software development to capture margin from vertically integrated competitors.
For New Entrants and Emerging Players: Launch via subscription-based Earth observation service models targeting Pacific island nations and agricultural insurers in Australia, where parametric payout systems create demand for guaranteed revisit frequencies. Vietnam's emerging space program offers the most penetrable geography, with ground segment software and tracking station partnerships representing immediate white-space opportunities.
For Investors and Strategic Acquirers: Defense contractors with captive government demand are the most active acquirer in this space, seeking manufacturing specialists with facility security clearances and rapid-cycle payload integration capabilities. Target acquisition archetypes include pure-play nanosatellite manufacturers with ISRO vendor certification and integrated platform-software providers serving Japanese commercial Earth observation operators. Monitor ITU filing backlogs and national spectrum allocation disputes as the primary signal for regulatory-driven consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Vendor Qualification Acceleration | India's PLI scheme compresses ISRO certification timelines from 18 months to 9 months for qualified applicants. |
| Integrated Ground-Segment Software Development | NEC Corporation's platform-software bundling captures recurring revenue from JAXA and commercial Earth observation operators. |
| Sovereign Constellation Deployment | Indonesia's defense ministry centralizes maritime surveillance satellite tasking through single command structures. |
| Edge AI Inference Capability Integration | On-board machine learning processors collapse 24-48 hour imagery delivery windows to hours for agricultural insurers. |
| Alternative Launch Infrastructure Access | Rocket Lab's Electron enables dedicated orbital insertion for technology demonstration payloads requiring specific planes. |
Study Parameters
Coverage spans China, Japan, India, Australia, and Vietnam, with primary inputs from each national space agency and commercial operator cluster. The research combines primary interviews with satellite manufacturing executives, ISRO vendor certification officers, defense procurement leads at Southeast Asian navies, and commercial Earth observation service directors with secondary validation from ISRO annual reports, METI manufacturing standard filings, JAXA mission databases, and ITU spectrum allocation records. Bottom-up unit economics for rideshare launch deployment and top-down sovereign constellation budget allocations were triangulated to establish market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from unit price evolution for each mass classification tier. The analytical framework models segmentation across nanosatellite, microsatellite, and minisatellite platforms; Earth observation, communications, and scientific research applications; and government, commercial, educational, and military end users. CAGRs were derived from deployment pipeline visibility and procurement cycle compression trends, with specific inputs from ISRO's PSLV manifest projections and defense ministry satellite acquisition announcements across Indonesia, Vietnam, and the Philippines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control disruptions for triple-junction solar cells and ITU filing backlogs exceeding 24 months. The analysis assumes continued PLI scheme funding in India and stable METI manufacturing standard enforcement in Japan, with forecasts reflecting these boundary conditions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Global LEO Satellite Market
Satellite
Global Satellite Propulsion System Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Military Satellite Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Satellite Data Analytics Services Market
Satellite
North America Military Satellite Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
North America Mobile Satellite Services Market