
 Europe Satellite Connectivity Market | 2026-2036
Europe Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Satellite Connectivity Market Analytics
Procurement strategy is shifting from single-source government contracts toward multi-vendor frameworks across European space agencies. SES S.A. leverages its O3b mPOWER constellation to anchor medium Earth orbit services for maritime and government clients. Thales Alenia Space competes through sovereign manufacturing partnerships in France and Italy, while OHB SE specializes in small satellite platforms for institutional programs.
Europe satellite connectivity denotes the transmission of data, voice, and video signals via orbiting spacecraft operating across geostationary, medium, and low Earth orbits, utilizing Ka-band, Ku-band, and emerging laser inter-satellite links to bridge terrestrial infrastructure gaps. Data connectivity services dominate revenue generation as enterprises migrate critical operations to satellite-backed networks, while low Earth orbit deployments represent the fastest-expanding technology tier driven by latency-sensitive applications including connected vehicles and telesurgery.
The European Union Agency for the Space Programme and national regulators in France, Germany, and Italy enforce frequency coordination, orbital slot allocation, and cybersecurity certification under the EU Space Programme and IRIS² sovereign infrastructure mandate. REACH and CE marking frameworks govern ground equipment manufacturing standards, while GDPR compliance shapes data governance for satellite-enabled IoT platforms. Stakeholders must track spectrum auction outcomes and cross-border service licensing agreements as sovereign constellation deployments reshape vendor qualification criteria.
Market Dynamics
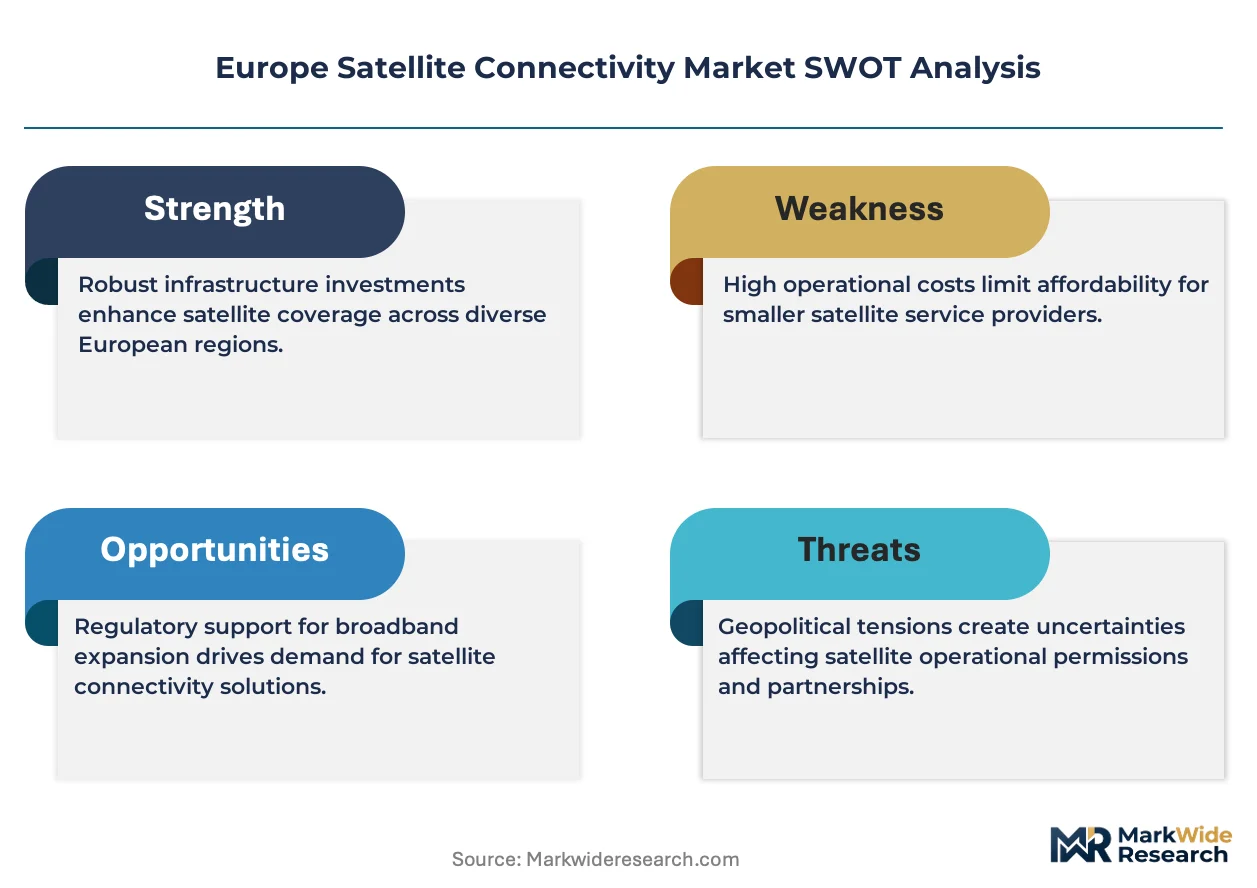
The IRIS² sovereign constellation mandate is forcing a wholesale reconfiguration of European procurement frameworks, as member states redirect institutional budgets toward multi-orbit architectures that reduce dependency on non-European infrastructure providers.
Growth Catalysts
- EU Space Programme funding:The European Union's dedicated budget lines for secure connectivity infrastructure are channeling institutional capital toward domestic constellation operators and ground segment manufacturers.
- Defense procurement acceleration:French, German, and British defense agencies are prioritizing encrypted satellite networks for tactical communications and intelligence dissemination across contested theaters.
- Laser inter-satellite links:Optical cross-connect technology is eliminating ground station bottlenecks, enabling constellation operators to deliver sub-100 millisecond latency for latency-sensitive enterprise workloads.
Market Restraints
- Launch capacity scarcity:European institutional reliance on Ariane 6 and Vega-C vehicles creates schedule risk, with commercial launch slots commanding premium pricing amid constrained pad availability.
- Spectrum coordination friction:CEPT and national regulators in France, Germany, and Italy impose extended licensing timelines for Ka-band and Q/V-band deployments, delaying commercial service activation.
- Terrestrial fiber substitution:Subsea cable investments across the Mediterranean and North Sea corridors are capturing price-sensitive enterprise traffic that satellite operators had targeted for backhaul displacement.
Strategic Opportunities
- Eastern European sovereign networks:Poland, Romania, and the Baltic states lack indigenous constellation capacity, creating first-mover positioning for infrastructure providers offering IRIS²-compatible ground segment integration.
- Maritime IoT convergence:The intersection of satellite connectivity and vessel autonomy systems is opening subscription revenue pools from shipping operators managing unmanned surface vehicle fleets.
- GDPR-compliant data sovereignty:Ground station networks located exclusively within EU jurisdiction are capturing enterprise clients in financial services and healthcare that face cross-border data transfer restrictions.
Industry Challenges
- Orbital mechanics talent scarcity:European universities produce insufficient specialists in constellation design and station-keeping algorithms, forcing operators to recruit from US and Asian aerospace programs.
- Ground station certification timelines:EASA and national aviation authorities impose multi-year approval processes for aeronautical mobile satellite terminals, compressing equipment refresh cycles.
- Interoperability complexity:Legacy geostationary infrastructure must integrate with emerging medium and low Earth orbit constellations, requiring costly gateway reconfigurations for hybrid service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Satellite Connectivity Market |
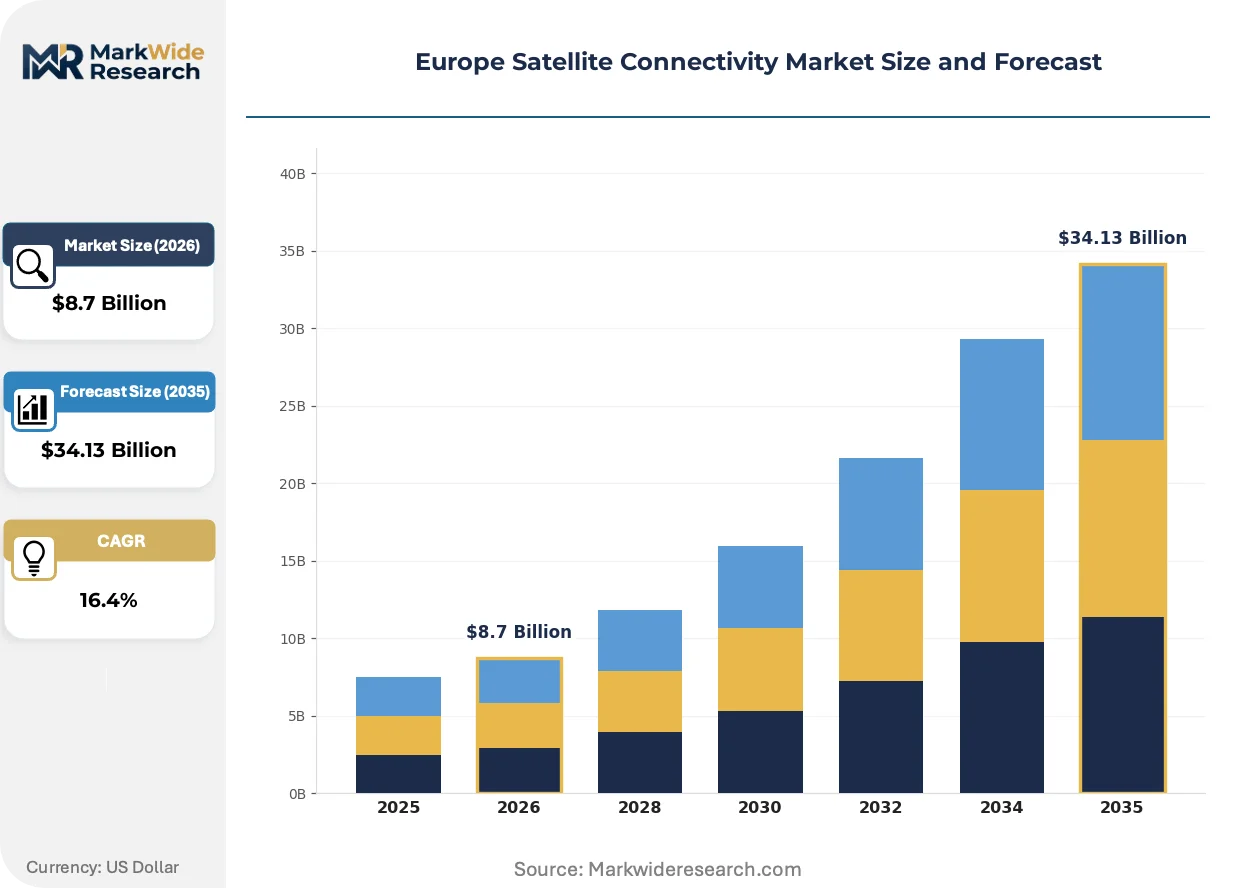
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Connectivity, Voice Services, Video Broadcasting, Remote Sensing End User: Aerospace, Maritime, Telecommunications, Government Technology: Geostationary Satellites, Low Earth Orbit, Medium Earth Orbit, High Throughput Satellites Application: Telesurgery, Disaster Management, Internet of Things, Connected Vehicles |
| Companies Covered | SES S.A., Eutelsat Communications, Inmarsat Global Limited, Intelsat S.A., Viasat Inc, Airbus Defence and Space, Thales Alenia Space, OHB SE, Hisdesat, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Satellite Connectivity Market Evolving Landscape
European satellite connectivity is undergoing architectural transformation as sovereign mandates intersect with commercial constellation deployment, reshaping how capacity is procured, regulated, and consumed across institutional and enterprise segments.
Software-defined payload technology is rewriting the economics of satellite manufacturing. Thales Alenia Space and OHB SE are integrating reprogrammable transponders that allow orbital reconfiguration without hardware replacement. Defense clients in France and Germany are specifying these architectures for multi-mission flexibility. The technology is compressing procurement cycles from decade-long satellite programs to iterative capacity upgrades.
GDPR enforcement by national data protection authorities in France, Germany, and Italy is imposing territorial processing requirements on satellite-enabled IoT platforms. Operators must deploy edge computing nodes within EU jurisdiction to avoid cross-border data transfer penalties. Healthcare and autonomous vehicle telemetry providers are selecting vendors based on ground station geography rather than price or latency metrics.
Enterprise buyers are consolidating vendor relationships around multi-orbit service contracts that bundle geostationary reliability with low Earth orbit latency. Maritime and energy sector procurement teams in Norway and the United Kingdom are rejecting single-constellation offerings, instead mandating seamless handover between orbital regimes. Channel partners are restructuring commission structures to reward solution architects who integrate terrestrial fiber failover with satellite primary links.
Europe Satellite Connectivity Market Segmentation
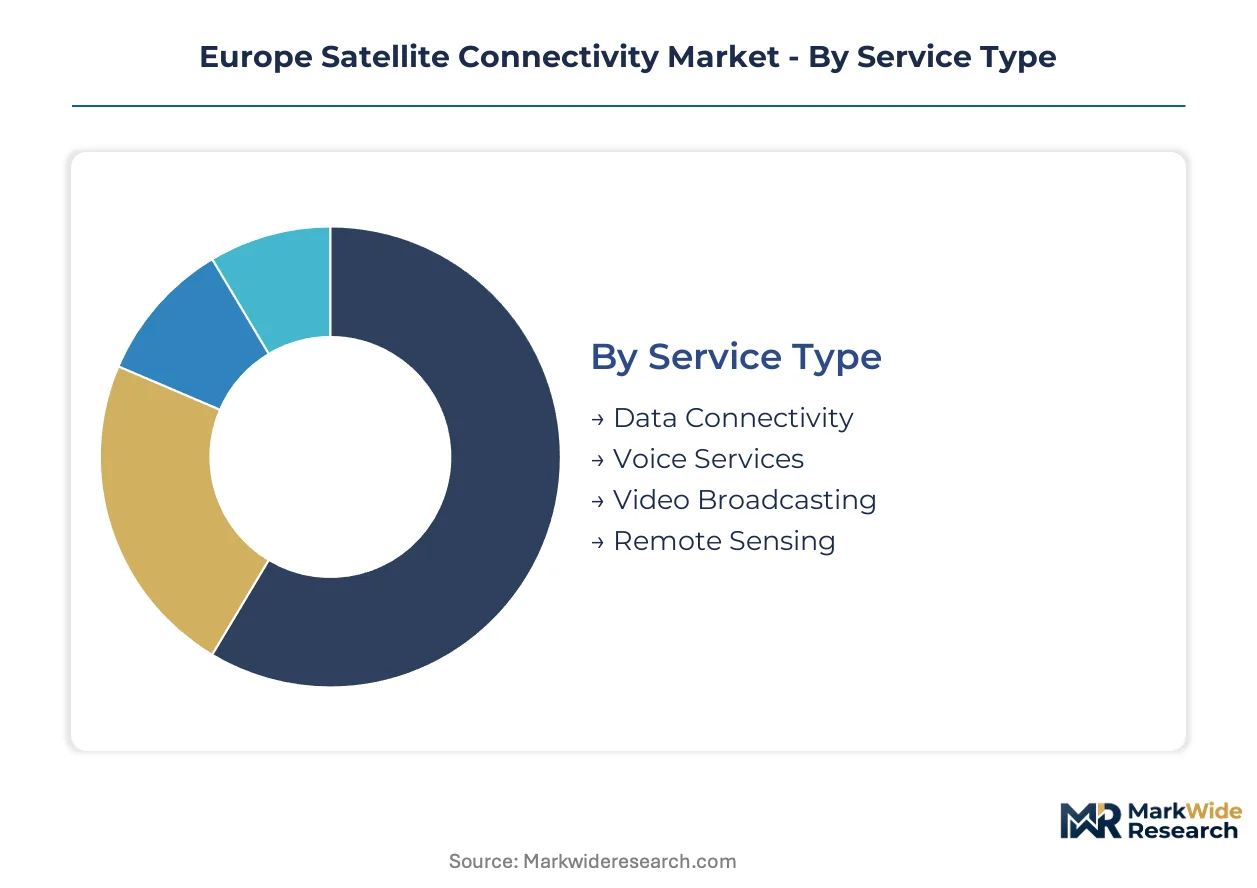
Segmentation in European satellite connectivity reveals divergent capital requirements, operational architectures, and regulatory exposure across service layers. Procurement patterns in France, Germany, and the United Kingdom concentrate spending in specific configurations while Eastern European markets remain underpenetrated.
Service Type:
Capital intensity varies sharply across service categories, with infrastructure-heavy data connectivity demanding the largest upfront constellation investment while voice services leverage legacy transponder capacity.
- Data Connectivity:High-bandwidth packet transmission via Ka-band and laser inter-satellite links supports enterprise cloud migration and maritime backhaul. French and German defense agencies are procuring encrypted data services for tactical networks under IRIS²-aligned frameworks.
- Voice Services:Circuit-switched and VoIP satellite links serve remote enterprise and aeronautical mobile applications. Demand concentrates in Eastern European territories lacking terrestrial fiber redundancy, where Polish and Romanian operators are negotiating framework agreements.
- Video Broadcasting:Direct-to-home and contribution feeds utilize geostationary capacity with established ground segment infrastructure.
- Remote Sensing:Earth observation data products require specialized payload integration and downlink architecture.
Data connectivity absorbs the bulk of installed capacity; remote sensing is expanding most quickly.
End User:
Customer archetypes shape procurement complexity, with government buyers imposing sovereign manufacturing requirements that commercial maritime operators rarely specify.
- Aerospace:In-flight connectivity and unmanned aerial vehicle command links demand low-latency LEO handoffs. British carriers are retrofitting narrow-body fleets with multi-orbit terminals as EASA certification timelines compress equipment selection windows.
- Maritime:Vessel autonomy systems and crew welfare bandwidth drive subscription revenue. Norwegian shipping operators managing unmanned surface vehicle fleets are mandating seamless terrestrial-satellite failover in North Sea and Baltic operations.
- Telecommunications:Rural backhaul and network extension services fill terrestrial coverage gaps.
- Government:Secure military and civil institutional networks require EU-manufactured payload components under GDPR and cybersecurity certification mandates.
Government end users command the highest contract values; maritime clients are climbing the fastest.
Technology:
Orbital altitude determines latency profiles, coverage economics, and ground station density requirements across competing architectures.
- Geostationary Satellites:Fixed orbital position at 35,786 kilometers enables continuous regional coverage with minimal ground infrastructure. Italian broadcasters and Mediterranean maritime operators continue procuring Ku-band and Ka-band capacity for video distribution and cruise connectivity.
- Low Earth Orbit:Constellations below 2,000 kilometers deliver sub-50 millisecond latency for connected vehicle telemetry and telesurgery applications. British autonomous vehicle trials in Oxfordshire and Milton Keynes are specifying LEO primary links with geostationary backup.
- Medium Earth Orbit:O3b and similar constellations balance latency and coverage for enterprise and government backhaul.
- High Throughput Satellites:Spot beam architecture multiplies capacity per orbital slot for concentrated demand zones.
Geostationary platforms retain the largest revenue base; low Earth orbit deployments are gaining share fastest.
Application:
Use case specificity drives terminal specification, service level agreements, and regulatory scrutiny across divergent operational contexts.
- Telesurgery:Sub-100 millisecond latency requirements with 99.999% availability mandate dedicated low Earth orbit capacity and terrestrial fiber backup. French university hospital networks in Paris and Lyon are piloting satellite-enabled remote surgical robotics under ANSM medical device oversight.
- Disaster Management:Rapidly deployable satellite terminals restore communications when terrestrial infrastructure fails. German federal civil protection agencies maintain pre-positioned ground segment assets for flood and earthquake response across Bavaria and Baden-Württemberg.
- Internet of Things:Narrowband satellite links connect agricultural sensors and utility meters in remote territories.
- Connected Vehicles:Automotive OEMs are integrating satellite modems for over-the-air updates and safety-critical messaging.
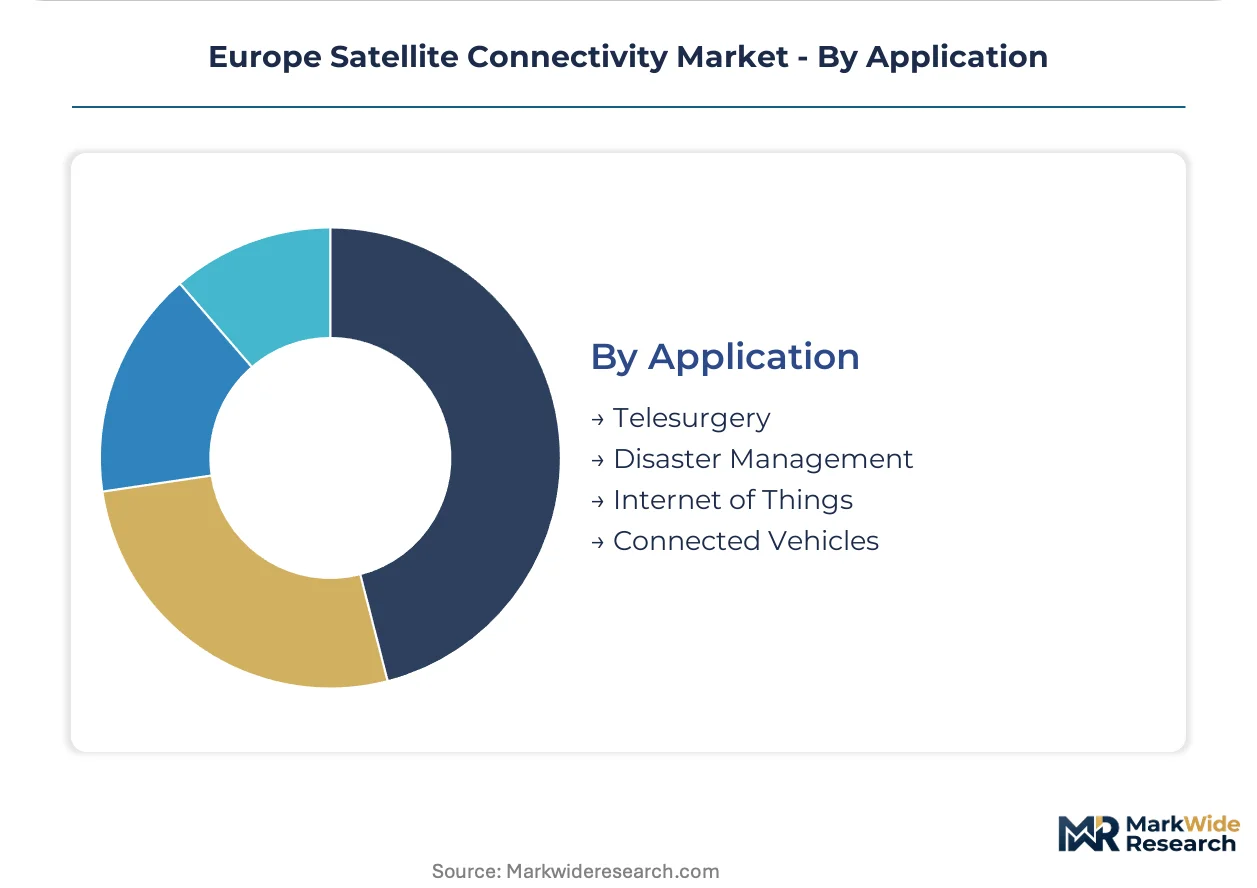
Disaster management applications absorb the most institutional procurement volume; telesurgery is on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France, Germany, and the United Kingdom concentrate the bulk of sovereign satellite procurement, with institutional buyers channeling capital toward IRIS²-aligned infrastructure and encrypted defense networks.
France
French defense agencies are accelerating encrypted satellite network procurement for tactical communications across contested theaters. ANSM and CNIL enforce GDPR-compliant data processing mandates for satellite-enabled healthcare applications. The Île-de-France cluster around Paris hosts Thales Alenia Space manufacturing partnerships supplying sovereign payload components to institutional programs.
Germany
German federal civil protection agencies maintain pre-positioned ground segment assets for disaster response across Bavaria and Baden-Württemberg. KBA and national regulators impose extended licensing timelines for Ka-band deployments under CEPT coordination frameworks. The Munich aerospace corridor concentrates constellation design specialists developing station-keeping algorithms for multi-orbit architectures.
United Kingdom
British carriers are retrofitting narrow-body fleets with multi-orbit terminals as EASA certification timelines compress equipment selection windows. UK defense procurement prioritizes secure intelligence dissemination networks independent of non-European infrastructure. Oxfordshire and Milton Keynes host autonomous vehicle trials specifying LEO primary links with geostationary backup for connected vehicle telemetry.
Italy
Italian broadcasters continue procuring Ku-band and Ka-band geostationary capacity for video distribution and Mediterranean maritime connectivity. National regulators enforce CE marking and REACH compliance for ground equipment manufacturing standards. The Lazio region around Rome concentrates Thales Alenia Space sovereign manufacturing partnerships serving institutional clients.
Norway
Norwegian shipping operators managing unmanned surface vehicle fleets are mandating seamless terrestrial-satellite failover in North Sea and Baltic operations. GDPR enforcement shapes vendor selection for maritime IoT platforms requiring EU-jurisdiction data processing. Oslo and Stavanger anchor maritime connectivity procurement teams consolidating multi-orbit vendor relationships.
Europe Satellite Connectivity Market Competitive Landscape
Multi-vendor framework contracting dominates the current landscape as procurement shifts away from single-source government awards toward competitive tendering across European space agencies. The vendor base stratifies across legacy geostationary operators, emerging low Earth orbit constellation developers, and sovereign manufacturing specialists. Three archetypes anchor competitive positioning: established fleet operators with multi-orbit portfolios, defense-focused payload manufacturers, and small satellite platform specialists. Strategic partnerships and technology licensing represent the primary competitive moves, with operators seeking gateway reconfigurations for hybrid service delivery.
Among Luxembourg and France-based fleet operators, SES S.A. and Eutelsat Communications occupy positions within the established operator tier, while Thales Alenia Space exemplifies the sovereign manufacturing archetype through its French-Italian partnership structure. These entities represent contrasting strategic postures: the fleet operators leverage orbital slot portfolios and ground segment density, while the manufacturing specialist anchors institutional procurement through EU-manufactured payload compliance. OHB SE sits within the small satellite platform specialization, serving institutional programs requiring rapid deployment timelines. Competitive differentiation increasingly hinges on IRIS² compatibility and GDPR-compliant ground station geography rather than raw capacity metrics.
| Leading Market Players |
|---|
| SES S.A. |
| Eutelsat Communications |
| Inmarsat Global Limited |
| Intelsat S.A. |
| Viasat Inc |
| Airbus Defence and Space |
| Thales Alenia Space |
| OHB SE |
| Hisdesat |
| Others |
Value Network & Pricing Analysis
A sharp bifurcation between sovereign-certified and commercial-grade capacity defines both pricing power and supply chain configuration across European satellite connectivity. Premium tiers command substantial markups for IRIS²-aligned payload components manufactured within EU jurisdiction, while commodity transponder leases face relentless compression from terrestrial fiber substitution and launch capacity scarcity.
Pricing Analysis
Volume-vs-margin splits sharply across orbital regimes. Three-tier pricing structure across premium, standard, and economy levels separates encrypted government networks from enterprise multi-orbit bundles and basic maritime backhaul. Price differentiation rests on cybersecurity certification tier under EU Space Programme mandates and sovereign manufacturing provenance. Pricing pressure intensifies in commercial segments as subsea cable investments capture price-sensitive enterprise traffic. Government buyers exhibit lowest price sensitivity, while Polish and Romanian telecommunications operators negotiating framework agreements demonstrate acute cost consciousness.
Supply Chain Analysis
Single-source vulnerability sits with French and Italian payload manufacturing clusters supplying Thales Alenia Space partnerships. Component sourcing draws from German precision optics specialists, Luxembourg-based fleet operators, and Belgian ground station electronics fabricators. Gallium nitride amplifiers, laser inter-satellite link terminals, and radiation-hardened processors constitute critical input dependencies. Tariff exposure on non-EU semiconductor content threatens cost structures. Distribution runs through national space agencies channeling institutional procurement toward qualified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European satellite connectivity occupies a technology-transition phase as laser inter-satellite links displace radio-frequency cross-connects and software-defined payloads obsolete hardware-fixed transponders. Legacy geostationary operators must reconfigure gateway architectures or face displacement by multi-orbit rivals.
For Market Incumbents: Anchor multi-orbit service contracts through exclusive terrestrial fiber failover partnerships with energy and maritime procurement teams in Norway and the United Kingdom. Deepen backward integration into software-defined payload manufacturing to compress refresh cycles from decade-long programs to iterative upgrades. Defend against emerging LEO constellation developers by securing EASA certification priority for aeronautical mobile terminals. For New Entrants and Emerging Players: Ground station operators in Poland, Romania, and the Baltic states represent the most penetrable white-space target, lacking indigenous constellation capacity and seeking IRIS²-compatible integration partners. Maritime IoT convergence offers subscription revenue pools from unmanned surface vehicle fleets managing North Sea operations. Pursue GDPR-compliant data sovereignty positioning with financial services and healthcare enterprises requiring EU-jurisdiction edge computing nodes. For Investors and Strategic Acquirers: Re-rating potential sits with sovereign manufacturing specialists given IRIS² procurement mandate acceleration across French, German, and British defense agencies. Long-term viability favors entities controlling both orbital slot portfolios and EU-manufactured payload compliance. Monitor spectrum auction outcomes and cross-border service licensing agreements as inflection indicators for vendor qualification reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-orbit Service Integration | Bundles geostationary reliability with LEO latency for maritime and energy procurement teams. |
| Software-defined Payload Development | Enables orbital reconfiguration without hardware replacement under Thales Alenia Space architectures. |
| GDPR-compliant Ground Station Expansion | Captures healthcare and autonomous vehicle telemetry requiring EU-jurisdiction data processing. |
| Laser Inter-satellite Link Deployment | Eliminates ground station bottlenecks for sub-100 millisecond latency enterprise workloads. |
| Sovereign Manufacturing Partnership | Secures institutional procurement preference under IRIS² payload compliance mandates. |
Research Methodology
Document review covered ESA procurement databases, EU Space Programme budget allocations, and national defense agency satellite communication tenders, complemented by interviews with constellation program directors, ground segment procurement leads, and regulatory affairs specialists at EASA and national aviation authorities. Secondary validation drew from CEPT spectrum coordination filings, REACH compliance registries, and GDPR enforcement actions by CNIL and national data protection authorities. Bottom-up capacity deployment tracking and top-down institutional budget analysis were triangulated against vendor revenue disclosures.
Cross-referencing historical launch manifests and constellation deployment timelines against expert panel input shaped the analytical framework. Segmentation dimensions modeled include orbital regime, service type, end-user archetype, and application specificity across the projection horizon. CAGRs were derived from capacity expansion schedules, procurement award trajectories, and technology substitution elasticities. Forecast inputs incorporated Ariane 6 and Vega-C launch cadence assumptions, spectrum licensing timeline distributions, and terrestrial fiber route completion schedules.
Caveats apply where launch vehicle delays, spectrum coordination disputes, or defense budget reallocation could materially shift the outlook. Forecasts reflect documented assumptions about IRIS² deployment phasing and multi-orbit interoperability standards adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Mexico Satellite Connectivity Market
Satellite
Military Satellite Market
Satellite
Satellite Antenna Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Satellite Communication Equipment Market
Satellite
LEO and GEO Satellite Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Global Satellite Modem Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Nano and Microsatellite Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Communication Satellite Launch Services Market