
 Middle East Satellite Communications Market | 2026-2036
Middle East Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Satellite Communications Market Insights
The Middle East satellite communications sector is pivoting around a widening performance gap between premium managed services and commodity bandwidth resale. Thuraya Telecommunications Company leverages its L-band heritage to anchor mobile satellite services across remote oil fields and desert corridors. Yahsat dominates government and military verticals through its sovereign fleet position over the Gulf. Intelsat S.A. competes on managed network integration, bundling terrestrial backhaul with orbital capacity for enterprise clients.
Middle East satellite communications encompasses the transmission, reception, and relay of voice, video, and data signals via geostationary and non-geostationary orbital assets operating across C-band, Ku-band, Ka-band, and high-throughput satellite architectures. These systems deliver connectivity to terrestrial infrastructure gaps, with transponder power budgets, orbital slot coordination, and link budget engineering determining service quality. Ka-band and HTS deployments are expanding fastest as maritime and aero operators demand higher throughput per unit cost. Telecommunication and broadcasting services remain mature revenue pools, while data transmission for energy sector digitalization commands premium pricing. Government and military end users sustain long-term contract visibility through sovereign capacity leases.
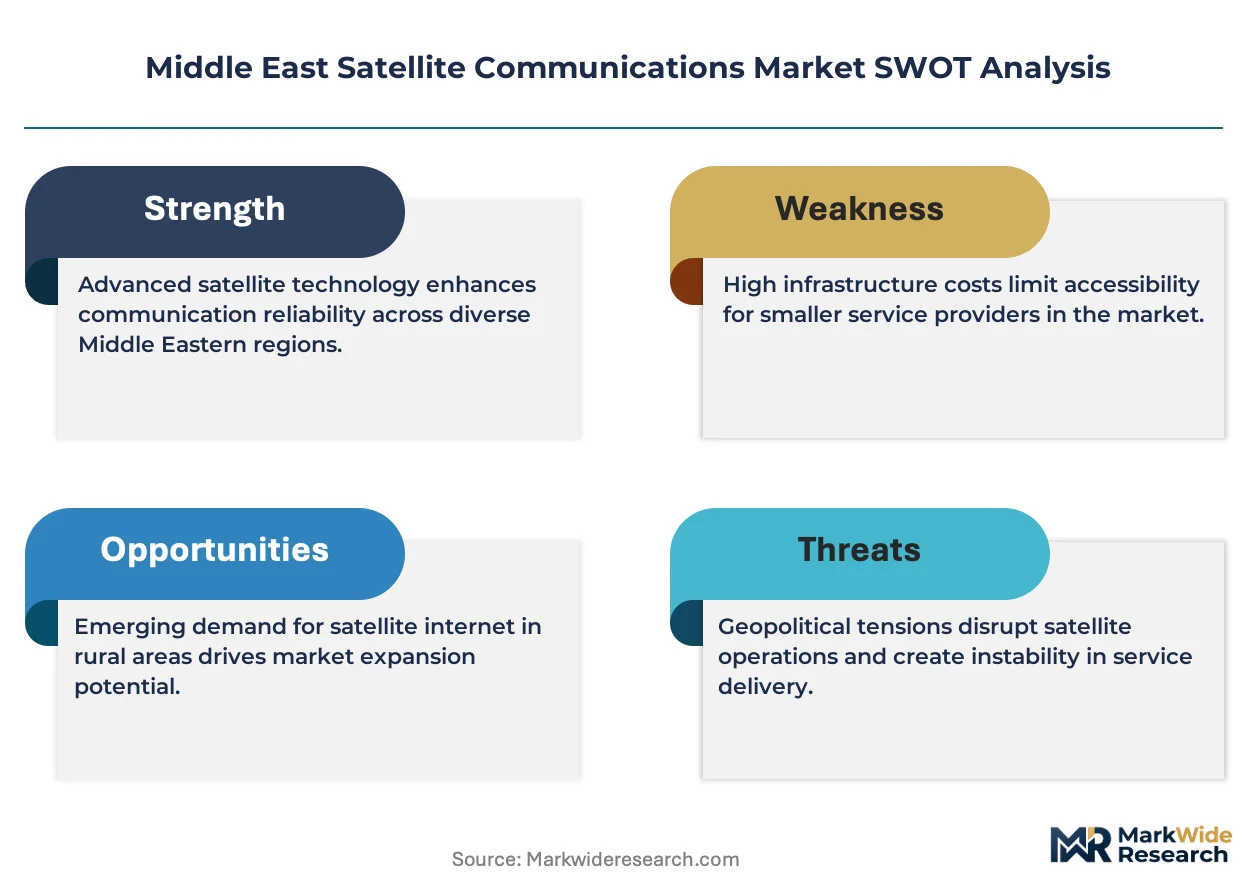
Saudi Arabia's CITC spectrum frameworks, the UAE's TDRA orbital coordination rules, and Egypt's NTRA licensing requirements collectively shape market access and operational compliance for foreign and domestic operators. HTS authorization timelines and national security vetting for gateway earth stations determine competitive positioning across Gulf markets. Stakeholders must weigh sovereign capacity mandates against commercial fleet economics as low Earth orbit constellations seek regional landing rights.
Market Dynamics
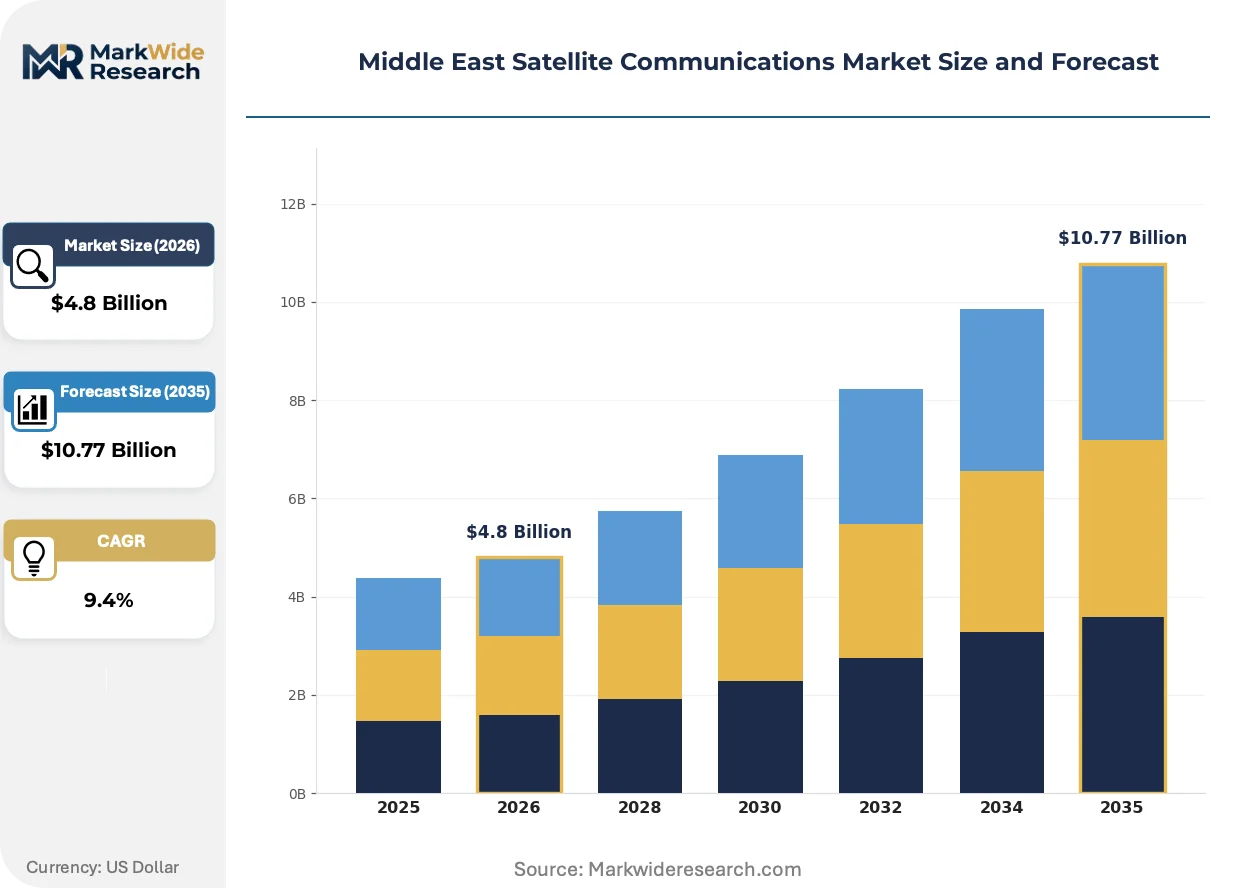
The Middle East satellite communications market is bifurcating around sovereign capacity mandates versus commercial fleet economics, as Gulf regulators impose national security vetting for gateway earth stations while low Earth orbit constellations seek regional landing rights.
Growth Catalysts
- Defense procurement expansion:Gulf state ministries are expanding secure satcom procurement for border surveillance and naval operations, creating sovereign capacity leases with decade-long visibility.
- Spectrum licensing streamlining:Saudi Arabia's CITC has accelerated non-geostationary constellation authorization timelines, reducing regulatory friction for orbital slot coordination.
- Energy sector digitalization:Remote oil field automation and offshore platform connectivity are driving Ka-band and HTS deployments across desert corridors and maritime zones.
Market Restraints
- Gateway infrastructure concentration:Abu Dhabi and Dubai host the region's primary teleport hubs, creating single-point vulnerability for traffic aggregation.
- Orbital slot scarcity:ITU coordination procedures and Gulf sovereign fleet positioning limit accessible geostationary slots for new market entrants.
- Terrestrial fiber substitution:Subsea cable expansions along Red Sea and Persian Gulf corridors are compressing price premiums for backhaul-dependent satellite services.
Strategic Opportunities
- Egyptian market underpenetration:NTRA licensing frameworks remain less restrictive than Gulf counterparts, offering first-mover positioning for managed service providers targeting North African enterprise demand.
- Maritime IoT convergence:Integration of satellite connectivity with vessel tracking and predictive maintenance systems is opening new revenue pools in shipping and offshore logistics.
- Aero passenger connectivity:Full-flat Ka-band coverage across Arabian Peninsula flight corridors remains incomplete, creating whitespace for regional airline fleet upgrades.
Industry Challenges
- RF engineering talent scarcity:Link budget optimization and transponder power management expertise concentrates in UAE and Saudi Arabia, constraining operator expansion timelines.
- Legacy C-band migration:Incumbent broadcast clients resist Ka-band transition, forcing dual-architecture maintenance and compressing HTS rollout efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Satellite Communications Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telecommunication, Broadcasting, Data Transmission, Internet Connectivity End User: Government, Military, Maritime, Aerospace Technology: C-band, Ku-band, Ka-band, HTS Deployment Model: On-premise, Managed Service, Hybrid, Others |
| Companies Covered | Thuraya Telecommunications Company, Intelsat S.A., Al Yah Satellite Communications Company PJSC (Yahsat), SES S.A., Eutelsat Communications S.A., Arab Satellite Communications Organization, Arabsat, Viasat Inc., Nilesat, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Satellite Communications Market Trends and Innovations
Orbital architecture diversification is fragmenting service delivery models across the Middle East, as legacy geostationary operators confront software-defined payload competition from non-geostationary systems.
Software-defined satellite payloads are modularizing capacity allocation across the Middle East, enabling real-time beam steering and frequency reuse optimization. Energy sector buyers in Saudi Arabia and Kuwait are adopting these flexible architectures fastest, drawn by pay-per-use throughput models. This modularity is compressing traditional transponder lease structures and forcing managed service bundling.
The UAE's TDRA orbital coordination rules now mandate cybersecurity certification for all gateway earth stations handling government traffic, tightening operational compliance burdens. This regulatory shift is accelerating sovereign fleet investment as foreign operators face extended national security vetting timelines. Egyptian and Jordanian operators are responding by pursuing bilateral spectrum reciprocity agreements to bypass Gulf regulatory bottlenecks.
Enterprise buyers are consolidating vendor relationships around integrated network service contracts rather than standalone capacity leases. Systems integrators and defense contractors are displacing pure-play satellite operators in direct procurement channels, particularly for military and critical infrastructure applications. This concentration is most visible in UAE government verticals, where long-term managed service agreements now dominate acquisition patterns.
Middle East Satellite Communications Market Segmentation
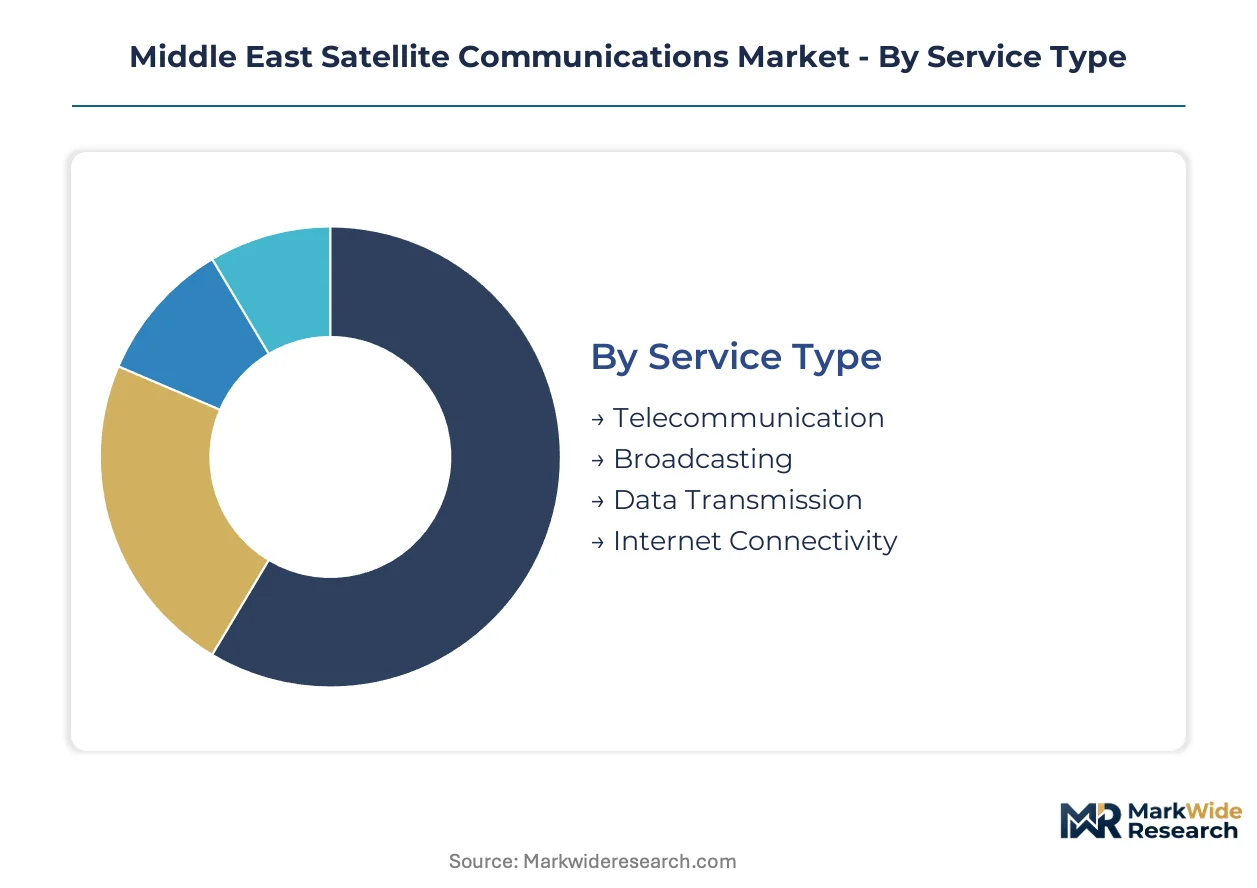
Satellite communications segmentation in the Middle East reveals divergent capital requirements across orbital architectures and service delivery models. Procurement patterns favor long-term sovereign leases in government verticals while commercial buyers shift toward consumption-based managed services.
Service Type:
Capital intensity varies sharply across service categories, with infrastructure-heavy broadcasting demanding substantial transponder commitments while data transmission leverages lighter ground segment investments.
- Telecommunication:Voice and messaging relay via geostationary transponders supports remote workforce connectivity across Saudi Aramco installations and UAE construction corridors. Demand concentrates in Kuwait's oil field camps where terrestrial cellular coverage remains intermittent.
- Broadcasting:Direct-to-home television distribution occupies the majority of legacy C-band and Ku-band capacity across Gulf orbital slots. Egyptian and Jordanian direct-to-home platforms sustain transponder utilization despite compression from streaming substitution.
- Data Transmission:Enterprise private networks and SCADA backhaul for pipeline monitoring.
- Internet Connectivity:Consumer broadband and community Wi-Fi hotspot aggregation.
Broadcasting absorbs the bulk of installed capacity; data transmission is expanding most quickly.
End User:
Customer type determines contract duration and pricing architecture, with defense and maritime buyers locking in decade-long terms while aerospace operators pursue shorter fleet upgrade cycles.
- Government:Sovereign capacity leases for civil administration and emergency response networks. Saudi Arabia's CITC mandates national security vetting for all gateway stations handling government traffic, extending procurement timelines.
- Military:Secure satcom for border surveillance and naval task force coordination. UAE defense procurement channels favor integrated managed service agreements over standalone capacity leases.
- Maritime:Vessel tracking, crew welfare connectivity, and predictive maintenance IoT integration.
- Aerospace:In-flight passenger broadband and cockpit data link services.
Government and military segments anchor long-term revenue visibility; maritime connectivity is climbing the fastest as IoT convergence accelerates.
Technology:
Spectral efficiency and throughput economics differentiate technology choices, with higher-frequency bands requiring more sophisticated ground infrastructure but delivering superior bits-per-Hertz performance.
- C-band:Legacy frequency allocation resilient to rain fade, sustaining broadcast and basic telephony in monsoon-affected zones. Incumbent operators in Egypt maintain dual C-band and Ka-band architectures to preserve existing client contracts.
- Ku-band:Intermediate frequency range dominating enterprise VSAT deployments and direct-to-home services. UAE teleport hubs concentrate Ku-band gateway infrastructure for regional traffic aggregation.
- Ka-band:High-frequency spectrum enabling spot beam architectures for concentrated capacity delivery.
- HTS:High-throughput satellite platforms with frequency reuse across multiple spot beams.
C-band retains the deepest installed base; HTS platforms are gaining share fastest as energy sector digitalization demands scalable throughput.
Deployment Model:
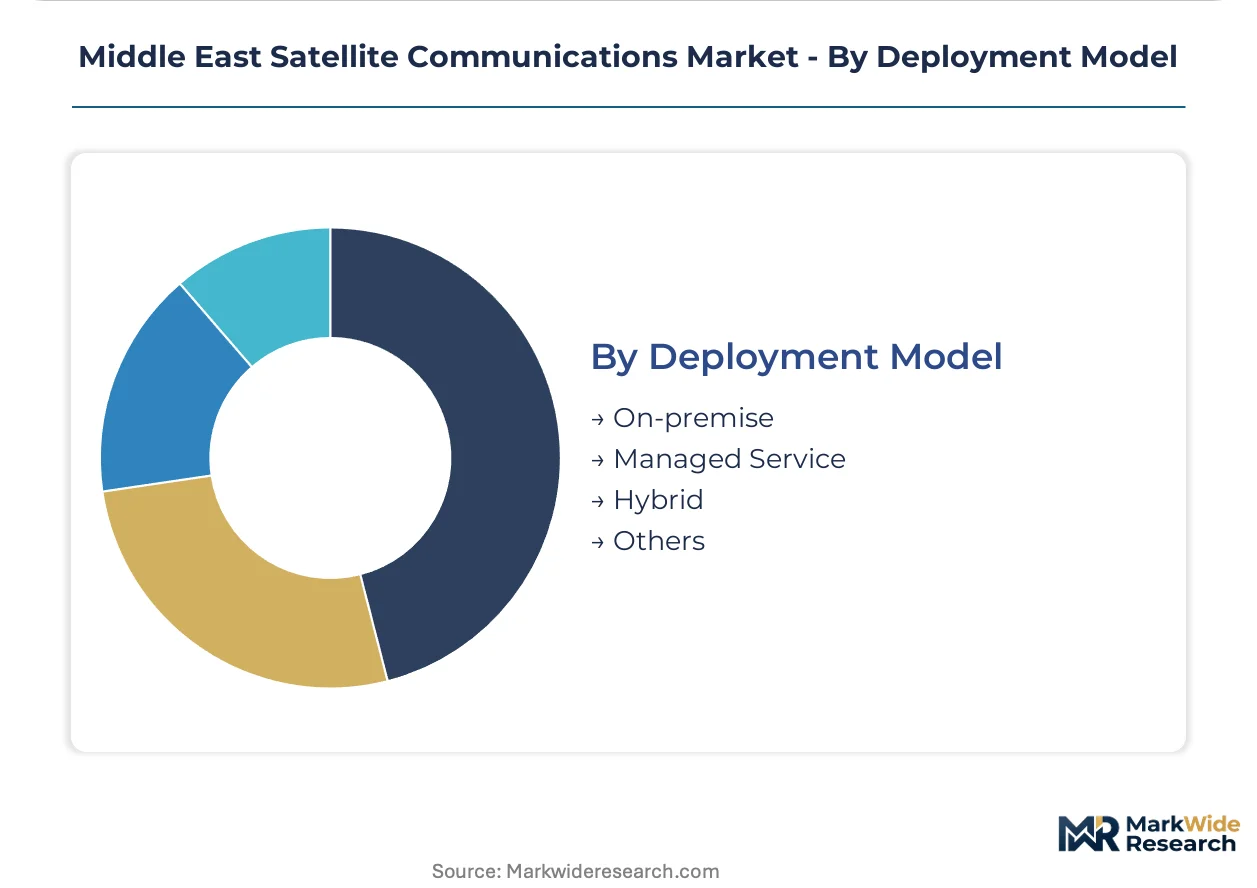
Operational responsibility allocation shapes buyer risk profiles, with on-premise models demanding internal RF engineering expertise while managed services transfer infrastructure burden to operators.
- On-premise:Customer-owned earth stations and network management systems. Large Saudi petrochemical complexes maintain captive teleport facilities for operational technology isolation.
- Managed Service:End-to-end service delivery including terrestrial backhaul integration. UAE enterprise buyers increasingly consolidate procurement around single-vendor managed network contracts.
- Hybrid:Split architecture combining customer premises equipment with operator-managed orbital capacity.
- Others:Emerging consumption-based and software-defined service models.
Managed service models capture the majority of new contract value; hybrid deployments are expanding most quickly among mid-size energy operators seeking operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi anchor Middle East satellite communications infrastructure through concentrated teleport hubs and satellite control centers that aggregate regional traffic flows.
United Arab Emirates
Abu Dhabi's sovereign fleet positioning and Dubai's enterprise VSAT density drive demand across government and commercial verticals. The UAE's TDRA mandates cybersecurity certification for gateway earth stations handling government traffic, tightening compliance timelines. Dubai Internet City hosts regional teleport infrastructure where managed service providers consolidate network operations.
Saudi Arabia
Saudi Aramco's remote oil field automation and defense ministry border surveillance programs anchor capacity consumption. The Communications and Information Technology Commission has streamlined non-geostationary constellation spectrum licensing, accelerating orbital slot coordination. Riyadh's technology zones concentrate RF engineering talent for link budget optimization.
Egypt
Nilesat's direct-to-home broadcasting footprint and Suez Canal maritime connectivity sustain transponder utilization. The National Telecommunications Regulatory Authority maintains less restrictive licensing frameworks than Gulf counterparts, attracting first-mover managed service providers. Cairo's media production clusters anchor C-band broadcast distribution across North Africa.
Kuwait
Offshore platform connectivity and remote oil field camp telecommunications drive Ka-band deployment in desert corridors. The Ministry of Communications coordinates spectrum allocation for energy sector digitalization initiatives. Kuwait City's enterprise zones concentrate VSAT procurement for midstream pipeline monitoring.
Israel
Defense procurement channels and cybersecurity-hardened satellite networks anchor sovereign capacity demand. The Ministry of Communications regulates gateway infrastructure through national security vetting procedures comparable to Gulf standards. Tel Aviv's technology corridor hosts specialized firms integrating satellite connectivity with predictive maintenance systems.
Middle East Satellite Communications Market Competitive Landscape
Capital-heavy fleet operators compete with asset-light service integrators across divergent business models in Middle East satellite communications. Thuraya Telecommunications Company and Yahsat anchor the sovereign capacity tier through regional orbital positioning and government contract visibility. Intelsat S.A. and SES S.A. represent the managed services tier bundling terrestrial backhaul with orbital capacity. Market consolidation centers on long-term sovereign leases and strategic partnerships for gateway infrastructure access.
Within the sovereign fleet tier, Thuraya Telecommunications Company and Al Yah Satellite Communications Company PJSC exemplify regional operators leveraging Gulf orbital slots for government and energy verticals. Intelsat S.A. occupies a position among international fleet operators competing through integrated network service contracts. These three anchors represent divergent strategic archetypes: regional sovereign positioning, international managed services bundling, and hybrid commercial-government portfolio balancing.
| Leading Market Players |
|---|
| Thuraya Telecommunications Company |
| Intelsat S.A. |
| Al Yah Satellite Communications Company PJSC (Yahsat) |
| SES S.A. |
| Eutelsat Communications S.A. |
| Arab Satellite Communications Organization |
| Arabsat |
| Viasat Inc. |
| Nilesat |
| Others |
Pricing and Supply Chain Analysis
Ku-band transponder lease rates on the MEASAT-3d and Yahsat-1B satellites anchor the regional pricing benchmark, cascading through managed service contracts into three-tier structures separating sovereign defense leases from energy sector throughput agreements and consumer broadband resale.
Pricing Analysis
Throughput-based pricing per megabit-per-second anchors managed service contracts across Gulf energy operators, with Ka-band spot beam premiums reflecting link availability guarantees during sandstorm conditions. Price differentiation separates military-grade encrypted capacity from commercial HTS resale, with Egyptian NTRA-licensed operators undercutting UAE TDRA-certified rivals on compliance cost pass-through. Margins are tightening in consumer broadband tiers due to terrestrial 5G fixed-wireless substitution. Maritime fleet operators exhibit lowest price sensitivity, prioritizing coverage continuity over per-gigabyte cost.
Supply Chain Analysis
Space-qualified gallium nitride amplifier supply rests on US and Japanese defense-tier semiconductor foundries, with European TESAT and Thales Alenia anchoring payload integration. Bus structure aluminum-lithium alloys and xenon propellant for electric orbit-raising draw from Russian and Chinese raw material streams despite sanctions-layered procurement complexity. Single-source vulnerability concentrates in solid-state power amplifier modules for L-band mobile terminals. Distribution runs through Dubai Internet City teleport operators for regional traffic aggregation, with Riyadh technology zones capturing Saudi defense procurement directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sovereign gateway infrastructure represents the decisive competitive lever as Gulf regulators extend national security vetting timelines for foreign operators.
For Market Incumbents: Lock in long-term sovereign capacity leases with Saudi defense procurement and UAE critical infrastructure operators before low Earth orbit constellations secure CITC landing rights. Pursue backward integration into Riyadh-based RF engineering talent pools to compress link budget optimization timelines. Certify Dubai and Abu Dhabi teleport facilities under TDRA cybersecurity mandates to forestall foreign competitor market entry. For New Entrants and Emerging Players: Cloud-managed network service platforms offer the lowest-friction route to Egyptian enterprise demand under NTRA's less restrictive licensing frameworks. Target Kuwaiti offshore platform operators seeking hybrid deployment flexibility for predictive maintenance IoT convergence. Position around consumption-based HTS pricing to undercut incumbent transponder lease structures in North African maritime corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional teleport operators with UAE gateway infrastructure and dormant Egyptian orbital coordination filings. Five-to-ten year viability hinges on sovereign fleet positioning as LEO constellations fragment commercial pricing power. Monitor Saudi CITC spectrum auction announcements as the critical inflection signal for non-geostationary constellation market access.| Strategic Initiative | Industry Significance |
|---|---|
| Gateway Infrastructure Acquisition | Captures UAE TDRA-certified teleport capacity before foreign LEO operators secure landing rights. |
| Sovereign Fleet Expansion | Positions operators for Saudi defense procurement under CITC national security vetting requirements. |
| Managed Service Platform Launch | Displaces pure-play capacity resellers in Egyptian enterprise VSAT procurement channels. |
| RF Engineering Talent Consolidation | Concentrates scarce link budget expertise in Riyadh technology zones for competitive differentiation. |
| Maritime IoT Integration Partnership | Opens predictive maintenance revenue pools with Kuwaiti offshore platform operators. |
Research Methodology
Multi-period observation of transponder utilization rates, spectrum auction filings, and defense procurement contract awards anchored the trend analysis, supplemented by interviews with satellite fleet procurement directors, teleport operations managers, CITC regulatory affairs leads, and energy sector IT infrastructure heads. Secondary validation drew from ITU orbital coordination databases, national regulator licensing disclosures, and customs records for ground segment equipment imports. Bottom-up capacity deployment tracking triangulated against top-down market sizing across service type, end user, and technology segmentations.
Segment-weighting approaches distributed value estimates across telecommunication, broadcasting, data transmission, and internet connectivity service categories, with end-user splits across government, military, maritime, and aerospace verticals. Technology segmentation incorporated C-band legacy capacity, Ku-band enterprise VSAT, Ka-band spot beam, and HTS platform deployments. CAGRs derived from regression analysis of historical capacity additions and forward-projected demand elasticity across the analysis window. Industry-specific inputs included Saudi Aramco remote field automation timelines and UAE defense ministry satcom modernization program visibility.
The model holds under stable Gulf regulatory frameworks and continued sovereign capacity preference; deviation in LEO constellation landing rights acceleration or terrestrial fiber substitution rates would shift competitive positioning and pricing power distributions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Sudan Satellite Transponder Market
Satellite
South Korea Satellite Communication Market
Satellite
Satellite Services Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Europe Satellite Manufacturing Market
Satellite
Tactical Satellite Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Satellite Manufacturing Market
Satellite
Satellite Gateway Market
Satellite
Spain Satellite-Based Earth Observation Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Global Maritime Satellite Communication Market
Satellite
Italy Satellite Communication Market
Satellite
North America Mobile Satellite Services Market
Satellite
Commercial LEO Satellite Market