
 EMEA Satellite Antenna Market | 2026-2036
EMEA Satellite Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Satellite Antenna Market Insights
Buyer concentration among European defence procurement agencies is shifting as joint acquisition frameworks replace national tenders. Thales Group leverages its integrated electronics portfolio to compete for multi-national military contracts. Airbus anchors civilian and institutional demand through its satellite manufacturing division. Cobham sustains niche positions in ruggedized mobile antenna systems for tactical deployments.
Satellite antennas are electromagnetic transducers that convert guided radio-frequency energy into free-space radiation, typically operating across L-band to Ka-band frequencies with gain specifications exceeding 30 dBi for geostationary links. Their primary commercial purpose is establishing reliable two-way communication between ground stations and orbital assets for broadcasting, navigation, and data relay. Parabolic reflector systems dominate installed base value due to proven reliability in fixed earth stations, while flat panel configurations represent the fastest-expanding technology segment as manufacturers reduce unit costs for consumer broadband terminals. Phased array architectures command premium pricing in military and aeronautical applications where electronic beam steering eliminates mechanical tracking latency.
EU Space Programme regulations, CE marking requirements for radio equipment, and national spectrum licensing through bodies such as France's ANFR and Germany's BNetzA shape product certification timelines and market access conditions across the region. ESA procurement rules and NATO standardization agreements further constrain vendor eligibility for institutional contracts. Stakeholders must monitor evolving frequency allocation decisions at the ITU level and corresponding national implementation deadlines that determine antenna specification roadmaps.
Market Dynamics
Joint acquisition frameworks across NATO member states are consolidating procurement authority into fewer hands, forcing vendors to restructure qualification processes and co-development partnerships around multi-national military specifications rather than national tender requirements.
Growth Catalysts
- EU Space Programme funding:Institutional budgets for secure satellite communications are expanding under the European Union's space sovereignty agenda, creating dedicated procurement streams for ground segment infrastructure.
- Flat panel antenna maturation:Manufacturing scale economies in consumer broadband terminals are driving unit cost reductions that enable new mobility applications in maritime and aeronautical segments.
- Toulouse-Bavaria corridor concentration:Aerospace engineering talent pools and satellite prime contractor proximity in France and Germany are accelerating product development cycles for next-generation phased array systems.
Market Restraints
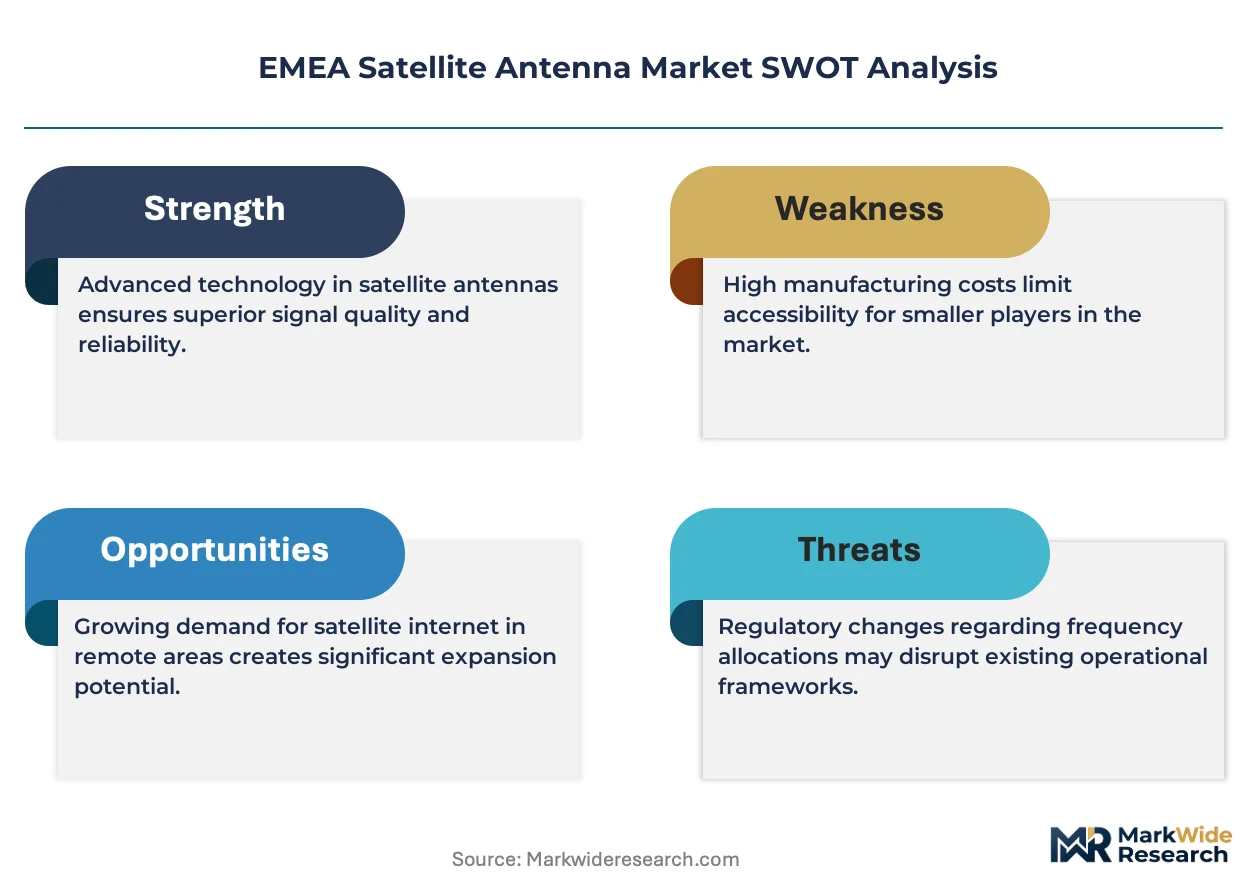
- Gallium nitride substrate costs:RF semiconductor material prices exhibit volatility that compresses margins on high-performance military-grade phased array subsystems.
- Single-source dependency for space-qualified components:European vendors face concentration risk in radiation-hardened integrated circuit supply chains dominated by limited qualified foundries.
- CE marking and RED compliance timelines:Radio equipment directive certification processes through notified bodies create 6-12 month market entry delays for new product introductions.
Strategic Opportunities
- Nordic defence modernisation:Sweden and Finland's NATO accession is unlocking joint procurement frameworks for tactical satellite communications infrastructure previously restricted to alliance members.
- Optical-terrestrial convergence:Hybrid RF-laser communication terminals are creating new product categories for low-latency government backhaul applications.
- ESA commercial partnership pathways:The agency's increasing use of public-private partnerships for ground segment development is opening institutional qualification routes for mid-tier technology providers.
Industry Challenges
- Phased array thermal engineering expertise:The specialised skill set for active electronically scanned array thermal management is concentrated among a shrinking cohort of defence electronics veterans approaching retirement.
- Multi-band interoperability certification:Antenna systems must simultaneously satisfy NATO STANAG, ESA, and national spectrum regulator requirements, multiplying test matrix complexity.
- Mechanical-to-electronic beam steering transition:Legacy ground station operators face integration complexity when retrofitting existing parabolic infrastructure with hybrid tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Satellite Antenna Market |
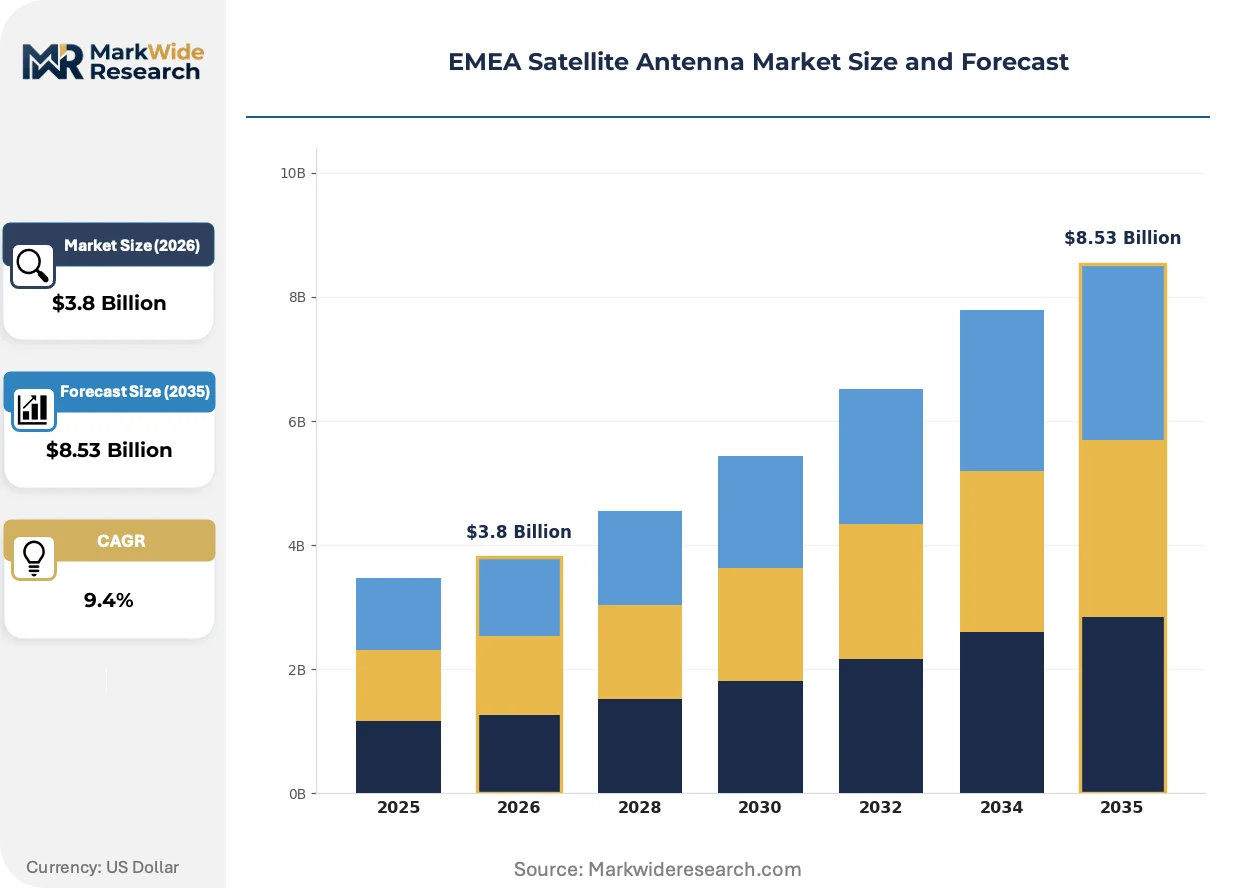
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic, Phased Array, Flat Panel, Cassegrain Technology: Active, Passive, Adaptive, Reflective End User: Government, Telecommunication, Military, Broadcasting Installation: Fixed, Portable, Mobile, Urban |
| Companies Covered | Airbus, Cobham, L3Harris Technologies, Hughes Network Systems, Viasat, Thales Group, General Dynamics Corporation, Communications & Power Industries, Honeywell International, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Satellite Antenna Market Trends and Innovations
Active electronically scanned array architectures are penetrating price points previously occupied by mechanically steered systems, while regulatory pressure on spectrum efficiency is mandating smarter RF front-ends across civilian and military applications.
Metamaterial-enabled flat panel antennas are rewriting the cost-performance trade-off for consumer and enterprise broadband terminals. Thales and Airbus Defence and Space are integrating these structures into aeronautical connectivity products for commercial aviation retrofit programs. The technology is compressing the addressable market for traditional parabolic reflector manufacturers in mobility applications.
EU AI Act transparency requirements are extending to autonomous satellite resource management systems that optimise antenna beam patterns in real-time. Equipment vendors must now document algorithmic decision pathways for military procurement agencies in France, Germany, and Italy. This is elongating product development cycles for intelligent ground segment software.
Defence procurement agencies are consolidating vendor panels through framework agreements that bundle antenna systems with satellite services and maintenance. The UK's Defence Digital organisation and France's DGA are leading this shift toward integrated capability procurement. Germany's BAAINBw is following with similar consolidated tender structures for tactical communications programs.
EMEA Satellite Antenna Market Segmentation
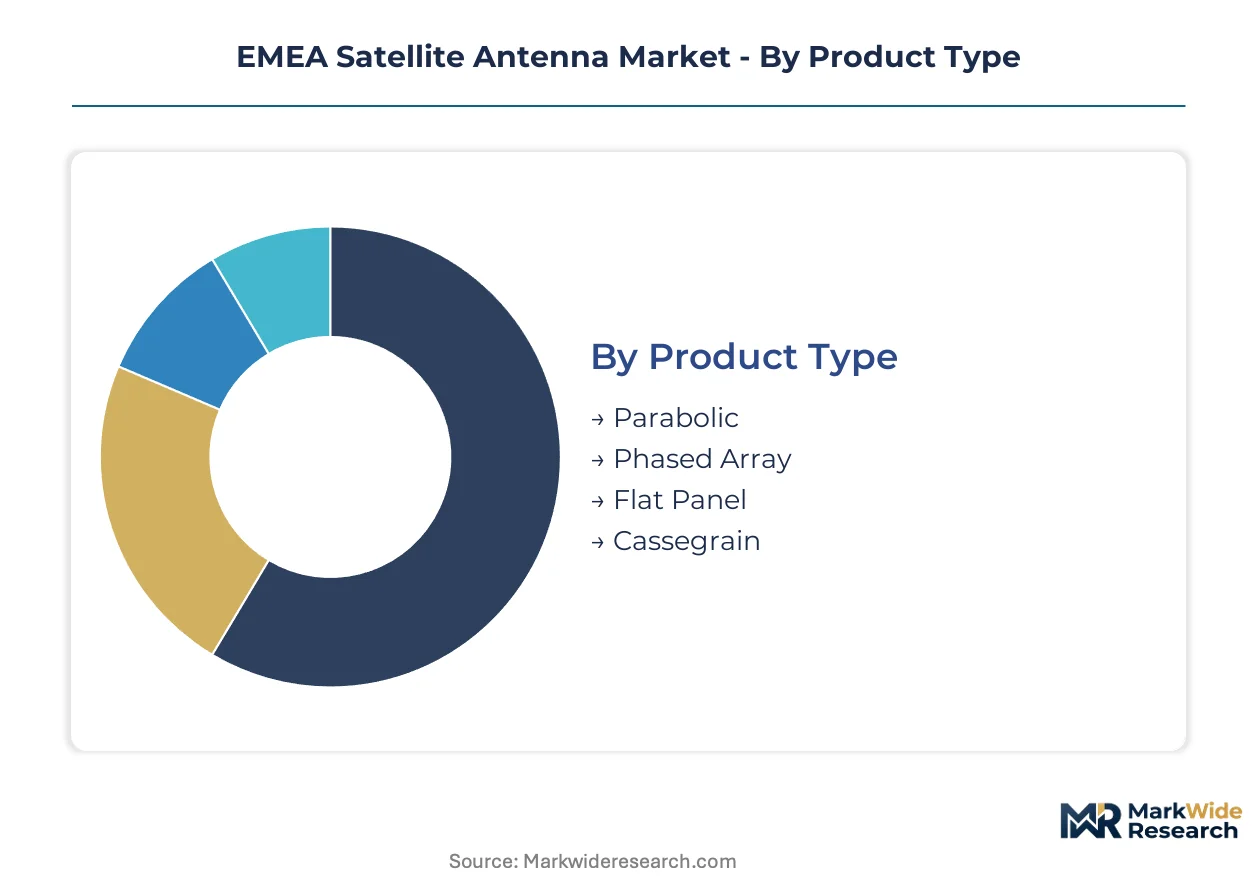
Antenna specification requirements diverge sharply across EMEA procurement channels. Military buyers prioritize electronic beam steering and thermal resilience, while civilian operators balance unit economics against installation flexibility. Segmentation reveals where engineering investment aligns with buyer willingness to pay.
Product Type:
Cost tier separates buyers most cleanly in this category, with procurement budgets dictating architectural choice from mechanically steered legacy systems to electronically agile platforms.
- Parabolic:Curved reflector surfaces concentrate RF energy through a single feed horn, achieving high gain at lower unit cost. Demand concentrates in Germany's broadcasting infrastructure and fixed earth stations across France's overseas territories, constrained by mechanical tracking latency in mobility applications.
- Phased Array:Active electronically scanned arrays steer beams through phase-shifted RF elements without moving parts. Military procurement in the UK and France drives adoption, with NATO standardization agreements mandating electronic beam agility for tactical communications.
- Flat Panel:Metamaterial-enabled planar structures reduce aerodynamic drag and visual signature for mobile platforms. Thales and Airbus Defence and Space integrate these into aeronautical retrofit programs.
- Cassegrain:Dual-reflector geometry with hyperbolic subreflector achieves compact focal length in large-aperture systems. ESA ground stations and deep-space tracking facilities in Spain and Italy specify this architecture.
Volume sits with Parabolic systems; growth tilts toward Flat Panel configurations as manufacturing scale economies penetrate mobility segments.
Technology:
Application environment—static versus dynamic, benign versus contested—determines whether passive simplicity or active adaptability justifies the cost premium.
- Active:Transmit-receive modules with integrated amplification enable real-time beam reconfiguration. Maritime and aeronautical connectivity providers in Scandinavia and the Mediterranean basin specify active architectures for link reliability in motion.
- Passive:Receive-only or transmit-only elements without onboard signal processing deliver lowest cost per unit. Consumer broadband terminals and rural broadcasting receive chains in Eastern Europe deploy passive front-ends.
- Adaptive:Algorithmic optimization of beam patterns responds to interference or atmospheric conditions. EU AI Act documentation requirements extend to these systems in France and Germany, elongating procurement cycles.
- Reflective:Purely passive wavefront manipulation through surface geometry eliminates active electronics. Legacy ground station upgrades in the UK and Italy retain reflective subsystems for cost containment.
Military procurement concentrates in Active systems; Adaptive architectures are gaining share fastest as software-defined radio capabilities mature.
End User:
Customer type dictates certification burden, with institutional buyers imposing multi-standard test matrices that exclude smaller vendors.
- Government:Civilian agencies and intergovernmental bodies require ESA-qualified ground segment equipment. The EU Space Programme generates dedicated procurement streams for secure communications infrastructure.
- Telecommunication:Mobile network operators and satellite service providers prioritize unit cost and installation speed. Consumer broadband terminal demand concentrates in Germany, France, and the UK.
- Military:Defence procurement agencies mandate NATO STANAG compliance and national security clearances. Joint acquisition frameworks across NATO member states are consolidating vendor qualification requirements.
- Broadcasting:Content distribution networks require high availability for direct-to-home services. France's ANFR and Germany's BNetzA spectrum licensing shapes regional specification roadmaps.
Telecommunication generates current volume; Military procurement is expanding most quickly as NATO modernisation accelerates.
Installation:
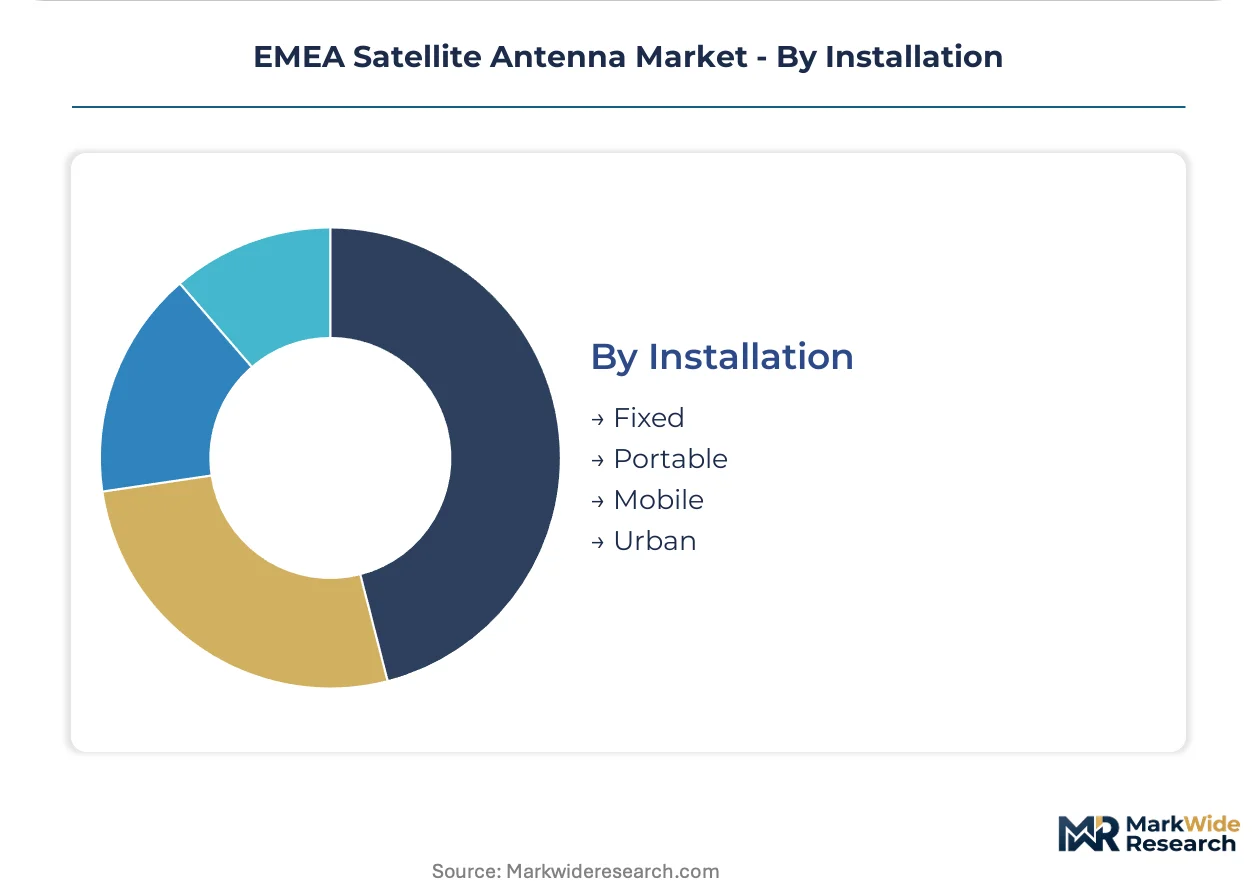
Deployment mobility determines environmental hardening requirements and regulatory jurisdiction, with urban installations facing distinct planning constraints.
- Fixed:Permanent ground stations with concrete foundations and weatherproof enclosures. France's aerospace cluster around Toulouse and Germany's Bavarian satellite corridor anchor manufacturing for this segment.
- Portable:Rapidly deployable systems for emergency response and temporary events. Nordic defence modernisation in Sweden and Finland is unlocking demand for expeditionary communications.
- Mobile:Vehicle-mounted or vessel-integrated terminals with active stabilization. Phased array thermal engineering expertise concentrated among defence electronics veterans constrains supply.
- Urban:Concealed or low-profile installations subject to municipal planning permissions. CE marking and RED compliance timelines through notified bodies create market entry delays.
Fixed installations retain volume dominance; Mobile configurations show the steepest expansion trajectory as flat panel costs enable new applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate supply from European foundries anchors the EMEA satellite antenna manufacturing base. Toulouse and Bavaria host the densest concentrations of aerospace engineering talent and prime contractor proximity.
France
DGA procurement frameworks and EU Space Programme funding accelerate demand for secure military communications infrastructure. ANFR spectrum licensing mandates shape antenna specification roadmaps for both defence and civilian applications. The Toulouse aerospace cluster concentrates phased array development teams serving NATO and institutional customers.
Germany
BAAINBw consolidated tender structures for tactical communications drive multi-standard certification requirements across vendor panels. BNetzA national spectrum licensing creates 6-12 month compliance timelines for radio equipment market entry. Bavaria's satellite manufacturing corridor anchors flat panel antenna production for aeronautical retrofit programs.
United Kingdom
Defence Digital organisation framework agreements bundle antenna systems with integrated satellite services and maintenance contracts. NATO STANAG compliance requirements constrain vendor eligibility for military procurement streams. South England hosts ground station upgrade programs transitioning parabolic infrastructure toward hybrid electronic steering.
Sweden
NATO accession unlocks joint procurement frameworks for tactical satellite communications previously restricted to alliance members. Swedish Defence Materiel Administration coordinates Nordic defence modernisation initiatives with Finland. Stockholm-region engineering firms develop portable expeditionary antenna systems for arctic deployment conditions.
Italy
ESA ground station specifications for deep-space tracking sustain demand for large-aperture Cassegrain architectures. National spectrum regulator implementation of ITU frequency allocation decisions determines antenna roadmap priorities. Italy's aerospace engineering base in Rome and Turin supports institutional procurement for space agency infrastructure.
EMEA Satellite Antenna Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue metamaterial-enabled flat panel specializations. The vendor structure consolidates around integrated defence electronics portfolios and satellite prime contractor captive ground segment capabilities. Three archetypes dominate: aerospace conglomerates with antenna divisions, dedicated RF component specialists, and service-integrated equipment providers. Competitive moves concentrate on framework agreement positioning for multi-national military procurement and co-development partnerships for EU Space Programme infrastructure.
Within the integrated defence electronics tier, Thales Group and Airbus exemplify the aerospace conglomerate archetype, leveraging broad electronics portfolios to compete for institutional and military contracts. Cobham occupies a specialist position in ruggedized mobile antenna systems. L3Harris Technologies represents the transatlantic defence electronics pattern common among NATO procurement participants. These three anchors illustrate how vendor qualification requirements increasingly favour entities with multi-national certification footprints and established prime contractor relationships.
| Leading Market Players |
|---|
| Airbus |
| Cobham |
| L3Harris Technologies |
| Hughes Network Systems |
| Viasat |
| Thales Group |
| General Dynamics Corporation |
| Communications & Power Industries |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate price indices cascade through RF semiconductor fabrication into tiered antenna system pricing, compressing margins on military-grade phased arrays while enabling cost reductions in consumer broadband terminals through manufacturing scale economies.
Pricing Analysis
Warranty and multi-year maintenance bundling separates institutional procurement from unbundled commercial transactions, with NATO framework agreements commanding premium pricing for integrated service contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ESA-qualified ground segment equipment sits at premium tiers, while consumer broadband terminals compete on unit cost. Pricing pressure stems from gallium nitride substrate volatility feeding into active electronically scanned array production. Government and military buyers demonstrate lowest price sensitivity due to mission-critical requirements; telecommunication operators exhibit highest sensitivity as consumer broadband margins compress.
Supply Chain Analysis
Space-qualified radiation-hardened integrated circuit supply rests on limited European foundry capacity concentrated in France, Germany, and the Netherlands. RF semiconductor substrates, precision machining for parabolic reflectors, and metamaterial composite structures constitute critical input dependencies. Single-source vulnerability in radiation-hardened component supply chains creates concentration risk for institutional procurement timelines. Distribution runs through prime contractor captive channels for military applications and satellite service provider direct procurement for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where CE marking and RED certification through notified bodies erect six-to-twelve month barriers that favor established players with regulatory affairs infrastructure.
For Market Incumbents: Extend framework agreement positioning across NATO joint procurement structures to lock out emerging competitors lacking multi-national certification footprints. Deepen thermal engineering talent retention programs as the specialized active electronically scanned array workforce approaches retirement. Backward integration into gallium nitride substrate supply hedges margin compression from RF semiconductor volatility. For New Entrants and Emerging Players: Launch via ESA commercial partnership pathways for ground segment development, exploiting institutional qualification routes opened by public-private partnership expansion. Target Nordic defence modernisation in Sweden and Finland, where NATO accession unlocks previously restricted tactical communications procurement. Pursue metamaterial-enabled flat panel specializations where manufacturing scale economies are rewriting cost-performance trade-offs against established parabolic manufacturers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier technology providers with ESA qualification credentials in Germany and France, where consolidation pressure from prime contractor captive capabilities creates acquisition opportunities. Five-to-ten year viability hinges on positioning for EU Space Programme infrastructure buildout. Monitor gallium nitride substrate price stabilization as the inflection signal for phased array margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-National Certification Investment | Unlocks NATO framework agreement eligibility across UK, France, and Germany procurement streams. |
| Metamaterial Manufacturing Scale-Up | Enables flat panel cost penetration into maritime and aeronautical mobility segments. |
| Thermal Engineering Talent Acquisition | Secures scarce active electronically scanned array expertise concentrated among defence electronics veterans. |
| ESA Public-Private Partnership Entry | Opens institutional qualification routes for mid-tier providers without prime contractor captive status. |
| Gallium Nitride Supply Backward Integration | Hedges margin compression from substrate price volatility in military-grade phased array production. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with defence procurement officers, satellite prime contractor engineering directors, RF component procurement leads, and notified body certification managers. ESA procurement databases, NATO standardization agreement repositories, ANFR and BNetzA spectrum licensing records, and aerospace industry export statistics provided validation layers. Bottom-up antenna unit shipment estimates triangulated against top-down institutional budget allocations.
Segment-level modeling addressed product type, technology architecture, end-user category, and installation mobility across the analysis window. Country-specific procurement frameworks in France, Germany, the UK, Sweden, and Italy incorporated distinct regulatory timelines and vendor qualification requirements. CAGR derivation synthesized historical budget execution patterns with announced modernization program scopes. Gallium nitride substrate price trajectories and flat panel manufacturing yield curves informed technology transition assumptions.
The model assumes a particular technology adoption path; alternative pathways for optical-terrestrial hybrid terminals would alter the outlook for RF-dominant ground segment investment. Forecasts reflect assumptions regarding NATO joint procurement consolidation rates and EU Space Programme funding continuity. Alternative spectrum allocation decisions at the ITU level or extended CE marking timelines could revise equipment deployment schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
UK Satellite Imagery Services Market
Satellite
Remote Sensing Satellite Market
Satellite
Low-Cost Satellite Market
Satellite
North America Satellite IoT Market
Satellite
Indonesia Satellite Communications Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Sudan Satellite Transponder Market
Satellite
France Satellite Imagery Services Market
Satellite
Satellite Market
Satellite
Germany Satellite Connectivity Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Global Small Satellite Service Market
Satellite
Israel Satellite Communications Market
Satellite
Europe Satellite IoT Market
Satellite
Germany Satellite Communications Market
Satellite
UAE Satellite Communication Market