
 Africa Satellite Connectivity Market | 2026-2036
Africa Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Satellite Connectivity Market Analytics
ITU spectrum harmonization protocols for Ka and Ku bands is rebalancing the cost-of-entry calculus for constellation operators seeking African orbital slots. Starlink leverages its vertically integrated launch-to-terminal supply chain to undercut legacy geostationary providers on deployment timelines. Eutelsat Communications anchors its position through long-term broadcast contracts with Francophone state broadcasters and hybrid satellite-fiber networks. SES S.A. competes by specializing in government and maritime mobility segments where service-level agreements command premium pricing.
Africa satellite connectivity encompasses the delivery of broadband, voice, and broadcast services via geostationary, medium-Earth orbit, and low-Earth orbit satellite systems operating across C, Ku, Ka, and L frequency bands with throughput capacities ranging from megabits to multiple gigabits per second. These systems bridge infrastructure gaps where terrestrial fiber and cellular networks remain uneconomical, serving as primary backhaul for remote enterprises, government agencies, maritime vessels, and unserved residential populations. Data services dominates revenue contribution as enterprise cloud migration and mobile network operator backhaul expansion accelerate bandwidth consumption across the continent. Very High Throughput Satellites represent the fastest-expanding technology category, with spot-beam architectures enabling cost-per-bit reductions that challenge traditional fixed satellite services in price-sensitive African markets.
National regulators including Nigeria's NCC, South Africa's ICASA, and Kenya's CA shape market access through orbital slot coordination, landing rights, and equipment type-approval requirements that vary across jurisdictions. The African Telecommunications Union coordinates cross-border spectrum planning, though implementation lags in harmonizing priority bands for satellite broadband services. Stakeholders must monitor evolving national broadband strategies that designate satellite as either complementary infrastructure or direct competitor to state-backed fiber initiatives, with procurement decisions hinging on these policy designations.
Market Dynamics
Very High Throughput Satellite spot-beam architectures are compressing cost-per-bit economics and forcing legacy geostationary operators to restructure pricing models across East African markets.
Growth Catalysts
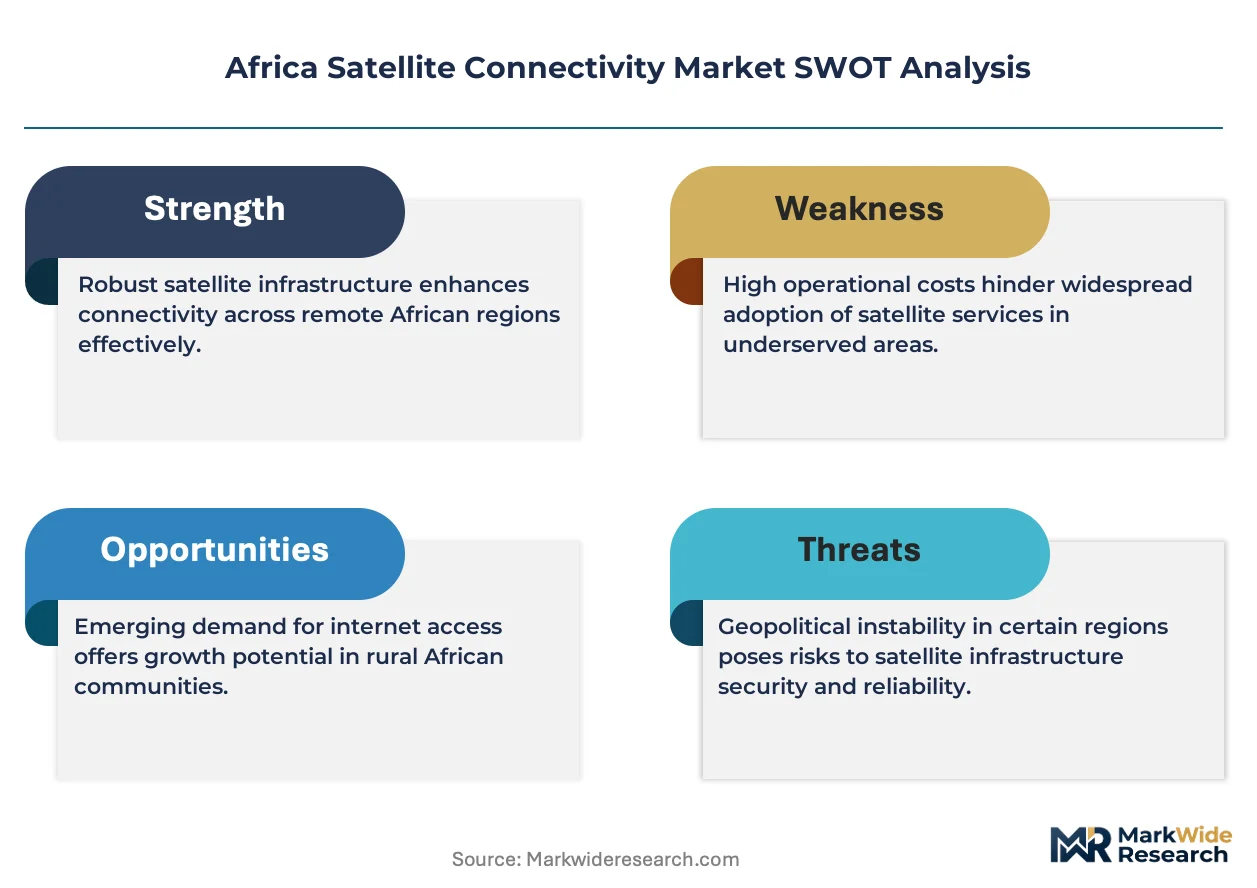
- Ka-band spectrum harmonization:ITU protocols are reducing orbital slot coordination friction for constellation operators seeking African landing rights. Kenya's Communications Authority has streamlined equipment type-approval timelines.
- Mobile network extension:Rural backhaul demand from Nigerian and Kenyan mobile operators is accelerating satellite bandwidth procurement for unserved cell towers.
- Telemedicine infrastructure:Healthcare networks in Kenya and Nigeria are deploying satellite-dependent remote diagnostics programs that require guaranteed uptime SLAs.
Market Restraints
- Launch cost concentration:Dependence on limited launch pad capacity and ride-share scheduling creates deployment timeline risk for constellation rollouts.
- Terminal hardware import duties:Nigeria's customs frameworks impose equipment levies that inflate consumer premise device costs relative to terrestrial alternatives.
- Fiber substitution in urban corridors:State-backed fiber initiatives in South African metropolitan zones are capturing enterprise customers that satellite previously served.
Strategic Opportunities
- Maritime mobility services:West African offshore oil platforms and fishing fleets represent underserved mobility segments requiring low-latency connectivity.
- Hybrid satellite-fiber procurement:Francophone state broadcasters are tendering integrated network architectures that combine geostationary capacity with terrestrial distribution.
- East African regulatory convergence:The African Telecommunications Union is coordinating cross-border spectrum planning that could reduce multi-jurisdiction licensing overhead.
Industry Challenges
- Satellite engineering talent scarcity:Constellation operators face recruitment bottlenecks for RF engineers and orbital mechanics specialists across the continent.
- Legacy broadcast integration:Migration from traditional C-band distribution to Ka-band spot-beam architectures requires customer-side hardware swaps that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Satellite Connectivity Market |
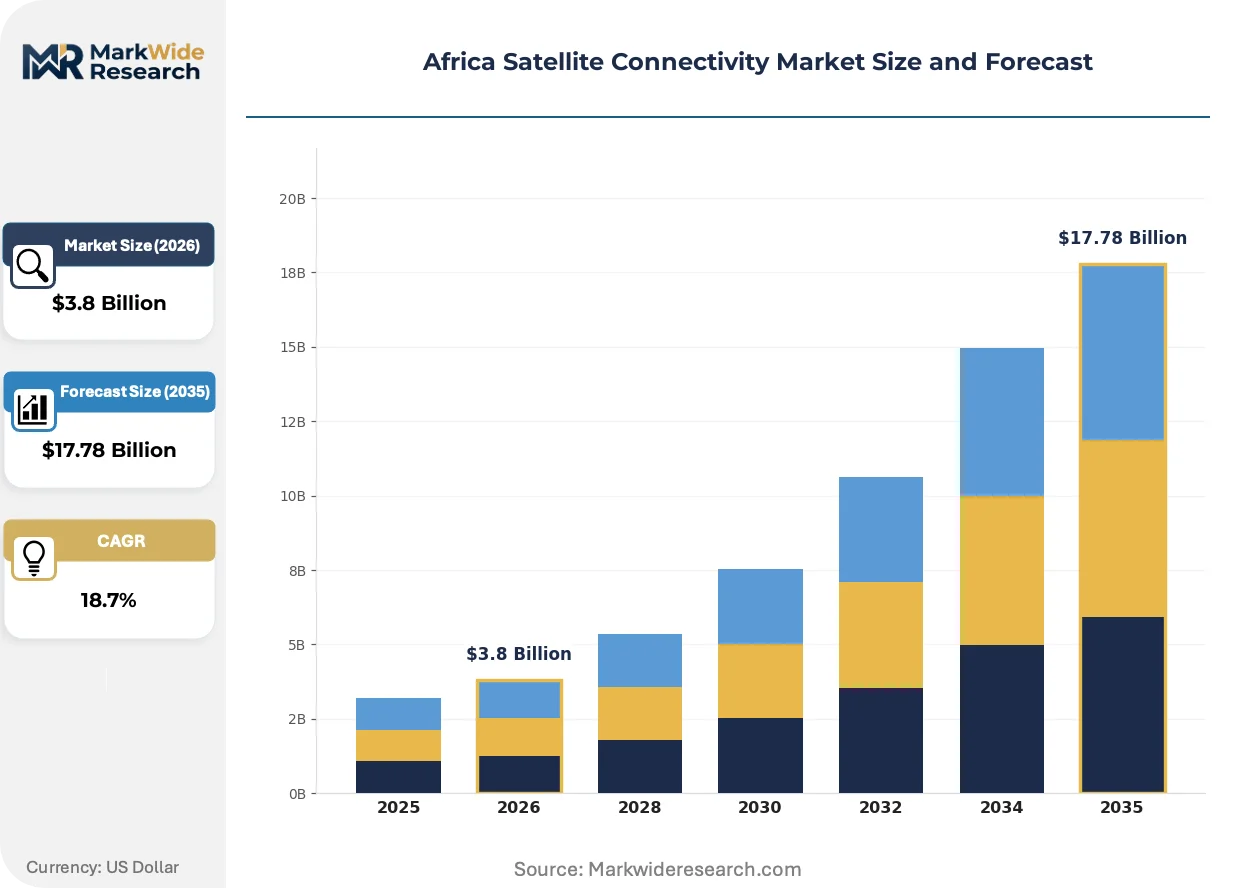
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Services, Voice Services, Video Services, Broadcasting Services End User: Government, Military, Maritime, Education Technology: Fixed Satellite Services, Mobile Satellite Services, Very High Throughput Satellites, Single Beam Systems Deployment: On-Premises, Cloud-Based, Hybrid Systems, Remote Locations |
| Companies Covered | OneWeb, Iridium Communications, Starlink, Viasat, Eutelsat Communications, SES S.A., Inmarsat, Gilat Satellite Networks, Amazon LEO, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Satellite Connectivity Market Evolving Landscape
Orbital slot competition and terrestrial infrastructure gaps are accelerating technology diversification across frequency bands and altitude regimes.
Software-defined payload architectures are modularizing satellite manufacturing timelines. Kenyan mobile network operators are procuring these flexible systems to match capacity deployment with cell tower backhaul ramp schedules. The technology is modularizing the traditional satellite procurement cycle from multi-year capital commitments to annual capacity leases.
South Africa's ICASA has implemented streamlined landing rights frameworks that compress foreign operator market entry timelines from 18 months to 9 months. The policy shift is redirecting constellation operator prioritization toward Southern African orbital slot coordination. Maritime and government mobility segments are responding by pre-positioning service agreements ahead of capacity availability.
Enterprise cloud migration patterns are fragmenting bandwidth procurement from centralized carrier contracts toward direct satellite operator relationships. Mining and agricultural operations in remote Nigerian and Kenyan territories are bypassing terrestrial resellers to negotiate dedicated beam capacity. This disintermediation is most visible in extractive industries where uptime penalties exceed terrestrial redundancy costs.
Africa Satellite Connectivity Market Segmentation
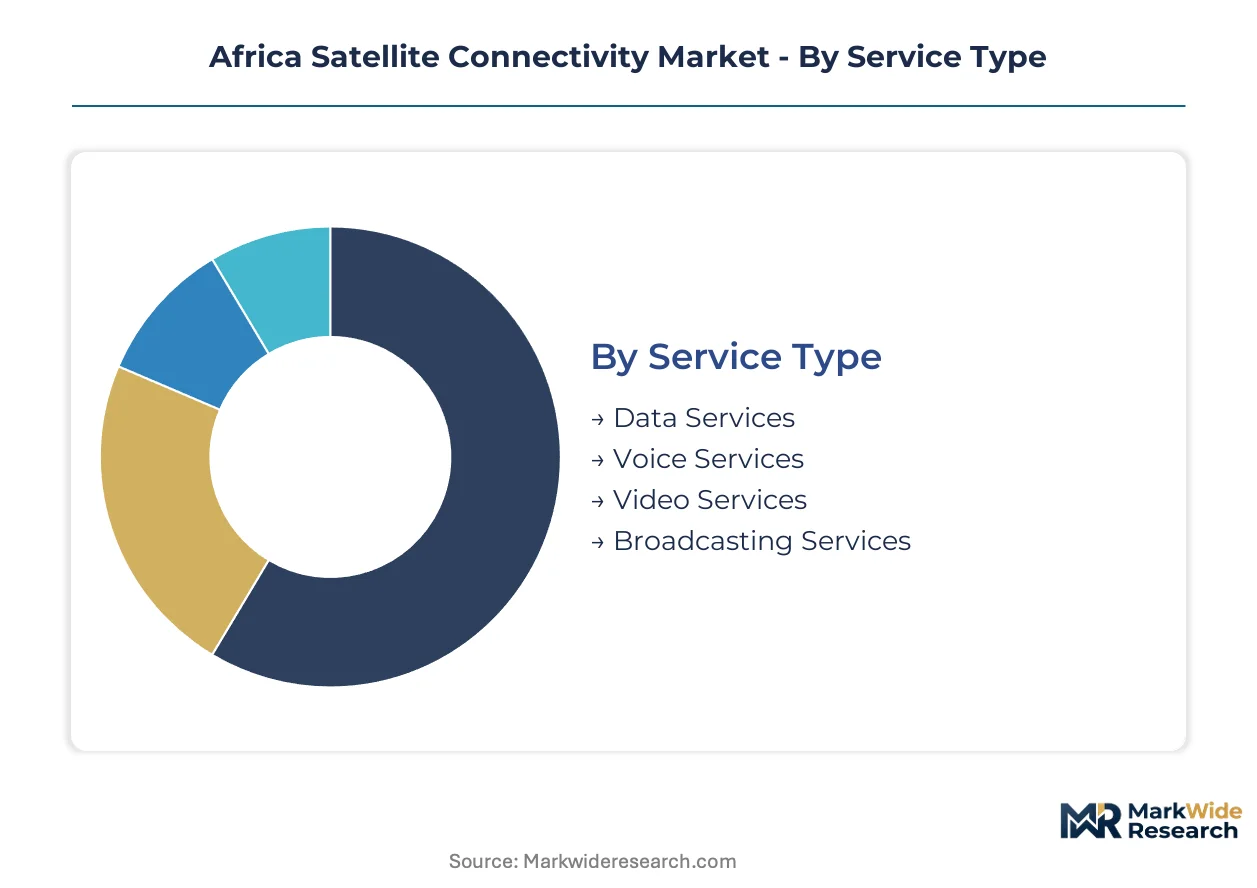
Satellite connectivity procurement in Africa fragments across service architectures, end-use requirements, and deployment topologies that each demand distinct capacity specifications and commercial terms. Understanding these segment boundaries clarifies where constellation operators must prioritize beam allocation and where legacy geostationary providers retain pricing power.
Service Type:
Upgrade cycles across service categories accelerate where terrestrial infrastructure gaps persist longest, with enterprise procurement shifting from bundled offerings toward discrete bandwidth commodities.
- Data Services:IP-based broadband delivery via Ka and Ku band spot-beams supports enterprise cloud migration and mobile network operator backhaul across East African fiber gaps. Mining operations in remote Nigerian territories negotiate dedicated beam capacity directly with operators, bypassing terrestrial resellers entirely.
- Voice Services:Circuit-switched and VoIP trunking for rural telephony networks and emergency communications. Kenyan healthcare networks deploy satellite-dependent voice backhaul for remote clinic coordination where cellular coverage terminates.
- Video Services:Contribution and distribution feeds for broadcasters and content aggregators. Francophone state broadcasters tender hybrid satellite-fiber architectures that blend geostationary capacity with terrestrial distribution nodes.
- Broadcasting Services:Direct-to-home and direct-to-premises television distribution. Long-term contracts with national broadcasters anchor revenue stability for established operators despite spot-beam competitive pressure.
Volume placements concentrate in Data Services; the faster expansion belongs to Video Services as streaming migration reshapes contribution network requirements.
End User:
Customer-type segmentation reveals where service-level agreement premiums offset higher per-bit costs and where standardized pricing dominates procurement.
- Government:Secure communications, disaster response networks, and rural administrative connectivity. Procurement prioritizes guaranteed uptime over cost optimization, with premium pricing attached to sovereign network requirements.
- Military:Tactical communications and intelligence, surveillance, and reconnaissance data exfiltration. Specialized frequency allocation and encryption mandates create vendor qualification barriers that limit competitive field.
- Maritime:Offshore platforms, fishing fleets, and merchant vessels traversing West African corridors. Oil majors pre-position service agreements ahead of capacity availability as ICASA streamlines landing rights timelines.
- Education:School connectivity initiatives and distance learning infrastructure. Universal service fund subsidization shapes procurement scale, with equipment cost sensitivity highest in this segment.
Margin capture peaks in Maritime; steepest expansion trajectory runs through Education as national broadband strategies designate satellite for school connectivity mandates.
Technology:
Architecture selection determines cost-per-bit economics and deployment flexibility, with spot-beam systems displacing traditional wide-beam coverage in price-sensitive applications.
- Very High Throughput Satellites:Spot-beam architectures enabling frequency reuse and gigabit-scale capacity per satellite. Kenyan mobile operators procure these flexible systems to match capacity deployment with cell tower backhaul ramp schedules.
- Fixed Satellite Services:Traditional geostationary wide-beam coverage for broadcast distribution and enterprise trunking. Long-term contract structures provide revenue predictability despite competitive pressure from lower-cost alternatives.
- Mobile Satellite Services:L-band and S-band systems for handheld and vehicular terminals. Maritime and aeronautical mobility segments drive procurement where continuous coverage across oceanic expanses remains essential.
- Single Beam Systems:Legacy architectures serving remote enterprise sites with predictable, low-variability bandwidth requirements. Migration to multi-beam alternatives accelerates as hardware refresh cycles mature.
Revenue concentration sits with Fixed Satellite Services; technology transition gains share fastest in Very High Throughput Satellites as spot-beam economics challenge legacy pricing models.
Deployment:
Topology selection reflects integration complexity with existing terrestrial infrastructure and regulatory constraints on data sovereignty and landing rights.
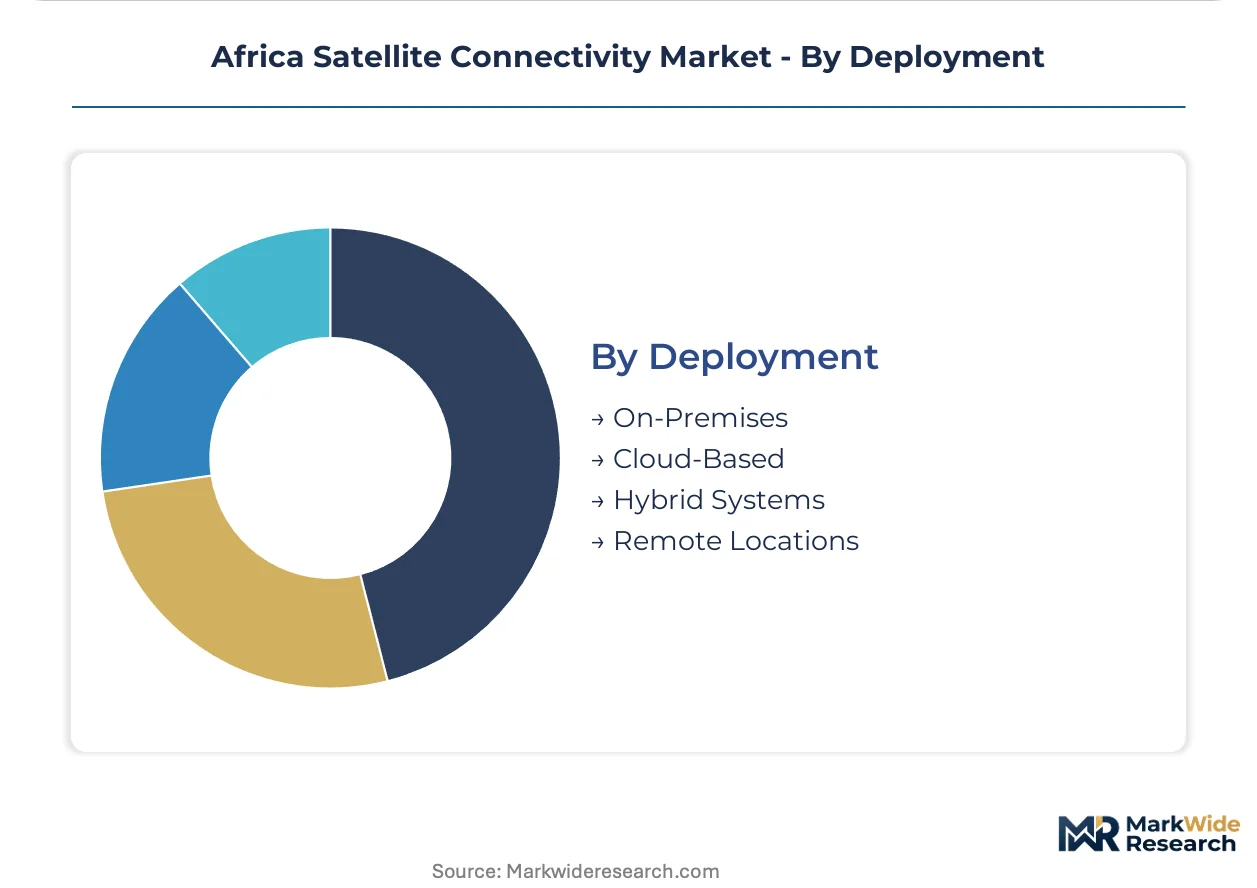
- Remote Locations:Standalone satellite terminals serving sites beyond terrestrial network economics. Agricultural and extractive operations in unserved Kenyan and Nigerian territories anchor demand.
- Hybrid Systems:Integrated satellite-terrestrial architectures that route traffic dynamically across available paths. Francophone broadcasters and mobile operators favor this approach for resilience and cost optimization.
- On-Premises:Customer-managed ground stations and terminal infrastructure. Government and military end-users mandate this topology for security and operational control.
- Cloud-Based:Satellite capacity delivered through managed service platforms with terrestrial handoff. Enterprise cloud migration patterns fragment procurement toward direct operator relationships in this configuration.
Deployment scale clusters in Remote Locations; Hybrid Systems are climbing the fastest as network architects prioritize resilience over single-path dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Africa concentrates satellite bandwidth procurement where fiber gaps and mobile network extension needs intersect most acutely. National regulators in Nigeria, Kenya, and South Africa are streamlining landing rights frameworks to attract constellation operators. Maritime corridors off West Africa and extractive operations in Central Africa generate specialized demand for low-latency mobility services.
Kenya
Rural healthcare networks and mobile operator backhaul expansion drive satellite procurement across unserved territories. The Communications Authority has compressed equipment type-approval timelines to accelerate terminal deployment. Nairobi anchors telemedicine program coordination while Mombasa maritime traffic generates mobility service demand.
Nigeria
Extractive industries in remote territories negotiate dedicated beam capacity directly with operators, bypassing terrestrial resellers entirely. The Nigerian Communications Commission shapes market access through orbital slot coordination and landing rights requirements. Lagos and Port Harcourt concentrate enterprise procurement for offshore oil platform connectivity.
South Africa
ICASA has implemented streamlined landing rights frameworks that compress foreign operator market entry timelines from 18 months to 9 months. State-backed fiber initiatives in metropolitan zones are capturing enterprise customers that satellite previously served. Cape Town and Johannesburg concentrate hybrid satellite-fiber procurement for broadcast distribution.
Ghana
Offshore oil platforms and fishing fleets traversing West African corridors generate underserved mobility segment demand. The National Communications Authority coordinates spectrum allocation for maritime connectivity services. Takoradi anchors pre-positioned service agreements for energy sector satellite procurement.
Ethiopia
Universal service fund subsidization shapes school connectivity procurement scale with high equipment cost sensitivity. The Ethiopian Communications Authority designates satellite as complementary infrastructure to state-backed fiber initiatives. Addis Ababa concentrates government and education segment coordination for rural administrative connectivity.
Africa Satellite Connectivity Market Competitive Landscape
European operators anchor one tier through long-term broadcast contracts and hybrid network architectures; American constellation specialists hold another through vertically integrated launch-to-terminal supply chains. The vendor base splits between legacy geostationary incumbents with revenue predictability and low-Earth orbit challengers compressing deployment timelines. Two strategic archetypes dominate: vertically integrated constellation operators and specialized government-maritime mobility providers. Competitive moves concentrate on spectrum coordination for African orbital slots and strategic partnerships with national broadcasters.
Among European-based operators, Eutelsat Communications and SES S.A. occupy positions within the established geostationary tier, representing archetypes of broadcast-anchored revenue stability. Starlink exemplifies the vertically integrated constellation model through its launch-to-terminal supply chain control. These three entities represent the competitive spectrum from legacy wide-beam coverage to spot-beam spot-beam architectures challenging traditional pricing models.
| Leading Market Players |
|---|
| OneWeb |
| Iridium Communications |
| Starlink |
| Viasat |
| Eutelsat Communications |
| SES S.A. |
| Inmarsat |
| Gilat Satellite Networks |
| Amazon LEO |
| Others |
Value Network & Pricing Analysis
Kenyan mobile operator backhaul procurement preferences for annual capacity leases rather than multi-year capital commitments are forcing satellite manufacturers to modularize production timelines and compress pricing structures. This demand-side shift toward operational expenditure models restructures how constellation operators contract launch capacity and terminal manufacturing.
Pricing Analysis
Volume capture concentrates in standardized data services while margin extraction persists in government and maritime segments where uptime guarantees command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates sovereign network requirements from enterprise cloud migration and residential broadband tiers. Cost compression in the economy tier intensifies because Starlink's vertically integrated supply chain undercuts legacy geostationary providers on deployment timelines. Education segments exhibit highest price sensitivity due to universal service fund dependency, while military and maritime buyers prioritize service-level agreement certainty over per-bit optimization.
Supply Chain Analysis
Equipment type-approval from Kenya's Communications Authority and South Africa's ICASA creates certification gating that filters terminal hardware suppliers. Manufacturing concentrates in the United States, France, and Luxembourg for satellite payloads and ground systems. Raw material dependencies span gallium arsenide semiconductors, carbon fiber composites, and rare earth magnets for propulsion systems. Single-source vulnerability runs through limited launch pad capacity at Cape Canaveral and Kourou. Distribution runs through national landing rights frameworks that require local partnerships for market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as Very High Throughput Satellite spot-beam economics force legacy wide-beam operators into defensive restructuring or exit. ITU spectrum harmonization protocols favor capital-rich constellation specialists with vertically integrated launch capabilities.
For Market Incumbents: Hedge against spot-beam displacement by securing long-term broadcast contracts with Francophone state broadcasters and hybrid satellite-fiber network tenders. Anchor revenue predictability through government and maritime mobility segments where service-level agreement premiums offset higher per-bit costs. Invest in software-defined payload architectures to modularize manufacturing timelines and match capacity deployment with buyer ramp schedules. For New Entrants and Emerging Players: The gap between premium sovereign network pricing and economy residential broadband tiers creates white-space opportunity in standardized enterprise data services for extractive industries. Target Nigerian mining operations and Kenyan agricultural cooperatives that bypass terrestrial resellers to negotiate dedicated beam capacity directly. Pursue regulatory convergence through African Telecommunications Union coordination to reduce multi-jurisdiction licensing overhead. For Investors and Strategic Acquirers: The window for entry favors vertically integrated constellation operators with captive launch capacity and terminal manufacturing control. Long-term viability hinges on spectrum coordination success for African orbital slots and strategic broadcaster partnerships. Watch for ICASA-equivalent regulatory streamlining in additional jurisdictions as the inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Coordination for Orbital Slots | ITU Ka-band harmonization protocols reduce landing rights friction for constellation operators seeking African market entry. |
| Hybrid Satellite-Fiber Network Deployment | Francophone state broadcasters tender integrated architectures combining geostationary capacity with terrestrial distribution nodes. |
| Software-Defined Payload Manufacturing | Kenyan mobile operators procure flexible systems matching capacity deployment with cell tower backhaul ramp schedules. |
| Maritime Mobility Service Pre-Positioning | Oil majors secure service agreements ahead of capacity availability as ICASA streamlines landing rights timelines. |
| Direct Enterprise Beam Capacity Negotiation | Nigerian mining operations bypass terrestrial resellers to negotiate dedicated capacity with satellite operators. |
Research Methodology
Document review covered satellite operator landing rights filings, national spectrum allocation decrees, and African Telecommunications Union coordination protocols, complemented by interviews with mobile network operator procurement directors, satellite payload engineering leads, national regulatory authority spectrum managers, and maritime connectivity service heads. Secondary validation drew from ITU orbital slot registries, national communications commission annual reports, and customs equipment import data. Bottom-up capacity deployment tracking and top-down bandwidth demand estimation were triangulated against disclosed contract values.
Segment-level outputs across service type, end user, technology, and deployment topology dimensions were generated through structured modeling. CAGRs were derived from capacity deployment schedules, terminal shipment trajectories, and bandwidth pricing trend analysis. Forecast inputs incorporated mobile network extension timelines for unserved cell towers, telemedicine infrastructure rollout commitments, and state-backed fiber initiative coverage maps.
Inputs from Kenyan Communications Authority type-approval databases and Nigerian Communications Commission licensing records were available through the study window; gaps in proprietary contract terms for government and military segments introduce uncertainty bands around revenue concentration estimates. Forecasts reflect assumptions regarding ITU protocol implementation timelines and national broadband strategy designations. A model refresh is warranted upon material change in African Telecommunications Union cross-border spectrum coordination progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Japan Satellite Communication Market
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Europe Satellite IoT Market
Satellite
Global Enterprise VSAT System Market
Satellite
China Satellite Imagery Services Market
Satellite
North America Remote Sensing Satellites Market
Satellite
Global Small Satellite Service Market
Satellite
Germany Satellite-Based Earth Observation Market
Satellite
Satellite Sensor Market
Satellite
Satellite Photography Service Market
Satellite
Europe Military Satellite Market
Satellite
North America Military Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Russia Satellite Imagery Services Market