
 Asia-Pacific Data Center Storage Market | 2026-2036
Asia-Pacific Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Storage Market Insights
The gap between all-flash enterprise arrays and bulk HDD archives is restructuring procurement patterns across Asia-Pacific. Huawei Technologies leverages its integrated chip-to-system stack to dominate domestic Chinese deployments. Dell Inc. anchors premium enterprise contracts through direct sales and service density in Australia and Japan. Seagate Technology LLC sustains its position in nearline HDD volumes by controlling manufacturing scale for hyperscaler tenders.
Asia-Pacific data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, typically measured by IOPS density, latency thresholds, and petabyte-scale rack efficiency in climate-controlled facilities. These systems serve cloud operators, financial institutions, and telecom carriers requiring continuous availability for transactional and analytical workloads. SSD deployments within the technology dimension command attention as NAND cost curves and endurance specifications improve, while hybrid storage configurations retain structural importance for tiered economics. Cloud storage under product type expands fastest where regional operators pursue multi-tenant architectures, though storage area network installations persist in BFSI end-user settings governed by data sovereignty requirements.
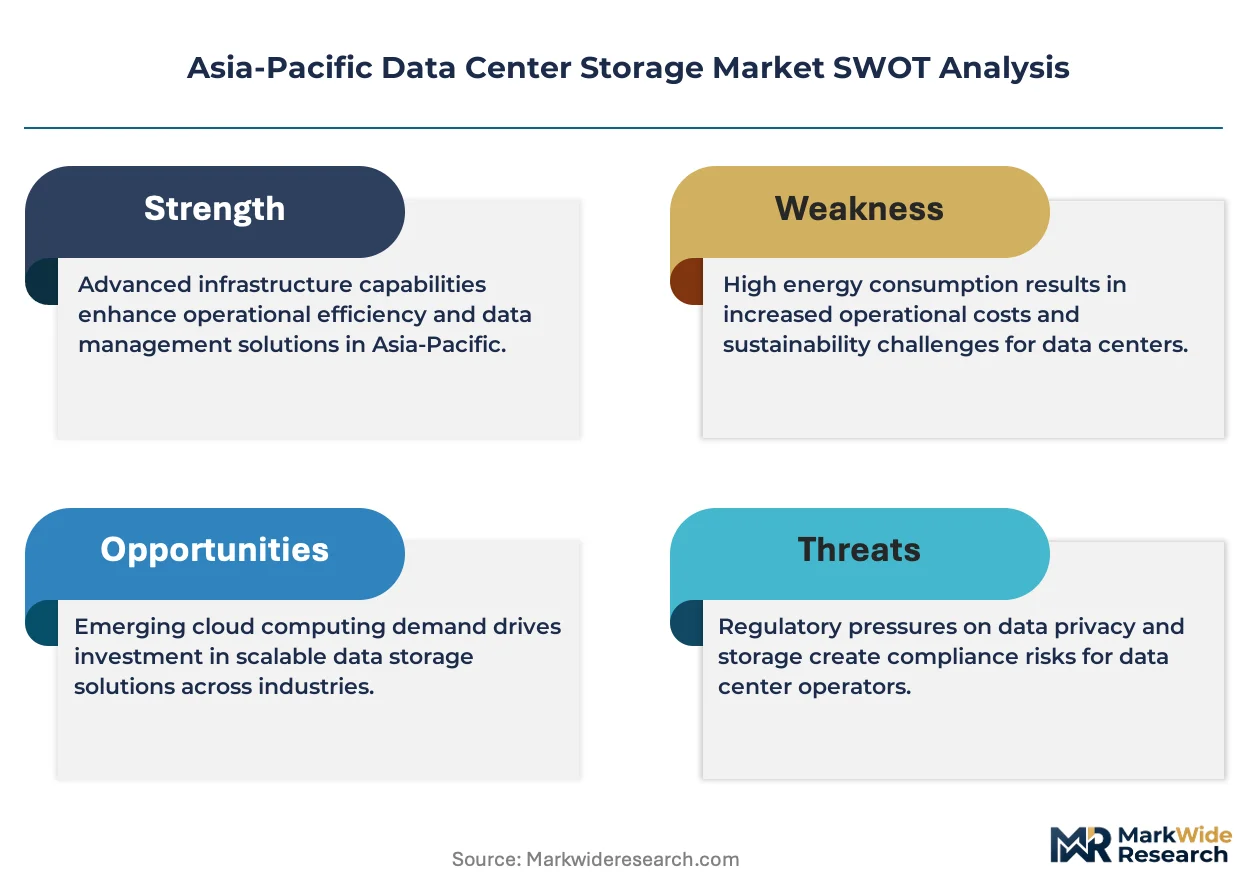
China's MIIT enforces GB standards for data center power usage effectiveness that directly constrain storage hardware selection. India's BIS certification and PLI scheme for electronics manufacturing shape import substitution trajectories for domestic assemblers. Japan's METI energy-efficiency benchmarks for data infrastructure influence procurement specifications for Tokyo and Osaka facilities. Stakeholders must weigh regulatory divergence against platform standardization as they allocate capital across national deployment footprints.
Market Dynamics
Hyperscaler procurement consolidation across the Asia-Pacific region is compressing supplier margins while favoring vertically integrated storage vendors capable of delivering petabyte-scale deployments with embedded power efficiency guarantees. This concentration dynamic restructures competitive positioning away from channel-driven distribution toward direct enterprise contracting.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Domestic assembly incentives reduce landed costs for SSD and HDD components, accelerating hyperscaler capacity buildouts in the Mumbai-Pune corridor.
- Cloud service provider expansion:Multi-tenant architectures across Southeast Asia drive demand for software-defined storage pools optimized for variable workload density.
- China's dual carbon goals:MIIT-enforced power usage effectiveness standards mandate energy-efficient storage hardware selection, favoring all-flash arrays over legacy electromechanical systems.
Market Restraints
- NAND flash supply concentration:Fabrication capacity constraints in South Korea and Taiwan create input cost volatility for SSD-dependent storage architectures.
- GB standards compliance friction:China's MIIT certification timelines extend procurement cycles for foreign storage vendors seeking domestic data center deployment rights.
- Nearline HDD technical limitation:Areal density plateaus in electromechanical storage constrain rack efficiency gains for archival-tier workloads.
Strategic Opportunities
- Indonesia's underpenetrated cloud infrastructure:Jakarta-Batam corridor data center buildouts lack mature storage supplier ecosystems, creating first-mover positioning for integrated solution providers.
- AI training workload convergence:GPU cluster deployments across China's Greater Bay Area demand high-throughput NVMe storage fabrics with sub-millisecond latency specifications.
- Japan's METI energy-efficiency benchmarks:Tokyo and Osaka facility procurement specifications reward storage vendors with verified carbon footprint disclosures.
Industry Challenges
- Embedded firmware engineering talent scarcity:Controller design and flash translation layer optimization expertise concentrates in Shenzhen and Hsinchu, constraining vendor R&D scaling.
- BIS certification timeline compression:India's import substitution mandates require accelerated testing cycles that strain quality assurance bandwidth for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Storage Market |
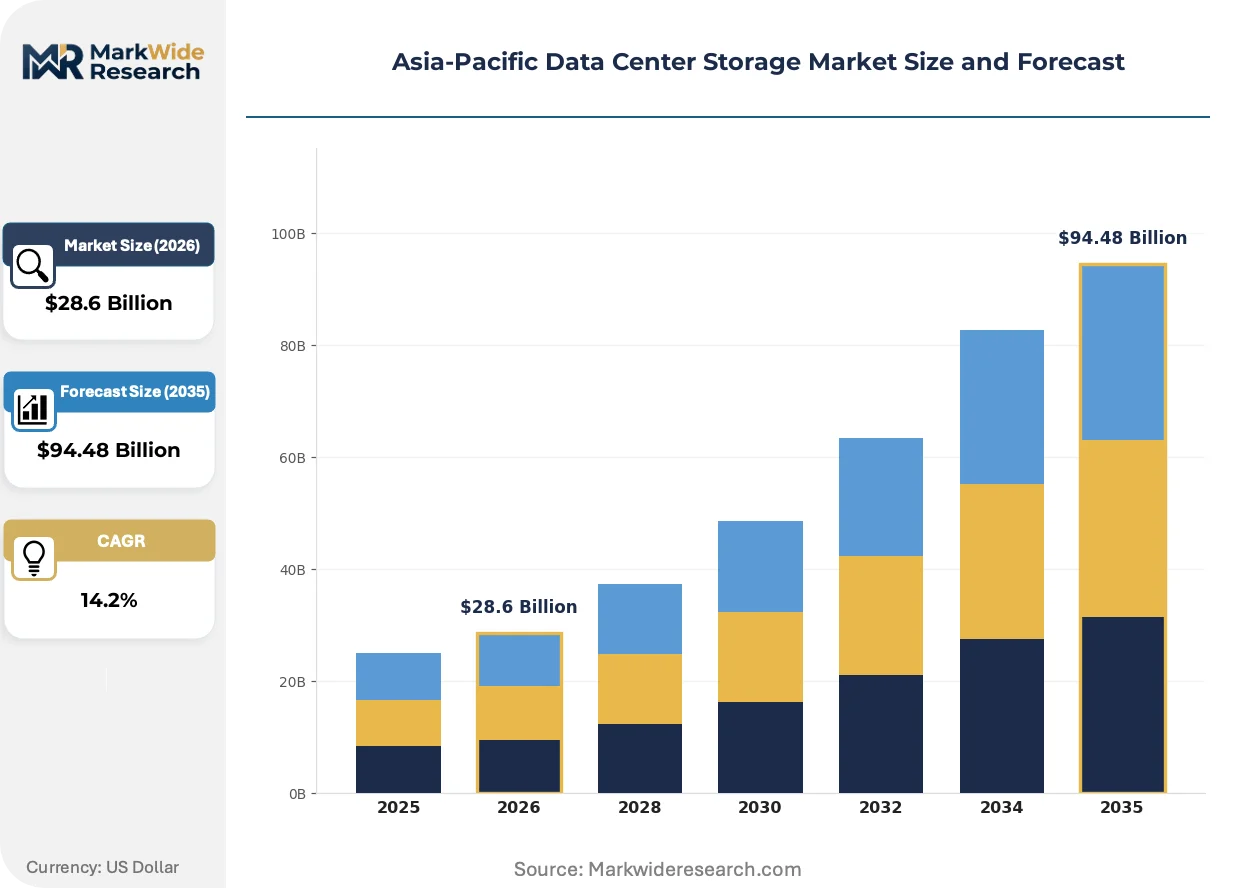
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Cloud Storage Technology: SSD, HDD, Hybrid Storage, Tape Storage End User: IT & Telecom, BFSI, Healthcare, Retail Form Factor: Rack-mounted, Tower, Blade, Modular |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies, Hitachi Vantara LLC, Lenovo Group Limited, Fujitsu Limited, Seagate Technology LLC, IBM, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Storage Market Trends and Innovations
Storage-class memory architectures are compressing the latency gap between DRAM and NAND, enabling new tiering strategies that reshape capital allocation across Asia-Pacific data center portfolios. This technological inflection favors vendors with in-house controller design capabilities.
QLC NAND with 1xx-layer vertical stacking is overtaking TLC configurations for read-intensive cloud storage tiers. Hyperscalers in India and Southeast Asia are adopting QLC-based all-flash arrays for warm data lakes. This density improvement is overtaking hybrid HDD-SSD architectures in procurement specifications for workloads with sub-5% write amplification.
China's MIIT enforces GB 40879-2021 data center power usage effectiveness standards that constrain storage hardware thermal envelopes. Foreign vendors must redesign chassis airflow and power supply efficiency to maintain domestic deployment eligibility. BFSI end-users in Shanghai and Beijing facilities are responding by specifying storage systems with embedded liquid cooling readiness.
Hyperscalers are consolidating storage procurement through framework agreements that unbundle hardware from professional services. Direct vendor relationships are displacing systems integrator intermediaries for petabyte-scale deployments. This channel compression is most visible in Australia's Sydney-Melbourne corridor where cloud operators negotiate consolidated supply contracts spanning compute, networking, and storage infrastructure.
Asia-Pacific Data Center Storage Market Segmentation
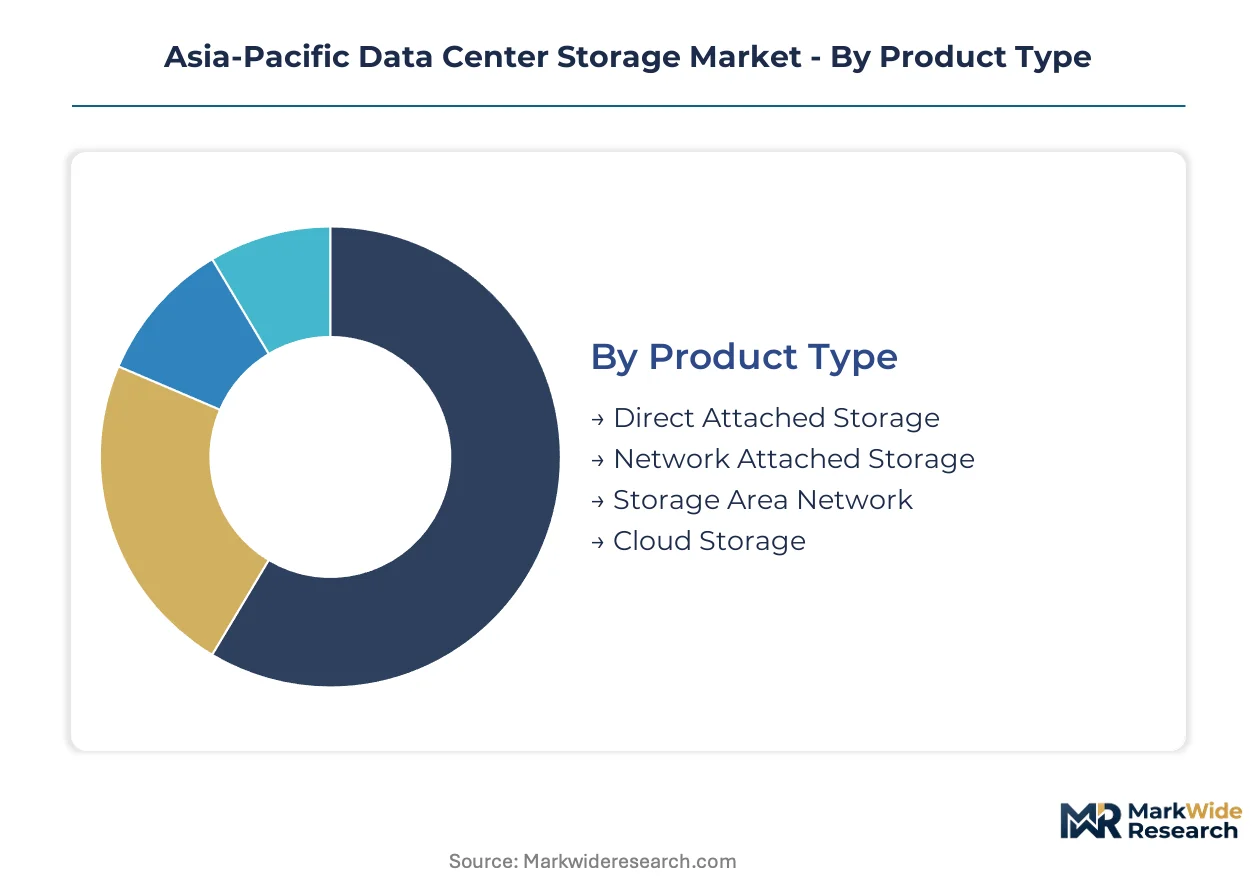
Storage procurement across Asia-Pacific clusters around workload-specific architectures that trade off latency, density, and sovereignty compliance. Upgrade cycles vary sharply by technology layer, with flash arrays refreshing faster than electromechanical archives.
Product Type:
Replacement timelines diverge most sharply across deployment architectures, with cloud-native configurations demanding continuous refresh versus on-premise systems running extended depreciation schedules.
- Direct Attached Storage:Localized storage directly integrated with single servers, optimized for low-latency transactional workloads. Financial institutions in Tokyo and Singapore specify DAS for high-frequency trading infrastructure where microseconds determine execution quality.
- Network Attached Storage:File-level storage accessed over standard network protocols, serving distributed creative and engineering workflows. Media production houses in Seoul and Sydney deploy NAS clusters for 4K/8K video rendering pipelines requiring shared access without SAN complexity.
- Storage Area Network:Block-level storage fabrics with dedicated high-speed interconnects. BFSI operators in Mumbai and Shanghai maintain SAN installations for core banking databases governed by strict data residency mandates.
- Cloud Storage:Multi-tenant object and block services delivered over API interfaces. Hyperscalers in Indonesia and Vietnam are scaling cloud storage pools ahead of domestic enterprise migration curves.
Cloud Storage sits at the top of the volume ranking, with Direct Attached Storage climbing the fastest.
Technology:
Cost tier stratification determines procurement sequencing, with premium solid-state layers commanding budget priority over archival electromechanical tiers.
- SSD:NAND-based solid-state drives with no moving parts, delivering sub-millisecond latency and high IOPS density. All-flash arrays dominate new deployments in China's Greater Bay Area where MIIT power efficiency standards penalize electromechanical alternatives.
- HDD:Electromechanical drives with rotating platters, offering cost-per-terabyte advantages for sequential read workloads. Nearline HDD volumes concentrate in Indian hyperscaler tenders where the PLI scheme reduces landed costs for domestic assembly.
- Hybrid Storage:Tiered architectures combining flash caching with HDD capacity layers. Australian enterprise data centers specify hybrid configurations for mixed workload environments balancing performance and capital efficiency.
- Tape Storage:Magnetic tape systems for long-term archival and air-gapped compliance. Japanese financial institutions maintain tape libraries for regulatory retention periods exceeding seven years.
HDD maintains the highest shipment volumes, though SSD is expanding most quickly across procurement specifications.
End User:
Application criticality shapes investment intensity, with latency-sensitive verticals outsping batch-oriented sectors on a per-petabyte basis.
- IT & Telecom:Cloud operators and carriers requiring continuous availability for subscriber-facing services. Southeast Asian telecoms are consolidating storage infrastructure around software-defined pools supporting 5G core network functions.
- BFSI:Banking, financial services, and insurance with stringent recovery point objectives. Singaporean wealth management platforms specify synchronous replication across geographically separated storage arrays.
- Healthcare:Medical imaging and electronic health record systems with exponential data growth. Australian hospital networks are migrating PACS archives to object storage with embedded encryption for patient privacy compliance.
- Retail:E-commerce and supply chain analytics with seasonal demand volatility. Indian retail platforms deploy elastic cloud storage for festival-period traffic spikes in the Mumbai-Pune corridor.
IT & Telecom commands the largest capacity allocation, with Healthcare gaining share fastest on imaging data expansion.
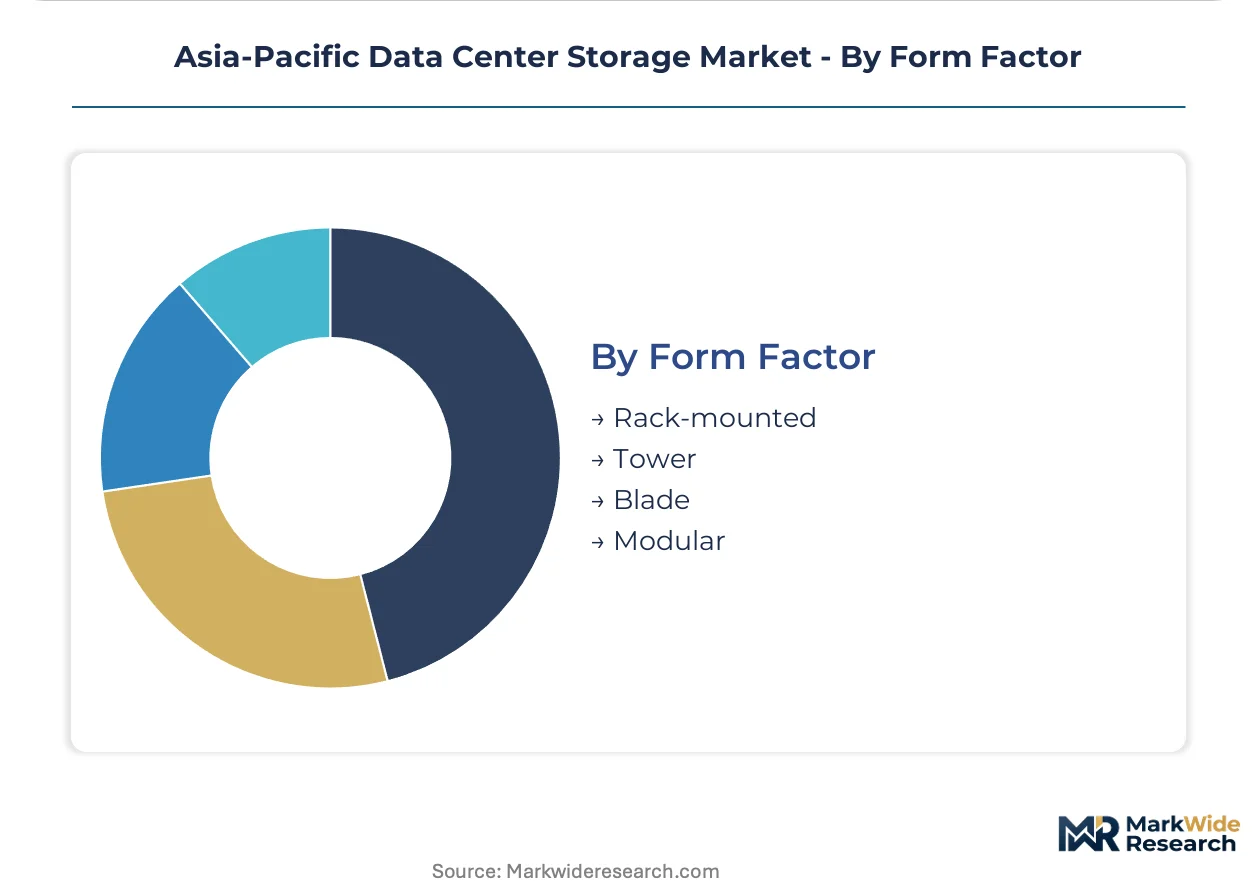
Form Factor:
Physical density requirements vary by facility constraints, with space-constrained metropolitan clusters favoring compact configurations over expandable tower alternatives.
- Rack-mounted:Standard 19-inch chassis designed for data center rack integration, maximizing floor space efficiency. Standard deployments across Tokyo and Osaka facilities where METI energy benchmarks reward optimized airflow designs.
- Tower:Vertical standalone enclosures for edge and remote office deployments. Branch banking locations in Indonesia specify tower configurations for limited-footprint server rooms lacking raised floor infrastructure.
- Blade:High-density modular servers with integrated storage sleds. Chinese internet companies deploy blade chassis in hyperscale campuses for homogeneous workload consolidation.
- Modular:Scalable enclosures supporting disaggregated compute and storage expansion. Australian co-location providers specify modular architectures for multi-tenant flexibility across Sydney-Melbourne corridors.
Rack-mounted systems dominate installed base, with Modular configurations climbing fastest on disaggregation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller design and flash translation layer expertise concentrates in Shenzhen and Hsinchu, anchoring regional R&D capacity for storage subsystem development. This talent distribution shapes procurement patterns across national deployment footprints.
China
Hyperscaler buildouts in the Greater Bay Area drive petabyte-scale storage demand for AI training clusters. MIIT enforces GB 40879-2021 power usage effectiveness standards that constrain thermal envelopes for data center hardware. Beijing and Shanghai facilities increasingly specify all-flash arrays with liquid cooling readiness to maintain deployment eligibility.
India
Cloud service provider expansion concentrates capacity growth in the Mumbai-Pune corridor. BIS certification timelines and PLI scheme incentives for electronics manufacturing accelerate domestic assembly of SSD and HDD components. Domestic assemblers leverage reduced landed costs to capture hyperscaler tender volumes.
Japan
Financial institutions in Tokyo and Osaka maintain strict recovery point objectives for core banking infrastructure. METI energy-efficiency benchmarks for data infrastructure reward vendors with verified carbon footprint disclosures. Kanto region facilities lead procurement of synchronous replication systems across geographically separated arrays.
Australia
Enterprise data centers in the Sydney-Melbourne corridor specify hybrid storage configurations for mixed workload environments. Cloud operators negotiate consolidated framework agreements that unbundle hardware from professional services. Co-location providers favor modular architectures supporting disaggregated compute and storage expansion.
Singapore
Wealth management platforms and regional headquarters operations demand strict data residency compliance for transactional storage. BFSI operators specify SAN installations governed by sovereignty requirements for cross-border data flows. The city-state serves as a procurement hub for Southeast Asian cloud infrastructure buildouts.
Asia-Pacific Data Center Storage Market Competitive Landscape
Top-tier vendors anchor premium enterprise contracts through direct sales density, while mid-tier specialists compete on modular configurations and regional service reach. The vendor base stratifies across integrated chip-to-system stacks, electromechanical volume manufacturing, and software-defined storage platforms. Three archetypes dominate: vertically integrated domestic champions, multinational enterprise incumbents with service networks, and component-scale manufacturers serving hyperscaler tenders. Competitive moves center on direct contracting displacement of channel intermediaries and petabyte-scale deployment guarantees with embedded power efficiency specifications.
Among Asia-Pacific-based technology conglomerates, Huawei Technologies and Fujitsu Limited occupy positions as integrated domestic champions with captive semiconductor capabilities. Dell Inc. anchors the multinational enterprise tier through Australia and Japan service density. Seagate Technology LLC exemplifies the component-scale archetype controlling manufacturing scale for nearline HDD hyperscaler tenders. These three represent distinct competitive vectors: integrated stack control, premium service anchoring, and volume manufacturing scale.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies |
| Hitachi Vantara LLC |
| Lenovo Group Limited |
| Fujitsu Limited |
| Seagate Technology LLC |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler framework agreements across the Asia-Pacific region concentrate procurement leverage among cloud operators in India's Mumbai-Pune corridor and China's Greater Bay Area, compressing supplier margins and forcing unbundled hardware pricing models that separate professional services from equipment costs. This buyer concentration reshapes vendor economics toward direct enterprise contracting with embedded power efficiency guarantees.
Pricing Analysis
Unbundled hardware-from-services pricing dominates petabyte-scale tenders, with three-tier pricing structure across premium, standard, and economy levels differentiating on MIIT certification tier and liquid cooling readiness. Cost compression in standard-tier SSD arrays intensifies because NAND flash supply volatility from South Korean and Taiwanese fabrication constraints feeds through to module pricing. Hyperscalers in Indonesia and Vietnam exhibit highest price sensitivity, while Japanese BFSI operators in Tokyo and Osaka facilities prioritize synchronous replication capabilities over per-terabyte cost.
Supply Chain Analysis
MIIT GB standards certification and BIS import qualification gating extend procurement cycles, with controller design and flash translation layer expertise anchored in Shenzhen and Hsinchu. NAND wafer supply draws from South Korean and Taiwanese fabrication facilities, while nearline HDD assembly concentrates in Thai and Malaysian plants serving Indian hyperscaler tenders. Single-source vulnerability in advanced NAND lithography equipment creates supply chain risk. Distribution runs through direct vendor relationships displacing systems integrator intermediaries for petabyte-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific data center storage market functions as a stable compounder, with cloud service provider capacity expansion across Southeast Asia providing steady demand tailwinds through the projection horizon.
For Market Incumbents: To counter hyperscaler procurement consolidation compressing margins, Dell Inc. and Huawei Technologies should deepen direct sales density in Australia and Japan while embedding liquid cooling readiness in chassis designs to maintain MIIT deployment eligibility. Controller design capability in Shenzhen and Hsinchu represents the critical lever for flash translation layer optimization defending premium positioning. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest-friction entry into Indonesia's underpenetrated Jakarta-Batam corridor, where mature storage supplier ecosystems remain absent. AI training workload convergence in China's Greater Bay Area presents white-space targeting for NVMe fabric specialists. Modular architecture positioning serves Australian co-location providers seeking disaggregated compute-storage flexibility. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space, seeking captive storage technology to secure supply chain control. Long-term viability hinges on in-house controller design capability spanning the 5-10 year technology transition. Watch for QLC NAND adoption inflection in Indian and Southeast Asian hyperscaler specifications as signal of tiering architecture shift.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Enterprise Contracting | Hyperscaler framework agreements in Sydney-Melbourne corridor displace channel intermediaries for consolidated infrastructure supply. |
| Liquid Cooling Integration | MIIT GB 40879-2021 compliance in Beijing and Shanghai facilities mandates thermal envelope redesign for deployment eligibility. |
| Controller Design Capability | In-house flash translation layer expertise in Shenzhen and Hsinchu anchors competitive differentiation for solid-state architectures. |
| PLI Scheme Localization | Domestic SSD and HDD assembly in India's Mumbai-Pune corridor reduces landed costs capturing hyperscaler tender volumes. |
| Software-Defined Storage Platforms | Southeast Asian telecom 5G core consolidation around software-defined pools enables multi-tenant workload density optimization. |
Research Methodology
Bottom-up hyperscaler capacity modeling reconciled against top-down NAND wafer supply tracking forms the analytical core, combining primary interviews with cloud procurement officers, data center facility managers, storage subsystem engineers, and channel distribution heads with secondary validation against MIIT GB standard filings, BIS certification registries, hyperscaler capex disclosures, and customs import data for SSD and HDD components.
Historical hyperscaler deployment trendlines across technology layers inform the projection framework, with segmentation modeling across product type, storage technology, end-user vertical, and form factor dimensions throughout the forecast period. CAGRs derive from capacity expansion trajectories in named metropolitan corridors, NAND cost curve assumptions, and regulatory compliance timeline impacts on procurement cycles.
The model assumes a particular technology adoption path; alternative pathways for storage-class memory architectures would alter the outlook. Forecasts reflect assumptions regarding hyperscaler consolidation momentum, NAND supply concentration stability, and regulatory divergence across national certification regimes. A model refresh is warranted upon material change in China's dual carbon goal enforcement intensity or India's PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
NAND Flash Memory Market
Data Storage
Next-Generation Storage Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Serial EEPROM Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Flash Memory Market
Data Storage
Zoned Flash Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Storage and Management Market
Data Storage
NAND Flash Market
Data Storage
Data Center Ssds Market
Data Storage
Ethernet Storage Market
Data Storage
Optical Disk Market
Data Storage
OTG Pen Drive Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Europe Next Generation Storage Market