
 Ireland Data Center Storage Market | 2026-2036
Ireland Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Storage Market Insights
NVMe-over-Fabrics architecture is reshaping how Irish data centers architect their storage tiers, collapsing latency boundaries between compute and persistent media. Dell Inc. leverages its PowerMax and PowerStore portfolios to anchor enterprise deployments across Dublin's hyperscale corridor. Pure Storage Inc. specializes in all-flash arrays that compete on density and energy efficiency for sustainability-conscious operators. Huawei Technologies Co. Ltd. extends its OceanStor line to occupy positions in telecommunications and cloud service provider facilities.
Ireland Data Center Storage encompasses electromechanical and solid-state systems designed for persistent data retention in climate-controlled facilities, spanning capacities from terabyte-scale direct attached units to multi-petabyte object storage clusters operating at sub-millisecond latency. These systems serve cloud computing, enterprise backup, and real-time analytics workloads requiring 99.999% availability. Flash Storage commands premium positioning for latency-sensitive applications, while Hybrid Storage captures mid-tier deployments balancing cost and performance. Object Storage grows fastest for unstructured data lakes serving Big Data Analytics and long-term Cloud Storage archives.
The Environmental Protection Agency enforces Ireland's Industrial Emissions Directive compliance for large data center operators, while the Commission for Regulation of Utilities oversees grid connection agreements that constrain power availability for new builds. The EU Energy Efficiency Directive mandates granular metering and PUE reporting that shapes procurement specifications toward lower-wattage storage technologies. Stakeholders must monitor carbon border adjustments and renewable power purchase agreement availability as determinants of site selection and technology refresh cycles.
Market Dynamics
NVMe-over-Fabrics architecture is collapsing latency boundaries between compute and persistent media across Irish facilities, forcing wholesale redesigns of storage tiering strategies as hyperscale operators demand sub-millisecond response times for real-time analytics workloads.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates granular metering and PUE reporting that push procurement toward flash-based and liquid-cooled storage systems with lower wattage profiles.
- Hyperscale cloud operators:Expansion in Dublin's Ashburn-style corridor creates concentrated demand for multi-petabyte object storage clusters serving AI training and inference pipelines.
- Big Data Analytics:Unstructured data lakes for machine learning and real-time processing drive fastest adoption of high-density all-flash arrays in County Dublin facilities.
Market Restraints
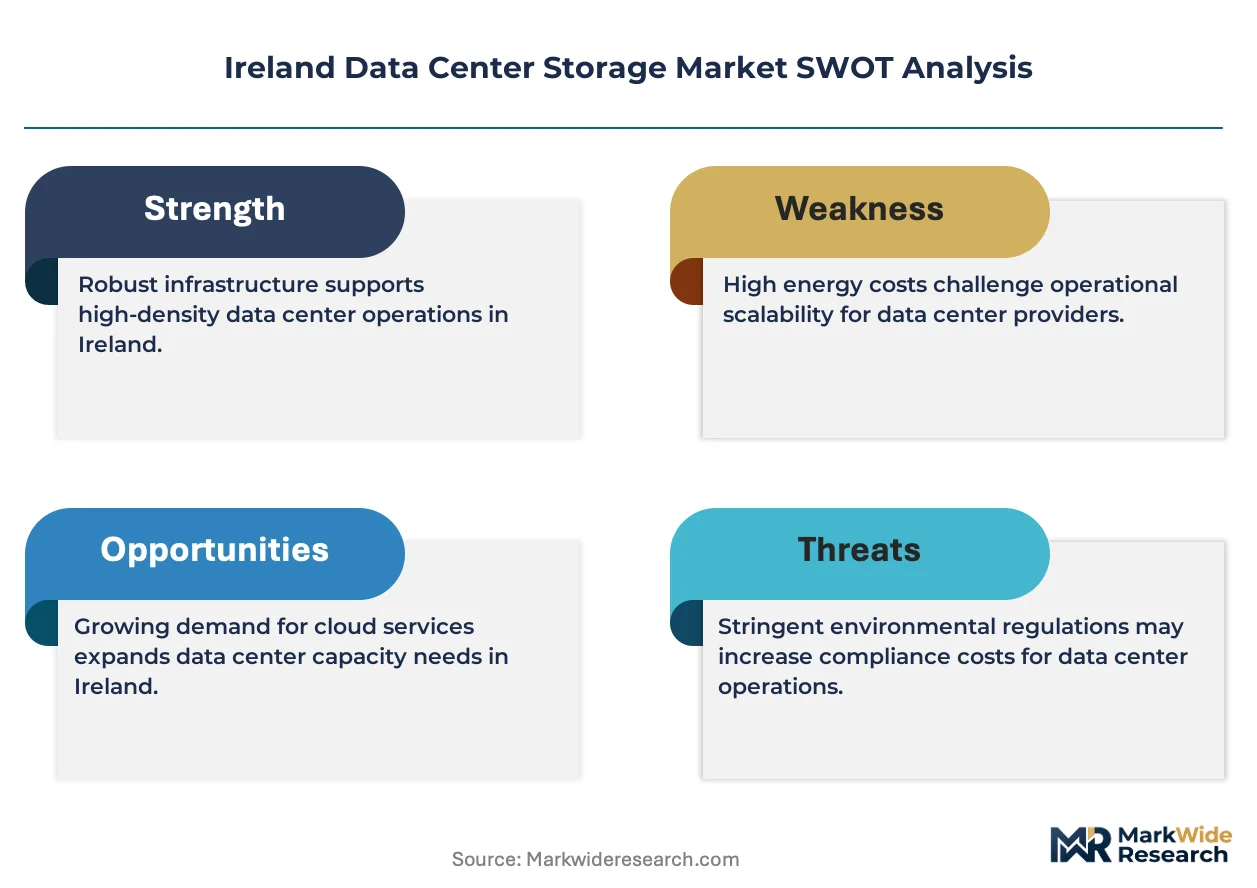
- Grid connection constraints:The Commission for Regulation of Utilities limits power availability for new builds, capping storage expansion in the Ashburn corridor despite latent demand.
- Flash memory supply concentration:NAND fabrication concentrates in East Asian foundries, exposing Irish operators to input cost volatility and geopolitical supply disruptions.
- Carbon border adjustment exposure:EU carbon border mechanisms threaten to inflate equipment import costs for storage hardware sourced from carbon-intensive manufacturing regions.
Strategic Opportunities
- Cork and Limerick secondary sites:Emerging data center clusters outside Dublin offer lower land costs and available grid capacity for distributed storage architectures.
- Renewable power purchase agreements:Ireland's national carbon targets create regulatory tailwinds for operators securing green energy contracts that favor energy-efficient flash storage procurement.
- AI inference at the edge:Convergence of NVMe-over-Fabrics with 5G infrastructure enables low-latency storage deployment for telecommunications and content delivery networks.
Industry Challenges
- Liquid cooling integration:Retrofitting existing air-cooled facilities with immersion or direct-to-chip cooling requires complex mechanical reconfiguration and extended deployment timelines.
- Legacy SAN migration:Enterprise customers face operational friction transitioning from traditional Fibre Channel architectures to NVMe-based fabrics without disrupting 99.999% availability SLAs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Storage Market |
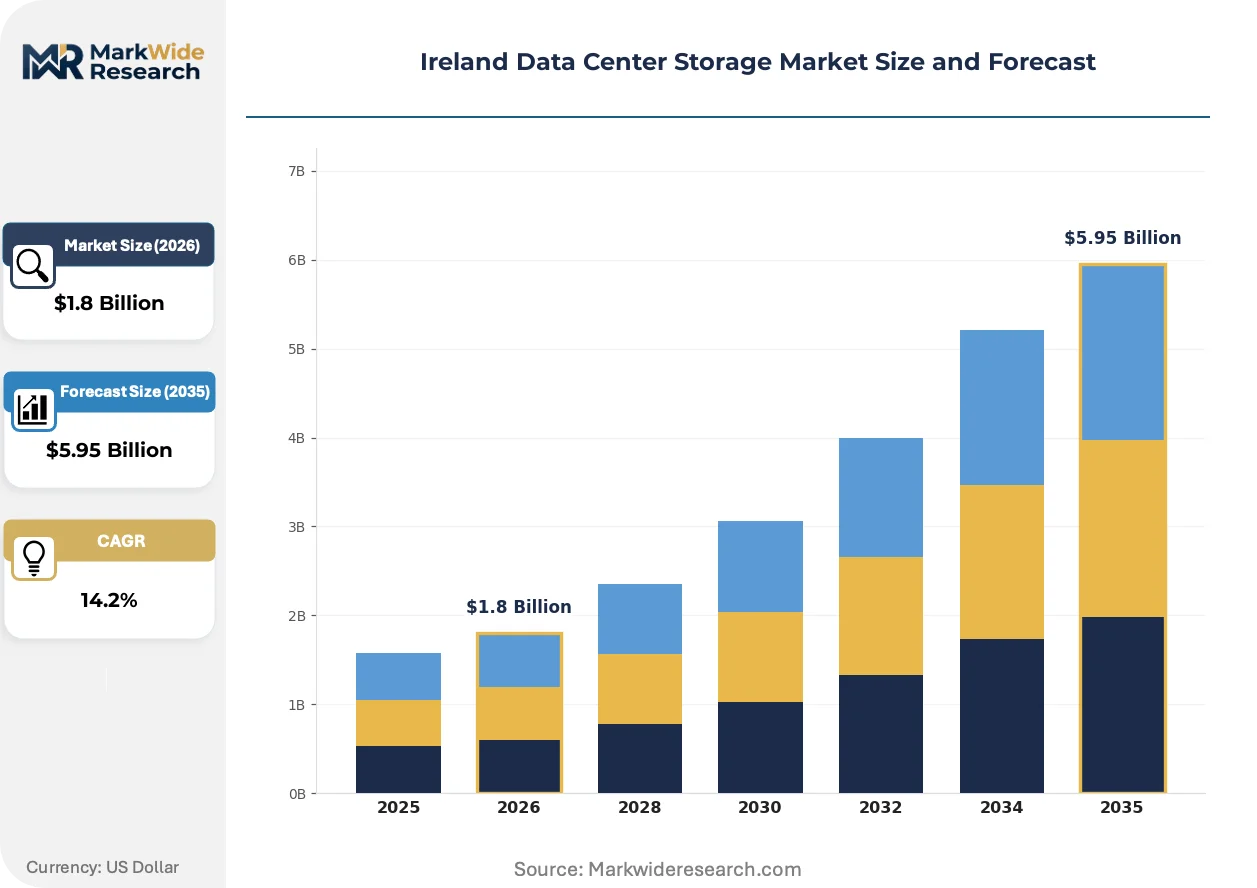
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Attached Storage, Network Attached Storage, Storage Area Network, Object Storage Application: Backup, Archiving, Cloud Storage, Big Data Analytics End User: IT Services, Telecommunications, Financial Services, E-Commerce Technology: Flash Storage, HDD, Hybrid Storage, Tape Storage |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies Co. Ltd., Hitachi Vantara LLC, Pure Storage Inc., Infinidat Ltd., Lenovo Group Limited, Fujitsu Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Storage Market Trends and Innovations
Computational storage is actively reshaping how Irish data centers process data at the media layer, embedding processing capabilities directly within SSD controllers to reduce data movement overhead and align with stringent carbon reduction mandates.
Computational storage drives embed ARM-based processors within NVMe SSD controllers to execute compression, encryption, and erasure coding locally. Hyperscale operators in Dublin's corridor are piloting these devices for AI training pipelines where data movement dominates energy consumption. This architecture is digitizing storage from passive retention into active compute nodes, collapsing the traditional boundary between processing and persistence layers.
The EU Energy Efficiency Directive mandates granular metering and public PUE disclosure for facilities exceeding 500kW capacity. Irish operators must now instrument every storage subsystem for real-time power reporting, forcing procurement teams to weight watt-per-TB metrics equally with IOPS performance. Flash storage arrays with adaptive power management capture preference in tender evaluations against legacy hybrid systems.
Irish enterprise buyers are consolidating vendor relationships around full-stack storage-as-a-service contracts that bundle hardware, software, and operational support into per-TB monthly fees. This displaces traditional capital purchase cycles with consumption-based models that shift refresh decisions from IT to procurement functions. Financial services and pharmaceutical verticals in Dublin lead this transition, driven by balance-sheet optimization and carbon accounting transparency requirements.
Ireland Data Center Storage Market Segmentation
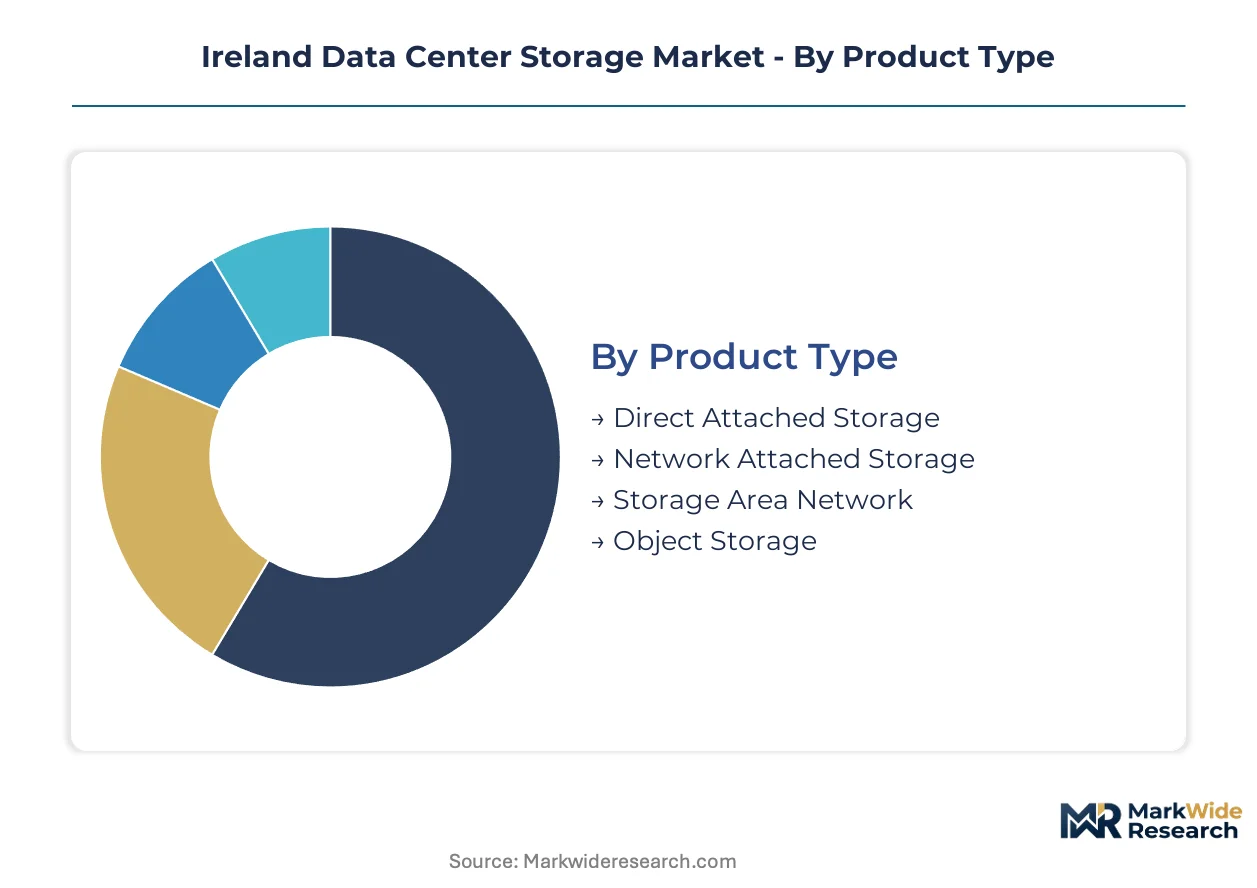
Storage procurement patterns across Irish facilities diverge sharply by workload latency requirements and carbon accounting obligations. Understanding these segment boundaries enables operators to align infrastructure investments with grid constraints and regulatory disclosure mandates.
Product Type:
Cost tier determines how Irish data centers balance capital efficiency against operational flexibility across deployment scales.
- Direct Attached Storage:Server-integrated NVMe and SAS drives deliver lowest latency for single-tenant compute nodes. Hyperscale operators in Dublin's Ashburn corridor deploy these for AI training scratch storage where microseconds matter.
- Object Storage:Distributed, metadata-driven architectures scale to hundreds of petabytes for unstructured data lakes. Cloud providers expanding in Cork secondary sites favor these systems for cost-optimized cold tiers and compliance archives.
- Network Attached Storage:File-level protocols serve enterprise collaboration and content repositories. Financial services firms in Dublin's IFSC district maintain these for legacy application compatibility.
- Storage Area Network:Block-level Fibre Channel and NVMe-oF fabrics consolidate enterprise storage pools. Pharmaceutical multinationals leverage SAN infrastructure for ERP and clinical data management.
Direct Attached Storage holds installed capacity. Object Storage is rotating up the share rankings.
Application:
Workload characteristics dictate power density requirements and cooling architecture across Irish facilities.
- Big Data Analytics:Real-time processing pipelines demand all-flash subsystems with sustained throughput for machine learning inference. County Dublin hyperscalers consume petabyte-scale deployments for recommendation engines and fraud detection.
- Cloud Storage:Multi-tenant object and file services require erasure-coded durability across geographically distributed nodes. Secondary clusters in Limerick attract these workloads for available grid capacity.
- Backup:Immutable snapshot and replication targets protect against ransomware and operational errors. Enterprise customers favor disk-based deduplication appliances over legacy tape for recovery time objectives.
- Archiving:Long-term retention for regulatory compliance and legal hold leverages low-wattage media. Healthcare and public sector buyers specify these systems for GDPR-mandated data lifecycle management.
Backup retains the largest footprint. Big Data Analytics is climbing the fastest.
End User:
Customer type shapes procurement sophistication, contract structure, and sustainability disclosure requirements.
- IT Services:Managed hosting and colocation providers aggregate demand across enterprise tenants. These buyers negotiate storage-as-a-service contracts that transfer refresh risk to vendors.
- Financial Services:Banks and insurers face ECB supervisory scrutiny on operational resilience and data sovereignty. Their procurement specifications mandate encrypted, air-gapped storage for trading and customer records.
- Telecommunications:5G infrastructure and edge computing deployments drive distributed storage for content caching. Eir and Vodafone expand capacity for low-latency video delivery.
- E-Commerce:Platform operators require elastic scaling for seasonal demand spikes. These customers prioritize consumption-based pricing over capital ownership.
IT Services dominates contract volume. Financial Services is gaining share fastest.
Technology:
Media type determines watt-per-TB metrics that influence grid connection approvals and carbon reporting accuracy.
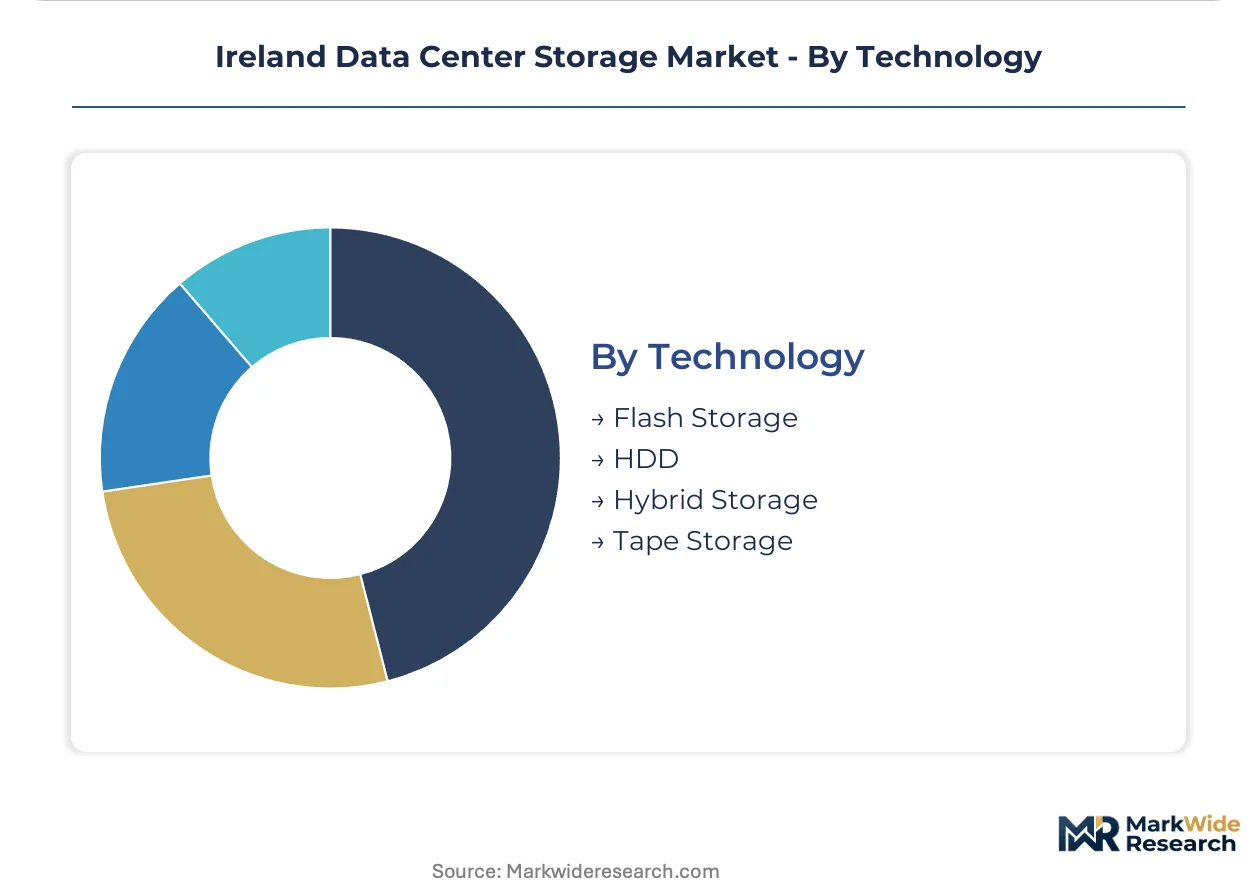
- Flash Storage:NAND-based SSDs with NVMe interfaces deliver highest IOPS density for latency-sensitive workloads. The EU Energy Efficiency Directive pushes hyperscale operators toward these systems for PUE optimization.
- Hybrid Storage:Tiered flash-disk combinations balance cost and performance for mixed workloads. Mid-market enterprises in Cork adopt these arrays during SAN refresh cycles.
- HDD:Conventional magnetic storage retains cost advantage for sequential throughput and capacity-heavy archives. Cold storage operators specify high-density helium drives for video and telemetry retention.
- Tape Storage:Linear tape file system libraries provide air-gapped immutability for ransomware protection. Government and research institutions maintain these for decade-scale retention.
HDD retains capacity leadership. Flash Storage is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German storage hardware exports flow into Irish hyperscale facilities through Dublin's port infrastructure, while Asian NAND fabrication concentrates supply risk for flash-dependent operators across the island.
County Dublin
Hyperscale cloud operators anchor multi-petabyte deployments in the Ashburn-style corridor between Dublin and Kildare. The Commission for Regulation of Utilities enforces grid connection caps that constrain power availability for new storage builds. Tallaght and Blanchardstown clusters host dense all-flash arrays serving real-time analytics for financial services tenants.
Cork
Secondary data center development accelerates in Cork Harbour to escape Dublin's grid constraints. Apple's existing campus anchors demand for object storage serving content distribution networks. The Environmental Protection Agency processes Industrial Emissions Directive permits for facilities exceeding 500kW capacity, favoring liquid-cooled flash deployments.
Limerick
Midwest connectivity infrastructure attracts distributed storage architectures for disaster recovery and backup workloads. University of Limerick research partnerships drive pilot deployments of computational storage for AI training pipelines. Shannon Free Zone retains legacy enterprise SAN installations serving pharmaceutical multinationals.
Galway
Medtech and diagnostics clusters generate specialized storage demand for clinical data management and regulatory archiving. Enterprise Ireland innovation funding supports edge storage pilots for connected health devices. Oranmore subsea cable landing stations enable low-latency replication to continental European facilities.
Ireland Data Center Storage Market Competitive Landscape
On the supply side, the industry is consolidating around full-stack infrastructure vendors capable of delivering storage-as-a-service contracts with embedded carbon accounting. Tier-one systems integrators capture hyperscale deployments through direct relationships, while specialist flash vendors penetrate sustainability-conscious mid-market accounts. Strategic archetypes include vertically integrated hardware-software platforms, pure-play all-flash specialists, and telecommunications-anchored system vendors. Competitive intensity manifests through portfolio diversification into computational storage and geographic expansion into secondary Irish markets.
Within the enterprise infrastructure tier, Dell Inc. and Hewlett Packard Enterprise occupy positions as full-stack platform providers serving Dublin's financial services corridor. Pure Storage Inc. exemplifies the all-flash specialist archetype competing on density metrics aligned with EU Energy Efficiency Directive compliance. Huawei Technologies Co. Ltd. represents the telecommunications-anchored vendor category extending from carrier relationships into cloud service provider facilities.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies Co. Ltd. |
| Hitachi Vantara LLC |
| Pure Storage Inc. |
| Infinidat Ltd. |
| Lenovo Group Limited |
| Fujitsu Limited |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian NAND fabrication facilities is compressing spot pricing for flash storage modules while simultaneously eroding supplier willingness to absorb currency volatility for Irish hyperscale buyers. This utilization dynamic forces Dublin-based procurement teams toward longer-term offtake contracts that trade price certainty against inventory carrying costs.
Pricing Analysis
Next-generation NVMe-oF arrays command a 40-60% premium over prior-generation Fibre Channel SAN infrastructure, while current-gen all-flash systems face accelerating cost compression as NAND oversupply persists. Three-tier pricing structure across premium, standard, and economy levels stratifies by IOPS density and energy efficiency certification, with EU Energy Efficiency Directive compliance tiers attracting green procurement premiums. Price erosion runs through mid-market hybrid arrays as Dell and Pure Storage compete on watt-per-TB metrics. Hyperscale cloud operators exhibit lowest price sensitivity due to TCO-focused procurement models, while enterprise SAN refresh cycles show acute sensitivity to capital budget timing.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor manufacturing equipment to Chinese fabs are concentrating premium NAND supply in South Korean and Japanese foundries, elevating supply security premiums for Irish buyers. Component sourcing draws from Taiwan for SSD controllers, South Korea for 3D NAND wafers, and Germany for precision cooling hardware. Single-source vulnerability concentrates in advanced node lithography equipment held by Dutch and Japanese vendors. Distribution runs through Rotterdam port consolidation followed by Dublin-based systems integrators for final configuration and commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Storage-as-a-service contracts are expanding at triple the rate of hardware-only transactions as Irish enterprises prioritize operational expenditure treatment and embedded carbon accounting transparency.
For Market Incumbents: Harden defensive positions through captive supply agreements with South Korean NAND foundries to insulate against geopolitical supply disruptions. Deepen backward integration into liquid cooling subsystem manufacturing to capture margin pools from EU Energy Efficiency Directive compliance mandates. Prioritize certification investment for ISO 14001 environmental management to differentiate in public-sector tenders. For New Entrants and Emerging Players: Secondary data center clusters in Cork and Limerick represent the most penetrable entry point, offering available grid capacity and less entrenched incumbent relationships than Dublin's Ashburn corridor. Mid-market pharmaceutical and medtech verticals in Galway show underserved demand for compliant archival storage with shorter sales cycles than financial services. A channel partnership strategy with Irish systems integrators accelerates referenceability without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated flash storage specialists with established computational storage roadmaps and existing hyperscale customer relationships. Long-term viability hinges on differentiation beyond commodity NAND aggregation into software-defined data services and sustainability reporting automation. The signal to watch is Commission for Regulation of Utilities grid connection approval velocity as an inflection indicator for demand expansion capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Storage Integration | Embedding ARM-based processing in NVMe controllers reduces data movement energy for AI training pipelines. |
| Liquid Cooling Infrastructure Partnership | Direct-to-chip cooling deployments align with EPA Industrial Emissions Directive permit requirements in Cork Harbour. |
| Renewable Power Purchase Agreement | Green energy contracts satisfy EU Energy Efficiency Directive PUE reporting mandates for hyperscale operators. |
| Storage-as-a-Service Platform Launch | Consumption-based pricing models displace capital purchase cycles in Dublin financial services verticals. |
| Secondary Site Geographic Expansion | Cork and Limerick clusters bypass Dublin grid constraints while serving distributed backup architectures. |
Research Methodology
A standing panel of data center infrastructure directors, storage procurement officers at hyperscale operators, Commission for Regulation of Utilities planning staff, and systems integration engineers provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Dell and Pure Storage, hyperscaler capex disclosure reports, EPA Industrial Emissions Directive permit databases, and EU Energy Efficiency Directive compliance filings. Bottom-up deployment tracking across County Dublin, Cork, Limerick, and Galway facilities triangulated against top-down market sizing from vendor shipment disclosures.
Scenario-bracketing around grid connection approval timelines, NAND supply volatility, and carbon border adjustment implementation generated high-low-bound projections across the analysis window. Segmentation dimensions modeled include storage architecture type, workload application, end-user vertical, and cooling technology tier. CAGRs were derived from deployment run-rate analysis and vendor pipeline disclosure rather than macroeconomic extrapolation. Forecast inputs incorporated real-time power pricing from Single Electricity Market Operator data and renewable PPA availability indices.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates, Irish grid interconnection capacity expansion, or EU carbon border adjustment scope would shift the trajectory materially. Forecasts reflect documented assumptions regarding hyperscale operator commitment to Dublin-region expansion and NAND fabrication capacity normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Blu-Ray Drive Market
Data Storage
North America Next Generation Storage Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
NAND Flash Market
Data Storage
All Flash Storage Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Data Storage Devices Market
Data Storage
SSD Controller Market
Data Storage
Hardware Storage Market
Data Storage
Germany Data Center Storage Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Flash Memory Market