
 Middle East and Africa AMH and Storage Systems Market | 2026-2036
Middle East and Africa AMH and Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa AMH and Storage Systems Market Foresight
Aftermarket service revenue is reshaping margin distribution across the Middle East and Africa AMH and Storage Systems landscape. Daifuku Co. Ltd anchors its regional presence through deep vertical integration in automated storage and retrieval systems. KION Group AG leverages its manufacturing scale to dominate forklift-to-automation transitions in South African distribution networks. Murata Machinery Ltd specializes in cleanroom-compatible material handling for pharmaceutical clients across the Gulf.
Automated material handling and storage systems integrate conveyors, robotic pick modules, and software-controlled retrieval architectures to move, store, and track inventory without manual intervention. These systems typically operate at throughput rates exceeding 1,000 picks per hour in high-density configurations, serving manufacturing floors and distribution centers where labor scarcity and accuracy requirements converge. Conveyor systems and automated storage and retrieval systems occupy the mature core of the installed base, while robotic pick systems represent the fastest-expanding margin pool as e-commerce operators demand piece-picking flexibility. End-user segmentation tilts toward logistics and e-commerce channels, where warehouse automation investments outpace traditional retail deployment cycles.
SFDA traceability mandates in Saudi Arabia, UAE dual carbon frameworks, and South African Occupational Health and Safety Act enforcement collectively elevate standards for system certification and energy reporting. These regulatory pressures filter procurement specifications toward vendors with demonstrated compliance documentation and localized service infrastructure. Stakeholders must monitor how Gulf standardization bodies harmonize automation safety codes with European CE marking precedents to anticipate certification cost trajectories.
Market Dynamics
E-commerce fulfillment velocity across Gulf Cooperation Council corridors is compressing warehouse design cycles and forcing automation retrofit decisions faster than depreciation schedules allow. SFDA pharmaceutical mandates and UAE dual carbon frameworks are rewriting procurement specifications before existing contracts expire.
Growth Catalysts
- SFDA Traceability Mandates:Saudi Arabia's pharmaceutical serialization requirements are compelling warehouse operators to deploy IoT-integrated storage systems with real-time inventory tracking capabilities.
- Robotic Pick Systems:E-commerce fulfillment centers across Dubai and Riyadh are installing piece-picking robots to handle SKU proliferation and same-day delivery windows.
- UAE Dual Carbon Goals:The Emirates' net-zero commitments are accelerating demand for energy-efficient automated storage and retrieval systems with regenerative drive technology.
Market Restraints
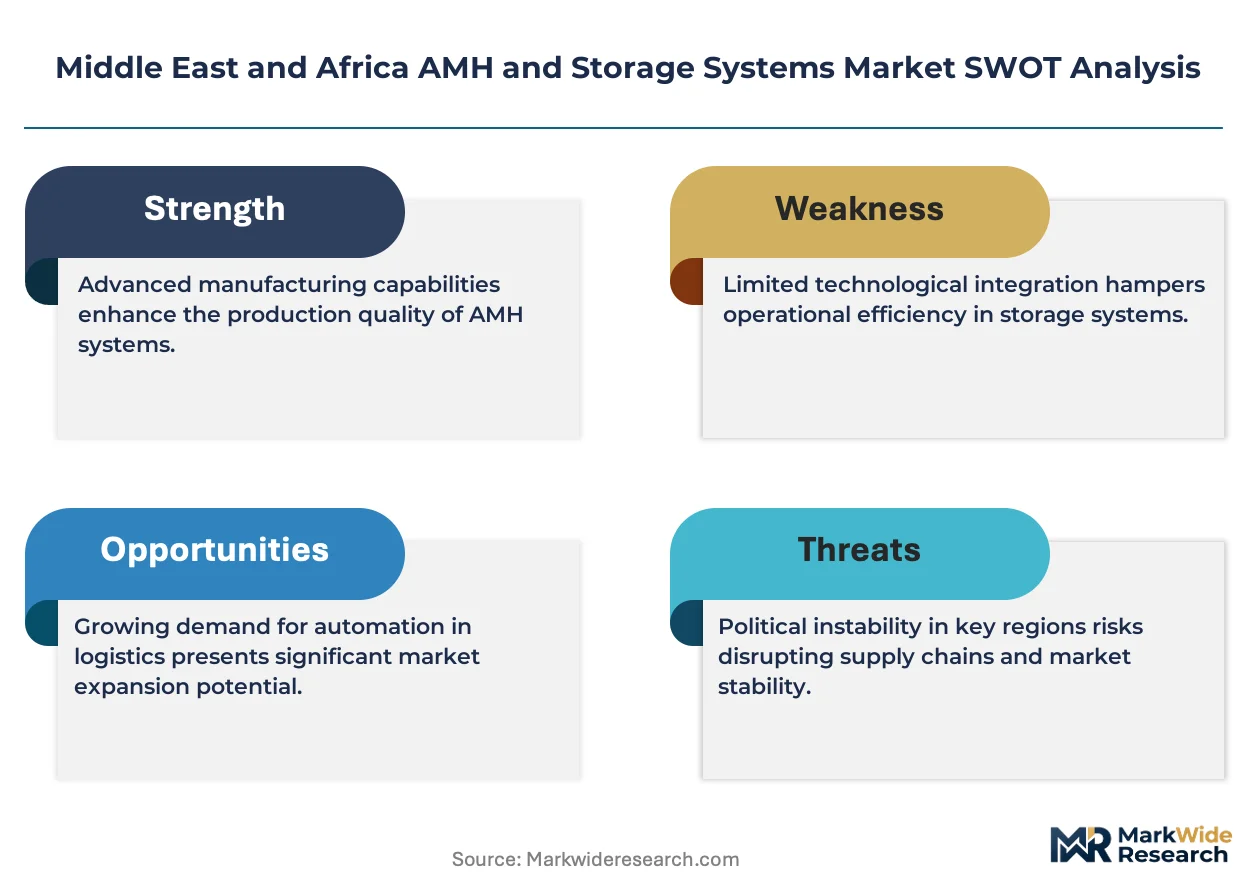
- Steel and Aluminum Input Volatility:Conveyor frame and rack system manufacturers face margin compression from fluctuating commodity prices with limited pass-through mechanisms in fixed-price contracts.
- European Component Concentration:Critical servo motors and PLCs for robotic systems originate from German and Italian suppliers, exposing regional integrators to euro-denominated cost spikes and extended lead times.
- Grid Infrastructure Limitations:Nigerian and Egyptian industrial zones lack the three-phase power stability required for high-throughput automated storage installations without substantial electrical upgrades.
Strategic Opportunities
- Cold Chain Pharmaceutical Expansion:Temperature-controlled automated storage for vaccines and biologics remains underdeployed across sub-Saharan Africa outside South Africa and Kenya.
- Solar-Integrated Warehouse Design:UAE and Saudi developers are piloting photovoltaic canopy structures over automated storage facilities to meet dual carbon reporting requirements.
- 5G-Enabled Fleet Management:South African mining and logistics operators are testing private 5G networks for real-time coordination between autonomous mobile robots and central warehouse management systems.
Industry Challenges
- Mechatronics Talent Scarcity:Gulf-based system integrators struggle to recruit technicians capable of maintaining robotic pick modules and servo-driven retrieval systems.
- CE-to-SASO Certification Gaps:European-manufactured equipment requires substantial retesting and documentation adaptation to meet Saudi Standards, Metrology and Quality Organization requirements, extending deployment timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa AMH and Storage Systems Market |
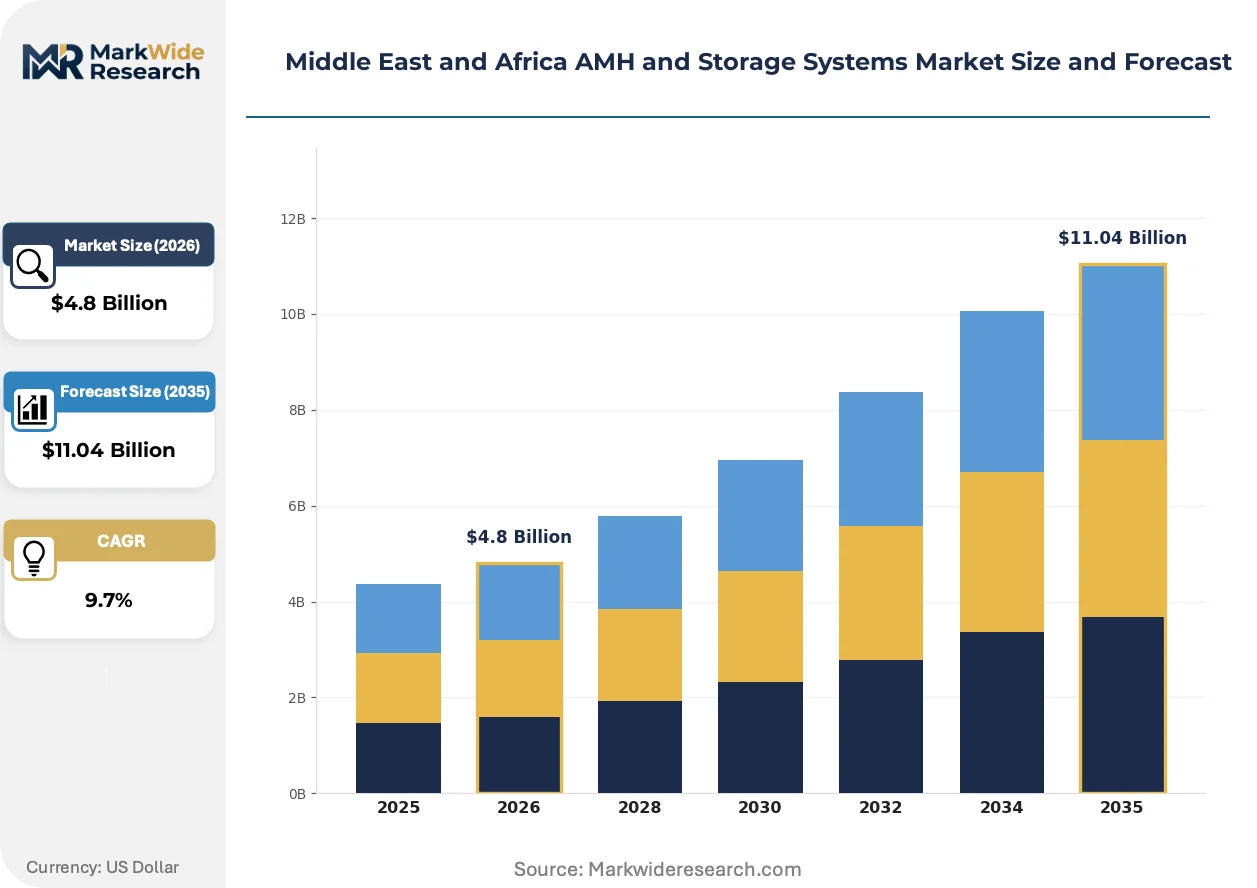
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Robotic Pick Systems, Automated Storage & Retrieval Systems End User: Retail, Manufacturing, Logistics, E-commerce Installation: On-premises, Cloud-based, Hybrid, Modular Technology: IoT Integration, AI-driven Solutions, RFID Tracking, Machine Learning |
| Companies Covered | Daifuku Co. Ltd, Murata Machinery Ltd, KION Group AG, Mecalux SA, SSI Schaefer, TGW Logistics Group, Kardex Holding AG, KNAPP AG, BEUMER Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa AMH and Storage Systems Market Shifts & Advancements
Software-defined orchestration layers are separating control intelligence from mechanical hardware, enabling retrofit automation without full infrastructure replacement. This decoupling permits warehouse operators to upgrade throughput without demolishing existing rack configurations.
Autonomous mobile robots equipped with machine vision and collaborative safety systems are collapsing the traditional boundary between fixed conveyor infrastructure and flexible manual picking zones. Pharmaceutical distributors in Jeddah and Dubai are deploying these units to satisfy SFDA lot-tracking requirements while maintaining piece-pick accuracy above 99.5 percent. The technology is collapsing capital allocation trade-offs that previously forced warehouses to choose between throughput and flexibility.
SFDA serialization mandates and UAE Ministry of Health and Prevention pharmaceutical storage regulations are mandating environmental monitoring data retention for seven years. Cold chain operators must now integrate warehouse management systems with national traceability databases, creating compliance-driven demand for software architectures with immutable audit trails. Saudi distributors are responding by specifying systems with pre-validated pharmaceutical module certifications.
Third-party logistics providers are unbundling automation-as-a-service from traditional facility leases, shifting capex risk to equipment financiers and system integrators. This model is displacing outright purchase decisions in South African distribution networks where capital constraints limit upfront automation investment. The shift is most visible in Johannesburg and Cape Town logistics corridors serving fast-moving consumer goods importers.
Middle East and Africa AMH and Storage Systems Market Segmentation
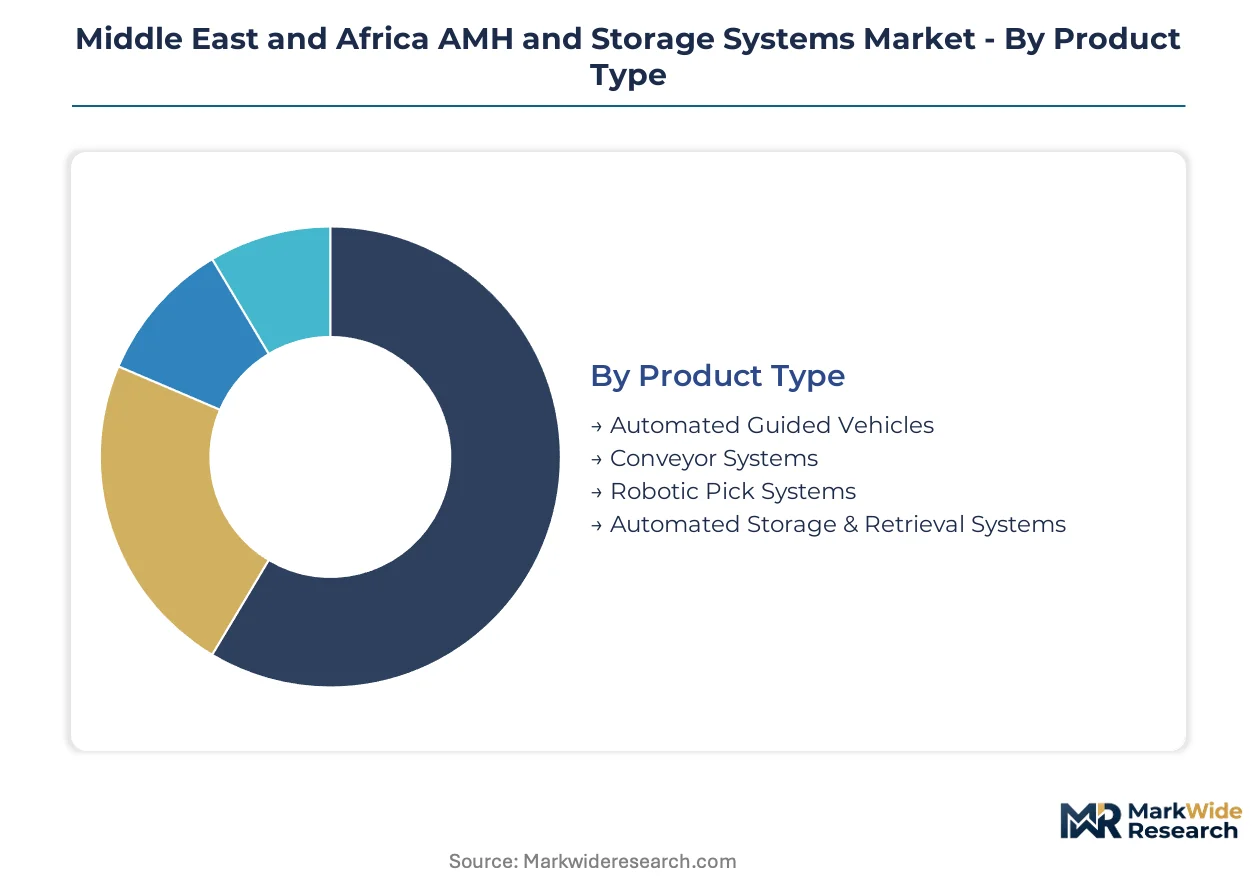
Segmentation in the Middle East and Africa AMH and Storage Systems market reveals how after-sales service intensity varies dramatically across equipment categories. Installation complexity and software dependency determine whether vendors capture recurring revenue streams or remain trapped in one-time hardware margins.
Product Type:
After-sales service intensity peaks with systems requiring continuous software calibration and mechanical maintenance, creating divergent margin profiles across the installed base.
- Automated Guided Vehicles:Battery-powered mobile platforms navigate warehouse floors using magnetic tape, laser guidance, or vision-based pathfinding. Logistics operators in Dubai and Riyadh deploy AGV fleets for pallet transport between receiving docks and high-density storage zones, with SFDA pharmaceutical mandates driving demand for units with integrated weight verification and lot-tracking sensors.
- Conveyor Systems:Belt, roller, and chain-driven transport infrastructure forms the mechanical backbone of regional distribution centers. Saudi Arabian e-commerce fulfillment centers specify modular conveyor architectures with regenerative drive technology to satisfy dual carbon reporting requirements under UAE federal frameworks.
- Robotic Pick Systems:Articulated arms and delta robots equipped with suction grippers or soft-actuator end effectors handle piece-picking operations. Demand concentrates in GCC e-commerce corridors.
- Automated Storage & Retrieval Systems:Crane-based or shuttle-based high-density storage architectures maximize cubic utilization. Cold chain pharmaceutical operators in Jeddah prioritize AS/RS with seven-year data retention capabilities.
By volume, Conveyor Systems leads. By growth pace, Robotic Pick Systems is climbing the fastest.
End User:
Capital deployment cycles and automation sophistication diverge sharply across customer categories, with digital maturity determining procurement specification complexity.
- Retail:Traditional brick-and-mortar distribution networks in South Africa and Nigeria pursue automation retrofit strategies to compete with e-commerce fulfillment velocity. Back-of-store micro-fulfillment centers in Cape Town and Johannesburg deploy compact AS/RS and conveyor modules to enable same-day delivery from existing retail footprints.
- Manufacturing:Discrete manufacturing floors in Morocco and Tunisia integrate AGV fleets with production scheduling systems to reduce work-in-process inventory buffers. Automotive component suppliers specify cleanroom-compatible material handling to meet quality certification requirements.
- Logistics:Third-party warehouse operators across the GCC represent the most software-sophisticated buyer segment, demanding API-first warehouse management integration and predictive maintenance dashboards.
- E-commerce:Pure-play online retailers in Dubai and Riyadh drive SKU proliferation handling requirements, with piece-picking accuracy specifications above 99.5 percent becoming standard procurement language.
Logistics commands the largest installed base. E-commerce is expanding most quickly.
Installation:
Deployment architecture choices determine upfront capital requirements, ongoing operational control, and compliance audit trail capabilities for regulated industries.
- On-premises:Complete hardware and software infrastructure resides within facility boundaries, delivering maximum data sovereignty. Saudi pharmaceutical distributors prefer on-premises warehouse management systems to satisfy SFDA serialization mandate requirements for direct database integration without third-party cloud intermediaries.
- Cloud-based:Software layers operate on vendor-managed infrastructure with subscription pricing, reducing upfront capital barriers. South African logistics operators with capital constraints increasingly specify cloud-based fleet management for AGV coordination.
- Hybrid:Critical control systems remain on-premises while analytics and reporting layers shift to cloud infrastructure. UAE-based operators pilot hybrid architectures to balance dual carbon reporting automation with operational technology security requirements.
- Modular:Pre-engineered mechanical and software components enable phased deployment without full-scale infrastructure replacement. Sub-Saharan African markets with grid instability favor modular conveyor and AS/RS units that can scale incrementally as power infrastructure improves.
On-premises retains the largest revenue share. Cloud-based is gaining share fastest.
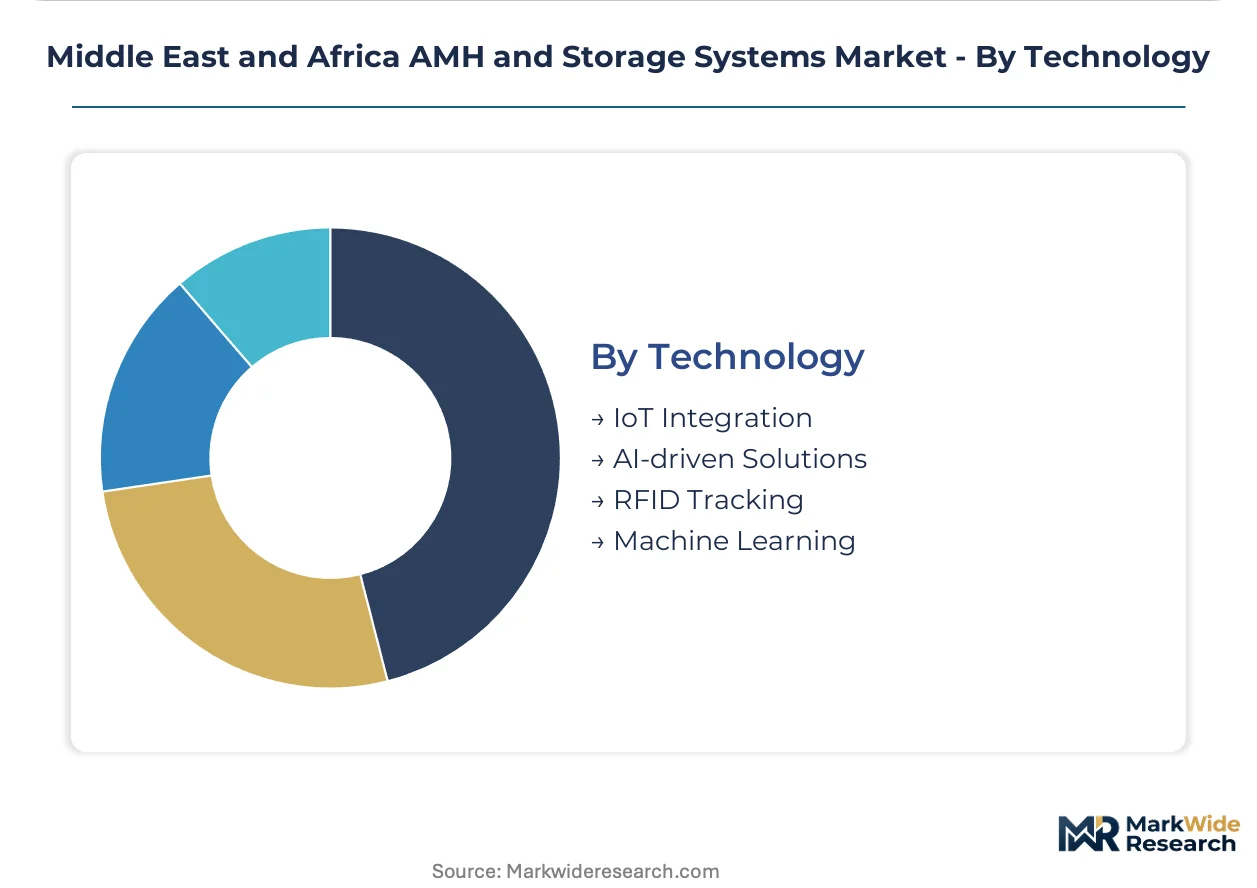
Technology:
Intelligence layer sophistication separates commodity hardware vendors from solution providers capable of capturing software recurring revenue.
- IoT Integration:Sensor networks on storage racks, conveyors, and mobile equipment stream operational telemetry to central monitoring systems. Temperature and humidity logging for pharmaceutical cold chain compliance represents the most regulated application.
- AI-driven Solutions:Predictive algorithms optimize pick path sequencing, inventory slotting, and maintenance scheduling. Demand concentrates in high-SKU-count e-commerce operations.
- RFID Tracking:Passive and active radio-frequency identification enables item-level traceability without line-of-sight scanning. SFDA mandates are accelerating deployment.
- Machine Learning:Pattern recognition systems improve demand forecasting accuracy and dynamic workforce allocation. South African mining logistics operators test private 5G-enabled ML coordination for autonomous mobile robot fleets.
IoT Integration holds the broadest deployment base. AI-driven Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Middle East and Africa AMH and Storage Systems landscape. Gulf Cooperation Council buyers prioritize throughput velocity and compliance certification over upfront cost, while sub-Saharan African operators remain acutely price-sensitive and favor modular, scalable deployments.
Saudi Arabia
Pharmaceutical distributors in Riyadh and Jeddah are retrofitting warehouses to meet SFDA serialization mandates for end-to-end lot traceability. The Saudi Standards, Metrology and Quality Organization enforces equipment certification timelines that extend European deployments by four to six months. King Abdullah Economic City hosts concentrated e-commerce fulfillment center construction where robotic pick systems handle same-day delivery windows.
United Arab Emirates
Dubai's logistics free zones attract third-party operators specifying API-first warehouse management integration and predictive maintenance dashboards. The UAE Ministry of Health and Prevention mandates seven-year environmental data retention for pharmaceutical cold chain facilities. Abu Dhabi industrial zones pilot photovoltaic canopy structures over automated storage installations to satisfy federal dual carbon reporting requirements.
South Africa
Johannesburg and Cape Town distribution corridors serve fast-moving consumer goods importers pursuing automation-as-a-service models to bypass capital constraints. The Occupational Health and Safety Act enforcement elevates system certification standards for warehouse equipment. Mining logistics operators in the Northern Cape test private 5G networks for real-time coordination between autonomous mobile robots and central systems.
Egypt
Nile Delta industrial zones lack three-phase power stability required for high-throughput automated storage without substantial electrical infrastructure upgrades. The country's national pharmaceutical regulator is developing traceability frameworks modeled on Gulf precedents. Alexandria port logistics operators favor conveyor and AGV systems with grid-independent battery backup configurations.
Nigeria
Lagos and Kano distribution networks concentrate demand for modular conveyor and AS/RS units that scale incrementally as power infrastructure improves. Central bank foreign exchange constraints complicate euro-denominated procurement of European servo motors and PLCs. Ikeja industrial clusters host regional headquarters for logistics operators serving West African consumer goods import corridors.
Middle East and Africa AMH and Storage Systems Market Competitive Landscape
Capability concentration sits with vertically integrated system architects; scale advantage sits with manufacturing-scale equipment producers. The Middle East and Africa AMH and Storage Systems market structures around three tiers: full-stack integrators commanding premium margins in Gulf pharmaceutical corridors, component-scale manufacturers supplying conveyor and rack infrastructure, and regional service specialists capturing aftermarket revenue. Dominant competitive moves include strategic partnerships with local certification bodies to compress SASO approval timelines, and portfolio diversification into cold chain pharmaceutical modules.
Within the full-stack integrator tier, Daifuku Co. Ltd and KION Group AG exemplify divergent strategic positions. Daifuku anchors high-complexity automated storage and retrieval system deployments through captive engineering and localized service infrastructure. KION Group AG occupies the manufacturing-scale position, leveraging production volume to supply forklift-to-automation transition pathways in South African distribution networks. Murata Machinery Ltd represents the specialization archetype, with market presence concentrated in cleanroom-compatible material handling for pharmaceutical clients across Gulf Cooperation Council jurisdictions.
| Leading Market Players |
|---|
| Daifuku Co. Ltd |
| Murata Machinery Ltd |
| KION Group AG |
| Mecalux SA |
| SSI Schaefer |
| TGW Logistics Group |
| Kardex Holding AG |
| KNAPP AG |
| BEUMER Group |
| Others |
Supply & Pricing Matrix
European component concentration for servo motors and PLCs determines both margin compression severity and supply chain vulnerability across Middle East and Africa AMH deployments. This single-source dependency from German and Italian suppliers compresses pricing tier spreads while forcing regional integrators into euro-denominated cost exposure without pass-through mechanisms.
Pricing Analysis
After-sales service revenue from parts, maintenance contracts, and software subscriptions drives lifetime value capture in robotic pick systems and AS/RS deployments. Three-tier pricing structure across premium certified, standard compliant, and economy modular levels separates pharmaceutical-grade SFDA-validated installations from general logistics equipment. Cost compression in economy conveyor tiers intensifies because steel and aluminum input volatility limits fixed-price contract viability. Third-party logistics operators in South Africa exhibit highest price sensitivity due to capital constraints, while Gulf pharmaceutical distributors show lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Tariff exposure between European component suppliers and Middle East integrators dominates supply chain risk architecture for high-throughput automated storage systems. Manufacturing concentration in Germany, Italy, and Japan for servo motors, PLCs, and precision rack systems feeds regional assembly operations in Saudi Arabia and the UAE. Critical dependencies on steel framing, aluminum extrusions, and lithium-ion battery packs for AGV fleets amplify commodity price volatility transmission. Distribution runs through Dubai and Jeddah logistics free zones serving as regional consolidation hubs for sub-Saharan African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa AMH and Storage Systems market sits at an early-cycle expansion phase justified by SFDA pharmaceutical traceability mandates forcing warehouse retrofit decisions ahead of depreciation schedules.
For Market Incumbents: Insulate margin positions by deepening captive engineering capabilities for SASO certification acceleration and establishing localized spare parts depots in Riyadh and Dubai to compress service response times. Threat substitution from Chinese automation vendors with faster certification timelines demands preemptive channel control investments in pharmaceutical verticals. For New Entrants and Emerging Players: Pursue modular conveyor and AS/RS white space in Nigerian and Egyptian industrial corridors where grid instability favors scalable battery-backed deployments. Cold chain pharmaceutical automation in sub-Saharan Africa outside South Africa and Kenya represents the most penetrable segment. Go-to-market execution should anchor on automation-as-a-service financing partnerships with regional equipment lessors. For Investors and Strategic Acquirers: The market sits at a capital deployment phase that favors vertically integrated system architects with demonstrated SASO compliance documentation. Long-term viability over the next decade hinges on software recurring revenue capture from predictive maintenance platforms. Acquisition targets should prioritize regional service specialists with pharmaceutical cold chain certifications. The signal to watch is harmonization progress between Gulf standardization bodies and European CE marking precedents as inflection indicator for certification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of critical PLCs reduces euro-denominated cost exposure for Saudi integrators. |
| SASO Certification Pre-Validation Partnership | Compressed approval timelines from four to six months unlock Gulf pharmaceutical contract velocity. |
| Automation-as-a-Service Platform Launch | Subscription pricing displaces capex barriers for South African logistics operators with capital constraints. |
| Photovoltaic Canopy Integration | Solar-embedded warehouse designs satisfy UAE dual carbon reporting requirements for federal compliance. |
| Private 5G Fleet Coordination Deployment | Real-time AMR synchronization meets South African mining logistics throughput specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed automation vendors, SFDA regulatory submissions, and Gulf standardization body documentation. Primary interviews captured perspectives from warehouse operations directors, system integration engineers, pharmaceutical compliance officers, and equipment procurement managers across Saudi Arabia, the UAE, South Africa, Nigeria, and Egypt. Bottom-up installation tracking and top-down macroeconomic triangulation validated demand estimates across the analysis window.
Forecast inputs span equipment type segmentation, end-user digital maturity tiers, installation architecture preferences, and technology integration intensity. Modeled dimensions include product category, customer vertical, deployment model, and regional regulatory cluster. CAGRs derive from trajectory fitting against historical adoption curves in comparable logistics automation markets. Industry-specific inputs incorporate SFDA mandate enforcement timelines, UAE dual carbon framework implementation schedules, and sub-Saharan African grid infrastructure improvement projections.
Sensitivities concentrate around euro exchange rate volatility, steel commodity price swings, and Gulf regulatory harmonization pace. Forecasts reflect documented assumptions regarding certification timeline compression and e-commerce fulfillment velocity maintenance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Japan Data Center Storage Market
Data Storage
Next-Generation Storage Market
Data Storage
Europe Next Generation Storage Market
Data Storage
NAND Flash Market
Data Storage
Enterprise Hard Drive Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
China Solid-State Drive Market
Data Storage
Data Center Ssds Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Serial EEPROM Market
Data Storage
North America SSD Caching Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Object-Based Storage Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Asia Pacific Transparent Caching Market