
 USB 3.1 Flash Drive Market | 2026-2036
USB 3.1 Flash Drive Market Size, Share, and Industry Trends Forecast 2026-2036
USB 3.1 Flash Drive Market Analytics
The USB 3.1 flash drive category is restructuring around a widening split between premium encrypted and rugged segments and commodity bulk-storage products. Samsung leverages captive NAND supply and controller integration to dominate high-performance tiers. Kingston anchors the enterprise channel through specialized encrypted drive portfolios with FIPS validation. ADATA competes aggressively on value-engineered USB-C form factors targeting mobile-first users.
USB 3.1 flash drives are non-volatile solid-state storage devices using NAND flash memory with a USB 3.1 Gen 2 interface supporting 10 Gbps transfer rates, typically housed in plastic or metal enclosures with standard-A, Type-C, or dual connectors for cross-platform data portability. Encrypted flash drives command premium positioning as enterprise security budgets harden around removable media policies, while OTG flash drives capture mobile-to-PC workflow demand in Android-dominant markets. Standard flash drives remain volume-heavy but margin-thin, with 128GB capacity tiers showing structural growth as 4K media files and software installers expand typical payload sizes.
The USB Implementers Forum governs connector and signaling compliance, while regional frameworks including FCC electromagnetic emissions rules in the United States and CE marking under EU Radio Equipment Directive shape market access requirements for imported drives. China's MIIT enforces domestic cybersecurity review protocols that encrypted drive vendors must navigate for government and SOE procurement eligibility. Stakeholders must monitor whether USB4 backward compatibility requirements and evolving Type-C mandate timelines in the European Union and India reshape controller architecture roadmaps and inventory planning horizons.
Market Dynamics
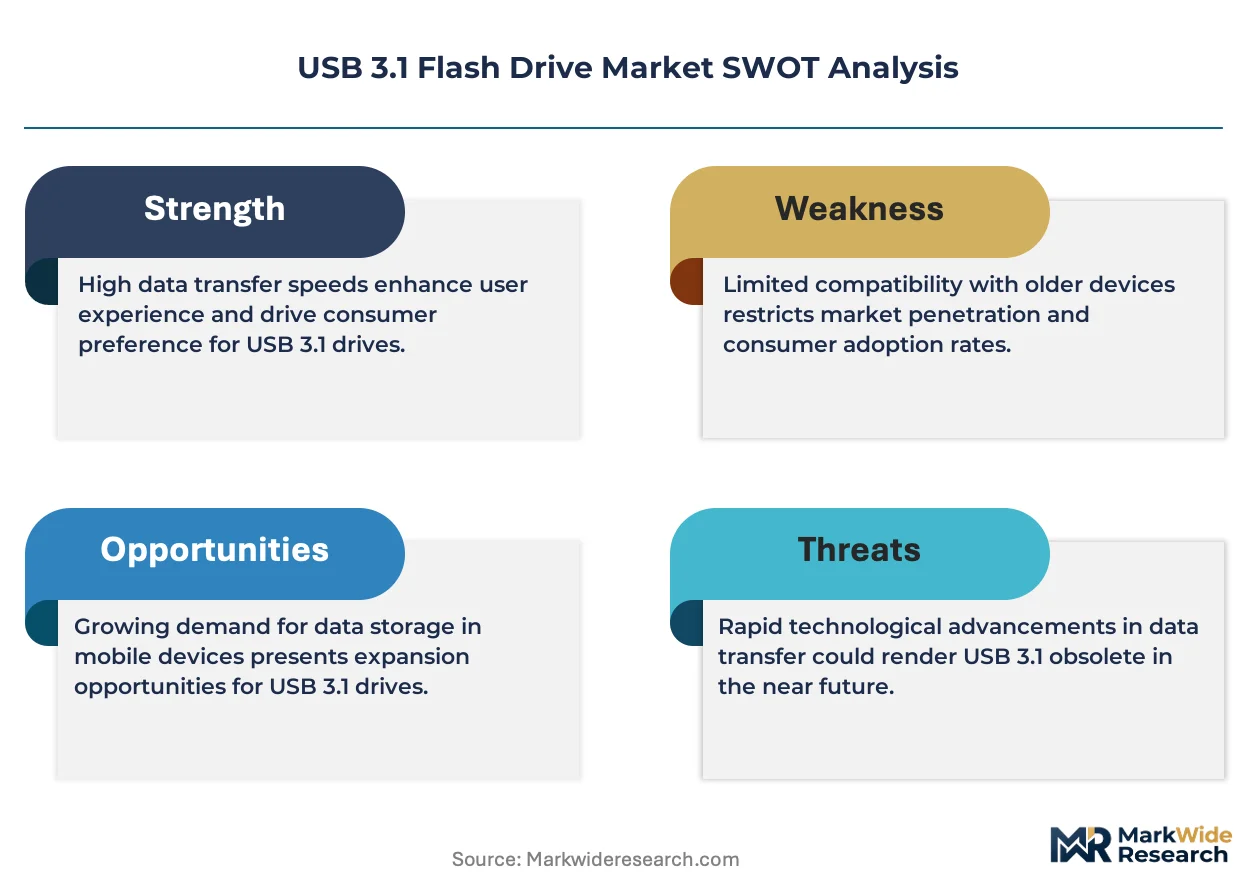
USB 3.1 flash drive procurement is bifurcating between enterprise-grade encrypted units and commodity bulk storage, with NAND flash supply concentration in East Asian fabrication clusters determining margin structures and inventory cycles for downstream assemblers.
Growth Catalysts
- EU USB Type-C Mandate:The European Union's universal charging directive accelerates USB-C connector adoption across consumer electronics, forcing peripheral ecosystem alignment and expanding addressable device populations for compatible flash drives.
- Enterprise Removable Media Security Policies:Financial services and healthcare IT departments harden data loss prevention protocols around hardware-encrypted portable storage, creating procurement pull for FIPS-validated drive portfolios.
- China NAND Fabrication Scale:Domestic wafer output from Yangtze Memory Technologies and Samsung Xi'an anchors component supply for both branded vendors and white-label assemblers serving price-sensitive volume segments.
Market Restraints
- NAND Flash Price Volatility:Memory spot market cyclicality compresses gross margins for drive assemblers lacking captive wafer supply or long-term foundry contracts.
- Controller ASIC Concentration:Taiwan and US-based fabless semiconductor houses dominate USB 3.1 bridge chip supply, creating single-source vulnerability for tier-two drive manufacturers.
- Cloud Storage Substitution:Enterprise file synchronization and mobile-native backup services displace physical media for routine data transfer workflows among knowledge-worker segments.
Strategic Opportunities
- India PLI Electronics Manufacturing:Production-linked incentive schemes for IT hardware assembly attract contract manufacturers establishing local USB drive packaging capacity for domestic government procurement.
- Industrial IoT Field Data Logging:Ruggedized USB 3.1 drives with extended temperature ratings capture demand from oilfield services and agricultural telemetry deployments requiring offline data retrieval.
- USB4 Backward Compatibility Requirements:Controller firmware architectures supporting dual-mode 10 Gbps and 40 Gbps signaling enable product line consolidation and inventory flexibility across interface generations.
Industry Challenges
- USB-IF Certification Queue Bottlenecks:SuperSpeed 10 Gbps interoperability testing backlog extends product launch timelines for vendors chasing seasonal retail windows.
- Cross-Border Encryption Export Controls:Hardware security module classifications trigger licensing complexity for drives shipping to restricted destinations, complicating distributor inventory allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB 3.1 Flash Drive Market |
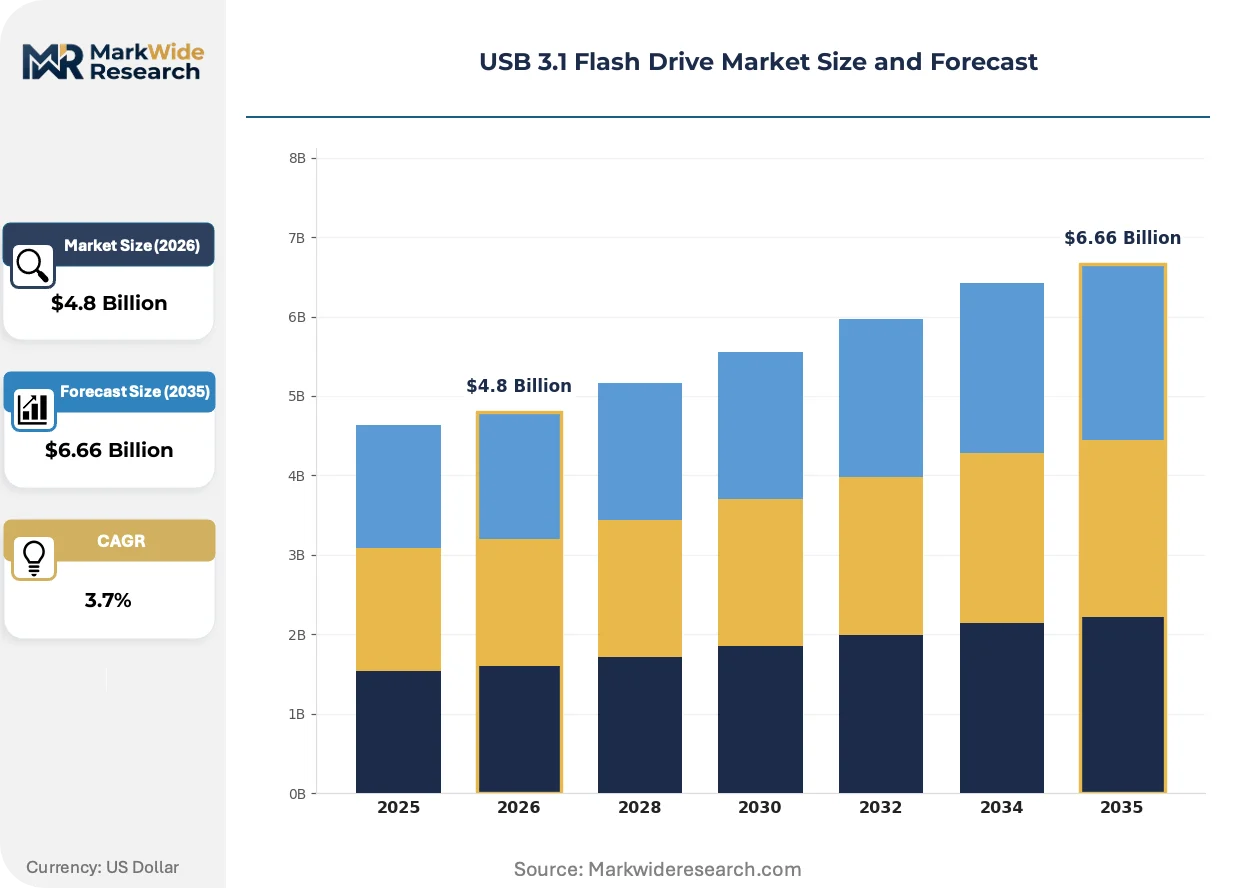
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flash Drive, Rugged Flash Drive, Encrypted Flash Drive, OTG Flash Drive Storage Capacity: 16GB, 32GB, 64GB, 128GB Form Factor: Thumb Drive, Keychain Drive, Card Style Drive, Wearable Drive Interface Type: USB-C, USB-A, USB OTG, Dual Interface |
| Companies Covered | PNY, Lexar, Samsung, Silicon Power, Transcend, SanDisk, ADATA, Goodram, Kingston, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB 3.1 Flash Drive Market Evolving Landscape
Controller firmware architectures and physical connector standards are converging in ways that compress product lifecycles and reshape how vendors differentiate across price tiers.
3D NAND TLC and QLC die stacking is rewriting cost-per-gigabyte economics for high-capacity portable storage. Enterprise procurement teams are adopting 256GB and 512GB tiers for software image deployment and forensic data collection. This density migration is compressing ASPs at legacy 64GB and 128GB price bands and forcing controller vendors to optimize error-correction for lower-endurance cell architectures.
China's MIIT cybersecurity review protocols for encrypted storage products are tightening market access requirements for foreign vendors serving government and state-owned enterprise accounts. Domestic certification timelines now extend 6-12 months beyond USB-IF compliance testing. Vendors with established in-country testing partnerships and localized firmware development teams are securing preferential procurement eligibility.
Direct-to-enterprise contracting is displacing traditional distributor-led volume purchasing for encrypted drive categories. IT security managers now specify FIPS validation levels and tamper-evident mechanical designs in RFP documents rather than accepting catalog SKUs. This specification sophistication is most visible in US federal contractor supply chains and German automotive supplier networks, where compliance documentation requirements exceed consumer-channel capabilities.
USB 3.1 Flash Drive Market Segmentation
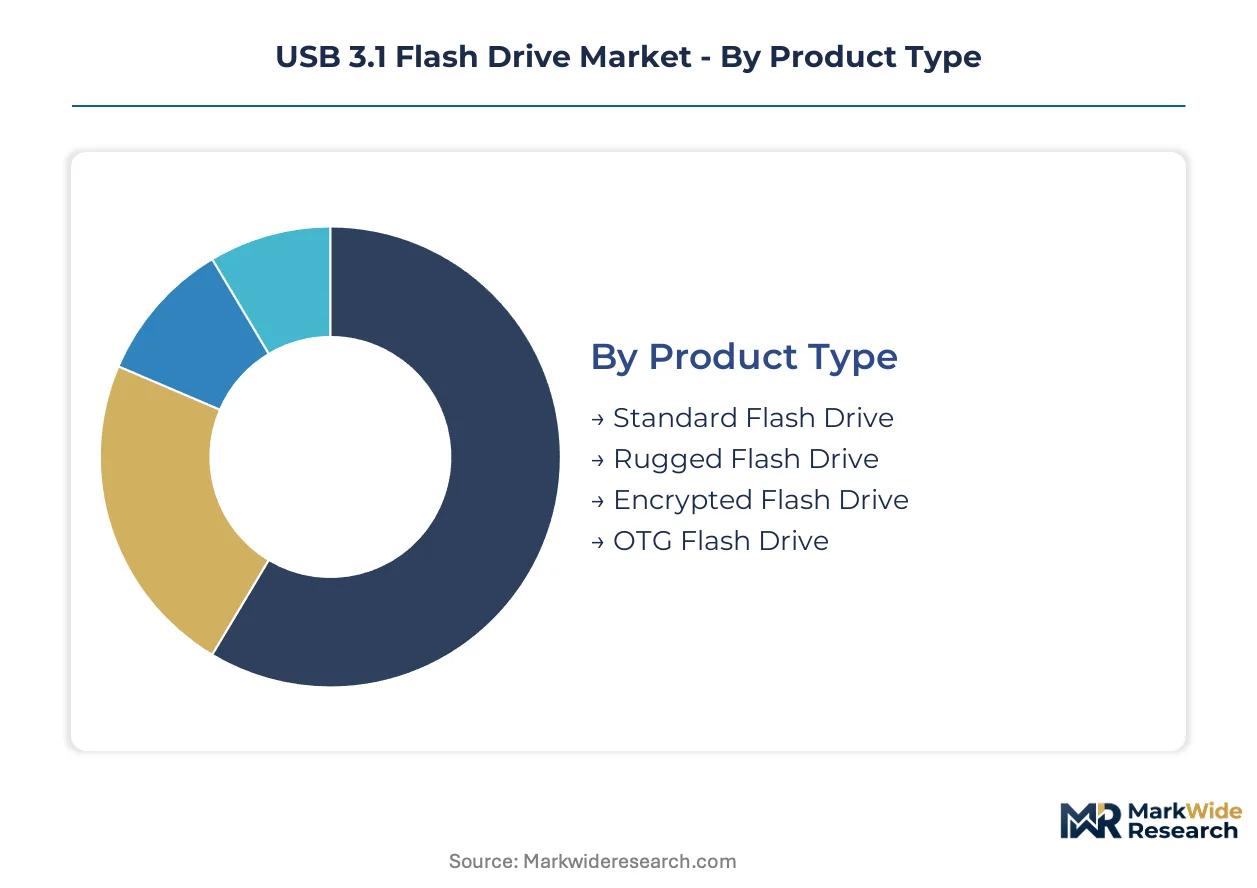
USB 3.1 flash drive procurement splits sharply between standalone portable storage and embedded system integration, with connector standardization and security certification determining which segments capture enterprise versus consumer wallet share. NAND density migration and Type-C mandate compliance are compressing legacy form factors while expanding encrypted and rugged categories.
Product Type:
Integration depth varies substantially across this category, with encrypted and rugged units embedding hardware security modules and temperature-rated components versus standard drives functioning as pure commodity storage.
- Standard Flash Drive:Plastic or metal enclosures housing NAND flash with basic USB 3.1 Gen 2 controllers, no hardware encryption. Volume concentrates in Southeast Asian retail channels and North American back-to-school procurement cycles, with margin pressure from white-label Shenzhen assemblers.
- Rugged Flash Drive:Shock-resistant aluminum or rubberized housings with IP68 water/dust ratings and extended temperature specifications. Demand clusters in German automotive supplier networks and Texas oilfield services, where offline data retrieval survives harsh field conditions.
- Encrypted Flash Drive:AES-256 hardware encryption with FIPS validation and tamper-evident firmware. Enterprise IT departments in US federal contractor supply chains and Japanese financial services specify these for removable media compliance policies.
- OTG Flash Drive:Micro-USB or USB-C dual connectors enabling Android smartphone-to-PC workflows. Adoption concentrates in India and Indonesia mobile-first markets, capturing media transfer demand where cloud connectivity remains intermittent.
Standard flash drives lead volumes today; encrypted flash drives are gaining share fastest.
Storage Capacity:
Cost tier stratification dominates this dimension, with die-stacking economics pushing procurement toward higher densities while legacy tiers serve price-sensitive bulk applications.
- 16GB:Single-layer TLC NAND configurations for basic document and installer storage. Remains viable in Indian government education procurement and African NGO distribution programs where unit cost dominates specifications.
- 32GB:Entry-level 3D NAND stacks for small media libraries and software recovery images. Retail shelf presence is contracting in favor of 64GB entry points across European consumer electronics chains.
- 64GB:Quad-layer cell configurations balancing cost and endurance for mainstream productivity workloads. Korean corporate procurement and Brazilian SME segments anchor current volume concentration.
- 128GB:Higher-density QLC or penta-layer TLC architectures accommodating 4K video and software image deployment. German creative agencies and US healthcare imaging departments drive specification upgrades.
64GB configurations anchor mainstream procurement today; 128GB tiers show steepest expansion trajectory.
Form Factor:
Application context determines form factor selection, with mobility requirements and port accessibility driving divergence between pocketable and wearable designs.
- Thumb Drive:Classic rectangular housings with retractable or cap-protected connectors. Dominates enterprise bulk purchasing and Japanese retail distribution where standardization simplifies inventory management.
- Keychain Drive:Metal loop attachments for keyring integration, typically miniaturized 32-64GB units. Italian fashion accessories distributors and US promotional products channels favor these for brand customization.
- Card Style Drive:Credit-card-thin profiles with embedded USB connectors for wallet storage. French banking sector procurement and Australian conference giveaway programs drive niche demand.
- Wearable Drive:Wristband or lanyard-integrated designs targeting fitness and event access applications. Experimental positioning in UAE corporate wellness programs and South Korean K-pop merchandise ecosystems.
Thumb drives maintain volume leadership today; card style drives are climbing the fastest among specialty formats.
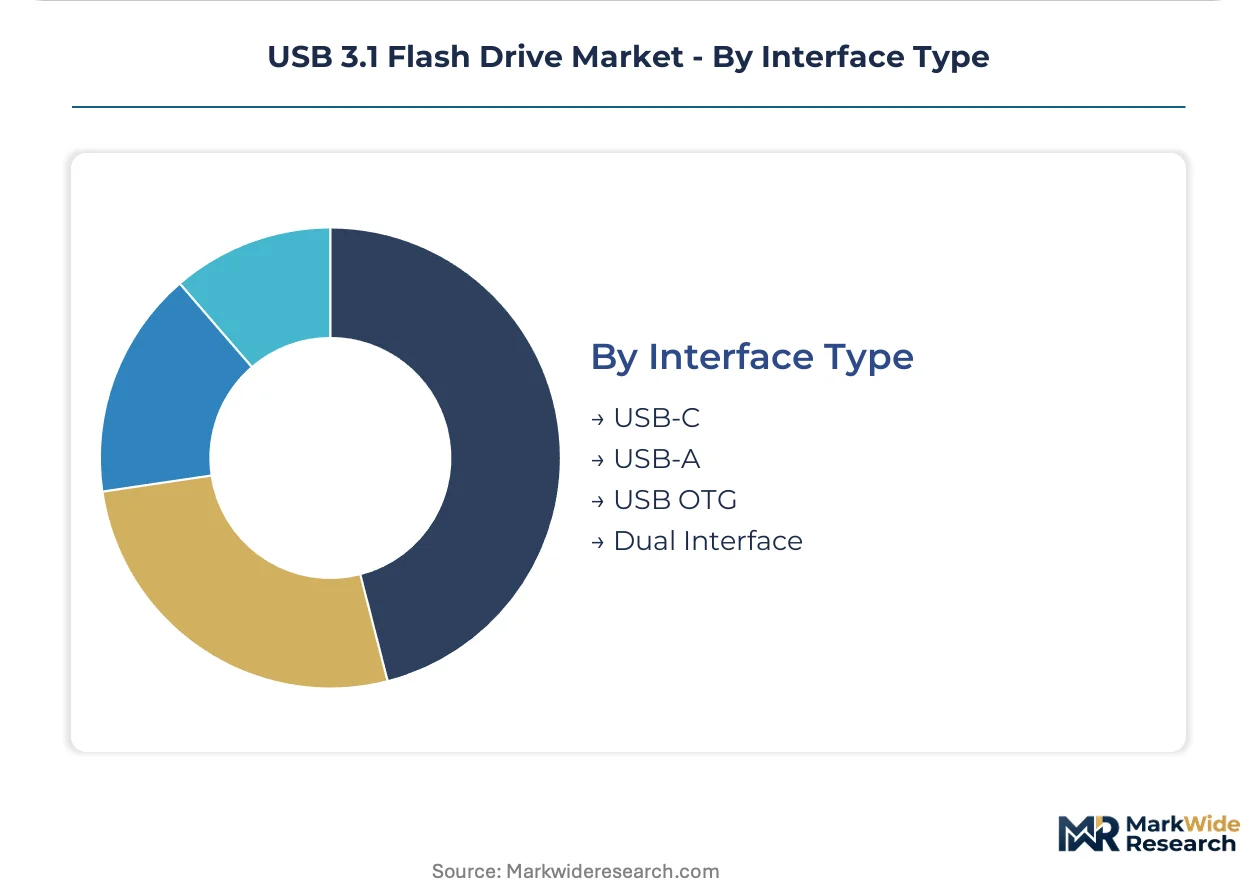
Interface Type:
Connector standardization mandates and backward compatibility requirements are reshaping controller architecture roadmaps across this category.
- USB-C:Reversible 24-pin connectors supporting USB 3.1 Gen 2 signaling and power delivery. EU universal charging directive compliance and Apple ecosystem alignment concentrate demand in Netherlands and California procurement.
- USB-A:Legacy rectangular connectors maintaining compatibility with installed PC infrastructure. Enterprise refresh cycles in UK government and Canadian healthcare extend this segment's commercial relevance.
- USB OTG:Micro-USB or USB-C On-The-Go protocols for direct mobile device attachment. Indian smartphone-first user bases and Indonesian small business workflows sustain this bridging technology.
- Dual Interface:USB-A and USB-C connectors on single drives via rotating or sliding mechanisms. Chinese business traveler segments and Singapore multi-device households prize cross-platform flexibility.
USB-A connectors retain installed-base dominance today; USB-C is expanding most quickly under regulatory mandate pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese NAND fabrication engineers and Shenzhen assembly technicians anchor the industry's geographic concentration, while German automotive procurement specialists and Indian government IT buyers shape demand patterns across distinct regulatory environments.
China
Yangtze Memory Technologies and Samsung Xi'an fabs supply NAND wafers to domestic drive assemblers clustered in Shenzhen and Dongguan. MIIT cybersecurity review protocols now extend 6-12 months beyond USB-IF certification for encrypted products targeting government procurement. White-label manufacturers in the Pearl River Delta dominate global commodity volume shipments.
United States
Federal contractor supply chains and healthcare IT departments drive FIPS-validated encrypted drive demand through specialized procurement channels. FCC electromagnetic emissions rules govern market access for imported controller chipsets and finished drives. Austin and San Jose host firmware development teams serving enterprise security specifications.
Germany
Automotive supplier networks and industrial machinery OEMs specify rugged drives with IP68 ratings for field data logging applications. CE marking under EU Radio Equipment Directive shapes import compliance testing for Asian-manufactured products. Bavarian industrial clusters around Munich anchor procurement specification development for temperature-rated storage.
India
Smartphone-first user bases in Maharashtra and Karnataka sustain OTG flash drive demand for Android-to-PC media workflows. PLI schemes for IT hardware assembly attract contract manufacturers establishing local USB drive packaging capacity. BIS certification requirements govern domestic market access for both imported and locally assembled units.
Japan
Financial services IT departments and corporate procurement teams specify tamper-evident encrypted drives for removable media compliance. METI industrial standards influence enterprise storage specification development. Tokyo and Osaka metropolitan areas concentrate distribution channel management for premium-tier product categories.
USB 3.1 Flash Drive Market Competitive Landscape
Capital-heavy NAND fabricators compete with asset-light controller designers and downstream assemblers across a tiered market structure. The vendor base separates into captive supply integrated players, specialized security-focused portfolios, and value-engineered volume assemblers. Two dominant competitive moves define current positioning: controller firmware differentiation for USB4 backward compatibility and direct-to-enterprise contracting that bypasses traditional distribution channels for encrypted categories.
Within the captive supply tier, Samsung leverages in-house NAND fabrication and controller integration to anchor high-performance positioning. Kingston Technology Corporation occupies the enterprise security specialist archetype through FIPS-validated encrypted portfolios. ADATA Technology Co., Ltd. exemplifies the value-engineered USB-C form factor strategy targeting mobile-first user segments across Asian consumer markets.
| Leading Market Players |
|---|
| PNY |
| Lexar |
| Samsung |
| Silicon Power |
| Transcend |
| SanDisk |
| ADATA |
| Goodram |
| Kingston |
| Others |
Value Network & Pricing Analysis
Enterprise IT security managers and federal procurement officers anchor demand for FIPS-validated encrypted drives, creating a bifurcated pricing structure where certification premiums separate hardware-encrypted units from commodity bulk storage. This buyer concentration forces assemblers to absorb NAND flash spot market volatility while maintaining tiered product portfolios across security grades.
Pricing Analysis
Hardware encryption and ruggedization features are unbundled from base storage, with FIPS validation and IP68 ratings commanding substantial premiums over standard plastic-enclosed units. Price differentiation rests on certification tier and NAND flash quality grade, with enterprise security budgets absorbing premium positioning while education and NGO segments drive cost compression at entry tiers. Pricing pressure stems from white-label Shenzhen assemblers flooding Southeast Asian retail channels with undifferentiated 64GB units. Government procurement offices show least price sensitivity; Indian SME segments exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers mandate qualified secondary controller vendors alongside primary Taiwan and US-based fabless semiconductor suppliers. NAND wafer supply concentrates in China, South Korea, and Japan, with Yangtze Memory Technologies and Samsung Xi'an fabs feeding Shenzhen assembly clusters. Raw material dependencies include 3D NAND TLC/QLC die, USB 3.1 Gen 2 bridge controllers, and aluminum alloy enclosures. Single-source vulnerability in controller ASIC supply creates structural risk. Distribution runs through specialized IT security distributors for encrypted tiers and mass retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as enterprise removable media policies harden around hardware-encrypted specifications, displacing commodity bulk storage for security-sensitive workflows.
For Market Incumbents: Anticipate controller firmware consolidation around USB4 backward compatibility architectures to collapse inventory complexity across interface generations. Defend margin position through captive NAND supply arrangements with Yangtze Memory Technologies or long-term foundry contracts insulating against spot market cyclicality. Reinforce enterprise channel control via direct contracting capabilities that bypass distributor markups for FIPS-validated portfolios. For New Entrants and Emerging Players: Launch via India PLI scheme contract manufacturing partnerships to capture domestic government procurement eligibility under BIS certification. Target industrial IoT field data logging applications in German automotive supplier networks and Texas oilfield services, where ruggedized temperature-rated specifications face limited incumbent specialization. White-space concentration sits in 256GB-512GB encrypted tiers for forensic data collection workflows. For Investors and Strategic Acquirers: NAND flash fabricators with downstream controller integration capabilities are the most active acquirer in this space, seeking to replicate Samsung's captive supply model. Long-term viability hinges on cybersecurity certification moats widening as China's MIIT review protocols extend timelines for foreign vendors. Acquisition target archetype: specialized encrypted drive developers with established FIPS validation pipelines and in-country testing partnerships. Signal to watch: USB-IF certification queue bottlenecks easing as indicator of product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Controller Firmware Consolidation | Dual-mode 10 Gbps and 40 Gbps signaling architectures reduce inventory fragmentation across USB generations. |
| Direct-to-Enterprise Contracting | Bypassing distributor channels captures FIPS-validated procurement margins from US federal contractor supply chains. |
| India PLI Manufacturing Localization | Domestic assembly capacity qualifies vendors for government procurement under BIS certification requirements. |
| USB4 Backward Compatibility Investment | Controller architectures supporting legacy signaling preserve installed-base relevance through interface transitions. |
| MIIT Cybersecurity Review Partnership | Localized firmware development teams compress 6-12 month certification extensions for China government eligibility. |
Research Methodology
Multiple input streams — primary interviews with NAND flash procurement directors, USB controller firmware engineers, and enterprise IT security managers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Secondary sources included USB Implementers Forum certification databases, FCC electromagnetic emissions filings, SEC 10-K disclosures from memory semiconductor firms, and customs trade data from East Asian fabrication clusters. Primary fieldwork encompassed conversations with distributors in Shenzhen's Huaqiangbei electronics markets and procurement officers at German automotive Tier 1 suppliers.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with volume and value outputs reflecting modeled segmentation across product type, storage capacity, form factor, interface type, and end-use vertical. CAGRs were derived from trend extrapolation of NAND flash cost-per-gigabyte economics and enterprise security budget allocation patterns. Industry-specific forecast inputs incorporated USB Type-C mandate compliance timelines in the European Union and India, plus MIIT cybersecurity review protocol evolution.
Several conditions sit outside the modeled scope, including unannounced USB4 specification revisions, sudden NAND flash supply disruptions from geopolitical events, and accelerated cloud storage substitution beyond current enterprise adoption curves. Forecasts reflect documented assumptions regarding interface transition velocities and certification timeline stability. Deviation in NAND flash spot market cyclicality or USB-IF testing queue durations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Flash Memory Market
Data Storage
Asia-Pacific Data Center Storage Market
Data Storage
Blu-Ray Drive Market
Data Storage
NAND Flash Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Distributed Storage System Market
Data Storage
Multiprotocol Storage Market
Data Storage
External Storage Market
Data Storage
NOR Flash Market
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
Hardware Storage Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Data Storage Devices Market
Data Storage
North America Next Generation Storage Market