
 Parry-Romberg Syndrome Market | 2026-2036
Parry-Romberg Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Parry-Romberg Syndrome Market Outlook
Specialty clinic demand is realigning the Parry-Romberg Syndrome treatment landscape toward outpatient surgical and injectable interventions. Pfizer Inc. leverages its immunology pipeline breadth to address underlying autoimmune mechanisms. Sanofi S.A. anchors its position through rare disease R&D intensity and European regulatory navigation. Novartis AG specializes in biologic delivery platforms that target facial tissue restoration pathways.
Parry-Romberg Syndrome constitutes a rare, progressive craniofacial disorder characterized by unilateral atrophy of skin, subcutaneous tissue, muscle, and occasionally bone, with disease progression typically spanning years before stabilization. The condition demands multidisciplinary management spanning dermatologic assessment, immunomodulatory therapy, and reconstructive surgical intervention to restore functional and aesthetic outcomes. Injectable biologics command premium positioning within the therapy area segmentation as immunology-directed treatments gain protocol adoption. Surgical procedures retain stable volume share where tissue loss advances beyond pharmacologic reversal capacity, while topical creams occupy an adjunctive role in early-stage disease management.
The FDA orphan drug program shapes therapeutic development economics through tax incentives and extended exclusivity periods for Parry-Romberg Syndrome indications. EMA's rare disease framework in Europe creates parallel market access pathways, though centralized reimbursement negotiations vary by member state. The WHO's International Classification of Diseases revision process influences diagnostic coding standardization and epidemiological tracking methodology. Stakeholders must monitor regulatory guidance evolution on tissue-engineered product classifications and autologous cell therapy manufacturing standards.
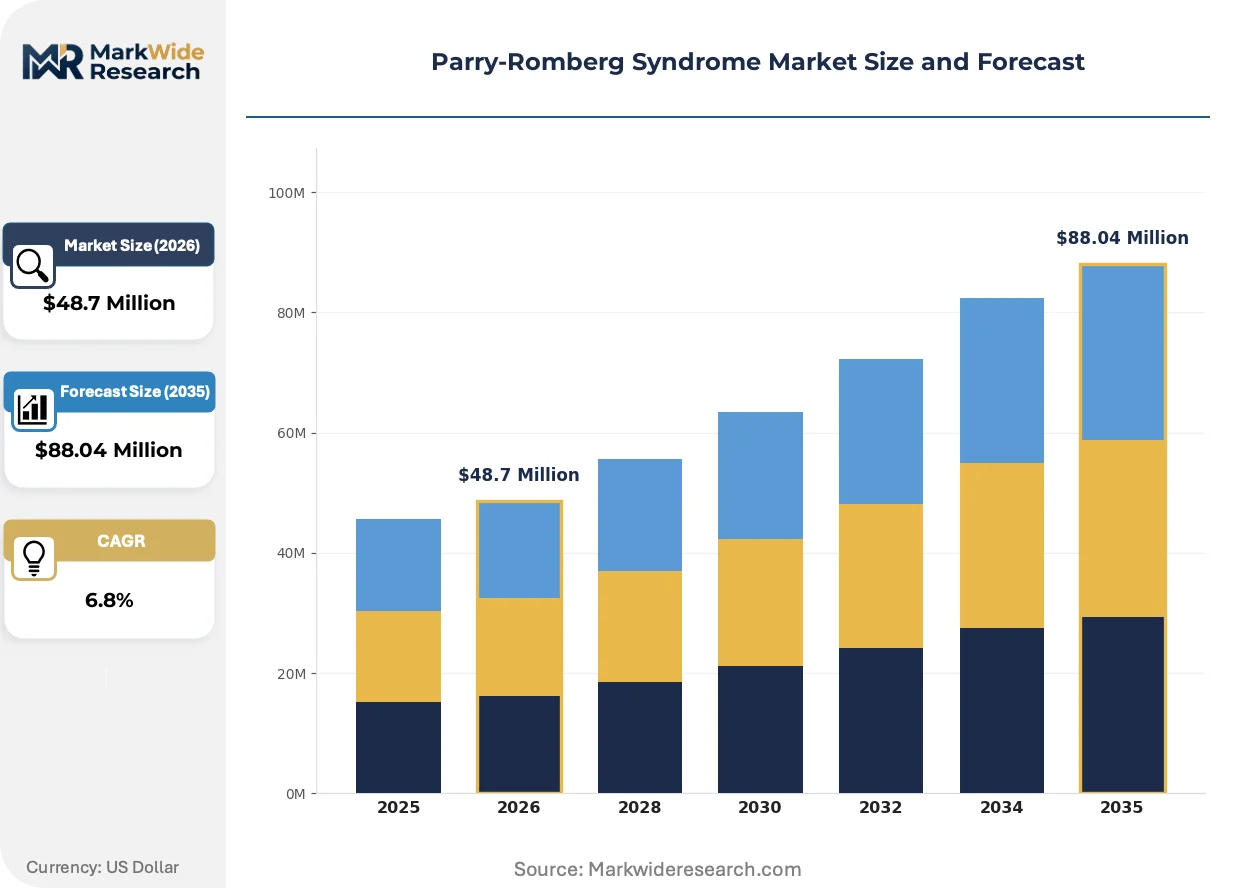
Market Dynamics
Orphan drug economics are restructuring competitive entry patterns for Parry-Romberg Syndrome therapeutics, with extended exclusivity windows attracting capital toward rare disease biologics while simultaneously fragmenting clinical trial recruitment pools across dispersed patient populations.
Growth Catalysts
- FDA Orphan Drug Tax Credits:The US tax incentive framework reduces effective R&D costs for sponsors pursuing facial tissue restoration biologics, accelerating IND filing velocity among mid-cap immunology developers.
- Specialty Clinic Networks:Outpatient surgical centers in Germany and the United States are standardizing multidisciplinary craniofacial protocols, creating predictable referral pathways for reconstructive intervention.
- Autologous Fat Grafting:This microsurgical technique is gaining protocol adoption for facial volume restoration where pharmacologic intervention proves insufficient, expanding addressable surgical caseloads.
Market Restraints
- Biologics Manufacturing Concentration:Contract development organizations in Switzerland and Massachusetts control critical fill-finish capacity for temperature-sensitive tissue therapies, creating single-source vulnerability.
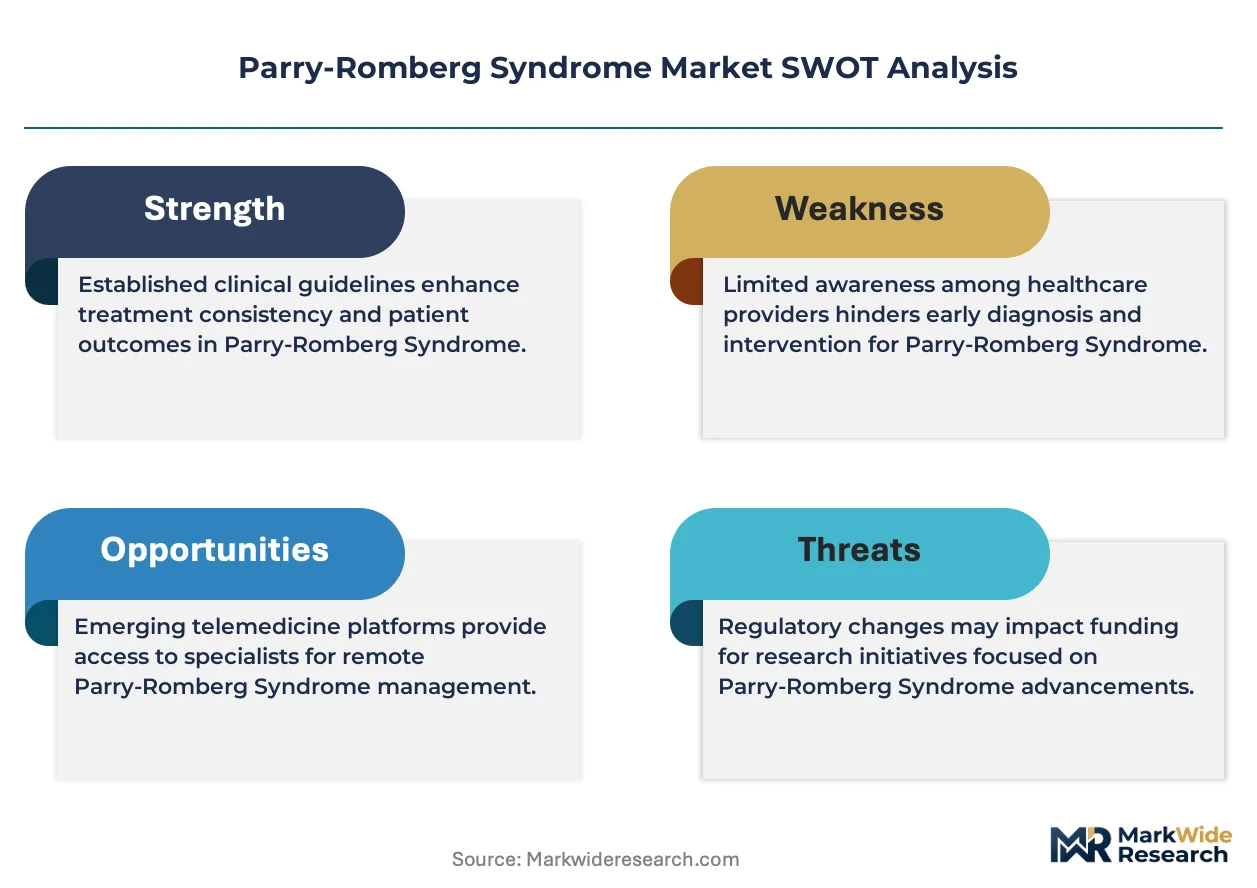
- Diagnostic Delay Friction:Average time from symptom onset to definitive Parry-Romberg Syndrome diagnosis exceeds four years in most healthcare systems, compressing the effective treatment window and limiting trial enrollment.
- Reimbursement Heterogeneity:France's ANSM and Germany's KBA apply divergent criteria for reconstructive surgery pre-authorization, forcing sponsors to maintain parallel evidence packages.
Strategic Opportunities
- Japan's Sakigake Pathway:PMDA's early approval framework for regenerative medicines offers priority review for facial tissue engineering products, enabling first-mover positioning in Asia-Pacific's second-largest pharmaceutical market.
- Pediatric Indication Expansion:Disease onset frequently occurs in childhood, yet most development programs target adult populations, leaving an unaddressed segment with distinct dosing and formulation requirements.
- Telemedicine Triage Integration:Remote dermatologic assessment platforms are penetrating rural catchment areas, potentially compressing diagnostic timelines and expanding addressable patient identification.
Industry Challenges
- Microsurgical Training Pipeline:Fellowship programs in craniofacial reconstructive surgery produce insufficient annual graduates to meet projected procedural demand, constraining service expansion.
- Cell Therapy CMC Complexity:Autologous product manufacturing requires patient-specific batch tracking and release testing, complicating scale-up beyond single-site academic production models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parry-Romberg Syndrome Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Injections, Surgical Procedures, Oral Medications Therapy Area: Dermatology, Immunology, Aesthetic Medicine, Pain Management Delivery Mode: Topical, Injectable, Oral, Surgical End User: Clinics, Hospitals, Home Care, Specialty Pharmacies |
| Companies Covered | Sanofi S.A., AstraZeneca, Pfizer Inc., Merck & Co., Johnson & Johnson, Novartis AG, GlaxoSmithKline plc, Allergan plc, Roche Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parry-Romberg Syndrome Market Strategic Shifts
Three interconnected developments are restructuring how Parry-Romberg Syndrome interventions reach patients: biologic delivery platform maturation, regulatory pathway refinement for tissue-engineered products, and care model decentralization toward ambulatory settings.
Injectable adipose-derived stem cell preparations are absorbing clinical attention as alternatives to open surgical reconstruction for moderate facial atrophy. Academic medical centers in Boston and Heidelberg are completing Phase II protocols, with preliminary data informing power calculations for pivotal trials. This technology is absorbing volume from traditional dermal filler placements by offering durable structural restoration rather than temporary volumization.
EMA's Advanced Therapy Medicinal Products framework is clarifying manufacturing and quality standards for tissue-engineered facial products, reducing regulatory uncertainty that previously deterred sponsor investment. The guidance harmonizes cell sourcing, expansion, and characterization requirements across member states. France and Germany are responding fastest, with ANSM and KBA establishing dedicated scientific advice pathways for craniofacial regenerative indications.
Patient advocacy organizations are consolidating referral influence, directing newly diagnosed individuals toward centers with established multidisciplinary protocols rather than general dermatology practices. This behavioral shift is compressing the traditional specialist-to-specialist handoff sequence, with patients arriving at reconstructive surgical consultation with completed immunology workups. The United States exhibits the most pronounced pattern, where the Romberg's Connection patient network maintains curated provider directories.
Parry-Romberg Syndrome Market Segmentation
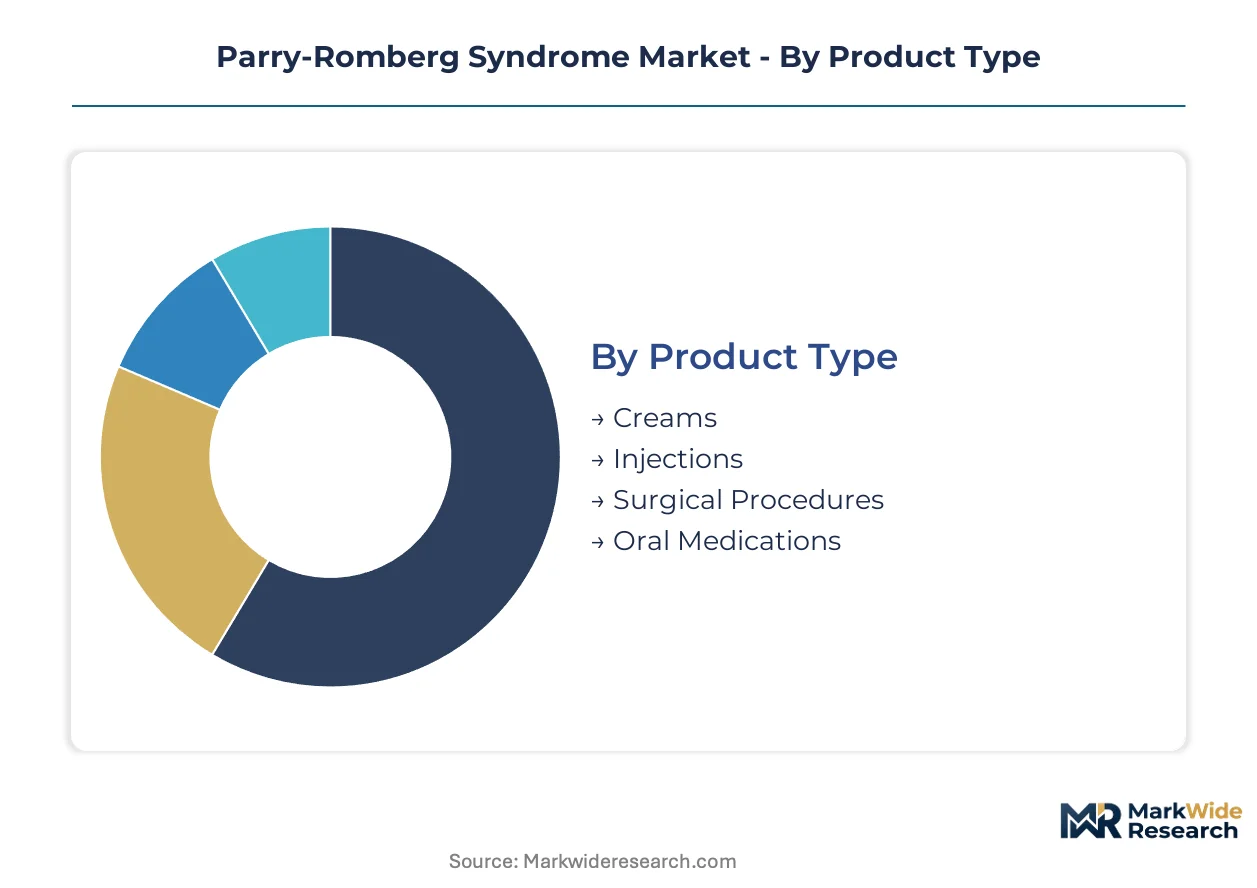
Parry-Romberg Syndrome treatment selection hinges on disease stage, tissue involvement depth, and patient tolerance for procedural intervention. Segmentation reveals how immunomodulatory biologics, reconstructive surgery, and supportive topicals partition the clinical pathway across progressive disease phases.
Product Type:
Cost tier drives initial therapy selection, with reimbursement thresholds separating pharmacologic from surgical pathways.
- Surgical Procedures:Microsurgical fat grafting and craniofacial reconstruction address advanced tissue loss beyond pharmacologic reversal. Demand concentrates in German and United States specialty clinic networks where multidisciplinary protocols standardize referral pathways.
- Injections:Biologic preparations including adipose-derived stem cell suspensions target moderate facial atrophy with durable structural restoration. Academic medical centers in Boston and Heidelberg are completing Phase II protocols, expanding addressable caseloads beyond traditional dermal fillers.
- Creams:Topical immunomodulators serve early-stage disease management as adjunctive therapy.
- Oral Medications:Systemic immunosuppressants address underlying autoimmune mechanisms in progressive disease phases.
Volume sits with Surgical Procedures; growth tilts toward Injections.
Therapy Area:
Application focus determines provider specialty and reimbursement coding complexity.
- Immunology:Disease-modifying biologics target underlying autoimmune etiology through cytokine pathway modulation. Pfizer Inc. leverages pipeline breadth to address T-cell mediated tissue destruction mechanisms.
- Aesthetic Medicine:Volume restoration and symmetry correction procedures absorb reconstructive surgical demand where functional outcomes overlap cosmetic objectives.
- Dermatology:Initial diagnostic assessment and skin-directed therapy management.
- Pain Management:Neuropathic symptom control in advanced disease stages.
Clinical volume concentrates in Immunology; Aesthetic Medicine claims the steepest expansion trajectory as regenerative techniques mature.
Delivery Mode:
Patient compliance and treatment setting requirements shape modality preference across disease progression.
- Injectable:Precision delivery of biologics and cell therapies to affected facial tissue planes. Temperature-sensitive formulations require cold-chain infrastructure controlled by contract development organizations in Switzerland and Massachusetts.
- Surgical:Open reconstruction for extensive tissue and bone involvement.
- Topical:Surface-directed therapy for early cutaneous manifestations.
- Oral:Systemic distribution for generalized immunomodulation.
Procedure volume favors Surgical delivery; Injectable modalities are gaining share fastest through ambulatory protocol adoption.
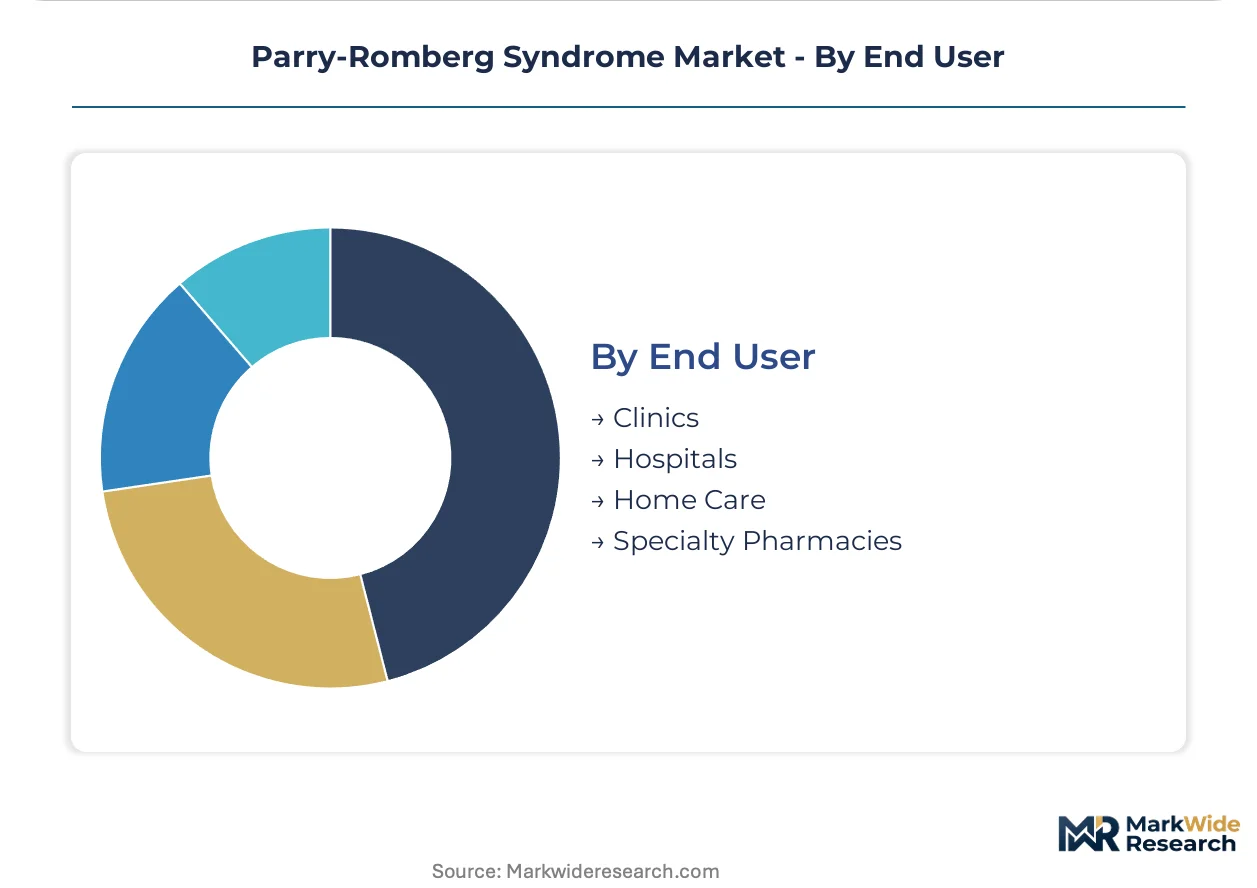
End User:
Care setting determines reimbursement pathway and capital equipment requirements.
- Specialty Clinics:Outpatient surgical centers in Germany and the United States standardize multidisciplinary craniofacial protocols. Autologous fat grafting and injectable biologics absorb volume from hospital-based reconstruction through reduced procedural overhead.
- Hospitals:Complex reconstructive cases requiring anesthesia support and inpatient monitoring.
- Home Care:Topical regimen administration and post-surgical recovery support.
- Specialty Pharmacies:Biologic dispensing and patient education for injectable therapies.
Service volume concentrates in Specialty Clinics; expansion tilts toward Hospital networks as academic medical centers scale cell therapy manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug tax credits concentrate pharmaceutical development activity in the United States, while EMA's rare disease framework and Japan's Sakigake pathway create parallel incentive structures across distinct regulatory zones.
United States
Specialty clinic networks in Boston and New York Metro standardize multidisciplinary craniofacial protocols for reconstructive intervention. The FDA's orphan drug designation pathway accelerates therapeutic development timelines through tax incentives and extended exclusivity periods. Massachusetts-based contract development organizations control critical fill-finish capacity for temperature-sensitive tissue therapies.
Germany
Outpatient surgical centers in Heidelberg and Munich absorb volume from hospital-based reconstruction through reduced procedural overhead. The KBA applies specific criteria for reconstructive surgery pre-authorization, requiring sponsors to maintain dedicated evidence packages. Bavaria hosts academic medical centers completing Phase II protocols for adipose-derived stem cell preparations.
France
ANSM's scientific advice pathways for craniofacial regenerative indications reduce regulatory uncertainty for tissue-engineered product sponsors. The country's centralized reimbursement negotiations vary by procedure type, creating distinct access pathways for surgical versus pharmacologic interventions. Paris-based research hospitals concentrate microsurgical training programs for craniofacial reconstructive surgery.
Japan
PMDA's Sakigake early approval framework offers priority review for facial tissue engineering products, enabling first-mover positioning in Asia-Pacific's second-largest pharmaceutical market. METI coordinates regenerative medicine commercialization support through designated national strategic zones. Tokyo and Osaka academic medical centers lead clinical protocol development for injectable biologic delivery platforms.
Switzerland
Swissmedic's regulatory clarity on autologous cell therapy manufacturing standards attracts sponsors seeking harmonized European market access. The country's contract development organizations command premium positioning for biologics manufacturing concentration. Basel and Zurich host specialized infrastructure for patient-specific batch tracking and release testing.
Parry-Romberg Syndrome Market Competitive Environment
Top-tier vendors anchor immunology-directed therapeutic development, while mid-cap specialists and surgical device manufacturers occupy distinct competitive tiers. The market structure reflects consolidation around rare disease biologics alongside fragmentation across reconstructive surgical supply chains. Three strategic archetypes dominate: multinational immunology developers leveraging pipeline breadth, rare disease-focused biotechs navigating orphan pathways, and microsurgical equipment specialists serving academic medical centers. Competitive moves concentrate on portfolio diversification into facial tissue restoration and strategic partnerships for cell therapy manufacturing scale-up.
Within the multinational immunology tier, Pfizer Inc., Sanofi S.A., and Novartis AG exemplify divergent approaches to autoimmune mechanism targeting. Pfizer occupies a position emphasizing pipeline breadth for T-cell mediated tissue destruction pathways. Sanofi exemplifies rare disease R&D intensity with European regulatory navigation capabilities. Novartis represents specialization in biologic delivery platforms targeting facial tissue restoration pathways.
| Leading Market Players |
|---|
| Sanofi S.A. |
| AstraZeneca |
| Pfizer Inc. |
| Merck & Co. |
| Johnson & Johnson |
| Novartis AG |
| GlaxoSmithKline plc |
| Allergan plc |
| Roche Holding AG |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade hyaluronic acid spot prices cascade through the Parry-Romberg Syndrome supply chain into three distinct procurement tiers: academic medical centers commanding volume discounts, specialty clinics absorbing premium markups for just-in-time delivery, and hospital systems negotiating bundled surgical reconstruction packages.
Pricing Analysis
Short lead-time premiums separate emergency surgical reconstruction bookings from scheduled elective procedures, with Boston and Heidelberg academic centers extracting favorable terms through guaranteed case volume commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-orphan-designated biologics commanding top-tier positioning. Cost compression in injectable adipose-derived stem cell preparations is intensifying because multiple sponsors are advancing parallel Phase II protocols. Pediatric indication development programs exhibit highest price sensitivity due to limited reimbursement precedent, while adult reconstructive surgery maintains lowest sensitivity through established procedural coding.
Supply Chain Analysis
FDA orphan drug manufacturing qualification and EMA Advanced Therapy Medicinal Products certification gate entry into the temperature-sensitive biologics tier, with only Swiss and Massachusetts contract development organizations meeting dual-jurisdiction standards. Supply concentrates in Switzerland, Massachusetts, and Bavaria for fill-finish capacity and autologous cell therapy batch release. Raw material dependencies include pharmaceutical-grade collagen matrices, cryopreservation media, and patient-specific adipose tissue harvest kits. Single-source vulnerability pervades the Swiss fill-finish node. Distribution runs through specialty pharmacy networks for outpatient injectables and direct-to-clinic surgical kits for reconstructive centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Parry-Romberg Syndrome market functions as a cost-of-compliance story where EMA's Advanced Therapy Medicinal Products framework erects barrier-to-entry moats favoring sponsors with pre-qualified manufacturing infrastructure and dedicated regulatory affairs capabilities.
For Market Incumbents: Anchor market position through backward integration into autologous cell therapy manufacturing capacity in Bavaria and Massachusetts, eliminating single-source dependency on Swiss contract development organizations. Invest in pediatric indication expansion to preempt competitor entry into the underserved childhood-onset segment. Threat vector: mid-cap immunology developers leveraging FDA orphan tax credits to compress development timelines. For New Entrants and Emerging Players: Telemedicine triage platforms offer the lowest-friction entry vector, enabling remote dermatologic assessment partnerships with rural catchment areas to compress diagnostic timelines and build referral channel relationships. Target Germany's outpatient surgical center networks as the most penetrable geography, where KBA pre-authorization pathways are standardizing faster than France's ANSM negotiations. Go-to-market angle: direct specialty clinic partnerships bypassing hospital-based procurement committees. For Investors and Strategic Acquirers: Distressed-cycle entries favor rare disease-focused biotechs with existing EMA scientific advice correspondence and Phase II-ready adipose-derived stem cell protocols in Heidelberg or Boston clusters. Long-term viability hinges on five-to-ten-year regulatory exclusivity windows and successful pediatric indication expansion. Signal to watch: PMDA Sakigake pathway approval for facial tissue engineering products as Asia-Pacific market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits reduce effective R&D costs for facial tissue restoration biologics. |
| Pediatric Indication Expansion | Childhood-onset disease prevalence creates unaddressed segment with distinct formulation requirements. |
| Specialty Clinic Network Partnerships | Outpatient surgical centers in Germany and the United States standardize multidisciplinary referral pathways. |
| Autologous Manufacturing Scale-Up | Patient-specific batch tracking infrastructure addresses cell therapy CMC complexity beyond academic production. |
| EMA Scientific Advice Engagement | Advanced Therapy Medicinal Products framework clarification reduces regulatory uncertainty for tissue-engineered sponsors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with reconstructive surgeons, specialty clinic operations directors, orphan drug regulatory affairs leads, and hospital procurement managers. FDA orphan drug designation databases, EMA scientific advice correspondence logs, ClinicalTrials.gov protocol registries, and German KBA reimbursement decision archives provided structured secondary validation. Bottom-up patient population estimates and top-down pharmaceutical development pipeline valuations were triangulated to constrain forecast ranges.
Granularity-level modeling addressed therapy area segmentation by immunology, aesthetic medicine, dermatology, and pain management; product type disaggregation across surgical procedures, injections, creams, and oral medications; and delivery mode differentiation between injectable, surgical, topical, and oral routes. CAGRs were derived from log-linear trend fitting across the analysis window, with cross-segment consistency checks enforcing logical relationships between adjacent categories. Forecast inputs incorporated orphan drug approval probability weightings and specialty clinic network expansion trajectories.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time specialty clinic procedure volume reporting introduce uncertainty bands around near-term surgical reconstruction forecasts. Model outputs reflect assumptions regarding orphan drug exclusivity period utilization and stable reimbursement coding for autologous fat grafting procedures. A model refresh is warranted upon material change in PMDA Sakigake pathway approval timelines or EMA Advanced Therapy Medicinal Products manufacturing guidance revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Batten Disease Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
North America Rett Syndrome Market