
 Autonomous Material Handling Equipment Market | 2026-2036
Autonomous Material Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Material Handling Equipment Market Analytics
E-commerce fulfillment is recalibrating equipment specifications toward higher throughput and smaller footprint designs. Daifuku Co., Ltd. leverages its conveyor-centric heritage to dominate airport baggage and retail distribution verticals. KION Group AG sustains manufacturing scale across European and Asian production networks. Dematic competes through dense software-hardware integration in grocery and apparel fulfillment.
Autonomous material handling equipment comprises self-propelled vehicles and robotic systems that transport, lift, sort, or store goods without direct human operation, typically incorporating LiDAR arrays, inertial measurement units, and programmable logic controllers to navigate dynamic warehouse environments. These systems serve to compress order cycle times, reduce labor injury rates, and enable continuous operation in temperature-controlled or hazardous zones. Automated Mobile Robots lead volume adoption among product types due to lower infrastructure requirements and retrofit compatibility with existing racking. Order Fulfillment commands the fastest application growth as same-day and next-day delivery service levels tighten across retail and pharmaceutical distribution. LiDAR-based navigation systems anchor premium pricing tiers where centimeter-level positional accuracy prevents product damage in narrow-aisle configurations.
The EU Machinery Directive and ISO 3691-4 safety standards mandate protective field monitoring and emergency braking protocols, elevating engineering costs for European market access while reducing liability exposure for compliant deployers. OSHA workplace injury reporting requirements in the United States accelerate substitution of manual forklift operations with sensor-equipped autonomous alternatives in high-frequency handling environments. Stakeholders must weigh regional certification timelines against fleet deployment schedules when selecting technology partners and manufacturing sourcing strategies.
Market Dynamics
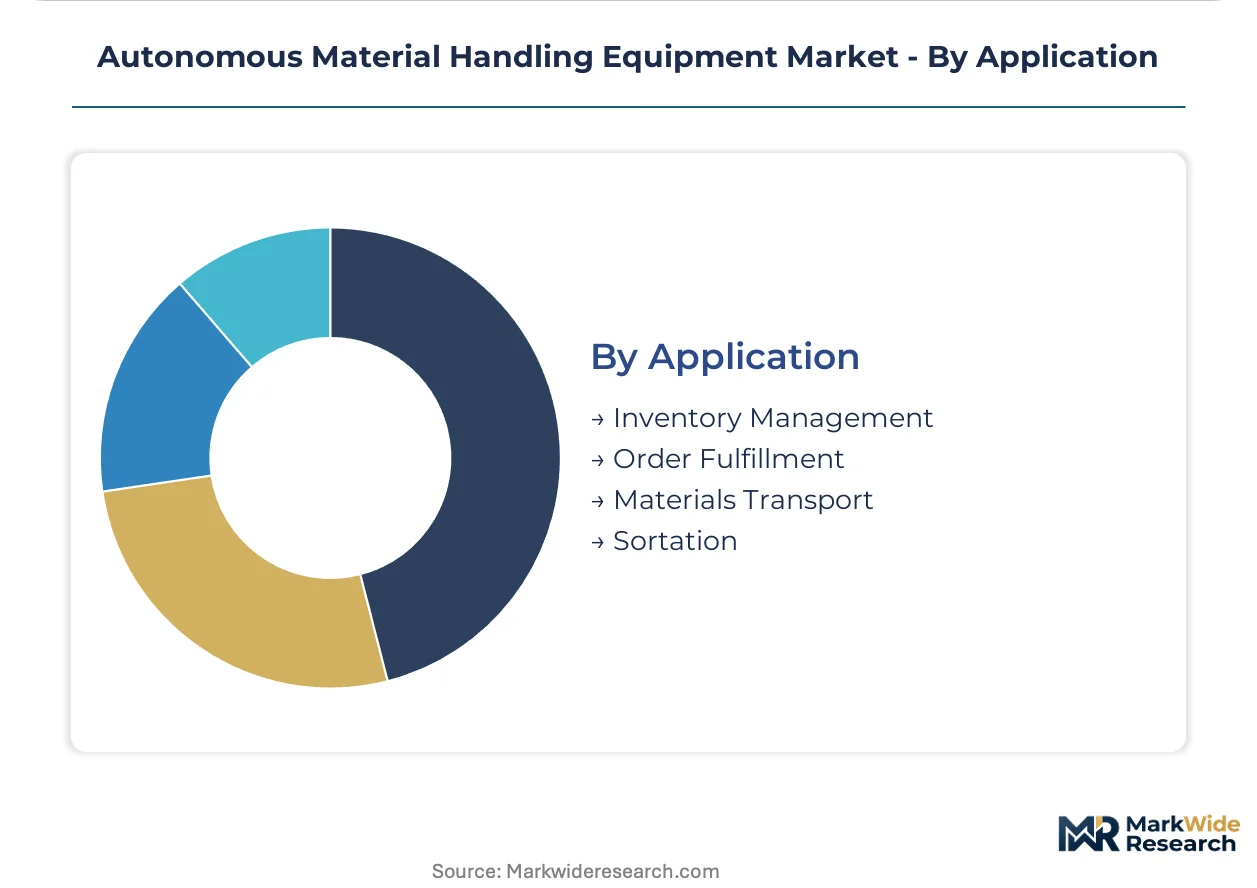
The EU Machinery Directive and ISO 3691-4 safety standards are compressing certification timelines while elevating engineering costs, forcing manufacturers to restructure R&D budgets and accelerate protective field monitoring capabilities ahead of fleet deployment schedules.
Growth Catalysts
- OSHA workplace injury reporting:High-frequency handling environments in the United States face intensified scrutiny, accelerating substitution of manual forklift fleets with sensor-equipped autonomous alternatives to reduce liability exposure and downtime incidents.
- Automotive cluster density in Germany:Stuttgart and Wolfsburg logistics hubs drive concentrated fleet procurement as just-in-sequence manufacturing demands continuous material flow without human shift limitations.
- LiDAR array cost curves:Solid-state sensor production scaling is compressing navigation system pricing, enabling centimeter-level accuracy deployments in narrow-aisle retrofit environments previously reserved for premium greenfield installations.
Market Restraints
- Protective field monitoring hardware:ISO 3691-4 compliant sensor suites and emergency braking modules add substantial BOM costs, particularly for European market access where liability frameworks mandate full certification before operational deployment.
- Rare earth magnet supply concentration:Permanent magnet motors for drive systems face input volatility tied to processing capacity in China, exposing fleet manufacturers to procurement risk during contract manufacturing negotiations.
- Legacy WMS integration complexity:Existing warehouse management system architectures lack native API protocols for autonomous fleet orchestration, requiring costly middleware development that extends deployment timelines.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Temperature-controlled distribution centers in the United States present white space for autonomous systems capable of continuous operation in hazardous or sub-zero environments where labor availability constrains throughput.
- EU Green Deal operational incentives:Carbon footprint reduction mandates for logistics operations create procurement preference for electric autonomous fleets over diesel forklift alternatives in Netherlands and Belgium distribution hubs.
- 5G private network convergence:Ultra-reliable low-latency communication infrastructure is enabling real-time fleet coordination at densities impossible under Wi-Fi 6, opening high-velocity sortation applications in apparel fulfillment.
Industry Challenges
- Functional safety engineering scarcity:ISO 13849 and IEC 62061 certified control system designers command premium compensation, constraining manufacturer capacity to parallelize certification programs across multiple product lines.
- Retrofit integration timelines:Existing racking clearances and floor specifications in brownfield facilities require extensive site surveys and structural modifications, compressing project margins and extending customer acceptance periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Material Handling Equipment Market |
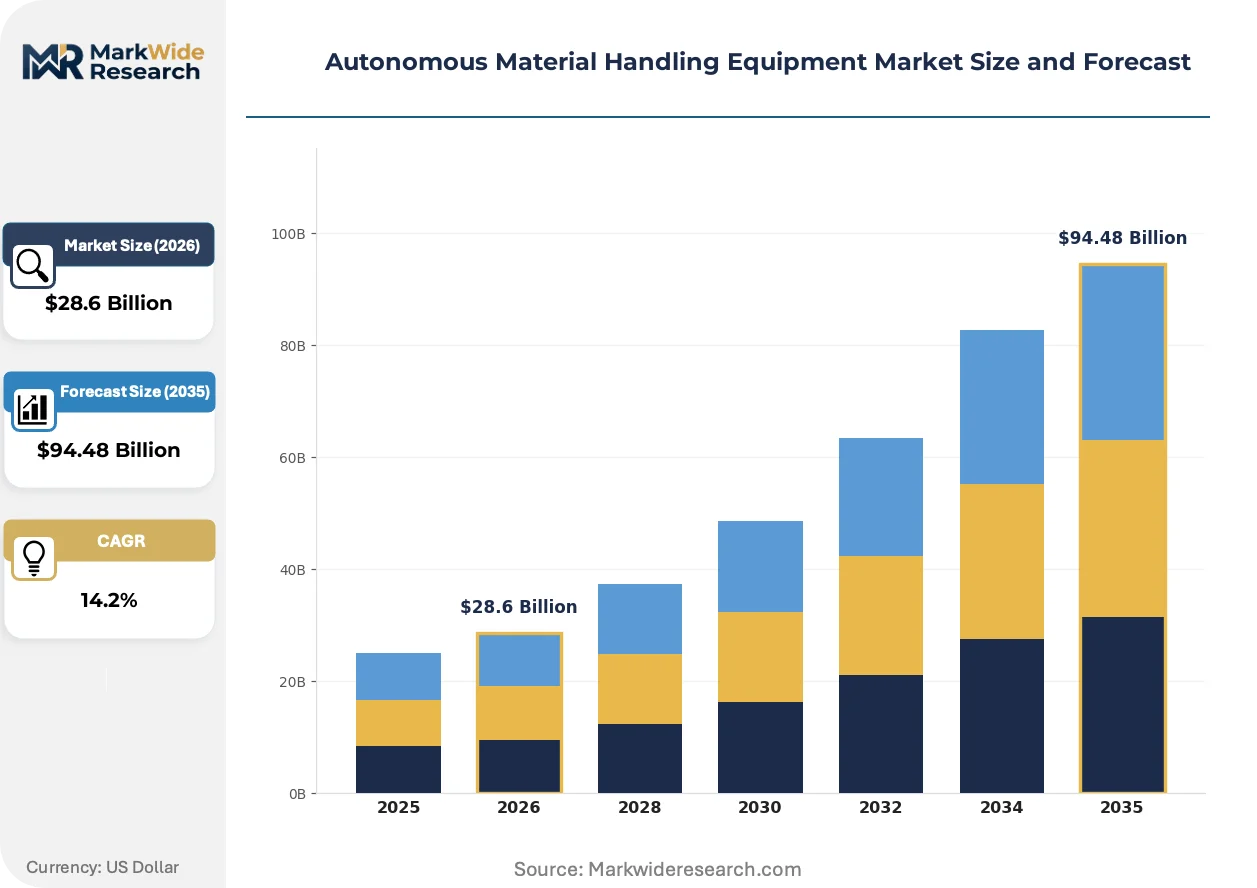
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Autonomous Mobile Robots, Drones, Automated Forklifts End User: Manufacturing, E-Commerce, Warehousing, Healthcare Technology: LiDAR, Computer Vision, RFID, Navigation Systems Application: Inventory Management, Order Fulfillment, Materials Transport, Sortation |
| Companies Covered | Daifuku Co., Ltd., KION Group AG, SSI Schaefer, Toyota Industries Corporation, Honeywell International Inc., Jungheinrich AG, Dematic, BEUMER Group, Swisslog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Material Handling Equipment Market Evolving Landscape
Swarm intelligence architectures and edge-compute navigation are displacing centralized fleet management models, while regulatory pressure on operational safety accelerates protective technology adoption across high-velocity handling environments.
Visual-inertial odometry fused with semantic scene understanding is decentralizing navigation authority from fixed infrastructure to individual vehicle compute nodes. Grocery and apparel fulfillment centers are adopting these systems at accelerated pace to enable dynamic path replanning around human pedestrians without warehouse-wide network dependency. This architecture is decentralizing capital deployment patterns, allowing phased fleet expansion without upfront facility-wide sensor installation.
REACH chemical substance restrictions and RoHS hazardous material limitations are reshaping battery chemistry selection and electronics assembly protocols for European market access. Manufacturers must reformulate power systems and solder compositions to maintain CE marking eligibility, elevating supply chain qualification burdens. Automated Mobile Robot categories face the steepest compliance cost absorption due to their higher electronics density relative to conveyor-based alternatives.
Equipment-as-a-service contracting is displacing traditional capital purchase models in mid-market logistics operations. Third-party logistics providers in Germany and the Netherlands are leading this transition, preferring per-pallet-handled pricing that transfers fleet optimization risk to technology vendors. This restructuring is most visible in automotive supplier parks where OEM production volatility makes fixed asset ownership economically unattractive.
Autonomous Material Handling Equipment Market Segmentation
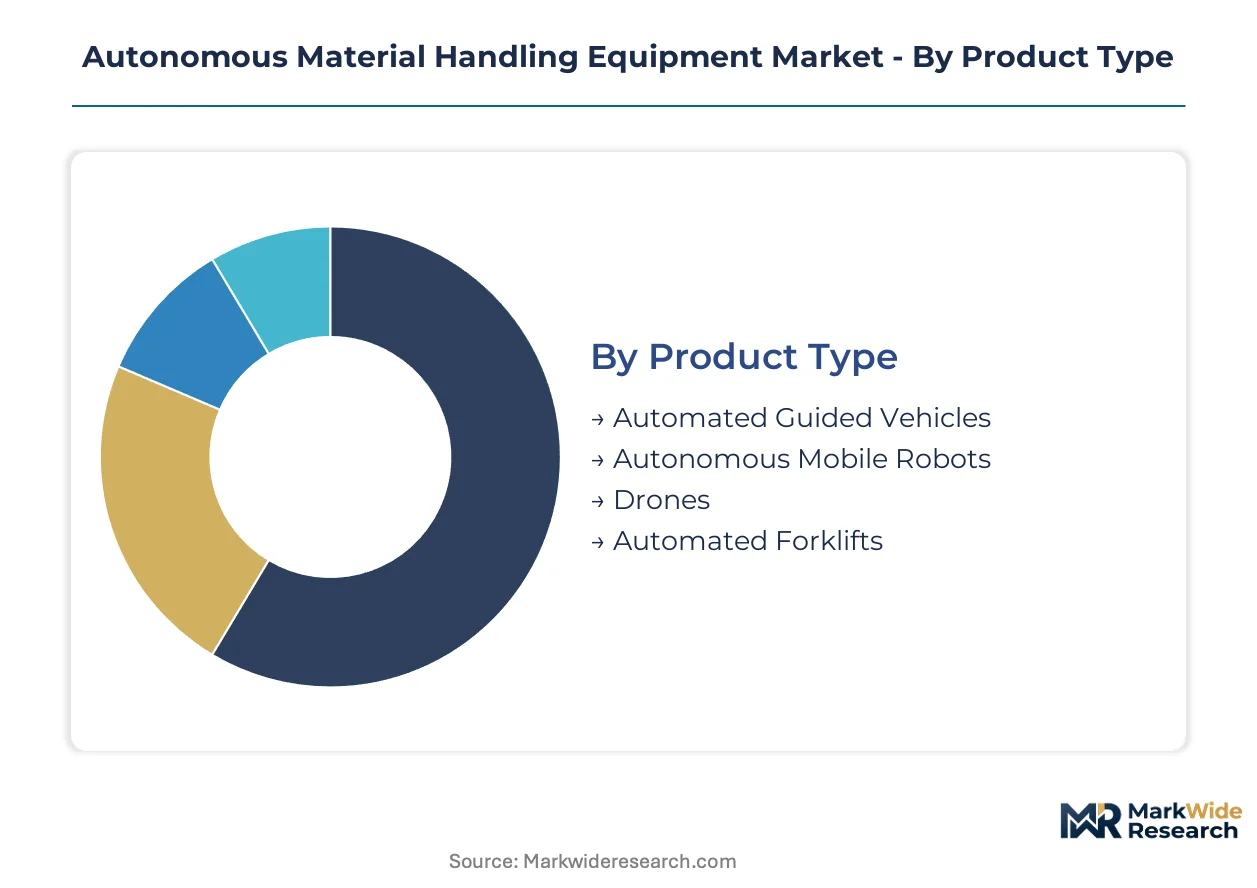
Equipment replacement cycles and facility modernization timelines dictate segment prioritization across procurement portfolios. Buyers align technology selection with existing infrastructure compatibility and workforce transition constraints.
Product Type:
Upgrade trajectories favor retrofit-friendly architectures that minimize structural modifications during brownfield deployments.
- Automated Guided Vehicles:Wire-guided and magnetic tape-based navigation systems dominate legacy installations in automotive assembly plants. Stuttgart manufacturing clusters sustain replacement demand as magnetic sensor arrays reach end-of-life and require LiDAR retrofits to meet ISO 3691-4 protective field requirements.
- Autonomous Mobile Robots:Swarm-enabled units with edge-compute navigation reduce dependency on facility-wide sensor infrastructure. E-commerce fulfillment centers in Germany and the Netherlands deploy these systems to enable phased fleet expansion without upfront capital commitment to fixed guidance installations.
- Drones:Aerial inventory scanning units with barcode recognition and RFID interrogation capabilities serve high-bay warehouse applications where vertical space utilization exceeds human reach.
- Automated Forklifts:Sensor-equipped pallet handling units with emergency braking protocols substitute manual forklift fleets in high-frequency environments facing OSHA injury reporting scrutiny.
Automated Mobile Robots sit at the top of the volume ranking, with Autonomous Mobile Robots climbing the fastest as retrofit compatibility accelerates procurement timelines.
End User:
Margin structures vary sharply across customer archetypes, with capital intensity and operational volatility shaping contract terms.
- Manufacturing:Just-in-sequence production lines in Wolfsburg and Stuttgart automotive supplier parks demand continuous material flow without shift limitations. Equipment-as-a-service contracting dominates here as OEM production volatility makes fixed asset ownership economically unattractive.
- E-Commerce:Same-day delivery service levels compress order cycle times and drive dense software-hardware integration requirements in grocery and apparel fulfillment.
- Warehousing:Third-party logistics operations in Belgium and Netherlands distribution hubs prioritize per-pallet-handled pricing that transfers fleet optimization risk to technology vendors.
- Healthcare:Pharmaceutical cold chain facilities in temperature-controlled environments require autonomous systems capable of continuous operation where labor availability constrains throughput.
Manufacturing commands the largest installed base, though E-Commerce is expanding most quickly as fulfillment specifications tighten.
Technology:
Cost tier differentiation separates premium navigation accuracy from commodity positioning systems.
- LiDAR:Solid-state sensor arrays with centimeter-level positional accuracy anchor premium pricing tiers. Narrow-aisle retrofit environments previously reserved for greenfield installations now access this capability as production scaling compresses unit costs.
- Computer Vision:Visual-inertial odometry fused with semantic scene understanding enables dynamic path replanning around human pedestrians without warehouse-wide network dependency.
- RFID:Passive and active tag interrogation systems support inventory tracking and authentication in pharmaceutical distribution where chain-of-custody documentation is mandatory.
- Navigation Systems:Integrated sensor fusion platforms combining inertial measurement units, wheel encoders, and landmark recognition serve as the foundational positioning layer across all autonomous vehicle categories.
LiDAR maintains the highest average selling prices, while Computer Vision is gaining share fastest through edge-compute decentralization.
Application:
Maturity curves separate established use cases from emerging deployment patterns.
- Order Fulfillment:Piece-picking and case-picking operations in apparel and grocery distribution face the tightest service level agreements. 5G private network convergence enables real-time fleet coordination at densities impossible under prior Wi-Fi infrastructure.
- Materials Transport:Point-to-point pallet movement between receiving docks and storage racks represents the most standardized autonomous application with established safety certification pathways.
- Inventory Management:Cycle counting and stock location verification through aerial and ground-based scanning reduces labor hours in high-SKU-count environments.
- Sortation:High-velocity parcel routing in cross-dock operations demands sub-second decision latency and precise divert timing.
Materials Transport holds the deepest installed base, with Order Fulfillment showing the steepest expansion trajectory as delivery windows compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined certification pathways. The EU Machinery Directive elevates compliance costs for European market access, while OSHA enforcement patterns in the United States accelerate fleet substitution timelines. Asian production networks capture contract manufacturing volumes where CE marking requirements do not constrain bill-of-material decisions.
United States
OSHA workplace injury reporting requirements intensify scrutiny of manual forklift operations in high-frequency handling environments. Pharmaceutical cold chain facilities in temperature-controlled distribution centers present white space for autonomous systems where labor availability constrains throughput. The Southeast automotive supplier corridor sustains equipment-as-a-service contracting as OEM production volatility makes fixed asset ownership economically unattractive.
Germany
Automotive cluster density in Stuttgart and Wolfsburg drives concentrated fleet procurement for just-in-sequence manufacturing demands. The EU Machinery Directive and ISO 3691-4 safety standards mandate protective field monitoring and emergency braking protocols before operational deployment. Third-party logistics providers in the Netherlands and Belgium distribution hubs prefer per-pallet-handled pricing that transfers fleet optimization risk to technology vendors.
China
Rare earth magnet supply concentration for permanent magnet motors exposes fleet manufacturers to procurement risk during contract manufacturing negotiations. GB standards and MIIT regulations shape domestic product certification requirements distinct from European frameworks. Yangtze River Delta logistics hubs deploy retrofit-compatible autonomous mobile robots to enable phased fleet expansion without upfront capital commitment to fixed guidance installations.
Japan
METI operational incentives and JIS standards anchor domestic safety certification frameworks for warehouse automation deployments. Visual-inertial odometry fused with semantic scene understanding enables dynamic path replanning around human pedestrians without warehouse-wide network dependency. Kansai manufacturing clusters adopt edge-compute navigation architectures to decentralize capital deployment patterns across brownfield facilities.
Netherlands
EU Green Deal carbon footprint reduction mandates for logistics operations create procurement preference for electric autonomous fleets over diesel forklift alternatives. REACH chemical substance restrictions and RoHS hazardous material limitations reshape battery chemistry selection for European market access. Randstad distribution hubs concentrate third-party logistics operations where equipment-as-a-service contracting displaces traditional capital purchase models.
Autonomous Material Handling Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects commanding premium positioning in fulfillment verticals while component suppliers capture volume in retrofit applications. The vendor base concentrates around three strategic archetypes: conveyor-centric heritage players, software-hardware integrators, and scale-driven industrial conglomerates. M&A activity targets navigation software capabilities, while strategic partnerships with 5G infrastructure providers enable real-time fleet coordination at densities impossible under prior Wi-Fi infrastructure.
Within the integrated system tier, Daifuku Co., Ltd. and KION Group AG exemplify divergent geographic anchoring strategies, with the former leveraging Japanese engineering heritage and the latter sustaining manufacturing scale across European and Asian production networks. Dematic occupies a position representing dense software-hardware integration specialization in grocery and apparel fulfillment verticals. These three entities collectively illustrate how heritage capabilities and regional certification expertise shape competitive positioning under tightening ISO 3691-4 and EU Machinery Directive compliance timelines.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| KION Group AG |
| SSI Schaefer |
| Toyota Industries Corporation |
| Honeywell International Inc. |
| Jungheinrich AG |
| Dematic |
| BEUMER Group |
| Swisslog |
| Others |
Value Network & Pricing Analysis
Solid-state LiDAR production scaling is compressing navigation system costs while concentrating manufacturing capacity among Asian sensor foundries, simultaneously reshaping equipment pricing tiers and procurement risk profiles for fleet deployers.
Pricing Analysis
Distributor margins in the 15-25% range separate direct-to-OEM fleet sales from third-party logistics procurement channels. Three-tier pricing structure across premium, standard, and economy levels aligns with ISO 3691-4 certification completeness and LiDAR array density. Pricing pressure stems from equipment-as-a-service contracting displacing capital purchases in German automotive supplier parks. Mid-market warehousing operations exhibit highest price sensitivity, while pharmaceutical cold chain facilities prioritize operational continuity over unit economics.
Supply Chain Analysis
Permanent magnet motor supply rests on Chinese rare earth processing capacity, Japanese solid-state LiDAR fabrication, and German precision drive component manufacturing. Critical inputs include neodymium-iron-boron magnets, indium gallium arsenide photodetectors, and silicon carbide power semiconductors. Single-source vulnerability in Chinese magnet refining exposes fleet manufacturers to procurement disruption during contract negotiations. Distribution runs through regional system integrators in Stuttgart and Rotterdam before final deployment at manufacturing clusters and fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 3691-4 protective field mandates are accelerating fleet replacement cycles, compounding demand for certified autonomous systems across European logistics operations.
For Market Incumbents: Extend certification coverage across Autonomous Mobile Robot product lines before EU Machinery Directive enforcement tightens. Acquire ISO 13849 control system design capabilities to reduce functional safety engineering bottlenecks. Build captive LiDAR sensor supply through backward integration into solid-state fabrication partnerships. Defend against emerging swarm-robotics specialists by embedding edge-compute navigation deeper into hardware architectures.
For New Entrants and Emerging Players: Third-party logistics providers in Belgium and the Netherlands represent the most penetrable channel for equipment-as-a-service contracting. Target pharmaceutical cold chain facilities in the United States where labor constraints and temperature requirements favor autonomous substitution. Pursue white-label navigation software licensing to established conveyor manufacturers lacking native autonomy stacks.
For Investors and Strategic Acquirers: Valuations sit cheapest among brownfield retrofit specialists with established middleware integration capabilities. Long-term viability favors vendors controlling both fleet orchestration software and protective field hardware certification pathways. Watch 5G private network deployment velocity in apparel fulfillment as inflection signal for high-density coordination demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 3691-4 Certification Acceleration | Compresses market access timelines for European fleet deployments while elevating engineering barriers. |
| Equipment-as-a-Service Contracting | Transfers fleet optimization risk to vendors in German automotive supplier parks facing production volatility. |
| 5G Private Network Partnerships | Enables real-time swarm coordination densities impossible under legacy Wi-Fi infrastructure in apparel fulfillment. |
| Backward Integration into LiDAR | Captures sensor cost compression and secures supply continuity against Asian foundry concentration. |
| Pharmaceutical Cold Chain Expansion | Opens white space for continuous-operation systems where sub-zero labor availability constrains throughput. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and the Netherlands, with primary inputs from each market cluster. The analysis combines structured interviews with warehouse operations directors, OEM procurement managers, and autonomous fleet deployment specialists with secondary validation against customs trade data, SEC 10-K filings, and EU Machinery Directive implementation notices. Bottom-up equipment shipment tallies triangulate against top-down logistics automation capex surveys to anchor volume estimates.
Granularity-level modeling disaggregates revenue across product type, navigation technology tier, end-use vertical, and regional regulatory cluster throughout the projection horizon. CAGRs derive from logistic curve adoption modeling fitted to brownfield retrofit penetration rates and greenfield installation schedules. Industry-specific forecast inputs include e-commerce fulfillment center buildout pipelines, automotive just-in-sequence manufacturing volatility indices, and LiDAR sensor cost curve trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions, 5G infrastructure deployment cadence, and EU Machinery Directive enforcement variance across member states. The analysis reflects documented assumptions regarding fleet replacement cycles and certification timeline elasticity. A small set of triggers—including OSHA enforcement pattern shifts, Chinese export restriction announcements, and major 5G private network operational deployments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Hydraulic Hoist Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Global Dewatering Equipment Market