
 Anti-Plagiarism Software Market | 2026-2036
Anti-Plagiarism Software Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Plagiarism Software Market Analysis
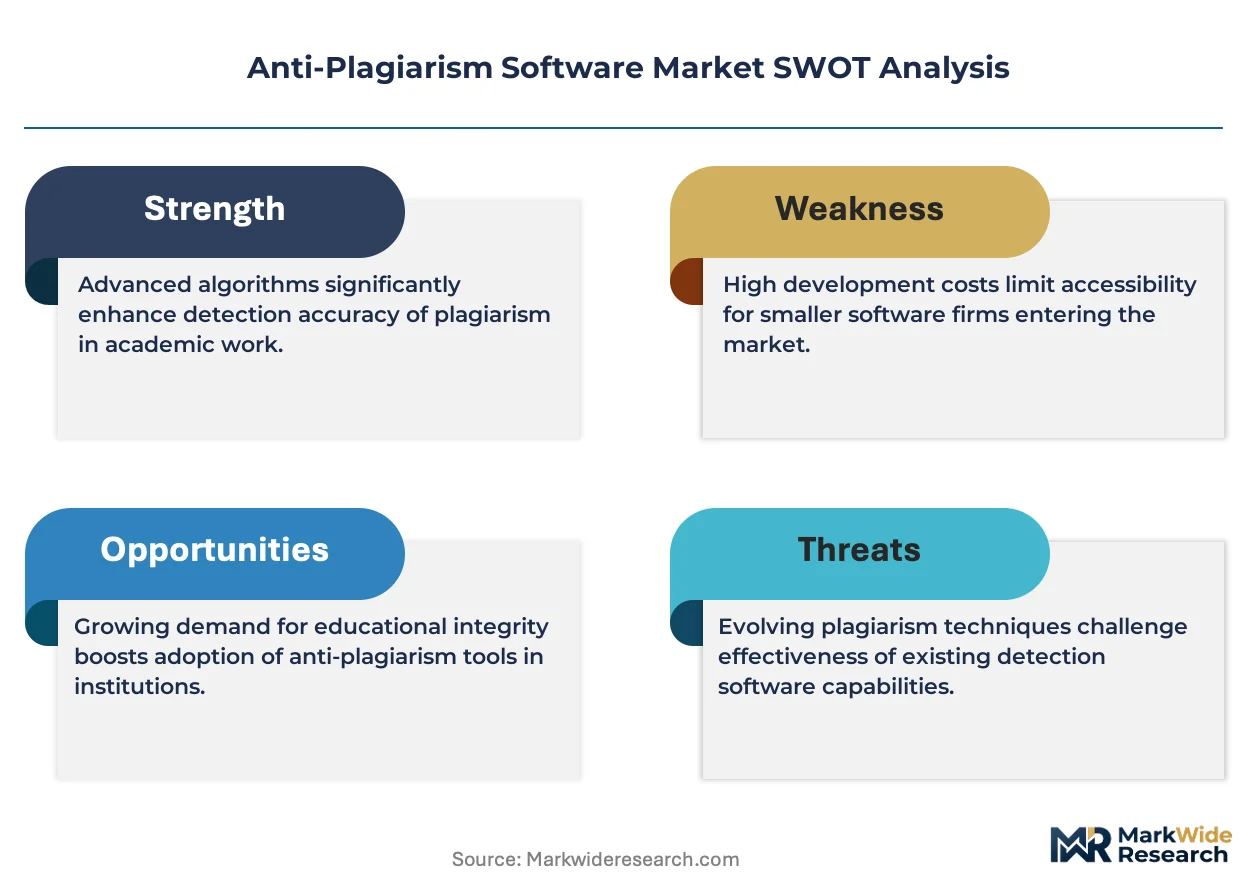
Subscription-based financing and SaaS leasing models is rewriting competitive dynamics for smaller entrants in the anti-plagiarism software space. Grammarly leverages freemium-to-paid conversion mechanics to sustain a massive user funnel across 30 million daily active accounts. Turnitin anchors institutional procurement through deep LMS integration and multi-year campus-wide contracts. Copyleaks specializes in enterprise API deployments, positioning its verification engine inside content management workflows rather than standalone interfaces.
Anti-plagiarism software comprises algorithmic text-matching systems that compare submitted documents against indexed repositories, employing fingerprinting, string-matching, and natural language processing to calculate similarity scores and flag unattributed overlap. These tools serve primary commercial purposes in academic integrity enforcement, content originality certification, and intellectual property protection across publishing and corporate knowledge management. Cloud-based deployment leads volume adoption among educational institutions seeking zero-maintenance infrastructure, while API integration represents the fastest-growing segment as platforms embed verification natively into writing environments. The subscription pricing model dominates recurring revenue structures, though freemium tiers increasingly function as user acquisition channels rather than sustainable monetization paths.
The U.S. Department of Education and Federal Research Integrity Policy shape institutional procurement requirements, while the EU AI Act establishes transparency obligations for automated content evaluation systems that vendors must architect around. GDPR and emerging state-level student data privacy laws in California and Illinois constrain cross-border data processing architectures, forcing localization of document fingerprinting databases. Stakeholders must monitor whether generative AI detection accuracy claims trigger FTC scrutiny over deceptive marketing practices, as false positive rates become a litmus test for vendor credibility and contract renewal rates.
Market Dynamics
Generative AI proliferation is forcing plagiarism detection vendors to rebuild algorithmic foundations around synthetic text identification rather than traditional source-matching, compressing development timelines and raising R&D burn rates across the competitive set.
Growth Catalysts
- Federal Research Integrity Policy:US funding agencies now mandate originality verification for grant applications, compelling universities to upgrade detection infrastructure and expand licensed seat counts.
- Large Language Model Integration:Publishers are embedding verification APIs directly into editorial workflows, creating embedded demand that bypasses standalone software procurement cycles.
- Corporate Knowledge Management:Fortune 500 legal departments are deploying plagiarism detection for internal document originality certification, opening non-academic revenue streams.
Market Restraints
- False Positive Contamination:AI-generated content detection algorithms exhibit elevated error rates against non-native English writing, creating liability exposure that slows enterprise adoption.
- Data Localization Mandates:GDPR and emerging state-level student privacy laws in California and Illinois force vendors to fragment document fingerprinting databases across jurisdictional boundaries, raising infrastructure costs.
- Open-Source Substitution:Free detection tools built on transformer architectures are capturing price-sensitive segments in emerging markets, compressing addressable market expansion.
Strategic Opportunities
- EU AI Act Compliance Services:Transparency obligations for automated content evaluation create advisory and certification revenue streams adjacent to core software licensing.
- India Higher Education Expansion:Central government mandates for academic integrity infrastructure across 1,000+ new universities under the National Education Policy create concentrated procurement windows.
- Multimodal Detection Convergence:Integration of image, audio, and code similarity detection alongside text expands total addressable use cases beyond traditional document verification.
Industry Challenges
- Computational Linguistics Talent Scarcity:Vendors compete for limited pools of researchers with expertise in stylometry and adversarial machine learning, inflating compensation costs.
- LMS Integration Complexity:Legacy learning management systems require custom API development for seamless embedding, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Plagiarism Software Market |
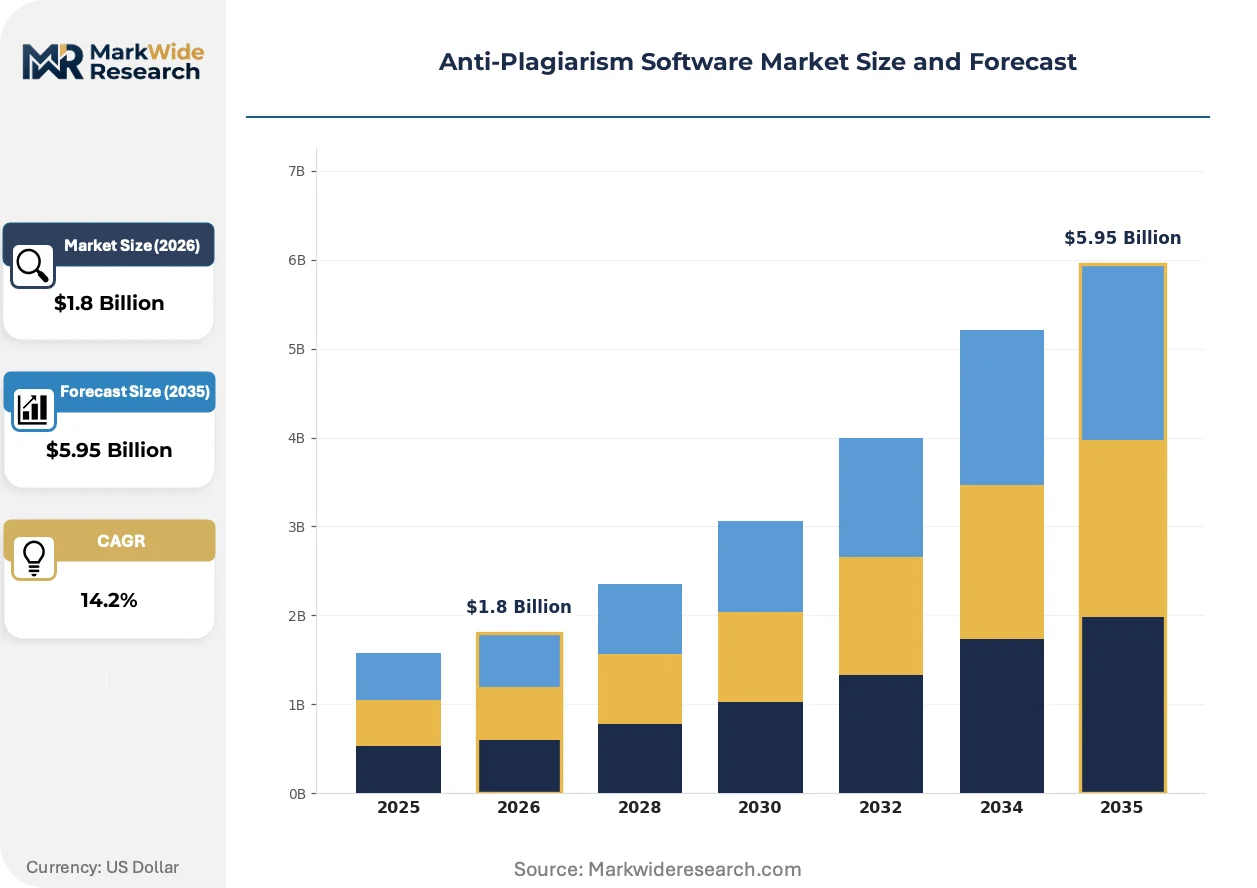
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop, Web-based, Mobile App, API End User: Educational Institutions, Corporates, Publishers, Students Deployment: Cloud-based, On-premises, Hybrid, SaaS Pricing Model: Subscription, One-time License, Freemium, Pay-as-you-go |
| Companies Covered | Scribbr, Grammarly, Winston AI, Quetext, Copyscape, Turnitin, Copyleaks, PlagScan, Paperpal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Plagiarism Software Market Emerging Trajectories
Detection methodology is pivoting from retrospective similarity scoring to real-time synthetic content interception, with vendors racing to embed verification engines at the point of content creation rather than submission.
Stylometric fingerprinting is migrating from post-hoc document analysis to continuous author verification during the writing process. EdTech platforms deploying this capability report reduced investigation overhead. The structural consequence is that standalone detection interfaces are losing share to invisible background processes.
The EU AI Act establishes mandatory disclosure requirements for automated content evaluation systems used in educational assessment. Vendors must architect explainability features that expose detection rationale to end-users. European universities are prioritizing procurement of systems with built-in audit trails and human-in-the-loop override capabilities.
Enterprise buyers are unbundling verification services from comprehensive academic integrity suites, selecting best-of-breed API components for specific use cases. This fragmentation favors specialized vendors with narrow technical excellence over platform consolidators. The pattern is most pronounced in US legal publishing and pharmaceutical regulatory writing environments.
Anti-Plagiarism Software Market Segmentation
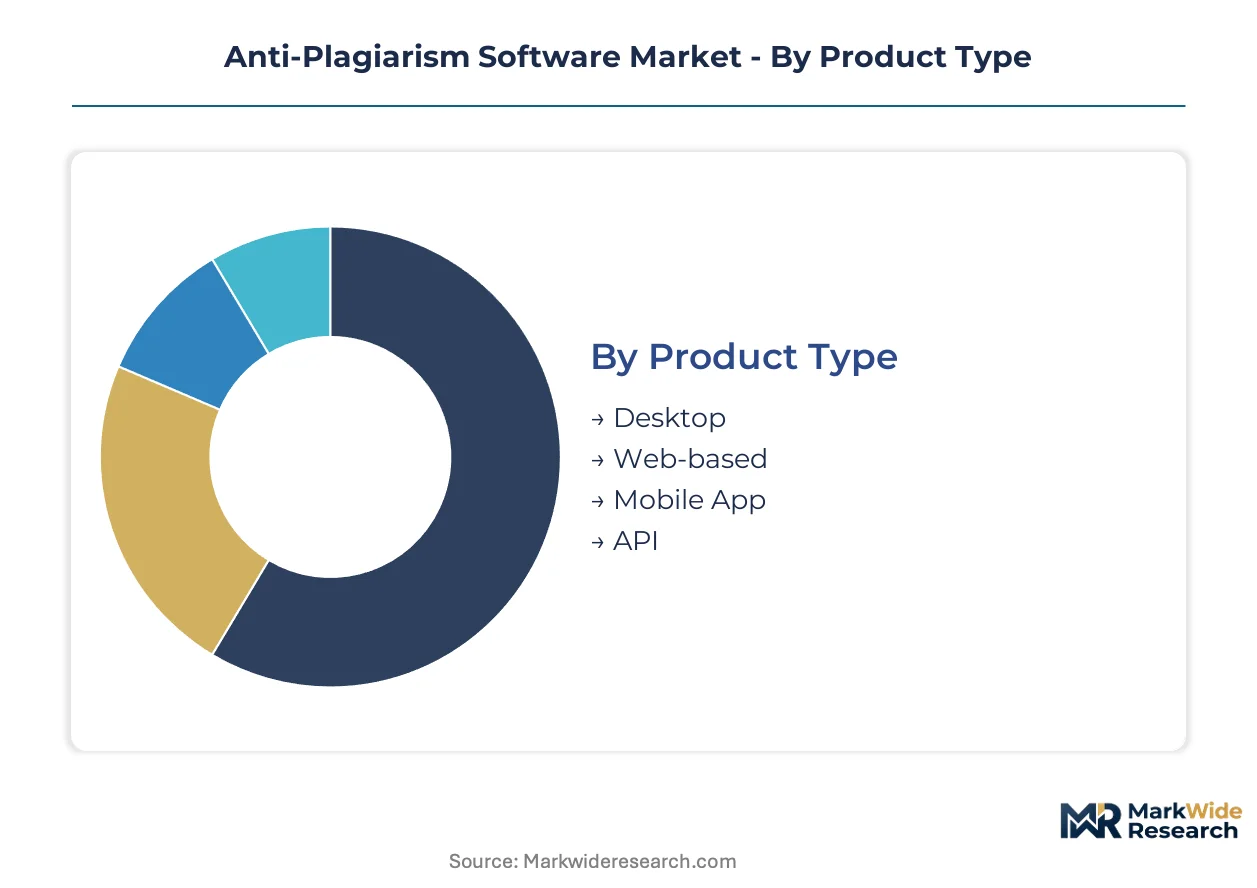
Segmentation in anti-plagiarism software reveals how procurement patterns split across technical architectures, customer workflows, and financial structures. Each dimension carries distinct margin profiles and competitive dynamics that vendors must navigate.
Product Type:
Technical delivery format determines integration depth and user friction across customer environments.
- Web-based:Browser-native interfaces eliminate installation overhead and enable instant deployment across distributed user bases. Universities in the United States prioritize these solutions for multi-campus standardization, though SSO integration complexity extends procurement cycles.
- API:Headless verification engines embed directly into content management systems and editorial workflows. Publishers in Germany and France are deploying these for real-time originality checking during manuscript submission, bypassing standalone interface adoption entirely.
- Desktop:Local installation suits air-gapped environments with strict data residency requirements.
- Mobile App:Lightweight verification for field researchers and remote academic supervisors.
Web-based holds installed capacity. API is rotating up the share rankings.
End User:
Customer type dictates feature requirements, pricing tolerance, and contract structures across the demand base.
- Educational Institutions:Universities and K-12 districts require LMS integration, bulk user management, and academic integrity policy enforcement tools. Federal research funding mandates in the United States are compelling upgrades to enterprise-tier licenses with expanded seat counts.
- Corporates:Legal departments and knowledge management teams deploy verification for internal document originality certification. Fortune 500 procurement in the United States favors API-first architectures that minimize workflow disruption.
- Publishers:Editorial boards need pre-publication screening with audit trails for peer review integrity.
- Students:Individual subscribers drive freemium conversion volumes with limited monetization per account.
Educational institutions dominate current revenue. Corporate deployment is expanding most quickly as non-academic use cases mature.
Deployment:
Infrastructure location shapes data governance compliance and total cost of ownership for procurement teams.
- Cloud-based:Zero-maintenance delivery with automatic updates and elastic scaling. GDPR constraints force European customers toward EU-hosted instances, fragmenting vendor infrastructure requirements.
- SaaS:Multi-tenant architectures with subscription metering and usage-based billing. Indian universities under National Education Policy mandates are procuring these for rapid rollout across new institutional formations.
- On-premises:Air-gapped installation for classified research environments and strict data sovereignty regimes.
- Hybrid:Split processing with sensitive fingerprinting local and reference database queries cloud-resident.
Cloud-based maintains volume leadership. SaaS is climbing the fastest as procurement teams prioritize operational simplicity over customization.
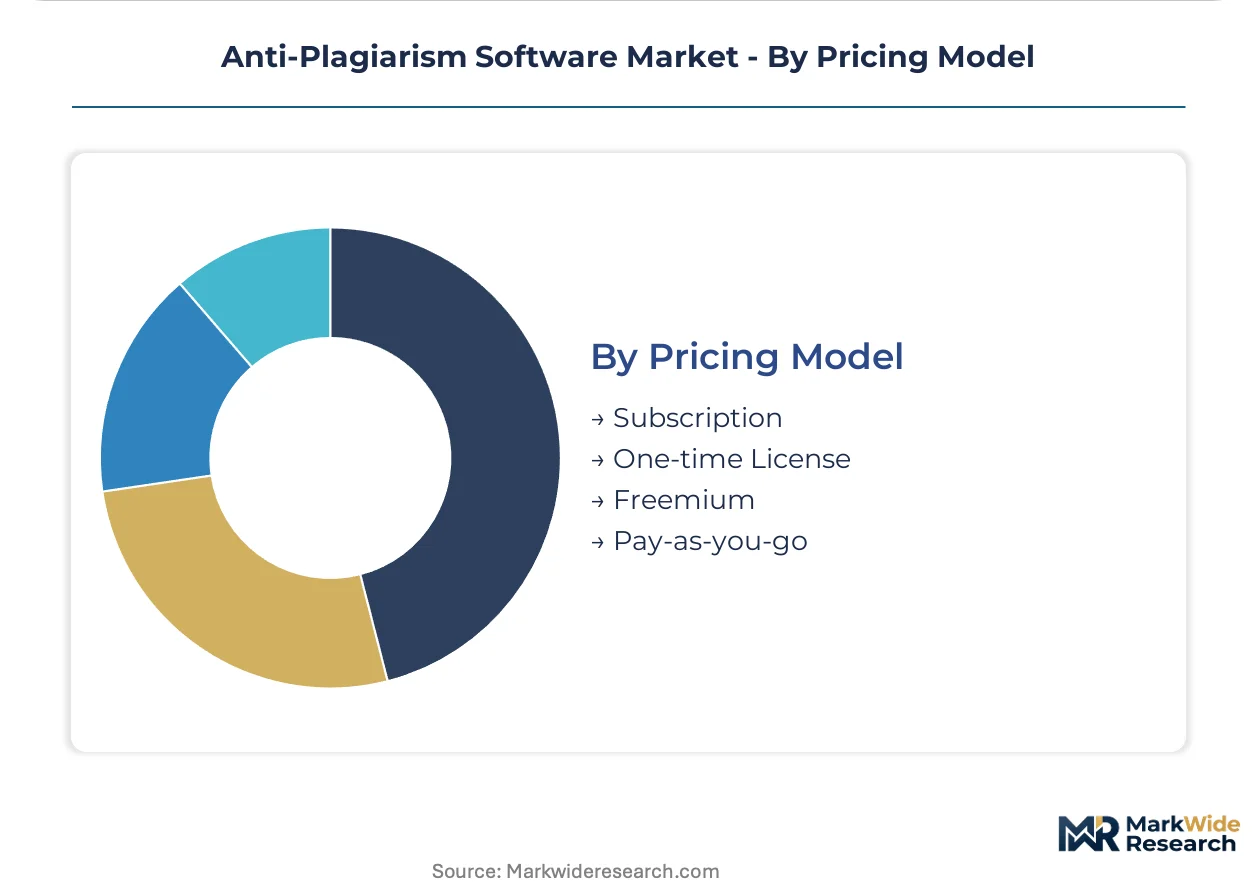
Pricing Model:
Financial structure determines customer acquisition economics and lifetime value trajectories across vendor strategies.
- Subscription:Recurring annual or monthly licensing with tiered feature access. Institutional procurement in the United States gravitates toward multi-year campus-wide contracts with predictable budget allocation.
- Freemium:Basic verification with conversion triggers to premium tiers. Grammarly's mechanics demonstrate massive user funnel potential, though conversion rates constrain sustainable monetization.
- One-time License:Perpetual purchase with maintenance add-ons for legacy preference customers.
- Pay-as-you-go:Metered consumption for episodic verification needs in project-based publishing workflows.
Subscription anchors vendor revenue stability. Freemium is gaining share fastest as user acquisition competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anti-plagiarism software trade flows predominantly from US and UK development centers toward educational institutions in Asia-Pacific and Middle Eastern markets, with net services exports running positive for Anglo-American vendors against localized competition in continental Europe and India.
United States
Federal research funding mandates from the National Science Foundation and National Institutes of Health now require originality verification for all grant submissions, compelling tier-one research universities to expand enterprise license footprints. The FTC monitors AI-detection accuracy claims under Section 5 authority, creating compliance overhead for vendors marketing synthetic text identification. Boston and the San Francisco Bay Area concentrate EdTech procurement decision-making, with MIT and Stanford procurement offices setting technical specifications that cascade to mid-tier institutions nationwide.
Germany
The EU AI Act mandates explainability features for automated content evaluation systems deployed in educational assessment, forcing vendors to architect audit-trail capabilities into verification engines. GDPR constraints fragment document fingerprinting databases, requiring EU-hosted infrastructure that raises operational costs for non-European suppliers. The Ruhr Valley university cluster and Munich's technical universities anchor procurement volume, with Baden-Württemberg's Ministry of Science implementing statewide plagiarism detection standardization across its 40+ institutions.
India
The National Education Policy mandates academic integrity infrastructure across 1,000+ new universities and 45,000 affiliated colleges, creating concentrated procurement windows through 2030. The University Grants Commission now requires originality verification for doctoral dissertations and journal submissions from centrally funded institutions. Bangalore and Hyderabad's emerging private universities are deploying cloud-based SaaS verification at scale, bypassing on-premises legacy systems that dominate established Delhi and Mumbai institutions.
United Kingdom
Office for Students regulatory pressure on academic standards has intensified institutional investment in detection infrastructure, with Russell Group universities renewing multi-year contracts at expanded seat counts. The UK Research and Innovation integrity framework extends originality requirements to all funded research outputs. London's university federation procurement consortia aggregate demand from 40+ institutions, while Edinburgh and Glasgow anchor Scottish adoption driven by Quality Assurance Agency audit requirements.
Japan
MEXT curriculum guidelines now explicitly address AI-generated content in student submissions, creating policy-driven demand for detection capabilities integrated into learning management workflows. Personal Information Protection Act amendments constrain cross-border data processing, favoring domestic vendors or localized foreign deployments. Tokyo's national universities and Osaka's private university cluster lead adoption, with Nagoya's engineering faculties pioneering real-time verification embedding during collaborative research writing processes.
Anti-Plagiarism Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: comprehensive academic integrity suites, API-first verification engines, and freemium consumer tools. Platform consolidators anchor institutional procurement through deep LMS integration and multi-year campus-wide contracts. Specialized vendors occupy workflow-embedded positions via headless API deployments. The dominant competitive moves are strategic partnerships with learning management system providers and geographic expansion through localized data residency infrastructure.
Within the platform consolidator tier, Turnitin and Grammarly exemplify divergent monetization architectures. Turnitin anchors enterprise procurement through institutional licensing and deep integration with Blackboard and Canvas environments. Grammarly occupies the freemium-to-paid conversion channel with massive user funnel scale across individual writers and light enterprise deployments. Copyleaks represents the API-first specialist archetype, positioning verification engines inside content management workflows rather than standalone interfaces. These three patterns capture the structural segmentation that defines vendor positioning across educational, corporate, and publishing demand segments.
| Leading Market Players |
|---|
| Scribbr |
| Grammarly |
| Winston AI |
| Quetext |
| Copyscape |
| Turnitin |
| Copyleaks |
| PlagScan |
| Paperpal |
| Others |
Supply Flow & Price Mechanics
GDPR data localization mandates create a regulatory chokepoint that simultaneously widens pricing tier spreads between EU-hosted and global-cloud deployments while fragmenting supply chain architecture across jurisdictional boundaries. Vendors must replicate document fingerprinting infrastructure in multiple geographies, raising fixed cost bases that compress margins on economy-tier offerings while protecting premium pricing for compliant enterprise licenses.
Pricing Analysis
Educational institutions anchor subscription-based pricing structures across the anti-plagiarism software landscape. Three-tier pricing structure across premium, standard, and economy levels separates enterprise API deployments with audit trails from basic web interfaces and freemium consumer tiers. Cost compression in the economy segment intensifies because open-source transformer models capture price-sensitive emerging market demand. Individual student subscribers exhibit highest price sensitivity, while Fortune 500 legal departments demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Upstream computational linguistics talent draws from a concentrated pool of researchers trained at Carnegie Mellon, Stanford, and MIT in the United States, with secondary centers at Cambridge and Oxford in the United Kingdom. Cloud compute infrastructure rests on hyperscaler data centers in Virginia, Frankfurt, and Singapore, while reference database indexing depends on publisher partnerships with Elsevier, Springer Nature, and Wiley. Single-source vulnerability concentrates around transformer model training clusters controlled by OpenAI and Anthropic. Distribution runs through direct enterprise sales teams for institutional contracts and self-serve web portals for individual conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-plagiarism software market functions as a service-attach opportunity where API consumption metering and compliance advisory layers expand faster than standalone license revenue. Recurring verification volume billing now outpaces perpetual seat licensing as publishers embed detection natively into editorial workflows.
For Market Incumbents: Insulate enterprise contract renewal rates by deepening LMS integration with Blackboard and Canvas while accelerating explainability feature development ahead of EU AI Act enforcement deadlines. Acquire specialized stylometry teams to defend against open-source substitution in the mid-market. Vertical integration into cloud infrastructure in Frankfurt and Mumbai reduces GDPR and data sovereignty exposure. For New Entrants and Emerging Players: Build out white-label API deployments for Indian private universities bypassing legacy on-premises systems in Delhi and Mumbai. Target corporate legal departments in the United States with internal document originality certification use cases. A channel partnership with document management platforms like SharePoint and Confluence accelerates workflow embedding without standalone interface development. For Investors and Strategic Acquirers: EU AI Act transparency obligations reshape the acquisition landscape toward vendors with built-in audit trails and human-in-the-loop override capabilities. Long-term viability centers on computational linguistics talent retention and reference database exclusivity rather than interface design. The signal to watch is FTC scrutiny of AI-detection accuracy claims as a leading indicator of vendor credibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedding verification engines into Canvas and Blackboard workflows captures institutional procurement decisions. |
| EU Data Residency Infrastructure | Frankfurt and Dublin data centers satisfy GDPR constraints and unlock German university system contracts. |
| Stylometry R&D Acquisition | Continuous author verification capabilities differentiate real-time detection from retrospective similarity scoring. |
| Compliance Advisory Services | EU AI Act certification revenue layers attach to core licensing and improve customer lifetime value. |
| India SaaS Expansion | National Education Policy mandates across 1,000 new universities create concentrated procurement windows through cloud delivery. |
Methodological Framework
Operator-level perspectives from chief technology officers at EdTech platforms, university procurement directors, legal department knowledge managers, API integration specialists, and regulatory affairs leads anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings of publicly traded education technology vendors, University Grants Commission procurement notices in India, EU AI Act implementation guidance documents, and FTC enforcement action records. Bottom-up seat-count modeling and top-down education technology spending analysis provided cross-verification across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning deployment model, end-user type, integration complexity, and regional regulatory cluster. CAGRs derived from trend extrapolation of licensed seat expansion and API call volume trajectories. Forecast inputs incorporated Federal Research Integrity Policy compliance deadlines and National Education Policy implementation timelines as demand accelerators.
Sensitivities concentrate around generative AI detection accuracy litigation, open-source model capability convergence, and data localization law proliferation beyond current EU and US state-level frameworks. Cross-checking against university procurement database subscription records and publisher API integration announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Embedded Software and Tools Market
Software & Services
Global Chemical Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Construction Suites Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Yacht Management Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Global Mindfulness Meditation Apps Market