
 Global Contract Management Software Market | 2026-2036
Global Contract Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contract Management Software Market Foresight
ISO 27001 certification is bifurcating the competitive landscape into audit-ready enterprise vendors and unqualified challengers. Icertis leverages its FedRAMP authorization to anchor federal and defense procurement contracts in the United States. DocuSign sustains broad channel control through embedded e-signature workflows that reduce standalone contract platform switching. SAP Ariba competes by extending procurement-to-payment integration, capturing manufacturing and industrial buyers who prioritize supplier network density over pure-play contract functionality.
Contract management software comprises digital platforms that automate authoring, negotiation, execution, and post-award analysis of legally binding agreements through AI-powered clause extraction, metadata tagging, and obligation-tracking algorithms. Cloud-based deployment leads solution delivery, though hybrid architectures are gaining traction among European financial organizations subject to data residency mandates under GDPR. Contract lifecycle management dominates solution spending as organizations seek pre-execution risk scoring and automated renewal triggers, while compliance management captures margin pools from regulated industries facing ESG disclosure requirements.
The EU AI Act, GDPR, and SEC climate disclosure rules are reshaping product roadmaps, forcing vendors to embed explainable AI for automated contract review and auditable consent trails. HIPAA and FedRAMP requirements in the United States create parallel certification burdens that filter vendor participation in healthcare and government verticals. Stakeholders must monitor whether emerging EU AI Act enforcement creates a two-speed market where certified providers capture regulated accounts while uncertified vendors retreat to mid-market commercial segments.
Market Dynamics
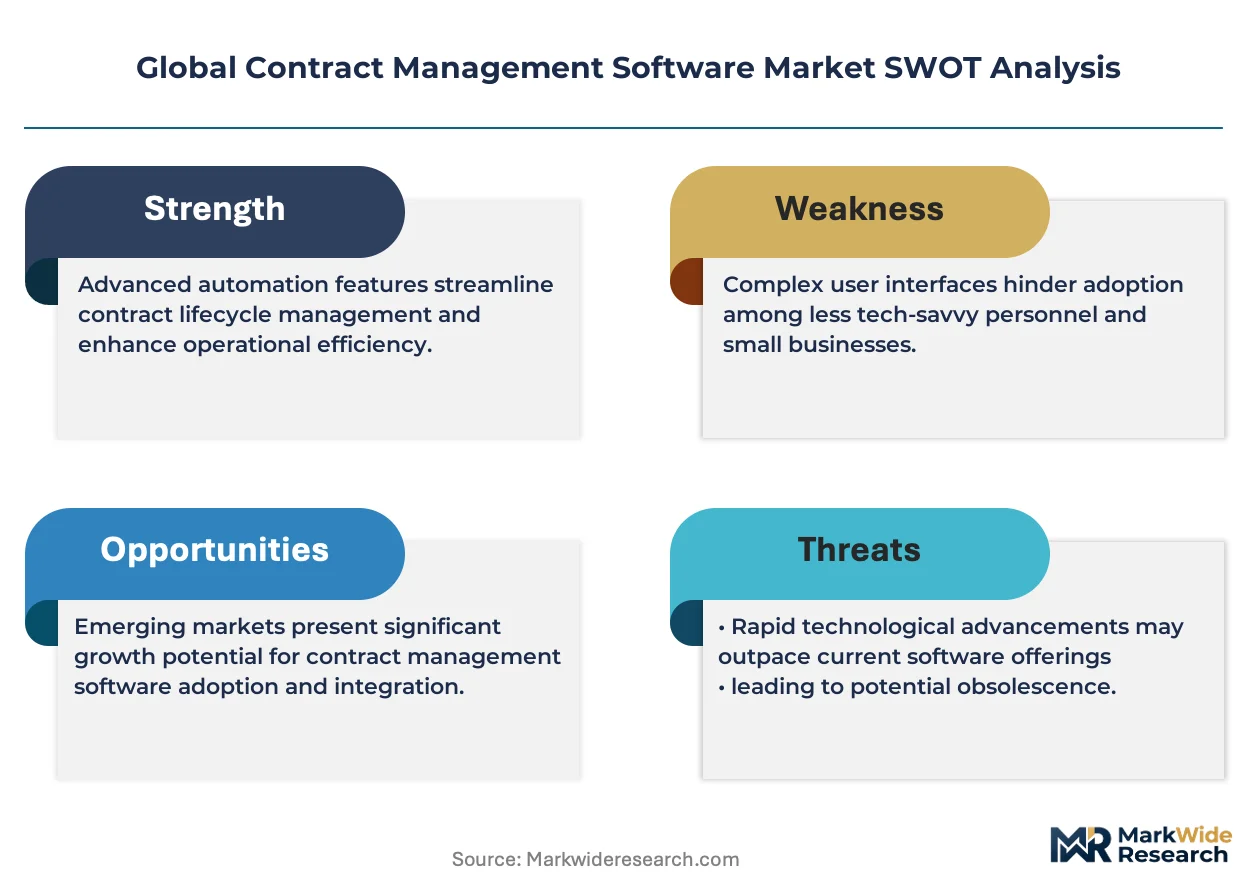
AI-powered clause extraction is decomposing traditional legal review workflows, forcing vendors to rearchitect platforms around explainable algorithms that satisfy audit requirements rather than opaque automation.
Growth Catalysts
- FedRAMP Authorization:Federal procurement reform in the United States mandates cloud security certification, filtering vendor pools and accelerating replacement of on-premise legacy systems with audit-ready SaaS alternatives.
- EU AI Act:Automated contract review tools must embed consent trails and explainable decision logic, creating mandatory upgrade cycles for European financial institutions managing algorithmic risk exposure.
- Private-Equity Portfolio Management:Consolidated ownership of distributed subsidiaries demands centralized obligation tracking and renewal orchestration, driving standardization on lifecycle platforms across holding company structures.
Market Restraints
- Data Residency Mandates:GDPR Article 44 cross-border transfer restrictions force hybrid architecture investments that inflate deployment costs 40-60% above pure-cloud alternatives for European buyers.
- ISO 27001 Concentration:Certification scarcity limits vendor participation in healthcare and defense verticals, concentrating supply among audit-ready incumbents and raising switching costs for mid-market buyers.
- Legacy System Entrenchment:Decades of customized ERP integrations in manufacturing create technical debt that resists API-based contract platform replacement without multimillion-dollar migration budgets.
Strategic Opportunities
- India's PLI Scheme:Manufacturing incentives attract multinational contract volume requiring localized compliance management, creating demand for India-data-resident lifecycle platforms with BIS-aligned security frameworks.
- ESG Disclosure Automation:SEC climate rules and EU CSRD mandate auditable supplier obligation tracking, opening margin pools for platforms embedding carbon clause extraction and renewable energy credit verification.
- Embedded Finance Convergence:Contract data streams fused with payment rail APIs enable dynamic pricing and automated escrow release, attracting fintech-native buyers underserved by standalone legaltech vendors.
Industry Challenges
- AI Ethics Expertise Gap:Explainable algorithm design requires rare cross-functional talent combining computational law, machine learning engineering, and regulatory compliance, constraining product roadmap velocity.
- Multi-Jurisdiction Certification Lag:Simultaneous pursuit of HIPAA, FedRAMP, and EU AI Act conformity extends compliance timelines 18-24 months, delaying market entry for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contract Management Software Market |
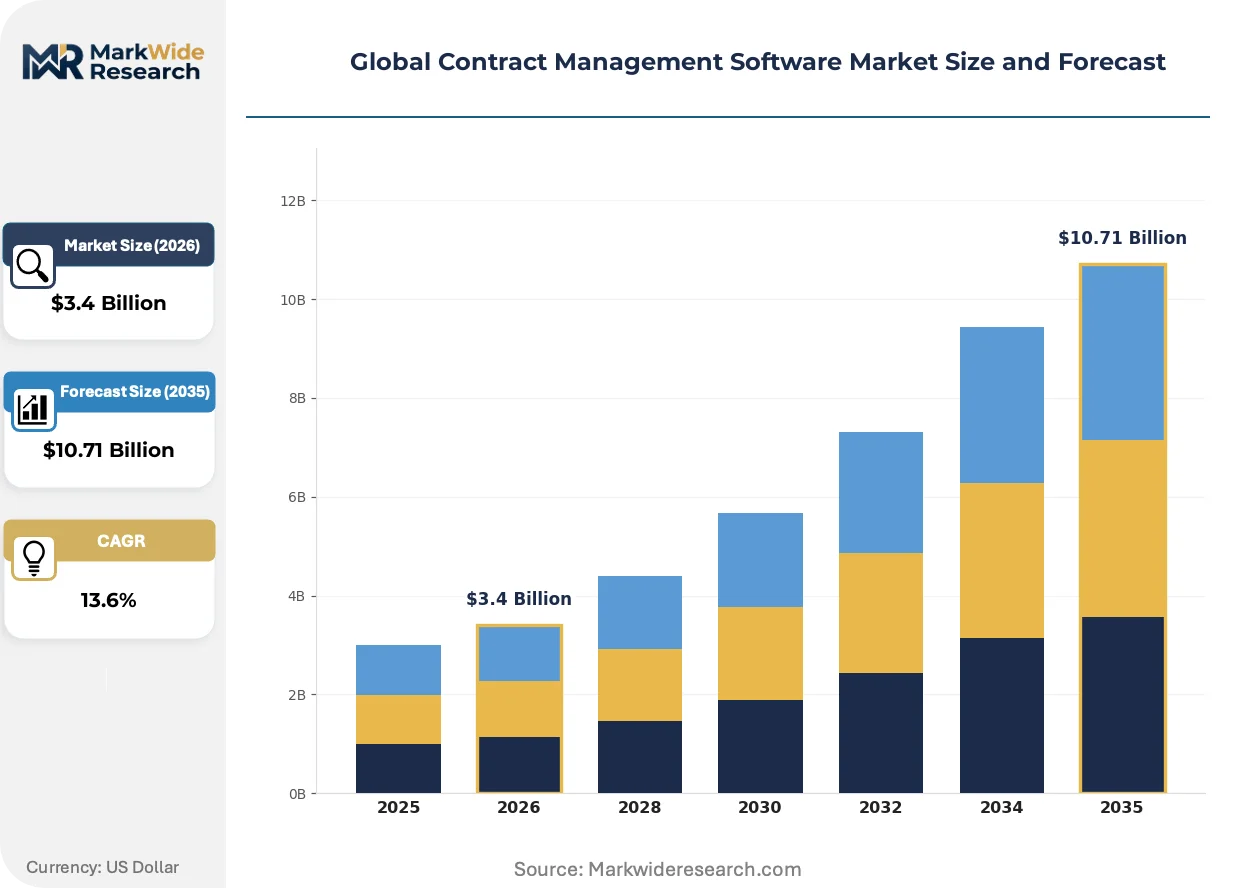
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.71 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
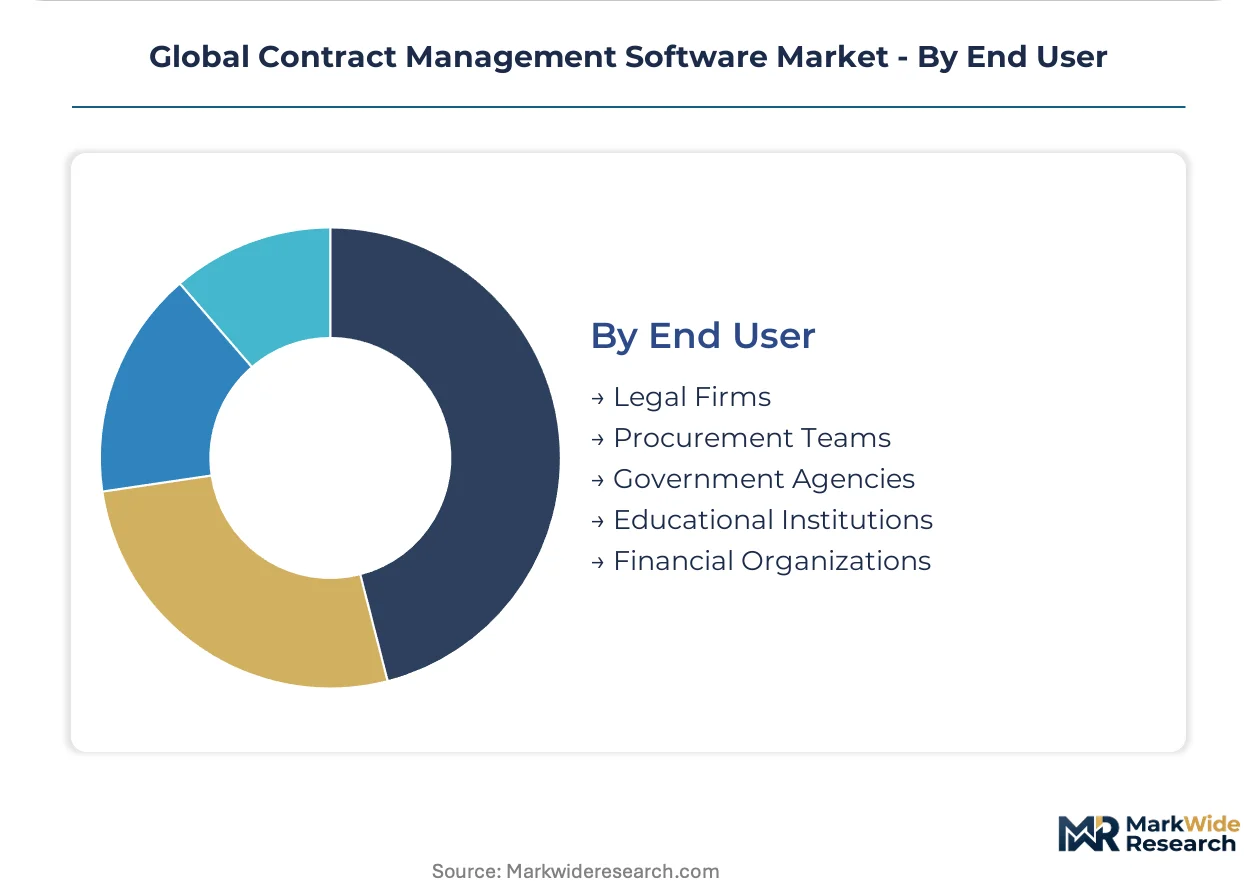
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution: Contract Lifecycle Management, Compliance Management, Risk Management, Document Management, Workflow Automation Use Case: Supplier Management, Sales Contracts, Mergers & Acquisitions, Real Estate Leases, Licensing Agreements End User: Legal Firms, Procurement Teams, Government Agencies, Educational Institutions, Financial Organizations |
| Companies Covered | Icertis, DocuSign, SAP Ariba, Agiloft, Coupa Software, GEP Worldwide, Ironclad, IBM Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contract Management Software Market Shifts & Advancements
Natural language processing architectures are fragmenting contract intelligence into modular, API-first components that dissolve monolithic platform boundaries and enable embedded deployment across enterprise software stacks.
Transformer-based clause extraction is decomposing document-centric workflows into atomic, searchable obligation objects. Fortune 500 legal departments in the United States are deploying these engines at scale, compressing due diligence cycles from weeks to hours while forcing standalone repository vendors toward headless, integration-native architectures.
The EU AI Act's risk-tier classification system is mandating human-in-the-loop overrides for high-stakes contract decisions. European financial institutions must retrofit automated review tools with auditable intervention logs, diverting R&D resources from feature expansion toward compliance infrastructure and widening capability gaps with US competitors.
Buyers are unbundling e-signature from contract lifecycle management, treating execution as a commodity utility while demanding specialized intelligence for pre-award risk scoring. This pattern concentrates most visibly among mid-market technology companies in Germany and the Netherlands, where procurement teams prioritize API flexibility over all-in-one suite consolidation.
Global Contract Management Software Market Segmentation
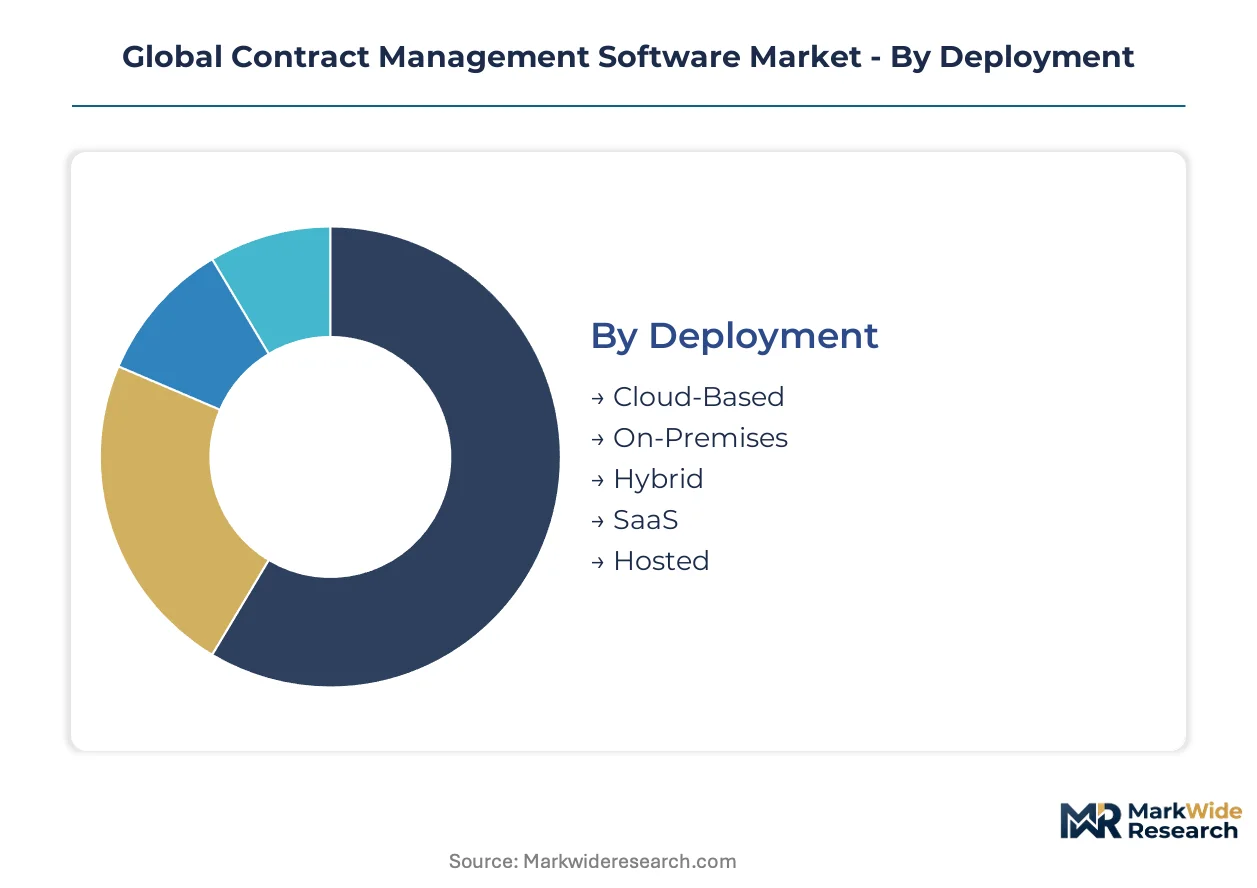
Segmentation in contract management software reveals how deployment constraints, regulatory complexity, and workflow specialization fragment purchasing decisions across buyer types. Vendors must architect modular platforms that span cloud-native startups and legacy-entrenched enterprises without sacrificing compliance depth.
Deployment:
Cloud-based configurations face substitution pressure from hybrid architectures as GDPR Article 44 and India's data localization mandates force architectural compromise.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling. Financial organizations in Germany and the Netherlands concentrate procurement here, though EU AI Act explainability requirements are forcing retrofit investments into audit trails.
- Hybrid:Split-stack designs segregate sensitive contract data on-premises while routing analytics to cloud inference engines. European banks subject to ECB oversight dominate adoption, absorbing 40-60% deployment cost premiums to satisfy cross-border transfer restrictions.
- On-Premises:Air-gapped installations persist in defense and intelligence verticals requiring FedRAMP High or equivalent isolation.
- SaaS:Subscription-native delivery with API-first integration layers attracts mid-market technology buyers prioritizing speed-to-value over customization depth.
- Hosted:Single-tenant managed deployments serve healthcare systems navigating HIPAA technical safeguard interpretations.
Cloud-based deployment anchors the volume base while hybrid configurations gain share at the steepest rate.
Solution:
Margin concentration follows regulatory intensity, with compliance modules commanding premium pricing against commoditized document repositories.
- Contract Lifecycle Management:End-to-end platforms orchestrating authoring through renewal with AI-powered obligation extraction. Private-equity holding companies in the United States standardize on these systems to centralize portfolio-wide contract visibility.
- Compliance Management:Specialized engines embedding ESG clause libraries and SEC climate disclosure workflows. EU CSRD and California climate laws are accelerating procurement among multinational manufacturers with complex supplier networks.
- Risk Management:Pre-award scoring algorithms assessing counterparty financial health and regulatory exposure.
- Document Management:Repository-centric systems with versioning and search, facing compression as buyers unbundle storage from intelligence layers.
- Workflow Automation:Rules-based routing and approval orchestration, often deployed as embedded capabilities within broader CLM suites.
Contract lifecycle management captures the largest revenue pool while compliance management expands most quickly on regulatory tailwinds.
Use Case:
Application fragmentation mirrors enterprise function boundaries, with procurement-led supplier management diverging from legal-led M&A workflows.
- Supplier Management:Obligation tracking across distributed vendor bases with automated performance scorecards. Industrial manufacturers in Germany and Japan prioritize these capabilities to manage tiered supply chain exposure.
- Sales Contracts:Revenue recognition alignment and renewal forecasting for subscription businesses. SaaS companies in California and Massachusetts concentrate investment here to compress quote-to-cash cycles.
- Mergers & Acquisitions:Due diligence acceleration through automated clause extraction and liability surfacing.
- Real Estate Leases:Lease accounting compliance under ASC 842 and IFRS 16 with critical date alerting.
- Licensing Agreements:Royalty calculation automation and intellectual property term monitoring.
Supplier management dominates current deployment value while sales contract applications climb the fastest on recurring revenue model proliferation.
End User:
Customer-type segmentation reflects budget authority dispersion, with procurement teams gaining platform control at legal departments' expense.
- Legal Firms:AmLaw 200 practices and Magic Circle firms deploying clause extraction to compress associate review hours. London and New York partnerships lead adoption, though ethical AI guidelines from state bars are constraining automation depth.
- Procurement Teams:Strategic sourcing organizations in Fortune 500 industrials standardizing on lifecycle platforms with supplier risk scoring. These buyers prioritize API flexibility over legal-centric feature depth.
- Government Agencies:Federal civilian and defense entities mandating FedRAMP authorization as table stakes.
- Educational Institutions:Research universities managing sponsored award compliance and technology transfer licensing.
- Financial Organizations:Banks and insurers subject to overlapping SEC, ECB, and national regulator oversight.
Legal firms anchor historical spending while procurement teams capture the steepest adoption trajectory through budget consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedRAMP authorization requirements and EU AI Act enforcement timelines are redistributing procurement budgets toward certified vendors in the United States and Germany. Private-equity consolidation in North America and data localization mandates in Asia are accelerating hybrid deployment architectures.
United States
Federal procurement reform mandates cloud security certification for civilian and defense agencies, filtering vendor participation toward FedRAMP-authorized platforms. SEC climate disclosure rules pressure Fortune 500 legal departments to embed auditable ESG clause tracking. Silicon Valley SaaS buyers and New York financial services firms concentrate demand for API-first lifecycle orchestration.
Germany
ECB oversight of systemically important banks enforces strict data residency for contract analytics, driving hybrid architecture adoption at 40-60% cost premiums. EU AI Act risk-tier classifications mandate human-in-the-loop overrides for automated review tools. Industrial manufacturers in Bavaria and Baden-Württemberg prioritize supplier obligation tracking across tiered automotive supply chains.
United Kingdom
Magic Circle law firms deploy clause extraction engines to compress associate review hours, though Solicitors Regulation Authority ethical AI guidelines constrain automation depth. Post-Brexit divergence from EU AI Act creates parallel compliance obligations for multinational banks operating across London and Frankfurt. The City of London anchors financial services procurement for lifecycle platforms with regulatory reporting integration.
India
PLI scheme manufacturing incentives attract multinational contract volume requiring localized compliance management and BIS-aligned security frameworks. RBI data localization directives force domestic data residency for banking and insurance contract records. Karnataka and Maharashtra technology corridors concentrate SaaS development for export-oriented lifecycle platforms serving ASEAN markets.
Japan
METI industrial digitization programs subsidize SME adoption of cloud-based contract repositories with JIS-aligned security certifications. Keiretsu supply chain structures demand centralized obligation visibility across keiretsu-affiliated supplier networks. Tokyo and Osaka metropolitan areas anchor enterprise procurement for manufacturing-led CLM deployments with embedded quality clause monitoring.
Global Contract Management Software Market Competitive Landscape
Player mix skews toward enterprise SaaS incumbents with vertical certification depth, creating a tiered structure where audit-ready vendors capture regulated accounts. Three archetypes dominate: FedRAMP-authorized federal specialists, embedded e-signature platforms with workflow lock-in, and procurement-to-payment suite extenders. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through localized data residency architectures.
Within the certified-enterprise tier, Icertis anchors federal and defense procurement positioning through FedRAMP authorization. DocuSign exemplifies workflow-embedded platform stickiness, while SAP Ariba occupies the procurement-suite integration vector. These three represent the dominant competitive anchors—each mapping to distinct buyer priorities around compliance depth, execution friction reduction, and supply network density.
| Leading Market Players |
|---|
| Icertis |
| DocuSign |
| SAP Ariba |
| Agiloft |
| Coupa Software |
| GEP Worldwide |
| Ironclad |
| IBM Corporation |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Cloud-native microservices architectures substituting for monolithic legacy stacks simultaneously redistribute engineering talent toward India and Eastern Europe while compressing implementation margins for systems integrators accustomed to waterfall deployment economics. This substitution dynamic fragments vendor pricing power across geography and delivery model.
Pricing Analysis
Certification level creates the primary spread between audit-ready enterprise tiers and unqualified alternatives. Three-tier pricing structure across FedRAMP-authorized premium, ISO 27001-compliant standard, and uncertified economy levels anchors the SaaS subscription model. Cost compression in the mid-market intensifies because buyers unbundle e-signature from intelligence layers. Procurement teams at Fortune 500 industrials exhibit lowest price sensitivity; mid-market technology companies in Germany and the Netherlands demonstrate highest.
Supply Chain Analysis
Just-in-time talent deployment through contract engineering shops dominates over strategic stockpiling of specialized AI ethics expertise. Engineering talent concentrates in India, Poland, and Romania for cost-optimized implementation while algorithm development centers on the United States and United Kingdom. The supply chain draws from scarce cross-functional expertise combining computational law and machine learning engineering. Single-source vulnerability runs through hyperscaler infrastructure dependencies. Distribution runs through systems integrator partnerships and direct enterprise sales motions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Contract Management Software Market sits at a regulatory inflection where EU AI Act enforcement timelines and FedRAMP authorization mandates are simultaneously accelerating replacement cycles and filtering vendor participation. This disruption creates asymmetric opportunity for certified incumbents.
For Market Incumbents: Shield installed base revenue through embedded workflow lock-in and accelerated FedRAMP certification investments. Prioritize vertical integration into explainable AI development capabilities to counter emerging challengers with opaque automation. Defend against unbundling pressure by deepening API-first architectures that resist point-solution substitution.
For New Entrants and Emerging Players: FedRAMP fast-track authorization represents the most penetrable wedge into federal and defense procurement verticals currently concentrated among three authorized vendors. Target mid-market private-equity portfolio companies in the United States with standardized obligation-tracking needs underserved by complex enterprise suites. Lead with carbon clause extraction modules to capture ESG disclosure automation budgets before incumbents retrofit.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified-platform acquirers with compliance infrastructure depth. Long-term viability rests on sustained regulatory complexity across multiple jurisdictions rather than feature differentiation. Acquisition target archetype: hybrid-architecture specialists with India data residency capabilities. Watch EU AI Act enforcement thresholds as the signal for accelerated M&A timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Fast-Track | Unlocks federal procurement contracts worth billions in aggregate lifetime value. |
| Explainable AI Platform Integration | Satisfies EU AI Act audit requirements while differentiating against opaque competitors. |
| Hybrid Architecture Geographic Expansion | Captures European financial institutions facing GDPR Article 44 cross-border restrictions. |
| ESG Clause Library Acquisition | Accelerates SEC climate disclosure compliance product roadmaps for manufacturing buyers. |
| Systems Integrator Partnership Deepening | Secures channel control through embedded deployment within SAP and Oracle ecosystems. |
Research Methodology
Desk research of vendor certification databases, regulatory filing repositories, and hyperscaler partnership disclosures preceded structured interviews with chief legal officers, procurement transformation leads, federal IT acquisition specialists, and private-equity operating partners. Primary fieldwork combined with secondary validation from SEC 10-K disclosures, FedRAMP marketplace listings, and EU AI Act implementation guidance. Bottom-up deployment estimates triangulated against top-down IT spend allocation models.
Variance decomposition across deployment model, organization size, vertical industry, and regional regulatory cluster shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by compliance mandate enforcement timelines. Forecast inputs included FedRAMP authorization pipeline velocity and EU AI Act risk-tier classification adoption rates.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory fragmentation and hyperscaler infrastructure concentration; material deviation would warrant model refresh. Revision becomes warranted when EU AI Act enforcement intensity crosses thresholds that trigger accelerated compliance investment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Category Management Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Global Equity Management Software Market
Software & Services
MEP Software Market
Software & Services
Self-Storage Software Market
Software & Services
Newsroom Software Market
Software & Services
Computer Backup Software Market
Software & Services
Global Home Inspection Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
3D CAD Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Tenant Billing Software Market