
 Pet Tracking Software Market | 2026-2036
Pet Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Tracking Software Market Insights
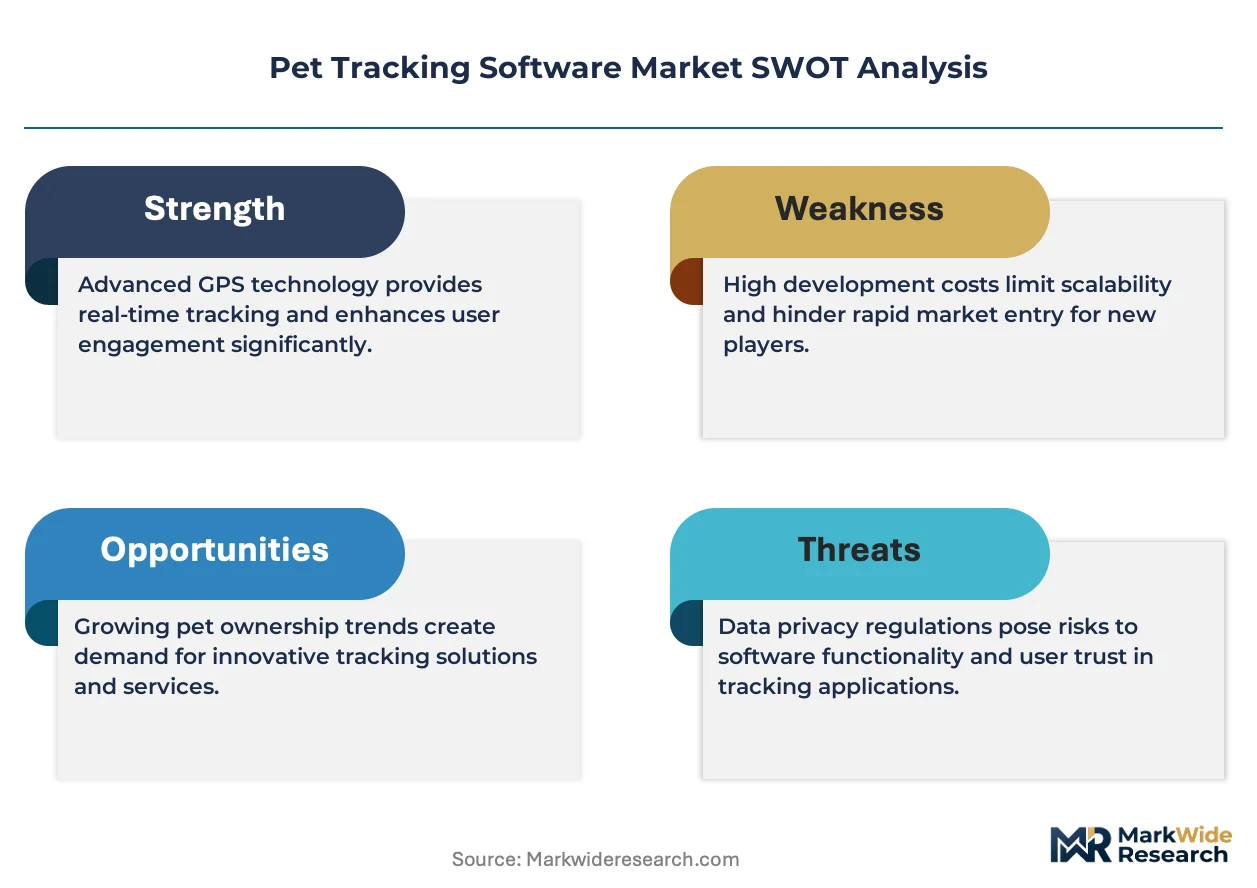
Veterinary data science talent is reorganizing how pet health platforms scale, as clinics demand predictive analytics alongside location tracking. Tractive GmbH leverages its European engineering base to sustain rapid feature iteration across cellular-connected wearables. Garmin Ltd. anchors its position through ruggedized hardware design that dominates outdoor and working dog segments. Whistle Labs Inc. competes on brand recognition and subscription retention within the North American consumer channel.
Pet tracking software encompasses GPS-enabled, cellular-connected, and Bluetooth-integrated platforms that collect geolocation, biometrics, and behavioral telemetry from companion animals for owner monitoring and veterinary intervention. Core systems process real-time coordinates through cloud architectures with sub-ten-meter accuracy thresholds while layering accelerometer-derived activity classification for health anomaly detection. GPS collars and wearable devices command the dominant hardware revenue pool due to recurring subscription attach rates and replacement cycles, while smartphone apps represent the fastest-expanding delivery mode as native sensor capabilities reduce hardware dependency. Activity monitoring and geofencing features concentrate margin pools through premium tiering, whereas basic real-time tracking approaches commoditization across budget entrants.
The Federal Communications Commission shapes device certification requirements for cellular-enabled trackers operating in US spectrum bands, while the EU Green Deal's e-waste directives pressure manufacturers toward repairable hardware architectures and reduced battery toxicity profiles. The FDA's Center for Veterinary Medicine maintains oversight boundaries on software claiming diagnostic utility, creating compliance segmentation between wellness and regulated health devices. Stakeholders must monitor evolving jurisdictional boundaries between consumer electronics and veterinary medical device classifications as algorithmic health insights deepen.
Market Dynamics
Veterinary clinics now demand predictive health analytics layered atop location tracking, forcing platform developers to revalidate algorithmic tools under tightening AI governance frameworks.
Growth Catalysts
- EU AI Act compliance deadlines:Developers accelerating algorithmic revalidation for veterinary health assessment tools before deployment across member states.
- German pet insurance penetration:Reimbursement policies for remote monitoring services driving clinic adoption of cellular-connected wearable platforms.
- Accelerometer-derived behavioral telemetry:Sensor fusion enabling chronic condition management in companion animals without invasive diagnostics.
Market Restraints
- Lithium-ion battery supply concentration:Raw material sourcing bottlenecks in cobalt and lithium processing geographies constraining hardware production scaling.
- FCC certification timelines:Cellular-enabled device approval processes creating 8-14 month launch delays for US market entry.
- Smartphone native sensor substitution:Bluetooth-tethered tracking apps reducing hardware attach rates among budget-conscious owners.
Strategic Opportunities
- EU Green Deal e-waste directives:Repairable hardware mandates creating first-mover advantage for modular collar architectures with replaceable battery packs.
- Working dog segments:Ruggedized GPS platforms for search-and-rescue and agricultural applications commanding premium subscription tiers.
- Telemedicine integration:API connectivity with veterinary practice management systems enabling automated health alert routing to clinicians.
Industry Challenges
- Veterinary data science talent scarcity:Shortage of clinicians cross-trained in machine learning model interpretation slowing predictive feature deployment.
- Jurisdictional classification ambiguity:FDA Center for Veterinary Medicine boundaries on diagnostic software claims creating compliance segmentation between wellness and regulated medical devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Tracking Software Market |
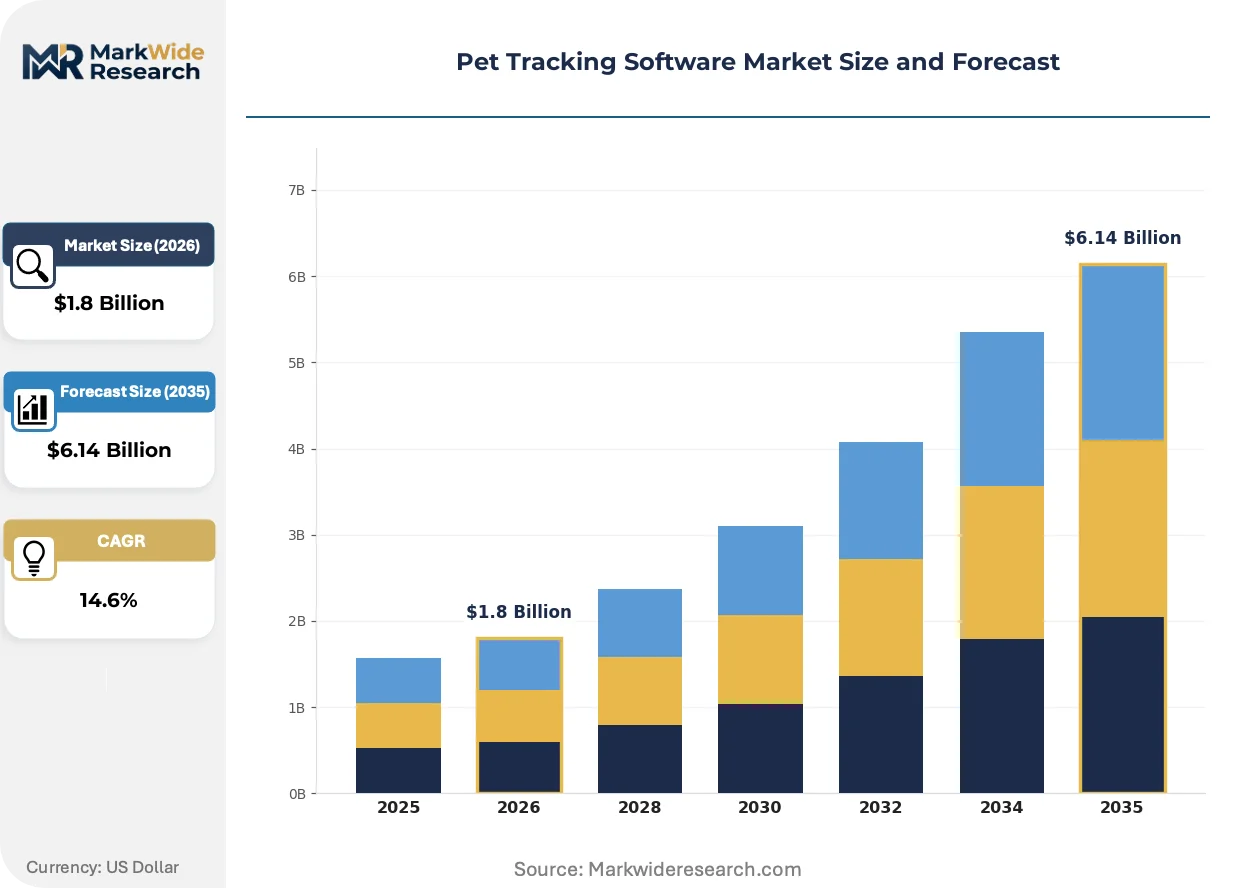
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Collars, Bluetooth Tags, Smartphone Apps, Wearable Devices End User: Pet Owners, Veterinarians, Pet Retailers, Animal Shelters Technology: RFID, Cellular, Wi-Fi, NFC Feature: Real-Time Tracking, Activity Monitoring, Geofencing, Health Insights |
| Companies Covered | Garmin Ltd., Whistle Labs Inc., Tractive GmbH, FitBark Inc., Petcube Inc., PetPace LLC, Loc8tor Ltd., Mars Petcare, Sure Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Tracking Software Market Trends and Innovations
Algorithmic health inference is compressing the boundary between consumer wellness devices and regulated veterinary diagnostics, reshaping how platforms architect their feature roadmaps and compliance strategies.
Ultra-wideband positioning chipsets are miniaturizing into sub-30-gram collar form factors while maintaining sub-meter accuracy for indoor geofencing applications. Boutique veterinary hospitals in urban corridors are piloting these systems for post-surgical recovery monitoring. The technology is miniaturizing hardware cost structures enough to displace legacy Bluetooth beacon deployments in multi-pet households.
REACH chemical restrictions on battery electrolytes are compelling manufacturers to reformulate power cells for reduced toxicity profiles and improved recyclability. Industrial consequences include extended supplier qualification cycles and accelerated R&D spend on solid-state alternatives. German engineering teams are responding fastest, integrating repairable battery architectures ahead of EU Green Deal enforcement timelines.
Subscription unbundling is fragmenting the traditional all-in-one pricing model, with owners selecting à-la-carte geofencing, activity monitoring, or telehealth connectivity tiers. Direct-to-consumer channels and veterinary clinic partnerships are displacing big-box retail as the primary acquisition path. This pattern concentrates in North American markets where pet insurance reimbursement workflows favor itemized service billing.
Pet Tracking Software Market Segmentation
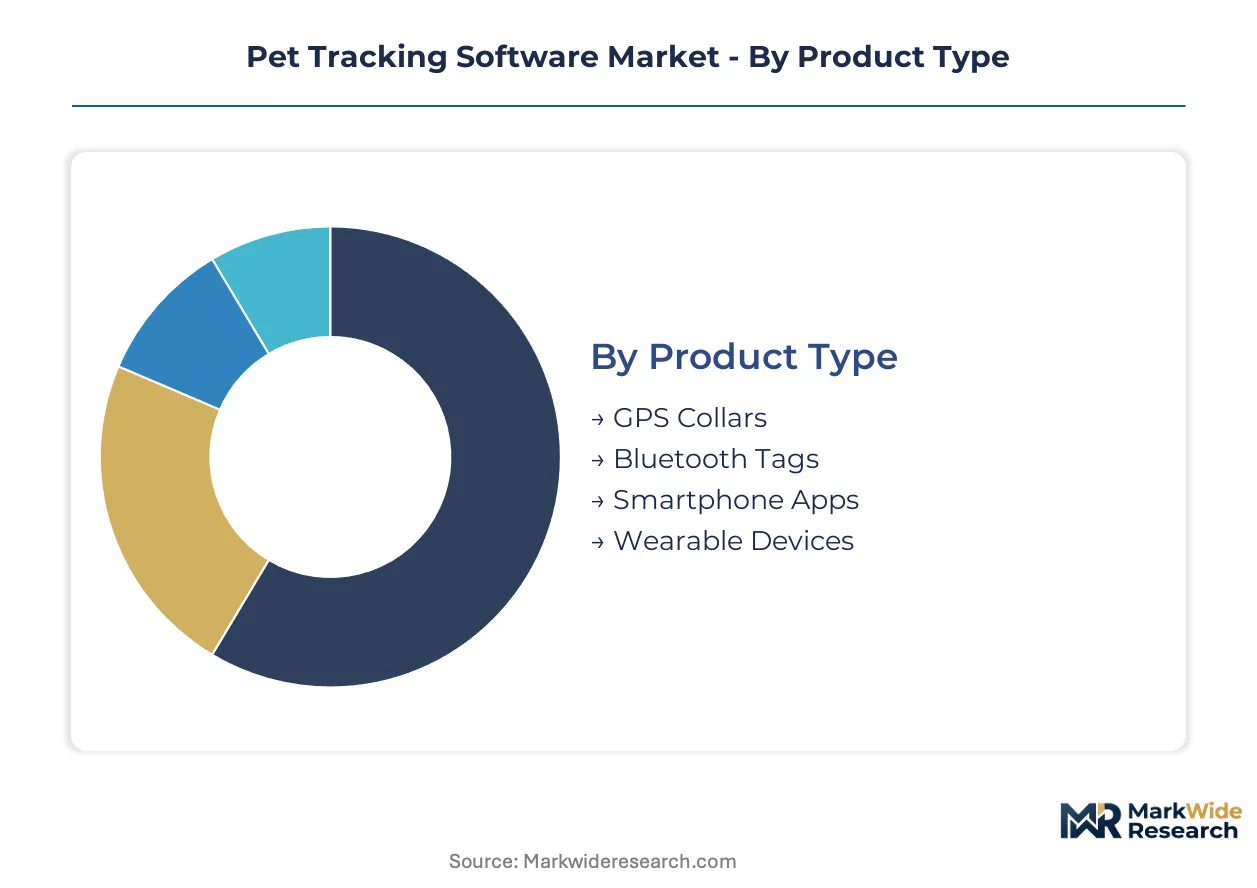
Segmentation in pet tracking software reflects divergent compliance pathways between consumer electronics and regulated veterinary devices. FDA Center for Veterinary Medicine oversight on diagnostic claims creates tiered development costs across feature sets, while EU AI Act deadlines force algorithmic revalidation for health-focused segments.
Product Type:
FDA certification requirements for cellular-enabled devices create cost stratification between regulated and unregulated hardware categories.
- GPS Collars:Ruggedized hardware with sub-ten-meter accuracy thresholds processes real-time coordinates through cloud architectures. Demand concentrates among working dog handlers in Germany and search-and-rescue units across Austria, driven by EU Green Deal repairability mandates accelerating modular battery adoption.
- Wearable Devices:Accelerometer-integrated form factors below 30 grams enable chronic condition monitoring without invasive diagnostics. German veterinary clinics and urban pet hospitals in Munich deploy these for post-surgical recovery, propelled by pet insurance reimbursement policies for remote monitoring services.
- Bluetooth Tags:Low-energy beacon technology for proximity-based indoor tracking in multi-pet households.
- Smartphone Apps:Native sensor platforms reducing hardware dependency through Bluetooth-tethered tracking functionality.
GPS collars handle the majority of hardware revenue throughput; wearable devices are gaining share fastest on veterinary channel expansion.
End User:
Customer procurement authority determines subscription pricing power and feature bundling flexibility.
- Veterinarians:Clinical decision-makers require predictive analytics layered atop location tracking for chronic condition management. German veterinary practices lead adoption, integrating cellular-connected platforms with practice management systems to automate health alert routing.
- Pet Owners:Direct consumers selecting à-la-carte geofencing, activity monitoring, or telehealth connectivity tiers. North American markets show strongest unbundled subscription uptake, where itemized service billing aligns with pet insurance workflows.
- Pet Retailers:Channel intermediaries shifting from big-box retail toward direct-to-consumer and clinic partnership models.
- Animal Shelters:Budget-constrained operators prioritizing basic real-time tracking over premium health analytics.
Veterinarians command the highest subscription attach rates; pet owners represent the steepest expansion trajectory on smartphone app substitution.
Technology:
Spectrum allocation and device certification timelines create geographic deployment constraints.
- Cellular:LTE-M and NB-IoT chipsets enabling nationwide coverage with 8-14 month FCC certification delays for US market entry. Demand clusters in Germany where digital veterinary service adoption and pet insurance penetration are highest in Europe.
- RFID:Passive identification systems for permanent pet registration and shelter intake processing.
- Wi-Fi:Indoor positioning networks for home-based geofencing without cellular subscription costs.
- NFC:Short-range contactless pairing for owner identification and veterinary record access.
Cellular technology carries the dominant installed base; RFID is climbing the fastest on municipal pet registration mandates.
Feature:
Margin concentration follows regulatory boundary lines between wellness and diagnostic claims.
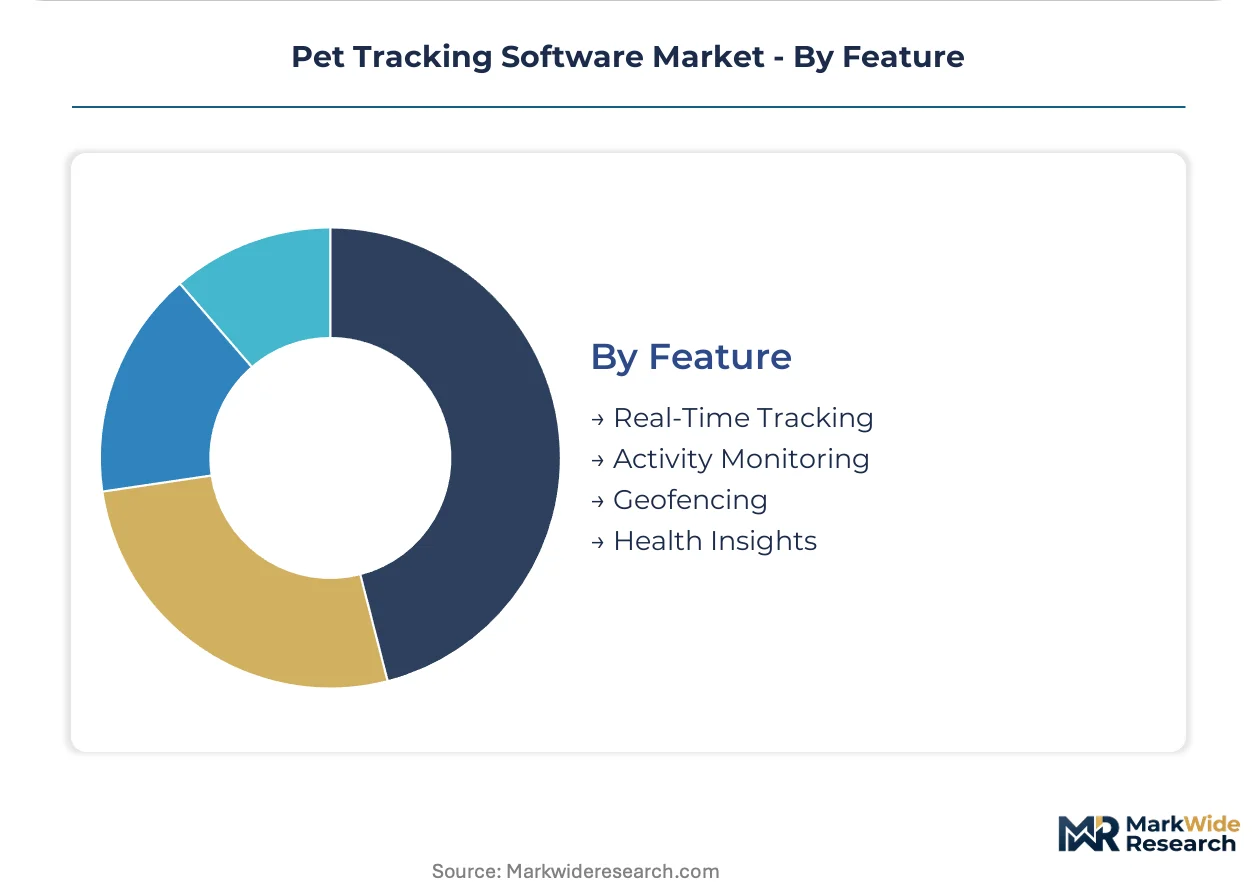
- Health Insights:Algorithmic inference from accelerometer-derived behavioral telemetry for anomaly detection. EU AI Act compliance deadlines force developers to revalidate veterinary health assessment tools before member state deployment, concentrating R&D spend in German engineering centers.
- Geofencing:Virtual boundary systems with sub-meter accuracy through ultra-wideband positioning. Boutique veterinary hospitals in Berlin and Hamburg pilot these for post-surgical recovery monitoring.
- Real-Time Tracking:Basic coordinate streaming approaching commoditization across budget market entrants.
- Activity Monitoring:Step-counting and sleep pattern classification for wellness-oriented consumer segments.
Health insights capture the premium tier margin pool; geofencing is expanding most quickly on ultra-wideband miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet owners pay subscription premiums that exceed US pricing by a factor of two, while Indian consumers cluster at entry-level hardware tiers with minimal recurring revenue attach rates.
United States
FCC certification timelines for cellular-enabled trackers create 8-14 month market entry delays, compressing first-mover advantages for new hardware entrants. The FDA's Center for Veterinary Medicine maintains strict oversight boundaries on software claiming diagnostic utility, forcing wellness-differentiation strategies. Austin and San Francisco host the densest concentrations of telemedicine-integrated platform developers.
Germany
Pet insurance penetration rates exceeding 30 percent drive reimbursement workflows for remote monitoring services, accelerating veterinary clinic adoption of cellular-connected wearables. EU AI Act compliance deadlines force algorithmic revalidation for health assessment tools before member state deployment. Munich engineering clusters lead modular battery architecture development ahead of EU Green Deal enforcement.
United Kingdom
Urban pet density in London and Manchester generates concentrated demand for ultra-wideband indoor geofencing systems in multi-pet households. GDPR compliance requirements shape data residency architectures for cloud-based health telemetry platforms. Cambridge boutique veterinary hospitals pilot sub-meter accuracy positioning for post-surgical recovery monitoring.
Japan
METI standards for IoT device cybersecurity create certification overhead for foreign platform entrants seeking market access. Aging pet populations in Tokyo and Osaka metropolitan areas drive demand for chronic condition monitoring without invasive diagnostics. Yokohama hardware manufacturers specialize in miniaturized accelerometer-integrated form factors below 30 grams.
Australia
Vast rural landholdings and high-value working dog populations sustain premium pricing for ruggedized GPS platforms with extended battery life. TGA classification ambiguity between consumer electronics and veterinary medical devices creates compliance segmentation challenges. Sydney and Melbourne veterinary networks increasingly demand API connectivity with practice management systems for automated health alert routing.
Pet Tracking Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where engineering-intensive hardware specialists coexist with software-first subscription platforms. The vendor base spans three strategic groupings: ruggedized outdoor equipment fabricators, cellular-connected wearable specialists, and smartphone-native app developers. Dominant competitive moves include portfolio diversification into veterinary telemedicine integration and geographic expansion through region-specific certification compliance.
Within the European engineering tier, Tractive GmbH exemplifies rapid feature iteration capabilities sustained through localized R&D clusters. Garmin Ltd. anchors the ruggedized hardware segment with positioning systems designed for working dog applications. Whistle Labs Inc. occupies a position within the North American consumer channel, competing primarily on brand recognition and subscription retention mechanics.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Whistle Labs Inc. |
| Tractive GmbH |
| FitBark Inc. |
| Petcube Inc. |
| PetPace LLC |
| Loc8tor Ltd. |
| Mars Petcare |
| Sure Petcare |
| Others |
Pricing and Supply Chain Analysis
Eight-to-fourteen-month FCC certification timelines for cellular-enabled trackers compress inventory turnover and amplify pricing power for incumbents with pre-certified hardware platforms. German engineering clusters exploit repairable battery mandates to command subscription premiums that exceed North American pricing by substantial margins, while lithium-ion supply concentration in East Asian processing geographies constrains margin expansion for budget-tier entrants.
Pricing Analysis
German pet owners absorb subscription premiums substantially above US levels, reflecting reimbursement workflows through pet insurance policies. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and veterinary channel integration, with FDA-tagged diagnostic devices commanding substantial uplifts over wellness-tier alternatives. Pricing pressure stems from smartphone-native sensor substitution eroding hardware attach rates among budget-conscious owners. Pet owners in price-sensitive geographies exhibit highest elasticity, while German veterinary clinics show lowest sensitivity due to insurance-backed procurement.
Supply Chain Analysis
Inventory cycles extending beyond twelve months for FCC-certified cellular modules force hardware manufacturers into pre-positioning strategies that strain working capital. Manufacturing concentrates in China, South Korea, and Japan for LTE-M chipsets, accelerometer sensors, and lithium-ion cells. Raw material dependencies on cobalt from the DRC and lithium from Chile create single-source vulnerability exposure. Distribution runs through direct-to-consumer channels and veterinary clinic partnerships, displacing traditional big-box retail concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where API interoperability with veterinary practice management systems separates ecosystem winners from isolated hardware vendors. The shift toward telemedicine-integrated alert routing creates winner-take-most dynamics for platforms achieving clinical workflow embedding.
For Market Incumbents: Secure algorithmic revalidation capabilities ahead of EU AI Act enforcement deadlines to maintain deployment rights across member states. Deepen backward integration into modular battery architectures to exploit EU Green Deal repairability mandates before competitor qualification cycles complete. Lock in exclusive API partnerships with dominant practice management software vendors to foreclose challenger telemedicine integration paths. For New Entrants and Emerging Players: Differentiate on ultra-wideband positioning accuracy for post-surgical recovery monitoring in boutique veterinary hospitals, where sub-meter precision justifies premium subscription tiers. Target Australian working dog segments with ruggedized hardware architectures that command extended battery life premiums. Pursue direct-to-consumer acquisition paths in North American markets where unbundled subscription tiers align with pet insurance reimbursement workflows. For Investors and Strategic Acquirers: Long-term, this sits as a data-network-effects play because predictive health analytics improve with veterinary telemetry volume, creating compounding moats for early platform scale. Acquisition targets should demonstrate cellular-connected wearable installed base above critical mass thresholds and active API integrations with practice management systems. Watch for FDA diagnostic classification rulings that would resegment wellness and regulated device addressable markets.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine API Integration | Automated health alert routing through veterinary practice management systems embeds platforms into clinical workflows. |
| EU AI Act Algorithmic Revalidation | Pre-deployment compliance across member states preserves market access for health-assessment feature sets. |
| Modular Battery Architecture Development | Repairable hardware designs satisfy EU Green Deal e-waste directives ahead of enforcement timelines. |
| Ultra-Wideband Positioning Miniaturization | Sub-meter indoor accuracy enables post-surgical recovery monitoring in boutique veterinary hospitals. |
| Pet Insurance Reimbursement Workflow Integration | Itemized service billing alignment accelerates subscription uptake in North American consumer channels. |
Research Methodology
Cross-validation between primary interviews with veterinary practice managers, platform engineering leads, and pet insurance reimbursement specialists anchors the qualitative findings against secondary validation. Veterinary clinic procurement directors, cellular chipset sourcing managers, and regulatory affairs consultants at FDA-registered device manufacturers contributed operational perspectives. Bottom-up triangulation against customs records for tracker hardware imports, FCC equipment authorization databases, and EU MDR vigilance reports grounds volume estimates in observable shipment and certification flows.
Sensitivity analysis across subscription attach rate assumptions and hardware replacement cycle scenarios shapes probabilistic output ranges across the projection horizon. Segmentation dimensions modeled include product type, end-user procurement authority, technology spectrum allocation, and feature regulatory classification. CAGRs derive from logistic adoption curve fitting against veterinary telemedicine penetration benchmarks and pet insurance reimbursement policy expansion trajectories. Forecast inputs incorporate cellular module cost curves, lithium-ion battery chemistry reformulation timelines, and algorithmic health inference accuracy improvement rates.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight boundaries and EU AI Act implementation schedules; material policy shifts would require re-modeling diagnostic claim segmentation and algorithmic deployment permissions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Content Marketing Software Market
Software & Services
Global Award Management Software Market
Software & Services
Global MSP Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Data Compression Software Market
Software & Services
Global Church Management Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Global App Design Software Market
Software & Services
Cemetery Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Performance Management Software Market
Software & Services
APAC Workforce Management Software Market