
 Global Core Banking Software Market | 2026-2036
Global Core Banking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Core Banking Software Market Foresight
Platform licensing revenue is fragmenting across deployment models as vendors compete for multi-year cloud contracts. Fiserv leverages its merchant-facing ecosystem to sustain cross-sell momentum in core banking migrations. Temenos anchors its growth on API-first architecture that appeals to tier-one institutions modernizing legacy stacks. Thought Machine differentiates through cloud-native ledger technology designed for banks seeking to escape mainframe dependency.
Core banking software comprises the integrated systems that manage a bank's fundamental operations including deposit accounting, loan origination, payment processing, and general ledger reconciliation through centralized databases with real-time transaction posting. These platforms serve as the operational backbone enabling financial institutions to process daily banking activities while maintaining regulatory compliance and customer data integrity. Cloud-based deployment represents the fastest-expanding segment as banks prioritize operational elasticity and reduced capital expenditure. Retail banking solutions occupy the largest solution-type share given the volume of individual account holders and transaction density. Payment processing applications command concentrated vendor investment due to real-time infrastructure mandates across multiple jurisdictions.
The European Banking Authority enforces open banking standards through PSD2 and PSD3 frameworks that compel incumbent institutions to expose APIs and modernize core infrastructure. The Reserve Bank of India mandates periodic technology audits through the RBI that push domestic banks toward vendor-managed cloud core systems. ISO 20022 message standards adopted by SWIFT and national payment systems require underlying core platforms to support enriched data fields for cross-border transactions. Stakeholders must evaluate whether their core architecture can absorb upcoming central bank digital currency integrations without full replacement cycles.
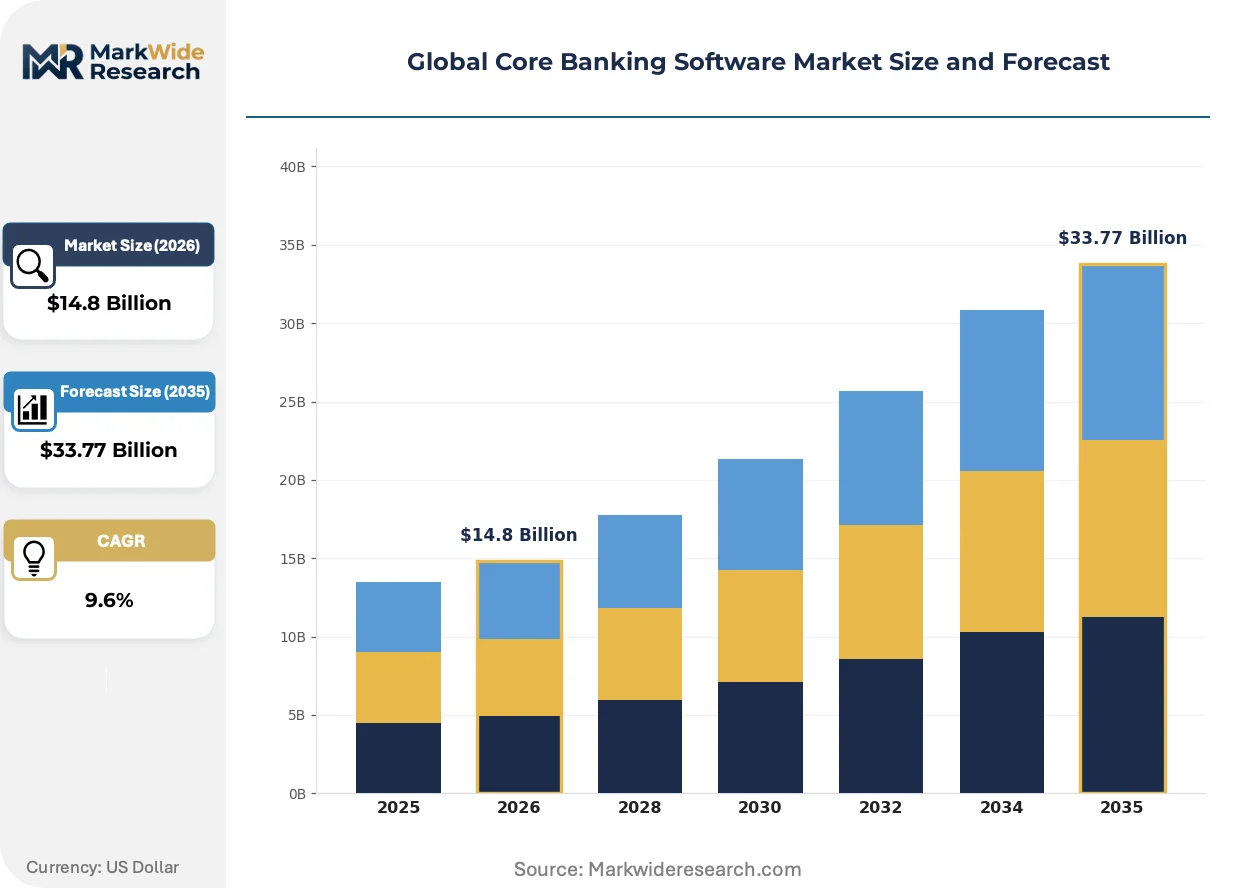
Market Dynamics
Cloud-native core banking platforms are compressing modernization cycles as incumbent institutions confront the technical debt of mainframe-dependent architectures. The Reserve Bank of India's mandatory technology audit regime and the European Banking Authority's PSD3 framework are forcing synchronous infrastructure overhauls across multiple jurisdictions simultaneously.
Growth Catalysts
- Open Banking Mandates:The EU's PSD2 and PSD3 frameworks compel incumbent banks to expose APIs and replace monolithic cores with modular architectures that support real-time data sharing.
- Real-Time Payment Infrastructure:India's UPI and Brazil's Pix instant payment systems require underlying core platforms to process transactions with sub-second latency, driving replacement demand.
- Neobank Proliferation:Digital-native challengers in the United Kingdom, Germany, and Singapore are licensing cloud-native cores from birth, bypassing legacy migration entirely.
Market Restraints
- Mainframe Skill Scarcity:Cobol and assembler expertise concentrates among aging specialists in the United States and Japan, inflating migration costs for tier-one institutions.
- Data Sovereignty Requirements:China's data localization laws and Russia's national payment system mandates restrict cross-border cloud deployment options for multinational vendors.
- Core Replacement Risk:The operational fragility of ledger migration creates board-level resistance at systemically important banks in Switzerland and Canada.
Strategic Opportunities
- Embedded Finance Expansion:Non-bank platforms in Indonesia and Nigeria require banking-as-a-service cores that can white-label deposit and lending products.
- Central Bank Digital Currency Readiness:The ECB's digital euro pilot and the Bank of England's retail CBDC consultation create demand for programmable ledger infrastructure.
- Climate Risk Integration:The EU's CSRD mandates granular carbon accounting in loan books, opening cores that embed emissions tracking directly into origination workflows.
Industry Challenges
- API Standardization Fragmentation:The absence of unified open banking protocols across Brazil, Mexico, and Argentina forces vendors to maintain multiple integration layers.
- Cloud Concentration Risk:Dependency on hyperscale providers in Ireland and Singapore for core hosting creates systemic operational vulnerability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Core Banking Software Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.77 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted, Managed Services Solution Type: Retail Banking, Corporate Banking, Universal Banking, Private Banking, Microfinance Application: Account Management, Loan Processing, Payment Processing, Customer Relationship Management, Risk Management End User: Credit Unions, Commercial Banks, Development Banks, Savings & Loan Associations, Investment Firms |
| Companies Covered | Fiserv, Oracle FLEXCUBE, Temenos, Finacle, TCS BaNCS, Finastra, Mambu, Thought Machine, FIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Core Banking Software Market Shifts & Advancements
Distributed ledger architectures and event-driven microservices are collapsing the batch-processing paradigms that defined twentieth-century banking infrastructure. Vendors and institutions are racing to decouple product logic from data storage without triggering operational discontinuity.
Event-sourced core banking systems are migrating from monolithic relational databases to distributed event stores that maintain immutable transaction logs. Tier-two institutions in Australia and the Netherlands are piloting these architectures to enable real-time analytics and regulatory reporting. The shift is migrating from experimental sandbox deployments to production environments handling retail deposit volumes.
The EU AI Act's risk classification framework is compelling core vendors to document algorithmic decision-making in automated credit origination modules. Banks deploying machine learning for fraud detection must now maintain audit trails that satisfy both the EBA's operational resilience standards and national data protection authorities. German and French regulators are conducting joint inspections of vendor AI governance documentation.
Subscription-based core banking contracts are displacing perpetual license models as procurement teams at Scandinavian and Benelux institutions prioritize operational expenditure predictability. Vendors are unbundling implementation services from ongoing platform fees, creating transparent cost structures that appeal to mutual banks and credit unions. This reconfiguration is most advanced in Denmark and the Netherlands, where cooperative banking groups negotiate collective SaaS agreements.
Global Core Banking Software Market Segmentation
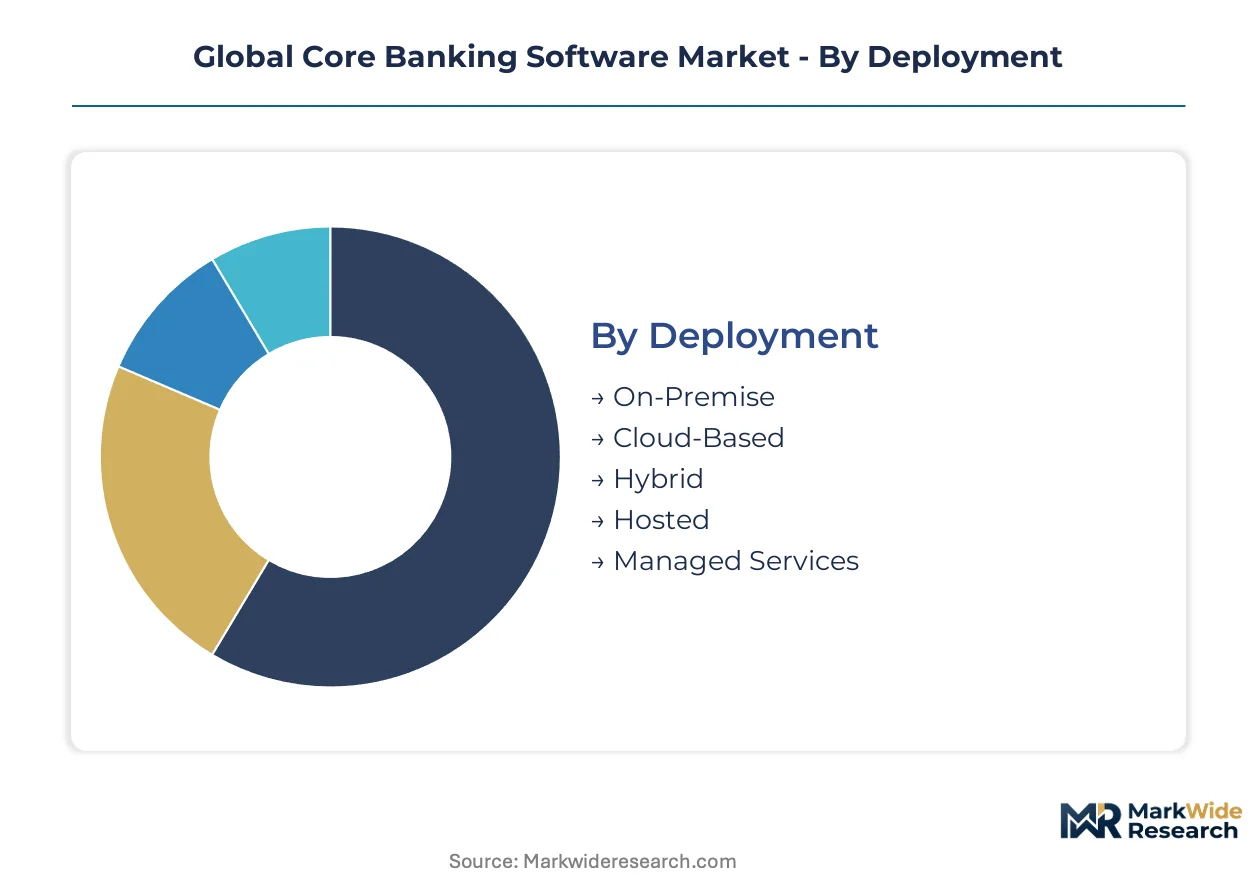
Core banking software segmentation reveals divergent modernization priorities across institutional archetypes. Deployment preferences split between risk-averse incumbents preserving capital investment and challengers seeking elastic infrastructure.
Deployment:
Use-case spectrum spans legacy preservation to greenfield cloud-native construction.
- On-Premise:Hardware-resident installations running on bank-managed data centers with dedicated server infrastructure. Tier-one institutions in Switzerland and Japan maintain these configurations to satisfy board-level risk committees and national financial stability mandates.
- Cloud-Based:Fully vendor-hosted platforms delivering elastic compute and storage through multi-tenant or dedicated cloud environments. Neobanks in the United Kingdom and Singapore license these from inception, bypassing mainframe migration entirely while achieving sub-second payment processing latency.
- Hybrid:Split architectures retaining sensitive ledger functions on-premise while routing customer-facing channels through cloud infrastructure. German and French mutual banks favor this model to reconcile data sovereignty requirements with mobile banking performance demands.
- Hosted:Single-tenant deployments in vendor-managed data centers that mimic on-premise control without capital ownership. Regional banks in the Netherlands and Belgium select this path to escape data center operations while preserving customization flexibility.
- Managed Services:Comprehensive outsourcing encompassing infrastructure, application management, and regulatory compliance monitoring. Scandinavian cooperative banking groups negotiate collective agreements to standardize operational expenditure across member institutions.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
Solution Type:
Customer complexity determines functional scope requirements across institutional tiers.
- Retail Banking:High-volume transaction processing for individual depositors and consumer lending products. Solutions in India and Brazil absorb UPI and Pix real-time payment volumes while maintaining regulatory reporting granularity.
- Corporate Banking:Multi-entity cash management, trade finance, and complex treasury operations for enterprise clients. Demand concentrates among tier-one institutions in the United States and United Kingdom serving multinational corporate relationships.
- Universal Banking:Integrated platforms spanning retail, commercial, and investment banking functions within unified ledger architecture. German and French full-service banks require these configurations to maintain cross-divisional customer visibility.
- Private Banking:Relationship-driven wealth management with customized portfolio accounting and fiduciary reporting. Swiss and Singaporean institutions deploy these solutions to serve ultra-high-net-worth client segments with complex cross-border holdings.
- Microfinance:Simplified core systems designed for high-volume, low-value transactions with group lending methodologies. Institutions in Indonesia and Nigeria utilize these platforms to achieve operational sustainability at sub-$50 average account balances.
Transaction density anchors Retail Banking; margin concentration elevates Private Banking.
Application:
Functional modules align with regulatory priority sequencing in each jurisdiction.
- Account Management:Real-time deposit posting, interest calculation, and statement generation across currency denominations. RBI-mandated technology audits in India accelerate replacement demand for batch-processing legacy systems.
- Loan Processing:Origination workflows, collateral management, and amortization scheduling with automated credit decisioning. EU AI Act compliance requirements in Germany and France now demand documented algorithmic audit trails for automated underwriting modules.
- Payment Processing:ISO 20022 message handling, real-time gross settlement integration, and cross-border correspondent banking connectivity. The ECB's TARGET2 consolidation and FedNow deployment in the United States drive concentrated vendor investment here.
- Customer Relationship Management:Unified customer data platforms integrating transaction history, interaction logs, and propensity modeling for personalized product recommendations.
- Risk Management:Integrated credit, market, and operational risk calculation engines with stress testing and regulatory capital allocation.
Regulatory urgency elevates Payment Processing; margin pressure intensifies Risk Management.
End User:
Institutional charter shapes procurement authority and implementation complexity tolerance.
- Credit Unions:Member-owned cooperatives prioritizing cost predictability and community-focused service models. Danish and Dutch credit union federations negotiate collective SaaS agreements to achieve procurement leverage.
- Commercial Banks:Full-service deposit-taking institutions with diverse product portfolios and complex regulatory obligations. Tier-one institutions in the United States and United Kingdom dominate absolute spending despite slower replacement cycles.
- Development Banks:Government-backed institutions financing infrastructure, agriculture, and export promotion with concessional lending mandates. These entities in India and Brazil require specialized modules for subsidized interest tracking and donor reporting.
- Savings & Loan Associations:Deposit-focused institutions with mortgage-centric lending portfolios and mutual ownership structures.
- Investment Firms:Broker-dealers and asset managers requiring securities processing integration alongside traditional banking functions.
Procurement scale favors Commercial Banks; contract flexibility favors Credit Unions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for core banking software diverges sharply across markets. Neobanks in the United Kingdom and Singapore accept premium cloud-native licensing, while regional banks in Germany and Japan resist migration costs despite regulatory pressure.
United States
Commercial banks drive replacement demand as FedNow real-time payment infrastructure forces legacy system overhauls. The SEC's operational resilience disclosure rules push tier-one institutions toward vendor-managed cloud cores. New York's financial district hosts concentrated procurement activity among money-center banks modernizing mainframe-dependent ledgers.
United Kingdom
Challenger banks and building societies license cloud-native platforms from inception, bypassing migration risk entirely. The Bank of England's retail CBDC consultation creates demand for programmable ledger infrastructure. London's fintech cluster generates cross-border SaaS procurement for Commonwealth banking groups.
Germany
Mutual banks and cooperative groups favor hybrid architectures reconciling data sovereignty with mobile performance. The EU AI Act compels documentation of algorithmic credit decisioning in automated origination modules. Frankfurt's banking quarter anchors vendor relationships for Sparkassen and Volksbanken federations.
India
Domestic banks accelerate toward vendor-managed cloud cores under RBI-mandated technology audit regimes. The UPI real-time payment standard processes billions of monthly transactions requiring sub-second latency. Mumbai's financial district concentrates implementation activity among public sector banks escaping batch-processing legacy systems.
Switzerland
Private banks and wealth managers maintain on-premise configurations to satisfy board-level risk committees. FINMA operational resilience standards enforce granular system recovery requirements. Zurich and Geneva host specialized procurement for ultra-high-net-worth client segments with complex cross-border holdings.
Global Core Banking Software Market Competitive Landscape
Capability concentration sits with specialized cloud-native architects; scale advantage sits with incumbent platform vendors with decades of installed base relationships. The vendor landscape organizes into three tiers: legacy mainframe modernizers, API-first modular specialists, and born-digital cloud-native providers. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into embedded finance orchestration layers.
Within the cloud-native specialist tier, Thought Machine and Mambu exemplify architecture designed for banks escaping mainframe dependency. Temenos anchors the API-first modular segment serving tier-one institutions modernizing legacy stacks. Fiserv occupies a position bridging merchant-facing ecosystems with core banking migration momentum.
| Leading Market Players |
|---|
| Fiserv |
| Oracle FLEXCUBE |
| Temenos |
| Finacle |
| TCS BaNCS |
| Finastra |
| Mambu |
| Thought Machine |
| FIS |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud infrastructure across Ireland and Singapore is compressing vendor margins while enabling aggressive SaaS pricing for tier-two banks. This utilization dynamic forces suppliers to bundle implementation services into recurring contracts and accelerates procurement team demands for operational expenditure predictability.
Pricing Analysis
Multi-year professional services and managed support contracts drive lifetime value more than initial platform licensing. Pricing stratifies across premium API-first architectures, standard modular cores, and economy hosted deployments. Cost compression in the standard tier is intensifying because hyperscale cloud providers are absorbing infrastructure risk. Regional banks in Germany and Japan exhibit highest price sensitivity; neobanks in the United Kingdom and Singapore accept premium cloud-native licensing.
Supply Chain Analysis
Extended payment terms from tier-one institutions in the United States and United Kingdom are forcing mid-tier vendors to secure supply-chain finance facilities. Software development capacity concentrates in India, Poland, and Romania. Core platform engineering draws from specialized system architects, cloud infrastructure engineers, and regulatory compliance specialists. Single-source vulnerability sits with concentrated hyperscale hosting in Ireland and Singapore. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The core banking software market sits in early-cycle expansion as regulatory mandates across the European Union, India, and Brazil force synchronous infrastructure replacement. Open banking frameworks and real-time payment standards are accelerating procurement velocity beyond traditional replacement cycles.
For Market Incumbents: Pre-empt cloud-native challengers by acquiring API orchestration specialists before they capture tier-two bank relationships. Defensive consolidation into embedded finance orchestration layers protects against non-bank platform disintermediation in Indonesia and Nigeria. Capacity addition in India addresses the RBI-mandated technology audit surge.
For New Entrants and Emerging Players: Build out white-label banking-as-a-service cores for microfinance institutions in Indonesia and Nigeria where operational sustainability at sub-fifty-dollar account balances remains unaddressed. The most penetrable segment is cooperative banking groups in Denmark and the Netherlands negotiating collective SaaS agreements. Go-to-market through regional system integrators accelerates trust-building with risk-averse mutual banks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native specialists serving neobanks from inception rather than legacy migration vendors. Long-term viability favors API-first modular architects over mainframe modernizers facing skill scarcity inflation. Acquisition targets should demonstrate programmable ledger infrastructure readiness for central bank digital currency pilots. The signal to watch is vendor participation in ECB digital euro and Bank of England retail CBDC consultation programs.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Temenos and modular specialists enable tier-one institutions to modernize legacy stacks without operational discontinuity. |
| Cloud-Native Core Development | Thought Machine and born-digital providers escape mainframe dependency for neobanks in Singapore and the United Kingdom. |
| Strategic Hyperscale Partnership | Fiserv leverages merchant-facing ecosystems to sustain cross-sell momentum in core banking migrations. |
| Embedded Finance Orchestration | White-label cores open non-bank platforms in Indonesia and Nigeria to deposit and lending product licensing. |
| Geographic Expansion into India | Vendor-managed cloud cores address RBI-mandated technology audits for public sector banks escaping batch-processing legacy systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief technology officers, IT procurement officers at tier-one and tier-two banks, platform integration specialists, and regulatory compliance leads. Secondary validation drew from SEC filings, European Banking Authority PSD2 and PSD3 implementation reports, Reserve Bank of India technology audit circulars, and SWIFT ISO 20022 migration disclosures. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Calibration against historical replacement cycles and regulatory mandate timelines anchored projections across the analysis window. Segmentation dimensions modeled include deployment architecture, institutional tier, solution type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and vendor contract visibility. Forecast inputs incorporated central bank digital currency pilot participation and open banking API exposure mandates.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native acquisition moves by legacy mainframe modernizers would shift outcomes. Macroeconomic deviation, accelerated CBDC deployment, or fragmentation in API standardization protocols would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Europe Application Modernization Services Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Paraphrasing Tools Market
Software & Services
Photo Editing Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Absence Management Software Market
Software & Services
Casino Management Systems Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Global Qualitative Data Analysis Software Market
Software & Services
Global CMDB Software Market
Software & Services
Vending Software Market
Software & Services
Job Description Management Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Global Continuous Integration Tools Market
Software & Services
Global Driving School Software Market