
 US Conducted Energy Weapons Market | 2026-2036
US Conducted Energy Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
US Conducted Energy Weapons Market Insights
The IRA's domestic manufacturing incentives for defense-adjacent electronics is restructuring procurement priorities for conducted energy platforms. Axon Enterprises dominates the civilian law enforcement channel through integrated body camera and energy weapon ecosystems. Raytheon Technologies anchors military-grade electromagnetic pulse development for tactical operations. Streetwise Security Products competes in the private security segment with compact electrical shock devices.
Conducted energy weapons are electroshock devices that deliver incapacitating electrical charges through direct contact or wired projectile deployment, typically operating at 50,000 to 100,000 volts with microcoulomb charge delivery sufficient to disrupt neuromuscular function without lethal force. Their primary purpose is to provide law enforcement and military personnel with intermediate force options between verbal commands and lethal firearms. The operational devices segment leads in revenue contribution due to recurring cartridge and battery replacement cycles, while training tools represent the fastest-growing category as agencies mandate certified proficiency programs under use-of-force policies. Less-lethal weapons concentrate margin pools in firmware-locked ecosystems where Axon controls accessory compatibility.
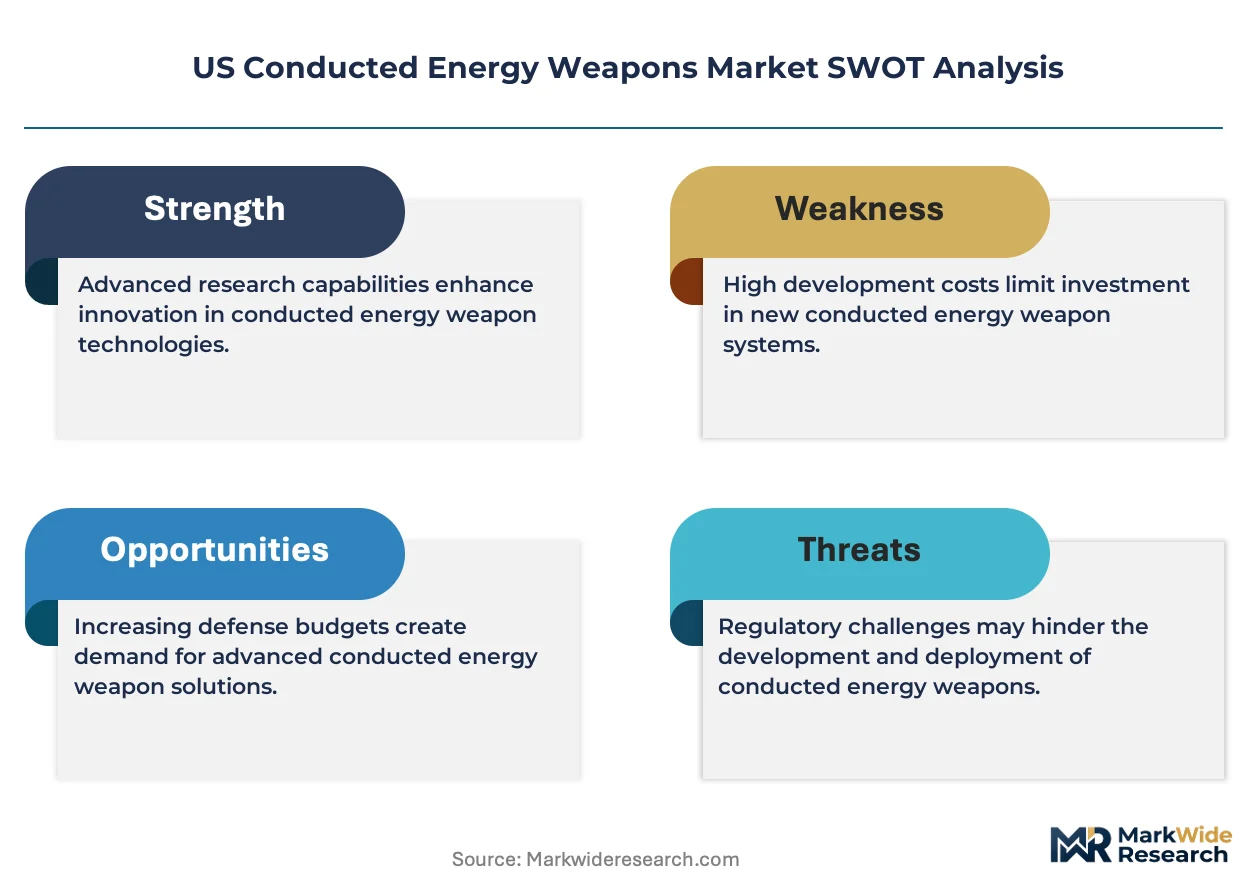
The National Institute of Justice sets electrical safety thresholds and waveform standards that manufacturers must satisfy for federal procurement eligibility, while the Bureau of Alcohol, Tobacco, Firearms and Explosives classifies certain conducted energy projectiles under munitions export controls. State-level POST commissions in California, Texas, and Florida impose additional training-hour mandates that filter vendor eligibility. Stakeholders must monitor emerging electromagnetic pulse regulations from the FCC and evolving municipal liability frameworks that could reshape product certification requirements and indemnification structures.
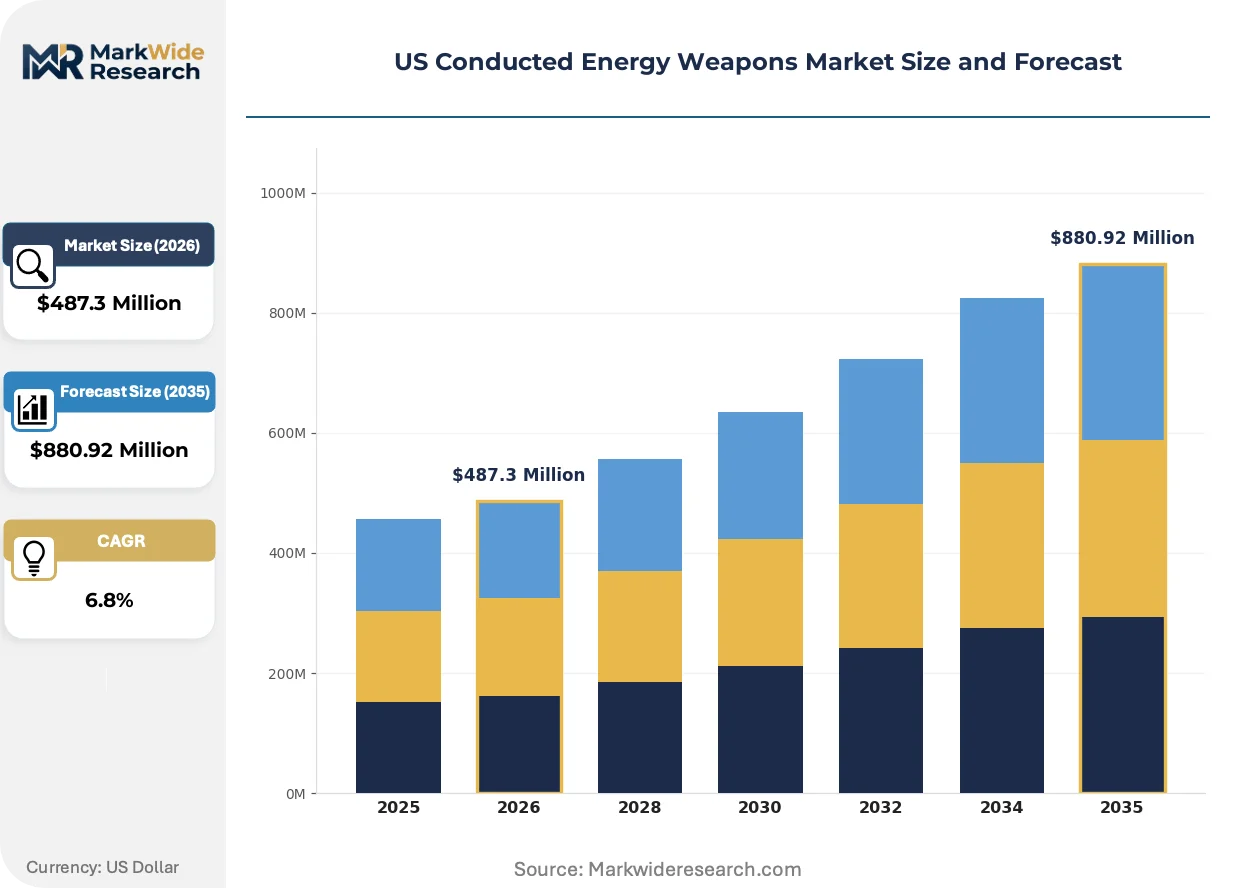
Market Dynamics
The IRA's domestic manufacturing incentives are restructuring procurement priorities for conducted energy platforms, forcing vendors to reshore electronics assembly and battery production to maintain federal eligibility under Buy American provisions.
Growth Catalysts
- State POST Mandates:California, Texas, and Florida impose certified training-hour requirements that filter vendor pools and lock in preferred suppliers through multi-year agency contracts.
- Electromagnetic Pulse R&D:Military demand for non-kinetic area denial is accelerating pulsed-energy platforms for tactical crowd control and checkpoint security applications.
- Municipal Liability Reform:Use-of-force insurance carriers are mandating less-lethal intermediate options, compelling mid-sized police departments to standardize on conducted energy devices.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in Asian manufacturing hubs, exposing cartridge replacement cycles to geopolitical supply disruptions and tariff exposure.
- FCC Spectrum Allocation:Emerging electromagnetic pulse platforms face uncertain radio-frequency authorization timelines, delaying product certification for wireless-activated deployments.
- Biometric Incapacitation Variance:Individual physiological response to electrical shock varies unpredictably, constraining universal safety thresholds and exposing agencies to litigation risk.
Strategic Opportunities
- Private Security Expansion:Corporate campus protection and critical infrastructure guarding represent underpenetrated demand outside traditional law enforcement channels.
- Body Camera Convergence:Integration of conducted energy weapons with real-time video streaming and cloud evidence management creates bundled procurement opportunities.
- Federal Training Center Standardization:The National Defense Authorization Act directs military-to-civilian technology transfer programs that accelerate civilian agency adoption curves.
Industry Challenges
- Firmware Security Certification:Connected devices require cybersecurity validation under evolving federal procurement standards, extending development timelines and validation costs.
- Legacy Holster Incompatibility:New form factors disrupt existing duty gear ecosystems, forcing agencies into costly complete-system replacements rather than incremental upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Conducted Energy Weapons Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Devices, Less-Lethal Weapons, Training Tools, Non-Lethal Munitions End User: Law Enforcement Agencies, Military Organizations, Security Firms, Industrial Facilities Application: Crowd Control, Riot Management, Self-Defense, Tactical Operations Technology: Electromagnetic Pulse, Electrical Shock, Acoustic Disruption, Laser Systems |
| Companies Covered | Axon Enterprises, Streetwise Security Products, PhaZZer, Guard Dog Security, Vipertek, SABRE - Security Equipment Corp., Foxfend, Lockheed Martin, Raytheon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Conducted Energy Weapons Market Trends and Innovations
Waveform optimization and connected-device architectures are compressing development cycles while expanding functional boundaries beyond traditional neuromuscular incapacitation.
Multi-pulse waveform modulation is absorbing advanced battery management algorithms to deliver variable charge profiles matched to subject physiology and environmental conditions. Large municipal departments in California and Texas are piloting these platforms for expanded operational envelopes. The technology is absorbing margin from legacy single-waveform products by enabling premium pricing for firmware-locked cartridge ecosystems.
The National Institute of Justice updated electrical safety standards in 2023, mandating independent third-party testing for all federal procurement eligibility. Manufacturers must now submit devices to accredited laboratories for waveform analysis and biological effects documentation. Vendors with existing NIJ certifications are accelerating product refresh cycles to maintain preferred supplier status under the revised framework.
Agency purchasing departments are consolidating vendor relationships through sole-source indefinite-delivery contracts that bundle devices, cartridges, training, and evidence management software. This behavior compresses supplier counts from multi-vendor competitive bidding to single-ecosystem standardization. The pattern is most visible in Florida, where state-level procurement cooperatives aggregate demand across municipal, county, and university police departments.
US Conducted Energy Weapons Market Segmentation
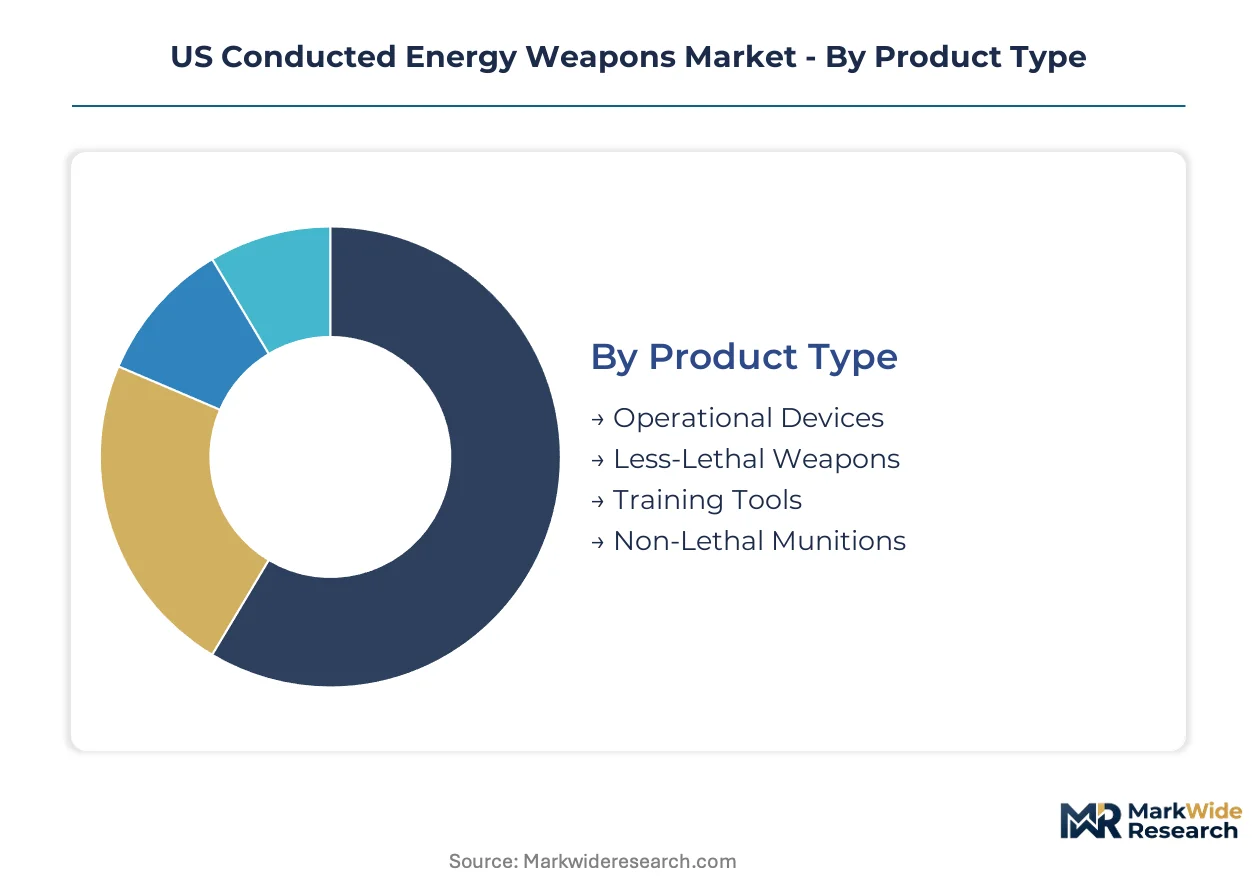
Procurement patterns across conducted energy platforms diverge sharply by operational intensity and regulatory exposure. Buyers prioritize cartridge ecosystem lock-in for high-deployment environments while cost-sensitive segments favor disposable compatibility.
Product Type:
Agency budget cycles and duty-gear replacement schedules create distinct purchasing rhythms across device categories.
- Operational Devices:These electroshock platforms deliver 50,000 to 100,000 volts through wired projectile or direct-contact deployment, with firmware-locked cartridges forcing recurring procurement. Major municipal departments in California and Texas standardize on these systems for patrol duty, driven by POST certification requirements and liability insurance mandates.
- Training Tools:Inert replicas and simulation cartridges enable certified proficiency programs without live electrical discharge. Florida's state procurement cooperatives aggregate demand across university and county police departments, accelerating adoption as agencies comply with updated use-of-force training hours.
- Less-Lethal Weapons:Compact electrical shock devices serve private security and corrections applications with simplified deployment protocols.
- Non-Lethal Munitions:Specialized projectile systems extend range beyond traditional conducted energy platforms for tactical scenarios.
Volume sits with Operational Devices; growth tilts toward Training Tools.
End User:
Federal funding eligibility and liability exposure separate institutional buyers from commercial adopters.
- Law Enforcement Agencies:Municipal, county, and state police departments constitute the core demand base, with procurement flowing through cooperative purchasing agreements and sole-source indefinite-delivery contracts. California POST commissions impose training-hour mandates that filter vendor pools.
- Military Organizations:The National Defense Authorization Act directs technology transfer programs from tactical military applications to civilian agency adoption, accelerating electromagnetic pulse platform development for checkpoint security.
- Security Firms:Corporate campus and critical infrastructure guarding represent expanding demand outside traditional public-sector channels.
- Industrial Facilities:Private sector adoption concentrates in high-value asset protection with limited regulatory standardization.
Revenue concentrates in Law Enforcement Agencies; Security Firms are expanding most quickly.
Application:
Deployment environment determines waveform specifications and platform portability requirements.
- Crowd Control:Area-denial configurations prioritize non-kinetic incapacitation over extended ranges, with electromagnetic pulse platforms gaining traction for checkpoint applications.
- Riot Management:Extended-duration deployment scenarios demand robust battery management and rapid cartridge cycling capabilities.
- Self-Defense:Compact form factors sacrifice neuromuscular incapacitation reliability for concealability and immediate accessibility.
- Tactical Operations:Military-derived specifications emphasize reliability under environmental stress and integration with existing duty gear ecosystems.
Mission profiles favor Riot Management for volume; Tactical Operations show steepest expansion trajectory.
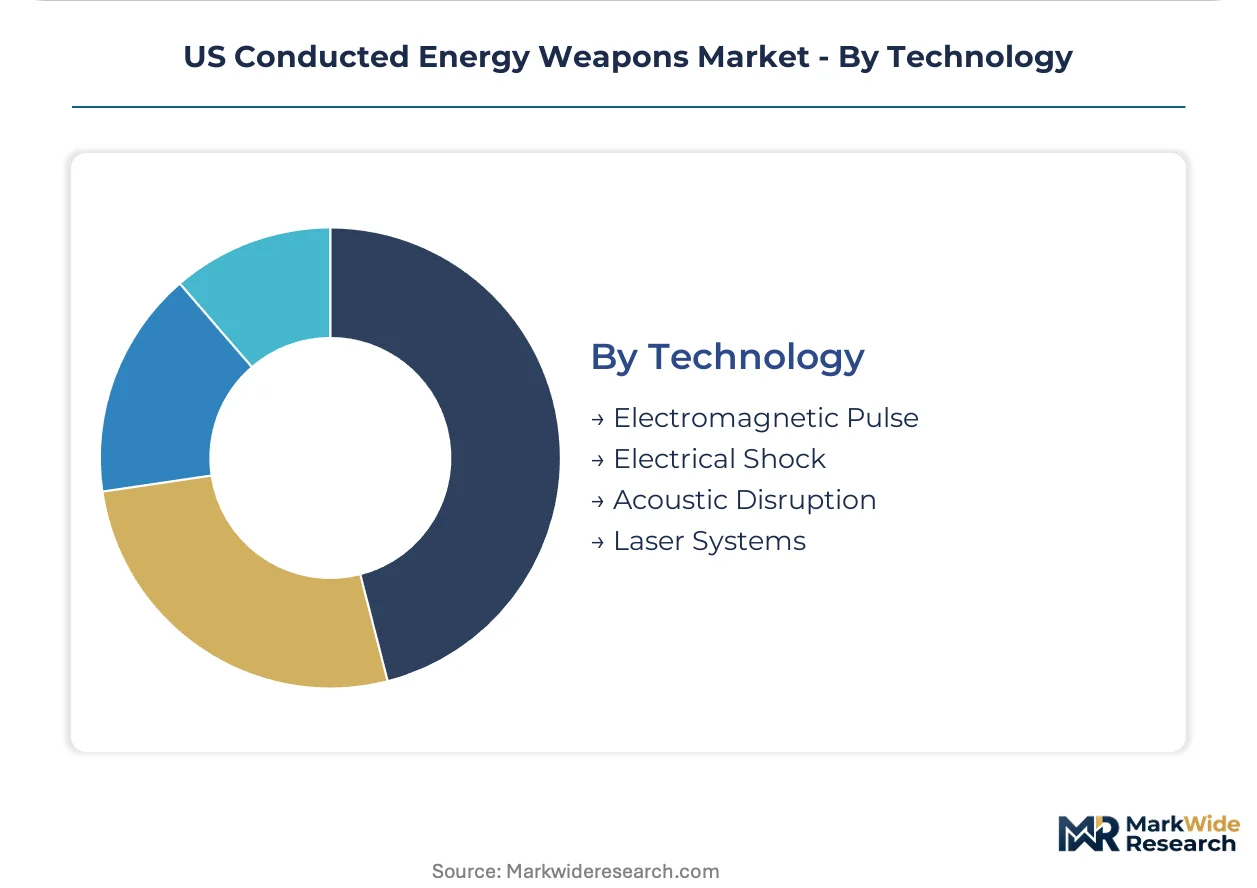
Technology:
Regulatory certification pathways and spectrum allocation timelines fragment competitive positioning across energy modalities.
- Electromagnetic Pulse:Pulsed-energy platforms enable wireless activation and area-denial applications, though FCC spectrum authorization timelines delay product certification for municipal deployment.
- Electrical Shock:Traditional neuromuscular incapacitation through direct contact or wired projectile delivery dominates installed base and established training protocols.
- Acoustic Disruption:Directional sound platforms serve specialized crowd dispersal with limited biological effects documentation for federal procurement eligibility.
- Laser Systems:Optical deterrent technologies face evolving safety threshold standards from the National Institute of Justice.
Electrical Shock retains volume dominance; Electromagnetic Pulse is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's law enforcement procurement corridors anchor domestic demand concentration for conducted energy platforms. State-level training mandates and municipal liability frameworks create differentiated adoption rhythms across sub-regional markets.
California
POST commission certification requirements filter vendor eligibility through mandated training-hour minimums. The IRA's domestic manufacturing incentives reshape federal procurement eligibility for electronics assembly reshoring. Los Angeles and San Francisco municipal departments drive volume through multi-year sole-source contracts.
Texas
Major metropolitan police departments standardize on firmware-locked cartridge ecosystems for patrol duty deployment. State procurement cooperatives aggregate demand across county and university police agencies. Dallas-Fort Worth corridor concentrates federal training center infrastructure accelerating technology transfer programs.
Florida
State-level purchasing cooperatives consolidate vendor relationships through indefinite-delivery contracts bundling devices and training tools. Municipal liability insurance carriers mandate less-lethal intermediate options for mid-sized departments. Miami-Dade and Tampa Bay regions pilot electromagnetic pulse platforms for checkpoint security applications.
Southeast
Georgia and North Carolina manufacturing zones absorb battery production reshoring under Buy American provisions. Regional private security expansion into corporate campus protection creates channel diversification. Atlanta metropolitan area hosts emerging electromagnetic pulse R&D facilities.
Pacific Northwest
Washington and Oregon state legislatures advance use-of-force reform bills accelerating standards for electrical shock deployment. Environmental compliance requirements for lithium-ion battery disposal filter cartridge replacement vendor pools. Seattle municipal procurement drives connected-device architecture adoption for evidence management integration.
US Conducted Energy Weapons Market Competitive Landscape
The competitive structure tilts toward integrated ecosystem providers with firmware-locked accessory compatibility. Procurement consolidation through sole-source indefinite-delivery contracts compresses supplier counts from multi-vendor bidding to single-platform standardization. Two strategic archetypes dominate: defense-adjacent electronics conglomerates with military technology transfer capabilities, and specialized less-lethal device manufacturers with civilian law enforcement channel depth. Dominant competitive moves include backward integration into domestic battery cell production and strategic partnerships for body camera convergence.
Among defense-anchored conglomerates, Raytheon Technologies and Lockheed Martin occupy positions exemplifying military-grade electromagnetic pulse development for tactical operations. Within the civilian law enforcement channel, Axon Enterprises represents the integrated ecosystem archetype combining conducted energy platforms with evidence management software. Streetwise Security Products sits within the private security specialization tier serving corporate and corrections applications with compact form factors.
| Leading Market Players |
|---|
| Axon Enterprises |
| Streetwise Security Products |
| PhaZZer |
| Guard Dog Security |
| Vipertek |
| SABRE - Security Equipment Corp. |
| Foxfend |
| Lockheed Martin |
| Raytheon Technologies |
| Others |
Pricing and Supply Chain Analysis
Sole-source indefinite-delivery contracts bundling devices, cartridges, and training software are compressing vendor pools and forcing suppliers to absorb certification and firmware development costs upfront, which concentrates pricing power with ecosystem-integrated incumbents while squeezing margins for component-only vendors.
Pricing Analysis
Value-based pricing anchored to liability reduction outcomes dominates procurement negotiations, with municipal insurance carriers mandating less-lethal intermediate force options as a condition of coverage renewal. Three-tier pricing structure across integrated ecosystem, standalone device, and disposable cartridge levels reflects firmware-locked compatibility premiums. Cost compression in standalone hardware tiers is intensifying because of Asian battery cell import dependencies and domestic reshoring requirements under IRA provisions. Mid-sized police departments exhibit highest price sensitivity due to constrained capital budgets, while federal training centers demonstrate lowest sensitivity given National Defense Authorization Act funding eligibility.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion battery cells are proliferating as agencies mandate supply chain resilience audits under Buy American provisions. Manufacturing concentrates in China, South Korea, and Japan for battery cell production, with domestic assembly reshoring accelerating in Texas and California. Cartridge production draws from specialty polymer suppliers and precision electronics fabricators concentrated in Asian manufacturing hubs. Single-source vulnerability in rare earth magnet supply for electromagnetic pulse platforms exposes vendors to export control disruptions. Distribution runs through state procurement cooperatives and federal GSA schedules rather than direct commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into domestic battery cell production and captive cartridge manufacturing represents the critical vertical-integration race, with firmware-locked ecosystems determining long-term margin capture.
For Market Incumbents: Deepen control over training certification networks by acquiring POST-authorized curriculum providers, insulating against emerging electromagnetic pulse substitutes that bypass traditional waveform protocols. Expand in-house lithium-ion cell assembly capacity in Texas or Southeast manufacturing zones to neutralize tariff exposure on Asian battery imports. Lock in multi-year sole-source contracts with Florida and California state procurement cooperatives before federal training center standardization accelerates technology transfer to civilian agencies. For New Entrants and Emerging Players: Launch via private security channel partnerships targeting corporate campus protection contracts in Georgia and North Carolina, where regulatory standardization remains minimal and buyer consolidation has not yet occurred. Target electromagnetic pulse platforms for checkpoint security applications in Miami-Dade and Tampa Bay pilot programs, exploiting FCC authorization timeline delays that freeze incumbent product refresh cycles. Position as firmware-agnostic cartridge suppliers to mid-sized departments seeking escape from Axon's ecosystem lock-in. For Investors and Strategic Acquirers: The window for entry favors defense-adjacent electronics specialists with existing NIJ certification infrastructure and military technology transfer relationships. Long-term viability hinges on capturing federal procurement eligibility under evolving cybersecurity validation standards rather than civilian market share alone. Watch electromagnetic pulse FCC authorization announcements as the primary inflection indicator for platform substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Battery Cell Production | IRA manufacturing incentives and Buy American provisions make captive supply chains essential for federal eligibility. |
| Firmware-Locked Cartridge Ecosystems | Recurring revenue attachment to device sales concentrates margin pools and raises switching costs for agency buyers. |
| POST Certification Network Acquisition | Control over mandated training-hour delivery locks in preferred supplier status across California, Texas, and Florida. |
| Electromagnetic Pulse R&D Investment | Military-derived technology transfer programs accelerate civilian adoption curves under National Defense Authorization Act directives. |
| Body Camera Convergence Partnerships | Integration with evidence management software creates bundled procurement opportunities that compress competitive vendor counts. |
Research Methodology
Multi-period observation of POST certification requirement changes, federal procurement award patterns, and municipal liability insurance mandate diffusion anchored the trend analysis, supplemented by interviews with law enforcement procurement officers, NIJ compliance testing laboratory directors, state training commission administrators, and private security firm operations executives. Secondary validation drew from National Defense Authorization Act legislative text, FCC equipment authorization databases, NIJ electrical safety standard updates, and GSA schedule contract award records. Bottom-up device shipment aggregation and top-down federal budget allocation analysis were triangulated against vendor-reported revenue segment disclosures.
Segment-weighting approaches applied differential growth assumptions across operational devices, training tools, and electromagnetic pulse platforms based on procurement cycle timing and certification pipeline status. Product type, end user institutional category, deployment application environment, and energy delivery technology modality structured the analytical framework throughout the projection horizon. CAGRs were derived from logistic diffusion modeling of agency adoption curves and replacement cycle elasticity estimates. Forecast inputs incorporated IRA domestic content requirement phase-in schedules and evolving municipal liability framework litigation frequency indices.
FCC spectrum allocation delays for electromagnetic pulse platforms, lithium-ion supply chain disruption severity, and biometric incapacitation litigation outcome variance are the dominant revision risks to modeled adoption trajectories. Deviation in FCC authorization timeline acceleration would shift the outlook materially toward earlier electromagnetic pulse platform substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market