
 Flu Protection Kits Market | 2026-2036
Flu Protection Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Flu Protection Kits Market Foresight
Workplace safety managers is unwinding from individual consumers as the dominant procurement archetype in flu protection kits. 3M Company leverages its respiratory protection heritage to anchor industrial channel relationships across North American manufacturing belts. Becton Dickinson and Company differentiates through clinical-grade thermometer and diagnostic bundling within enterprise kit configurations. Abbott Laboratories sustains consumer mindshare with over-the-counter brand equity that now extends into corporate wellness programs.
Flu protection kits comprise coordinated assemblies of personal protective equipment, hygiene products, and diagnostic tools designed to reduce influenza transmission in communal environments. Typical configurations integrate ASTM F2100-rated face masks, alcohol-based hand sanitizers exceeding 60% ethanol concentration, and non-contact infrared thermometers calibrated to clinical accuracy standards. Face masks and hand sanitizers occupy the largest value share within product type segmentation, reflecting their universal deployment across all application settings. Healthcare facilities and workplace safety applications generate the fastest expansion within application segmentation, as institutional buyers shift from reactive pandemic stockpiling to systematic seasonal preparedness programs.
FDA device classification for thermometers and OSHA bloodborne pathogen standards shape product composition requirements for kits entering US commercial channels. EU MDR and CE marking frameworks govern diagnostic component claims within European kits, while REACH chemical restrictions limit disinfectant wipe formulations. Stakeholders must monitor evolving employer mandate legislation and seasonal vaccine mismatch patterns to calibrate kit inventory depth and component mix.
Market Dynamics
Employer liability frameworks are tightening across industrialized economies, converting seasonal flu preparedness from discretionary wellness spending into mandatory occupational health compliance. Workplace safety managers now drive procurement volumes that individual consumers cannot match.
Growth Catalysts
- OSHA bloodborne pathogen standards:US manufacturing employers must maintain accessible PPE inventories, creating baseline kit demand across industrial facilities.
- German occupational health mandates:Dense manufacturing employment in the Ruhr and Bavarian industrial corridors sustains premium kit consumption through regulatory compulsion.
- Non-contact infrared thermometry:Clinical-grade temperature screening integration is elevating kit specifications beyond basic PPE assemblies.
Market Restraints
- Ethanol feedstock volatility:Hand sanitizer formulations exceeding 60% ethanol concentration remain exposed to agricultural commodity price swings.
- ASTM F2100 mask supply concentration:Medical-grade meltblown polypropylene capacity clusters in East Asian manufacturing zones, creating single-source vulnerability.
- REACH chemical restrictions:EU disinfectant wipe formulations face ongoing substance authorization hurdles that compress permissible active ingredient options.
Strategic Opportunities
- Corporate wellness program integration:Over-the-counter brand equity extension into employer-sponsored preventive health initiatives opens B2B channel access.
- EU MDR diagnostic component claims:CE-marked thermometer bundling within enterprise configurations creates premium positioning against commodity kit assemblers.
- Seasonal vaccine mismatch preparedness:Institutional buyers are systematizing stockpiling programs independent of annual immunization efficacy variability.
Industry Challenges
- FDA device classification timelines:Clinical-grade thermometer inclusion requires 510(k) clearance processes that extend kit development cycles.
- Multi-standard certification complexity:Simultaneous OSHA, FDA, and EU MDR compliance demands specialized regulatory affairs capacity that smaller assemblers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flu Protection Kits Market |
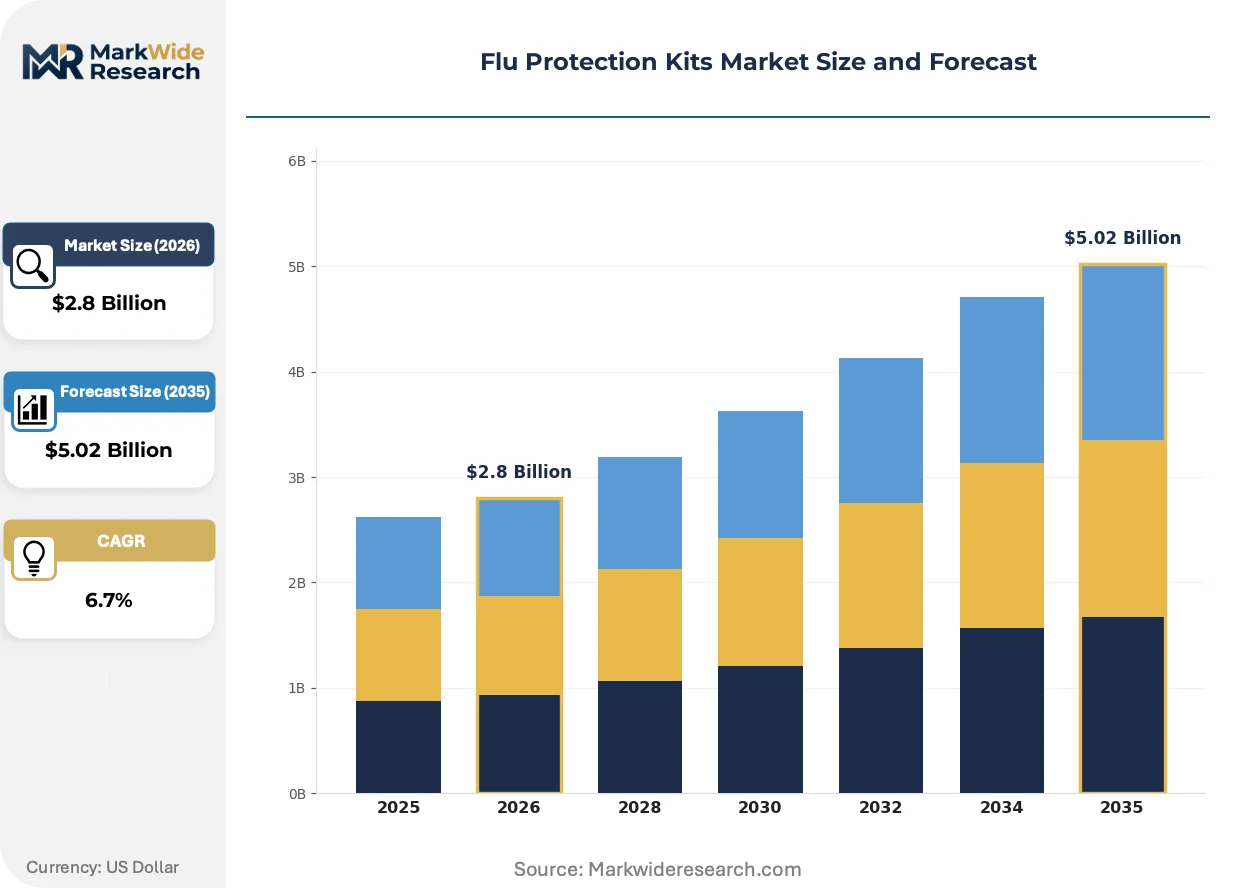
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Masks, Hand Sanitizers, Disinfectant Wipes, Thermometers, Gloves Application: Personal Use, Workplace Safety, Educational Institutions, Public Transport, Healthcare Facilities End User: Individual Consumers, Corporate Offices, Schools & Universities, Pharmacies, Government Agencies Distribution Channel: Retail Pharmacies, Online Stores, Medical Supply Distributors, Supermarkets, Specialty Health Shops |
| Companies Covered | Evav8, Pandemic Protection, Life Secure, Bell Cross, 3M Company, Abbott Laboratories, Becton Dickinson and Company, Meridian Bioscience, Quidel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flu Protection Kits Market Shifts & Advancements
Kit composition is diverging sharply between clinical-grade enterprise configurations and consumer-oriented basic assemblies. Component sourcing decisions now hinge on whether buyers require regulatory documentation for liability protection or merely functional coverage.
Smart packaging with embedded temperature and humidity sensors is bifurcating inventory management approaches. Pharmaceutical distributors and hospital procurement departments are adopting these technologies for cold-chain-adjacent storage validation. This capability compression is squeezing commodity kit suppliers who cannot justify sensor costs against thin margins.
EU MDR technical documentation requirements for diagnostic components are forcing kit assemblers to requalify thermometer suppliers. Manufacturers must now maintain clinical accuracy validation records traceable to notified body assessments. Workplace safety applications in Germany and France are absorbing these compliance costs most readily due to existing occupational health infrastructure.
Enterprise buyers are consolidating vendor relationships around full-service preventive health platforms. Industrial channel distributors are displacing fragmented PPE resellers by bundling kit provisioning with training and compliance documentation. This concentration is most visible across North American manufacturing belts where liability exposure drives preference for documented supply partnerships.
Flu Protection Kits Market Segmentation
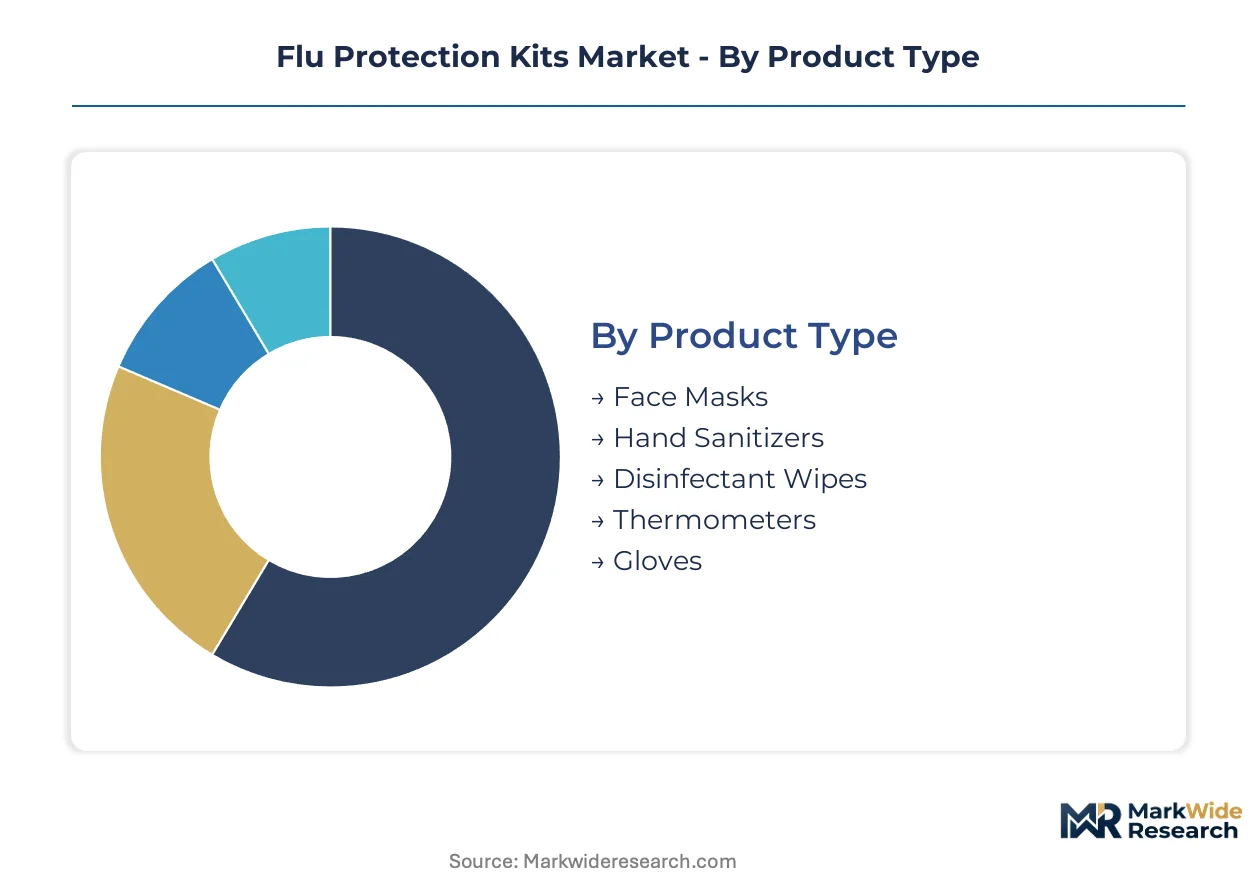
Kit composition varies sharply across procurement contexts, with regulatory documentation requirements and liability exposure dictating component specifications. Segmentation reveals how industrial buyers command premium configurations while consumer channels absorb commodity-grade assemblies.
Product Type:
Domestic manufacturing dominates thermometer and glove production for regulated markets, while face mask and hand sanitizer supply chains stretch across East Asian chemical and textile zones.
- Face Masks:ASTM F2100-rated surgical masks and N95 respirators form the core protective layer in enterprise configurations. German automotive plants and US Midwest manufacturing facilities absorb medical-grade meltblown polypropylene output under tightening OSHA enforcement.
- Hand Sanitizers:Alcohol-based formulations exceeding 60% ethanol concentration serve as universal hygiene components. Ethanol feedstock volatility from Brazilian sugarcane and US corn belt harvests creates price instability that procurement managers hedge through quarterly contracting.
- Disinfectant Wipes:Quaternary ammonium and hydrogen peroxide formulations face REACH substance authorization hurdles in European markets.
- Thermometers:Non-contact infrared devices require FDA 510(k) clearance or CE marking under EU MDR for clinical accuracy claims.
- Gloves:Nitrile and latex examination gloves complete contact-protection protocols in healthcare-oriented kit assemblies.
Face masks command the established base. The steepest expansion runs through thermometers as temperature screening becomes standard in workplace protocols.
Application:
Cost tier differentiation separates liability-driven institutional procurement from discretionary individual purchases, with compliance documentation commanding 40-60% price premiums over functional equivalents.
- Personal Use:Consumer-oriented basic assemblies emphasize portability and shelf stability over regulatory certification. German and French retail channels move significant volume through pharmacy networks during seasonal peaks.
- Workplace Safety:Enterprise configurations integrate documented supply chains and training protocols to satisfy employer liability frameworks. US manufacturing belts and Ruhr industrial corridors sustain premium consumption through mandatory occupational health compliance.
- Educational Institutions:K-12 and university procurement departments balance budget constraints against duty-of-care exposure.
- Public Transport:Municipal transit authorities deploy rapid-response kits for operator protection and passenger screening.
- Healthcare Facilities:Hospital procurement departments demand full clinical-grade documentation including sterilization validation and lot traceability.
Healthcare facilities anchor premium pricing. Workplace safety applications are climbing the fastest as employer mandates systematize seasonal preparedness.
End User:
Customer type determines whether kits require regulatory file maintenance, with corporate and government buyers absorbing compliance costs that individual consumers reject.
- Individual Consumers:Price-sensitive purchasing through retail pharmacies and online marketplaces drives commodity kit assembly.
- Corporate Offices:Facility managers consolidate vendor relationships around full-service preventive health platforms with documented training.
- Schools & Universities:Educational procurement departments navigate duty-of-care obligations against constrained operating budgets.
- Pharmacies:Retail chains and independent druggists serve as final-mile distributors with seasonal inventory buildups.
- Government Agencies:Federal, state, and municipal purchasers mandate domestic sourcing preferences and certified small-business participation.
Corporate offices concentrate contract value. Government agencies are gaining share fastest through pandemic-era stockpiling program institutionalization.
Distribution Channel:
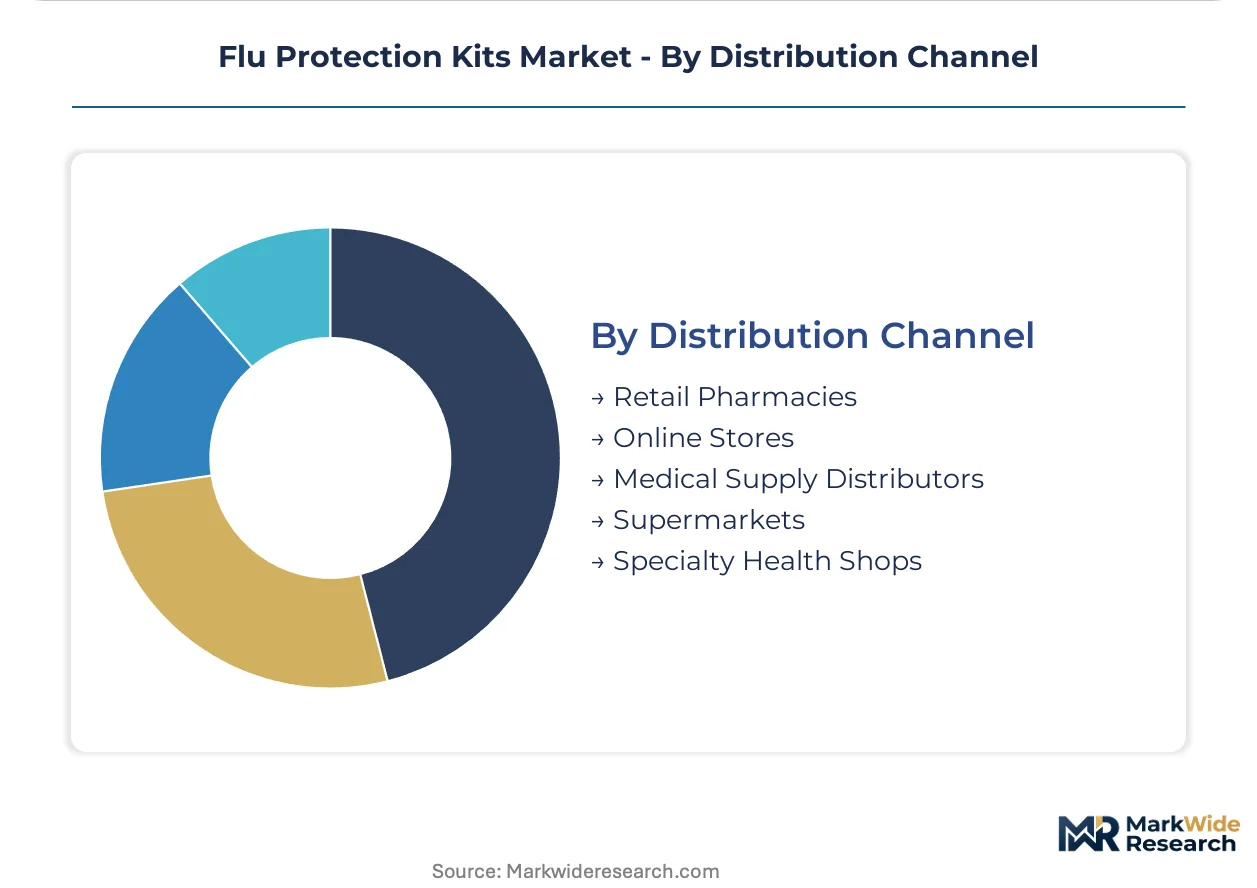
Supply concentration in medical supply distributors is displacing fragmented PPE resellers as enterprise buyers demand bundled compliance documentation.
- Retail Pharmacies:CVS, Walgreens, and independent chains serve seasonal consumer demand with basic configurations.
- Online Stores:Amazon and specialized health e-commerce platforms compete on price transparency and subscription replenishment.
- Medical Supply Distributors:McKesson, Cardinal Health, and regional operators dominate institutional channels with regulatory file management.
- Supermarkets:Mass merchandisers capture impulse purchases through prominent seasonal displays.
- Specialty Health Shops:Occupational safety suppliers and industrial distributors serve manufacturing sector procurement with technical consultation.
Medical supply distributors command institutional volume. Online stores are expanding most quickly through subscription model penetration in corporate wellness programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workplace safety managers concentrate procurement power in industrialized economies where employer liability frameworks have tightened most aggressively. Germany, the United States, and select Asian manufacturing hubs now absorb the majority of premium kit volumes.
United States
OSHA bloodborne pathogen standards mandate accessible PPE inventories across manufacturing facilities. FDA 510(k) clearance requirements for clinical-grade thermometers shape kit composition for enterprise buyers. The Midwest manufacturing belt spanning Michigan, Ohio, and Illinois sustains dense consumption through automotive and heavy industry employment.
Germany
Ruhr industrial corridor and Bavarian automotive plants absorb medical-grade kit configurations under strict occupational health mandates. EU MDR technical documentation requirements for diagnostic components elevate supplier qualification thresholds. Dense manufacturing employment in North Rhine-Westphalia sustains premium consumption through regulatory compulsion.
China
Domestic meltblown polypropylene capacity clusters in East Asian manufacturing zones supply ASTM F2100-rated mask components. NMPA and GB standards govern thermometer accuracy claims for kits entering domestic channels. Yangtze River Delta industrial zones drive bulk procurement for workplace safety applications.
Japan
METI industrial safety guidelines and PMDA device regulations structure enterprise kit specifications. Aging workforce demographics accelerate preventive health spending in manufacturing sectors. Kansai region automotive suppliers and Kanto electronics assemblers systematize seasonal preparedness programs.
United Kingdom
Health and Safety Executive enforcement patterns elevate employer liability exposure for influenza transmission in communal workplaces. MHRA device regulations parallel EU MDR requirements for thermometer component claims. London financial services and Midlands manufacturing distribute demand across corporate wellness and industrial safety channels.
Flu Protection Kits Market Competitive Landscape
Player mix skews toward diversified health conglomerates with respiratory protection heritage and clinical diagnostics capabilities. Three strategic archetypes dominate: industrial PPE specialists leveraging channel relationships, clinical diagnostics firms bundling thermometer and testing components, and consumer health brands extending into corporate wellness. Competitive moves concentrate on regulatory file consolidation and multi-standard certification capacity building.
Among diversified health conglomerates, 3M Company, Abbott Laboratories, and Becton Dickinson and Company exemplify the three dominant positioning vectors. 3M occupies a position anchored in respiratory protection heritage across North American industrial channels. Abbott represents consumer brand equity extension into employer-sponsored preventive health initiatives. Becton Dickinson sits within the clinical-grade diagnostics tier, with thermometer and testing bundling capabilities that satisfy enterprise documentation requirements.
| Leading Market Players |
|---|
| Evav8 |
| Pandemic Protection |
| Life Secure |
| Bell Cross |
| 3M Company |
| Abbott Laboratories |
| Becton Dickinson and Company |
| Meridian Bioscience |
| Quidel Corporation |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance requirements for clinical-grade thermometers gate both supplier qualification and price stratification, compressing commodity assemblers into thin-margin territory while rewarding documented medical-grade providers with 40-60% premiums across enterprise procurement channels.
Pricing Analysis
Current-generation FDA-cleared infrared thermometers command substantial premiums over prior-generation contact devices and uncertified imports. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade enterprise configurations with full regulatory documentation from basic consumer assemblies. Cost compression in the economy tier is intensifying because East Asian mask suppliers are absorbing ethanol feedstock volatility without contractual pass-through mechanisms. Individual consumers exhibit highest price sensitivity through retail pharmacy channels, while workplace safety managers absorb compliance premiums for liability protection.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for East Asian-sourced meltblown polypropylene and ethanol-based sanitizer formulations. Manufacturing gravity centers on China for mask components, the United States for thermometer final assembly, and Germany for diagnostic validation services. Raw material dependencies span Brazilian sugarcane ethanol, Saudi petrochemical feedstocks, and Malaysian nitrile rubber. Single-source vulnerability concentrates in East Asian meltblown capacity for ASTM F2100-rated filtration media. Distribution runs through medical supply distributors with regulatory file management capabilities displacing fragmented PPE resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats as multi-standard certification capacity demands specialized compliance infrastructure that smaller assemblers cannot replicate.
For Market Incumbents: Shield market position by deepening backward integration into domestic meltblown polypropylene production to offset East Asian supply concentration, while accelerating CE marking investments ahead of EU MDR enforcement waves. Channel control through industrial distributor exclusivity agreements limits emerging entrant access to workplace safety procurement committees. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for non-contact infrared thermometers offer the most penetrable entry vector against established diagnostics conglomerates. White-space concentration sits in mid-tier educational institution procurement, where duty-of-care obligations exceed budget constraints but fall short of healthcare-grade documentation requirements. Direct-to-corporate subscription models bypass distributor markup capture. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward targets with notified body relationships and clinical accuracy validation records. Long-term viability favors diversified health conglomerates with respiratory protection heritage extending into diagnostic bundling. Watch employer mandate legislation in German federal states as the signal for seasonal preparedness program institutionalization.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | Simultaneous FDA, OSHA, and EU MDR compliance unlocks premium enterprise channel access. |
| Backward Integration into Meltblown Capacity | Domestic polypropylene filtration media production mitigates East Asian single-source vulnerability. |
| Corporate Wellness Platform Bundling | Over-the-counter brand equity extension captures B2B procurement consolidation trends. |
| Smart Packaging Sensor Integration | Temperature and humidity validation capabilities displace commodity kit suppliers in hospital channels. |
| Industrial Distributor Exclusivity Agreements | Documented supply partnerships with training protocols satisfy tightening employer liability frameworks. |
Research Methodology
Initial hypotheses were tested against primary input from workplace safety managers, hospital procurement directors, industrial distributor account executives, and regulatory affairs specialists at diagnostics manufacturers, then refined through secondary validation across FDA 510(k) device databases, OSHA enforcement records, EU MDR technical documentation filings, and hospital GPO contract repositories. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Variance decomposition across product type, application tier, end-user category, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling calibrated to employer mandate legislative trajectories and seasonal vaccine efficacy variability patterns. Diagnostic component bundling ratios and PPE inventory turnover benchmarks served as industry-specific forecast anchors.
Decision-makers should treat outputs as directional under assumptions of sustained employer liability tightening and stable ethanol feedstock availability; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Instrumentation Systems Market