
 Middle East and Africa N95 Mask Market | 2026-2036
Middle East and Africa N95 Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa N95 Mask Market Foresight
NIOSH certification is reorganizing competitive access across the Middle East and Africa N95 Mask Market, filtering out suppliers lacking validated filtration documentation. 3M leverages its established regulatory dossiers to sustain tender participation across Gulf hospital systems. Kimberly-Clark anchors institutional procurement channels through direct contracts with national health ministries. Honeywell International Inc. differentiates via industrial safety specialization, targeting oil and gas sector buyers with flame-resistant respirator variants.
An N95 mask is a disposable particulate-filtering facepiece respirator engineered to achieve minimum filtration efficiency of 95% against airborne particles measuring 0.3 microns, constructed from layered polypropylene melt-blown nonwoven electret media bonded to spunbond outer and inner facing layers. Cup shape configurations dominate industrial contracts where fit stability under heavy exertion matters, while flat fold designs lead healthcare procurement due to compact storage and lower unit cost in bulk pandemic stockpiles. Valve type segments face structural headwind from clinical settings banning exhalation valves to protect sterile fields, redirecting margin pools toward valveless NIOSH Approved units.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority frameworks govern import registration, with NIOSH and CE marking serving as parallel acceptance benchmarks for cross-border tenders. The UAE's Ministry of Health and Prevention mandates shelf-life verification and lot-traceability documentation that reshapes distributor qualification requirements. Stakeholders must monitor harmonization between Gulf Standards Organization respirator specifications and existing NIOSH protocols to anticipate dual-testing cost impacts on sourcing economics.
Market Dynamics
NIOSH certification mandates are compressing supplier access across Middle East and Africa hospital procurement channels, filtering out uncertified imports while elevating validated domestic manufacturers into national stockpile tenders.
Growth Catalysts
- Saudi Food and Drug Authority stockpile mandates:Revised pandemic preparedness frameworks require ministry-level procurement of NIOSH-approved respirators, institutionalizing demand from Saudi Arabian hospital systems.
- Oil and gas sector occupational safety enforcement:Gulf Cooperation Council states are tightening respiratory protection requirements for petrochemical and refining operations, expanding industrial N95 consumption beyond healthcare.
- Electret melt-blown media localization:Polypropylene supply chain investments in South Africa and Egypt are reducing import dependency for filtration layer materials.
Market Restraints
- Polypropylene price volatility:Feedstock cost swings for spunbond and melt-blown nonwoven layers compress margin predictability for contract manufacturers.
- Testing facility concentration:NIOSH-equivalent validation capacity clusters in South Africa and UAE, creating bottlenecks for East African and Levantine suppliers seeking market entry.
- Surgical mask substitution in low-acuity settings:Lower-cost procedure masks displace N95 demand in non-aerosol-generating clinical environments.
Strategic Opportunities
- Kenya and Ethiopia healthcare infrastructure expansion:World Bank-funded hospital construction programs create first-mover advantages for NIOSH-certified suppliers establishing East African distribution.
- Flame-resistant respirator variants for energy sector:Convergence of fire safety and respiratory protection standards opens specialized product lines for offshore and downstream oil operations.
- Direct-to-institution e-procurement platforms:UAE and Saudi Arabian health ministry digital tender systems reduce distributor markup layers for qualified manufacturers.
Industry Challenges
- NIOSH approval timeline compression:Extended validation queues at accredited testing bodies delay product launches for new market entrants by 12-18 months.
- Fit-testing competency scarcity:Occupational health technician shortages across Gulf states limit proper respirator program implementation for industrial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa N95 Mask Market |
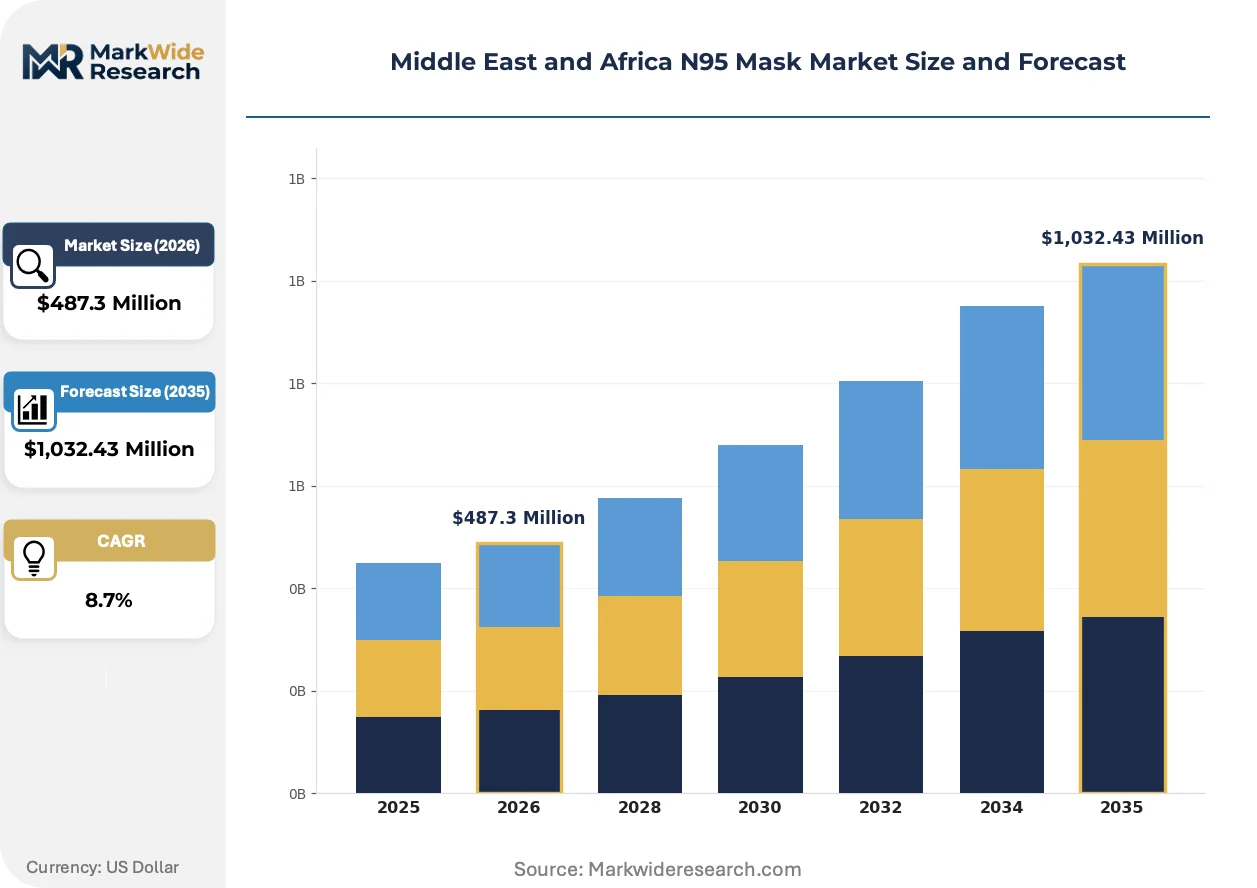
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Fold, Cup Shape, Valve Type, Niosh Approved End User: Healthcare, Construction, Manufacturing, Agriculture Distribution Channel: Online Retail, Pharmacies, Wholesalers, Hospitals Application: Personal Protection, Industrial Safety, Healthcare Facilities, Emergency Response |
| Companies Covered | 3M, Honeywell International Inc., Kimberly-Clark, Medline Industries, Cardinal Health, Owens & Minor, Ansell, Moldex-Metric, Shanghai Dasheng Health Products Manufacture Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa N95 Mask Market Shifts & Advancements
Respirator design and distribution architectures across the Middle East and Africa are converging around portability, regulatory interoperability, and procurement digitization.
Ultrasonic welding of multi-layer polypropylene assemblies is miniaturizing production footprints for regional manufacturers. Compact melt-blown lines are enabling South African and Egyptian producers to achieve NIOSH-grade filtration consistency without capital-intensive imported equipment. This technology diffusion is compressing the minimum efficient scale for viable domestic production.
South African Health Products Regulatory Authority alignment with NIOSH protocols is streamlining cross-border acceptance for certified respirators. The framework eliminates redundant testing for products holding US approval, reducing time-to-market for manufacturers targeting both SADC and North American buyers. Industrial procurement officers in mining and petrochemical sectors are prioritizing dual-certified inventory to simplify compliance documentation.
Hospital buyers across Gulf Cooperation Council states are consolidating respiratory protection contracts under framework agreements spanning 24-36 month terms. Long-tenor procurement is displacing spot-market purchasing, compressing distributor margins while rewarding manufacturers with validated supply continuity records. Saudi Arabian ministry tenders now specify lot-traceability and shelf-life verification as mandatory evaluation criteria.
Middle East and Africa N95 Mask Market Segmentation
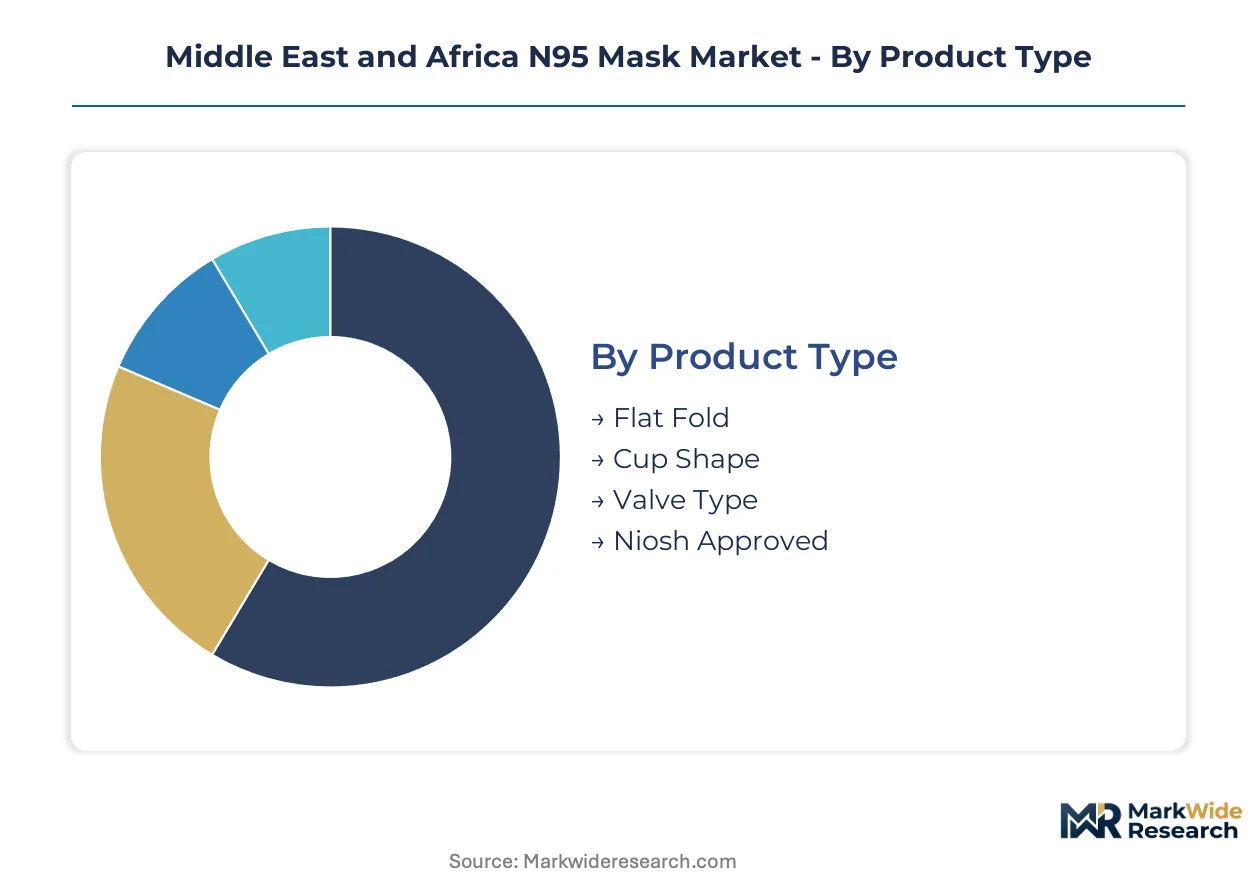
N95 mask procurement across the Middle East and Africa fragments across four intersecting dimensions. Regulatory alignment, end-use concentration, channel control, and application severity each reshape supplier access and margin capture differently.
Product Type:
NIOSH approval status creates the sharpest commercial divide, with certified units commanding tender eligibility and uncertified alternatives relegated to informal trade.
- Flat Fold:Multi-layer polypropylene construction enables compact storage and lower per-unit shipping costs. Saudi Arabian ministry stockpiles favor this format for pandemic warehousing density, though fit-testing failure rates run higher than cup alternatives in industrial settings.
- Cup Shape:Rigid thermoformed shells maintain seal integrity under heavy exertion and facial movement. Oil and gas operators across the UAE and Qatar specify cup configurations for offshore platform maintenance crews where respirator displacement risks exposure.
- Valve Type:Exhalation valves reduce breathing resistance and heat buildup for extended industrial wear. Clinical bans on valved units across Gulf hospital systems have collapsed healthcare demand, redirecting production toward petrochemical buyers.
- NIOSH Approved:Validated filtration documentation unlocks participation in Saudi Food and Drug Authority-regulated tenders and South African Health Products Regulatory Authority registrations. This designation functions as a binary market access gate across formal procurement channels.
Flat Fold handles the majority of throughput; NIOSH Approved is expanding most quickly on share as regulatory enforcement tightens.
End User:
Demand concentration varies sharply by sector compliance maturity and respiratory protection program sophistication.
- Healthcare:Ministry-level stockpiling in Saudi Arabia and South Africa institutionalizes bulk purchasing through framework agreements. Aerosol-generating procedure mandates sustain valveless N95 consumption despite surgical mask substitution in low-acuity wards.
- Construction:Silica dust exposure regulations are fragmenting across Gulf Cooperation Council jurisdictions, with UAE enforcement outpacing Kuwait and Oman. Fit-testing infrastructure gaps limit proper program implementation on smaller building sites.
- Manufacturing:Cement and metal fabrication plants represent the largest industrial volume outside oil and gas. Egyptian and Moroccan factory inspectors are beginning to reference NIOSH protocols in occupational safety audits.
- Agriculture:Grain dust and pesticide exposure drives seasonal demand spikes during harvest windows. Distribution runs through agricultural cooperatives rather than industrial safety suppliers, creating channel discontinuity with healthcare procurement systems.
Healthcare dominates current volume; Manufacturing is climbing the fastest as factory inspection regimes formalize.
Distribution Channel:
Channel control determines margin retention and customer relationship depth across divergent buyer types.
- Online Retail:E-commerce platforms serve individual buyers and small businesses with limited procurement infrastructure. Saudi Arabian and UAE consumers increasingly verify NIOSH certification numbers through manufacturer databases before purchase.
- Pharmacies:Community pharmacy networks handle consumer-facing sales with limited technical guidance on fit and seal testing. South African retail pharmacy chains are expanding respiratory protection SKUs following pandemic-driven category awareness.
- Wholesalers:Industrial distributors maintain inventory breadth across safety categories and provide fit-testing equipment alongside respirator supply. Margin compression from direct e-procurement platforms threatens traditional wholesaler economics in Gulf hospital systems.
- Hospitals:Direct contracting with national health ministries eliminates intermediary markups for qualified manufacturers. Lot-traceability and shelf-life documentation requirements are reshaping supplier qualification criteria in Saudi Arabian tenders.
Hospitals capture the steepest expansion trajectory; Wholesalers retain the largest share of industrial volume.
Application:
Application severity dictates performance specifications and replacement frequency across use cases.
- Personal Protection:Individual purchase decisions prioritize cost and availability over fit-testing rigor. Informal construction and transportation workers across the Levant and North Africa rely on uncertified alternatives due to price sensitivity.
- Industrial Safety:Regulatory compliance programs mandate documented fit testing, training, and respirator maintenance. Oil and gas majors in Qatar and the UAE specify flame-resistant variants for downstream and offshore operations.
- Healthcare Facilities:Infection control protocols require valveless designs and validated filtration efficiency. Pandemic preparedness mandates in Saudi Arabia and South Africa institutionalize strategic stockpile requirements.
- Emergency Response:Civil defense and disaster management agencies require surge-ready inventory with extended shelf-life documentation. UAE and Saudi Arabian emergency response frameworks specify NIOSH-approved units for hazmat and pandemic scenarios.
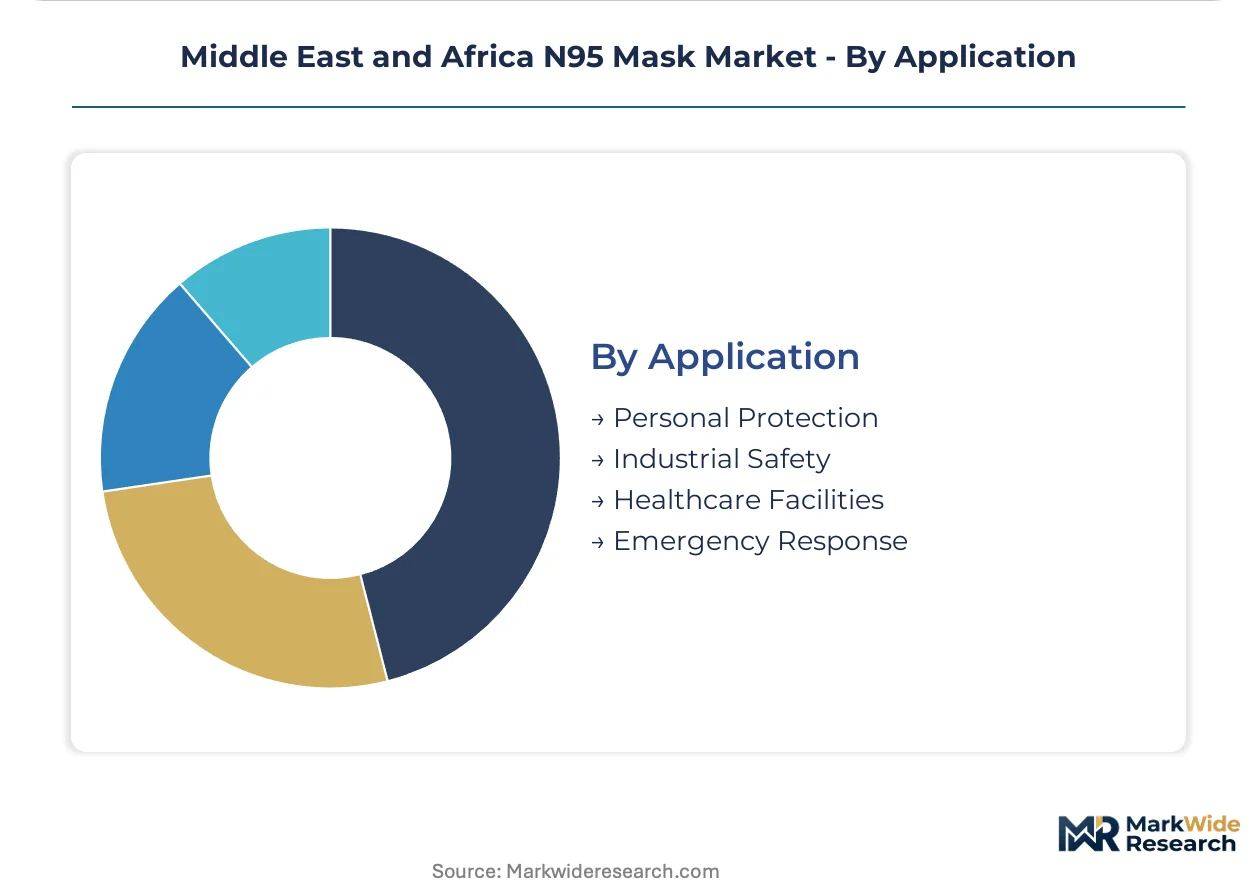
Healthcare Facilities command the dominant share; Industrial Safety is gaining share fastest as occupational safety enforcement broadens beyond oil and gas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ministry procurement officers and industrial safety managers dominate purchasing decisions across the Middle East and Africa N95 Mask Market, with tender participation gated by NIOSH validation documentation.
Saudi Arabia
SFDA stockpile mandates and hospital infrastructure spending institutionalize bulk purchasing through 24-36 month framework agreements. The Saudi Food and Drug Authority requires lot-traceability and shelf-life verification as mandatory tender evaluation criteria. Riyadh-based ministry procurement channels concentrate demand for valveless NIOSH-approved units in healthcare facilities.
United Arab Emirates
MOHAP mandates and oil sector occupational safety enforcement sustain dual demand streams across healthcare and petrochemical applications. The Ministry of Health and Prevention mandates shelf-life verification and lot-traceability documentation that reshapes distributor qualification requirements. Dubai and Abu Dhabi hospital systems consolidate respiratory protection contracts under long-tenor procurement agreements.
South Africa
SAHPRA registration alignment with NIOSH protocols streamlines cross-border acceptance for certified respirators targeting SADC buyers. The South African Health Products Regulatory Authority framework eliminates redundant testing for products holding US approval. Johannesburg and Cape Town industrial distributors maintain inventory breadth across mining and manufacturing safety categories.
Egypt
Polypropylene melt-blown media localization investments reduce import dependency for filtration layer materials in domestic manufacturing. Factory inspector reference to NIOSH protocols in occupational safety audits formalizes respirator program requirements. Cairo and Alexandria cement and metal fabrication plants represent expanding industrial volume outside oil and gas.
Qatar
Offshore platform maintenance specifications and downstream fire safety standards drive demand for flame-resistant respirator variants. Energy sector convergence of fire safety and respiratory protection standards opens specialized product lines for petrochemical buyers. Doha-based oil and gas majors specify cup configurations for crews facing respirator displacement risks.
Middle East and Africa N95 Mask Market Competitive Landscape
Player mix skews toward multinational safety conglomerates with established NIOSH dossiers, compressing access for uncertified regional entrants. Tiered supplier segmentation separates validated tender participants from informal trade alternatives. Three archetypes dominate: diversified industrial safety conglomerates with respiratory specialization, healthcare-focused disposable hygiene manufacturers, and emerging regional fabricators investing in electret media localization. Competitive moves concentrate on direct ministry contracting to bypass distributor markups and on flame-resistant product line extensions for energy sector differentiation.
Among US-based industrial safety conglomerates, 3M and Honeywell International Inc. anchor the premium tier through established regulatory dossiers and tender participation records. Shanghai Dasheng Health Products Manufacture Company exemplifies the emerging regional fabricator archetype, representing investments in polypropylene supply chain localization. Kimberly-Clark occupies a position bridging healthcare and industrial channels through direct ministry contracting capabilities.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Kimberly-Clark |
| Medline Industries |
| Cardinal Health |
| Owens & Minor |
| Ansell |
| Moldex-Metric |
| Shanghai Dasheng Health Products Manufacture Company |
| Others |
Supply & Pricing Matrix
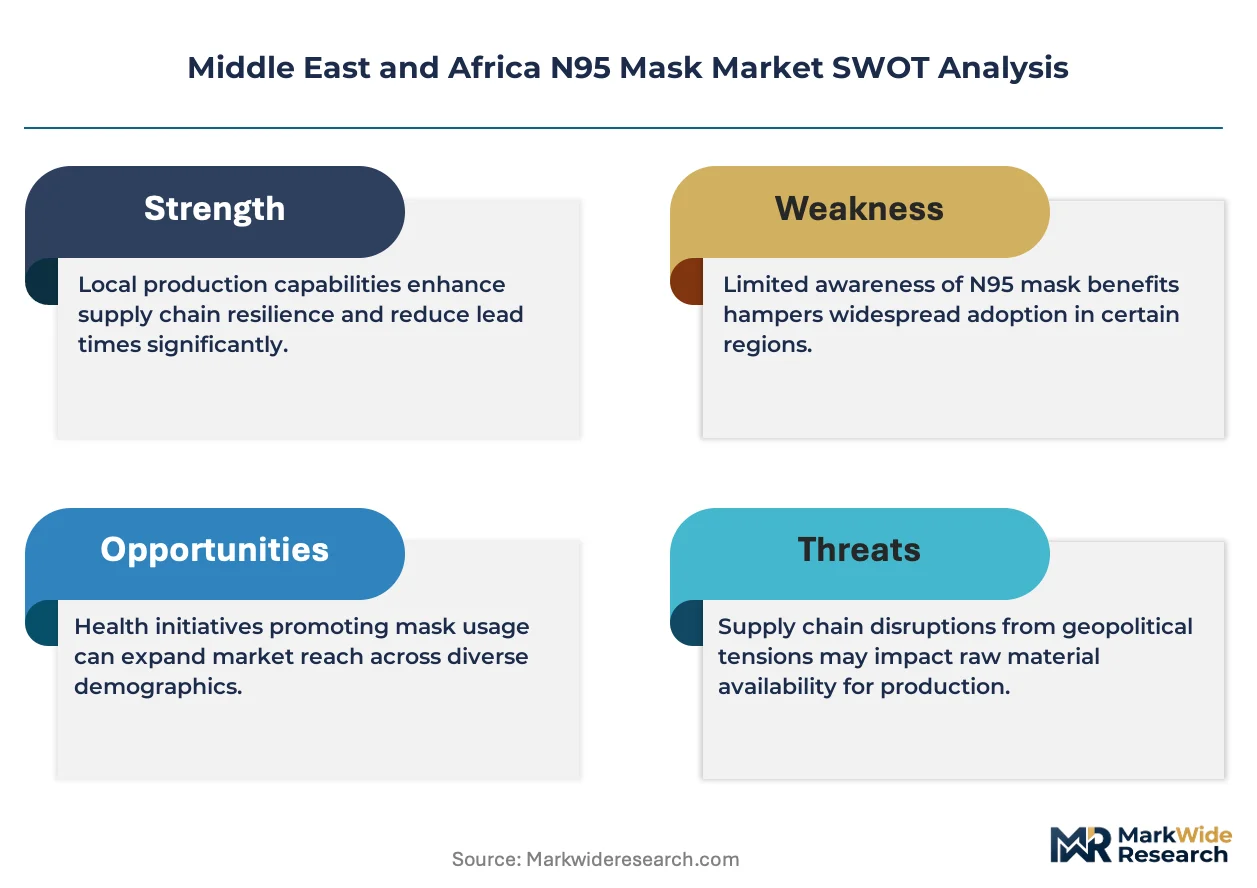
NIOSH certification gates simultaneously determine supplier qualification tiers and price differentiation ladders across Middle East and Africa procurement channels. Saudi Food and Drug Authority tender requirements compress margin pools for uncertified alternatives while elevating validated manufacturers into premium contract brackets.
Pricing Analysis
Cost-plus contracts with polypropylene indexation dominate Saudi Arabian ministry tenders and UAE hospital framework agreements. Three-tier pricing structure across NIOSH-approved premium, CE-marked standard, and uncertified economy levels tracks certification depth and lot-traceability documentation. Price differentiation stems from validation documentation completeness and volume scale commitments. Pricing pressure intensifies in the economy tier as Egyptian and South African domestic producers achieve electret media localization. Industrial oil and gas buyers demonstrate lowest price sensitivity due to regulatory compliance mandates, while informal construction workers across the Levant exhibit acute cost consciousness.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock delivery timelines for Gulf Cooperation Council melt-blown production facilities. Polypropylene resin supply concentrates in Saudi Arabia, South Africa, and Egypt following downstream petrochemical investments. Raw material dependencies span spunbond nonwoven facing layers, electret-charged melt-blown filtration media, and aluminum nose clip components. Single-source vulnerability clusters in NIOSH-equivalent testing capacity located in South Africa and UAE, creating validation bottlenecks for East African entrants. Distribution runs through industrial safety wholesalers for energy sector buyers and direct ministry contracting for healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats for validated participants, as NIOSH certification switching costs lock hospital systems into proven supplier relationships.
For Market Incumbents: Fortify tender participation records through direct contracting with Saudi Arabian and South African health ministries. Deepen backward integration into electret melt-blown media production to offset polypropylene price volatility. Expand flame-resistant respirator SKUs for Qatar and UAE offshore oil specifications. Counter emerging Egyptian and South African fabricators by accelerating NIOSH approval timeline compression through pre-submission testing protocols. For New Entrants and Emerging Players: SAHPRA-NIOSH alignment fast-tracks cross-border acceptance for products holding US validation, opening SADC market entry without redundant testing. Prioritize Kenya and Ethiopia healthcare infrastructure expansion funded by World Bank hospital construction programs. Target agricultural cooperative distribution channels for seasonal grain dust protection demand. Secure e-procurement platform registration with UAE and Saudi Arabian health ministry digital tender systems to bypass traditional wholesaler markups. For Investors and Strategic Acquirers: SFDA stockpile mandate implementation reshapes the acquisition landscape toward certified manufacturers with established ministry contract books. Frame long-term viability around regulatory barrier sustainability rather than pandemic demand cyclicality. Target acquisition candidates with dual NIOSH-CE certification and existing Gulf hospital framework agreements. Monitor harmonization progress between Gulf Standards Organization respirator specifications and NIOSH protocols as signal for dual-testing cost impacts on regional sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Fast-Track Investment | SFDA tender eligibility unlocks Saudi Arabian ministry stockpile contracts. |
| Electret Media Localization | Cairo and Johannesburg production reduces import dependency for filtration layers. |
| Flame-Resistant Product Line Extension | Qatar offshore specifications open specialized petrochemical buyer segments. |
| Direct Ministry E-Procurement Registration | UAE MOHAP digital platforms eliminate distributor margin layers. |
| East African Distribution Establishment | World Bank-funded hospital construction in Kenya creates first-mover positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hospital procurement databases. Interviews with Saudi Food and Drug Authority compliance officers, South African Health Products Regulatory Authority registration specialists, UAE Ministry of Health and Prevention procurement directors, and industrial safety managers at Qatar petroleum operators informed demand segmentation. Secondary sources included SFDA medical device registration records, Gulf Standards Organization technical specifications, and electret media production capacity disclosures from Egyptian and South African manufacturers. Bottom-up unit demand estimates triangulate against top-down healthcare expenditure allocations.
Segmentation dimensions modeled span product type, end user, distribution channel, and application severity across the projection horizon. NIOSH approval status, valve configuration, and flat fold versus cup shape architecture drive product-level forecasts. Healthcare ministry stockpile mandates, oil and gas occupational safety enforcement, and manufacturing inspection regime formalization shape end-use trajectories. CAGRs derive from regression analysis of historical procurement volumes against regulatory milestone implementation timelines. Electret melt-blown media localization progress and polypropylene feedstock cost indices serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained NIOSH certification enforcement and stable Gulf hospital infrastructure spending; material deviation in regulatory harmonization timelines or petrochemical sector capital allocation would warrant model refresh. Practitioners should keep alternative scenarios live as Saudi-Egyptian polypropylene supply chain integration and East African healthcare financing commitment levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Latin America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market