
 China Premium Motorcycle Helmet Market | 2026-2036
China Premium Motorcycle Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
China Premium Motorcycle Helmet Market Outlook
Modular helmet configurations is decoupling the traditional full-face monopoly by letting riders switch between open and closed modes without carrying multiple units. Schuberth GmbH leverages its acoustic engineering heritage to dominate touring-oriented modular designs. LS2 Helmets competes on manufacturing scale from its Zhejiang production base. Arai Helmet Ltd sustains its position through hand-built shell construction and rigorous quality protocols that command premium shelf placement in tier-one Chinese cities.
A premium motorcycle helmet is a protective headgear system engineered to absorb impact energy through multi-density EPS liners and distribute crash loads across carbon fiber, fiberglass, or Kevlar composite shells, primarily serving riders who demand certified safety performance above statutory minimums. Full-face variants occupy the largest revenue pool due to their structural integrity and noise isolation, while carbon fiber material grades capture the fastest growth trajectory as weight reduction becomes a decisive purchase criterion among performance-oriented buyers. Bluetooth-enabled feature sets are maturing into baseline expectations rather than differentiators, shifting margin pools toward integrated communication ecosystems.
China's GB 811-2022 national standard, administered by the Standardization Administration of China (SAMR), mandates stricter impact testing and visor optical clarity benchmarks that disqualify legacy inventory and force distributor network upgrades. The Ministry of Industry and Information Technology (MIIT) coordinates with provincial traffic authorities to align enforcement timelines, creating phased compliance windows that advantage prepared suppliers. Stakeholders must monitor how SAMR's anticipated alignment with United Nations ECE R22.06 protocols will reshape import certification pathways and domestic R&D investment priorities.
Market Dynamics
GB 811-2022 compliance deadlines are compressing replacement cycles and forcing distributor inventory turnover, while carbon fiber shell adoption accelerates among performance buyers who treat weight reduction as a non-negotiable purchase criterion.
Growth Catalysts
- Leisure touring expansion:Middle-class urban professionals in Shanghai and Hangzhou are entering the premium helmet category, expanding the addressable buyer base beyond traditional motorsport enthusiasts.
- GB 811-2022 mandate:SAMR's stricter impact-absorption testing disqualifies legacy inventory, forcing systematic replacement and creating compliance-driven demand windows.
- Yangtze River Delta clustering:E-commerce fulfillment networks anchored by Shanghai and Hangzhou enable same-day premium delivery, reducing purchase friction for high-consideration safety equipment.
Market Restraints
- Carbon fiber input volatility:Toray-grade prepreg supply concentrates among Japanese and Korean suppliers, exposing margin structures to aerospace demand competition and currency fluctuation.
- MIIT enforcement fragmentation:Provincial traffic authorities operate on staggered compliance timelines, creating inventory stranding risk for distributors serving multiple jurisdictions.
- Modular mechanism durability:Chin-bar pivot systems face accelerated wear testing under GB 811-2022 protocols, raising warranty exposure for multi-configuration designs.
Strategic Opportunities
- Western China penetration:Chengdu and Chongqing rider communities remain underpenetrated by premium retail presence, presenting first-mover expansion potential for experiential showroom formats.
- ECE R22.06 alignment:SAMR's anticipated protocol harmonization will streamline import certification for European manufacturers, reducing time-to-market for certified premium entrants.
- Integrated communication ecosystems:Mesh-network intercom systems are integrating with helmet-embedded speakers and noise-canceling microphones, shifting margin pools from hardware to subscription service layers.
Industry Challenges
- EPS liner molding precision:Multi-density liner fabrication requires tight tolerance control that outstrips domestic equipment capabilities, forcing reliance on Taiwanese and Korean mold suppliers.
- Visor optical clarity certification:GB 811-2022's refractive index benchmarks demand capital-intensive metrology equipment that smaller domestic manufacturers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Premium Motorcycle Helmet Market |
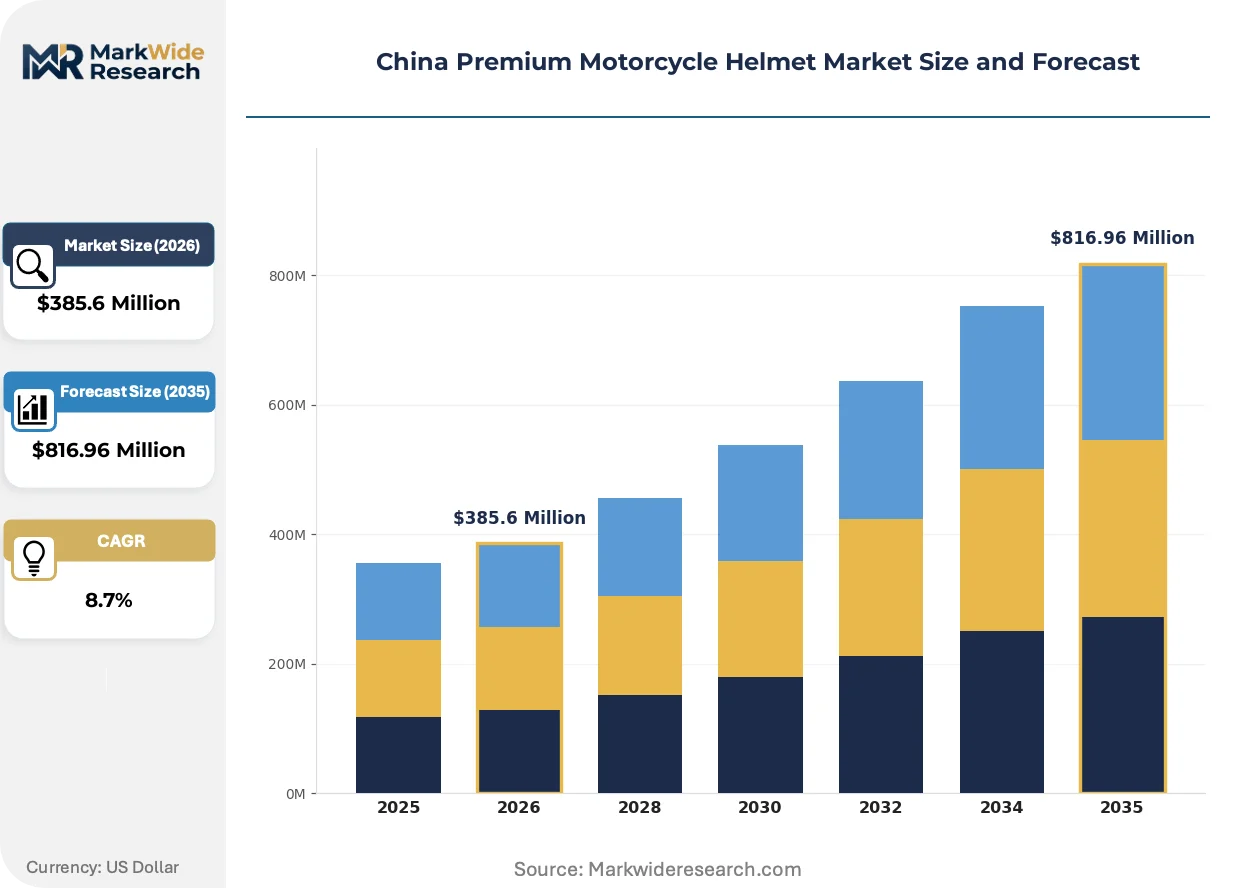
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face, Open-Face, Modular, Half-Helmet Material: Polycarbonate, Fiberglass, Carbon Fiber, Kevlar End User: Motorcyclists, Delivery Riders, Tourists, Off-Road Enthusiasts Feature: Bluetooth-Enabled, Sun Visor, Anti-Fog, Lightweight |
| Companies Covered | Shark Helmets, Schuberth GmbH, AGV, Nolan Group, HJC Helmets, Shoei Co. Ltd, LS2 Helmets, KYT Helmets, Arai Helmet Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Premium Motorcycle Helmet Market Strategic Shifts
Active noise cancellation and heads-up display projection are migrating from automotive into helmet-embedded systems, while regulatory pressure on impact performance drives material substitution toward advanced composites.
Carbon fiber reinforced polymer shell construction is integrating multi-axial layup patterns that optimize crush-zone deformation while preserving structural integrity at the chin and temple. Performance-oriented buyers in Guangdong and Zhejiang provinces are specifying T800-grade fiber density as a baseline requirement. This material transition is integrating weight reduction as a primary competitive axis, compressing market share for fiberglass-dominant product lines.
MIIT's coordination with SAMR on GB 811-2022 enforcement timelines is creating phased compliance windows that advantage prepared suppliers with existing testing infrastructure. The standard's visor optical clarity benchmarks disqualify polycarbonate formulations that previously satisfied legacy requirements. Full-face variants with integrated sun visor mechanisms face the steepest redesign burden, as dual-lens systems must simultaneously satisfy impact and optical protocols.
Certification-driven preference shifts are compressing purchase decision cycles among fleet and club buyers who previously prioritized aesthetic customization. Group procurement through riding clubs and delivery platforms is displacing individual retail transactions in tier-one cities. This concentration is most visible in Beijing and Shenzhen, where corporate safety programs mandate ECE or GB-certified equipment for commercial riders.
China Premium Motorcycle Helmet Market Segmentation
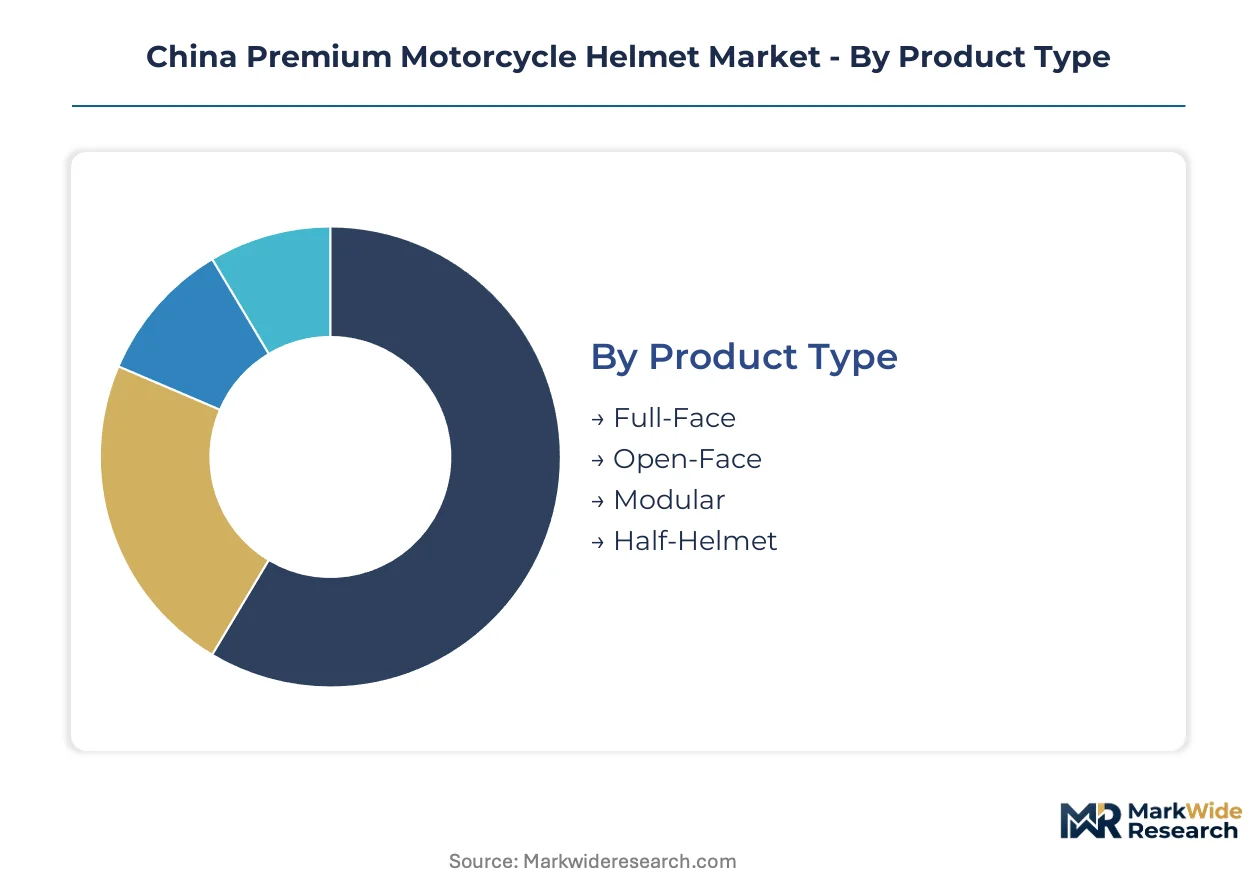
Helmet buyers in China stratify sharply across protection priorities, price sensitivity, and riding context. Segmentation reveals where GB 811-2022 compliance costs concentrate and which material upgrades riders will actually pay for.
Product Type:
Structural integrity demands separate touring professionals from urban commuters who trade coverage for convenience.
- Full-Face:Enclosed chin-bar construction delivers maximum impact protection and wind noise suppression. Demand clusters among Yangtze River Delta touring clubs where Shanghai-based riders prioritize certified safety over ventilation convenience. GB 811-2022's stricter chin-bar testing reinforces this segment's structural advantages.
- Modular:Hinged chin-bar mechanisms permit open-face configuration without helmet removal. Hangzhou's leisure touring community drives adoption as riders switch between highway cruising and city photography stops. Pivot durability under new impact protocols raises warranty exposure for multi-mode designs.
- Open-Face:Three-quarter coverage preserves peripheral vision and ventilation for low-speed urban navigation. Delivery platforms in Shenzhen specify these for last-mile efficiency despite reduced protection ratings.
- Half-Helmet:Minimal scalp coverage meets statutory minimums at lowest price points. Rural replacement markets in Henan and Sichuan absorb inventory displaced from tier-one compliance upgrades.
Volume sits with Full-Face; growth tilts toward Modular.
Material:
Shell composition determines weight-to-strength ratios that separate performance buyers from price-driven purchasers.
- Carbon Fiber:T800-grade multi-axial layups achieve 30-40% weight reduction over fiberglass equivalents. Guangdong track-day enthusiasts specify this density as non-negotiable, though Toray-grade prepreg supply constraints expose margins to aerospace demand competition.
- Fiberglass:Woven glass-reinforced polymer balances impact absorption with manufacturing scalability. Zhejiang production bases supply mid-tier distributors serving Hangzhou and Ningbo commuter markets.
- Kevlar:Aramid fiber reinforcement enhances penetration resistance for off-road and adventure applications. Chongqing's emerging rider base shows early preference for this specification.
- Polycarbonate:Injection-molded thermoplastic shells dominate entry-premium pricing. GB 811-2022's optical clarity benchmarks are forcing formulation upgrades that compress already-thin margins.
Revenue concentrates in Carbon Fiber; expansion runs fastest through Fiberglass as compliance-driven replacement scales.
End User:
Risk exposure and employer liability reshape procurement patterns across rider categories.
- Motorcyclists:Enthusiast owners making discretionary safety investments. Beijing and Shanghai club membership drives group purchasing that displaces individual retail.
- Delivery Riders:Platform-employed couriers subject to corporate safety mandates. Meituan and Ele.me procurement contracts now require GB or ECE certification, compressing decision cycles.
- Tourists:Rental fleet operators in Chengdu and Xi'an seeking damage-resistant inventory with standardized fit systems.
- Off-Road Enthusiasts:Desert and mountain riders prioritizing ventilation and goggle compatibility over highway noise isolation.
Procurement volume aggregates with Delivery Riders; margin expansion favors Motorcyclists.
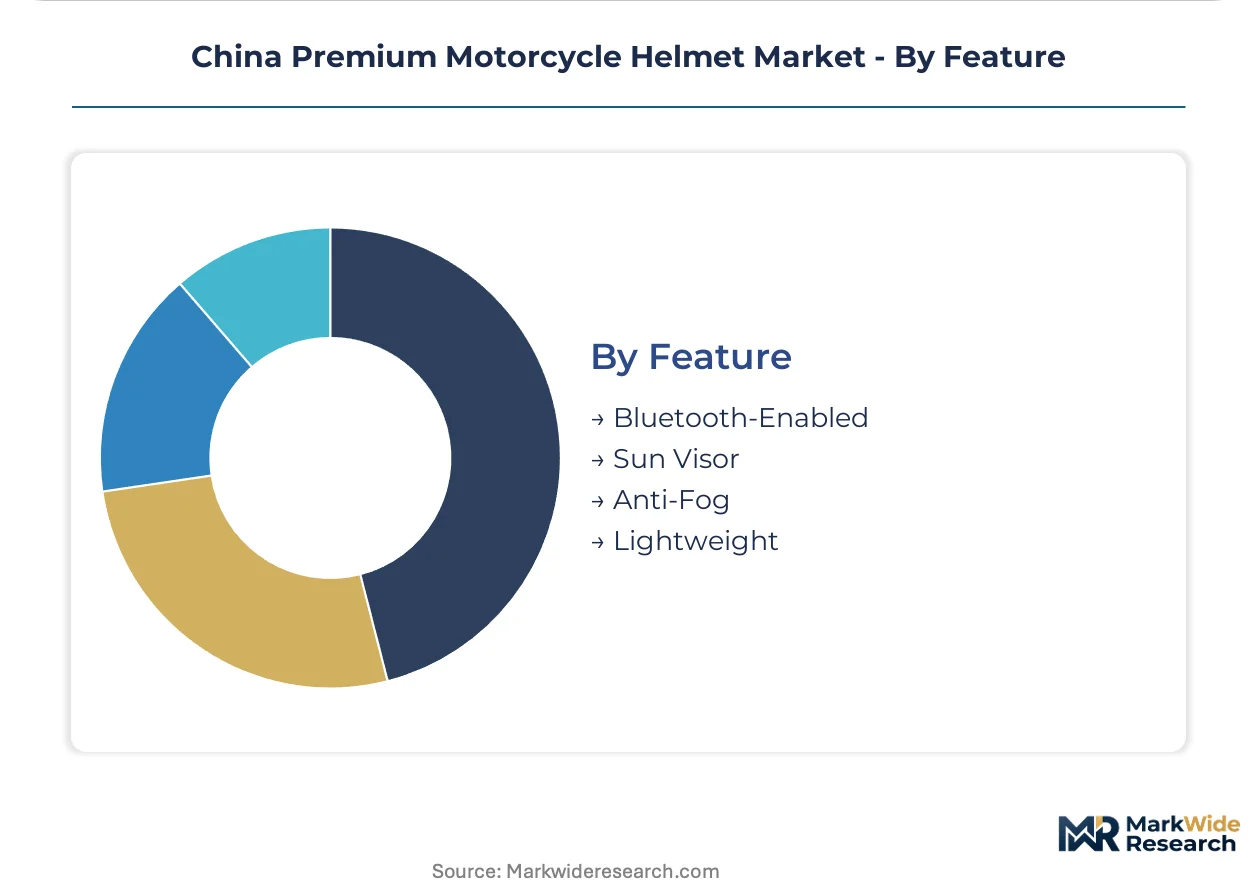
Feature:
Connectivity and comfort specifications are shifting from premium differentiators to baseline expectations.
- Bluetooth-Enabled:Integrated speaker and microphone arrays for navigation and intercom functions. Mesh-network compatibility is becoming standard in tier-one retail.
- Sun Visor:Drop-down internal tint reduces glare without external lens changes. Dual-lens configurations face steepest GB 811-2022 redesign burden.
- Anti-Fog:Pinlock insert systems and hydrophilic coatings maintain visibility across temperature differentials. Humid southern climates drive specification priority.
- Lightweight:Sub-1400g targets that favor carbon fiber shell adoption. Weight reduction is displacing aesthetic customization as primary purchase criterion.
Adoption saturates in Bluetooth-Enabled; specification intensity builds around Lightweight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's premium helmet production concentrates in Zhejiang and Guangdong provinces, while consumption clusters in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor. This geographic split creates distinct logistics and compliance challenges for distributors serving multiple provincial enforcement timelines under MIIT coordination.
Yangtze River Delta
Shanghai and Hangzhou anchor the nation's largest premium helmet consumption cluster, driven by leisure touring clubs and middle-class urban professionals. SAMR's GB 811-2022 enforcement has compressed replacement cycles among these safety-conscious buyers. E-commerce fulfillment networks headquartered in Shanghai enable same-day delivery of certified equipment to Jiangsu and Zhejiang riders.
Pearl River Delta
Guangdong's manufacturing base supplies carbon fiber shell components to domestic and export markets, with Shenzhen serving as the primary import certification gateway. Track-day enthusiasts in the province specify T800-grade fiber density as non-negotiable. Delivery platforms operating from Guangzhou now mandate GB or ECE certification for fleet procurement.
Beijing-Tianjin-Hebei
Corporate safety programs in the capital drive group purchasing through riding clubs, displacing individual retail transactions. The municipal traffic authority enforces GB 811-2022 on an accelerated timeline compared to western provinces. Tianjin's port infrastructure handles bulk import of European-certified inventory for northern distribution.
Sichuan-Chongqing
Western China's emerging rider base remains underpenetrated by premium retail presence, presenting first-mover expansion potential. Chongqing's motorcycle manufacturing heritage supports growing local demand for adventure and touring configurations. Provincial enforcement of GB 811-2022 lags coastal timelines, creating temporary inventory stranding risks.
Shandong Peninsula
Qingdao and Yantai host fiberglass shell production facilities serving mid-tier distributors across northern provinces. The region's industrial base lacks precision EPS liner molding capabilities, forcing reliance on Taiwanese equipment suppliers. Local riders prioritize weight reduction and Bluetooth integration over aesthetic customization.
China Premium Motorcycle Helmet Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's premium helmet market. The vendor base stratifies into three tiers: European heritage brands commanding premium shelf placement, Asian scale manufacturers optimizing production economics, and domestic challengers leveraging regulatory proximity. Consolidation pressure intensifies as GB 811-2022 compliance costs favor entities with existing testing infrastructure. Dominant competitive moves include backward integration into carbon fiber supply chains and strategic partnerships with e-commerce platforms for same-day fulfillment.
Within the European heritage tier, Schuberth GmbH and Arai Helmet Ltd exemplify acoustic engineering and hand-built quality protocols respectively. LS2 Helmets occupies a scale-driven position from its Zhejiang production base, competing on manufacturing throughput rather than premium positioning. These three entities represent distinct strategic archetypes: engineering-led differentiation, craftsmanship-based exclusivity, and operational efficiency at volume.
| Leading Market Players |
|---|
| Shark Helmets |
| Schuberth GmbH |
| AGV |
| Nolan Group |
| HJC Helmets |
| Shoei Co. Ltd |
| LS2 Helmets |
| KYT Helmets |
| Arai Helmet Ltd |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists concentrated in Zhejiang province anchor carbon fiber shell production, enabling pricing discipline that resists commoditization despite GB 811-2022 compliance cost inflation. Their captive control over Toray-grade prepreg allocation channels cost pressure selectively toward polycarbonate-dependent competitors while preserving margin pools in T800-grade premium tiers.
Pricing Analysis
Cost-down pressure on polycarbonate entry tiers accelerates because GB 811-2022 optical clarity mandates force formulation upgrades that domestic manufacturers cannot absorb. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy polycarbonate levels stratifies buyer access, with certification grade and weight specification as primary differentiation drivers. Margin tightening in the economy segment reflects aerospace demand competition for Toray prepreg, while track-day enthusiasts in Guangdong exhibit lowest price sensitivity for T800-grade specifications. Delivery platforms purchasing at volume scale drive the steepest price compression in mid-tier fiberglass configurations.
Supply Chain Analysis
MIIT's domestic-content alignment with GB 811-2022 testing infrastructure is reshaping sourcing toward in-country EPS liner mold fabrication and visor metrology equipment deployment. Shell production concentrates in China, Japan, and South Korea, with Zhejiang and Guangdong provinces feeding carbon fiber layup capacity and Toray-grade prepreg flowing from Japanese suppliers. Raw material dependencies rest on aerospace-grade carbon fiber, multi-density EPS compounds, and polycarbonate resin formulations. Single-source vulnerability concentrates in Toray's T800-grade fiber allocation, where automotive and defense demand competes for fixed capacity. Distribution runs through Shanghai-anchored e-commerce fulfillment networks enabling same-day certified equipment delivery across the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB 811-2022 compliance costs erect a barrier-to-entry moat favoring suppliers with existing SAMR-certified testing infrastructure, transforming market access into a capital-intensive qualification game rather than a design-competition.
For Market Incumbents: Lock in backward integration into carbon fiber supply chains through long-term Toray prepreg offtake agreements that freeze out emerging competitors. Expand Hangzhou and Shanghai experiential showroom footprints to capture leisure touring club procurement migrating from individual retail. Defensive positioning requires preemptive warranty reserve builds for modular chin-bar pivot systems facing accelerated GB 811-2022 wear testing protocols. For New Entrants and Emerging Players: Chongqing's adventure rider community presents an underserved buyer archetype with early preference for Kevlar-reinforced specifications and minimal incumbent retail presence. White-space penetration demands experiential pop-up formats at Sichuan motorcycle rallies rather than tier-one city flagship investments. First-mover positioning in western China compliance lag windows enables inventory placement before MIIT enforcement timelines synchronize. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic manufacturers with stranded polycarbonate inventory facing GB 811-2022 disqualification in coastal provinces. Long-term viability hinges on certified testing infrastructure ownership rather than brand equity or distribution scale. Acquisition targeting should prioritize entities with existing SAMR laboratory partnerships. The inflection signal to monitor is SAMR's anticipated ECE R22.06 protocol alignment announcement, which will recertify import pathway economics for European heritage brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Supply | Long-term Toray prepreg contracts insulate margin structures from aerospace demand competition. |
| GB 811-2022 Testing Infrastructure Investment | SAMR-certified laboratories convert compliance burden into competitor exclusion mechanism. |
| Western China Showroom Expansion | Chengdu and Chongqing experiential formats capture underpenetrated adventure touring demand. |
| Mesh-Network Communication Ecosystem Development | Subscription service layers shift margin pools beyond hardware into recurring revenue streams. |
| ECE R22.06 Pre-Certification Pathway | Early protocol alignment streamlines import certification for European heritage brand entrants. |
Study Parameters
Document review covered SAMR regulatory filings, MIIT enforcement circulars, and GB 811-2022 technical specifications, complemented by interviews with helmet product managers at Zhejiang manufacturing bases, procurement leads at Shanghai-based e-commerce platforms, SAMR certification laboratory directors, and carbon fiber supply specialists at Japanese prepreg distributors. Secondary validation drew from customs trade data, motorcycle registration databases, and riding club membership records. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Historical shipment patterns cross-referenced against panel input from distributor inventory managers and retail category buyers informed the analytical framework. Segmentation modeling captured product type, material grade, end-user archetype, and connectivity feature intensity dimensions. CAGRs derived from unit-volume trajectory analysis applied to average selling price evolution by certification tier. Industry-specific forecast inputs included GB 811-2022 replacement cycle compression assumptions and Toray-grade fiber allocation constraints.
Revisions become necessary when MIIT provincial enforcement timelines diverge from modeled synchronization, when Toray T800-grade capacity expands into non-aerospace markets, or when SAMR accelerates ECE R22.06 alignment beyond anticipated windows. Forecasts reflect documented assumptions regarding compliance cost pass-through elasticity and carbon fiber substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market