
 Coding and Marking Systems Market | 2026-2036
Coding and Marking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Coding and Marking Systems Market Intelligence
Software-defined print management and cloud-connected maintenance subscriptions is pivoting how coding vendors monetize hardware installations. Domino Printing Sciences plc leverages its service infrastructure across pharmaceutical packaging lines in Europe. Videojet Technologies Inc. anchors its competitive stance through extensive channel control in North American food processing plants. Markem-Imaje Corporation differentiates via deep specialization in high-speed continuous inkjet for beverage bottling operations.
Coding and marking systems encompass industrial equipment that applies alphanumeric codes, barcodes, QR codes, and graphics onto products and packaging substrates at speeds ranging from 1,000 to 100,000 marks per hour. These systems serve primarily to enable supply chain traceability, regulatory compliance, and anti-counterfeiting protection across manufacturing environments. Continuous inkjet technology commands the largest installed base due to its versatility across porous and non-porous substrates, while UV laser systems represent the fastest-expanding segment driven by permanent marking requirements in electronics and medical device manufacturing. The food and beverage end-user segment generates the deepest margin pools because of stringent date-coding mandates and high-volume production lines that demand minimal downtime.
The FDA enforces strict labeling requirements under 21 CFR Part 201 for pharmaceutical identification, directly mandating machine-readable codes that sustain demand for high-resolution marking equipment. In Europe, the EU Falsified Medicines Directive and MDR framework compel manufacturers to implement serialisation and unique device identification, reshaping procurement criteria toward integrable traceability platforms. China's NMPA and SAMR have tightened medical product coding standards, adding compliance complexity for multinational suppliers. Stakeholders must monitor how divergent national traceability timelines affect equipment replacement cycles and software upgrade pathways.
Market Dynamics
Software-defined print management is compressing equipment replacement cycles as pharmaceutical and food manufacturers demand cloud-connected traceability platforms that integrate directly with MES and ERP systems rather than standalone hardware.
Growth Catalysts
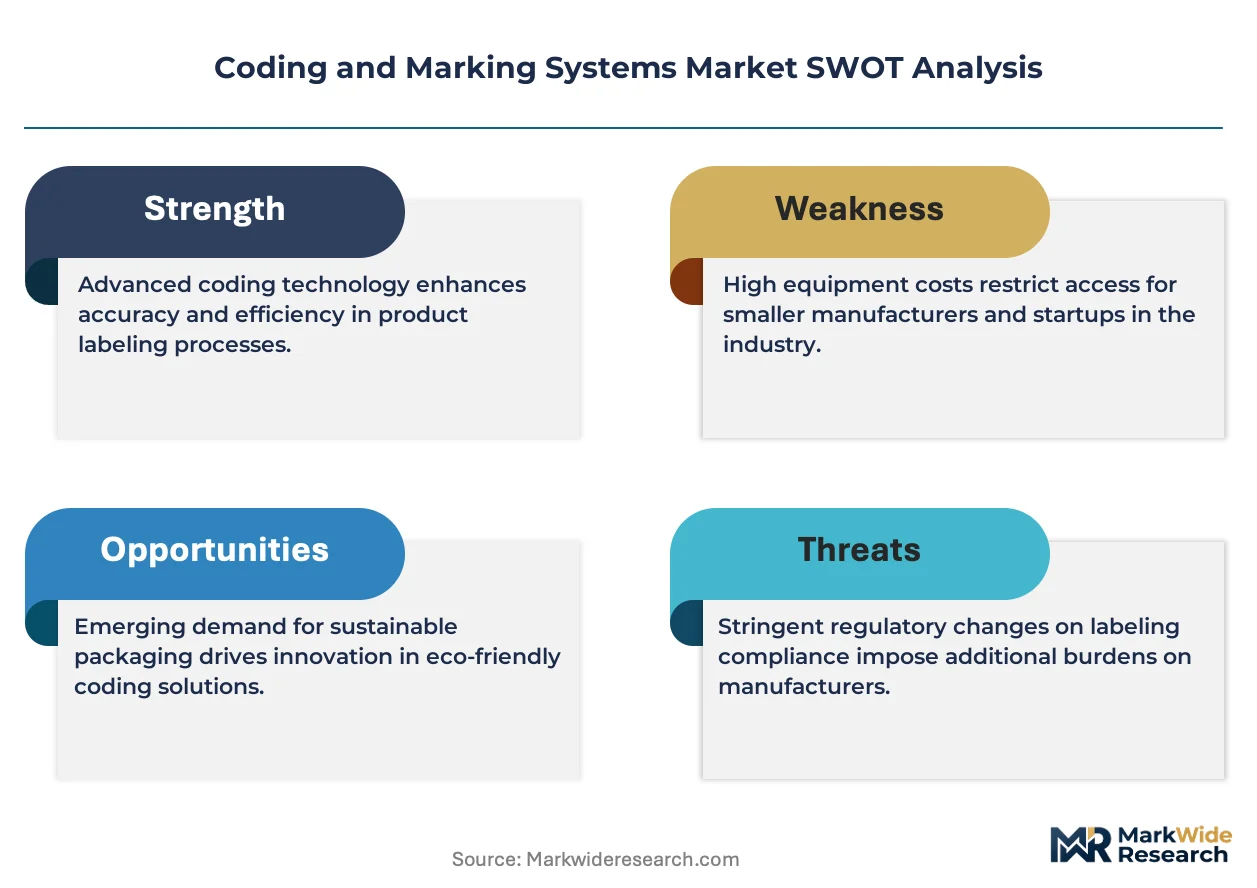
- EU Falsified Medicines Directive serialisation mandates:European pharmaceutical packaging lines require integrable coding platforms that embed unique identifiers at production speeds exceeding 50,000 units per hour.
- UV laser adoption in electronics manufacturing:Permanent marking requirements for printed circuit boards and semiconductor components drive replacement of solvent-based inkjet systems.
- India's medical device traceability expansion:CDSCO alignment with Global Harmonization Task Force standards compels domestic manufacturers to upgrade from manual date stamping to automated coding infrastructure.
Market Restraints
- Piezoelectric printhead supply concentration:Japanese and German component suppliers control proprietary MEMS fabrication, creating single-source vulnerability for continuous inkjet OEMs.
- MEE environmental compliance costs:China's emissions standards for volatile organic compounds in solvent inks force reformulation investments that compress hardware margins.
- Thermal inkjet speed ceiling:Drop-on-demand physics limits marking rates to approximately 300 meters per minute, excluding the technology from high-speed beverage canning lines.
Strategic Opportunities
- Brazil's ANVISA track-and-trace implementation:LatAm pharmaceutical serialization lag creates first-mover advantage for integrators offering Portuguese-language compliance software.
- AI-driven predictive maintenance convergence:Machine vision inspection systems paired with cloud analytics enable subscription revenue models that displace break-fix service contracts.
- Cell-cultured protein date-coding:Emerging food biotechnology facilities require nitrogen-flushed packaging with laser-etched lot codes that resist condensation degradation.
Industry Challenges
- OT-IT cybersecurity certification:IEC 62443 compliance for industrial control systems extends commissioning timelines by four to six months for pharmaceutical installations.
- Legacy CO2 laser obsolescence:Maintenance technician scarcity for gas-tube systems forces premature capital expenditure before end-of-depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coding and Marking Systems Market |
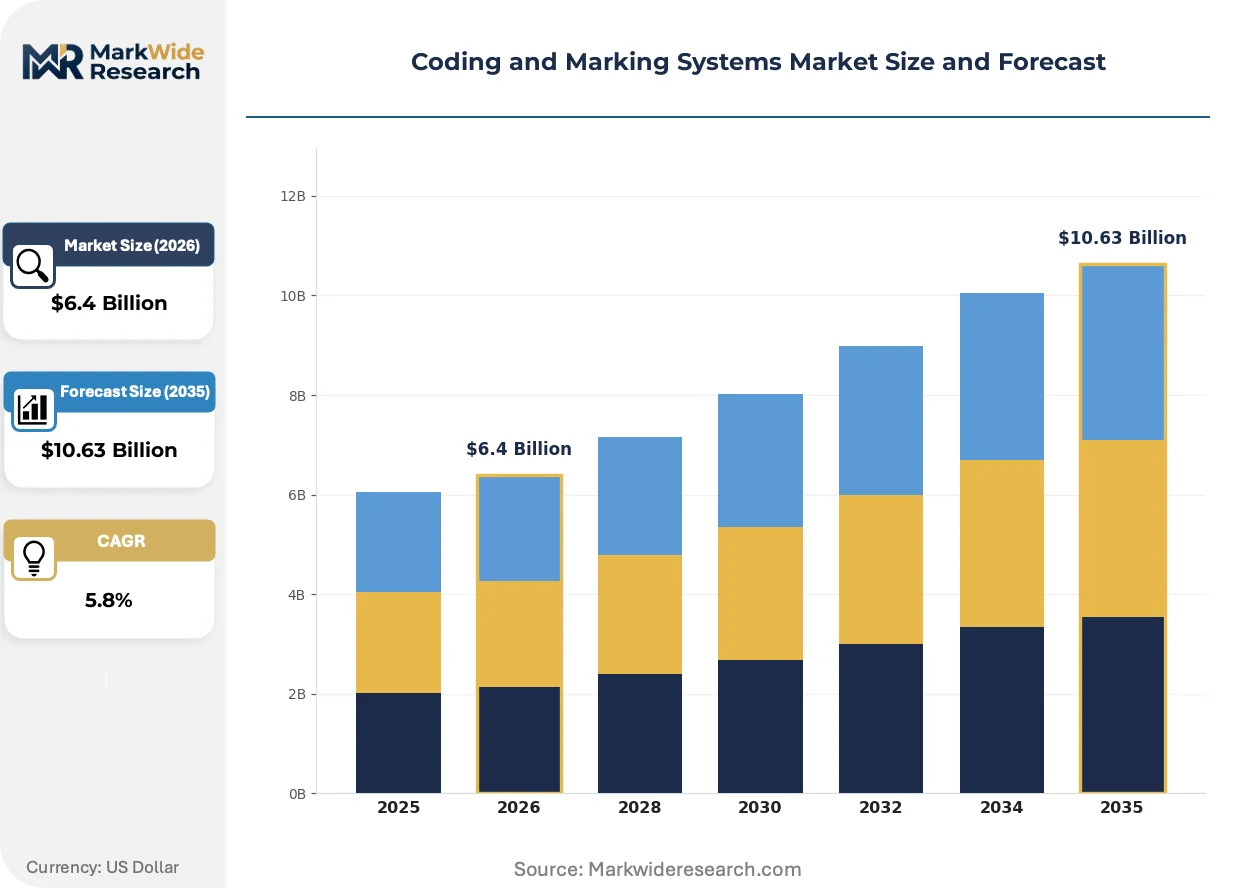
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
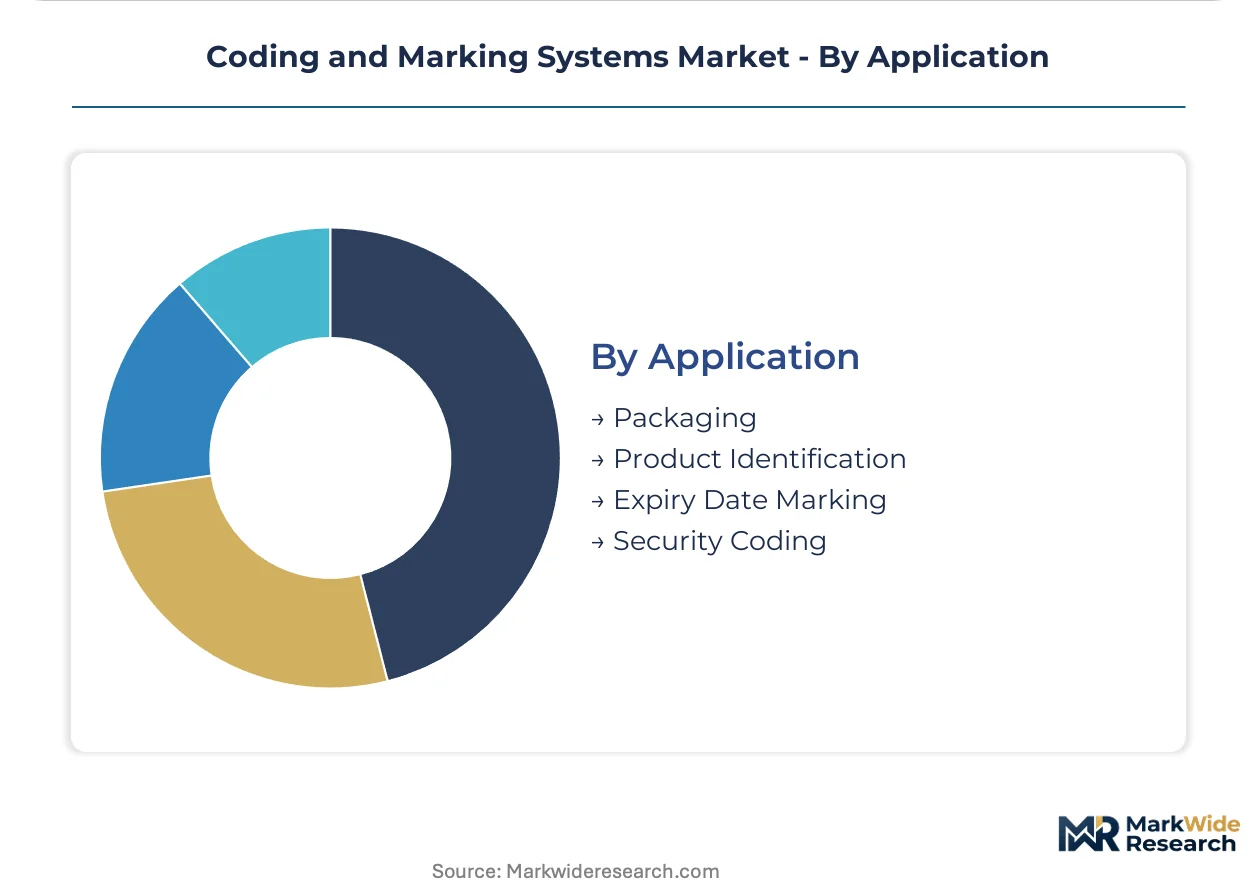
| Segmentation | Product Type: Inkjet Printers, Laser Printers, Thermal Transfer Printers, Labeling Systems End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Technology: Continuous Inkjet, Drop-On-Demand, UV Laser, Dot Matrix Application: Packaging, Product Identification, Expiry Date Marking, Security Coding |
| Companies Covered | Videojet Technologies Inc., Domino Printing Sciences plc, Markem-Imaje Corporation, Hitachi Industrial Equipment Systems, REA Elektronik GmbH, Linx Printing Technologies Ltd., Matthews International Corporation, Paul Leibinger GmbH & Co. KG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coding and Marking Systems Market Strategic Shifts & Innovations
Hardware commoditization is forcing coding vendors to reposition around data infrastructure and compliance software, with equipment margins collapsing while recurring service revenue expands.
Ultrafast fiber laser systems operating at picosecond pulse durations enable cold ablation marking on heat-sensitive medical polymers without carbonization or structural degradation. Medical device contract manufacturers in Switzerland and Germany are adopting these systems for UDI-compliant direct part marking. This precision capability is converging with automated vision verification to create closed-loop quality systems that eliminate manual inspection stations.
REACH Annex XVII restrictions on chromium VI compounds in pigment formulations are compelling ink suppliers to reformulate black CIJ fluids using alternative carbon black dispersions. The regulatory pressure extends to cobalt-based driers in specialty substrates, forcing beverage and cosmetics packagers to validate new adhesion chemistries. German chemical regulators at ECHA are accelerating substance evaluation timelines, compressing the window for supply chain qualification.
Outcome-based service contracts tied to equipment uptime guarantees are displacing traditional time-and-materials maintenance arrangements in North American food processing plants. Large CPG conglomerates now specify availability SLAs above 99.5% in RFP documents, transferring operational risk to OEM service organizations. This liability shift concentrates in high-volume dairy and bakery operations where unplanned downtime exceeds $50,000 per hour in lost production value.
Coding and Marking Systems Market Segmentation

Equipment selection in coding and marking hinges on substrate compatibility, line speed requirements, and regulatory traceability mandates. Manufacturers configure procurement around these technical boundaries rather than brand preference alone.
Product Type:
Standardization dominates high-volume beverage and pharmaceutical lines, while custom-engineered systems serve niche substrates like cell-cultured protein packaging and nitrogen-flushed medical pouches.
- Inkjet Printers:Continuous and drop-on-demand architectures apply solvent-based or UV-curable inks onto porous and non-porous surfaces at speeds reaching 100,000 marks per hour. Demand concentrates in German automotive component plants and North American dairy processing facilities where frequent changeovers require rapid drying formulations.
- Laser Printers:CO2, fiber, and UV laser sources ablate or discolor substrates without consumables, delivering permanent marks resistant to solvents and abrasion. Swiss medical device contract manufacturers deploy picosecond fiber systems for UDI-compliant polymer marking where carbonization risks disqualify thermal methods.
- Thermal Transfer Printers:Wax-resin or resin ribbons transfer ink via heated printheads onto flexible packaging films and adhesive labels. These systems serve Brazilian pharmaceutical serialization lines where ANVISA track-and-trace mandates require high-contrast barcode durability.
- Labeling Systems:Pressure-sensitive, shrink-sleeve, and in-mold labeling equipment applies pre-printed substrates rather than direct marking. Demand clusters in premium cosmetics packaging where decorative finishes exceed inkjet resolution limits.
Leading the category by volume: Inkjet Printers. Expanding most quickly: Laser Printers.
End User:
Margin structures vary sharply across verticals, with pharmaceutical and electronics buyers accepting premium pricing for compliance-critical traceability while food processors prioritize uptime guarantees over equipment features.
- Food & Beverage:Date-coding mandates for perishables drive installed base density, with high-volume bakeries and dairies specifying 99.5% uptime SLAs that transfer operational risk to OEM service organizations. European meat processors face dual pressure from EU Green Deal packaging rules and F-Gas Regulation compliance for refrigeration-integrated lines.
- Pharmaceuticals:Serialization under FDA 21 CFR Part 201 and EU Falsified Medicines Directive compels integrable platforms embedding unique identifiers at 50,000+ units per hour. Indian CDSCO alignment with Global Harmonization Task Force standards is accelerating automated infrastructure upgrades.
- Electronics:Permanent marking requirements for printed circuit boards and semiconductor components favor UV laser systems over solvent inkjet. China's MIIT standards for component traceability reinforce this technology shift.
- Consumer Goods:Anti-counterfeiting graphics and variable data printing on personal care packaging demand mid-speed continuous inkjet with quick-dry formulations. REACH Annex XVII restrictions on chromium VI pigments are forcing ink reformulation validations.
Deepest margin pools: Pharmaceuticals. Steepest volume expansion: Food & Beverage.
Technology:
Physics constraints lock each technology into specific speed and substrate envelopes, creating parallel supply chains with limited cross-competition.
- Continuous Inkjet:Pressurized fluid loops recirculate ink through piezoelectrically driven printheads, enabling 24/7 operation on curved and irregular surfaces. Japanese and German MEMS fabricators control proprietary piezoelectric actuator supply, creating single-source vulnerability for OEMs.
- Drop-On-Demand:Thermal and piezoelectric printheads eject individual droplets without continuous recirculation, reducing solvent consumption. Drop-on-demand physics caps marking rates at approximately 300 meters per minute, excluding the technology from high-speed beverage canning.
- UV Laser:Solid-state sources at 355nm wavelength photochemically alter substrate surfaces without thermal damage. Electronics manufacturers in South Korea and Taiwan adopt these systems for heat-sensitive component marking.
- Dot Matrix:Electromagnetically driven pins impact ribbon or substrate to create embossed or inked characters. Legacy installations persist in heavy industrial environments where electromagnetic interference disqualifies electronic marking.
Widest installed base: Continuous Inkjet. Gaining share fastest: UV Laser.
Application:
Functional requirements determine hardware specification, with packaging line integration demanding MES connectivity while standalone product identification tolerates simpler architectures.
- Packaging:Primary and secondary packaging lines require variable data printing synchronized to line speeds and product detection sensors. Cloud-connected maintenance subscriptions are displacing break-fix contracts in North American CPG plants.
- Product Identification:Direct part marking with alphanumeric codes, logos, and 2D symbologies enables supply chain traceability. Medical device manufacturers in Germany and Switzerland combine ultrafast fiber lasers with automated vision verification for closed-loop quality.
- Expiry Date Marking:Legibility mandates for perishables drive specification of high-contrast inks and laser ablation on flexible films. Cell-cultured protein facilities require nitrogen-flushed packaging with condensation-resistant laser etching.
- Security Coding:Covert and overt anti-counterfeiting features including microtext, UV-fluorescent inks, and destructible patterns protect high-value goods. Cosmetics and spirits packagers in France deploy these features under ANSM guidance.
Highest equipment density: Packaging. Fastest software attachment: Security Coding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor manufacturers in Germany deploy continuous inkjet systems across automotive component plants at densities unmatched elsewhere. Regulatory divergence between jurisdictions is fragmenting equipment specifications and forcing localized compliance architectures.
Germany
Automotive suppliers in Baden-Württemberg demand high-speed marking for powertrain components at 100,000 units per hour. ECHA acceleration of REACH Annex XVII substance evaluations compresses ink reformulation qualification windows. Stuttgart-based precision engineering clusters are migrating from solvent-based to UV-curable formulations ahead of regulatory deadlines.
United States
FDA 21 CFR Part 201 mandates machine-readable pharmaceutical codes that sustain premium equipment procurement in New Jersey and Massachusetts biopharma corridors. USDA inspection protocols for dairy and meat processing drive uptime guarantee contracts exceeding 99.5% availability. Chicago-area food conglomerates specify cloud-connected maintenance subscriptions that displace traditional service arrangements.
China
NMPA serialization requirements for medical devices compel domestic manufacturers to upgrade from manual stamping to automated laser infrastructure. MEE volatile organic compound standards force solvent ink reformulation investments that compress hardware margins. Yangtze River Delta electronics contract manufacturers adopt UV laser systems for permanent printed circuit board marking under MIIT traceability guidelines.
Switzerland
Swissmedic UDI enforcement drives medical device contract manufacturers toward picosecond fiber laser systems for heat-sensitive polymer marking. Precision manufacturing clusters in Zurich and Basel combine ultrafast lasers with automated vision verification for closed-loop quality systems. Geneva-based pharmaceutical packaging specialists demand integrable traceability platforms embedding unique identifiers at production speeds exceeding 50,000 units per hour.
India
CDSCO alignment with Global Harmonization Task Force standards accelerates automated coding infrastructure upgrades across domestic medical device manufacturers. FSSAI date-coding mandates for packaged foods concentrate demand in Maharashtra and Gujarat processing corridors. Mumbai-area pharmaceutical exporters retrofit packaging lines to meet EU Falsified Medicines Directive serialisation requirements for European market access.
Coding and Marking Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers across equipment fabrication and software development layers. The vendor base stratifies between integrated multinational platforms and specialized regional fabricators serving niche substrate applications. Three archetypes dominate: full-stack platform providers bundling hardware with compliance software, component specialists controlling proprietary printhead MEMS fabrication, and regional system integrators offering localized regulatory expertise. Consolidation pressure concentrates through strategic technology licensing arrangements and geographic expansion into emerging serialization markets.
Within the integrated platform tier, Videojet Technologies Inc., Domino Printing Sciences plc, and Markem-Imaje Corporation exemplify capital-intensive operators with extensive service infrastructures. Videojet anchors North American food processing dominance through channel control and uptime guarantee contracts. Domino occupies a position across European pharmaceutical packaging lines leveraging cloud-connected maintenance subscriptions. Markem-Imaje sits within high-speed beverage bottling specialization where continuous inkjet physics advantages persist. These three represent the consolidation endpoint toward which mid-cap specialists and regional integrators are gravitating through partnership or acquisition.
| Leading Market Players |
|---|
| Videojet Technologies Inc. |
| Domino Printing Sciences plc |
| Markem-Imaje Corporation |
| Hitachi Industrial Equipment Systems |
| REA Elektronik GmbH |
| Linx Printing Technologies Ltd. |
| Matthews International Corporation |
| Paul Leibinger GmbH & Co. KG |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
UV laser migration from solvent-based inkjet systems is compressing consumables revenue while concentrating procurement power among electronics contract manufacturers in Taiwan and South Korea. This technology transition simultaneously elevates upfront equipment costs and locks buyers into single-source fiber laser module dependencies.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for high-volume food and pharmaceutical lines, with availability SLAs above 99.5% commanding 40-60% service premiums over standard maintenance arrangements. Three-tier pricing structure across premium compliance-integrated platforms, standard standalone hardware, and economy refurbished units differentiates procurement segments. Cost compression in economy-tier continuous inkjet hardware is intensifying because Chinese OEMs are flooding export markets with piezoelectric printhead clones. Food processors in North American dairy corridors exhibit highest price sensitivity, while Swiss medical device contract manufacturers accept premium positioning for UDI-validated laser systems.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German MEMS fabricators controlling proprietary piezoelectric actuator production for continuous inkjet printheads. Component sourcing draws from precision engineering clusters in Japan, Germany, and Switzerland for optical assemblies, while UV laser diodes concentrate through South Korean and Taiwanese semiconductor foundries. Tariff exposure on Chinese-manufactured control electronics threatens margin structures for European OEMs assembling finished systems. Distribution runs through authorized service networks rather than direct sales, with regional integrators capturing compliance-software attachment revenue in Brazil and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected predictive maintenance platforms are displacing break-fix service contracts across pharmaceutical and food processing installations, marking a definitive transition from hardware-centric to subscription-based revenue models.
For Market Incumbents: Cement service infrastructure dominance by acquiring regional integrators with ANVISA or CDSCO compliance expertise in Brazil and India. Lock in pharmaceutical packaging lines through backward integration into vision verification systems, defending against emerging AI-native entrants offering pure-software traceability overlays.
For New Entrants and Emerging Players: Capture cell-cultured protein packaging white space by specializing in nitrogen-flushed laser etching systems resistant to condensation degradation. Target Brazilian pharmaceutical serialization lag with Portuguese-language compliance software bundles. Lead with outcome-based pricing tied to lot-code legibility guarantees rather than equipment capex.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where hardware OEMs absorb software-defined maintenance specialists. Long-term viability favors full-stack providers bundling equipment with MES-integrable traceability platforms. Watch for IEC 62443 cybersecurity certification delays as inflection indicator for pharmaceutical installation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Maintenance Subscription Launch | Transforms Domino Printing Sciences' European pharmaceutical service revenue from break-fix to recurring. |
| Backward Integration into Vision Verification Systems | Enables Markem-Imaje to capture closed-loop quality budgets from Swiss medical device manufacturers. |
| Portuguese-Language Compliance Software Development | Positions integrators for ANVISA track-and-trace implementation in Brazilian pharmaceutical corridors. |
| Picosecond Fiber Laser Platform Expansion | Addresses Swissmedic UDI enforcement for heat-sensitive polymer marking in Basel precision clusters. |
| Piezoelectric Printhead MEMS Fabrication Partnership | Mitigates single-source vulnerability with Japanese and German component suppliers for CIJ OEMs. |
Research Approach
Multi-period observation of equipment replacement cycles, regulatory compliance deadlines, and service contract attachment rates anchored the trend analysis, supplemented by interviews with plant engineers at dairy and pharmaceutical facilities, aftermarket service heads at OEMs, procurement teams at CPG conglomerates, and regulatory affairs leads at medical device manufacturers. Secondary validation drew from FDA 21 CFR Part 201 filings, EMA serialization guidance documents, CDSCO track-and-trace notifications, and SEC 10-K disclosures from listed equipment vendors. Bottom-up triangulation across installed base estimates and top-down cross-check against capital expenditure surveys ensured forecast robustness.
Input-output matrices mapped technology adoption curves against substrate compatibility constraints and line speed requirements across the projection horizon. Segmentation dimensions modeled include product architecture, end-use vertical, geographic regulatory cluster, and integration complexity tier. CAGRs were derived from slope analysis of historical equipment shipments correlated with compliance mandate effective dates. Forecast inputs incorporated MEE volatile organic compound enforcement timelines and EU Falsified Medicines Directive serialisation phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to piezoelectric component supply disruptions, REACH Annex XVII substance restriction accelerations, and OT-IT cybersecurity certification bottlenecks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Global Pack Conveyors Market
Packaging Equipment
Vacuum Sealers Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Container Washing System Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Loading Spout Market